
 Asia-Pacific 3D Printing Construction Market | 2026-2036
Asia-Pacific 3D Printing Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific 3D Printing Construction Market Analytics
High-strength concrete formulations rated above 50 MPa is unwinding the performance ceiling for load-bearing printed structures. Winsun leverages proprietary gantry systems to dominate large-scale housing prototypes in China. COBOD International anchors Nordic-Australian technology transfer through distributor partnerships. Beijing Huashang Luhai Technology specializes in geopolymers that reduce Portland cement dependence.
Asia-Pacific 3D printing construction deploys layer-by-layer material deposition to fabricate structural and non-structural building components directly from digital models, typically using cementitious pastes with particle sizes below 1 mm and layer heights between 5-30 mm to achieve compressive strengths suitable for residential and commercial occupancy. Material extrusion systems currently occupy the largest installed base across the region due to lower capital requirements and compatibility with conventional concrete supply chains. Residential buildings represent the fastest-growing application segment as governments in Vietnam, the Philippines, and Indonesia pilot printed social housing to address urban shortfalls.
China's SAMR enforces GB standards for printed concrete durability, while Australia's National Construction Code mandates third-party certification for non-traditional building methods. Japan's MLIT evaluates seismic performance of additive structures through dedicated working groups. Stakeholders must monitor how harmonization between Chinese GB frameworks and ASEAN national codes reshapes cross-border equipment deployment and material sourcing strategies.
Market Dynamics
China's GB standards for 3D-printed concrete are forcing equipment manufacturers to redesign extrusion systems for compliance certification before regional export. This regulatory harmonization pressure is compressing technology development cycles across Southeast Asian supply chains.
Growth Catalysts
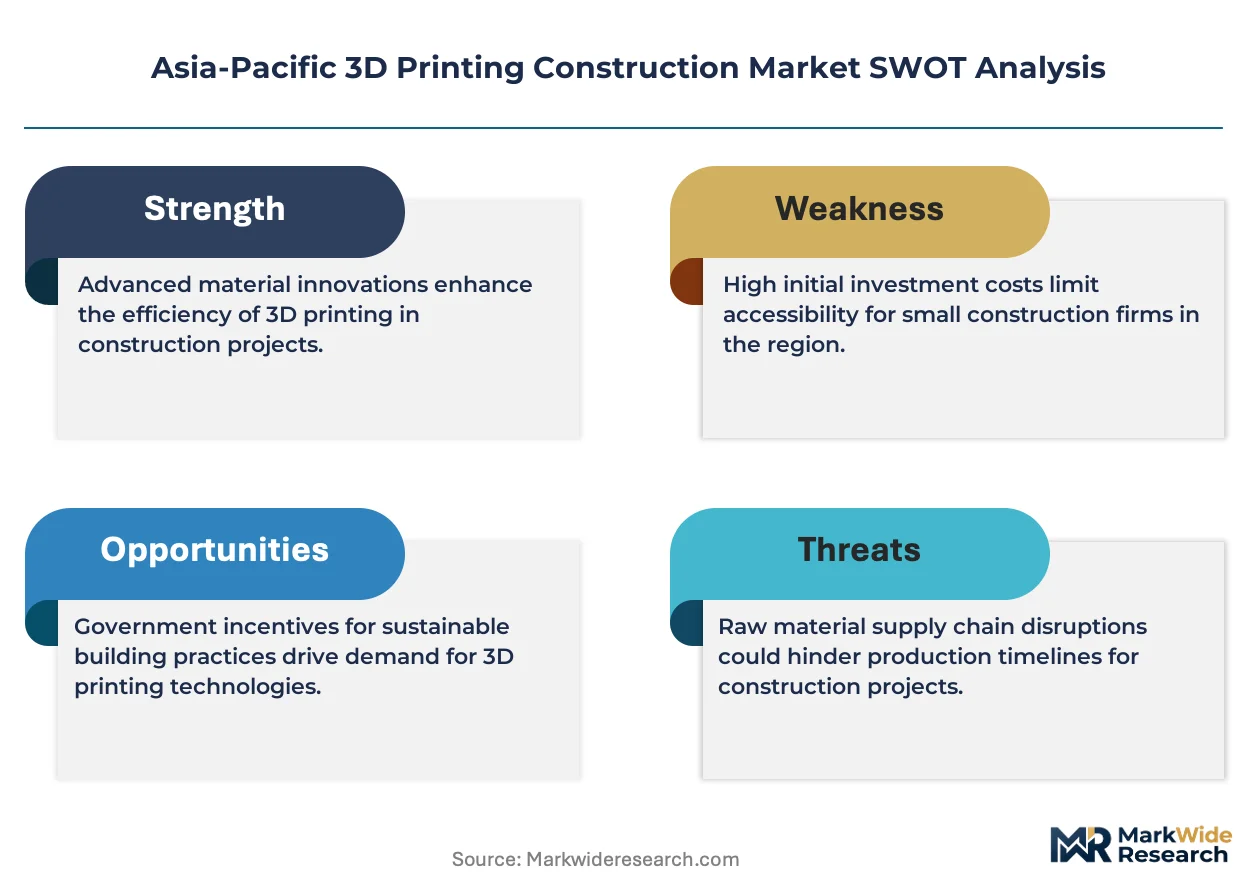
- Geopolymer formulations:Beijing Huashang Luhai Technology's Portland cement alternatives reduce carbon intensity by 40% versus conventional mixes, aligning with China's dual carbon goals and Singapore's green building codes.
- Australia's National Construction Code amendments:Third-party certification pathways for non-traditional methods now recognize additive manufacturing, unlocking modular residential procurement by volume builders facing skilled labor deficits.
- Material extrusion compatibility:Existing concrete supply chains integrate with gantry-based printers without batching plant retrofits, lowering contractor switching costs in Vietnam's social housing pilots.
Market Restraints
- Specialized nozzle supply concentration:Precision extrusion heads rated for 50 MPa+ paste rheology originate from German and Danish suppliers, creating 12-16 week lead times for Asia-Pacific printer OEMs.
- Rebar integration limitations:Continuous steel reinforcement placement during printing remains unresolved, restricting printed structures to compression-dominant wall systems and non-load-bearing partitions.
- Cross-border equipment certification:China's SAMR type-approval requirements for construction machinery do not automatically recognize Australian or Japanese testing protocols, forcing redundant validation expenditures.
Strategic Opportunities
- Indonesia's 3 million unit housing backlog:Periurban land conversion around Jakarta and Surabaya offers scale deployment sites for printed social housing clusters with centralized material batching.
- Seismic performance validation:Japan's MLIT working group protocols for additive structures, once finalized, will create first-mover certification advantages for suppliers targeting Ring of Fire construction markets.
- Digital fabrication-as-a-service:Contractor leasing models for mobile gantry systems reduce upfront capital barriers for mid-tier builders in the Philippines' fragmented construction sector.
Industry Challenges
- Multi-material process control:Simultaneous deposition of structural concrete, insulation, and finish layers requires real-time rheology monitoring that exceeds current operator training curricula in regional technical institutes.
- Layer-to-layer bond verification:Non-destructive testing protocols for cold joint integrity in 5-30 mm layer heights lack standardized acceptance criteria, delaying occupancy permits in Australia's modular sector.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific 3D Printing Construction Market |
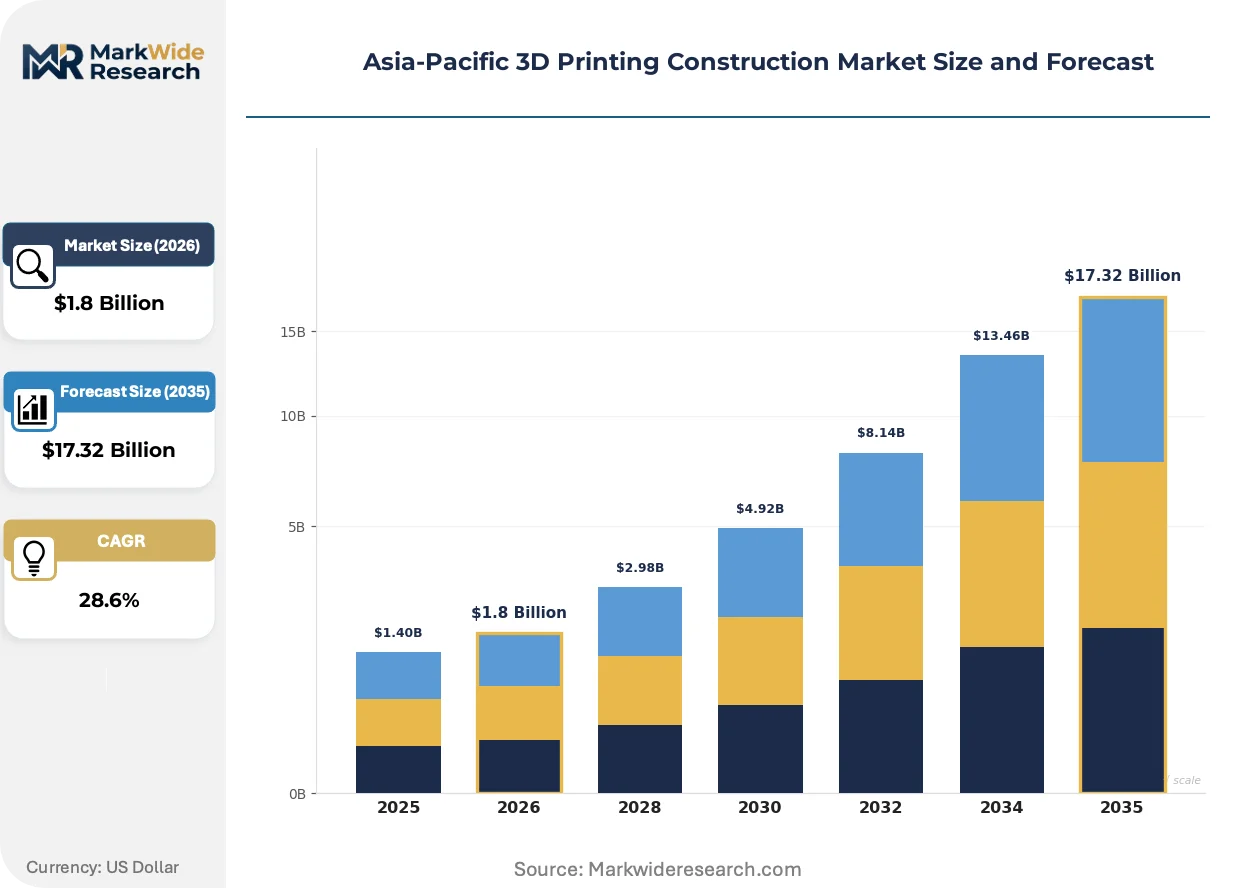
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $17.32 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Residential Buildings, Commercial Structures, Infrastructure Projects, Decorative Elements Material: Cement, Plastics, Metal Alloys, Composites Technology: Binder Jetting, Material Extrusion, Powder Bed Fusion, Vat Polymerization End User: Contractors, Architects, Government Agencies, Real Estate Developers |
| Companies Covered | Yingchuang Building Technique (Shanghai) Co. Ltd. (Winsun), Beijing Huashang Luhai Technology, COBOD International A/S, Apis Cor, CyBe Construction, Contour Crafting Corporation, ICON Technology, Inc., WASP S.r.l., Constructions-3D, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific 3D Printing Construction Market Evolving Landscape
Digital twin integration is compressing design-to-fabrication timelines for complex geometries previously uneconomical with formwork-based methods. Equipment suppliers are embedding sensors throughout deposition systems to enable predictive maintenance and quality traceability.
Contour crafting technology for vertical wall construction is miniaturizing from building-scale gantries to deployable robotic arms mounted on standard construction hoists. Australian modular residential developers are piloting these systems for bathroom pod fabrication, achieving 48-hour cycle times versus two-week conventional schedules. This scale reduction is enabling site-based production for infill projects where logistics constraints previously excluded additive methods.
China's SAMR is harmonizing GB/T 51328 durability standards with ASEAN national building codes through bilateral mutual recognition agreements. The industrial consequence is equipment manufacturers designing single certification packages for multi-country deployment. Vietnam's Ministry of Construction is referencing these frameworks for its own printed concrete guidelines, accelerating regulatory convergence across mainland Southeast Asia.
Performance-based procurement specifications are displacing prescriptive material callouts in Australian state government housing tenders. Volume builders now bid on thermal performance and structural warranty outcomes rather than mandated construction techniques, allowing printed wall systems to compete on total installed cost. This shift is most visible in New South Wales and Victoria, where Landcom and Homes Victoria have issued additive manufacturing eligibility criteria for their development pipelines.
Asia-Pacific 3D Printing Construction Market Segmentation
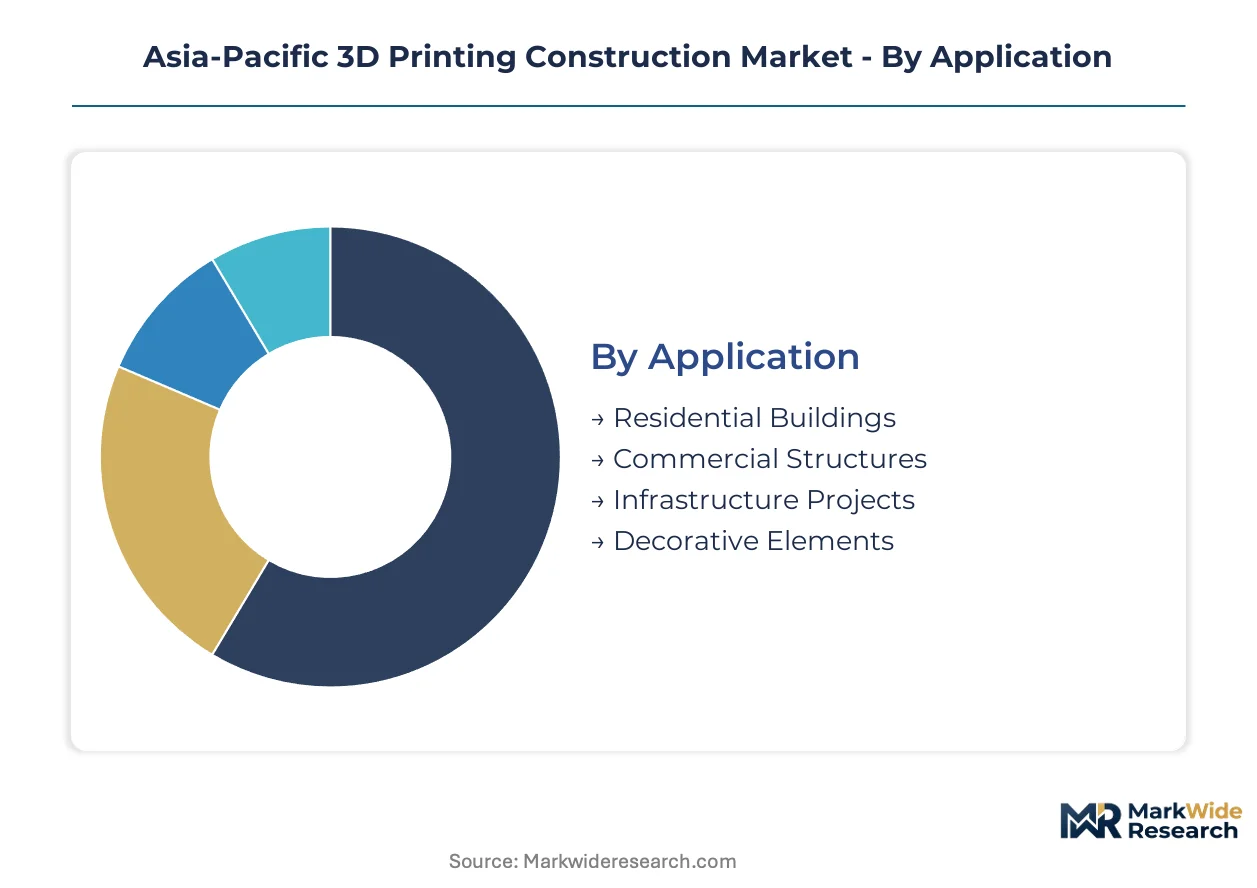
Segmentation in Asia-Pacific 3D printing construction reveals divergent technology maturities across national regulatory environments. Application patterns cluster around housing deficits in Indonesia and Vietnam versus modular commercial pilots in Australia. Material choices track cement supply chain densities and carbon reduction mandates in China and Singapore.
Application:
Domestic demand concentrates in social housing programs across Southeast Asian markets, while export-oriented technology licensing flows from Chinese equipment manufacturers to regional contractors.
- Residential Buildings:Layer-by-layer fabrication of structural wall systems achieves compressive ratings above 50 MPa for multi-story occupancy. Indonesia's 3 million unit housing backlog and Vietnam's urban migration pressures concentrate procurement in per-urban Jakarta and Ho Chi Minh City clusters, with China's Winsun supplying gantry systems for localized production.
- Commercial Structures:Office and retail prototypes demonstrate 30-40% reduction in construction schedules versus conventional methods, though rebar integration constraints limit height and span capabilities. Australia's National Construction Code amendments now permit additive methods for modular commercial pods, unlocking volume builder procurement in Sydney and Melbourne.
- Infrastructure Projects:Bridge components and utility housings utilize geopolymers from Beijing Huashang Luhai Technology for reduced carbon intensity.
- Decorative Elements:Façade panels and interior features leverage design freedom without structural certification burdens.
Residential Buildings commands the established base. The steepest expansion runs through Commercial Structures.
Material:
Cost tiers separate Portland cement formulations from premium geopolymers and specialty alloys, with procurement patterns tracking carbon pricing exposure across national markets.
- Cement:Conventional Portland-based pastes with particle sizes below 1 mm dominate installed printer bases due to supply chain compatibility with existing batching infrastructure. Vietnam's social housing pilots and China's rural revitalization programs anchor demand, though carbon intensity faces tightening scrutiny under Singapore's green building codes and China's dual carbon goals.
- Plastics:Acrylonitrile butadiene styrene and polylactic acid formulations serve non-structural applications including formwork molds and temporary bracing. Australian modular residential developers utilize plastic-based contour crafting for bathroom pod fabrication, achieving 48-hour cycle times.
- Metal Alloys:Stainless steel and aluminum deposition remain nascent, constrained by equipment costs and thermal distortion control.
- Composites:Fiber-reinforced cementitious matrices offer intermediate performance for load-bearing applications requiring reduced weight.
Cement retains the volume base. Composites are climbing the fastest as performance requirements tighten.
Technology:
Maturity stages separate field-proven extrusion systems from emerging powder-based methods, with deployment patterns tracking capital availability and operator training depth.
- Material Extrusion:Gantry-based and robotic arm systems deposit cementitious pastes in 5-30 mm layer heights, achieving bond strengths suitable for residential occupancy. Compatibility with conventional concrete supply chains lowers switching costs for Vietnamese and Indonesian contractors, while Australia's modular sector drives sensor integration for predictive maintenance.
- Binder Jetting:Powder-based processes deposit binding agents onto sand or metal substrates for tooling and mold production. Chinese research institutes pilot scaled systems for construction components, though material waste rates and post-processing requirements constrain commercial deployment.
- Powder Bed Fusion:Selective laser sintering of metals remains confined to architectural hardware and connection details.
- Vat Polymerization:Stereolithography serves scale models and design validation, not structural fabrication.
Material Extrusion holds the installed base. Binder Jetting faces the steepest capability expansion as waste reduction improves.
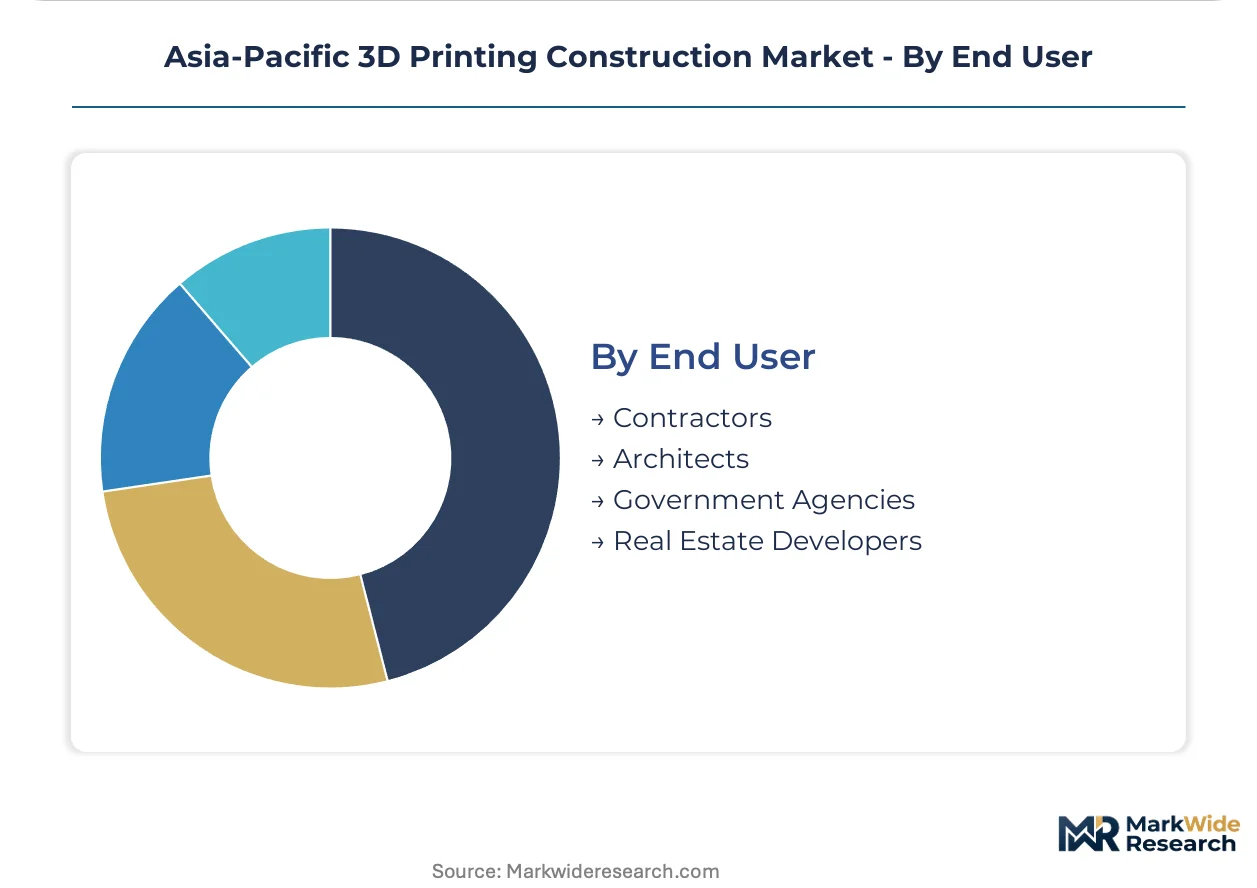
End User:
Customer types separate capital-constrained public procurement from performance-specified private development, with contract structures determining technology risk allocation.
- Contractors:Mid-tier builders in the Philippines and Indonesia lease mobile gantry systems through fabrication-as-a-service models, avoiding upfront capital barriers. Australia's skilled labor deficits drive volume builders toward additive methods for repetitive modular components, with Landcom and Homes Victoria issuing eligibility criteria for state housing pipelines.
- Government Agencies:National housing authorities in Vietnam, Indonesia, and the Philippines pilot printed social housing with centralized material batching and quality oversight. China's Ministry of Housing and Urban-Rural Development references GB/T 51328 standards for durability verification.
- Architects:Design firms specify complex geometries uneconomical with formwork methods, though construction risk transfer remains unresolved.
- Real Estate Developers:Private developers in Australian state markets bid on thermal performance outcomes rather than prescribed techniques.
Contractors anchor the established base. Government Agencies are gaining share fastest as social housing procurement scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment manufacturers cluster in eastern Chinese industrial zones, while demand dispersion stretches from Australia's modular residential corridors to Indonesia's peri-urban housing backlogs. SAMR certification requirements for construction machinery now function as de facto regional standards through bilateral mutual recognition agreements with Vietnam and Indonesia.
China
Winsun's proprietary gantry systems anchor large-scale housing prototypes in Shanghai and Suzhou industrial parks. SAMR enforces GB/T 51328 durability standards that neighboring markets reference for printed concrete compliance. Beijing-Tianjin-Hebei corridor concentrates geopolymer research at Beijing Huashang Luhai Technology facilities reducing Portland cement dependence.
Australia
Volume builders facing skilled labor deficits drive additive manufacturing procurement for repetitive modular components. National Construction Code amendments now recognize third-party certification pathways for non-traditional methods. New South Wales and Victoria state housing pipelines through Landcom and Homes Victoria have issued explicit additive manufacturing eligibility criteria.
Vietnam
Urban migration pressures concentrate social housing demand in Ho Chi Minh City peri-urban clusters. Ministry of Construction guidelines reference Chinese GB frameworks for printed concrete standards. Centralized material batching operations in Dong Nai and Binh Duong provinces support contractor adoption of gantry-based extrusion systems.
Indonesia
Three million unit housing backlog creates scale deployment opportunities for printed social housing clusters. Peri-urban land conversion around Jakarta and Surabaya offers contiguous sites for centralized production models. National housing authority pilots incorporate quality oversight protocols adapted from Chinese regulatory templates.
Japan
MLIT working groups evaluate seismic performance protocols for additive structures in Ring of Fire construction markets. METI-funded research institutes pilot powder-based binder jetting systems for construction component fabrication. Kanto and Kansai industrial corridors concentrate equipment testing facilities for earthquake-resistance validation.
Asia-Pacific 3D Printing Construction Market Competitive Landscape
Concentration sits with Chinese equipment manufacturers leveraging integrated supply chains for gantry system production. The vendor base organizes around three strategic archetypes: proprietary technology developers, regional licensing partners, and material formulation specialists. Competitive positioning hardens through technology licensing agreements and cross-border certification package standardization.
Within the proprietary technology tier, Yingchuang Building Technique (Shanghai) Co. Ltd. (Winsun) and Beijing Huashang Luhai Technology represent contrasting approaches to market development. Winsun exemplifies scale-driven equipment deployment through integrated gantry systems. Beijing Huashang Luhai Technology occupies a position as material specialist focused on geopolymer formulations. COBOD International A/S anchors Nordic-Asian technology transfer through distributor partnership structures.
| Leading Market Players |
|---|
| Yingchuang Building Technique (Shanghai) Co. Ltd. (Winsun) |
| Beijing Huashang Luhai Technology |
| COBOD International A/S |
| Apis Cor |
| CyBe Construction |
| Contour Crafting Corporation |
| ICON Technology, Inc. |
| WASP S.r.l. |
| Constructions-3D |
| Others |
Value Network & Pricing Analysis
Project-based procurement contracts with centralized material batching lock in supply access and price visibility for contractors deploying gantry systems across Vietnam and Indonesia's social housing programs. China's SAMR certification requirements for extrusion equipment create compliance cost premiums that propagate through regional equipment leasing markets.
Pricing Analysis
China's GB/T 51328 durability standards dictate the pricing tier structure across the Asia-Pacific 3D printing construction market. Three-tier pricing structure across certified-premium, compliance-standard, and pilot-economy levels separates Winsun's proprietary gantry systems from regional licensing packages and mobile fabrication-as-a-service offerings. Price differentiation centers on SAMR type-approval status and geopolymer formulation performance. Cost compression in economy-tier equipment intensifies because Indonesian and Philippine contractors prioritize capital efficiency over certification depth. Government housing agencies exhibit lowest price sensitivity due to centralized procurement budgets, while mid-tier contractors in fragmented markets face acute margin pressure.
Supply Chain Analysis
Twelve-to-sixteen-week lead times for precision extrusion heads rated for 50 MPa+ paste rheology expose inventory vulnerabilities across Asia-Pacific printer OEMs. Component manufacturing concentrates in Germany, Denmark, and eastern Chinese industrial zones. Raw material dependencies include Portland cement alternatives, geopolymer activators, and fiber reinforcement matrices. Single-source vulnerability runs through specialized nozzle suppliers, with tariff exposure on European precision components compounding cost structures. Distribution runs through equipment manufacturer direct sales for large-scale systems and regional distributor networks for mobile gantry leases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific 3D printing construction market operates as a substitution defense against conventional formwork-based methods, with prefabricated modular construction representing the most credible incumbent technology threat that additive manufacturing must displace on total installed cost metrics.
For Market Incumbents: Fortify certification moats by accelerating SAMR-ASEAN mutual recognition package standardization before competitor equipment achieves multi-country deployment eligibility. Deepen backward integration into geopolymer formulation production to capture margin from Beijing Huashang Luhai Technology's Portland cement alternatives. The threat of Chinese equipment manufacturers licensing gantry systems to regional contractors at compressed royalty rates demands proactive channel control through exclusive distribution lock-ups in Indonesia and Vietnam.
For New Entrants and Emerging Players: Digital fabrication-as-a-service gaps in the Philippines' fragmented contractor base offer white-space entry with minimal incumbent leasing infrastructure. Target per-urban Jakarta and Surabaya clusters where Indonesia's national housing authority pilots concentrate demand for printed social housing at scale. Site-based technical training partnerships with regional technical institutes provide differentiated go-to-market positioning against equipment-heavy sales models.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among material formulation specialists with captive geopolymer supply contracts to government housing pipelines. Long-term viability across the projection horizon hinges on seismic performance certification progress in Japan's Ring of Fire markets. Acquisition target archetype: vertically integrated equipment-and-material players with SAMR certification and ASEAN licensing reach. Monitor MLIT working group protocol finalization as the critical inflection signal for seismic-validated system demand.
| Strategic Initiative | Industry Significance |
|---|---|
| GB-ASEAN Certification Harmonization | SAMR mutual recognition agreements compress multi-country equipment deployment costs for Winsun and COBOD distributor networks. |
| Geopolymer Manufacturing Scale-Up | Beijing Huashang Luhai Technology's Portland cement alternatives align with China's dual carbon goals and Singapore's green building codes. |
| Fabrication-as-a-Service Launch | Mobile gantry leasing models reduce capital barriers for mid-tier Philippine contractors facing skilled labor deficits. |
| Seismic Performance Validation | Japan's MLIT protocol completion unlocks first-mover certification advantages for Ring of Fire construction markets. |
| Digital Twin Platform Integration | Sensor-embedded deposition systems enable predictive maintenance contracts with Australian volume builders. |
Research Methodology
The analysis maps material extrusion systems, binder jetting pilots, geopolymer formulations, and gantry-based housing prototypes, each validated through equipment manufacturer executives, construction contractor procurement leads, government housing authority technical officers, and concrete supply chain managers. Primary interview insights triangulate against SAMR regulatory filings, ASEAN national building code amendments, Australian National Construction Code updates, and Japan's MLIT working group documentation. Secondary validation draws from customs equipment import records, state housing tender specifications, and geopolymer patent filings. Bottom-up unit economics for printed housing clusters reconcile with top-down market sizing across the analysis window.
Consistency checks against external benchmarks validate volume and value outputs for extrusion system installations and material consumption projections. The analytical framework segments by application type, material formulation, technology maturity, and end-user procurement structure across the modeling period. CAGRs derive from installed base growth curves and social housing pipeline commitments. Forecast inputs incorporate regulatory harmonization timelines and seismic certification progress specific to Ring of Fire construction requirements.
Underlying assumptions cover SAMR-ASEAN mutual recognition expansion, geopolymer cost parity achievement, and contractor training pipeline scaling, with deviation risk concentrated in rebar integration technology breakthroughs and powder-based method commercialization delays. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Delumper Market
Others
Retail Media Platform Market
Others
Food Technology Market
Others
Solar Lighting Tower Market
Others
Diamond Mining Market
Others
Coloring Apps Market
Others
Asia Pacific Video Conferencing Hardware Market
Others
Football Sportswear Market
Others
Latin America IT Device Market
Others
5G Tester Market
Others
Fenoxanil Market
Others
Connected Homes Market
Others
Europe Polycarbonate Sheets Market
Others
Latin America Video Conferencing Hardware Market
Others
HPHT Diamond Cubic Press Market
Others
Technical Films Market