
 Edible Insects for Animal Feed Market | 2026-2036
Edible Insects for Animal Feed Market Size, Share, and Industry Trends Forecast 2026-2036
Edible Insects for Animal Feed Market Analysis
Aquaculture operators and premium pet food manufacturers are reorganizing procurement priorities around insect-derived proteins. Ÿnsect SAS leverages vertical integration from breeding to processing to control input costs across its French facilities. Innovafeed SAS anchors industrial-scale black soldier fly production through its Nesle plant, supplying major aquafeed compounders. Protix B.V. dominates European larvae processing capacity and extends its technology licensing model into Asia-Pacific markets.
Edible insects for animal feed comprise whole, processed, or fractionated insect biomass—typically containing 40-65% crude protein and 10-25% fat on a dry matter basis—manufactured through controlled rearing, harvesting, drying, and milling operations to replace conventional protein ingredients in formulated feeds. Black soldier fly larvae lead volume deployment in fish feed applications due to superior feed conversion ratios and amino acid profiles matching salmonid requirements. Mealworm powder occupies premium positioning in poultry and pet nutrition segments where AAFCO-approved ingredient status commands price premiums over uncertified alternatives.
The European Food Safety Authority evaluates novel feed materials under EU Regulation 2015/2283, while the FDA exercises enforcement discretion for black soldier fly in specific aquaculture and poultry applications within the United States. BIS feed safety standards and FSSAI ingredient approvals in India create divergent compliance pathways that fragment cross-border trade. Stakeholders must monitor regulatory reciprocity developments between major producing and consuming jurisdictions to anticipate which certification tiers will unlock scalable offtake contracts.
Market Dynamics
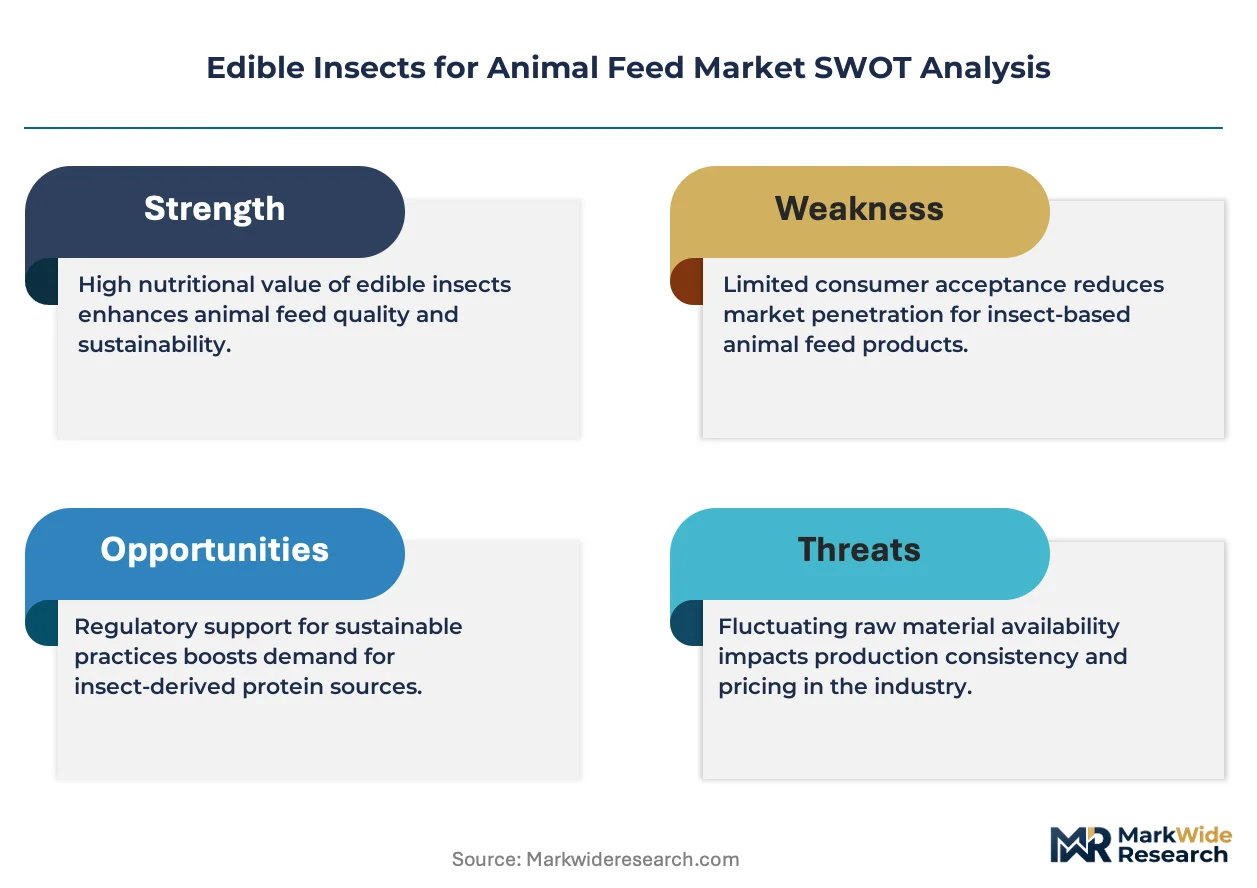
Fishmeal supply constraints from Peruvian anchovy quota reductions are forcing aquafeed compounders toward insect protein alternatives at unprecedented speed. This supply shock intersects with EU Novel Food Regulation harmonization to restructure procurement priorities across salmon, trout, and shrimp feed sectors.
Growth Catalysts
- EU Novel Food Regulation:EFSA approval pathways for black soldier fly larvae in aquafeed are unlocking multi-ton offtake contracts from Norwegian and Scottish salmon producers previously blocked by regulatory uncertainty.
- Thailand's feed safety modernization:Updated BAFAC standards now explicitly permit processed insect meal in poultry and swine rations, triggering domestic capacity expansion and export qualification.
- Precision fermentation integration:Combined bioprocessing facilities are co-locating insect rearing with microbial protein production, sharing thermal energy and waste streams to drive unit economics below fishmeal parity.
Market Restraints
- Organic substrate cost volatility:Brewer's spent grain and fruit pulp prices fluctuate with beverage and juice processing cycles, compressing margins for larvae producers dependent on consistent feedstock supply.
- Regulatory reciprocity gaps:FDA enforcement discretion for black soldier fly in US aquafeed lacks formal codification, deterring institutional capital from multi-year capacity commitments.
- Mealworm amino acid limitations:Methionine and lysine deficiencies relative to fishmeal require synthetic supplementation, adding formulation complexity and cost in premium salmonid diets.
Strategic Opportunities
- India's FSSAI feed ingredient pathway:Pending approvals for Hermetia illucens meal in poultry rations would open a 3 million ton annual feed market with limited domestic protein alternatives.
- Pet food superpremium channel:AAFCO-certified insect protein commands 40-60% price premiums over conventional poultry meal in freeze-dried and fresh-frozen formats.
- Carbon credit stacking:Insect rearing facilities co-processing agricultural residues qualify for multiple compliance and voluntary carbon mechanisms in EU and UK markets.
Industry Challenges
- Entomological expertise scarcity:Industrial-scale rearing requires specialized knowledge in population genetics and pathogen management that outpaces university training programs in France and the Netherlands.
- Downstream integration complexity:Larvae processing equipment must achieve precise fat extraction thresholds to prevent rancidity in finished feeds, demanding capex-intensive fractionation lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Edible Insects for Animal Feed Market |
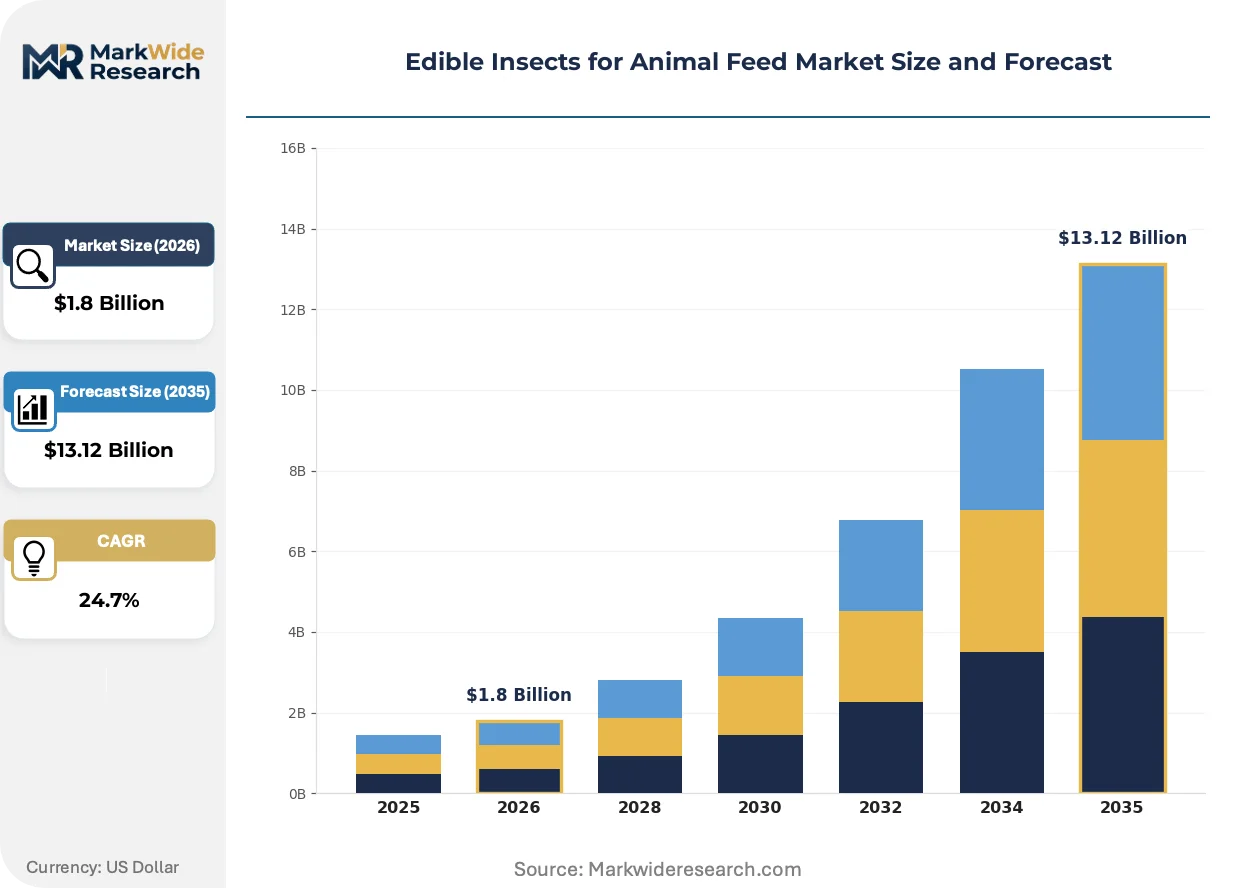
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $13.12 Billion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Crickets, Mealworms, Grasshoppers, Black Soldier Fly Application: Poultry Feed, Fish Feed, Swine Feed, Ruminant Feed Form: Powder, Whole, Pellets, Oil Certification: Organic, Non-GMO, ISO Certified, AAFCO Approved |
| Companies Covered | Ÿnsect SAS, Innovafeed SAS, Protix B.V., EnviroFlight, Entobel, Nasekomo, Hexafly, Aspire Food Group, Nutrition Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Edible Insects for Animal Feed Market Emerging Trajectories
Automated rearing systems and novel processing technologies are compressing production costs while regulatory clarity expands addressable feed categories. These forces are converging to reposition insect protein from niche substitute to primary formulation ingredient.
Automated climate-controlled rearing environments with machine vision monitoring are displacing manual husbandry in black soldier fly facilities. Dutch and French producers deploy these systems to achieve 99.5% larval survival rates across 14-day growth cycles. The resulting consistency in protein and fat content is displacing batch-to-batch variation that previously limited inclusion rates in compound feeds.
EFSA's 2021 safety opinion on frozen and dried insect products established precedent for expanded species approvals under EU Regulation 2015/2283. Member states are now processing applications for mealworm, cricket, and grasshopper derivatives in poultry and pig feed. German and Polish regulators are accelerating evaluation timelines to match French and Dutch authorization speeds.
Compound feed manufacturers are consolidating supplier relationships around vertically integrated insect producers with captive breeding and processing capabilities. Long-term offtake agreements with fixed volume tiers are replacing spot market purchasing in Norwegian salmon feed supply chains. This concentration is most pronounced in the Nesle and Amiens production clusters where rail-linked distribution reaches North Sea aquaculture ports within 48 hours.
Edible Insects for Animal Feed Market Segmentation
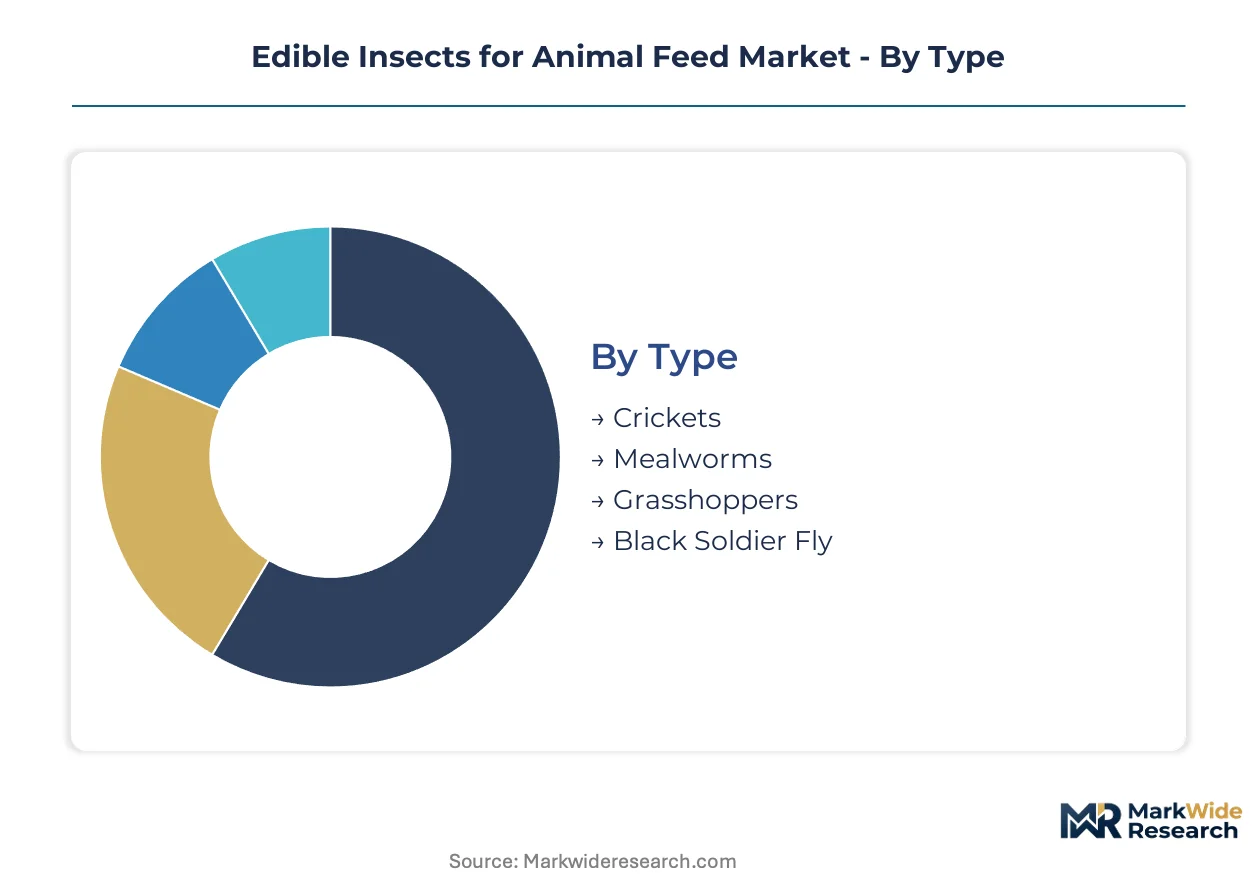
Insect protein procurement channels diverge sharply by segment. Aquafeed compounders demand consistent amino acid profiles that only specific species deliver, while pet food manufacturers prioritize certification tiers that command shelf price premiums.
Type:
Channel flow varies dramatically across insect categories, with aquaculture offtake concentrating on larvae species while premium pet nutrition gravitates toward whole-insect formats with visible morphology.
- Black Soldier Fly:Larvae contain 40-45% crude protein and 30-35% fat with favorable feed conversion ratios. Norwegian salmon producers anchor demand as EFSA approvals unlock multi-ton contracts previously blocked by regulatory uncertainty.
- Mealworms:Tenebrio molitor delivers 50-55% protein with established AAFCO approval pathways in North American markets. Premium freeze-dried pet food applications in Germany and France absorb volume at 40-60% price premiums over conventional poultry meal.
- Crickets:Acheta domesticus biomass suits poultry starter diets with digestibility coefficients exceeding 85%. Thai and Vietnamese producers scale capacity for domestic feed safety modernization under BAFAC standards.
- Grasshoppers:Locusta migratoria and related species serve ruminant feed applications in East African markets with limited supply chain infrastructure.
By volume, Black Soldier Fly leads. By growth pace, Mealworms are expanding most quickly.
Application:
Cost tier stratification separates commodity feed applications from specialty nutrition where formulation premiums apply.
- Fish Feed:Salmonid diets require precise amino acid balancing with methionine supplementation. Scottish and Norwegian aquafeed compounders consolidate supplier relationships around vertically integrated larvae producers with rail-linked distribution to North Sea ports.
- Poultry Feed:Broiler and layer rations incorporate insect meal at 5-15% inclusion rates pending FSSAI approvals in India. Thai poultry integrators accelerate uptake following explicit BAFAC authorization for processed insect meal.
- Swine Feed:Weaner diets show promise for gut health modulation through chitin-derived prebiotic effects. EU regulatory pathways lag aquaculture approvals, constraining near-term volume.
- Ruminant Feed:Cattle and sheep applications remain experimental with limited commercial scale due to rumen microbial adaptation requirements and methane emission interaction uncertainties.
By margin contribution, Fish Feed commands premium positioning. By addressable market expansion, Poultry Feed is gaining share fastest.
Form:
Supply concentration in processing infrastructure determines which formats achieve cost-competitive scale.
- Powder:Milled and fractionated biomass enables precise inclusion in extruded feeds. Dutch and French producers deploy automated climate-controlled systems to achieve batch consistency that displaces variation limiting compounder adoption.
- Oil:Fat extraction yields lauric acid-rich fractions with antimicrobial properties. Precise extraction thresholds prevent rancidity, demanding capex-intensive fractionation lines that concentrate supply among technology-licensing specialists.
- Whole:Intact dried larvae serve visible-ingredient positioning in superpremium pet channels. Freeze-dried formats absorb moisture premiums in fresh-frozen retail segments.
- Pellets:Compacted formats reduce handling costs for bulk aquafeed operations with automated feeding systems.
By processing throughput, Powder dominates. By value per kilogram, Oil exhibits the steepest expansion trajectory.
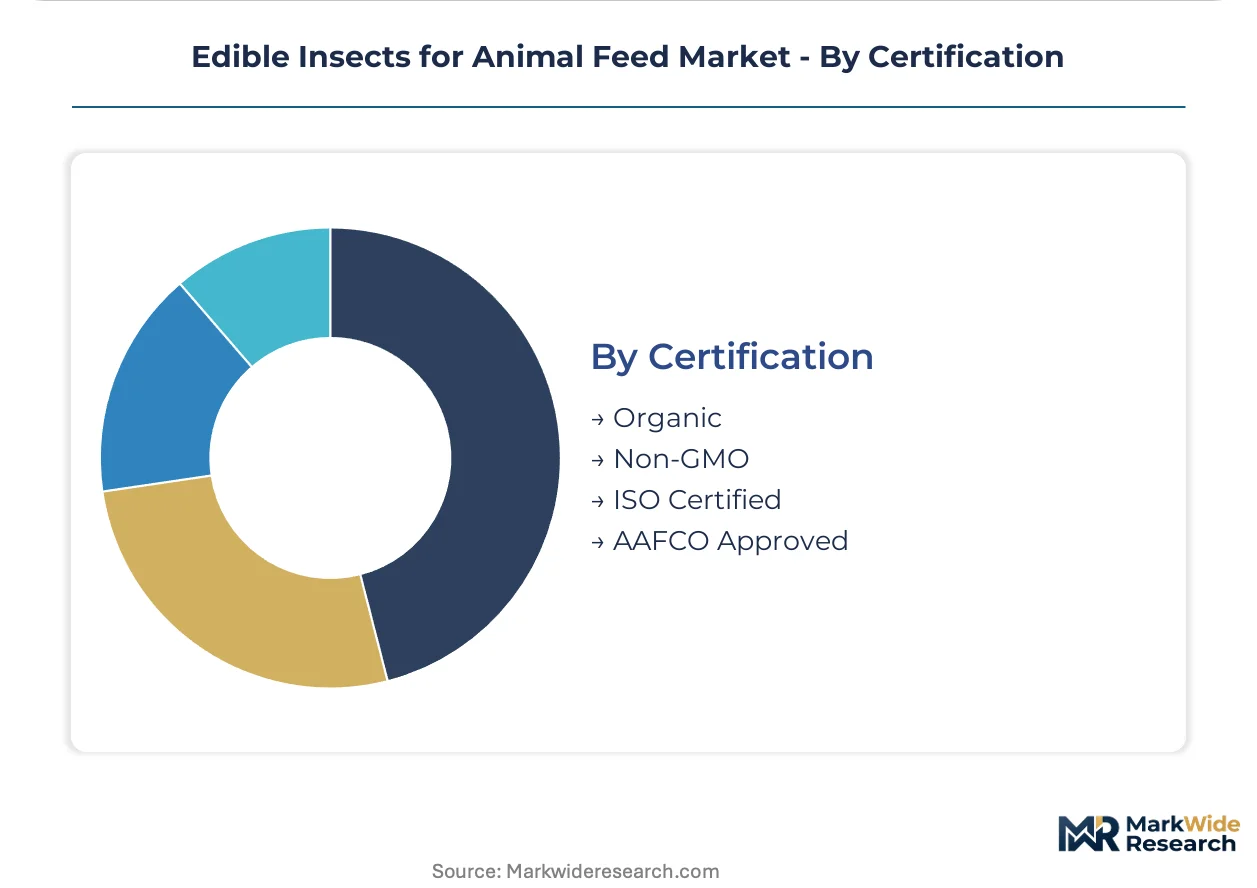
Certification:
Customer type segmentation separates institutional compounders from specialty manufacturers where label claims drive purchasing decisions.
- AAFCO Approved:Official ingredient status unlocks mainstream pet food distribution in US and Canadian markets. Certification investment separates scalable suppliers from uncertified alternatives excluded from national brand formulations.
- Organic:EU Organic Regulation compliance enables premium positioning in European retail channels. Substrate traceability requirements constrain supply expansion to certified agricultural residue streams.
- Non-GMO:Identity preservation through rearing and processing appeals to natural feed positioning in North American and European markets.
- ISO Certified:Quality management system credentials facilitate business-to-business procurement from risk-averse aquafeed multinationals.
By contract value, AAFCO Approved secures the largest offtake agreements. By certification growth, Organic climbs the fastest as EU Green Deal incentives reshape agricultural residue valorization economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold chain infrastructure underwrites Dutch insect protein re-export capacity to Norwegian aquaculture operations. Rail-linked distribution from French production clusters reaches North Sea ports within 48 hours. Thailand's Eastern Economic Corridor anchors Southeast Asian feed safety modernization.
France
French salmon feed compounders consolidate procurement around vertically integrated larvae producers with captive breeding capabilities. EFSA approvals under EU Regulation 2015/2283 unlock multi-ton offtake contracts previously blocked by regulatory uncertainty. The Amiens production cluster leverages rail distribution to reach Scottish and Norwegian aquaculture ports.
Netherlands
Dutch black soldier fly facilities deploy automated climate-controlled rearing environments with machine vision monitoring. The national feed safety framework aligns with EFSA novel feed material evaluations. Protix B.V. anchors industrial-scale larvae processing capacity in the southern provinces, extending technology licensing into Asia-Pacific markets.
Thailand
Thai poultry integrators accelerate insect protein uptake following BAFAC standards modernization explicitly permitting processed insect meal. Domestic capacity expansion targets export qualification to neighboring ASEAN feed markets. The Eastern Economic Corridor concentrates new rearing facility investments with beverage industry substrate partnerships.
United States
American aquafeed compounders navigate FDA enforcement discretion for black soldier fly in specific aquaculture applications without formal codification. This regulatory ambiguity deters institutional capital from multi-year capacity commitments. EnviroFlight exemplifies domestic larvae production archetypes awaiting clearer federal pathways.
India
Indian poultry feed manufacturers await FSSAI approvals for Hermetia illucens meal in poultry rations to access a 3 million ton annual feed market with limited domestic protein alternatives. BIS feed safety standards create divergent compliance pathways that fragment cross-border trade. Maharashtra and Gujarat concentrate pilot rearing operations targeting eventual national scale.
Edible Insects for Animal Feed Market Vendor Landscape
Concentration sits with vertically integrated specialists controlling breeding through processing operations. French and Dutch producers dominate European capacity through captive supply chains and automated rearing systems. Three archetypes define competitive positioning: species-specialized larvae producers, multi-insect portfolio operators, and technology licensors exporting equipment and know-how. Capacity expansion and strategic partnerships constitute the dominant competitive moves as stakeholders secure long-term offtake agreements.
Among France-based integrated producers, Ÿnsect SAS and Innovafeed SAS exemplify the vertically controlled archetype spanning breeding to fractionation operations. Dutch technology leader Protix B.V. occupies a licensing position extending European processing expertise into Asia-Pacific markets. These three entities anchor the supplier base through distinct geographic and operational specializations.
| Leading Market Players |
|---|
| Ÿnsect SAS |
| Innovafeed SAS |
| Protix B.V. |
| EnviroFlight |
| Entobel |
| Nasekomo |
| Hexafly |
| Aspire Food Group |
| Nutrition Technologies |
| Others |
Supply Flow & Price Mechanics
Fishmeal substitution by insect protein larvae simultaneously redistributes production geography toward France and the Netherlands while compressing per-kilogram economics through substrate cost volatility and certification tier premiums. This dual restructuring concentrates pricing power with vertically integrated breeders and fragments margin capture for substrate-dependent operators.
Pricing Analysis
Volume-discount tiering structures separate long-term offtake agreements from spot market transactions. AAFCO-certified mealworm powder commands substantial premiums over uncertified alternatives in North American pet food channels. Cost compression in standard-grade larvae meal intensifies because brewer's spent grain prices fluctuate with beverage processing cycles. Aquafeed compounders exhibit lowest price sensitivity due to fishmeal supply constraints, while small-scale poultry integrators face acute margin pressure.
Supply Chain Analysis
Strait of Malacca transit underwrites Southeast Asian substrate import routes for Thai producers. France, the Netherlands, and Thailand anchor larvae production capacity. Brewer's spent grain, fruit pulp, and agricultural residues constitute critical feedstock inputs. Single-source vulnerability concentrates in organic substrate suppliers tied to seasonal processing cycles. Distribution runs through rail-linked cold chains reaching North Sea aquaculture ports within 48 hours.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity sits with regulatory divergence creating certification-tier niches across EU, US, and Asian feed safety frameworks. Species-specialized producers capture margin premiums as aquafeed compounders reorganize procurement around amino acid specificity.
For Market Incumbents: Shield captive breeding capabilities through population genetics IP and automated rearing system deployment. Entomological expertise scarcity threatens operational continuity as university training programs lag industrial demand. Prioritize backward integration into substrate supply partnerships with beverage processors to lock in feedstock cost stability.
For New Entrants and Emerging Players: Lead with FSSAI pre-approval positioning in Indian poultry feed channels pending Hermetia illucens authorization. India's 3 million ton annual feed market offers the most penetrable geography with limited domestic protein alternatives. Pursue technology licensing arrangements with European specialists to bypass capex-intensive fractionation line requirements.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed larvae producers in France and the Netherlands holding EFSA-approved capacity expansion pipelines. Long-term viability hinges on regulatory reciprocity developments unlocking multi-jurisdictional offtake scalability. Monitor FDA codification progress for black soldier fly aquafeed applications as the critical institutional capital inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | EFSA novel feed material authorization unlocks Norwegian salmon producer contracts. |
| Backward Integration | Captive breeding operations control genetic diversity and pathogen management protocols. |
| Long-term Supply Agreement | Rail-linked distribution contracts secure 48-hour delivery windows to North Sea ports. |
| Technology Licensing | Automated rearing system exports transfer European processing expertise to Asia-Pacific markets. |
| Certification Investment | AAFCO ingredient status commands 40-60% price premiums in premium pet food channels. |
Methodological Framework
Operator-level perspectives from aquafeed procurement directors, insect rearing facility managers, regulatory affairs specialists at EFSA and FDA, and pet food formulation scientists anchored the qualitative base. Secondary validation drew from EU Regulation 2015/2283 implementation documents, BAFAC feed safety standard updates, FSSAI ingredient approval dockets, and trade flow databases tracking fishmeal substitution patterns. Bottom-up capacity assessments and top-down demand modeling were triangulated against disclosed offtake agreement volumes.
Sensitivity analysis tested projection stability across regulatory approval timeline variations, substrate cost volatility scenarios, and species substitution elasticity assumptions. Segmentation dimensions spanned insect type, application category, processed form, and certification tier. CAGRs were derived from installed capacity expansion pipelines cross-referenced with feed inclusion rate adoption curves. Fishmeal price trajectories and EU Green Deal agricultural residue valorization incentives constituted key forecast inputs.
The analysis sits within stated boundaries; outcomes outside EFSA-FDA regulatory reciprocity developments or sustained fishmeal supply constraints would require recalibration. Forecasts reflect assumptions around approval timeline continuity and substrate cost normalization. Practitioners should keep alternative scenarios live as FSSAI poultry feed authorization decisions and Thai BAFAC export qualification standards evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Remanufacturing-as-a-Service (RaaS) Market
Others
Global Duty-Free Retailing Market
Others
Ambient Assisted Living and Smart Home Market
Others
Thermal Energy Flow Metering Solutions Market
Others
Global Platform Trolley Market
Others
Bitcoin Mining Servers Market
Others
Digital Supply Chain Market
Others
Foldable Smartphone Market
Others
Smart Home Platforms Market
Others
Interference Mitigation Filters Market
Others
Commercial Aircraft Angle of Attack Sensors Market
Others
South America Orange Market
Others
Military Sensors Market
Others
Global Electroshock Weapons Market
Others
UK 3D Printing Construction Market
Others
Global Video Processing Platform Market