
 Cellular-Connected Laptops Market | 2026-2036
Cellular-Connected Laptops Market Size, Share, and Industry Trends Forecast 2026-2036
Cellular-Connected Laptops Market Insights
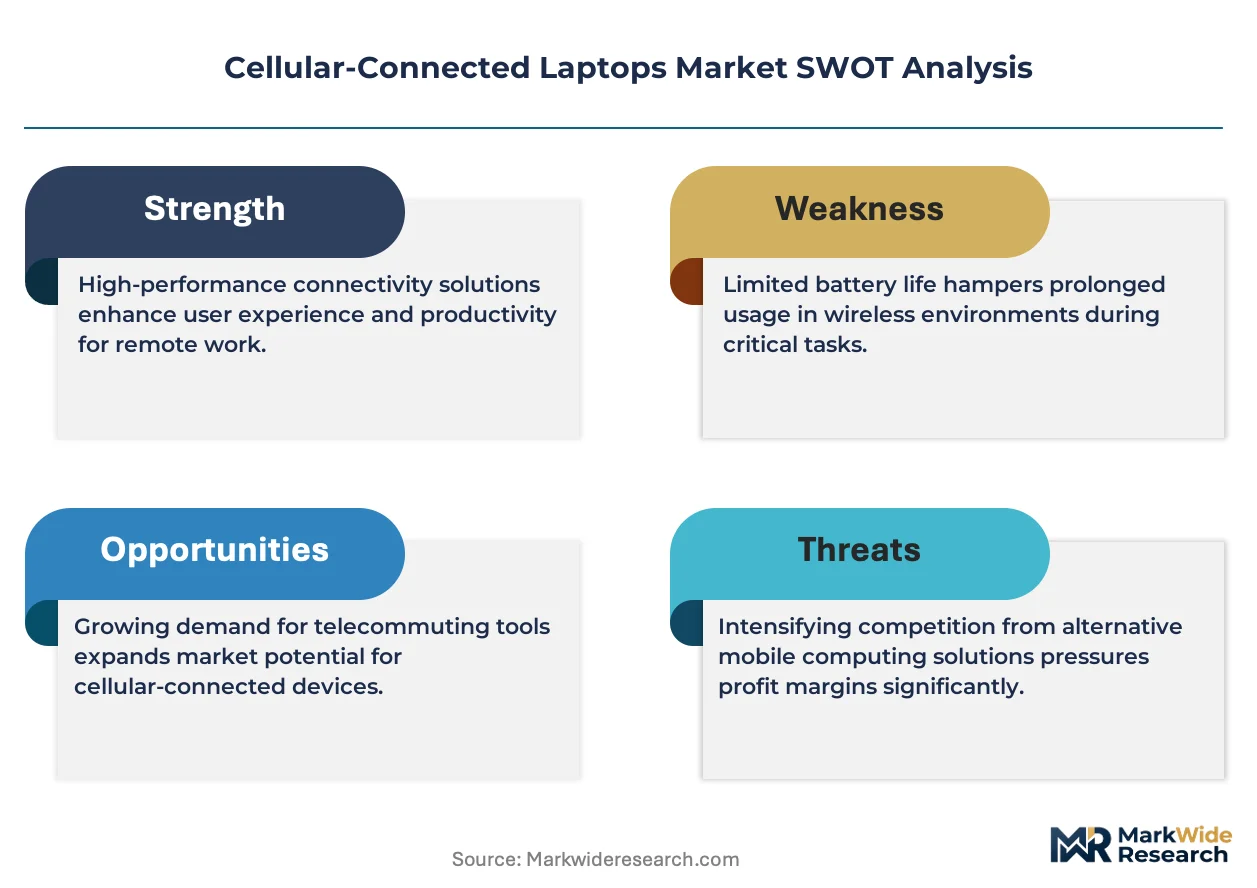
Embedded modem engineering talent scarcity is reorganizing how OEMs allocate R&D budgets across cellular-integrated product lines. Dell Technologies leverages its enterprise channel relationships to sustain large-volume contracts with Fortune 500 firms requiring seamless mobile connectivity. HP Inc. anchors its position through specialized rugged laptop variants targeting field-service verticals where terrestrial Wi-Fi remains unreliable.
Cellular-connected laptops integrate subscriber identity module (SIM) or embedded SIM (eSIM) chipsets with cellular modems operating on licensed spectrum bands, enabling internet access independent of local Wi-Fi infrastructure through direct carrier network authentication. The 5G technology segment leads value contribution as millimeter-wave and sub-6 GHz implementations command premium pricing from business professionals needing low-latency cloud application access. Ultrabooks represent the fastest-growing product type among remote workers prioritizing portability alongside persistent connectivity, while traditional laptops retain volume dominance in education procurement cycles where cost thresholds dominate selection criteria.
The Federal Communications Commission governs spectrum allocation and device certification requirements in the United States, directly constraining modem configurations and transmission power limits for products entering this market. CE marking under the European Union's Radio Equipment Directive mandates electromagnetic compatibility and safety compliance for cellular-integrated devices distributed across member states. Industry stakeholders must monitor evolving national spectrum auctions and carrier aggregation standards to anticipate which modem specifications will unlock market access in priority geographies.
Market Dynamics
The 5G standalone network buildout by telecom operators is compressing the connectivity gap between cellular laptops and tethered alternatives, forcing OEMs to recalibrate modem sourcing strategies around carrier certification timelines.
Growth Catalysts
- Enterprise hybrid work mandates:Fortune 500 procurement policies now require persistent connectivity for field-deployed knowledge workers, expanding addressable device pools beyond traditional mobile-worker segments.
- FCC spectrum reallocation:Mid-band auction proceeds in the United States are unlocking contiguous 5G channels that reduce modem engineering complexity for multi-carrier compatibility.
- eSIM provisioning automation:Over-the-air carrier switching eliminates physical SIM logistics, reducing enterprise IT deployment friction for geographically distributed workforces.
Market Restraints
- Modem chipset supply concentration:Qualcomm and MediaTek collectively control cellular baseband silicon, creating single-source vulnerability for OEMs seeking dual-vendor strategies.
- Millimeter-wave antenna integration costs:High-frequency 5G implementations require complex phased-array designs that inflate bill-of-materials relative to sub-6 GHz alternatives.
- Carrier certification bottlenecks:Each major network operator maintains proprietary testing protocols that extend product launch timelines by six to nine months.
Strategic Opportunities
- India PLI scheme for electronics manufacturing:Production-linked incentives for telecom equipment assembly create localized modem integration capacity serving South Asian demand centers.
- First responder and public safety verticals:Mission-critical communications requirements in emergency services generate premium pricing tolerance for ruggedized cellular laptops with priority network access.
- Automotive dealership service lanes:Technician diagnostic tool replacement cycles are accelerating cellular adoption where Wi-Fi penetration in service bays remains inconsistent.
Industry Challenges
- RF engineering talent scarcity:Cellular modem integration requires specialized electromagnetic expertise that OEMs struggle to retain against semiconductor industry compensation benchmarks.
- Multi-carrier firmware fragmentation:Each network operator's band aggregation requirements necessitate discrete software builds that complicate inventory management and over-the-air update pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cellular-Connected Laptops Market |
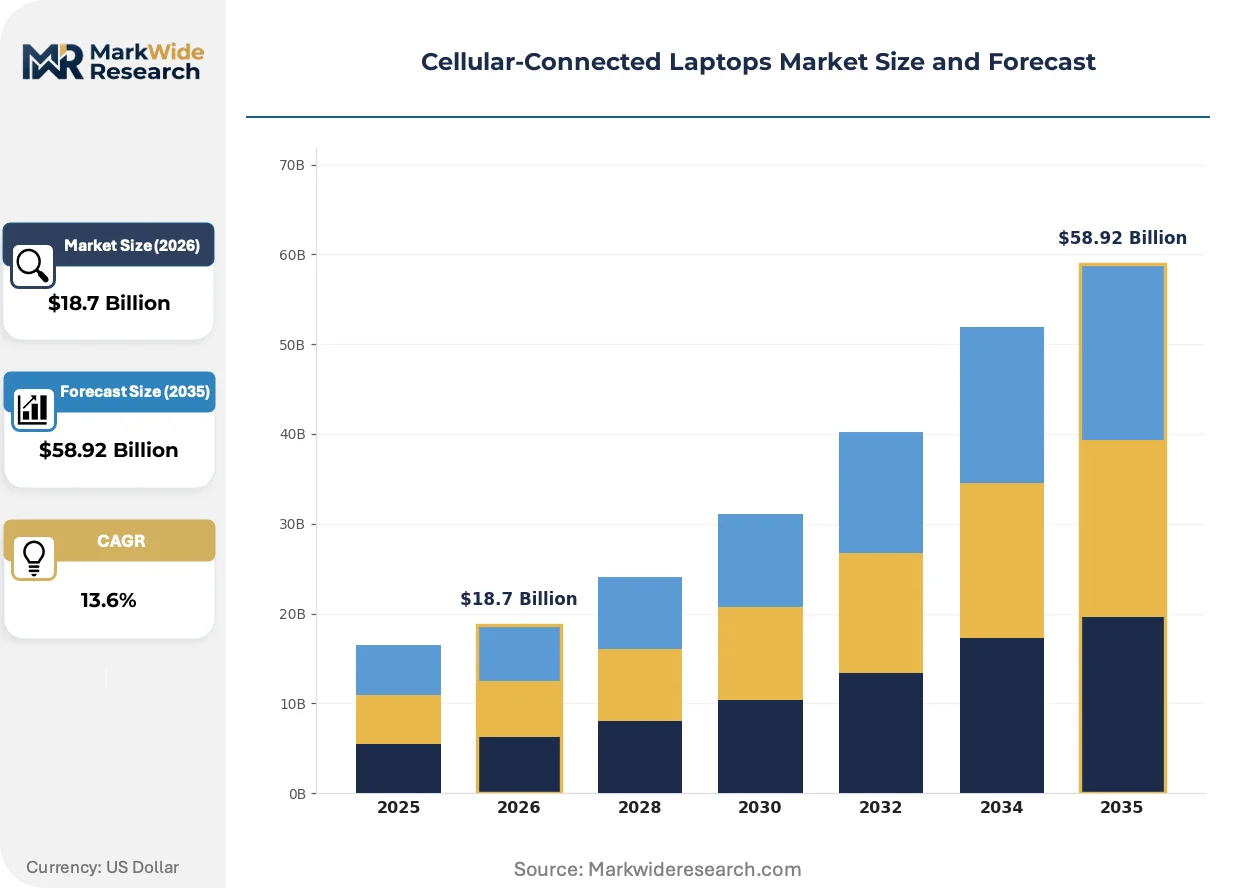
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $58.92 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 2-in-1 Devices, Ultrabooks, Traditional Laptops, Rugged Laptops End User: Business Professionals, Educators, Students, Remote Workers Technology: 5G, 4G LTE, Wi-Fi 6, Wi-Fi 5 Distribution Channel: Online Retail, Specialty Stores, Direct Sales, Telecom Partners |
| Companies Covered | Dell Technologies, HP Inc., Lenovo Group Limited, Apple Inc., Samsung Electronics Co., Ltd., Microsoft Corporation, ASUSTeK Computer Inc., Acer Inc., Huawei Technologies Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cellular-Connected Laptops Market Trends and Innovations
Hardware-software decoupling in cellular connectivity stacks is enabling faster feature deployment without full device recertification, compressing competitive response cycles among incumbent OEMs.
Embedded eSIM with integrated secure element is displacing removable SIM trays across enterprise laptop portfolios. Dell and HP have committed to soldered eSIM implementations in 2024 commercial SKUs, eliminating physical card slots that add thickness and failure points. This transition is displacing third-party SIM logistics providers from enterprise procurement workflows, compressing supply chain touchpoints and accelerating zero-touch provisioning for IT departments managing thousands of distributed endpoints.
CE marking under the EU Radio Equipment Directive now mandates cybersecurity resilience assessments for cellular-integrated devices accessing public networks. The European Commission's 2024 implementing act requires firmware update guarantees spanning minimum five-year lifecycles. German and French enterprise buyers are prioritizing OEMs with established Brussels regulatory affairs capabilities, shifting procurement weight toward vendors with dedicated EU compliance infrastructure.
Consumption-based connectivity pricing is emerging as the dominant enterprise procurement model, displacing traditional per-device data pool arrangements. Verizon and AT&T now offer API-driven usage billing that aligns connectivity costs with actual application consumption patterns. Healthcare and financial services verticals in the United States are piloting these structures for seasonal workforce fluctuations, avoiding over-provisioning during low-activity periods.
Cellular-Connected Laptops Market Segmentation
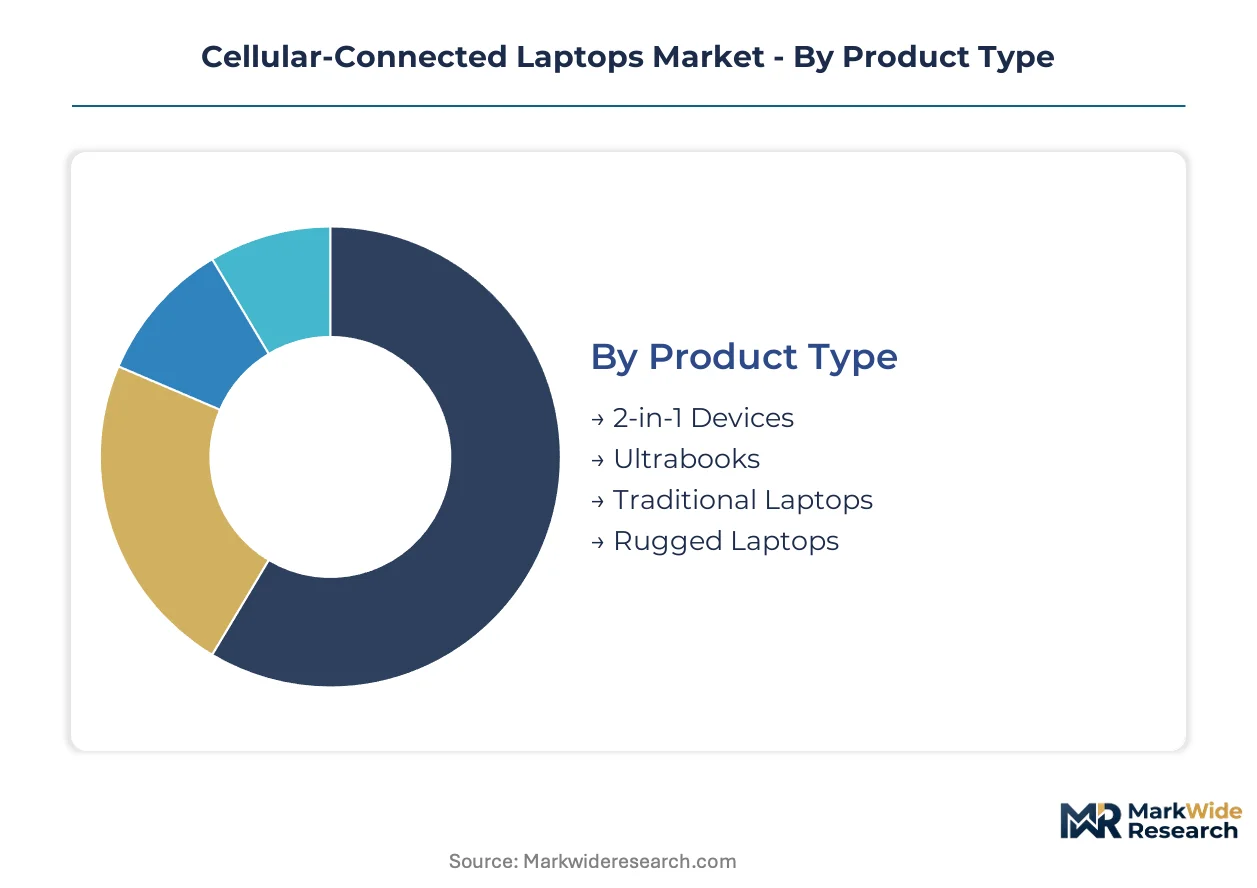
Segmentation in the cellular-connected laptops market reveals how connectivity requirements diverge across use cases, with modem specifications and form-factor trade-offs creating distinct margin architectures. Procurement patterns vary sharply between enterprise fleets requiring carrier-certified reliability and consumer segments prioritizing purchase price over subscription flexibility.
Product Type:
Margin pools concentrate in specialized form factors where engineering complexity justifies premium positioning against commoditized alternatives.
- Ultrabooks:Thin-and-light chassis designs integrate sub-6 GHz 5G modems with thermal constraints driving antenna placement innovation. Remote workers in the United States and Germany are concentrating demand here, prioritizing sub-1.2kg portability for airline cabin compliance alongside persistent connectivity.
- Rugged Laptops:MIL-STD-810H certification requirements combine with IP65 sealing to protect cellular modems in field-service deployments. Utility technicians and oil-field engineers across Texas and Alberta generate pricing tolerance for reinforced housing that sustains modem performance through vibration and thermal extremes.
- 2-in-1 Devices:Detachable keyboards and stylus integration target mobile clinicians and insurance adjusters needing tablet flexibility with laptop-grade connectivity.
- Traditional Laptops:Standard clamshell designs dominate education procurement cycles where cost thresholds override modem sophistication.
Traditional laptops hold installed capacity. Ultrabooks are rotating up the share rankings.
End User:
Volume distribution tracks hybrid work policy enforcement intensity across Fortune 500 employers and public-sector institutions.
- Business Professionals:Knowledge workers in consulting, financial services, and legal sectors require seamless handoff between office Wi-Fi and cellular networks during client site visits. Manhattan and London-based firms mandate always-connected devices for associates below the partnership tier, expanding addressable pools beyond traditional road-warrior segments.
- Remote Workers:Distributed employees without dedicated home office infrastructure depend on cellular as primary connectivity. Rural broadband gaps in the United States and Australian outback regions sustain demand for laptops with embedded modems as infrastructure substitutes rather than supplements.
- Students:Higher education procurement through campus technology stores emphasizes purchase price over modem capability, with cellular activation rates trailing enterprise segments significantly.
- Educators:K-12 district bulk purchasing prioritizes durability and manageability, with cellular connectivity typically restricted to administrative staff rather than classroom deployment.
Business professionals anchor current revenue contribution. Remote workers are expanding most quickly as hybrid policies normalize.
Technology:
Modem generation determines carrier certification timelines and spectrum band support, directly constraining geographic deployment flexibility.
- 5G:Millimeter-wave and sub-6 GHz implementations enable low-latency cloud application access with peak throughput exceeding 1 Gbps. Enterprise procurement in South Korea and the United States leads adoption, where carrier infrastructure investments support premium device positioning.
- 4G LTE:Mature modem ecosystems deliver proven compatibility across legacy carrier networks with lower bill-of-materials impact. Cost-sensitive education and developing-market segments retain volume concentration where 5G coverage remains sparse.
- Wi-Fi 6:802.11ax integration complements cellular connectivity in campus and enterprise environments with high-density access point deployment.
- Wi-Fi 5:802.11ac remains standard in entry-tier SKUs where wireless LAN performance suffices for anticipated use patterns.
4G LTE maintains shipment volume leadership. 5G is climbing the fastest as standalone network buildouts mature.
Distribution Channel:
Channel selection determines carrier relationship depth and enterprise account control, with direct engagement capturing the highest lifetime value per endpoint.
- Telecom Partners:Verizon, AT&T, and T-Mobile enterprise sales organizations bundle cellular laptops with connectivity contracts spanning 24-36 month terms. Fortune 500 procurement teams in Chicago and Atlanta favor this channel for consolidated billing and dedicated account management.
- Direct Sales:OEM field sales organizations engage multinational clients with custom imaging and zero-touch provisioning requirements. Healthcare systems and financial institutions with complex security policies concentrate here, bypassing retail intermediaries.
- Online Retail:Amazon and manufacturer e-commerce sites serve small-business and prosumer segments with standardized configurations and rapid fulfillment.
- Specialty Stores:Best Buy and regional business technology resellers provide hands-on evaluation for price-sensitive buyers.
Telecom partners dominate enterprise wallet share. Direct sales are gaining share fastest as OEMs build vertical-specific solution teams.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FCC governs spectrum allocation and device certification requirements in the United States, directly constraining modem configurations and transmission power limits for products entering this market.
United States
Enterprise procurement of always-connected devices for hybrid workforces accelerates as 5G network rollouts by Verizon and AT&T remove coverage barriers. The FCC's mid-band auction proceeds unlock contiguous 5G channels that reduce modem engineering complexity for multi-carrier compatibility. Manhattan-based consulting firms and Chicago-headquartered Fortune 500 companies mandate always-connected devices for associates, expanding addressable device pools.
Germany
Industrial field-service deployments drive demand for ruggedized cellular laptops with priority network access in manufacturing corridors. CE marking under the EU Radio Equipment Directive mandates electromagnetic compatibility and safety compliance for cellular-integrated devices distributed across member states. Bavarian automotive clusters and North Rhine-Westphalia industrial zones generate premium pricing tolerance for reinforced housing that sustains modem performance through vibration extremes.
China
Domestic 5G infrastructure buildout by MIIT-licensed operators creates localized demand for sub-6 GHz implementations with proven carrier compatibility. GB standards and MIIT equipment certification requirements govern radio transmission parameters and electromagnetic emissions thresholds for devices entering the domestic market. Yangtze River Delta electronics manufacturing hubs and Pearl River Delta assembly clusters concentrate modem integration capacity serving Asia-Pacific demand centers.
Japan
Mobile clinicians and insurance adjusters needing tablet flexibility with laptop-grade connectivity concentrate demand in 2-in-1 form factors. METI industrial policy and JIS standards frameworks shape procurement criteria for public-sector technology refresh cycles. Tokyo-based financial services firms and Osaka-area logistics operators prioritize seamless handoff between office Wi-Fi and cellular networks during client site visits.
South Korea
Enterprise procurement leads 5G adoption where carrier infrastructure investments support premium device positioning for low-latency cloud application access. MFDS equipment registration and spectrum licensing by the national telecom regulator constrain modem specifications for products entering the domestic market. Seoul Capital Area technology campuses and Busan-Ulsan industrial zones anchor demand for millimeter-wave implementations with peak throughput exceeding 1 Gbps.
Cellular-Connected Laptops Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with consolidated enterprise channel relationships determining account control. The upper tier captures Fortune 500 procurement through direct sales organizations with custom imaging capabilities. Specialist players concentrate in ruggedized form factors and education procurement cycles. Competitive moves center on eSIM provisioning automation and backward integration into modem firmware development.
Within the integrated tier, Dell Technologies and HP Inc. exemplify vendors leveraging enterprise channel relationships to sustain large-volume contracts. Lenovo Group Limited occupies a position bridging commercial and consumer segments with geographic diversification. These three anchors represent distinct strategic postures: Dell through Fortune 500 direct engagement, HP through ruggedized vertical specialization, and Lenovo through scale-driven portfolio breadth.
| Leading Market Players |
|---|
| Dell Technologies |
| HP Inc. |
| Lenovo Group Limited |
| Apple Inc. |
| Samsung Electronics Co., Ltd. |
| Microsoft Corporation |
| ASUSTeK Computer Inc. |
| Acer Inc. |
| Huawei Technologies Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements between OEMs and Qualcomm lock in modem supply access while providing price visibility across multi-year enterprise refresh cycles, insulating procurement teams from spot-market volatility in cellular baseband silicon.
Pricing Analysis
Contract-based long-term offtake dominates enterprise procurement, with Verizon and AT&T bundling devices into 24-36 month connectivity subscriptions. Price differentiation hinges on carrier certification tier and ruggedization grade, with MIL-STD-810H variants commanding substantial premiums over standard commercial SKUs. Cost compression in education-tier 4G LTE models is intensifying because MediaTek modem alternatives undercut Qualcomm solutions on bill-of-materials. Students and K-12 districts exhibit highest price sensitivity, while first responder agencies demonstrate lowest sensitivity due to mission-critical reliability requirements.
Supply Chain Analysis
Inventory lead times for millimeter-wave antenna modules extend carrier certification timelines by six to nine months, constraining OEM launch flexibility. Modem integration capacity concentrates in China, Taiwan, and South Korea, with Yangtze River Delta facilities handling sub-6 GHz implementations and South Korean fabs managing premium 5G silicon. The supply chain rests on concentrated gallium arsenide substrate sourcing and specialized RF filter components. Single-source vulnerability around Qualcomm baseband dominance creates structural risk. Distribution runs through telecom partner enterprise sales organizations with consolidated billing infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward Fortune 500 procurement teams as enterprise fleet consolidation reduces OEM account fragmentation, compressing pricing leverage for device vendors.
For Market Incumbents: Secure carrier certification exclusivity windows through accelerated firmware co-development with Verizon and AT&T, insulating against emerging entrants lacking regulatory affairs depth. Prioritize backward integration into eSIM provisioning platforms to displace third-party connectivity orchestrators from enterprise IT workflows.
For New Entrants and Emerging Players: Differentiate on ruggedized form factors for utility and oil-field verticals where HP and Dell maintain limited SKU breadth. Target automotive dealership service lanes as the most penetrable segment, leveraging inconsistent Wi-Fi coverage in service bays. Pursue direct sales to mid-market fleet operators bypassing telecom partner channel complexity.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among OEMs with captive eSIM provisioning platforms and multi-year enterprise connectivity contracts. Long-term viability favors vendors with established Brussels regulatory infrastructure and MIIT certification capabilities in Beijing. Monitor India PLI scheme utilization rates as the inflection signal for localized modem integration capacity scaling.
| Strategic Initiative | Industry Significance |
|---|---|
| eSIM Platform Integration | Eliminates physical SIM logistics and accelerates zero-touch enterprise provisioning. |
| Carrier Certification Acceleration | Compresses Verizon and AT&T testing timelines from nine months to four months. |
| Ruggedized SKU Expansion | Captures utility and oil-field premiums where terrestrial connectivity fails. |
| India Manufacturing Localization | Accesses PLI incentives for telecom equipment assembly serving South Asian demand. |
| EU Cybersecurity Compliance Investment | Satisfies CE marking mandates for five-year firmware update guarantees. |
Research Methodology
The analysis maps 5G modem implementations, eSIM provisioning platforms, ruggedized form factors, and carrier-certified enterprise SKUs, each validated through procurement directors at Fortune 500 firms, RF engineering leads at Tier 1 OEMs, and enterprise sales executives at major telecom operators. Primary interview findings were cross-referenced against FCC equipment authorization databases, MIIT certification registries, and SEC 10-K disclosures from Dell Technologies, HP Inc., and Lenovo Group Limited. Bottom-up volume estimates triangulated with top-down connectivity subscription forecasts.
Consistency checks validated model outputs against carrier-reported 5G device attachment rates and enterprise mobility spend benchmarks from Gartner and IDC. The analytical framework segments by modem generation, form factor ruggedization tier, end-user vertical, and distribution channel depth across the projection horizon. CAGRs were derived from connectivity subscription growth curves and enterprise refresh cycle compression patterns. Forecast inputs incorporated FCC spectrum auction timelines and EU Radio Equipment Directive implementing act compliance costs.
The analysis sits within stated boundaries; outcomes outside sustained 5G standalone network buildout velocity or carrier aggregation standard convergence would require recalibration. Forecasts reflect documented assumptions around enterprise hybrid work policy permanence and modem chipset supply concentration. Specific risk factors include Qualcomm baseband supply disruption, mid-band spectrum reallocation delays, and EU cybersecurity resilience assessment implementation strictness. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Edge Computing in Healthcare Market
Others
Coriolis Meters Market
Others
United States Printed Signage Market
Others
Aerospace Tester Market
Others
Heat Treatment Furnace Market
Others
North America Industrial Wearable Devices Market
Others
Tanned Fish Skin Leather Market
Others
Calendered Polyvinyl Chloride Flexible Films Market
Others
LED Packaging Market
Others
Global Solder Balls Market
Others
Middle East and Africa Electric Vehicle Battery Electrolyte Market
Others
North America Luxury Car Market
Others
United States Smart Homes Market
Others
China Online Gambling Market
Others
Gym Wipes Market
Others
Global Application Testing Services Market