
 Inorganic Tin Chemicals Market | 2026-2036
Inorganic Tin Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Inorganic Tin Chemicals Market Analytics
Technical-grade maintenance contracts and purity-certification subscriptions is hardening the commercial model around inorganic tin chemicals. Songxiang Chemical leverages captive smelter access to sustain cost leadership in stannous oxide batches. Yunnan Tin Company Group Limited anchors Chinese domestic supply through integrated mine-to-chemical operations. PT. Timah Industri competes on archipelagic logistics, controlling port-linked distribution across Indonesian industrial zones.
Inorganic tin chemicals encompass refined tin-based compounds including stannous oxide, stannic oxide, and tin chloride, typically manufactured via acid dissolution of metallic tin followed by controlled precipitation or calcination to achieve specified oxidation states and particle sizes between 1-50 microns for catalyst and surface-coating applications. Plastics applications currently dominate value capture as PVC stabilizer demand persists, while electronics-grade tin chloride segments exhibit the fastest structural expansion driven by semiconductor electroplating requirements. Powder delivery modes retain margin concentration in specialty coatings, whereas bulk liquid formats serve commoditized agricultural and construction chemical blending operations.
REACH registration mandates from ECHA govern stannous oxide import thresholds into European chemical processing facilities, while China's MEE enforces wastewater discharge limits that elevate purification costs for tin chloride producers operating near the Yangtze industrial belt. Indonesia's national mineral regulator imposes export licensing requirements on refined tin chemical derivatives, restricting market access for unregistered foreign suppliers. Stakeholders must monitor evolving battery-grade tin specification thresholds as sodium-ion and solid-state cell architectures redefine purity requirements ahead of commercial scale decisions.
Market Dynamics
Semiconductor electroplating specifications are compressing acceptable impurity thresholds for tin chloride below 10 ppm, forcing purification capex cycles across Southeast Asian chemical processors serving electronics manufacturing corridors.
Growth Catalysts
- REACH registration mandates:ECHA compliance requirements for stannous oxide imports into European chemical processing facilities are elevating certified-purity premiums and locking in subscription-based technical service relationships with established suppliers.
- Electronics manufacturing corridors:Indonesia and Malaysia are concentrating regional demand through expanding semiconductor packaging and PCB fabrication clusters requiring high-purity tin chloride for barrier-layer electroplating.
- Dual carbon goals:China's MEE wastewater discharge limits near the Yangtze industrial belt are accelerating membrane filtration adoption among tin chloride producers, creating technical differentiation for compliant batches.
Market Restraints
- Raw tin price volatility:London Metal Exchange tin contract fluctuations transmit directly into stannous oxide batch economics, compressing margin visibility for non-integrated chemical processors lacking captive smelter access.
- Archipelagic logistics concentration:Indonesian port-linked distribution networks controlled by domestic incumbents restrict foreign supplier market access through national mineral regulator export licensing requirements on refined tin chemical derivatives.
- Sodium-ion battery substitution:Emerging solid-state and sodium-ion cell architectures are redefining battery-grade tin specification thresholds ahead of commercial scale decisions, creating demand uncertainty for tin oxide anode precursors.
Strategic Opportunities
- Solid-state battery qualification:Pre-commercial specification-setting for tin-based anode materials in next-generation cell architectures offers first-mover certification advantages for oxide producers meeting emerging purity benchmarks.
- Technical-grade service subscriptions:Maintenance contracts bundling purity certification with just-in-time powder delivery are hardening recurring revenue models and raising switching costs among specialty coating end-users.
- Integrated mine-to-chemical operations:Backward integration into upstream tin concentrate processing enables cost leadership in stannous oxide batches through captive feedstock control and waste-stream valorization.
Industry Challenges
- Electroplating chemistry expertise scarcity:Semiconductor fabs require tin chloride suppliers to field on-site technical support teams capable of bath chemistry optimization, constraining scalable deployment for mid-cap chemical processors.
- Multi-jurisdiction certification timelines:Simultaneous REACH, GB standard, and emerging battery-grade qualification pathways impose parallel testing burdens that extend product launch cycles by 18-24 months for new oxide grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inorganic Tin Chemicals Market |
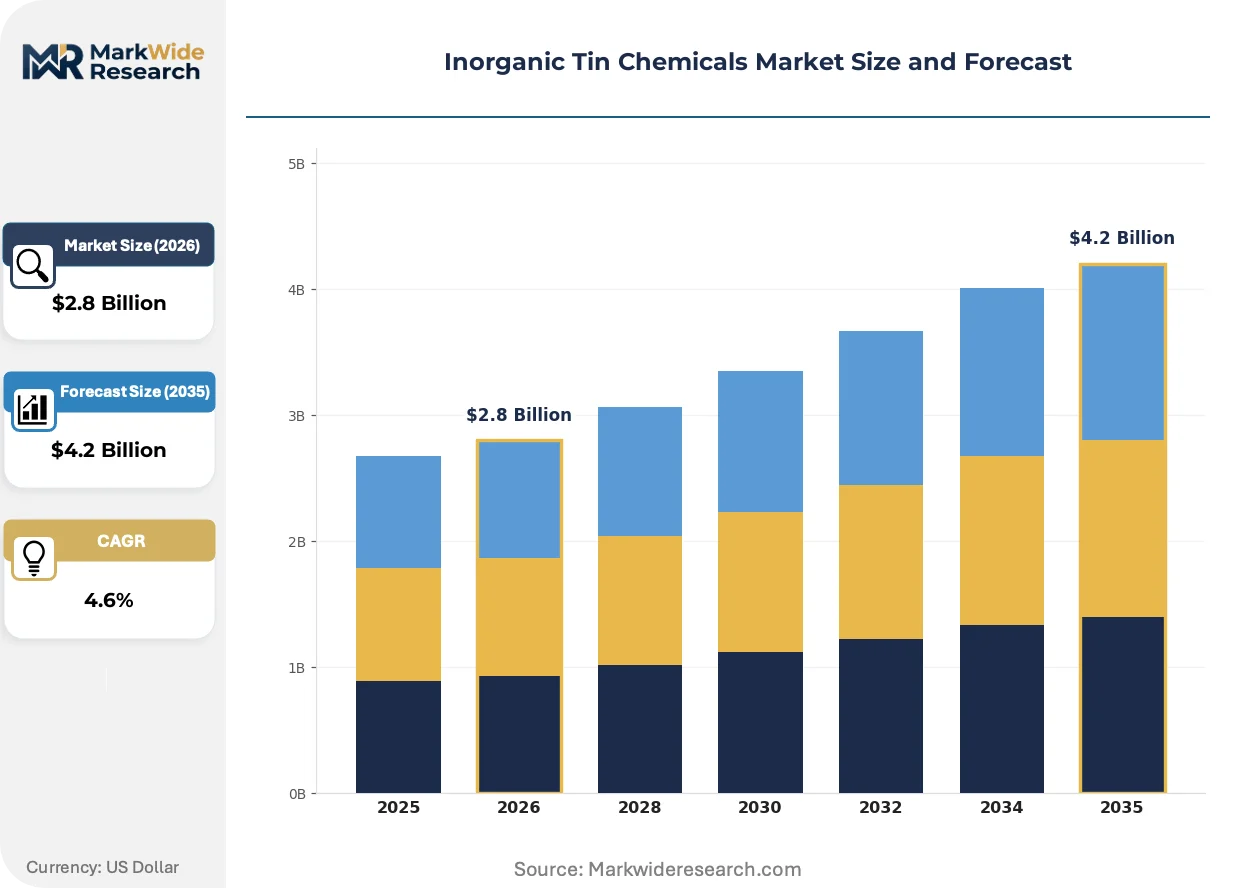
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stannous Oxide, Stannic Oxide, Organotin Compounds, Tin Chloride Application: Plastics, Coatings, Electronics, Healthcare End Use Industry: Automotive, Chemical, Agriculture, Construction Delivery Mode: Bulk, Liquid, Powder, Granular |
| Companies Covered | Songxiang Chemical, Dow, Yunnan Tin Company Group Limited, Westman Chemicals, Mason Corporation, TIB Chemicals, Showa, Lorad Chemical Corporation, PT. Timah Industri, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inorganic Tin Chemicals Market Evolving Landscape
Continuous precipitation control systems and real-time oxidation-state monitoring are displacing batch-wise manufacturing in tin chemical production, enabling tighter particle size distribution for catalyst applications.
Closed-loop acid recovery systems with automated pH titration are automating wastewater minimization in tin chloride production facilities. Malaysian and Indonesian electroplating chemical processors are adopting these systems fastest to preempt MEE-equivalent discharge enforcement. The technology is compressing variable cost structures for integrated producers while raising compliance barriers for tolling operators.
EU F-Gas Regulation phase-down schedules are accelerating hydrofluorocarbon replacement in tin oxide sputtering target manufacturing processes. German and French thin-film solar coating facilities now specify low-GWP alternative precursors in procurement tenders. This regulatory pressure is diverting R&D budgets toward chloride-based vapor deposition chemistries that bypass fluorinated intermediates entirely.
Specification-driven supplier consolidation is concentrating procurement authority among electronics manufacturing services firms. Tier-one semiconductor packaging houses in Penang and Batam now mandate quarterly purity audits and locked-in technical service clauses that exclude spot-market sourcing. This behavioral shift is fragmenting the merchant market into certified-partnership and commodity-residual tiers with diverging margin structures.
Inorganic Tin Chemicals Market Segmentation
Segmentation in inorganic tin chemicals reveals how capital intensity and purity requirements fragment competitive positioning across product tiers. Each dimension exposes different margin structures and supplier capabilities.
Product Type:
Capital intensity varies sharply across oxidation states and molecular complexity, with electroplating-grade chlorides demanding the most sophisticated purification infrastructure.
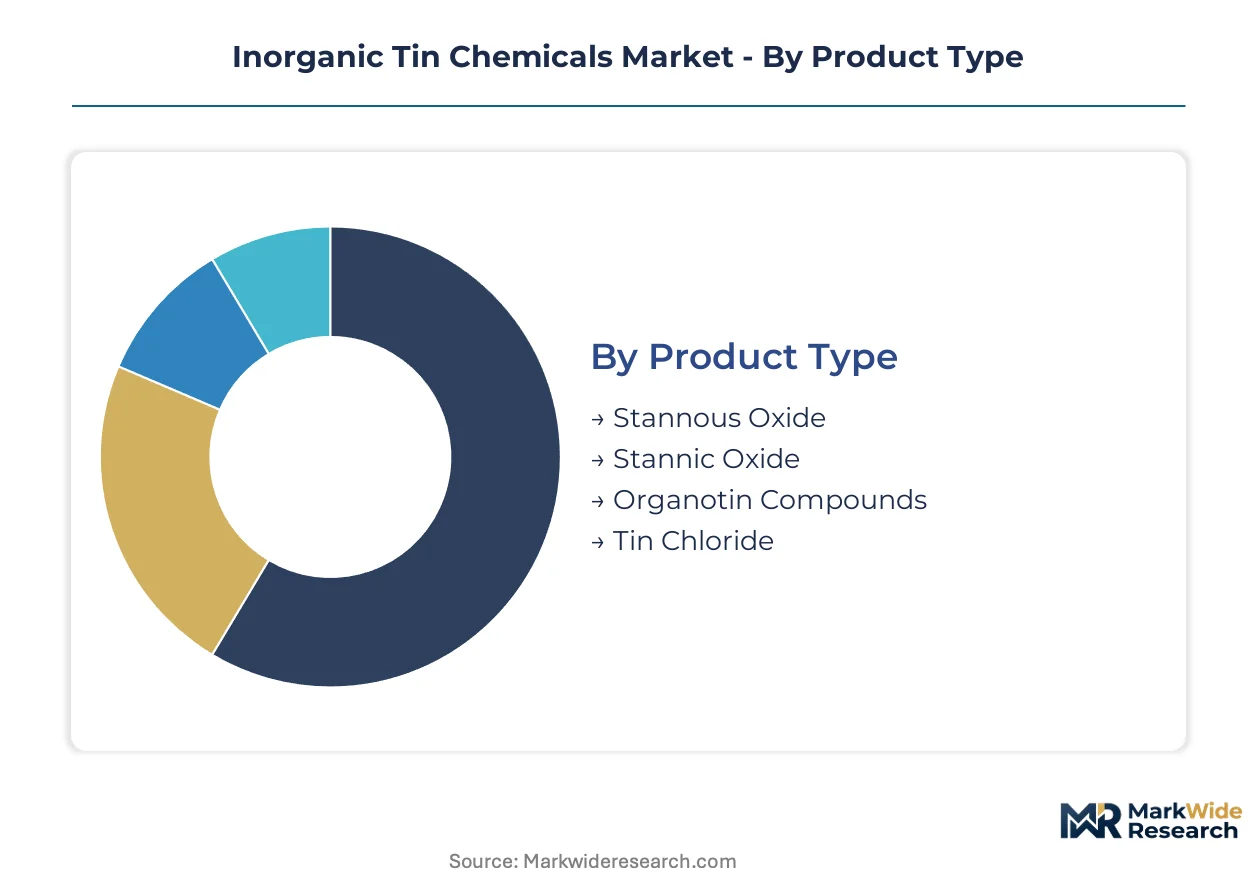
- Stannous Oxide:Divalent tin oxide produced via controlled calcination of precipitated tin hydroxide, typically specified at 99.5% purity for catalyst applications. Demand concentrates in Chinese PVC stabilizer manufacturing along the Yangtze corridor, where REACH-registered batches command certified-purity premiums over technical-grade alternatives.
- Tin Chloride:Stannous and stannic chloride formulations manufactured through acid dissolution of metallic tin followed by crystallization or anhydrous processing. Semiconductor electroplating specifications in Penang and Batam are compressing impurity thresholds below 10 ppm, forcing Southeast Asian processors into membrane filtration capex cycles.
- Stannic Oxide:Tetravalent oxide serving ceramic opacifier and sensor applications with moderate purity requirements.
- Organotin Compounds:Tin-carbon bonded derivatives for biocidal and catalytic uses, constrained by ECHA authorization restrictions on certain alkyltin formulations.
Most installed capacity flows through Stannous Oxide. Expansion is steepest in Tin Chloride.
Application:
Application segmentation tracks how end-use purity requirements stratify pricing power and technical service intensity.
- Electronics:Semiconductor packaging and PCB fabrication demand high-purity tin chloride for barrier-layer electroplating, with quarterly purity audits now mandatory at tier-one Malaysian and Indonesian contract manufacturers.
- Plastics:PVC thermal stabilizer applications dominate volume throughput, with stannous oxide batches serving extrusion and calendering operations across Chinese construction material supply chains.
- Coatings:Specialty powder coatings and thin-film solar applications specifying low-GWP precursor alternatives under EU F-Gas Regulation phase-down schedules.
- Healthcare:Pharmaceutical-grade tin compounds for diagnostic reagents and dental applications, governed by multi-j pharmacopeia compliance.
Plastics absorbs the highest volume throughput. Electronics generates the steepest margin expansion trajectory.
End Use Industry:
Industry verticals differentiate procurement patterns between specification-driven contract manufacturing and price-sensitive commodity blending.
- Automotive:Underhood plastics stabilization and sensor ceramics drive consistent stannic oxide demand from tier suppliers in Germany and Japan.
- Chemical:Catalyst and intermediate manufacturing for fine chemical synthesis, with batch purity certification locked into technical service subscriptions.
- Agriculture:Commoditized organotin biocide blending operations favor bulk liquid delivery formats with minimal technical support.
- Construction:PVC pipe and window profile extrusion serving price-sensitive regional markets with standard-grade stabilizer specifications.
Chemical industry procurement concentrates the most certified-partnership relationships. Automotive is climbing the fastest on semiconductor-linked electroplating demand.
Delivery Mode:
Physical form factors align with customer scale, handling infrastructure, and inventory turnover requirements.
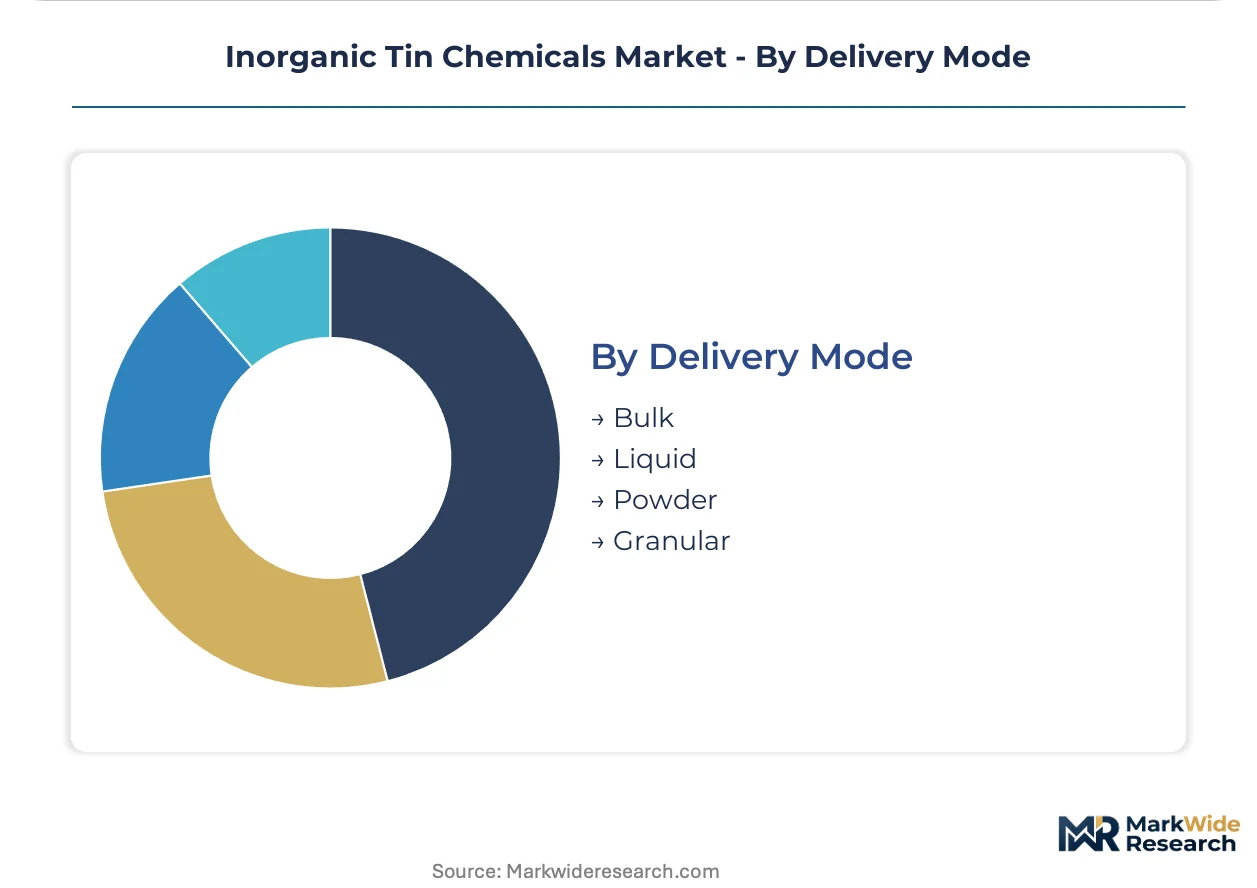
- Powder:Micronized oxide and chloride formulations for specialty coating and catalyst applications, delivered in moisture-barrier packaging with particle size distribution certificates.
- Bulk:Tanker and railcar shipments of liquid tin chloride serving high-volume electroplating operations and agricultural chemical blenders.
- Liquid:Aqueous and alcoholic tin chloride solutions for just-in-time semiconductor fab delivery with automated bath chemistry monitoring.
- Granular:Free-flowing oxide granules for ceramic and glass manufacturing with reduced dusting characteristics.
Bulk formats move the highest tonnage. Powder commands the steepest per-kilogram premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands the largest installed capacity for stannous oxide, yet Indonesia and Malaysia are capturing the fastest margin expansion through semiconductor electroplating corridors. Regulatory divergence across these manufacturing hubs is fragmenting certification requirements and reshaping supplier access patterns.
China
Dual carbon goals enforced by MEE are elevating wastewater treatment costs for Yangtze River Delta tin chloride producers. GB standard compliance for battery-grade oxide precursors is tightening ahead of sodium-ion commercialization. Jiangsu and Zhejiang provinces concentrate the highest density of PVC stabilizer manufacturing, where REACH-registered batch premiums now separate certified from technical-grade suppliers.
Indonesia
National mineral regulator export licensing restricts foreign supplier participation in refined tin chemical derivatives. PT. Timah Industri controls archipelagic port-linked distribution networks serving Batam semiconductor packaging clusters. The Riau Islands industrial zone is expanding electroplating chemical capacity to meet quarterly purity audit requirements from tier-one contract manufacturers.
Malaysia
Penang's electronics manufacturing services sector mandates locked-in technical service clauses that exclude spot-market tin chloride sourcing. Closed-loop acid recovery systems are spreading fastest here to preempt MEE-equivalent discharge enforcement. The Northern Corridor Economic Region is consolidating procurement authority among certified-partnership tiers with diverging margin structures.
Germany
EU F-Gas Regulation phase-down schedules are diverting R&D budgets toward chloride-based vapor deposition chemistries at thin-film solar coating facilities. ECHA REACH registration mandates govern stannous oxide import thresholds into chemical processing facilities. Bavarian and Baden-Württemberg industrial zones specify low-GWP alternative precursors in procurement tenders for sputtering target manufacturing.
United States
EPA discharge monitoring and OSHA process safety management shape tin chemical handling protocols at electroplating operations. Semiconductor fabs in Arizona and Texas require on-site technical support teams capable of bath chemistry optimization. The Southwest manufacturing corridor is experiencing specification-driven supplier consolidation among electronics manufacturing services firms.
Inorganic Tin Chemicals Market Competitive Landscape
Top-tier vendors anchor certified-partnership supply relationships with tier-one semiconductor packaging houses, while mid-cap tolling operators struggle to field the electroplating chemistry expertise required for scalable deployment. The market structures around three strategic archetypes: integrated mine-to-chemical producers with captive smelter access, archipelagic logistics controllers leveraging port-linked distribution, and specialty coating specialists bundling purity certification with technical service subscriptions. Dominant competitive moves include backward integration into upstream tin concentrate processing and membrane filtration capex cycles to meet compressed impurity thresholds below 10 ppm.
Among Asia-Pacific-based integrated producers, Yunnan Tin Company Group Limited and PT. Timah Industri exemplify contrasting geographic advantages. The former represents Chinese domestic supply anchoring through mine-to-chemical operations spanning concentrate processing to oxide batch production. The latter occupies a position within archipelagic logistics control, leveraging Indonesian mineral regulator licensing to restrict foreign competitor access. Songxiang Chemical sits within the cost leadership archetype, sustaining position through captive smelter access for stannous oxide manufacturing.
| Leading Market Players |
|---|
| Songxiang Chemical |
| Dow |
| Yunnan Tin Company Group Limited |
| Westman Chemicals |
| Mason Corporation |
| TIB Chemicals |
| Showa |
| Lorad Chemical Corporation |
| PT. Timah Industri |
| Others |
Value Network & Pricing Analysis
Captive smelter integration by Chinese producers anchors cost leadership in stannous oxide batches while compressing margin visibility for non-integrated tolling operators across Southeast Asian electroplating corridors. This upstream control pattern concentrates pricing power among mine-to-chemical operators like Yunnan Tin Company Group Limited, forcing merchant processors into purity-certification subscriptions to defend position.
Pricing Analysis
Capacity additions in Indonesia and Malaysia are reshaping price floors for high-purity tin chloride as membrane filtration capex cycles elevate batch economics. Three-tier pricing structure across REACH-registered premium, GB-standard mid-tier, and technical-grade economy levels separates certified-partnership supply from spot-market sourcing. Cost compression in technical-grade batches is intensifying because London Metal Exchange tin contract volatility transmits directly into non-integrated processor margins. Construction sector PVC stabilizer buyers exhibit highest price sensitivity, while semiconductor fabs in Penang and Batam prioritize locked-in technical service clauses over unit cost.
Supply Chain Analysis
Dual-sourcing qualification mandates from tier-one electronics manufacturing services firms are fragmenting supplier tiers into certified-partnership and commodity-residual categories with diverging margin structures. Supply concentrates in China, Indonesia, and Malaysia, with archipelagic port-linked distribution networks controlled by domestic incumbents. Raw material dependencies draw from tin concentrate feedstock, hydrochloric acid reagents, and membrane filtration membranes. Single-source vulnerability runs through Indonesian mineral regulator export licensing restrictions on refined tin chemical derivatives. Distribution runs through port-linked warehousing clusters serving Batam and Penang semiconductor packaging zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where MEE wastewater discharge enforcement in China's Yangtze River Delta elevates purification costs faster than equivalent regulatory pressure builds in Malaysian and Indonesian industrial zones.
For Market Incumbents: Cement certified-partnership lock-ins with quarterly purity audits and locked-in technical service clauses that exclude spot-market competitors from tier-one semiconductor packaging procurement. Deepen captive smelter integration into upstream tin concentrate processing to sustain cost leadership against London Metal Exchange volatility. Prioritize membrane filtration capex cycles ahead of compressed impurity threshold deadlines from semiconductor fabs. For New Entrants and Emerging Players: Launch via technical-grade service subscription models bundling purity certification with just-in-time powder delivery to specialty coating end-users in chemical and automotive sectors. Target sodium-ion battery precursor qualification pathways where specification thresholds remain unsettled and first-mover certification advantages are attainable. Exploit archipelagic logistics gaps through port-linked distribution partnerships with Indonesian mineral regulator licensing compliance. For Investors and Strategic Acquirers: Consolidation pressure builds where electroplating chemistry expertise scarcity constrains scalable deployment for mid-cap tolling operators lacking on-site technical support capabilities. Long-term viability centers on integrated mine-to-chemical producers with captive feedstock control and waste-stream valorization infrastructure. Acquisition target archetype: Southeast Asian processors with membrane filtration installed capacity and existing REACH registration pathways. Signal to watch: battery-grade tin oxide specification finalization from sodium-ion and solid-state cell architecture developers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tin Concentrate Processing | Captive feedstock control insulates margin from London Metal Exchange volatility for Yangtze Delta producers. |
| Membrane Filtration Capacity Expansion | Compliance with MEE wastewater discharge limits creates technical differentiation for tin chloride batches. |
| REACH Registration Pathway Completion | ECHA certified-purity premiums lock in subscription-based technical service relationships with European chemical processors. |
| Long-term Supply Agreement with Semiconductor Fabs | Locked-in technical service clauses exclude spot-market sourcing from tier-one Penang and Batam contract manufacturers. |
| Joint Venture for Archipelagic Distribution Control | Indonesian mineral regulator licensing restricts foreign competitor access to Batam electroplating corridors. |
Research Methodology
Bottom-up electroplating and PVC stabilizer modeling reconciled against top-down tin chemical production capacity tracking forms the analytical core of this study. Primary interviews with plant managers at Southeast Asian chemical processors, procurement leads at Malaysian electronics manufacturing services firms, distribution channel partners in Indonesian port-linked networks, and technical R&D directors at Chinese oxide producers combined with secondary validation from customs and trade data, SEC 10-K filings of integrated tin producers, ECHA REACH registration databases, and Yangtze River Delta environmental discharge records. Triangulation between demand-side application forecasts and supply-side capacity announcements ensures consistency across the analysis window.
Input-output matrices mapping tin concentrate feedstock flows through acid dissolution, precipitation control, and calcination stages to finished oxide and chloride batch outputs structure the projection framework. Segmentation dimensions span oxidation state chemistry, end-use industry vertical, purity certification tier, and regional production hub concentration. CAGRs derive from installed capacity utilization rates, purity threshold compression timelines, and battery-grade specification evolution trajectories across the modeling period. Forecast inputs include semiconductor fab expansion announcements in Penang and Batam, MEE enforcement intensity indicators, and sodium-ion cell architecture commercialization signals.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated battery-grade specification finalization or abrupt London Metal Exchange tin price discontinuities. Deviation in Indonesian mineral regulator export licensing enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Corn Fiber Market
Others
Asia-Pacific Air Separation Unit Market
Others
Bakery Packaging Market
Others
Europe Intercom Devices Market
Others
Solar Animal Repeller Market
Others
Sunflower Husk Pellets Market
Others
Saudi Arabia Laser Hair Removal Market
Others
Saudi Arabia Cat Food Market
Others
Smart Home Controller Market
Others
Global Essential Oils and Plant Extracts for Livestock Market
Others
US Legal Services Market
Others
Middle East and Africa Surface Analysis Market
Others
Security Envelopes Market
Others
Mine Rescue Vehicle Market
Others
Solar Animal Repellent Market
Others
Global Transparent Plastics Market