
 Cloud-Based Streaming Services Market | 2026-2036
Cloud-Based Streaming Services Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud-Based Streaming Services Market Outlook
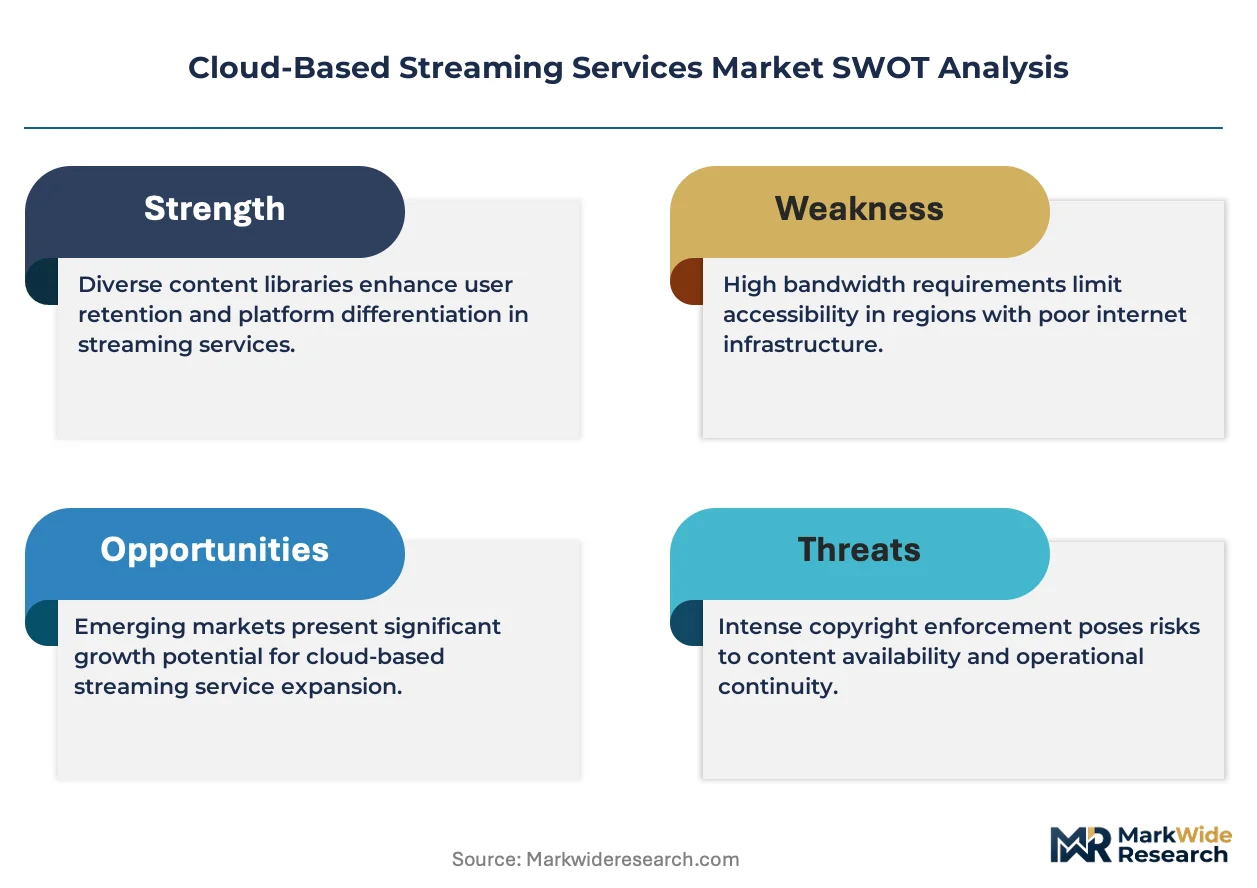
Edge computing integration with content delivery networks is tilting the infrastructure layer toward distributed processing nodes. Netflix leverages proprietary Open Connect appliances to reduce transit costs and improve buffer ratios. Amazon Web Services anchors hyperscale capacity through its CloudFront and Elemental MediaConvert services. Google Cloud differentiates through YouTube's built-in infrastructure and AI-powered encoding pipelines.
Cloud-based streaming services deliver audiovisual content over IP networks using adaptive bitrate protocols, content delivery networks, and containerized encoding farms that transcode source media into multiple resolutions and codecs for device-agnostic playback. These systems serve commercial purposes spanning entertainment consumption, enterprise communications, and interactive broadcasting. Video streaming occupies the largest revenue pool among service types, while live streaming captures the fastest expansion as latency compression techniques mature. Enterprise end users represent an underpenetrated segment relative to individuals, with media companies consolidating licensed content spend toward exclusive original programming.
FCC net neutrality rulings in the United States shape last-mile delivery economics and interconnection fee structures for streaming platforms. EMA data governance standards and GDPR cross-border transfer rules in Europe constrain viewer analytics deployment and personalization engine training. India's TRAI tariff regulations and content certification requirements from the Ministry of Information and Broadcasting dictate pricing transparency and catalog availability. Stakeholders must monitor regulatory divergence between data localization mandates and cloud infrastructure portability standards as they architect multi-territory service deployments.
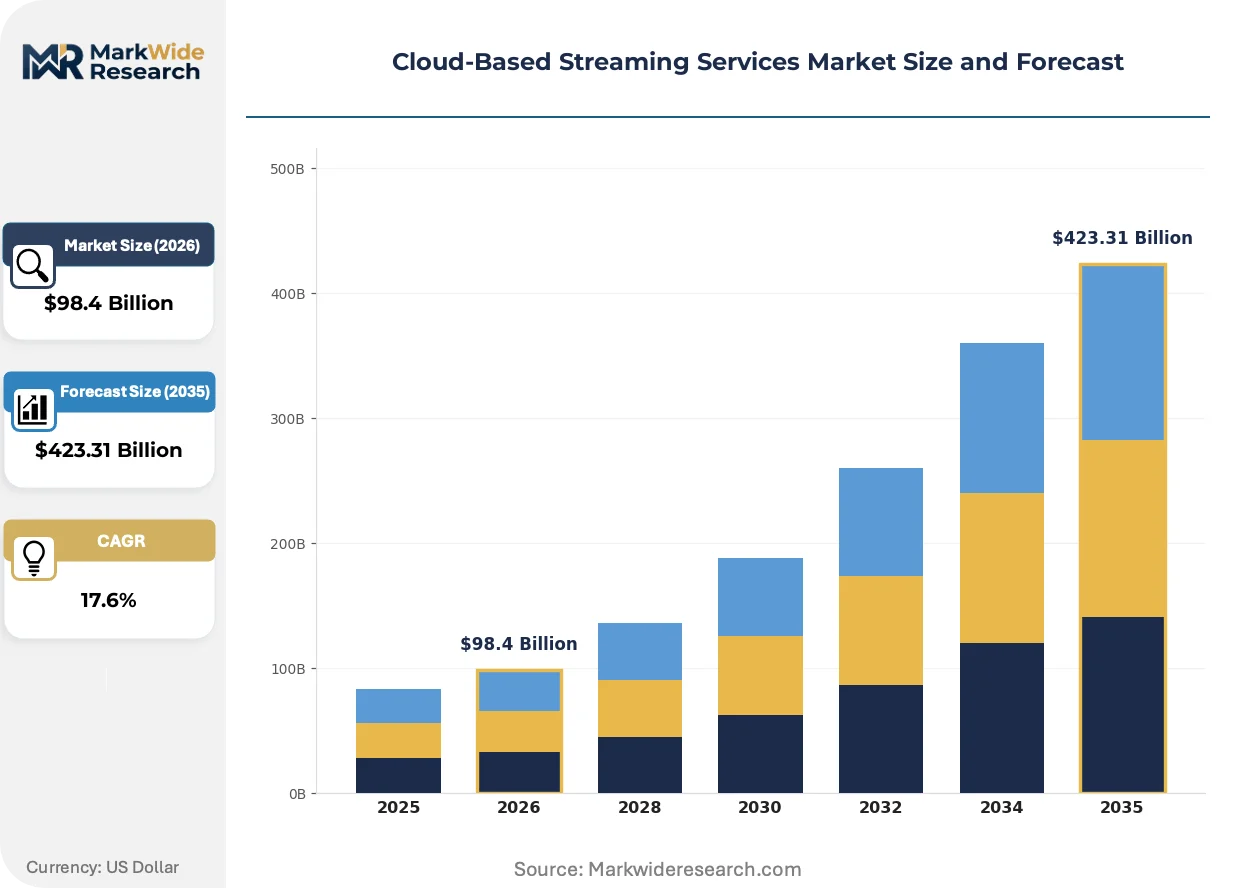
Market Dynamics
Edge computing integration with content delivery networks is redistributing processing loads away from centralized hyperscale data centers toward distributed nodes closer to end users, compressing latency benchmarks and reshaping infrastructure capex allocation across the streaming value chain.
Growth Catalysts
- Enterprise video communications:Remote workforce training protocols at Fortune 500 firms are migrating from on-premise learning management systems to cloud-hosted interactive streaming platforms, expanding addressable seat counts.
- GDPR-compliant personalization engines:European broadcasters are investing in privacy-preserving recommendation algorithms that process viewer data within regional boundaries, unlocking monetization previously constrained by cross-border transfer restrictions.
- India's multilingual content mandates:Ministry of Information and Broadcasting certification requirements for local-language catalog quotas are driving platform localization investments that expand subscriber bases beyond English-proficient urban cohorts.
Market Restraints
- Energy input cost volatility:Data center power purchase agreements face repricing pressure from grid instability and carbon offset credit markets, squeezing operating margins for encoding farm operators.
- CDN supplier concentration:Three hyperscale cloud providers control over 70% of edge server deployment capacity, creating single-source risk for mid-tier streaming platforms negotiating interconnection terms.
- Codec licensing fragmentation:Patent pool disputes between AV1, HEVC, and VVC standard bodies impose royalty uncertainty that delays hardware decoder deployment in consumer electronics.
Strategic Opportunities
- Interactive live commerce integration:Southeast Asian markets are pioneering shoppable video streams that merge entertainment consumption with real-time transaction processing, opening advertising revenue pools beyond subscription models.
- FCC rural broadband subsidies:Universal Service Fund allocations for last-mile fiber deployment in underserved US counties will expand addressable households for high-bitrate 4K services previously limited by DSL infrastructure.
- AI-generated content localization:Neural dubbing and automated subtitling convergence is enabling same-day global release windows that previously required weeks of manual post-production.
Industry Challenges
- Real-time encoding specialist scarcity:FFmpeg and GPU kernel optimization expertise concentrates among a narrow cohort of engineers, inflating compensation premiums and delaying product roadmap execution.
- Legacy broadcast integration complexity:National television networks migrating to IP-based contribution feeds face SDI-to-NDI conversion bottlenecks that require parallel infrastructure operation during transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud-Based Streaming Services Market |
| Market Size in 2026 | $98.4 Billion |
| Market Size in 2035 | $423.31 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Video Streaming, Music Streaming, Gaming Streaming, Live Streaming End User: Individuals, Media Companies, Educational Institutions, Enterprises Subscription Model: Monthly Subscription, Annual Subscription, Pay-per-View, Freemium Content Type: Original Content, Licensed Content, User-Generated Content, Live Events |
| Companies Covered | Amazon Web Services, Microsoft Azure, Google Cloud, Netflix, YouTube, Amazon Prime Video, Apple TV+, Disney+, iQIYI, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud-Based Streaming Services Market Strategic Shifts
Latency compression technologies and AI-powered encoding pipelines are converging to enable interactive use cases that were technically infeasible under prior broadcast architectures, compressing the gap between live event capture and viewer playback.
Server-side ad insertion (SSAI) technology is digitizing the traditional commercial break, stitching targeted advertisements into content streams at the CDN edge before delivery to consumer devices. Media buyers at consumer packaged goods firms are reallocating television upfront budgets toward these addressable inventory pools. The technology is digitizing audience segmentation practices that previously relied on demographic proxies, enabling household-level targeting based on viewing history and purchase data.
The EU AI Act's content moderation requirements are mandating automated detection systems for manipulated media and illegal material across streaming platforms operating in member states. Compliance investments are diverting engineering resources from feature development toward trust and safety infrastructure. Live streaming services serving European audiences are responding by deploying pre-broadcast delay buffers and human moderator escalation workflows that increase operational overhead.
Subscription fatigue among North American households is fragmenting entertainment budgets across multiple niche services rather than consolidating around one or two flagship platforms. Consumers are churning through free trial periods and seasonal promotional pricing to access specific original programming drops. This behavior is most visible in the United States, where average streaming service subscriptions per household peaked and have begun declining as viewers optimize spend against content release calendars.
Cloud-Based Streaming Services Market Segmentation
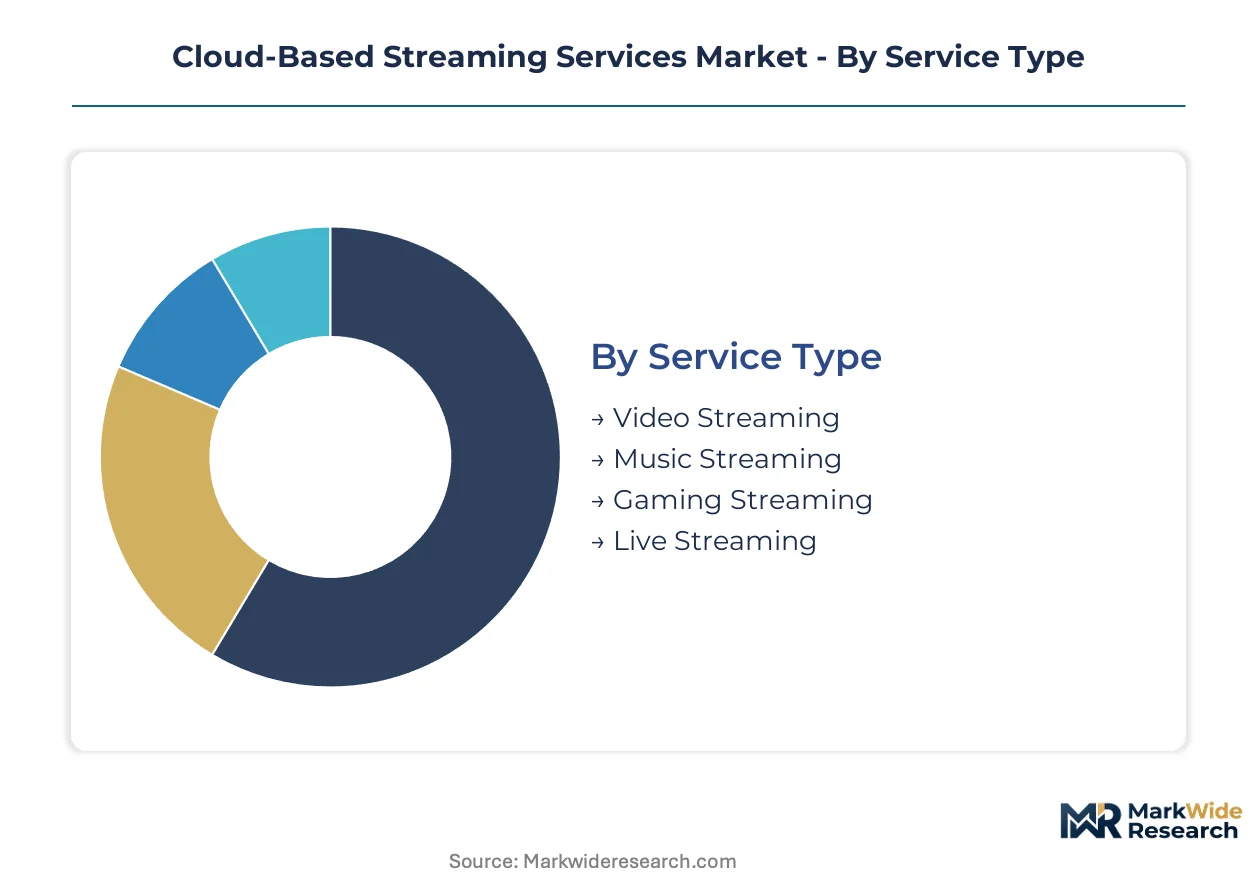
Streaming platforms architect their infrastructure around distinct consumption patterns that dictate encoding priorities, CDN topology, and monetization mechanics. Segmentation reveals where capital allocation concentrates and which service configurations justify premium pricing versus commodity positioning.
Service Type:
Cost tier differentiation separates bandwidth-intensive formats from lightweight audio delivery, with infrastructure commitments scaling nonlinearly across video fidelity requirements.
- Video Streaming:Adaptive bitrate protocols transcode source media into multiple resolutions for device-agnostic playback. Demand concentrates in North American households where 4K-capable displays and fiber last-mile penetration enable premium tier uptake, though encoding farm operators face margin pressure from energy input volatility.
- Live Streaming:Latency compression techniques mature fastest in this segment, enabling interactive use cases from sports wagering to real-time commerce. India's multilingual content ecosystem drives platform localization investments that expand subscriber bases beyond English-proficient urban cohorts.
- Music Streaming:Audio codecs require substantially lower bandwidth than video, reducing CDN edge server deployment intensity.
- Gaming Streaming:Cloud-rendered interactive streams demand sub-20 millisecond latency thresholds that constrain viable geographic coverage.
Video Streaming commands the established base. The steepest expansion runs through Live Streaming.
End User:
Customer type determines contract structure, with seat-based enterprise licensing yielding predictable recurring revenue against individual subscriber churn volatility.
- Individuals:Direct-to-consumer subscriptions generate the largest revenue pool, though subscription fatigue in United States households fragments entertainment budgets across niche services. Churn optimization through seasonal promotional pricing now dominates customer acquisition strategy.
- Enterprises:Remote workforce training protocols at Fortune 500 firms are migrating from on-premise learning management systems to cloud-hosted interactive platforms, expanding addressable seat counts with multi-year contract visibility.
- Media Companies:Licensed content spend consolidates toward exclusive original programming, reshaping supplier relationships with production studios.
- Educational Institutions:Lecture capture and asynchronous course delivery require specialized compliance with accessibility standards and student data privacy frameworks.
Individuals anchor current revenue. Enterprises are gaining share fastest as procurement shifts from capitalized on-premise systems to operationalized cloud subscriptions.
Subscription Model:
Application timing—continuous access versus event-based consumption—shapes cash flow predictability and customer lifetime value calculations.
- Monthly Subscription:Recurring billing with cancellation flexibility dominates consumer-facing platforms. United States viewers optimize spend against content release calendars, cycling through free trials to access specific original programming drops.
- Annual Subscription:Prepaid commitments improve working capital position and reduce churn exposure, common in enterprise training contracts.
- Freemium:Ad-supported tiers expand addressable markets in price-sensitive geographies, with SSAI technology enabling household-level targeting.
- Pay-per-View:Event-based pricing captures premium for live sports and exclusive theatrical windows, though technical infrastructure must handle extreme demand spikes.
Monthly Subscription holds the installed base. Freemium is climbing the fastest as platforms compete for emerging market penetration.
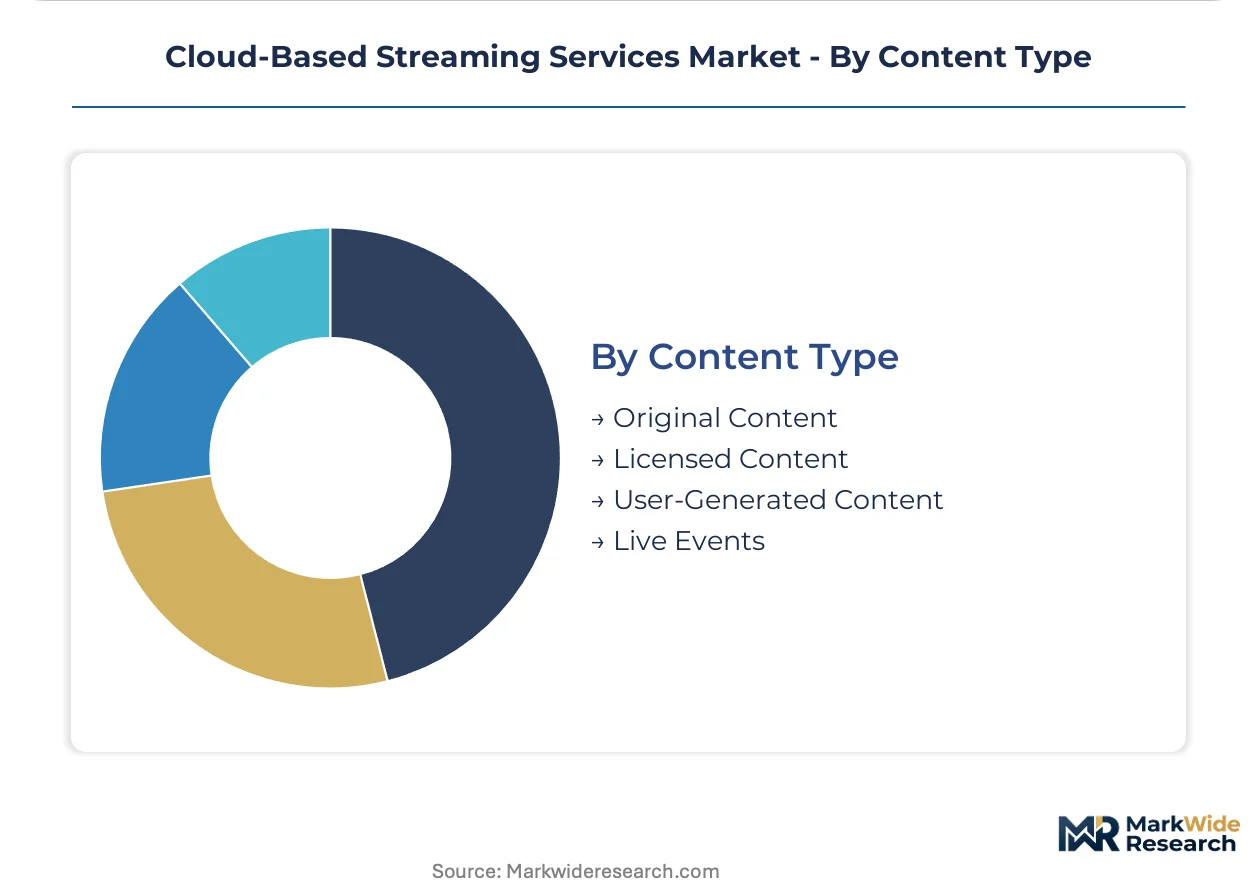
Content Type:
Supply concentration—proprietary production versus licensed aggregation—determines margin structure and catalog risk exposure.
- Licensed Content:Third-party rights acquisitions require ongoing renegotiation, with exclusivity premiums escalating as platforms compete for finite premium inventory. India's Ministry of Information and Broadcasting certification requirements for local-language catalog quotas reshape procurement priorities.
- Original Content:Proprietary production eliminates renewal risk and builds durable subscriber loyalty. EU AI Act content moderation requirements divert engineering resources toward trust and safety infrastructure, increasing operational overhead for original programming pipelines.
- User-Generated Content:Platform liability frameworks vary by jurisdiction, with automated detection systems mandated for European operations.
- Live Events:Sports and concert rights command premium positioning, though technical failure tolerance approaches zero.
Licensed Content maintains current volume leadership. Original Content shows the steepest expansion trajectory as platforms defend subscriber retention through exclusive programming.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based hyperscale cloud providers export streaming infrastructure services to enterprise buyers across Germany, India, and Brazil, establishing transatlantic and transpacific data corridors that reshape local content delivery economics.
United States
FCC rural broadband subsidies through the Universal Service Fund expand addressable households for 4K streaming in underserved counties. Net neutrality rulings reshape last-mile delivery economics and interconnection fee structures. Los Angeles and Seattle anchor original content production clusters where studios negotiate exclusive programming deals with platform operators.
Germany
GDPR-compliant personalization engines unlock monetization previously constrained by cross-border data transfer restrictions. EMA data governance standards constrain viewer analytics deployment for health-related content streams. Berlin and Munich host broadcast technology clusters where public-service media operators migrate from terrestrial to IP-based distribution.
India
Multilingual content mandates from the Ministry of Information and Broadcasting drive platform localization investments beyond English-proficient urban cohorts. TRAI tariff regulations dictate pricing transparency for subscription services. Mumbai and Bangalore concentrate engineering talent pools where streaming platforms build regional encoding facilities.
Brazil
Pay-TV subscriber erosion accelerates migration to ad-supported streaming tiers in price-sensitive metropolitan markets. ANVISA content classification requirements impose certification delays for imported programming. São Paulo anchors Latin American headquarters clusters where global platforms localize Portuguese-language catalog and advertising sales operations.
South Korea
Gaming-integrated streaming demand compresses latency thresholds for cloud-rendered interactive content. MFDS digital health content regulations shape therapeutic video streaming compliance frameworks. Seoul Capital Area concentrates 5G network infrastructure where mobile carriers bundle zero-rated streaming with data plans.
Cloud-Based Streaming Services Market Competitive Environment
Channel-controlling players compete with product-specialist players across three discernible tiers. Hyperscale cloud providers anchor infrastructure supply through captive CDN and encoding services. Entertainment platforms differentiate through exclusive content libraries and proprietary delivery appliances. Regional telecom operators bundle streaming access with connectivity subscriptions to reduce churn. Dominant competitive moves include vertical integration into original production and strategic partnerships for licensed sports rights.
Within the hyperscale infrastructure tier, Amazon Web Services exemplifies the integrated cloud-to-edge model, while Netflix occupies a position representing proprietary appliance deployment for cost-optimized transit. Google Cloud anchors the advertising-integrated streaming archetype through built-in video platform infrastructure.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft Azure |
| Google Cloud |
| Netflix |
| YouTube |
| Amazon Prime Video |
| Apple TV+ |
| Disney+ |
| iQIYI |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in North American edge server deployment is compressing interconnection fee negotiations while simultaneously enabling hyperscale providers to bundle encoding services at marginal cost, reshaping how mid-tier platforms structure their infrastructure procurement and pass-through pricing to end subscribers.
Pricing Analysis
AV1-to-HEVC-to-VVC codec generation gaps drive substantial pricing stratification across hardware decoder ecosystems, with legacy H.264 tiers commanding commodity rates while next-generation VVC-enabled premium streams justify subscription uplifts through bandwidth efficiency claims. Three-tier pricing structure across premium, standard, and economy levels separates 4K HDR with Dolby Atmos from 1080p stereo and ad-supported 720p tiers. Cost compression in standard-tier encoding farms is intensifying because energy purchase agreement repricing squeezes operator margins. Enterprise training seat contracts exhibit lowest price sensitivity due to multi-year procurement visibility, while individual subscribers in price-sensitive emerging markets churn aggressively through promotional windows.
Supply Chain Analysis
Extended payment terms from hyperscale cloud providers now stretch 90-120 days for mid-tier streaming platforms, forcing encoding farm operators to absorb working capital pressure or seek supply-chain finance facilities at premium rates. Hardware decoder chipset fabrication concentrates in Taiwan, South Korea, and China, while CDN edge server assembly feeds from Chinese and Mexican manufacturing hubs. Raw material dependencies span silicon wafers, rare earth magnets for cooling systems, and copper for interconnects. Single-source vulnerability runs through GPU kernel optimization specialist labor pools concentrated in Bangalore and Taipei. Distribution runs through direct hyperscale provisioning contracts rather than traditional channel intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face sustained substitution pressure from decentralized Web3 streaming protocols and peer-to-peer content delivery networks that threaten to disintermediate traditional platform economics.
For Market Incumbents: Entrench proprietary delivery infrastructure through captive Open Connect-style appliance deployment at ISP peering points, reducing transit cost exposure while improving buffer ratios against emerging peer-to-peer alternatives. Deepen backward integration into original content production to eliminate licensed catalog renewal risk and build durable subscriber loyalty that resists churn to decentralized alternatives.
For New Entrants and Emerging Players: Build out interactive live commerce capabilities in Southeast Asian markets where shoppable video streams merge entertainment with real-time transaction processing, opening advertising revenue pools beyond saturated subscription models. Target enterprise remote workforce training segments with specialized compliance features for GDPR and HIPAA frameworks, leveraging seat-based contracts with superior lifetime value against volatile consumer subscriptions.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among enterprise SaaS streaming platforms with multi-year training contracts and embedded workflow integration, suggesting superior cash-flow quality versus consumer-facing subscription volatility. Long-term viability hinges on AI-powered encoding differentiation and edge computing deployment density. Acquisition target archetype: regional encoding specialists with FFmpeg optimization expertise and established ISP peering relationships. Monitor FCC rural broadband subsidy disbursement velocity as inflection indicator for addressable household expansion in underserved US counties.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge Server Deployment Expansion | Hyperscale CDN capacity additions in Mumbai and São Paulo reduce latency for emerging market subscribers. |
| AI-Powered Encoding Pipeline Investment | Neural compression algorithms from Google Cloud and AWS Elemental cut bandwidth costs per stream delivered. |
| Original Content Production Integration | Netflix and Disney+ exclusive programming builds subscriber retention against licensed catalog churn. |
| Enterprise Training Platform Partnership | Fortune 500 LMS migrations to cloud-hosted interactive streaming expand addressable seat counts. |
| GDPR-Compliant Personalization Engine | Privacy-preserving recommendation algorithms unlock European monetization previously constrained by cross-border restrictions. |
Study Parameters
Operator-level perspectives from platform engineering directors, CDN procurement leads, content licensing executives, and enterprise training administrators anchored the qualitative base, supplemented by secondary validation through SEC filings from hyperscale cloud providers, TRAI tariff orders, FCC net neutrality rulings, and EU AI Act implementation guidance. Bottom-up encoding capacity estimates triangulated against top-down subscription revenue projections.
Scenario-bracketing around energy price volatility, codec adoption curves, and regulatory enforcement intensity shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include service type, end-user archetype, subscription model, and content sourcing strategy. CAGRs derived from fitted growth curves incorporating historical penetration rates and addressable market expansion. Industry-specific forecast inputs encompass data center power purchase agreement pricing and 5G network deployment timelines.
Practitioners should monitor EU AI Act content moderation enforcement actions, India TRAI tariff regulation amendments, and FCC rural broadband subsidy allocation velocity for early signals of demand or supply disruption. Forecasts reflect documented assumptions about codec migration timelines and enterprise procurement cycle normalization. Macroeconomic contraction, regulatory divergence on data localization, or breakthrough peer-to-peer streaming technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
US Quantum Computing Market
Others
Moonstone Market
Others
Video Encoder Market
Others
Process Instrumentation Equipment Market
Others
North America Flexographic Printing Market
Others
Industrial Gauges Market
Others
Bio-Imaging Technologies Market
Others
Global Phablets and Superphones Market
Others
Global Simulation in Healthcare Market
Others
Europe Video Encoder Market
Others
Global Microcontroller Embedded Systems Market
Others
Asia-Pacific Induced Pluripotent Stem Cells (Ipscs) Market
Others
Global Active Speaker Market
Others
Fresh Pears Market
Others
France Location-Based Services Market
Others
Fire Sprinkler Market