
 Agitation System Market | 2026-2036
Agitation System Market Size, Share, and Industry Trends Forecast 2026-2036
Agitation System Market Analytics
A capital-intensity divergence between integrated process equipment builders and specialized agitation component suppliers is unwinding competitive stability in the sector. EKATO Group leverages captive casting and machining capacity to anchor long-term reactor-agitator bundling contracts with European chemical producers. SPX FLOW competes through modular platform architectures that reduce field installation labor for food and dairy processors. Sulzer Ltd specializes in high-shear impeller geometries for polymerization reactors, occupying a defensible niche in viscous fluid handling.
An agitation system is a mechanical assembly comprising a drive unit, shaft, and impeller designed to induce controlled fluid motion in vessels, typically operating at power inputs from 0.1 to 100 kW per cubic meter depending on process intensity. Its primary purpose is to achieve uniform mixing, heat transfer, suspension of solids, or gas dispersion in batch and continuous industrial operations. Mechanical agitators retain the largest installed base across chemical production due to proven torque transmission and seal reliability under abrasive conditions. Magnetic agitators are gaining share in pharmaceutical manufacturing as aseptic processing requirements harden against contamination risks from mechanical seal leakage. Portable installation configurations are expanding fastest among research laboratories and pilot-scale facilities seeking flexible campaign-based deployment.
EMA's GMP guidelines and FDA's process validation requirements shape equipment qualification protocols, lengthening sales cycles but creating vendor stickiness once systems achieve regulatory filing status. REACH compliance on wetted materials and EPA emissions controls on volatile organic compound handling further constrain material selection and seal technology choices. Stakeholders must monitor evolving sterile processing standards and carbon border adjustment mechanisms to calibrate R&D priorities and geographic manufacturing investments.
Market Dynamics
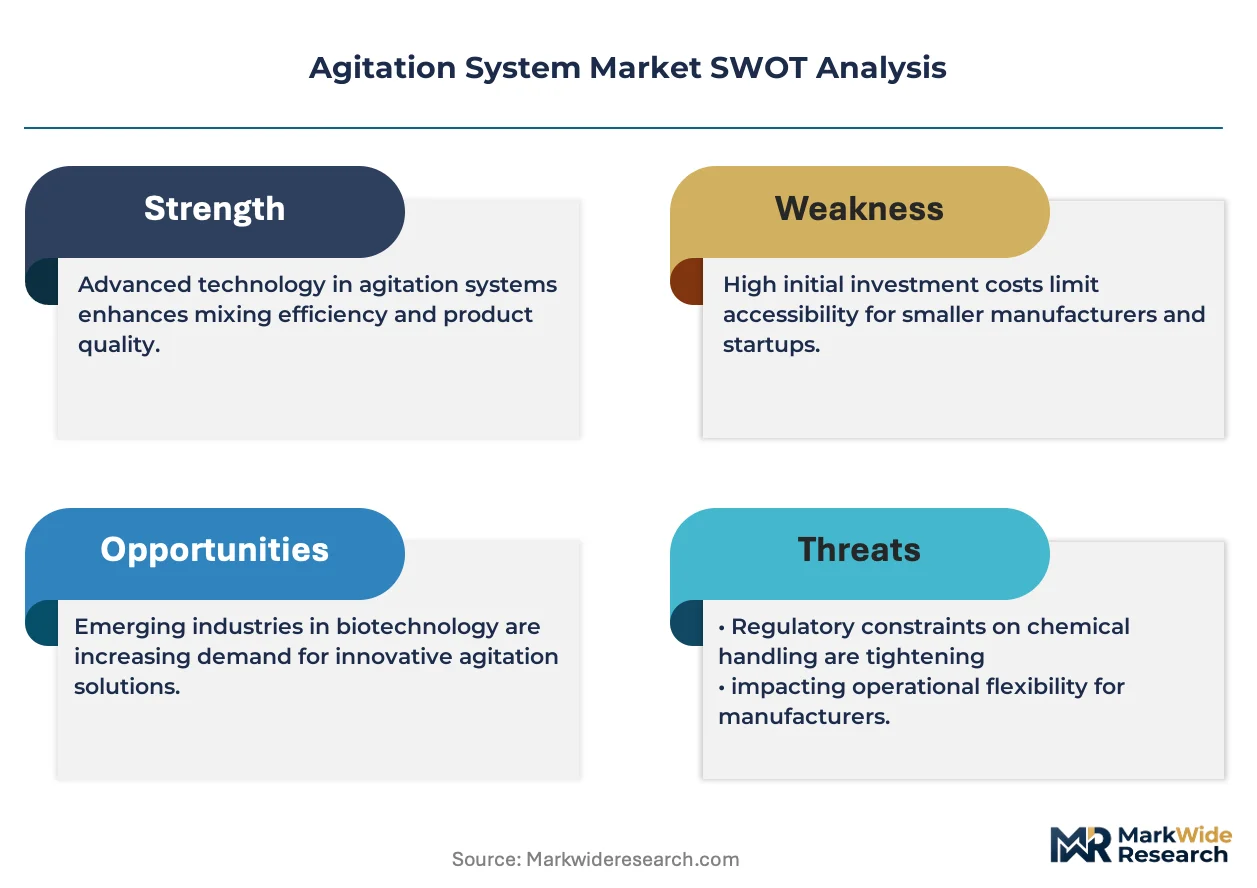
Magnetic drive technology is compressing the addressable market for mechanical seal maintenance services while expanding the total equipment value pool through higher unit pricing and extended qualification timelines.
Growth Catalysts
- EU GMP Annex 1 sterile processing mandates:Pharmaceutical manufacturers in Germany and India are retrofitting bioreactor vessels with aseptic agitation systems to eliminate contamination pathways from mechanical seal leakage.
- Polymerization reactor intensity:High-viscosity synthetic rubber and specialty polymer production in the US Gulf Coast is demanding purpose-built high-shear impeller geometries with reinforced shaft designs.
- Gujarat pharmaceutical cluster expansion:CDSCO-compliant sterile processing infrastructure buildouts are concentrating demand for magnetic agitators with integrated CIP/SIP capabilities.
Market Restraints
- Specialized alloy input cost volatility:Hastelloy and titanium wetted component pricing fluctuates with nickel and titanium sponge commodity markets, compressing margins on corrosion-resistant agitator builds.
- German casting capacity concentration:Captive foundry operations at integrated equipment builders limit third-party access to precision impeller castings for specialized suppliers.
- Mechanical seal reliability in abrasive slurries:Mining and mineral processing applications retain conventional sealed designs despite leakage risks, slowing magnetic technology penetration in these end-uses.
Strategic Opportunities
- Brazilian generic pharmaceutical manufacturing:ANVISA alignment with FDA and EMA standards is opening qualification pathways for aseptic agitation equipment in São Paulo's expanding API production base.
- Modular platform architectures:Standardized drive units with field-configurable shaft and impeller combinations are reducing installation labor costs for food and dairy processors.
- Portable pilot-scale configurations:Research laboratories in the United States and Germany are adopting campaign-deployable agitation skids with rapid vessel changeover capabilities.
Industry Challenges
- Multi-regulatory qualification timelines:Simultaneous FDA process validation, EMA GMP inspection, and CDSCO licensing extends sales-to-revenue cycles for pharmaceutical equipment vendors.
- Computational fluid dynamics modeling expertise:Custom impeller design for non-Newtonian fluids requires specialized simulation talent that concentrates at integrated engineering firms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agitation System Market |
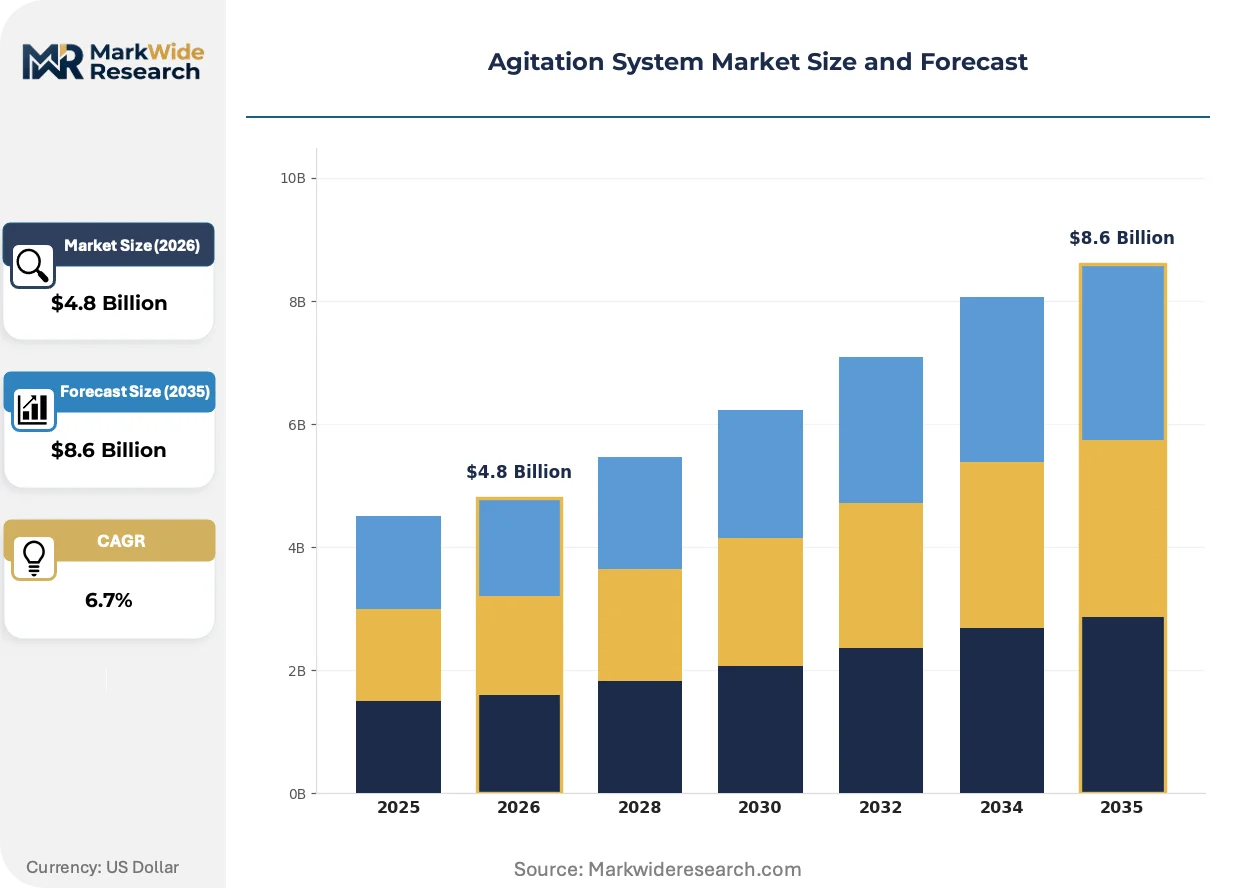
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Magnetic Agitators, Mechanical Agitators, Pneumatic Agitators, Static Mixers Application: Pharmaceutical Manufacturing, Food Processing, Chemical Production, Water Treatment End User: Manufacturing Plants, Research Laboratories, Wastewater Facilities, Oil Refineries Installation: Fixed Systems, Portable Systems, Overhead Systems, Inline Systems |
| Companies Covered | EKATO Group, SPX FLOW, Sulzer Ltd, Alfa Laval, Xylem Inc., National Oilwell Varco, Philadelphia Mixing Solutions, Silverson Machines, De Dietrich Process Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agitation System Market Evolving Landscape
Equipment architectures are fragmenting between sealed sterile designs and open mechanical systems, with software-enabled process control emerging as the binding layer across both categories.
Magnetic drive agitation is supplanting conventional mechanical seal arrangements in high-purity pharmaceutical and biotechnology applications. Single-use bioreactor manufacturers are specifying magnetic couplings to eliminate seal wear particles and lubricant contamination risks. This transition is compressing the aftermarket revenue stream for seal replacement kits while expanding upfront equipment value through integrated sensor and control packages.
REACH substance restrictions on chromium(VI) surface treatments and PFAS-containing seal materials are forcing material substitutions in wetted component specifications. Equipment builders are qualifying alternative passivation chemistries and fluoropolymer-free elastomer compounds for FDA and EMA filings. Pharmaceutical OEMs in Germany and Switzerland are absorbing extended qualification timelines to maintain regulatory filing status across their installed base.
Life-cycle service contracting is displacing transactional spare parts procurement among large chemical producers. Operators in the US Gulf Coast and Germany's chemical corridor are bundling predictive maintenance, impeller refurbishment, and performance guarantees into multi-year agreements. This shift concentrates vendor relationships around integrated service capabilities rather than component pricing competitiveness.
Agitation System Market Segmentation
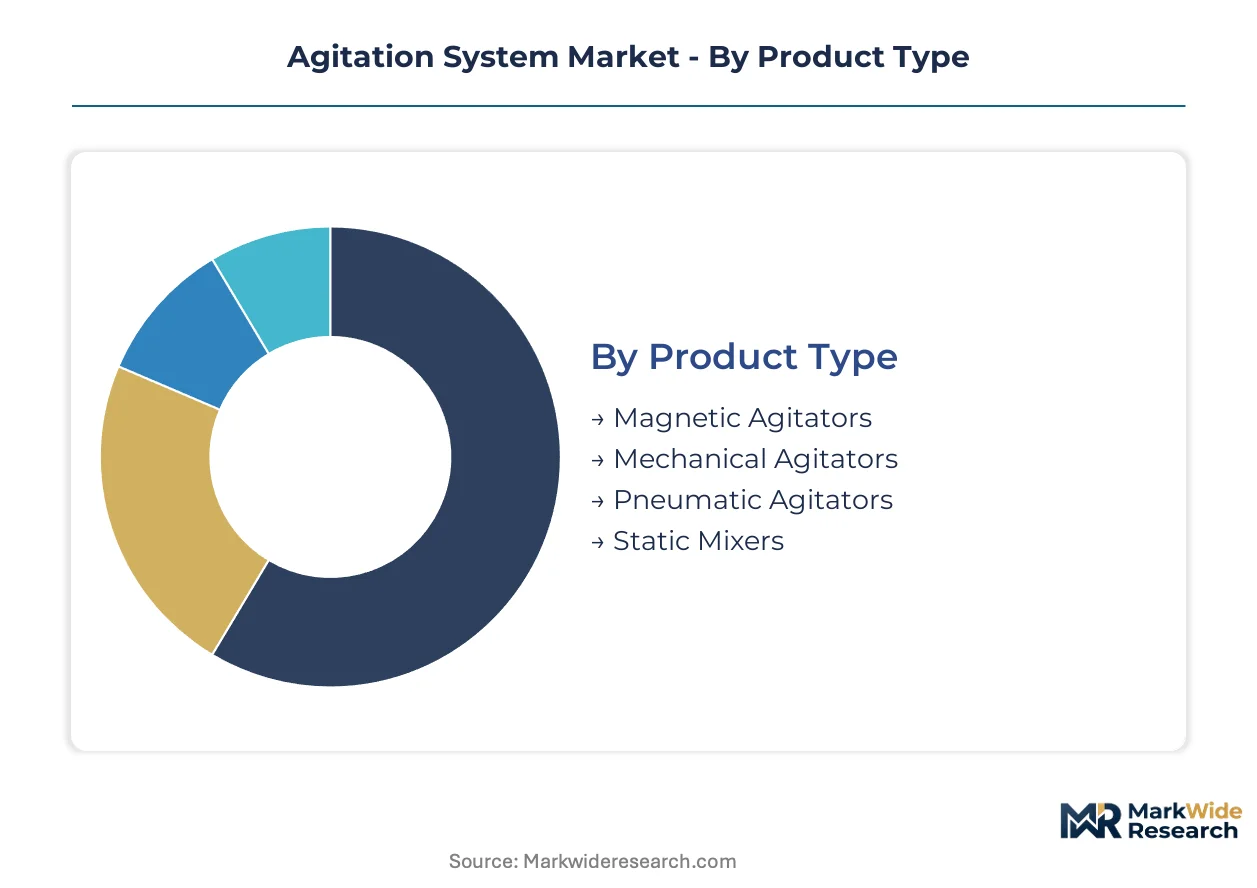
Agitation system procurement patterns diverge sharply across product architectures and installation modes. Pharmaceutical manufacturers prioritize sterile magnetic designs while chemical producers balance seal reliability against maintenance economics. Understanding these segment boundaries clarifies where technology substitution accelerates versus where incumbent designs retain durable positions.
Product Type:
Magnetic agitators concentrate in export-oriented pharmaceutical supply chains serving regulated markets, while mechanical agitators dominate domestic chemical production where abrasive conditions favor proven seal architectures.
- Magnetic Agitators:Hermetically sealed drive systems eliminate shaft penetration through the vessel wall, enabling aseptic processing under FDA and EMA sterile manufacturing mandates. Demand clusters in Germany's biologics corridor and Gujarat's injectables cluster where EU GMP Annex 1 compliance is mandatory for export qualification.
- Mechanical Agitators:Conventional sealed shaft designs transmit torque through packed or mechanical seals, offering superior power density for high-viscosity polymerization and mining slurry applications. The US Gulf Coast synthetic rubber belt and German chemical corridor sustain substantial installed base renewal cycles despite magnetic technology encroachment.
- Pneumatic Agitators:Compressed-air driven systems serve explosion-hazard environments and remote installations lacking electrical infrastructure.
- Static Mixers:Motionless mixing elements integrated into piping suit continuous flow processes with predictable rheology profiles.
Mechanical agitators command the established base. The steepest expansion runs through magnetic agitators.
Application:
Application segments stratify by regulatory intensity, with pharmaceutical and food processing commanding premium pricing tiers against commoditized water treatment procurement.
- Pharmaceutical Manufacturing:Bioreactor and formulation vessel agitation operates under validated processes requiring IQ/OQ/PQ documentation for FDA 21 CFR Part 11 compliance. Magnetic drive systems with integrated CIP/SIP capabilities capture specification preference in Germany, Switzerland, and India's export-oriented sterile facilities.
- Chemical Production:Polymerization, crystallization, and suspension processes demand customized impeller geometries for non-Newtonian rheology. The US Gulf Coast specialty chemical belt and Germany's Ludwigshafen-Leuna corridor sustain demand for high-shear mechanical designs with reinforced shaft bearings.
- Food Processing:Hygienic design requirements under FDA and EFSA frameworks drive stainless steel construction with polished surface finishes.
- Water Treatment:Flocculation and chemical dosing applications prioritize capital efficiency over precision control in municipal procurement.
Chemical production anchors volume throughput. Pharmaceutical manufacturing captures the steepest value expansion trajectory.
End User:
End user categories separate by scale economics, with manufacturing plants amortizing capital across continuous campaigns versus research laboratories requiring rapid reconfiguration.
- Manufacturing Plants:Continuous and batch production facilities specify agitation systems for 10-20 year operational lifecycles with predictive maintenance contracts. German chemical producers and US Gulf Coast refiners bundle performance guarantees into multi-year service agreements.
- Research Laboratories:Pilot-scale and campaign-based operations demand portable skids with quick vessel changeover capabilities. Academic and corporate R&D facilities in the United States and Germany are standardizing on modular agitation platforms.
- Wastewater Facilities:Municipal and industrial effluent treatment prioritizes operational simplicity over precision control.
- Oil Refinuries:Hydrotreating and alkylation units specify heavy-duty mechanical agitators for high-temperature hydrocarbon service.
Manufacturing plants command the established base. Research laboratories are expanding most quickly.
Installation:
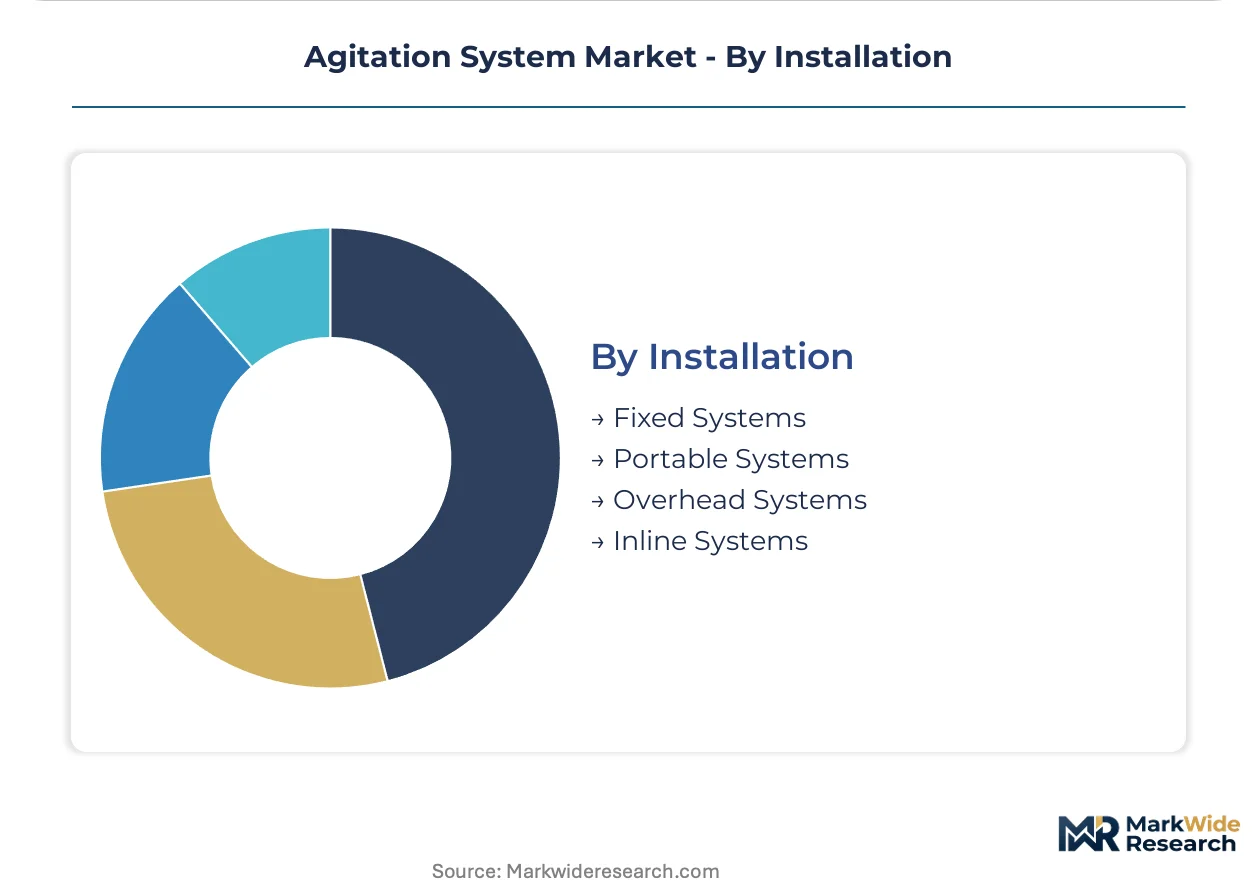
Installation configurations distribute by mobility requirements, with fixed systems dominating process industry infrastructure versus portable designs serving flexibility-driven segments.
- Fixed Systems:Permanently mounted top-entry and side-entry agitators integrate with vessel pressure ratings and nozzle geometries during original construction. Greenfield pharmaceutical facilities in India and Brazil specify magnetic drive fixed systems to preempt retrofit costs.
- Portable Systems:Skid-mounted or clamp-on configurations enable campaign-based deployment across multiple vessels. Contract research organizations and pilot plants in Germany and the United States absorb higher unit costs for operational flexibility.
- Overhead Systems:Bridge or gantry-mounted drives serve open-top tanks in mining and mineral processing.
- Inline Systems:Pipeline-integrated static or dynamic mixers suit continuous flow chemistry applications.
Fixed systems command the established base. Portable systems are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. German pharmaceutical buyers absorb premium magnetic agitator pricing for regulatory compliance, while Indian domestic chemical producers prioritize mechanical seal economics over sterile design.
United States
The US Gulf Coast synthetic rubber belt and Texas-Louisiana refining corridor sustain demand for high-shear mechanical agitators with reinforced shaft bearings. EPA emissions controls on volatile organic compound handling constrain seal technology choices in petrochemical applications. Houston-area specialty polymer producers are retrofitting crystallization vessels with purpose-built impeller geometries for non-Newtonian rheology.
Germany
Ludwigshafen-Leuna chemical producers and Bavarian biologics manufacturers drive divergent procurement patterns. EU GMP Annex 1 sterile processing mandates from EMA harden contamination controls for export-oriented pharmaceutical facilities. The country's chemical corridor sustains substantial installed base renewal cycles for mechanical designs despite magnetic technology encroachment in pharma.
India
Gujarat's pharmaceutical cluster and Maharashtra's chemical belt concentrate divergent demand profiles. CDSCO licensing requirements and alignment with FDA standards open qualification pathways for aseptic agitation equipment in export-oriented sterile facilities. Ahmedabad and Vadodara injectables manufacturers are scaling bioreactor agitation capacity to meet EU GMP Annex 1 compliance for European market access.
Brazil
São Paulo's expanding API production base and generic pharmaceutical manufacturing sector present qualification opportunities. ANVISA alignment with FDA and EMA standards is opening regulatory pathways for aseptic processing infrastructure. Campinas and São Paulo metro area manufacturers are retrofitting formulation vessels with magnetic drive systems to preempt export market barriers.
China
Yangtze River Delta chemical producers and Pearl River Delta pharmaceutical manufacturers operate under divergent regulatory intensities. NMPA sterile processing guidelines and GB standards shape equipment qualification protocols for domestic and export markets. Shanghai and Suzhou biologics facilities are specifying magnetic couplings to eliminate seal wear particles in single-use bioreactor applications.
Agitation System Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Integrated process equipment builders with captive casting and machining capacity anchor long-term bundling contracts with European chemical producers. Specialized component suppliers compete on modular platform architectures and field installation efficiency. The dominant competitive moves center on multi-year service contracting with predictive maintenance guarantees and geographic expansion through regulatory qualification partnerships.
Within the integrated equipment tier, EKATO Group and Sulzer Ltd represent contrasting specialization strategies—EKATO through reactor-agitator bundling and Sulzer through high-shear impeller geometries for viscous fluid handling. SPX FLOW occupies a distinct position on modular platform architectures that reduce field labor for food and dairy processors. These three anchors demonstrate how competitive positioning fragments between captive manufacturing integration and configurable product platforms.
| Leading Market Players |
|---|
| EKATO Group |
| SPX FLOW |
| Sulzer Ltd |
| Alfa Laval |
| Xylem Inc. |
| National Oilwell Varco |
| Philadelphia Mixing Solutions |
| Silverson Machines |
| De Dietrich Process Systems |
| Others |
Value Network & Pricing Analysis
EU GMP Annex 1 sterile processing mandates gate both supplier qualification and price differentiation simultaneously, compressing vendor pools while expanding premium tiers for compliant equipment. Pharmaceutical buyers in Germany and India absorb 40-60% unit cost premiums for magnetic drive systems with integrated validation documentation, whereas domestic chemical processors prioritize mechanical seal economics.
Pricing Analysis
After-sales service contracting drives lifetime value, with multi-year predictive maintenance agreements now representing 35-45% of vendor revenue streams. Three-tier pricing structure across premium, standard, and economy levels separates validated pharmaceutical-grade magnetic systems from modular food-processing platforms and commodity water-treatment agitators. Pricing pressure stems from nickel and titanium sponge commodity volatility compressing margins on corrosion-resistant Hastelloy builds. Contract research organizations exhibit highest price sensitivity due to campaign-based deployment needs, while integrated chemical producers show lowest sensitivity when bundling performance guarantees.
Supply Chain Analysis
Inventory lead times for precision impeller castings extend 16-24 weeks due to captive foundry concentration at integrated German equipment builders. Supply concentrates in Germany's chemical corridor foundries, India's Gujarat machining clusters, and US Gulf Coast specialty alloy distributors. Raw material dependencies center on nickel-based superalloys, titanium sponge, and high-purity stainless steel billet. Single-source vulnerability runs through German captive casting capacity limiting third-party access. Distribution runs through direct OEM channels for large chemical producers and specialized distributors serving research laboratory segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward integrated chemical producers and pharmaceutical OEMs consolidating vendor relationships around multi-year service contracts. Fragmentation among specialized component suppliers is accelerating procurement centralization at top-tier accounts.
For Market Incumbents: Fortify captive casting and machining capacity to anchor reactor-agitator bundling contracts against modular platform competitors. Deepen backward integration into precision impeller manufacturing to offset German foundry access constraints. Invest in FDA and EMA qualification documentation to maintain regulatory filing status across pharmaceutical installed bases.
For New Entrants and Emerging Players: Life-cycle service contracting gaps at mid-tier chemical producers create white-space targets for predictive maintenance entrants. Brazilian generic pharmaceutical manufacturing presents the most penetrable geography as ANVISA alignment with FDA standards opens qualification pathways. Pursue portable pilot-scale configurations for research laboratories seeking campaign-deployable skids with rapid vessel changeover.
For Investors and Strategic Acquirers: EMA's evolving sterile processing guidelines reshape the acquisition landscape toward vendors with integrated validation capabilities. Long-term viability favors equipment builders with captive manufacturing and multi-regulatory filing status. Target acquisition archetypes include specialized high-shear impeller designers and modular platform architects. Signal to monitor: CDSCO licensing acceleration in India's export-oriented sterile facilities.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Casting | Captive foundry capacity anchors long-term bundling contracts with BASF and Bayer. |
| Multi-Regulatory Qualification Investment | Simultaneous FDA, EMA, and CDSCO filings extend sales cycles but create vendor stickiness. |
| Modular Platform Architecture Expansion | Standardized drive units reduce field installation labor for Danone and Nestlé dairy processors. |
| Life-Cycle Service Contracting | Predictive maintenance bundles concentrate Dow and ExxonMobil relationships around integrated capabilities. |
| Portable Pilot-Scale Configuration Launch | Skid-mounted systems capture flexible deployment demand at Merck and Roche R&D facilities. |
Research Methodology
The analysis maps magnetic drive systems, mechanical agitators, pneumatic configurations, and static mixers, each validated through equipment procurement managers at pharmaceutical OEMs, maintenance directors at chemical plants, and aftermarket service heads at integrated builders. Primary interviews with plant engineers, regulatory affairs leads, and distribution channel partners combined with secondary validation from FDA 510(k) filings, EMA GMP inspection records, CDSCO licensing databases, and SEC equipment supplier disclosures. Bottom-up unit economics triangulated against top-down market sizing across the analysis window.
Consistency checks validated volume and value outputs against customs trade data for precision impeller imports, ACC capital expenditure surveys, and bioreactor installation records at major pharmaceutical facilities. Segmentation dimensions modeled include product architecture, application intensity, end-user scale economics, and installation mobility across the projection horizon. CAGRs derived from regression analysis of historical capacity additions correlated with regulatory mandate implementation timelines and sterile processing infrastructure buildouts.
Underlying assumptions cover continued EMA and FDA sterile processing stringency, with deviation risk concentrated in commodity alloy price volatility and multi-regulatory qualification timeline extensions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Telecom Transformers Market
Others
Industrial Air Purifiers Market
Others
Social Media Engagement Applications Market
Others
Global Extruded Plastics Market
Others
Fiberglass Storage Tanks Market
Others
Global Mica Market
Others
North America Astrology Market
Others
North America Smart Homes Market
Others
Latin America IT Device Market
Others
Water and Waste Water Treatment Chemicals Market
Others
Hookah Tobacco Market
Others
Retail Digital Signage Market
Others
Smart Electric Curtain Market
Others
Italy 3D Printing Construction Market
Others
Czech Republic Market
Others
Human Enhancement Technology Market