
 Bio-Imaging Technologies Market | 2026-2036
Bio-Imaging Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Bio-Imaging Technologies Market Analysis
ISO 13485 certification is reorganizing competitive access across the Bio-Imaging Technologies landscape, forcing smaller component suppliers into costly quality management overhauls. GE Healthcare leverages its installed base of MRI and CT systems to sustain service revenue streams across hospital networks. Philips Healthcare anchors its position through integrated informatics platforms that connect imaging hardware to departmental workflow software. Hitachi Medical Corporation specializes in compact MRI architectures for facilities with constrained infrastructure footprints.
Bio-imaging technologies encompass non-invasive systems that capture anatomical, physiological, or molecular information through electromagnetic radiation, acoustic waves, or magnetic fields, typically resolving structures below one millimeter for diagnostic decision-making. These platforms serve primarily to detect disease, guide interventions, and monitor therapeutic response in clinical settings. Magnetic Resonance Imaging commands premium pricing due to superconducting magnet complexity and situates margin pools with OEMs controlling cryogen supply chains. Ultrasound Imaging penetrates point-of-care environments fastest, driven by portable semiconductor transducer arrays and simplified operator training curves. Imaging Software captures expanding value as AI-based reconstruction algorithms reduce scan acquisition times and radiologist reading burdens.
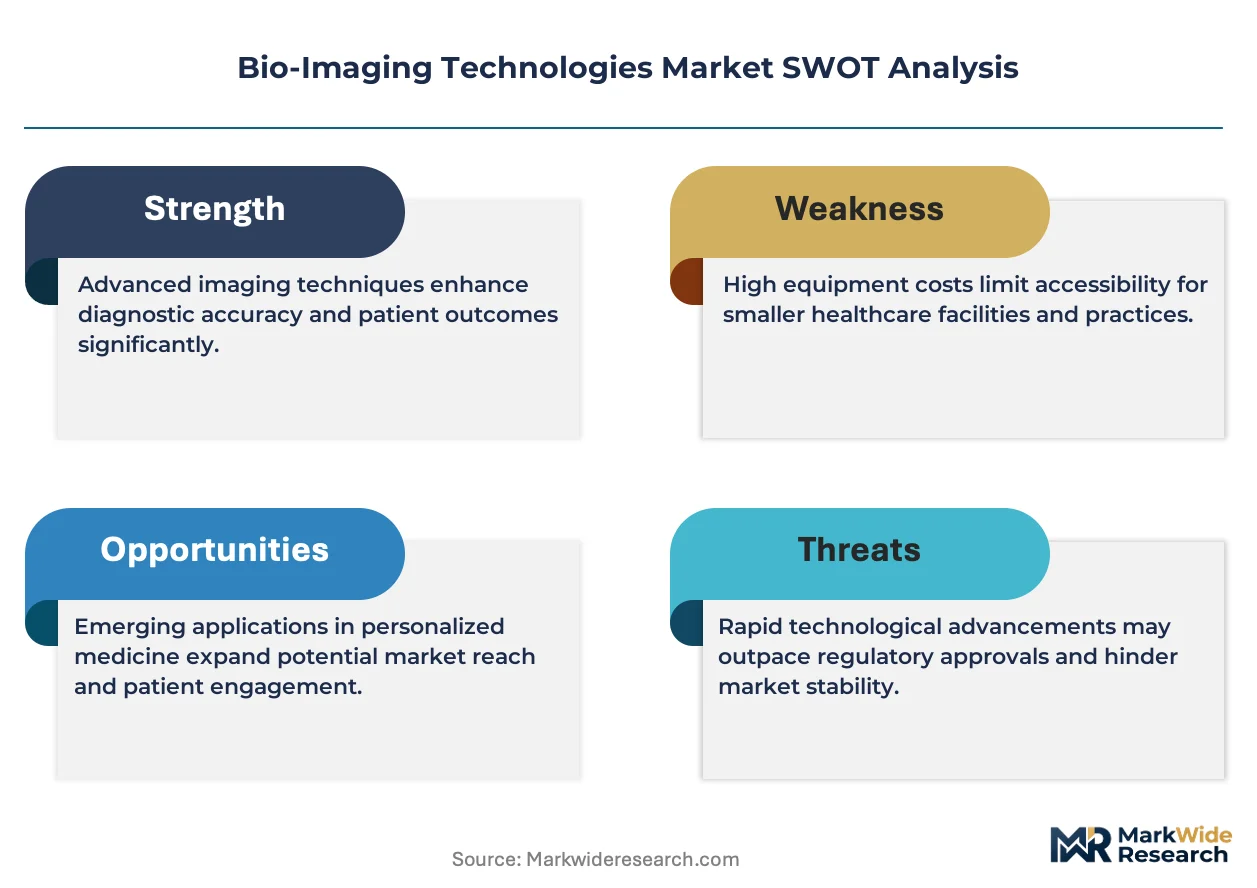
FDA premarket clearance requirements under 21 CFR 892 shape hardware entry barriers, while HIPAA security rules govern cloud-based image archiving and telemedicine transmission protocols. The EU Medical Device Regulation imposes clinical evidence thresholds on software-as-a-medical-device classifications, affecting imaging analytics vendors seeking European market access. Stakeholders must monitor evolving predicate device pathways for AI-enhanced modalities and calibrate R&D budgets against shifting reimbursement validation requirements from CMS and private payers.
Market Dynamics
Superconducting magnet supply chains concentrate manufacturing capability among cryogen specialists, forcing OEMs to secure long-term helium sourcing contracts while semiconductor foundries battle for advanced node capacity in AI reconstruction chipsets.
Growth Catalysts
- AI-enabled premarket notification pathway:FDA's streamlined 21 CFR 892 review process accelerates software clearance timelines for diagnostic algorithms. Radiology departments at academic medical centers expand procurement budgets for validated AI tools.
- Point-of-care semiconductor transducer arrays:Portable ultrasound systems penetrate emergency departments and rural clinics previously dependent on centralized imaging infrastructure. Simplified operator training curves reduce specialist labor requirements.
- Medicare reimbursement shifts:CMS outpatient prospective payment system revisions favor freestanding imaging center expansion over hospital-based department economics. Independent diagnostic testing facilities capture volume migration from inpatient settings.
Market Restraints
- Helium supply concentration:Superconducting MRI magnet cooling depends on Qatar and Algeria LNG extraction byproduct streams. Geopolitical disruption risks cascade through cryogen distribution networks.
- EU MDR clinical evidence thresholds:Software-as-a-medical-device classifications impose retrospective validation studies on imaging analytics vendors. European market access timelines extend for algorithm-based diagnostic tools.
- CT ionizing radiation substitution:MRI and ultrasound modalities displace computed tomography in pediatric and repeat-monitoring applications. Radiation dose concerns drive protocol revision at children's hospitals.
Strategic Opportunities
- Compact MRI architecture penetration:Facilities with constrained infrastructure footprints in Vietnam and Indonesia lack shielding capacity for conventional superconducting systems. Permanent magnet designs address siting limitations.
- Integrated informatics platform convergence:PACS-VNA-AI workflow unification connects imaging hardware to departmental software. Radiology information system vendors capture recurring subscription revenue.
- Cloud-native image archiving:HIPAA-compliant telemedicine transmission protocols enable teleradiology service expansion across state licensing boundaries. Subspecialist interpretation networks aggregate demand from underserved regions.
Industry Challenges
- ISO 13485 quality management overhaul:Component suppliers face certification costs exceeding smaller vendor capital reserves. Forced exits concentrate sourcing options among Tier 1 manufacturers.
- AI reconstruction algorithm validation:FDA predicate device pathway uncertainty delays R&D budget allocation for next-generation iterative reconstruction techniques.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bio-Imaging Technologies Market |
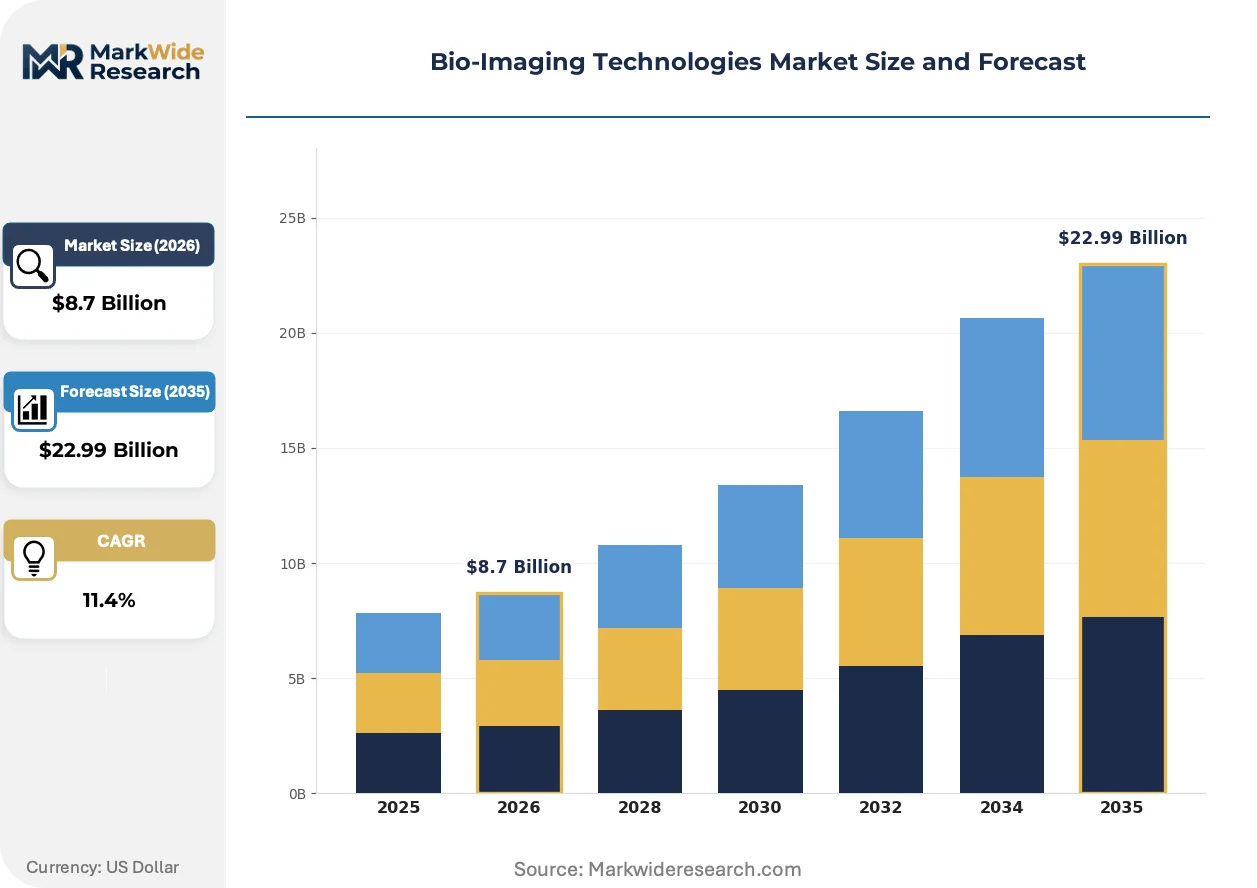
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Magnetic Resonance Imaging, Computed Tomography, Ultrasound Imaging, X-Ray Imaging Product Type: Imaging Agents, Imaging Software, Imaging Devices, Accessories End User: Hospitals, Diagnostic Labs, Research Institutions, Imaging Centers Application: Oncology, Neurology, Cardiology, Orthopedics |
| Companies Covered | Bracco Imaging S.P.A, Esaote S.p.A, GE Healthcare, Digirad Corporation, Hologic Inc., Philips Healthcare, Hitachi Medical Corporation, FONAR Corporation, Bayer HealthCare Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bio-Imaging Technologies Market Emerging Trajectories
Computational reconstruction methods and semiconductor transducer miniaturization are redrawing equipment form factors and service delivery models across diagnostic imaging workflows.
Photon-counting CT detector technology is fragmenting conventional energy-integrating sensor architectures. Cardiac imaging departments at tertiary centers adopt dual-source configurations for spectral tissue characterization. Hardware differentiation compresses pricing power among legacy scintillator-crystal suppliers.
FDA's updated premarket notification pathway for AI-enabled diagnostic devices compresses 510(k) clearance timelines for algorithm-based reconstruction tools. Software vendors redirect regulatory affairs resources toward post-market surveillance obligations. Radiology groups accelerate procurement cycles for cleared AI decision-support modules.
After-sales service unbundling disrupts traditional OEM captive maintenance contracts. Third-party imaging equipment servicers penetrate hospital networks with parts-plus-labor alternatives. Independent service organizations capture 15-20% cost advantages in MRI coldhead and gradient coil replacement segments across United States metropolitan markets.
Bio-Imaging Technologies Market Segmentation
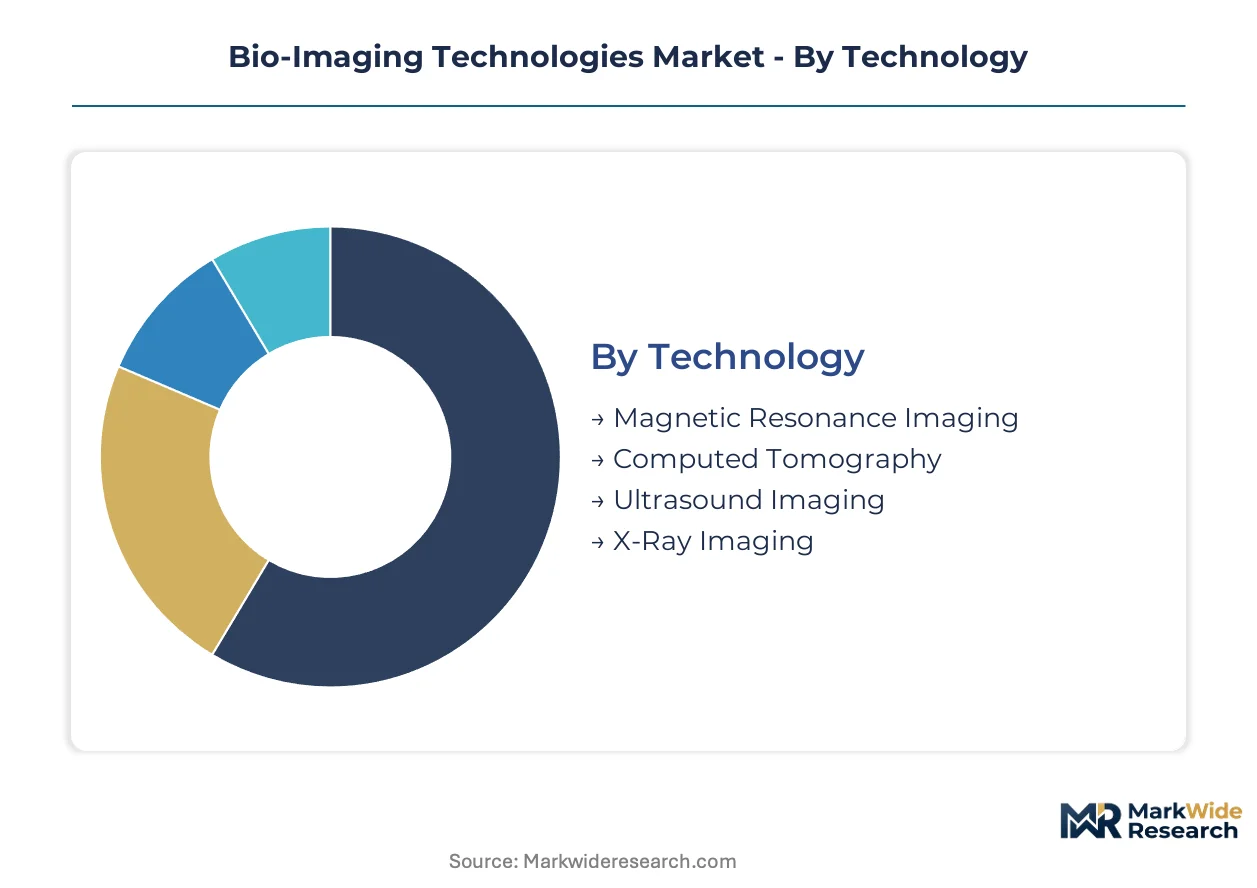
Segmentation in bio-imaging technologies reveals how substitution pressures and reimbursement economics reshape procurement patterns across clinical environments. Understanding these divides helps vendors align R&D investments with where margin pools are migrating.
Technology:
Substitution pressure concentrates most intensely on ionizing radiation modalities as pediatric protocols and repeat-monitoring applications drive protocol revision.
- Magnetic Resonance Imaging:Superconducting magnet architectures generate anatomical and functional images through magnetic field manipulation and radiofrequency pulse sequences. Premium pricing reflects cryogen supply chain control and siting complexity, with demand concentrating at academic medical centers pursuing advanced neuroimaging protocols.
- Ultrasound Imaging:Semiconductor transducer arrays convert electrical pulses into acoustic waves for real-time anatomical visualization. Point-of-care penetration accelerates in emergency departments and rural clinics where portable systems reduce infrastructure dependencies and specialist labor requirements.
- Computed Tomography:Rotating X-ray tube-detector gantries reconstruct cross-sectional anatomical slices through filtered back-projection algorithms.
- X-Ray Imaging:Digital radiography panels and computed radiography systems capture projection images for skeletal and thoracic assessment.
Magnetic Resonance Imaging anchors the volume base while Ultrasound Imaging gains share at the steepest rate.
Product Type:
Cost tier stratification separates capital-intensive hardware from recurring-revenue consumables and software subscriptions.
- Imaging Devices:Integrated scanner platforms combine radiation sources, detector arrays, and reconstruction hardware into FDA-cleared diagnostic systems. Hospital capital budgets concentrate procurement authority at integrated delivery networks negotiating enterprise-wide fleet replacements.
- Imaging Software:AI-based reconstruction algorithms and clinical decision-support modules process raw acquisition data into diagnostic images. Cloud-native deployment models attract teleradiology networks seeking HIPAA-compliant image distribution across state licensing boundaries.
- Imaging Agents:Gadolinium-based contrast media and microbubble suspensions enhance tissue differentiation in magnetic resonance and ultrasound procedures.
- Accessories:Coils, probes, and patient positioning equipment extend scanner functionality across specialized clinical applications.
Imaging Devices generate the largest revenue pool while Imaging Software expands most quickly.
End User:
Customer type determines purchasing authority structure and service contract negotiation leverage.
- Hospitals:Inpatient and outpatient departments within acute care facilities operate the largest installed base of high-field MRI and CT systems. CMS reimbursement differentials between hospital-based and freestanding settings concentrate volume migration toward independent diagnostic testing facilities.
- Imaging Centers:Freestanding diagnostic facilities specialize in high-throughput elective procedures with streamlined patient throughput. Medicare outpatient prospective payment system revisions favor these entities through favorable rate differentials and reduced regulatory overhead.
- Diagnostic Labs:Clinical laboratory networks integrate imaging with pathology and molecular diagnostics for comprehensive disease characterization.
- Research Institutions:Academic medical centers and university laboratories deploy preclinical and experimental imaging platforms for translational studies.
Hospitals retain the dominant installed base while Imaging Centers capture volume at the fastest clip.
Application:
Clinical indication drives modality selection and reimbursement code valuation.
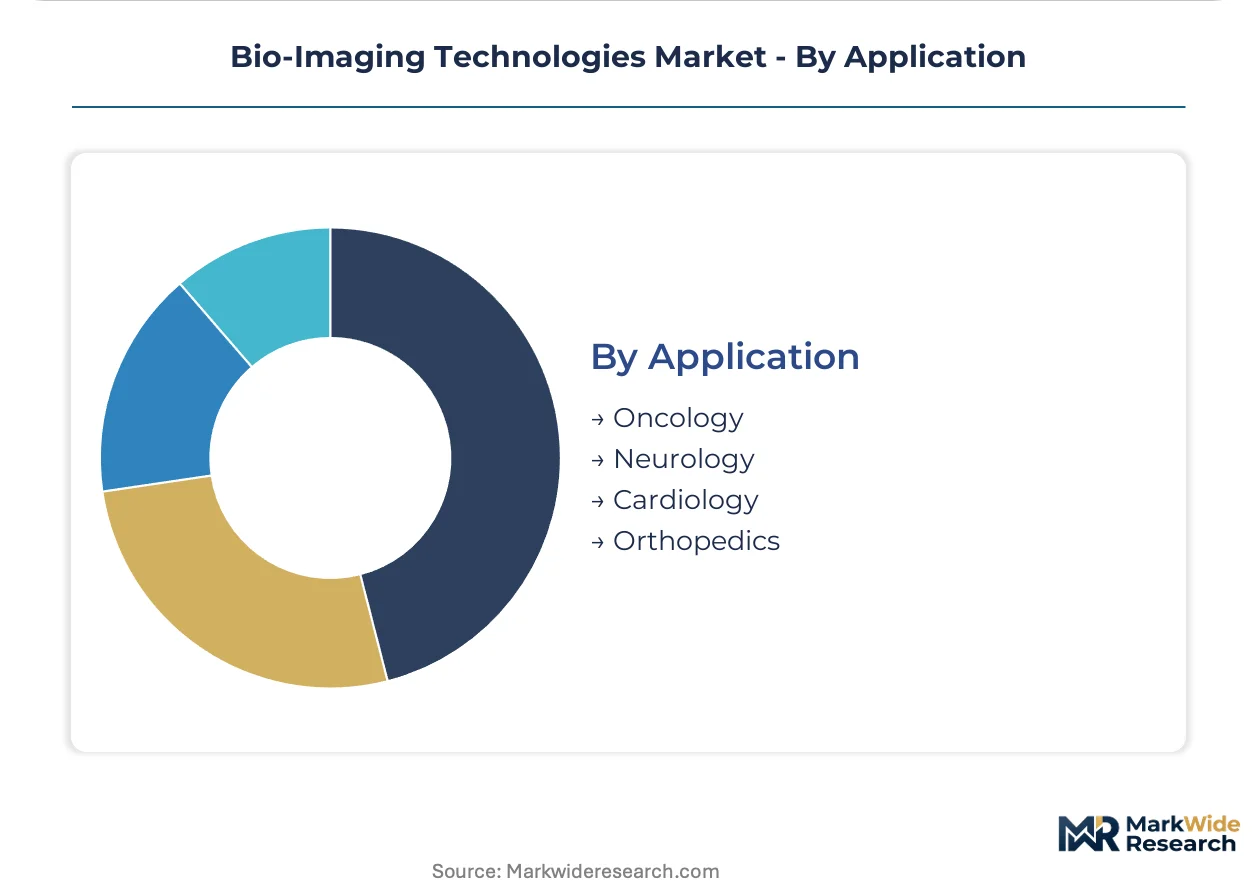
- Oncology:Staging, treatment planning, and response monitoring applications combine PET-CT fusion, multiparametric MRI, and contrast-enhanced ultrasound protocols. Academic medical center oncology departments represent the fastest-expanding end-use customer base as precision medicine protocols demand serial biomarker imaging.
- Cardiology:Stress perfusion MRI, coronary CT angiography, and echocardiography assess myocardial function and vascular patency. Tertiary centers adopt photon-counting CT and dual-source configurations for spectral tissue characterization.
- Neurology:Diffusion tensor imaging and functional MRI map white matter tracts and cortical activation patterns for surgical planning.
- Orthopedics:Musculoskeletal MRI and weight-bearing CT evaluate joint integrity and implant positioning.
Oncology commands the largest procedure volume while Cardiology shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cryogen distribution terminals underpin European helium supply chains for MRI magnet cooling. Singapore's biomedical manufacturing corridor anchors Asia-Pacific imaging device assembly. Dubai's healthcare free zones channel Middle Eastern procurement toward premium diagnostic platforms.
United States
Academic medical centers in Boston and Houston expand AI-enabled imaging procurement budgets. FDA's streamlined 510(k) pathway under 21 CFR 892 accelerates software clearance timelines for diagnostic algorithms. The Mayo Clinic cluster in Rochester, Minnesota, pilots photon-counting CT protocols for cardiac tissue characterization.
Germany
University hospitals in Munich and Heidelberg drive demand for compact MRI architectures in constrained infrastructure settings. EU Medical Device Regulation imposes clinical evidence thresholds on software-as-a-medical-device classifications. The Baden-Württemberg medical technology corridor concentrates superconducting magnet engineering expertise.
Japan
Metropolitan Tokyo hospitals prioritize point-of-care ultrasound penetration in emergency departments. PMDA harmonizes with FDA predicate device pathways for AI reconstruction algorithms. The Osaka-Kobe manufacturing belt supplies semiconductor transducer arrays for portable imaging systems.
China
Tier-2 cities in Sichuan and Shandong provinces install permanent magnet MRI designs lacking conventional shielding capacity. NMPA accelerates review timelines for domestically manufactured diagnostic devices. The Yangtze River Delta imaging equipment cluster scales production of AI-based reconstruction chipsets.
India
Diagnostic chains in Maharashtra and Karnataka deploy teleradiology networks across state licensing boundaries. CDSCO aligns medical device classification rules with international standards for software-enabled platforms. The Hyderabad medical devices park attracts contract manufacturing for compact ultrasound transducers.
Bio-Imaging Technologies Market Vendor Landscape
Listed leaders compete with private specialists across capital intensity tiers. The vendor base organizes around three structural positions: diversified conglomerates controlling cryogen supply chains, mid-scale equipment specialists, and software analytics vendors. Consolidation pressures concentrate procurement authority at integrated delivery networks. Competitive moves center on service contract unbundling and informatics platform convergence.
Within the diversified conglomerate tier, GE Healthcare and Philips Healthcare represent integrated hardware-software positioning. Hitachi Medical Corporation exemplifies compact architecture specialization for infrastructure-constrained facilities. Esaote S.p.A occupies a position among mid-scale equipment specialists with geographic concentration in European and Asian markets.
| Leading Market Players |
|---|
| Bracco Imaging S.P.A |
| Esaote S.p.A |
| GE Healthcare |
| Digirad Corporation |
| Hologic Inc. |
| Philips Healthcare |
| Hitachi Medical Corporation |
| FONAR Corporation |
| Bayer HealthCare Pharmaceuticals |
| Others |
Supply Flow & Price Mechanics
Long-term helium offtake agreements between MRI original equipment manufacturers and Qatar-based LNG extraction facilities lock in cryogen supply access while capping price volatility exposure for superconducting magnet cooling contracts. These contractual structures concentrate procurement leverage among OEMs with balance sheet capacity to secure multi-year capacity reservations, forcing smaller imaging device assemblers into spot-market exposure for critical cooling inputs.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared AI reconstruction modules from CE-marked equivalents and uncertified analytical tools. Price differentiation hinges on regulatory validation tier and after-sales service bundling, with premium tiers capturing recurring software subscription revenue. Cost compression in standard-tier imaging devices is intensifying because semiconductor foundry capacity constraints elevate chipset input costs. Independent diagnostic testing facilities exhibit highest price sensitivity, while academic medical centers prioritize clinical validation over unit economics.
Supply Chain Analysis
Strategic stockpiling of helium reserves dominates inventory strategy among superconducting magnet manufacturers, contrasting with just-in-time semiconductor procurement for AI reconstruction chipsets. Manufacturing concentration centers on Qatar, Algeria, and the United States for cryogen extraction, while Taiwan and South Korea anchor advanced node semiconductor fabrication. Raw material dependencies span rare earth elements for magnet cores, liquid helium for cooling systems, and silicon wafers for transducer arrays. Single-source vulnerability in Qatar's LNG byproduct streams poses structural supply risk. Distribution runs through integrated delivery networks negotiating enterprise-wide fleet procurement contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists across the bio-imaging technologies landscape as point-of-care deployment shifts create specialized niches for compact architecture vendors outside traditional hospital procurement hierarchies.
For Market Incumbents: Shield installed base revenue streams through captive service contract retention and cryogen supply chain backward integration into helium liquefaction capacity. Emerging independent service organizations threaten aftermarket margin pools with 15-20% cost advantages in MRI coldhead replacement segments. Priority defensive lever rests on PACS-VNA-AI workflow platform convergence that raises switching costs for radiology department customers. For New Entrants and Emerging Players: FDA's streamlined 510(k) premarket notification pathway offers accelerated clearance timelines for AI-enabled diagnostic algorithms targeting teleradiology networks. White-space concentration appears in compact permanent magnet MRI designs for Vietnamese and Indonesian facilities lacking conventional shielding infrastructure. Cloud-native image archiving deployment models enable HIPAA-compliant telemedicine transmission across state licensing boundaries as the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Capital is best deployed toward software analytics vendors with cleared AI reconstruction algorithms and recurring subscription revenue models rather than capital-intensive hardware manufacturers. Long-term viability over the projection horizon favors informatics platform specialists connecting imaging hardware to departmental workflow software. Acquisition target archetype: teleradiology service aggregators with subspecialist interpretation networks. Signal to monitor: CMS outpatient prospective payment system revisions accelerating volume migration toward freestanding imaging centers.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Pathway | Accelerated clearance timelines under 21 CFR 892 compress software vendor regulatory cycles. |
| Hospital System Partnership | Integrated delivery network fleet procurement contracts concentrate purchasing authority at enterprise level. |
| Software Companion Development | AI-based reconstruction algorithms reduce radiologist reading burdens and scan acquisition times. |
| CE Marking Pathway | EU MDR clinical evidence thresholds extend European market access timelines for algorithm-based tools. |
| Reimbursement Strategy | Medicare outpatient prospective payment system revisions favor independent diagnostic testing facilities. |
Methodological Framework
Operator-level perspectives from radiology department chairs, biomedical engineering directors, GPO contracts managers, and hospital procurement committees anchored the qualitative base for this study. Primary interview intelligence combined with secondary validation from FDA 510(k) clearance databases, CMS Medicare reimbursement filings, hospital procurement records, and EU MDR notified body guidance documents. Bottom-up equipment shipment tracking and top-down healthcare expenditure analysis enabled triangulation across independent analytical paths.
Sensitivity analysis tested forecast robustness across alternative helium supply disruption scenarios and AI regulatory pathway acceleration assumptions. Segmentation modeling spanned technology modality, product type tier, end-user facility category, and clinical application area throughout the projection horizon. CAGRs derived from equipment replacement cycle analysis, reimbursement code valuation trends, and installed base expansion patterns across academic medical centers and outpatient imaging centers.
Underlying assumptions cover stable CMS reimbursement differentials and FDA predicate device pathway continuity, with deviation risk concentrated in EU MDR retrospective validation study requirements and Qatar helium export policy shifts. Forecasts reflect these foundational conditions with explicit scenario boundaries. Revision becomes warranted when independent service organization market penetration crosses 25% share in metropolitan MRI maintenance segments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Asia-Pacific Social Media Management Market
Others
Radiation Detection Monitoring and Safety Market
Others
Digital Thermal Plates Market
Others
South Korea Intellectual Property Market
Others
Wood Stoves Market
Others
Digital Tattoos Market
Others
Smart Home Solutions Market
Others
Palatants Market
Others
Europe Aircraft Lighting Systems Market
Others
Sunflower Husk Pellets Market
Others
Europe Military 4D Printing Market
Others
North America Industrial Wearable Devices Market
Others
Tote Bags Market
Others
Smart Card Market
Others
5G Edge Computing Market
Others
Thailand Travel Retail Market