
 United Arab Emirates Oil and Gas Downstream Market | 2026-2036
United Arab Emirates Oil and Gas Downstream Market Size, Share, and Industry Trends Forecast 2026-2036
United Arab Emirates Oil and Gas Downstream Market Analytics
Abu Dhabi is reshaping the United Arab Emirates oil and gas downstream landscape through its Ruwais industrial complex expansion. Abu Dhabi National Oil Company anchors the nation's refining and petrochemical integration strategy. Emirates National Oil Company leverages its Jebel Ali refinery and retail network to sustain fuel supply dominance across the northern emirates. TotalEnergies SE competes through its downstream partnerships and lubricants distribution channels in the UAE market.
Oil and gas downstream operations encompass refining crude oil into usable products such as gasoline, diesel, jet fuel, lubricants, asphalt, and petrochemical feedstocks, typically requiring atmospheric distillation at temperatures exceeding 350°C and subsequent catalytic cracking or hydrocracking processes. These operations serve transportation, industrial manufacturing, residential heating, and power generation applications by converting raw hydrocarbons into higher-value energy and chemical products. Refined fuels and petrochemicals command the largest product-type revenue pools given their linkage to transportation and plastics manufacturing demand. The automotive and aviation end-user segments exhibit the strongest structural momentum as the UAE expands its position as a regional aviation hub and luxury vehicle market.
MOHAP oversees petroleum product registration and safety standards, while the Emirates Authority for Standardization and Metrology enforces UAE-specific fuel quality specifications that often exceed baseline Gulf Cooperation Council requirements. These regulatory layers elevate compliance costs for importers while creating protected market access for domestic refiners meeting stricter sulfur and benzene thresholds. Stakeholders must monitor how the UAE's evolving low-carbon policies and potential carbon border adjustments reshape long-term demand for conventional refined products versus biofuel blends and synthetic fuels.
Market Dynamics
The UAE's downstream sector faces structural pressure from ADNOC's Ruwais expansion, which concentrates refining and petrochemical capacity in Abu Dhabi while tightening feedstock access for independent blenders and traders operating across the northern emirates.
Growth Catalysts
- Petrochemical integration:The Ruwais Derivatives Complex converts refinery outputs into higher-margin chemical feedstocks, pulling demand from plastics manufacturers in Saudi Arabia and India.
- MOHAP product registration pathways:Streamlined safety approvals for new fuel formulations enable faster commercialization of low-sulfur diesel and specialized aviation blends.
- Aviation hub expansion:Dubai International and Al Maktoum airports drive jet fuel consumption as Emirates Airlines and low-cost carriers expand long-haul route networks.
Market Restraints
- Crude import dependency:The UAE relies on external crude sources to supplement domestic Upper Zakum and Murban grades, exposing margins to OPEC+ production quota volatility.
- Abu Dhabi capacity concentration:Over 80% of national refining sits within Ruwais, creating single-point vulnerability for supply disruptions or maintenance cycles.
- Emirates Authority for Standardization and Metrology sulfur thresholds:Stricter benzene and particulate limits raise reformer investment requirements for smaller importers.
Strategic Opportunities
- Dubai lubricants specialization:Jebel Ali's blending infrastructure and free zone status attract international additive suppliers seeking Gulf re-export positioning.
- Hydrogen co-production:Steam methane reforming at Ruwais yields gray hydrogen for ammonia synthesis, with carbon capture retrofit potential under UAE net-zero commitments.
- Marine fuel bunkering:Fujairah's port infrastructure supports very low sulfur fuel oil supply to shipping lines transiting the Strait of Hormuz.
Industry Challenges
- Process control engineering scarcity:Advanced catalytic cracking and hydrocracking operations require specialized talent that competes with Saudi Aramco and Kuwait National Petroleum for regional expertise.
- Legacy refinery configuration:ENOC's Jebel Ali facility lacks deep conversion capacity, constraining residue upgrading and forcing fuel oil exports at discounted netbacks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Arab Emirates Oil and Gas Downstream Market |
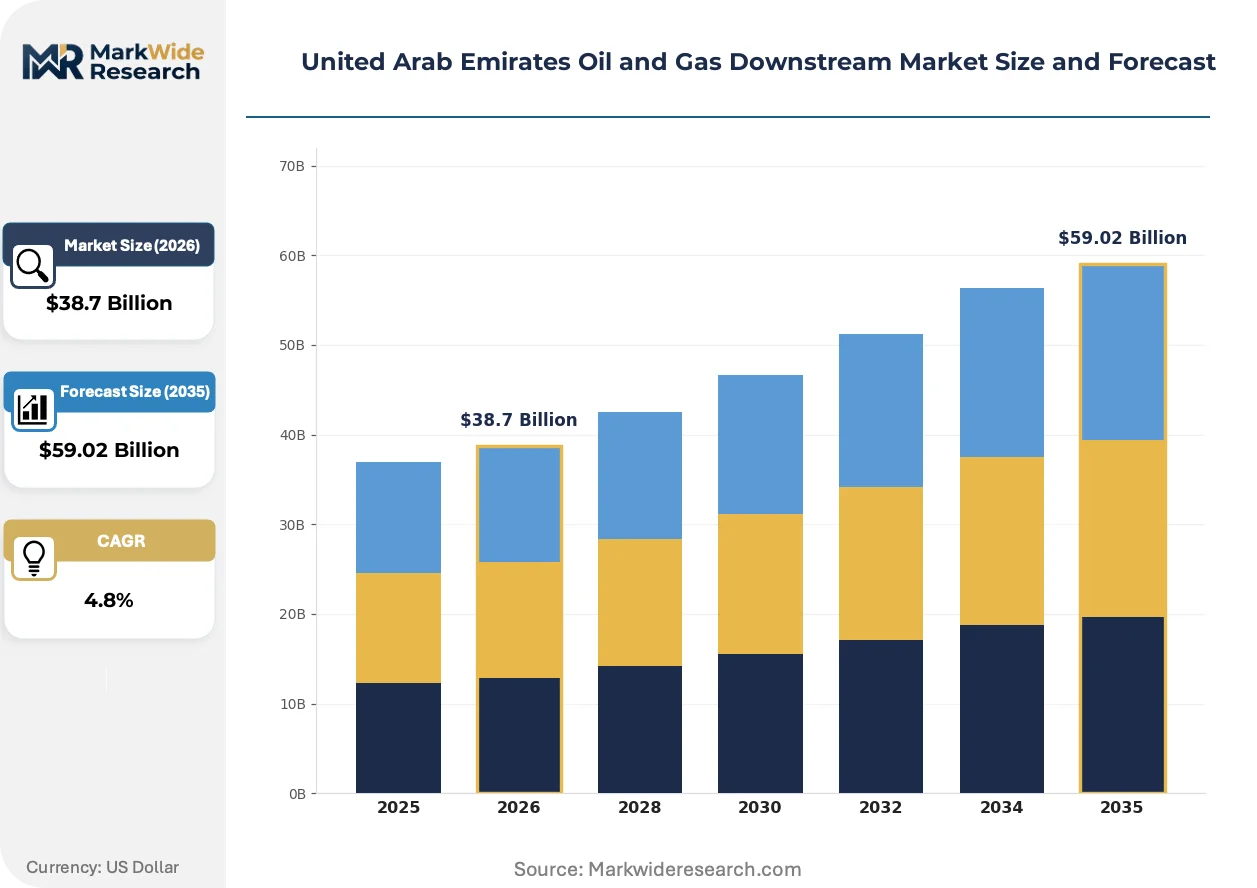
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $59.02 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refined Fuels, Lubricants, Petrochemicals, Asphalt Application: Transportation, Industrial, Residential Heating, Power Generation Distribution Channel: Retail Outlets, Distribution Hubs, Direct Supply, Online Platforms End User: Automotive Sector, Manufacturing Sector, Aviation Industry, Marine Sector |
| Companies Covered | Emirates National Oil Company, Abu Dhabi National Oil Company, TotalEnergies SE, Royal Dutch Shell PLC, Exxon Mobil Corporation, BP PLC, Mubadala Petroleum, Abu Dhabi Polymers Company Ltd, Sunrise Petroleum FZC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Arab Emirates Oil and Gas Downstream Market Evolving Landscape
Downstream operators in the UAE are retrofitting existing assets for chemical yield maximization rather than greenfield construction, reflecting capital discipline and site optimization priorities across the Gulf.
Residual fluid catalytic cracking units are hybridizing with petrochemical modes, shifting output slates from transportation fuels to propylene and aromatics. ADNOC's Ruwais refineries deploy this configuration to serve Borouge's polyolefin complexes. The technology is compressing standalone refinery economics while rewarding integrated operators with captive chemical offtake.
MOHAP and the Emirates Authority for Standardization and Metrology are tightening fuel quality specifications ahead of Gulf Cooperation Council harmonization timelines. The regulations force importers to source higher-grade components or absorb blending cost premiums. Dubai's retail fuel distributors are responding by consolidating procurement through ENOC's integrated supply chain.
Aviation fuel procurement is consolidating around long-term offtake agreements with fixed differentials, displacing spot market exposure for Emirates and Etihad Airways. Ground handlers at Dubai International now manage inventory on behalf of airlines through tankage outsourcing contracts. This shift is most visible in the jet fuel segment, where credit risk and working capital requirements have intensified post-pandemic.
United Arab Emirates Oil and Gas Downstream Market Segmentation
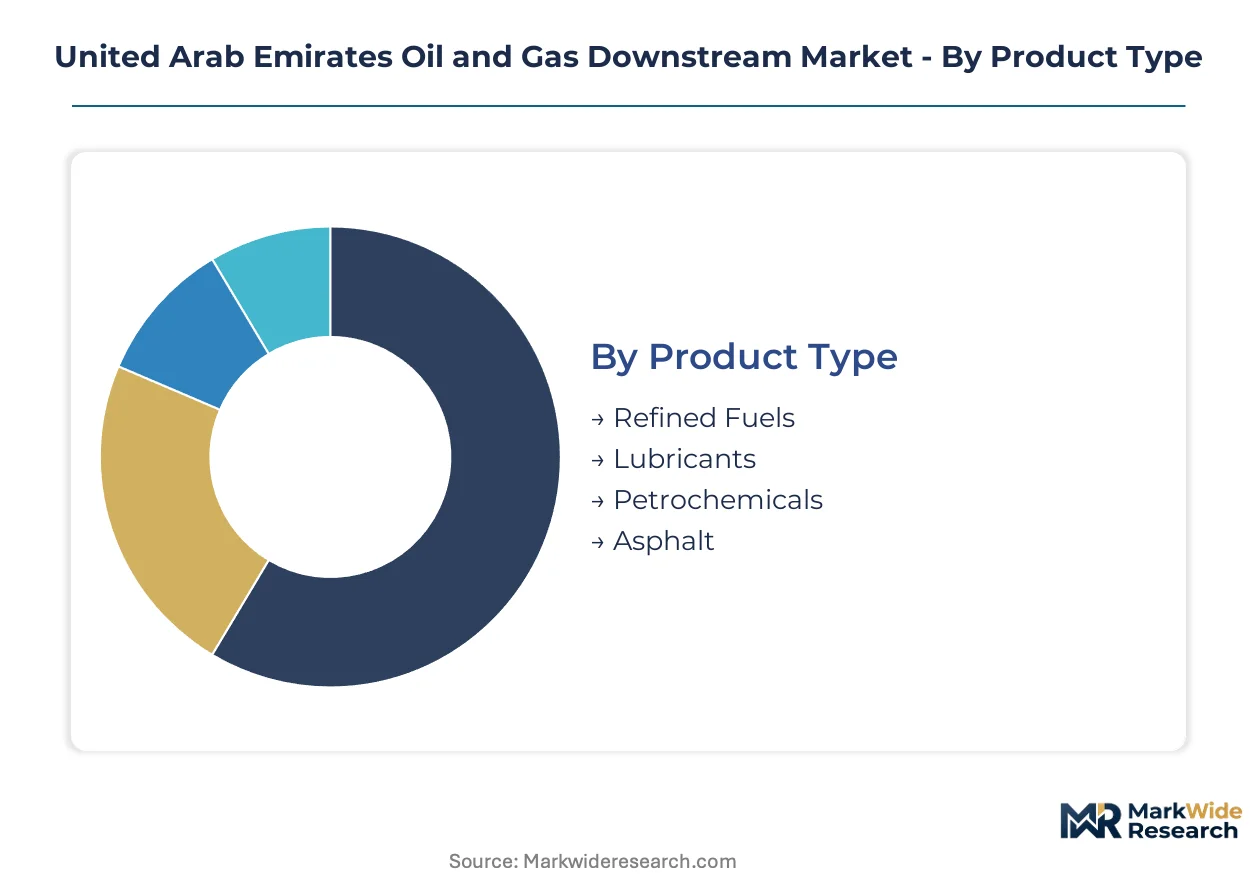
Segmentation of the UAE downstream market exposes how product specifications, channel economics, and end-use concentration shape margin capture across Abu Dhabi's integrated complexes versus Dubai's trading and blending operations. Understanding these dimensions clarifies where ADNOC's Ruwais expansion tightens supply control and where ENOC retains flexibility in northern emirates distribution.
Product Type:
Cost tier differentiation separates commodity-grade outputs from specialty formulations requiring additive packages and tighter sulfur specifications.
- Refined Fuels:Gasoline, diesel, and jet fuel produced through atmospheric distillation and catalytic cracking at Ruwais. ADNOC's Ruwais refinery complex supplies Emirates Airlines and Etihad Airways through dedicated aviation fuel pipelines, with demand anchored by Dubai International's expansion as a long-haul hub.
- Petrochemicals:Olefins, aromatics, and polyolefin feedstocks derived from residual fluid catalytic cracking integration. The Ruwais Derivatives Complex converts naphtha and refinery gases into Borouge's polyethylene and polypropylene output, pulling demand from Indian plastics manufacturers.
- Lubricants:Engine oils, industrial greases, and marine cylinder lubricants formulated with base oil and additive packages. Jebel Ali's blending infrastructure serves re-export markets across the Gulf and East Africa.
- Asphalt:Paving and roofing bitumen from vacuum residue processing. Road construction projects in Sharjah and Ras Al Khaimah absorb seasonal volumes.
Refined fuels hold installed capacity. Petrochemicals are rotating up the share rankings.
Application:
Application mix tracks the UAE's economic structure — transportation and industrial manufacturing absorb the largest volume flows, with aviation and power generation exhibiting divergent growth trajectories.
- Transportation:Road fuels for passenger vehicles, commercial trucking, and public transit fleets. Dubai's Salik toll infrastructure and metro expansion moderate gasoline demand growth even as vehicle registrations climb.
- Industrial:Process heat, feedstock, and motive power for manufacturing clusters. Ruwais Industrial City and Kizad in Abu Dhabi concentrate demand for naphtha and fuel oil.
- Residential Heating:Kerosene and LPG for household cooking and space conditioning. Northern emirates with limited district cooling infrastructure retain seasonal demand spikes.
- Power Generation:Fuel oil and natural gas liquids for electricity production. Dubai's Hassyan clean coal and solar expansion is displacing fuel oil in the emirate's generation mix.
Transportation anchors volume throughput. Power generation is losing share fastest as renewable capacity expands.
Distribution Channel:
Channel structure reflects the tension between ADNOC's integrated supply chain control and ENOC's retail network density across the northern emirates.
- Retail Outlets:Service stations and fuel pumps under ADNOC Distribution and ENOC branding. ENOC operates over 100 stations across Dubai and the northern emirates, with ADNOC dominating Abu Dhabi.
- Distribution Hubs:Bulk storage terminals and secondary distribution points. Fujairah's port infrastructure serves marine fuel bunkering and regional re-export.
- Direct Supply:Pipeline deliveries and dedicated offtake agreements for large industrial and aviation consumers. Emirates Airlines sources jet fuel through direct pipeline connections to Dubai International.
- Online Platforms:Digital procurement portals for lubricants and specialty products. B2B platforms are gaining traction among fleet operators seeking transparent pricing.
Retail outlets hold network density. Direct supply is climbing the fastest as long-term offtake agreements displace spot purchasing.
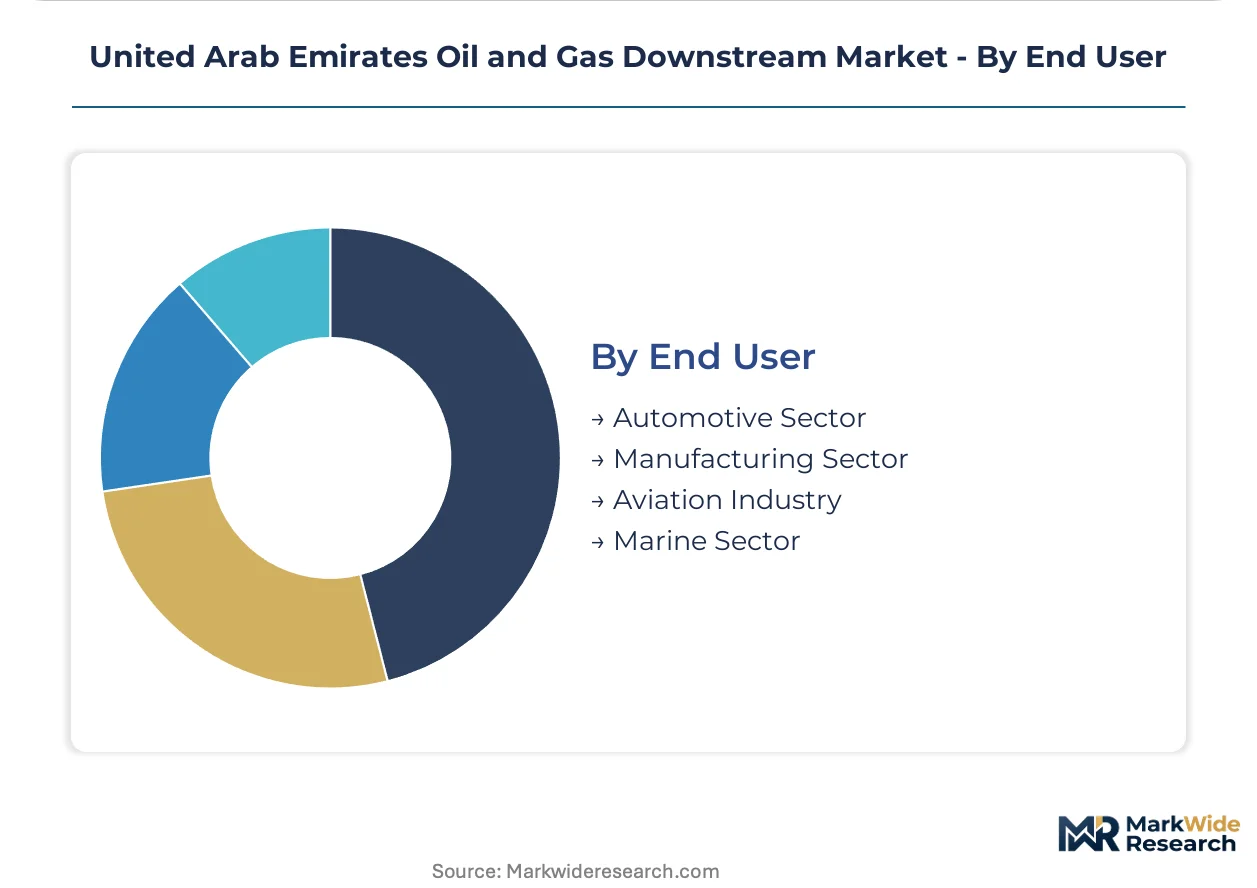
End User:
End-user concentration reveals where specification requirements tighten and where volume scale permits standardized product flows.
- Aviation Industry:Jet fuel and aviation gasoline for commercial airlines, cargo operators, and general aviation. Dubai International and Al Maktoum airports drive specification-grade demand with strict MOHAP quality registration requirements.
- Automotive Sector:Passenger vehicles, commercial fleets, and motorsport applications. Luxury vehicle penetration in Dubai sustains demand for high-performance lubricants and premium gasoline grades.
- Manufacturing Sector:Plastics, chemicals, and construction materials producers. Borouge's polyolefin complexes at Ruwais represent the largest captive chemical offtake in the GCC.
- Marine Sector:Bunker fuel and lubricants for shipping lines transiting the Strait of Hormuz. Fujairah ranks among the world's top three bunkering ports by volume.
Aviation holds specification premium. Marine is expanding most quickly as IMO 2020 compliance drives very low sulfur fuel oil demand at Fujairah.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Fujairah port complex anchors the UAE's position as a marine fuel bunkering hub for vessels transiting the Strait of Hormuz, with storage capacity exceeding 10 million cubic meters. Pipeline infrastructure connects Ruwais refining centers to Abu Dhabi's industrial zones and aviation terminals.
Abu Dhabi
ADNOC's Ruwais refining and petrochemical complex drives feedstock demand from Borouge's polyolefin plants and Emirates Steel's operations. MOHAP petroleum product registration requirements tighten as the emirate expands derivatives manufacturing. Ruwais Industrial City concentrates downstream capacity, with the Derivatives Complex converting refinery outputs into higher-margin chemical feedstocks for export markets.
Dubai
Jebel Ali refinery operations and lubricants blending infrastructure serve re-export demand across the Gulf and East Africa. ENOC's retail network density exceeds 100 stations across the emirate and northern territories. Dubai International and Al Maktoum airports concentrate aviation fuel demand, with Emirates Airlines sourcing jet fuel through dedicated pipeline connections.
Sharjah
Seasonal asphalt consumption from road construction projects and residential heating fuel demand sustain downstream product flows. The emirate's manufacturing clusters absorb naphtha and fuel oil for process applications. Hamriyah Free Zone attracts chemical traders seeking proximity to Dubai's logistics infrastructure without Jebel Ali congestion.
Northern Emirates
Ras Al Khaimah and Fujairah concentrate marine bunkering activity, with Fujairah ranking among the world's top three ports for very low sulfur fuel oil supply. The emirates lack indigenous refining capacity, importing refined products through ENOC's distribution network. Fujairah's storage terminal expansion supports regional re-export and ship refueling operations.
United Arab Emirates Oil and Gas Downstream Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the value chain. The UAE downstream sector exhibits concentrated structure around state-owned refining assets, with international oil companies occupying trading and lubricants niches. Two archetypes dominate: integrated national oil companies controlling feedstock and refining, and international majors leveraging global supply networks for product import and distribution. Capacity expansion at Ruwais and strategic partnerships for technology licensing represent the primary competitive vectors.
Among Abu Dhabi-based integrated operators, Abu Dhabi National Oil Company anchors the national refining and petrochemical integration strategy. Emirates National Oil Company, a Dubai-headquartered entity, occupies a position across northern emirates retail distribution and Jebel Ali refining. TotalEnergies SE represents the international major archetype, participating through downstream partnerships and lubricants channels. These three exemplify the tiered competitive structure separating domestic feedstock control from international trading expertise.
| Leading Market Players |
|---|
| Emirates National Oil Company |
| Abu Dhabi National Oil Company |
| TotalEnergies SE |
| Royal Dutch Shell PLC |
| Exxon Mobil Corporation |
| BP PLC |
| Mubadala Petroleum |
| Abu Dhabi Polymers Company Ltd |
| Sunrise Petroleum FZC |
| Others |
Value Network & Pricing Analysis
Ruwais refinery concentration in Abu Dhabi concentrates margin capture within ADNOC's integrated complexes while forcing independent blenders in Dubai and the northern emirates to absorb higher feedstock procurement costs. This upstream consolidation translates into pricing power asymmetry between state-backed refiners and trading-dependent distributors.
Pricing Analysis
MOHAP fuel quality registration dictates the pricing tier structure across the UAE downstream market, separating specification-compliant products from import-restricted alternatives. Pricing stratifies across premium aviation blends, standard automotive fuels, and economy-grade industrial feedstocks based on sulfur content and benzene thresholds. Cost compression in the standard gasoline tier is intensifying because ENOC's Jebel Ali facility lacks deep conversion capacity and must source higher-grade components externally. Fleet operators and independent traders exhibit the highest price sensitivity, while Emirates Airlines and Etihad Airways accept fixed-differential long-term contracts that insulate them from spot volatility.
Supply Chain Analysis
Export-control restrictions on advanced catalytic cracking technology limit refinery upgrade options for UAE operators dependent on licensed process designs from U.S. and European engineering firms. Feedstock supply draws from Saudi Arabia, Kuwait, and Iraq to supplement domestic Upper Zakum and Murban crude grades. Hydrogen, specialized catalysts, and proprietary additive packages constitute critical input dependencies. Single-source vulnerability concentrates around licensed refinery technology providers. Distribution runs through ADNOC's pipeline network to Abu Dhabi industrial zones, ENOC's Jebel Ali storage complex, and Fujairah's marine bunkering terminals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE downstream market functions as a service-attach opportunity where technical support contracts and long-term offtake agreements expand faster than standalone product margins. Lubricants blending and aviation fuel management services capture recurring revenue streams that hardware-centric refining cannot replicate.
For Market Incumbents: Insulate Ruwais-derived feedstock access through dedicated pipeline contracts with Borouge and Emirates Steel, blocking independent traders from securing comparable supply terms. Deepen backward integration into hydrogen production via carbon capture retrofits at steam methane reforming units, preempting regulatory pressure on gray hydrogen emissions. MOHAP's tightening benzene limits threaten smaller importers unable to fund reformer investments. For New Entrants and Emerging Players: Establish a beachhead in Dubai's lubricants blending segment, where Jebel Ali's free zone status and re-export infrastructure lower capital barriers compared to Abu Dhabi's refinery-dominated landscape. Target marine bunkering at Fujairah, where IMO 2020 compliance drives very low sulfur fuel oil demand without requiring indigenous refining capacity. Partner with international additive suppliers seeking Gulf distribution partners rather than competing on feedstock access. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed lubricants distributors and independent fuel traders lacking long-term supply agreements with ADNOC or ENOC. Five-to-ten year viability hinges on securing captive offtake relationships as Ruwais expansion tightens feedstock availability. Watch for ADNOC's derivatives complex commissioning timelines as the inflection signal indicating when independent blenders face margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hydrogen Production | Carbon capture retrofits at Ruwais align with UAE net-zero commitments while securing ammonia synthesis feedstock. |
| Long-term Aviation Fuel Offtake Agreement | Emirates Airlines and Etihad Airways pipeline connections displace spot market exposure for ground handlers. |
| Marine Bunkering Capacity Expansion | Fujairah's very low sulfur fuel oil supply captures IMO 2020 compliance demand from Strait of Hormuz transits. |
| Lubricants Blending Specialization | Jebel Ali's free zone infrastructure attracts international additive suppliers seeking Gulf re-export positioning. |
| Petrochemical Integration Joint Venture | Ruwais Derivatives Complex partnerships with Borouge lock in captive polyethylene and polypropylene offtake. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of ADNOC and ENOC annual disclosures, MOHAP petroleum product registration databases, and Emirates Authority for Standardization and Metrology fuel quality specifications. Interviews with refinery operations managers, aviation fuel procurement officers at Emirates and Etihad, lubricants blending specialists at Jebel Ali, and marine bunkering coordinators at Fujairah informed demand-side validation. Customs and trade data, Gulf Cooperation Council energy reports, and project development databases provided supply-side triangulation. Bottom-up capacity modeling and top-down consumption estimates were cross-referenced for convergence.
Forecast inputs incorporate refining capacity expansion timelines, petrochemical integration project milestones, and aviation hub passenger growth trajectories across the projection horizon. Segmentation dimensions include product type, application sector, distribution channel, and end-user concentration. CAGRs derive from historical throughput correlations with industrial production indices and aviation traffic data. Hydrogen co-production economics and carbon capture retrofit feasibility inform long-term structural assumptions.
Sensitivities concentrate around OPEC+ production quota adjustments, MOHAP sulfur threshold revisions, and Ruwais complex commissioning delays. Forecasts reflect documented assumptions regarding feedstock import dependency and regulatory harmonization timelines. Material shifts in UAE low-carbon policy implementation or carbon border adjustment mechanisms would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Latin America Drilling Fluids Market
Oil & Gas
Small Scale LNG (SSLNG) Market
Oil & Gas
Romania Oil and Gas Market
Oil & Gas
Canada Oil and Gas Pipeline Services Market
Oil & Gas
SCADA Oil and Gas Market
Oil & Gas
Oil Storage Terminal Market
Oil & Gas
Wellhead System Market
Oil & Gas
Oil and Gas Data Monetization Market
Oil & Gas
Crude Oil Carriers Market
Oil & Gas
Seismic Survey Equipment Market
Oil & Gas
Rotary Steerable System Market
Oil & Gas
Digital Drilling Rigs Market
Oil & Gas
Latin America Artificial Lift System Market
Oil & Gas
Africa Oil Country Tubular Goods (OCTG) Market
Oil & Gas
Algeria Oil and Gas Upstream Market
Oil & Gas
Libya Oil and Gas Midstream Market