
 Green Tea Bag Market | 2026-2036
Green Tea Bag Market Size, Share, and Industry Trends Forecast 2026-2036
Green Tea Bag Market Insights
Health enthusiasts is rotating toward premium functional tea formats, displacing traditional retail consumers as the dominant buyer archetype in volume contribution. Unilever leverages its global distribution network to sustain shelf dominance across mass-market channels. Twinings anchors its position through heritage branding and specialty-grade sourcing that commands price premiums in mature Western markets.
A green tea bag consists of processed Camellia sinensis leaves enclosed in a permeable filter material, typically paper, silk, or food-grade nylon mesh, designed for single-serve hot-water extraction of catechins and L-theanine. The product delivers standardized dosing convenience for both home consumption and commercial food service operations. Flavored and matcha variants are capturing margin pools as consumers trade up from traditional bag formats, while biodegradable packaging is accelerating as regulatory pressure and buyer preferences converge on sustainability credentials. Pyramid bags occupy the fastest-growing structural position due to superior infusion geometry and premium positioning in specialty shops and online retail channels.
FDA food contact substance regulations govern nylon and PET mesh materials in the United States, while EFSA and REACH frameworks in Europe restrict synthetic additives and mandate compostability disclosures for biodegradable claims. These standards are reshaping raw material procurement and forcing reformulation of heat-seal adhesives across the supply base. Stakeholders must monitor evolving compostability certification requirements and calibrate packaging investments against regional regulatory divergence.
Market Dynamics
Biodegradable packaging mandates under the EU Green Deal and REACH frameworks are forcing material reformulation across the green tea bag supply base, compressing margins for nylon-dependent producers while opening procurement advantages for compostable fiber innovators.
Growth Catalysts
- Functional Health Positioning:Catechin and L-theanine fortification is pulling wellness-focused consumers from conventional black tea toward premium green variants in North American and Western European retail channels.
- REACH Compostability Mandates:European regulatory pressure on synthetic mesh materials is accelerating certified biodegradable fiber adoption, creating first-mover advantages for suppliers with EFSA-compliant heat-seal adhesive portfolios.
- Pyramid Bag Geometry:Superior infusion kinetics and specialty retail shelf presence are driving format migration from flat pillow bags in Japan and South Korea convenience store networks.
Market Restraints
- Raw Material Cost Volatility:Food-grade abaca and cornstarch fiber prices fluctuate with agricultural commodity cycles, squeezing gross margins for biodegradable-focused producers relative to nylon incumbents.
- Supply Concentration Risk:Heat-seal adhesive formulation expertise clusters among German and Swiss specialty chemical suppliers, creating single-source vulnerability for compostable bag manufacturers.
- Technical Limitation:Current plant-based mesh materials exhibit 15-20% lower wet strength versus nylon, limiting high-temperature brewing applications in commercial food service environments.
Strategic Opportunities
- Underpenetrated Indian Market:Loose-leaf traditional consumption dominates, yet urban convenience-store expansion creates white space for single-serve bag formats targeting time-constrained professionals in Mumbai and Bangalore.
- Regulatory Tailwind:China's dual carbon goals and SAMR packaging sustainability directives favor domestic biodegradable fiber production, rewarding local supply chain partnerships.
- Channel Innovation:Direct-to-subscription models bypass conventional retail slotting fees, enabling margin capture and consumer data accumulation for specialty-grade matcha and flavored variants.
Industry Challenges
- Certification Timeline Compression:Industrial compostability validation under ASTM D6400 and EN 13432 protocols requires 180-day testing cycles, delaying product launches and freezing working capital in inventory.
- Skill Scarcity in Bio-Polymer Processing:Heat-seal adhesive formulation for plant-based fibers demands polymer science expertise concentrated among legacy packaging engineers unfamiliar with tea industry hygiene requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Green Tea Bag Market |
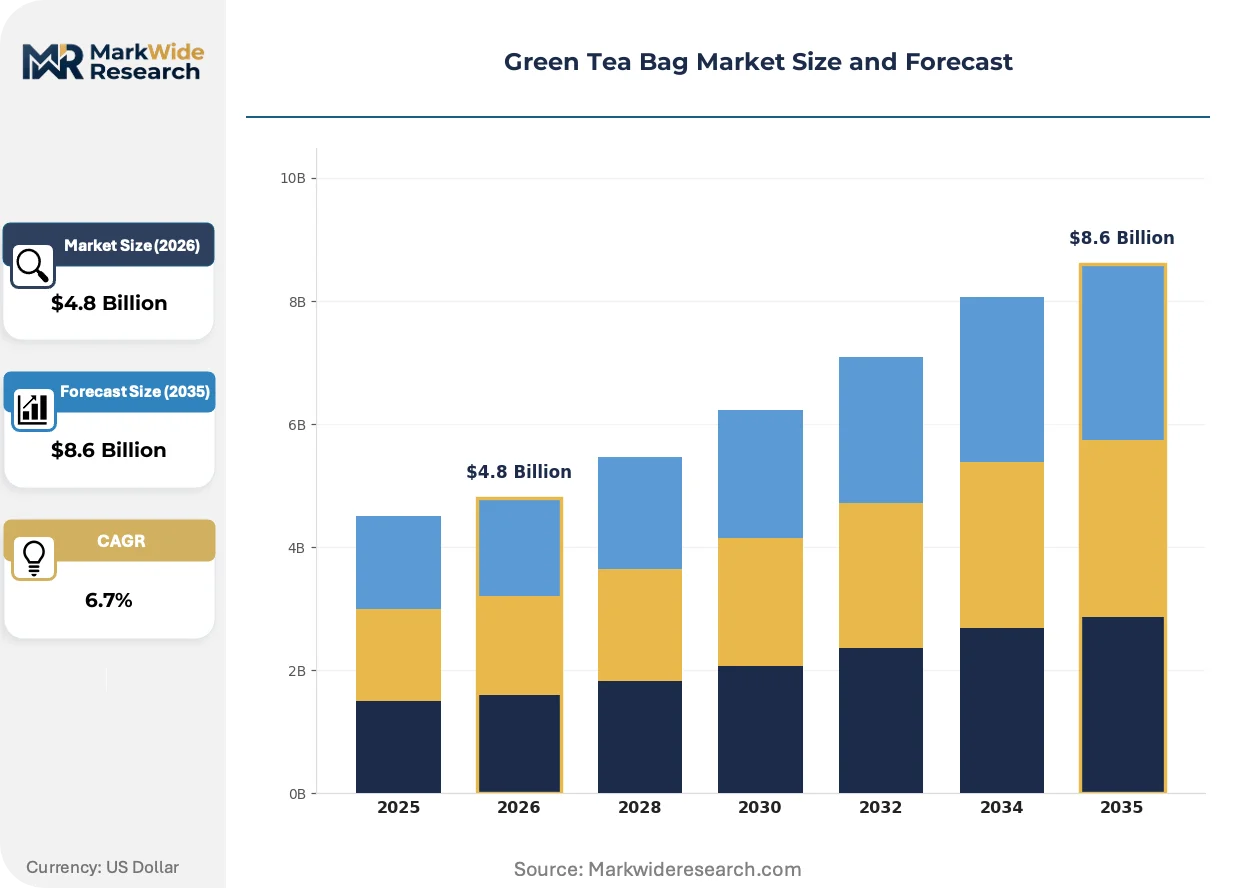
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Loose Leaf, Matcha, Flavored, Herbal Packaging Type: Biodegradable, Pyramid Bags, Traditional Bags, Tins Distribution Channel: Supermarkets, Online Retail, Health Stores, Specialty Shops End User: Health Enthusiasts, Food Service, Retail Consumers, Restaurants |
| Companies Covered | Unilever, Twinings, Lipton, Tata Consumer Products, Ito En, Associated British Foods, Nestle, Harney & Sons, Numi Organic Tea, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Green Tea Bag Market Trends and Innovations
Material science breakthroughs and regulatory compliance pressures are converging to reshape product architecture and supply chain configuration across the green tea bag category.
Plant-based polylactic acid (PLA) mesh is decomposing the historical nylon monopoly in premium bag construction. Specialty retailers and organic-certified brands in Germany and France are adopting PLA at accelerated procurement cycles. This material transition is decomposing incumbent supplier relationships while compressing price premiums for conventional synthetic mesh.
REACH framework amendments on microplastic release are tightening enforcement against conventional nylon and PET mesh materials across EU member states. Industrial heat-seal adhesive formulations face mandatory disclosure requirements for synthetic additive content. Small and mid-size private-label manufacturers in Eastern Europe are responding by consolidating procurement through certified biodegradable fiber distributors.
Wellness-oriented consumers are rotating purchasing authority from traditional grocery channels toward specialized tea boutiques and practitioner-recommended direct brands. Conventional supermarket shelf placement is losing volume contribution to subscription-curated discovery models. This behavioral shift concentrates most visibly in urban Australian and Canadian markets where functional beverage culture penetrates professional demographics.
Green Tea Bag Market Segmentation
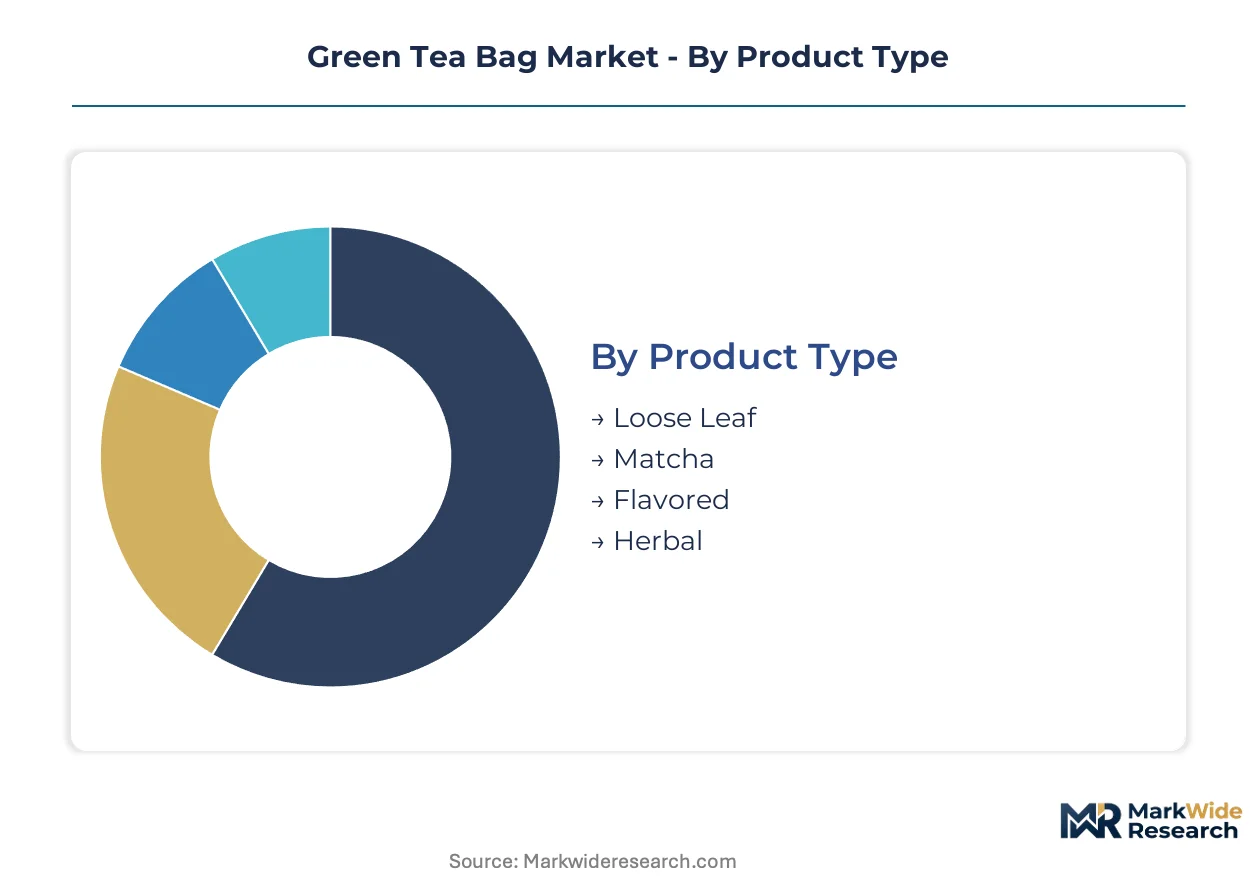
Green tea bag segmentation reveals how functional positioning and sustainability credentials are redrawing competitive boundaries. Material choices and channel strategies now determine margin capture more than volume scale alone.
Product Type:
Margin pools concentrate in value-added formats where catechin fortification and flavor innovation command price premiums over commodity-grade offerings.
- Matcha:Finely ground tencha leaves deliver concentrated L-theanine and chlorophyll content in soluble powder format. Demand clusters in Japanese convenience stores and North American wellness boutiques where ceremonial-grade positioning supports pricing power. Single-origin sourcing from Uji and Nishio regions creates supply scarcity that protects manufacturer margins.
- Flavored:Infusions incorporate jasmine, citrus, or botanical extracts to differentiate commodity green tea base. Fruit-forward variants are capturing shelf space in German and French organic retail channels where EFSA-compliant natural flavoring certifications serve as entry barriers. Seasonal limited releases rotate inventory velocity faster than traditional formats.
- Loose Leaf:Unpackaged dried leaves retain higher catechin integrity and support custom brewing rituals in Chinese and Indian households.
- Herbal:Non-Camellia sinensis botanical blends appeal to caffeine-averse demographics in Australian practitioner-recommended channels.
Matcha holds installed capacity. Flavored is rotating up the share rankings.
Packaging Type:
Volume distribution follows brewing occasion segmentation, with format choice signaling price tier and environmental commitment simultaneously.
- Pyramid Bags:Three-dimensional nylon or PLA mesh structures maximize leaf expansion and infusion kinetics. South Korean and Japanese convenience store networks are migrating flat pillow inventory toward pyramid formats where superior extraction geometry justifies 40-60% price premiums. Specialty retailers in Toronto and Sydney use visible shelf presence to drive impulse conversion.
- Biodegradable:Abaca, cornstarch fiber, or PLA constructions meet EU Green Deal compostability mandates. German and Dutch supermarket chains are delisting conventional nylon mesh as REACH enforcement tightens, creating procurement urgency for certified alternatives. Industrial compostability validation under EN 13432 protocols extends supplier qualification timelines.
- Traditional Bags:Flat paper or pillow constructions dominate emerging market entry-level price tiers.
- Tins:Metal canister formats target gift and ceremonial segments in premium Chinese and Japanese retail.
Traditional bags hold installed capacity. Biodegradable is climbing the fastest.
Distribution Channel:
Channel selection determines customer acquisition economics and data ownership, with digital-native models capturing margin pools that physical retail relinquishes.
- Online Retail:Direct-to-subscription platforms bypass slotting fees and accumulate consumption data for personalized replenishment. Australian and Canadian urban professionals are migrating discovery and repurchase toward curated delivery models where functional benefit storytelling replaces shelf visibility. Subscription lock-in reduces price sensitivity and extends lifetime value metrics.
- Specialty Shops:Staff-assisted tasting and origin storytelling command 50-100% premiums over mass-market equivalents. Tea boutiques in Paris, London, and Melbourne concentrate purchasing authority from wellness-oriented consumers who reject supermarket anonymity. Practitioner recommendation networks in Vancouver and Auckland extend credibility to functional positioning claims.
- Supermarkets:Mass-market shelf placement retains volume contribution in price-sensitive demographics.
- Health Stores:Supplement-adjacent positioning in GNC-type formats emphasizes catechin and antioxidant content.
Supermarkets hold installed capacity. Online retail is gaining share fastest.
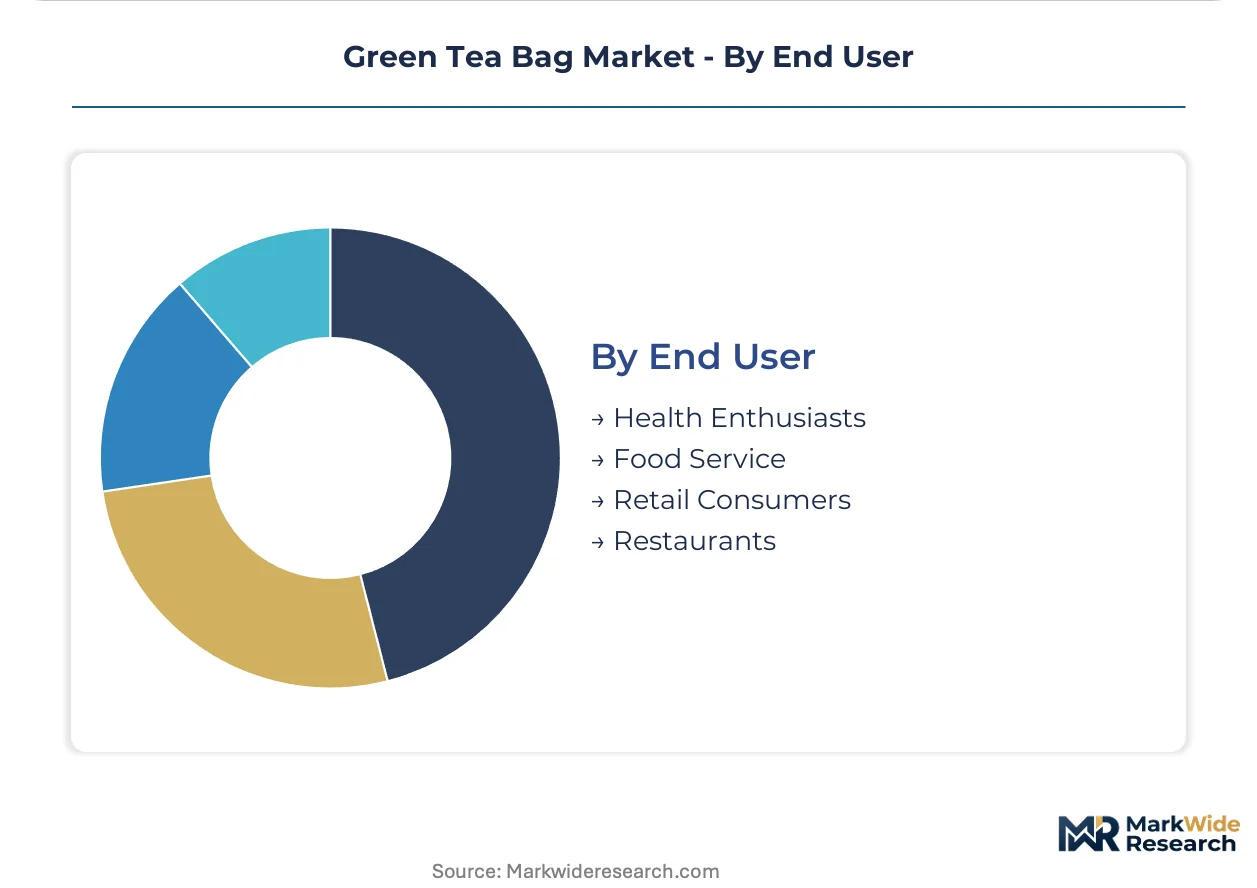
End User:
Customer archetype segmentation tracks the displacement of traditional retail buyers by wellness-motivated purchasers willing to trade up for functional credentials.
- Health Enthusiasts:Catechin-conscious consumers prioritize EGCG content, organic certification, and clean-label sourcing over price minimization. This cohort concentrates purchasing authority in North American and Western European markets where functional beverage culture penetrates professional demographics. Matcha and fortified variants capture disproportionate volume contribution from this segment.
- Food Service:Commercial brewing operations in hotels, airlines, and corporate catering demand consistent extraction and portion control. Biodegradable formats face adoption friction here due to wet strength limitations in high-temperature service environments.
- Retail Consumers:Traditional grocery channel buyers exhibit declining volume share as wellness positioning fragments the category.
- Restaurants:Fine-dining and casual formats use origin-specific offerings to signal menu sophistication.
Retail consumers hold installed capacity. Health enthusiasts are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Raw material sourcing clusters in Fujian and Zhejiang provinces, while consumption demand fragments across wellness-oriented urban centers in North America, Western Europe, and East Asia. Regulatory divergence on packaging compostability is forcing regional supply chain reconfiguration.
China
Domestic consumers in Shanghai and Beijing are migrating from loose-leaf traditions toward convenience formats, with SAMR packaging sustainability directives accelerating biodegradable fiber adoption. The dual carbon goals framework favors domestic PLA and abaca production capacity expansion in Fujian province, where tea processing heritage converges with new material science investment.
United States
FDA food contact substance regulations govern nylon and PET mesh materials, creating compliance friction for imported European biodegradable formats. Wellness-focused professionals in Brooklyn, Austin, and Los Angeles are driving matcha and functional variant demand through direct-to-subscription channels that bypass conventional retail slotting structures.
Germany
REACH enforcement and EU Green Deal mandates are delisting conventional nylon mesh from REWE and EDEKA supermarket shelves, forcing rapid supplier qualification for EN 13432-certified alternatives. Berlin and Munich specialty retailers are consolidating procurement through certified biodegradable fiber distributors to maintain shelf access.
Japan
METI standards on food contact materials and convenience store network expansion in Tokyo and Osaka are driving pyramid bag format migration from flat pillow constructions. Ito En and competing chains are leveraging superior infusion geometry to justify 40-60% price premiums in 7-Eleven and Lawson locations nationwide.
India
Loose-leaf consumption dominates nationally, yet FSSAI packaged food regulations and urban convenience store expansion in Mumbai and Bangalore create white space for single-serve formats. Time-constrained professionals in technology and financial services sectors represent the addressable cohort for bagged convenience migration.
Green Tea Bag Market Competitive Landscape
Concentration sits with multinational FMCG conglomerates controlling mass-market shelf presence through global distribution networks and heritage brand equity. The competitive structure tiers across premium specialty specialists, mid-market private-label fabricators, and scale-driven beverage giants. Strategic moves center on biodegradable packaging portfolio conversion and direct-to-consumer channel bypass of retail intermediaries.
Within the heritage-brand tier, Unilever and Twinings occupy positions that exemplify divergent competitive vectors—Unilever leveraging scale-driven mass-market penetration, Twinings anchoring specialty-grade sourcing credibility. Among Japanese beverage specialists, Ito En represents the convenience-store format innovation archetype that pyramid bag geometry enables.
| Leading Market Players |
|---|
| Unilever |
| Twinings |
| Lipton |
| Tata Consumer Products |
| Ito En |
| Associated British Foods |
| Nestle |
| Harney & Sons |
| Numi Organic Tea |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at Fujian and Zhejiang tea processing clusters shapes both raw material procurement leverage and finished goods price floors, compressing margins for biodegradable-focused producers while insulating nylon incumbents with legacy scale economies.
Pricing Analysis
Volume-discount tiering structures separate ceremonial-grade matcha from commodity pillow bags and economy-grade traditional formats. Three-tier pricing stratification across premium, standard, and economy levels tracks organic certification status and pyramid bag geometry. Pricing pressure stems from REACH-mandated material reformulation costs transferring downstream. Health enthusiasts exhibit lowest price sensitivity while retail consumers in emerging markets resist premium migration.
Supply Chain Analysis
Inbound logistics costs through Shanghai and Ningbo port congestion fluctuate with container availability on Asia-Europe trade lanes, compressing landed margins for European distributors. Raw material supply anchors in China, India, and Kenya for leaf sourcing, with German and Swiss specialty chemical suppliers controlling heat-seal adhesive formulation. Abaca and cornstarch fiber prices hinge on agricultural commodity cycles. Single-source vulnerability clusters among adhesive innovators. Distribution runs through supermarket chain procurement offices and direct-to-subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The green tea bag market is cycling through a regulatory-driven recovery phase, with EU Green Deal implementation and China's dual carbon goals creating synchronized demand pull for biodegradable formats.
For Market Incumbents: Compound shelf dominance through accelerated EN 13432 certification acquisition ahead of REACH enforcement deadlines. Secure captive supply of abaca and PLA fiber through backward integration into Fujian province material science clusters. Defend against private-label erosion by locking exclusive pyramid bag geometry patents in Japanese convenience store networks. For New Entrants and Emerging Players: Lead with biodegradable certification as the entry credential for German and Dutch supermarket delisting waves. Capture white space in Indian urban convenience stores where time-constrained professionals in Mumbai and Bangalore lack bagged format options. Deploy practitioner-recommended direct channels in Australian and Canadian wellness markets to bypass slotting fee barriers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors compostable fiber innovators with validated heat-seal adhesive portfolios over nylon-dependent legacy assets. Long-term viability across the projection horizon rests on regulatory tailwinds hardening into permanent procurement mandates. Acquisition targets should demonstrate industrial compostability validation under ASTM D6400 or EN 13432 protocols. Monitor FSSAI packaging sustainability directive implementation in India as the inflection signal for emerging market biodegradable adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Packaging Conversion | REACH enforcement delists nylon mesh from REWE and EDEKA shelves, mandating certified fiber adoption. |
| Direct-to-Subscription Channel Launch | Bypasses supermarket slotting fees while accumulating consumption data for personalized replenishment in Brooklyn and Austin. |
| Pyramid Bag Geometry Patenting | Ito En leverages superior infusion kinetics to justify 40-60% price premiums in Tokyo 7-Eleven locations. |
| Backward Integration into PLA Fiber | Dual carbon goals in Fujian province favor domestic production capacity for SAMR-compliant sustainable packaging. |
| Practitioner Recommendation Network | Wellness credentialing in Vancouver and Auckland channels converts catechin claims into purchasing authority. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with specialty tea boutique owners, supermarket category buyers, biodegradable fiber procurement managers, and heat-seal adhesive formulation chemists. Secondary validation drew from EFSA additive disclosure databases, SAMR packaging directives, FDA food contact substance filings, and EN 13432 compostability certification registries. Bottom-up volume modeling triangulated against top-down category spend estimates.
Across the analysis window, forecasts integrated product type segmentation by matcha, flavored, and traditional formats; packaging type migration from pillow to pyramid geometries; and channel shift toward direct-to-subscription models. CAGRs were derived from regression analysis against historical convenience store network expansion rates and regulatory implementation timelines. Industry-specific inputs included PLA fiber capacity buildout in Fujian province and METI food contact material standard revisions.
Forecasts assume regulatory continuity in EU REACH enforcement, China SAMR sustainability directives, and US FDA food contact substance frameworks; material policy shifts would require re-modeling. Model boundaries exclude black tea and herbal category cross-elasticity effects. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tea
Green Tea Extract Market
Tea
Africa Tea Market
Tea
Camellia Sinensis Leaf Extract Market
Tea
Smart Tea Maker Market
Tea
Global Tea Extract Market
Tea
Global Fruit Tea Market
Tea
US RTD Organic Tea Market
Tea
RTD Tea Market
Tea
Matcha Products Market
Tea
Global Tea Market
Tea
Green Tea Market
Tea
Tea Packaging Market
Tea
Butterfly Pea Flower Tea Market
Tea
Matcha Market
Tea
Light-Fermented Tea Market
Tea
Moringa Tea Market