
 Global Fruit Tea Market | 2026-2036
Global Fruit Tea Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fruit Tea Market Foresight
Market Context
Premium loose-leaf specification tiers is reorganizing competitive dynamics across the global fruit tea landscape. Unilever PLC leverages its Twinings heritage and direct-sourcing relationships to sustain quality positioning in European retail. Tata Consumer Products Ltd. anchors its growth in South Asian and diaspora markets through regional flavor specialization. Ito En, Ltd. competes in East Asian markets with green-fruit hybrid formulations and cold-brew technology leadership.
Technical Definition and Segment Structure
Fruit tea denotes a beverage category comprising dried fruits, flowers, herbs, and spices infused in hot or cold water, typically containing no Camellia sinensis leaves and caffeine-free unless blended with traditional tea bases. Commercial formulations specify infusion temperature parameters between 90°C and 100°C for optimal polyphenol and volatile compound extraction, serving both wellness-oriented retail and foodservice channels. Black Fruit Tea and Green Fruit Tea dominate volume, with Herbal Fruit Tea representing the fastest-expanding margin pool as consumers reject artificial flavoring. The Packaging Type dimension reveals structural divergence: sachet and bottle formats capture convenience-driven demand, while tin and loose-leaf formats command premium shelf positioning in specialty retail.
Regulatory Framework and Outlook
The EU Green Deal and REACH frameworks govern botanical ingredient traceability and pesticide residue thresholds for European fruit tea imports, while the FDA oversees GRAS status and labeling accuracy in the United States. Japan's Ministry of Health, Labour and Welfare enforces strict agricultural chemical standards on imported dried fruit components through positive list systems. Stakeholders must monitor evolving disclosure mandates and origin certification requirements as procurement compliance becomes a decisive market access filter.
Market Dynamics
Specialty cafés in Berlin, Paris, and Tokyo are accelerating format experimentation as loose-leaf premium specifications reorganize procurement priorities across the value chain. Cold-brew extraction systems and botanical traceability mandates now determine supplier qualification thresholds.
Growth Catalysts
- EU Green Deal disclosure mandates:Botanical sourcing transparency requirements are forcing retail chains to upgrade supplier certification protocols, creating tiered access for compliant processors.
- Cold-brew technology adoption:Ready-to-drink bottling lines with nitrogen-flush capabilities are capturing young adult demand in urban café clusters across Germany and South Korea.
- Wellness channel expansion:Pharmacy and spa retail formats in Switzerland and Austria are adding premium fruit tea SKUs to capitalize on caffeine-free positioning.
Market Restraints
- Dried fruit input volatility:Turkish and Egyptian supply concentration for rose hips and hibiscus creates margin compression during harvest disruptions.
- REACH compliance costs:Small-batch importers face disproportionate testing burdens for pesticide residue documentation under ECHA frameworks.
- Functional beverage substitution:Kombucha and adaptogenic seltzers are diverting trial budgets from fruit tea in North American convenience channels.
Strategic Opportunities
- Brazilian market underpenetration:Specialty retail infrastructure in São Paulo and Rio de Janeiro remains undeveloped for premium loose-leaf formats.
- Direct-to-subscription models:Curated monthly sachet programs are bypassing traditional wholesale markups in UK and Netherlands urban markets.
- Green-fruit hybrid formulations:Matcha-berry and sencha-citrus blends are opening new occasion-based consumption in Japanese and Australian foodservice.
Industry Challenges
- Sensory evaluation talent scarcity:Professional cupping certification for volatile compound assessment remains concentrated in Germany and Sri Lanka.
- Legacy ERP integration:Batch-level traceability systems for EU Green Deal compliance require costly middleware upgrades at mid-sized blenders.
- Origin certification timelines:Organic and fair-trade audits for African dried fruit suppliers extend procurement cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fruit Tea Market |
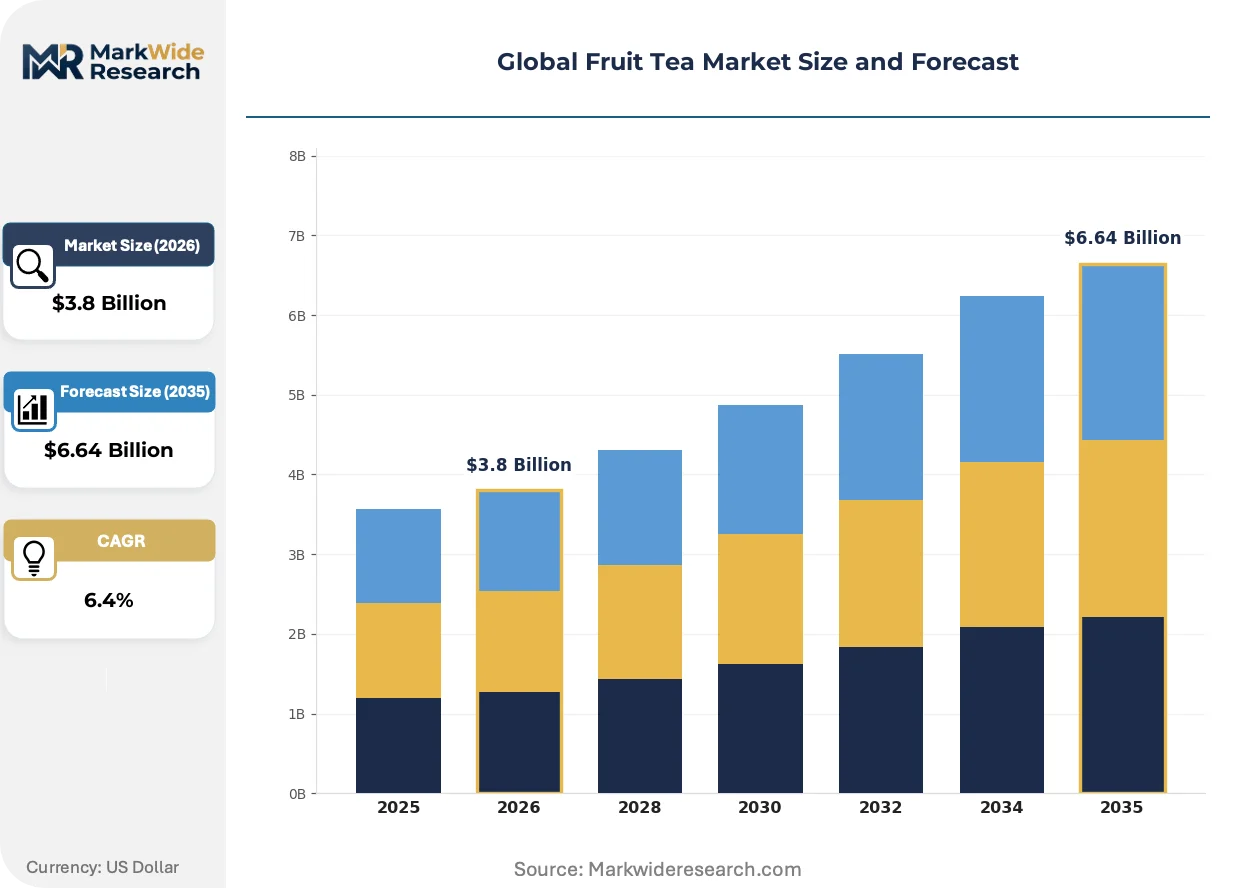
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Black Fruit Tea, Green Fruit Tea, Herbal Fruit Tea, White Fruit Tea, Oolong Fruit Tea Flavor: Peach, Citrus, Berry, Mango, Apple, Pineapple Packaging Type: Bottle, Can, Carton, Sachet, Loose Leaf, Tin Distribution Channel: Supermarkets & Hypermarkets, Convenience Stores, Online Retail, Specialty Stores, Foodservice Outlets |
| Companies Covered | PepsiCo, Inc., Ito En, Ltd., Unilever PLC, Tata Consumer Products Ltd., The Hain Celestial Group, Inc., Nestlé S.A., Keurig Dr Pepper Inc., R. Twining and Co. Ltd., The Coca-Cola Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fruit Tea Market Shifts & Advancements
Extraction technology and botanical authentication systems are compressing traditional quality-assurance timelines while opening new format possibilities. Three developments are restructuring competitive positioning.
Cold-brew nitrogen infusion systems operating at 4-8°C are displacing conventional hot-brew bottling for ready-to-drink lines. Specialty café chains in Seoul and Melbourne are adopting these systems to preserve volatile aromatic compounds. The technology is displacing shelf-stable pasteurization as the default quality threshold in premium convenience retail.
REACH Annex XVII updates on botanical allergen labeling are forcing reformulation of multi-fruit blends sold into EU markets. ECHA documentation requirements now cover 34 additional dried fruit and flower species. German and Austrian private-label suppliers are consolidating SKUs to reduce testing overhead.
Curated subscription boxes with origin-story content are capturing repeat purchase loyalty previously held by supermarket brands. Direct-to-consumer channels in London and Stockholm are replacing quarterly buying cycles with monthly personalization algorithms. This pattern is most visible among 25-34 demographic cohorts in Nordic markets.
Global Fruit Tea Market Segmentation
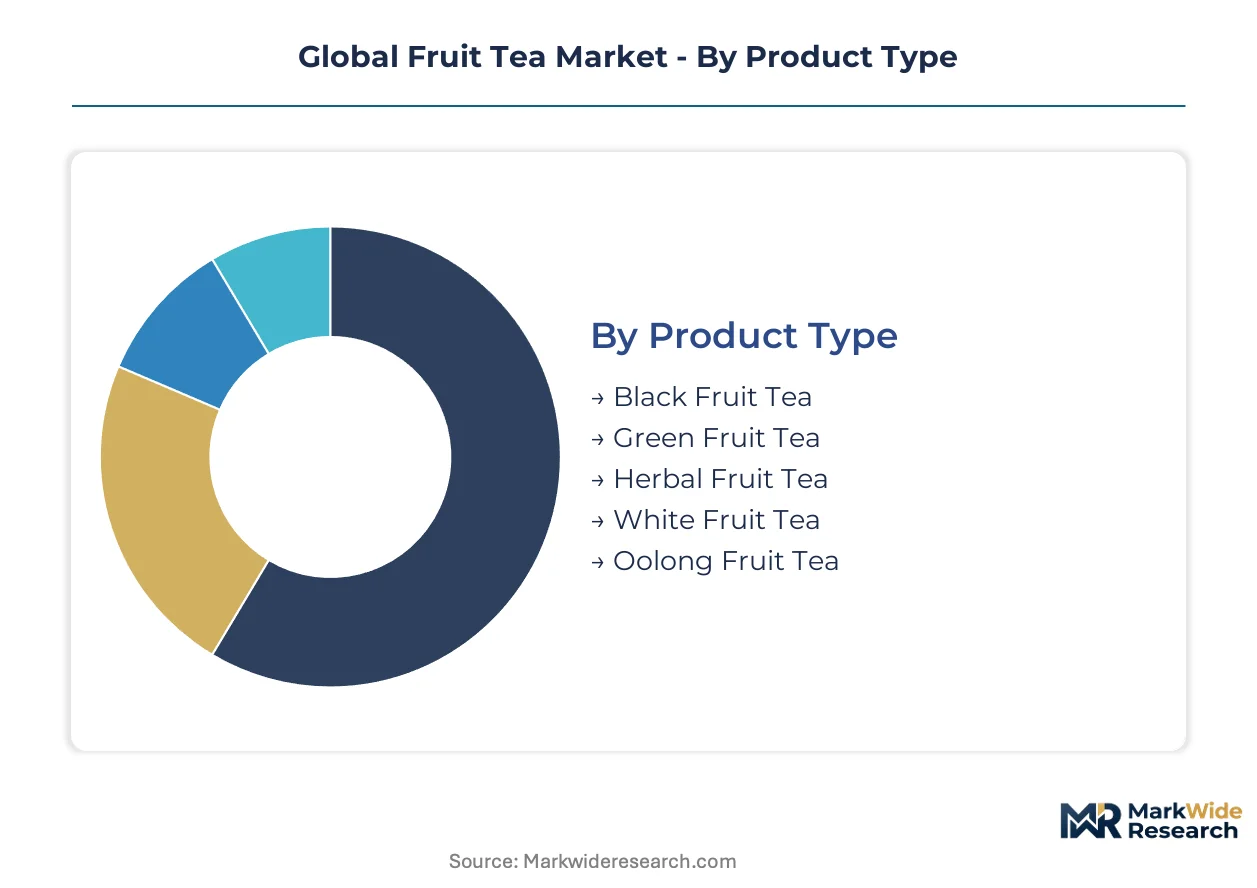
Fruit tea segmentation reveals distinct channel affinities that determine margin capture and procurement complexity. Format specifications and flavor positioning create divergent growth trajectories across retail and foodservice pathways.
Product Type:
Channel-mix patterns show traditional tea bases dominating supermarket shelf space while herbal variants capture specialty retail premiums.
- Black Fruit Tea:Camellia sinensis base blended with dried fruit pieces delivers full-bodied infusion profiles preferred in German and British retail. Demand concentrates in conventional supermarket aisles where Twinings and Ahmad Tea maintain visibility through heritage positioning.
- Herbal Fruit Tea:Caffeine-free formulations of dried fruits, flowers, and herbs command the steepest expansion trajectory in pharmacy and wellness channels across Switzerland and Austria. Clean-label rejection of artificial flavoring drives SKU proliferation in this segment.
- Green Fruit Tea:Sencha or dragonwell bases with fruit inclusions target East Asian markets and diaspora communities. Ito En and regional competitors leverage cold-brew technology leadership here.
- White Fruit Tea:Delicate silver needle bases with subtle fruit essences occupy ultra-premium gifting tiers in Chinese and Japanese duty-free retail.
- Oolong Fruit Tea:Partially oxidized bases with tropical fruit pairings serve Taiwanese bubble tea supply chains and Southeast Asian foodservice.
Black Fruit Tea dominates installed base. Herbal Fruit Tea is where expansion concentrates.
Flavor:
Cost-tier stratification separates commodity fruit powders from whole-dried-piece formulations with traceable origin documentation.
- Berry:Hibiscus-berry blends with anthocyanin color stability anchor European private-label portfolios. Turkish rose hip supply disruptions create periodic margin volatility for this high-volume category.
- Citrus:Dried orange peel and lemongrass formulations with terpene retention specifications drive ready-to-drink innovation in South Korean and Australian bottling lines.
- Peach:White peach essence dominates Japanese convenience retail and vending machine channels through seasonal limited releases.
- Mango:Alphonso and Kent varietal specificity commands premium positioning in Indian domestic markets and UK diaspora retail.
- Apple:Dried apple chunk inclusions with malic acid preservation serve Central European conventional retail as entry-level SKUs.
- Pineapple:Freeze-dried pineapple pieces with bromelain activity claims target Brazilian and Mexican wellness channel development.
Berry flavors anchor volume throughput. Citrus is climbing the fastest on cold-brew format adoption.
Packaging Type:
Volume scale separates mass-market single-serve from artisan loose-leaf procurement with batch-level traceability requirements.
- Sachet:Individually wrapped filter bags with nitrogen-flush sealing dominate UK and Netherlands supermarket distribution. Unilever's pyramid bag innovations maintain technology leadership in this high-velocity channel.
- Loose Leaf:Bulk formats with origin certification documentation command specialty retail premiums in Berlin, Paris, and Tokyo café supply chains. EU Green Deal botanical disclosure mandates favor established blenders with integrated sourcing.
- Bottle:Ready-to-drink cold-brew lines with nitrogen infusion capture Seoul and Melbourne convenience demand.
- Tin:Decorative metal caddies with resealing mechanisms serve gifting occasions in Chinese and Middle Eastern retail.
- Carton:Aseptic brick formats for foodservice fountain systems concentrate in North American quick-service chains.
- Can:Aluminum formats with pasteurization stability target Brazilian and Indonesian outdoor vending channels.
Sachet formats dominate installed base. Loose Leaf is where expansion concentrates.
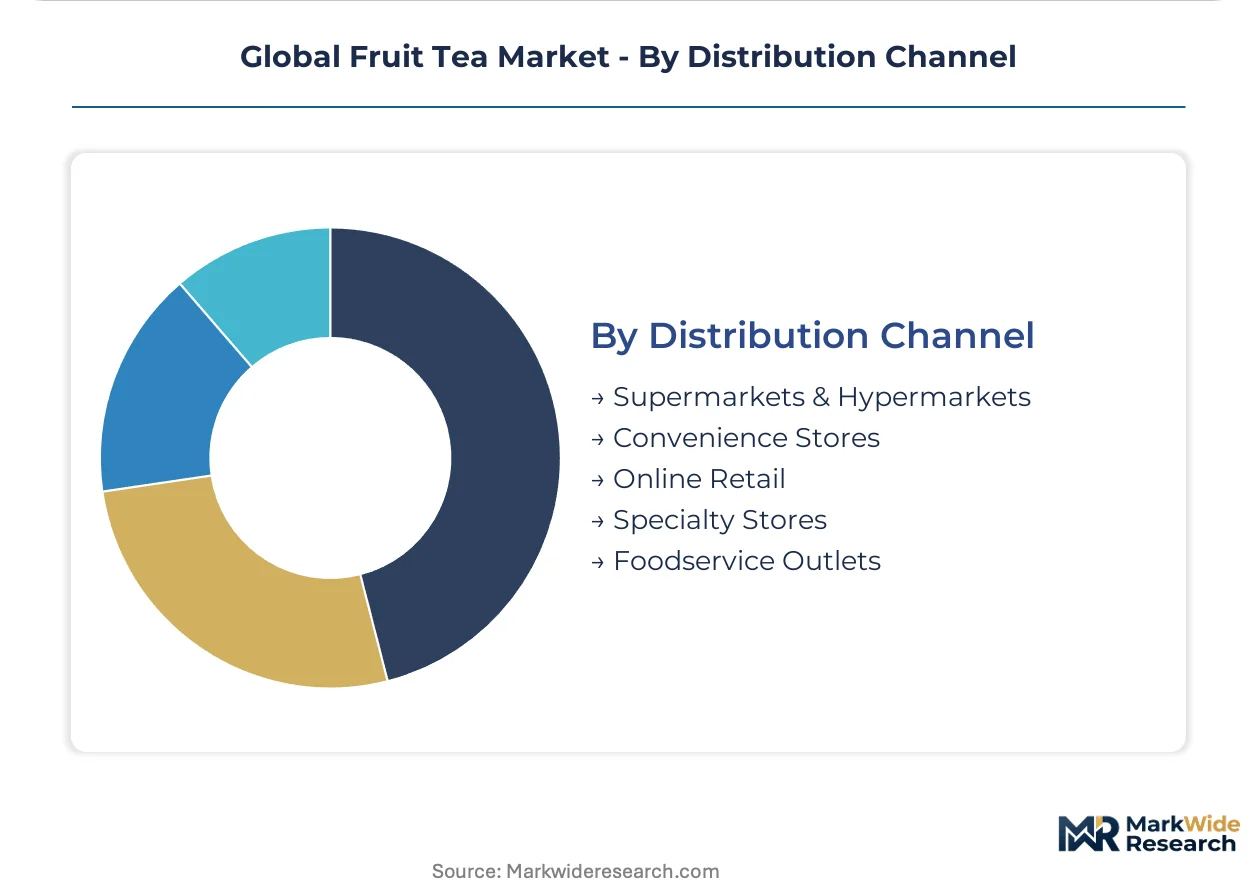
Distribution Channel:
Customer-type stratification separates impulse convenience from planned premium purchasing with subscription retention mechanics.
- Specialty Stores:Curated loose-leaf assortments with cupping service and origin storytelling command the highest margin per square meter in London, Stockholm, and Copenhagen retail clusters. Monthly subscription algorithms now displace quarterly wholesale buying cycles among 25-34 demographic cohorts.
- Online Retail:Direct-to-consumer platforms with personalization engines bypass traditional distributor markups in UK and Netherlands urban markets. Curated subscription boxes with provenance content capture repeat loyalty previously held by supermarket brands.
- Supermarkets & Hypermarkets:Standardized sachet and bottle formats with promotional slotting fees dominate volume throughput in German and French retail.
- Foodservice Outlets:Bulk loose-leaf supply with extraction equipment leasing serves Berlin, Paris, and Tokyo specialty café chains.
- Convenience Stores:Single-serve bottles and cans with chilled distribution target grab-and-go occasions in South Korean and Japanese urban corridors.
Supermarkets & Hypermarkets dominate installed base. Specialty Stores is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany runs a structural trade surplus in premium loose-leaf fruit tea, while the United States and Japan rely on imported dried fruit inputs from Turkish and Egyptian suppliers. Export competitiveness now hinges on EU Green Deal botanical traceability certification rather than commodity pricing alone.
Germany
Specialty café chains in Berlin and Hamburg drive loose-leaf procurement with cupping-service retail formats. ECHA REACH Annex XVII mandates 34-species allergen documentation for multi-fruit blends, forcing SKU consolidation among private-label suppliers. The Rhine-Ruhr industrial corridor hosts mid-sized blenders upgrading ERP systems for batch-level traceability compliance.
United States
Ready-to-drink cold-brew adoption concentrates in urban café clusters across New York and Los Angeles. FDA GRAS status reviews and labeling accuracy enforcement shape formulation decisions for botanical ingredients. Pacific Northwest specialty retailers are piloting direct-to-subscription models with monthly personalization algorithms.
Japan
Green-fruit hybrid formulations target convenience retail and vending machine channels through seasonal limited releases. METI-aligned agricultural chemical standards and positive list systems enforce strict residue thresholds on imported dried fruit components. Tokyo and Osaka specialty cafés deploy nitrogen-infusion cold-brew systems to preserve volatile aromatic compounds.
South Korea
Citrus-terpene ready-to-drink lines capture young adult demand in Seoul convenience corridors. MFDS enforces pesticide residue documentation parallel to EU standards, creating dual-compliance burdens for imported inputs. Busan-Ulsan bottling facilities are retrofitting lines with nitrogen-flush capabilities for premium positioning.
United Kingdom
Curated subscription boxes with origin-story content displace quarterly supermarket buying cycles in London and Manchester. FSA allergen labeling rules and post-Brexit import documentation requirements complicate EU-sourced botanical procurement. Midlands-based blenders face middleware upgrade costs for legacy ERP integration with traceability mandates.
Global Fruit Tea Market Competitive Landscape
Listed leaders compete with private specialists across heritage positioning and direct-sourcing capabilities. The vendor base organizes into three tiers: multinational FMCG conglomerates with retail shelf dominance, regional specialists with flavor-localization expertise, and private-label blenders serving pharmacy and wellness channels. Consolidation pressure concentrates among mid-sized European processors facing REACH compliance cost escalation. Dominant competitive moves include backward integration into Turkish and Egyptian dried fruit supply chains, plus technology licensing for cold-brew nitrogen infusion systems.
Within the heritage-brand tier, Unilever PLC and Tata Consumer Products Ltd. occupy positions defined by retail channel anchoring and diaspora market specialization respectively. Ito En, Ltd. exemplifies the technology-driven archetype through cold-brew format leadership in East Asian markets. These three entities represent distinct competitive vectors: European retail heritage, South Asian regional focus, and Japanese extraction innovation.
| Leading Market Players |
|---|
| PepsiCo, Inc. |
| Ito En, Ltd. |
| Unilever PLC |
| Tata Consumer Products Ltd. |
| The Hain Celestial Group, Inc. |
| Nestlé S.A. |
| Keurig Dr Pepper Inc. |
| R. Twining and Co. Ltd. |
| The Coca-Cola Company |
| Others |
Supply & Pricing Matrix
Eight-to-fourteen-month origin certification timelines for African dried fruit suppliers compress procurement flexibility and anchor pricing power with established blenders holding integrated sourcing relationships. This lead-time band forces smaller competitors into spot-market exposure for Turkish rose hips and Egyptian hibiscus, amplifying margin volatility during harvest disruptions.
Pricing Analysis
Specialty café buyers anchor three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on EU Green Deal compliance certification and cold-brew technology integration, with heritage-brand suppliers capturing premiums through batch-level traceability documentation. Pricing pressure stems from REACH Annex XVII testing cost escalation, compressing margins for private-label importers lacking scale. Price sensitivity concentrates among mid-sized European blenders facing ERP upgrade burdens, while wellness-channel buyers in Switzerland and Austria absorb premiums for clean-label positioning.
Supply Chain Analysis
Inventory cycles extending beyond annual harvest windows expose processors to Turkish and Egyptian supply concentration for rose hips and hibiscus. Raw material dependencies center on freeze-dried fruit pieces, nitrogen-flush packaging substrates, and cold-brew extraction equipment. Single-source vulnerability runs through Istanbul-originating dried fruit corridors subject to climate disruption. Distribution runs through Rhine-Ruhr industrial corridor blenders serving Berlin and Hamburg specialty retail clusters, with direct-to-subscription platforms bypassing traditional wholesale markups in UK and Netherlands urban markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion characteristics define this market as cold-brew nitrogen infusion systems displace conventional pasteurization in premium ready-to-drink formats, accelerating adoption among Seoul and Melbourne café clusters.
For Market Incumbents: Shield heritage positioning through backward integration into Turkish and Egyptian dried fruit supply chains, securing origin certification documentation ahead of EU Green Deal disclosure mandates. Lock in cupping-service retail formats in Berlin and Tokyo to defend against direct-to-subscription disintermediation. Prioritize middleware ERP upgrades for REACH Annex XVII compliance automation. For New Entrants and Emerging Players: Anchor in Brazilian specialty retail underpenetration, where São Paulo and Rio de Janeiro infrastructure remains undeveloped for premium loose-leaf formats. Target pharmacy and wellness channel development in Switzerland and Austria with caffeine-free herbal formulations. Deploy curated monthly subscription algorithms with origin-story content to bypass established wholesale relationships. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because REACH compliance cost escalation disproportionately burdens mid-sized European processors without captive sourcing. Acquisition candidates blend backward integration capabilities with cold-brew technology licensing positions. Watch nitrogen-infusion equipment adoption rates in Seoul and Melbourne as inflection indicators for format transition velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dried Fruit Supply | Captive sourcing from Turkish and Egyptian suppliers secures EU Green Deal traceability certification ahead of competitors. |
| Cold-Brew Nitrogen Infusion Licensing | Technology transfer agreements with Seoul and Melbourne café chains establish format leadership in premium convenience retail. |
| Direct-to-Subscription Platform Launch | Monthly personalization algorithms in London and Stockholm displace quarterly supermarket buying cycles among 25-34 cohorts. |
| ERP Traceability System Upgrade | Batch-level compliance automation reduces REACH Annex XVII documentation overhead for multi-fruit blend portfolios. |
| Wellness Channel Expansion | Pharmacy and spa retail placement in Switzerland and Austria captures caffeine-free demand with premium margin capture. |
Research Methodology
The analysis maps black fruit tea, herbal fruit tea, green fruit tea, and ready-to-drink format sub-sectors, each validated through primary interviews with procurement directors at European blenders, category buyers at German and UK retailers, and regulatory affairs specialists at ECHA-aligned testing laboratories. Secondary validation draws from EU Green Deal implementation guidance, REACH Annex XVII species documentation, customs records for Turkish and Egyptian dried fruit trade flows, and specialty café equipment procurement databases. Bottom-up volume modeling triangulates against top-down value estimates from retail audit data.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, packaging format, flavor positioning, distribution channel, and regional regulatory cluster. CAGRs derive from adoption curve analysis of cold-brew technology penetration and wellness-channel expansion velocity. Forecast inputs incorporate EU Green Deal disclosure mandate implementation timelines and nitrogen-infusion equipment deployment rates in East Asian and Australian foodservice markets.
Decision-makers should treat outputs as directional under assumptions of sustained EU Green Deal enforcement and stable Turkish-Egyptian dried fruit trade flows; material deviation would warrant model refresh. Revision becomes warranted when REACH compliance cost escalation triggers processor consolidation beyond baseline assumptions or when cold-brew format adoption crosses critical mass thresholds in convenience retail channels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tea
Bottled Tea Market
Tea
Ready-To-Drink (RTD) Tea Market
Tea
Europe Ready-To-Drink Tea Market
Tea
US Ready to Drink Tea Market
Tea
Probiotic Tea Market
Tea
Tea Subscription Market
Tea
Matcha Products Market
Tea
Kombucha Tea Market
Tea
South America Tea Market
Tea
Herbal Tea Market
Tea
Oolong Tea Market
Tea
Butterfly Pea Flower Tea Market
Tea
Matcha Market
Tea
North America Ready-To-Drink Tea Market
Tea
Tea Essence Market
Tea
Rooibos Tea Market