
 Light-Fermented Tea Market | 2026-2036
Light-Fermented Tea Market Size, Share, and Industry Trends Forecast 2026-2036
Light-Fermented Tea Market Insights
Specialty shop distribution is tilting toward premium loose-leaf formats as consumers seek provenance transparency. GT's Living Foods leverages its kombucha infrastructure to cross-merchandise light-fermented SKUs in natural grocery sets. Menghai Tea Factory anchors its position through captive sourcing of Yunnan raw leaf. Hain Celestial competes via broad portfolio breadth spanning multiple wellness beverage categories.
Light-fermented tea encompasses partially oxidized or minimally processed Camellia sinensis leaf, typically retaining higher polyphenol content and lighter liquor color than black tea equivalents, with oxidation levels ranging from unoxidized (green/white) through semi-oxidized (oolong, roughly 20-80%) and micro-fermented (yellow tea). The category serves functional beverage, ceremonial, and wellness applications where antioxidant retention and delicate flavor profiles command price premiums. Green tea occupies the largest volume position across retail channels, while oolong captures disproportionate margin pools in specialty direct-to-consumer and Asian export markets. Ready-to-drink packaging formats are gaining velocity among young adult segments, though loose leaf sustains the highest per-unit economics in health stores and tea houses.
FDA labeling requirements and USDA organic certification shape product positioning for US-bound shipments, while China's SAMR enforces GB standards for residue limits and geographical indication claims on domestic processing. EFSA health claim regulations in Europe constrain functional marketing language, pushing brands toward taste and origin narratives rather than explicit wellness positioning. Stakeholders must monitor evolving organic equivalency agreements between major producing and consuming jurisdictions, as these directly determine market access speed and certification cost structures.
Market Dynamics
Specialty beverage retailers in North America and Europe are expanding shelf space allocation for lightly oxidized teas, compressing traditional black tea facings and forcing processors to certify origin traceability systems.
Growth Catalysts
- Functional beverage positioning:Polyphenol retention in minimal oxidation processes commands price premiums in wellness channels. Health-conscious consumers prioritize antioxidant density over caffeine intensity.
- China's GB standard harmonization:SAMR enforcement of unified processing and labeling protocols reduces export friction for Yunnan and Fujian processors. Certification reciprocity accelerates market access.
- Ceremonial consumption revival:Gongfu tea preparation methods spread through specialty retail education programs. Young adult segments adopt ritual consumption as lifestyle differentiation.
Market Restraints
- Raw leaf supply concentration:Premium white and oolong grades depend on captive sourcing from Menghai and Anxi processing clusters. Weather volatility in these microclimates disrupts vintage consistency.
- Organic certification cost inflation:USDA and EU organic equivalency maintenance requires dual audit trails. Smallholder farms face exclusion from premium export tiers.
- RTD substitution pressure:Kombucha and functional sodas capture convenience-oriented trial. Loose-leaf formats lose younger demographics to ready-to-drink packaging.
Strategic Opportunities
- Micro-fermented yellow tea development:The category remains undercommercialized outside Chinese domestic markets. Processors can establish first-mover positioning in European specialty channels.
- Direct-to-consumer subscription models:Tea houses bypass wholesale margin compression through origin-story digital marketing. Provenance transparency justifies recurring revenue structures.
- Carbon labeling alignment:China's dual carbon goals create incentive structures for low-emission processing. Early certifiers access preferential procurement from sustainability-focused retailers.
Industry Challenges
- Master tea roaster talent scarcity:Traditional oxidation skill transmission lags behind commercial scaling needs. Automated monitoring systems require human calibration expertise.
- Geographical indication enforcement complexity:Fujian's Tieguanyin and Yunnan's Pu'er protected designations face dilution from adjacent province labeling. Legal frameworks struggle with cross-border e-commerce verification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Light-Fermented Tea Market |
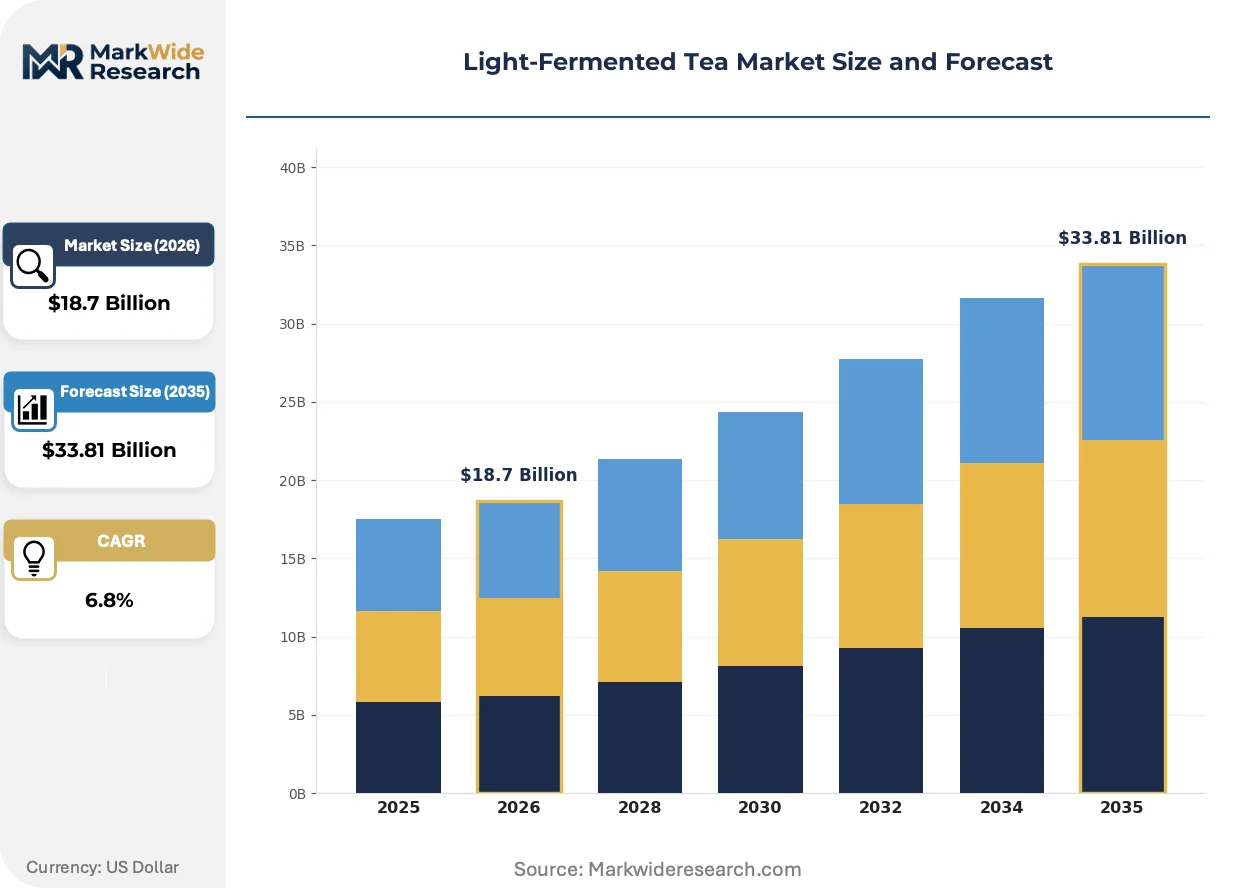
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Green Tea, White Tea, Oolong Tea, Yellow Tea Distribution Channel: Online Retail, Supermarkets, Health Stores, Specialty Shops Customer Type: Health-conscious Consumers, Tea Enthusiasts, Young Adults, Seniors Packaging Type: Loose Leaf, Tea Bags, Ready-to-drink, Eco-friendly Packs |
| Companies Covered | GT’s Living Foods, KeVita, Humm Kombucha, Live Soda LLC, Buddha Teas, Mandala Tea, Menghai Tea Factory, Hunan Provincial Baishaxi Tea Industry Co., Ltd., The Hain Celestial Group, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Light-Fermented Tea Market Trends and Innovations
Processing automation and digital provenance systems are compressing traditional artisan tea production timelines while elevating quality consistency benchmarks across export grades.
Precision oxidation control technology using real-time humidity and temperature sensors is rendering obsolete the master roaster intuition-dependent batch variation that historically defined oolong terroir. Large-scale processors in Fujian deploy these systems to achieve vintage-to-vintage consistency required by European importers. The standardization this enables is compressing price premiums for traditionally variable small-batch production.
EFSA health claim regulations constrain functional marketing language for antioxidant positioning in European markets. Brands pivot toward taste and origin narratives rather than explicit wellness claims. Premium white tea SKUs emphasize liquor clarity and harvest timing over polyphenol content in German and French retail sets.
Specialty retailers unbundle ceremonial service from product sales, converting tea houses into education venues with attached subscription fulfillment. Young adult consumers in US coastal cities purchase brewing equipment and monthly leaf shipments rather than single-origin cups. This disintermediation of café consumption concentrates lifetime value in direct relationships.
Light-Fermented Tea Market Segmentation
Light-fermented tea segmentation reveals distinct service and education requirements across channels. Product oxidation levels determine storage protocols and brewing instruction intensity. Packaging format selection directly shapes repurchase frequency and customer lifetime value calculations.
Product Type:
After-sales service intensity varies sharply across oxidation grades, with semi-fermented varieties demanding the most consumer education and brewing support.
- Green Tea:Unoxidized leaf retains maximum catechin content and requires precise temperature control during preparation to prevent astringency. Demand concentrates in China's Zhejiang and Anhui provinces where Dragon Well and Huangshan Maofeng processing clusters supply premium grades to Japanese and North American importers facing FDA residue testing protocols. Health-conscious consumers in Germany and France prioritize organic-certified shipments despite EFSA restrictions on antioxidant health claims.
- Oolong Tea:Partial oxidation ranging 20-80% creates the most complex flavor development trajectory and necessitates gongfu brewing education for optimal extraction. Fujian's Anxi and Guangdong's Phoenix Mountain processing clusters dominate supply, with Tieguanyin and Dancong varieties capturing disproportionate margins in specialty direct-to-consumer channels across Taiwan, Hong Kong, and California. Young adult segments adopt ceremonial preparation as lifestyle differentiation.
- White Tea:Minimal withering and drying preserves delicate silver needle and peony grades. Fuding and Zhenghe county processors in Fujian face weather volatility affecting vintage consistency.
- Yellow Tea:Micro-fermentation through sealed yellowing remains undercommercialized outside Chinese domestic markets. Junshan Yinzhen from Hunan commands scarcity premiums.
Green tea holds the largest share; momentum sits with oolong tea.
Distribution Channel:
Cost tier stratification separates mass-market volume plays from premium relationship-driven formats requiring substantial education investment.
- Specialty Shops:Curated loose-leaf selection with attached brewing education and origin storytelling. Urban centers in Portland, Melbourne, and London sustain highest per-unit economics through staff-trained ceremonial service.
- Online Retail:Subscription models bypass wholesale margin compression. Direct-to-consumer fulfillment from Yunnan and Fujian processors accelerates through digital provenance verification.
- Supermarkets:Standardized tea bag formats dominate shelf space. Price competition compresses margins for mid-tier processors.
- Health Stores:Organic certification and functional positioning drive placement. GT's Living Foods cross-merchandises light-fermented SKUs through kombucha infrastructure.
Specialty shops generate highest customer lifetime value; online retail expands most quickly.
Customer Type:
Application intensity varies from casual convenience consumption to ritual ceremonial practice, determining packaging and service requirements.
- Tea Enthusiasts:Pursue provenance transparency and vintage variation. Gongfu preparation methods spread through specialty retail education programs in New York and San Francisco.
- Health-conscious Consumers:Prioritize antioxidant density over caffeine intensity. EFSA regulations constrain functional marketing language in European markets.
- Young Adults:Convenience-oriented trial through ready-to-drink formats. Kombucha and functional sodas capture initial category entry.
- Seniors:Traditional preparation methods and established brand loyalty. Japan's aging demographic sustains ceremonial consumption.
Tea enthusiasts command premium pricing; young adults represent the steepest expansion trajectory.
Packaging Type:
Volume scale separates artisan small-batch production from industrial processing, with sustainability credentials increasingly determining placement.
- Loose Leaf:Highest per-unit economics in health stores and tea houses. Provenance transparency justifies recurring revenue structures through subscription fulfillment.
- Ready-to-drink:Captures convenience-oriented trial among young adult segments. Bottled formats gain velocity in convenience stores across South Korea and Taiwan.
- Tea Bags:Standardized portion control for foodservice and hospitality. Pyramid sachets bridge quality perception gaps.
- Eco-friendly Packs:Compostable and plastic-free materials align with China's dual carbon goals. Early certifiers access preferential procurement from sustainability-focused retailers in Scandinavia.
Loose leaf sustains margin leadership; eco-friendly packs gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's cold-chain reefer terminals anchor European light-fermented tea import infrastructure, while China's high-speed rail network connects Yunnan and Fujian processing clusters to coastal export gateways.
China
Domestic consumption of white and oolong varieties drives volume through ceremonial gifting channels. SAMR enforces GB standards for residue limits and geographical indication claims on Tieguanyin and Pu'er labeling. Menghai Tea Factory in Yunnan and Anxi processing clusters in Fujian supply premium grades to specialty buyers in Taiwan and California.
United States
Specialty beverage retailers in Portland and New York expand shelf space for loose-leaf formats as young adults adopt gongfu preparation. FDA labeling requirements and USDA organic certification shape product positioning for import shipments. GT's Living Foods leverages kombucha infrastructure to cross-merchandise light-fermented SKUs in natural grocery sets.
Germany
Health-conscious consumers in Berlin and Hamburg prioritize organic-certified green tea despite EFSA restrictions on antioxidant health claims. EU organic equivalency agreements with China determine certification cost structures for Yunnan processors. Specialty tea houses in Munich sustain highest per-unit economics through staff-trained ceremonial service.
Japan
Aging demographics sustain ceremonial consumption of minimally processed leaf in Tokyo and Kyoto. METI oversees JIS standards alignment for imported oolong grades from Fujian. Osaka-based distributors consolidate procurement from Zhenghe county white tea processors for premium retail channels.
United Kingdom
London specialty shops convert tea houses into education venues with attached subscription fulfillment for young adult segments. Trading relationships with Fujian exporters predate regulatory harmonization, creating entrenched procurement patterns. Manchester and Edinburgh clusters develop direct-to-consumer digital provenance systems bypassing wholesale margin compression.
Light-Fermented Tea Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in raw leaf sourcing and oxidation processing. The vendor base stratifies across three tiers: multinational wellness beverage conglomerates with cross-category portfolios, regional processing clusters with captive sourcing relationships, and direct-to-consumer tea houses with subscription infrastructure. Two strategic moves dominate competitive positioning: backward integration into Yunnan and Fujian raw leaf supply, and portfolio diversification into ready-to-drink formats targeting convenience-oriented demographics.
Within the wellness beverage platform tier, The Hain Celestial Group, Inc. exemplifies broad portfolio breadth spanning multiple categories, while GT's Living Foods occupies a position leveraging kombucha infrastructure for cross-merchandising. Among China-based processing specialists, Menghai Tea Factory anchors its competitive stance through captive sourcing of Yunnan raw leaf. These three entities represent distinct archetypes: multinational conglomerate, platform-integrated functional beverage player, and vertically integrated regional processor.
| Leading Market Players |
|---|
| GT's Living Foods |
| KeVita |
| Humm Kombucha |
| Live Soda LLC |
| Buddha Teas |
| Mandala Tea |
| Menghai Tea Factory |
| Hunan Provincial Baishaxi Tea Industry Co., Ltd. |
| The Hain Celestial Group, Inc. |
| Others |
Pricing and Supply Chain Analysis
The Port of Hamburg's cold-chain reefer terminals anchor European import infrastructure, with per-container logistics costs compressing margins for Yunnan and Fujian processors while enabling three-tier price stratification across German specialty retail channels. This freight corridor's cost dynamics concentrate pricing power among vertically integrated processors with captive leaf supply, forcing smaller exporters toward economy-tier positioning in supermarket tea bag formats.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates the category. Certification grade and volume scale drive price differentiation, with USDA organic and EU organic equivalency commanding substantial premiums in North American and German health stores. Cost compression in mid-tier loose-leaf formats is intensifying because automated oxidation monitoring systems reduce vintage variation that historically justified artisan premiums. Young adult convenience seekers exhibit highest price sensitivity, while tea enthusiasts purchasing direct-to-consumer subscriptions show lowest elasticity.
Supply Chain Analysis
Raw leaf sourcing draws from China's Yunnan and Fujian provinces, with secondary processing clusters in Taiwan and limited Japanese white tea production. Premium oolong grades rest on Tieguanyin cultivar stock from Anxi county, while silver needle white tea hinges on Fuding's Da Bai varietals. Single-source vulnerability from weather volatility in these microclimates disrupts vintage consistency. Distribution runs through specialty retailers in Portland and London, direct-to-consumer subscription fulfillment, and kombucha-cross-merchandised health store sets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense against kombucha and functional sodas capturing convenience-oriented trial among young adult demographics. The category's premium positioning requires active guarding against RTD format erosion.
For Market Incumbents: Pre-empt kombucha substitution by cross-merchandising light-fermented SKUs through functional beverage infrastructure in natural grocery sets. Backward integration into Menghai and Anxi raw leaf supply secures captive sourcing against weather-driven vintage disruption. Certification investment in carbon labeling aligns with China's dual carbon goals and unlocks preferential procurement from Scandinavian sustainability-focused retailers.
For New Entrants and Emerging Players: Yellow tea micro-fermentation in European specialty channels offers underpenetrated white-space opportunity, with Junshan Yinzhen scarcity premiums replicable through Hunan processor partnerships. Digital provenance verification enables direct-to-consumer subscription models bypassing wholesale margin compression in London and Melbourne urban centers. Gongfu brewing education programs convert tea houses into acquisition funnels with attached recurring revenue structures.
For Investors and Strategic Acquirers: Carve-out targets emerge from wellness beverage conglomerates divesting non-core tea portfolios; regional processing clusters with captive Yunnan sourcing and established EU organic equivalency present consolidation candidates. Long-term viability frames around ceremonial consumption revival and carbon-labeled premium positioning. Monitor EFSA health claim regulation relaxation as inflection signal for functional marketing expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Raw Leaf Supply | Captive sourcing from Menghai and Anxi clusters insulates against weather-driven supply disruption. |
| Carbon Labeling Certification | China's dual carbon goals create preferential procurement access with Scandinavian sustainability-focused retailers. |
| Direct-to-Consumer Subscription Launch | Digital provenance verification from Yunnan processors enables recurring revenue bypassing wholesale compression. |
| Gongfu Brewing Education Programs | Tea houses in New York and San Francisco convert ceremonial service into customer lifetime value concentration. |
| Yellow Tea Micro-Fermentation Development | Junshan Yinzhen scarcity premiums establish first-mover positioning in undercommercialized European specialty channels. |
Research Methodology
Desk research of customs trade records, GB standard filings, and organic certification databases preceded structured interviews with Yunnan processing cluster managers, Fujian tea factory technical directors, specialty retailer category buyers in Portland and London, and kombucha brand portfolio managers. Primary fieldwork with these stakeholders combined with secondary validation from SAMR regulatory disclosures and EFSA health claim registers. Bottom-up volume modeling across oxidation grades and top-down value triangulation against import reefer terminal throughput data converged on segment-level estimates.
Assumptions held China's GB standard harmonization trajectory and EU organic equivalency maintenance as fixed boundary conditions, while varying RTD substitution rates and ceremonial consumption revival intensity across the projection horizon. Segmentation modeling spanned oxidation level, distribution channel format, packaging type, and customer application intensity. CAGRs derived from vintage-to-vintage price elasticity observed in German and US specialty retail audit data, with inputs from Menghai Tea Factory capacity utilization and Port of Hamburg cold-chain throughput trends.
The forecast holds incumbent behavior within observed patterns; aggressive moves by kombucha platform integrators into tea category expansion would shift outcomes substantially. Cross-checking against EFSA regulatory filing trajectories and SAMR enforcement patterns is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tea
Edible Tea Market
Tea
High Protein Tea Market
Tea
Tea Subscription Market
Tea
Herbal Tea Market
Tea
Organic Tea Market
Tea
Europe Green Tea Market
Tea
Tea Essence Market
Tea
RTD Tea Market
Tea
White Tea Extract Market
Tea
Instant Tea Premix Consumption Market
Tea
Asia-Pacific Green Tea Market
Tea
Matcha Market
Tea
Black Tea Base Bubble Tea Market
Tea
Moringa Tea Market
Tea
Global Fruit Tea Market
Tea
Green Tea Market