
 Matcha Products Market | 2026-2036
Matcha Products Market Size, Share, and Industry Trends Forecast 2026-2036
Matcha Products Market Outlook
Café and foodservice buyer concentration is pivoting toward premium ceremonial-grade suppliers as chain procurement teams consolidate vendor lists. ITO EN Ltd. leverages its integrated Japanese supply chain to secure consistent tencha leaf access across North American retail channels. Marukyu Koyamaen anchors the high-end segment through direct-to-consumer distribution and centuries-old stone-grinding expertise. Encha competes on organic certification density, sourcing exclusively from single-estate farms in Uji and Kagoshima.
Matcha products encompass finely ground powder from shade-grown Camellia sinensis leaves, typically processed through de-stemming, steaming, drying, and granite mill grinding to particle sizes below 10 microns for optimal suspension and bioactive retention. The powder serves as a functional ingredient delivering concentrated L-theanine and catechin content for beverages, confectionery, and nutraceutical applications. Loose leaf and powder formats occupy the largest volume share, though ready-to-drink formulations are capturing the fastest growth trajectory as convenience-oriented consumers shift from at-home preparation. Organic and traditional form categories command premium pricing, while culinary-grade powders serve as the margin pool workhorse for industrial bakery and confectionery clients.
Japan's Ministry of Agriculture, Forestry and Fisheries enforces JAS organic standards that constrain export volumes from non-certified processors, while the FDA's Food Safety Modernization Act mandates preventive controls for importers of powdered green tea products. The European Food Safety Authority evaluates health claim substantiation for matcha-derived catechin products under the Nutrition and Health Claims Regulation, directly shaping permissible marketing language. Stakeholders must monitor evolving pesticide maximum residue limits across Japan, the United States, and EU member states, as tightening thresholds threaten sourcing flexibility from conventional tencha cultivation regions.
Market Dynamics
Café procurement teams are consolidating vendor lists around vertically integrated Japanese suppliers capable of delivering certified organic ceremonial-grade powder at industrial scale. This concentration is compressing margins for mid-tier blenders while rewarding estates with direct tencha cultivation control.
Growth Catalysts
- Functional beverage formulation:Ready-to-drink matcha lattes and energy drinks are capturing shelf space from conventional coffee SKUs in US and UK convenience retail channels.
- JAS organic certification density:Export eligibility under Japan's Ministry of Agriculture standards is unlocking premium pricing tiers for certified processors in European specialty foodservice.
- Wellness-oriented quick-service restaurant expansion:Health-focused chains across Germany and France are adding matcha-based beverages and desserts to permanent menus.
Market Restraints
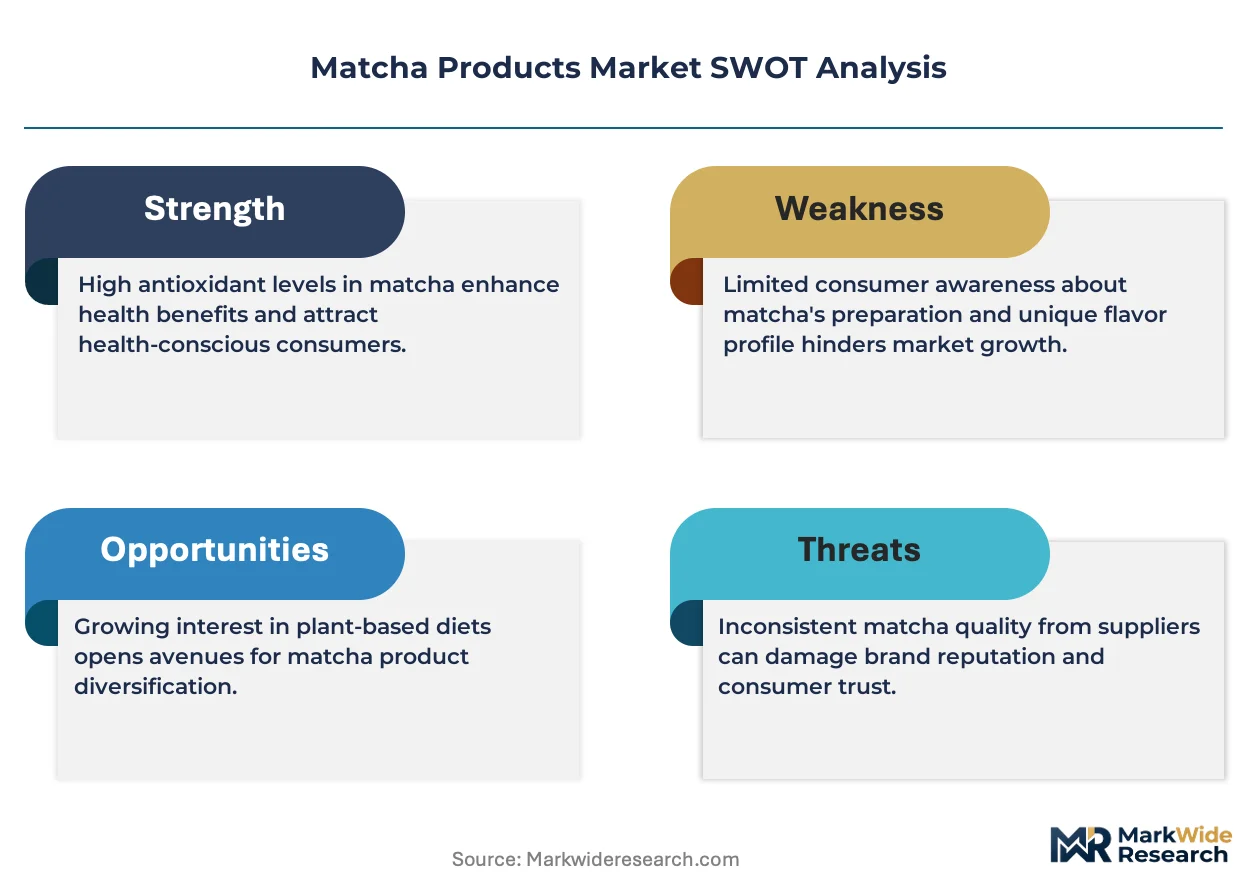
- Tencha leaf supply concentration:Shade-grown cultivation remains geographically concentrated in Uji, Kagoshima, and Shizuoka prefectures, creating weather-dependent input volatility.
- EU Novel Food compliance friction:Novel Food Regulation substantiation requirements delay market entry for new matcha-derived ingredient formats by 18-24 months.
- Granite mill grinding bottleneck:Traditional stone-grinding to sub-10-micron particle size limits production throughput and capital efficiency versus roller milling alternatives.
Strategic Opportunities
- Underpenetrated German foodservice:Bakery and confectionery manufacturers in Bavaria and North Rhine-Westphalia represent untapped industrial-grade powder demand.
- EFSA health claim substantiation:Successful catechin-related claims under the Nutrition and Health Claims Regulation would unlock pharmaceutical and nutraceutical channel expansion.
- Direct-to-consumer subscription models:Single-estate brands are bypassing traditional import distributors through proprietary e-commerce platforms in the United States.
Industry Challenges
- Organic certification timeline compression:JAS and USDA Organic dual-certification processes require 3-5 year field conversion periods that strain working capital for estate operators.
- Traceability system integration:Blockchain and ERP platform deployment across multi-tier Japanese supply chains demands technical expertise scarce among traditional tea cooperatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Matcha Products Market |
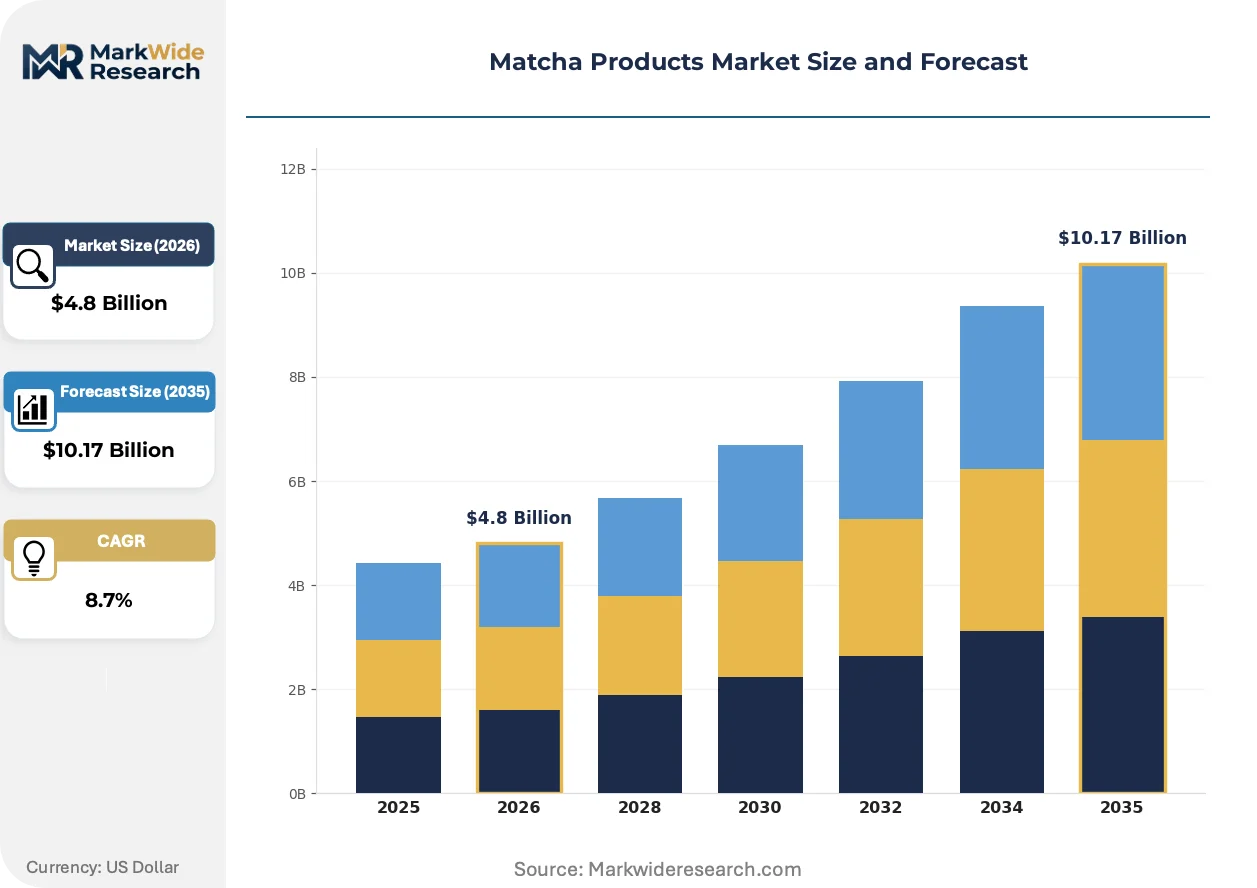
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Loose Leaf, Powder, Tea Bags, Ready-to-Drink End User: Food Service, Retail Consumers, E-commerce, Health Stores Form: Organic, Natural, Culinary, Traditional Application: Beverages, Bakery, Confectionery, Supplements |
| Companies Covered | AIYA America Inc., The AOI Tea Company, ITO EN Ltd., Marukyu Koyamaen, DoMatcha, Encha, Ippodo Tea Co., Midori Spring Ltd., Vivid Vitality Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Matcha Products Market Strategic Shifts
Processing technology and regulatory science are converging to redefine quality verification and procurement patterns across matcha value chains. Three developments warrant particular attention.
Cold-brew soluble matcha powder is unifying beverage preparation workflows by eliminating traditional whisking requirements. US café chains and office coffee service providers are adopting these instant-dissolve formats for labor cost reduction. The technology is unifying equipment standards across previously incompatible preparation methods, compressing supplier qualification criteria toward solubility performance metrics.
EFSA's evolving position on catechin health claims under the Nutrition and Health Claims Regulation is forcing reformulation strategies among nutraceutical developers. Permitted marketing language now hinges on specific EGCG concentration thresholds and consumption quantity disclaimers. Powder suppliers serving the European functional food segment are restructuring product specifications to align with these evidentiary requirements.
Buyer concentration among North American specialty coffee chains is reshaping contract structures toward multi-year procurement agreements with price collars. Direct estate relationships are displacing traditional importer intermediaries for volume purchasers seeking traceability guarantees. This consolidation is most visible in California and New York metropolitan markets where flagship store density supports dedicated supply lines.
Matcha Products Market Segmentation
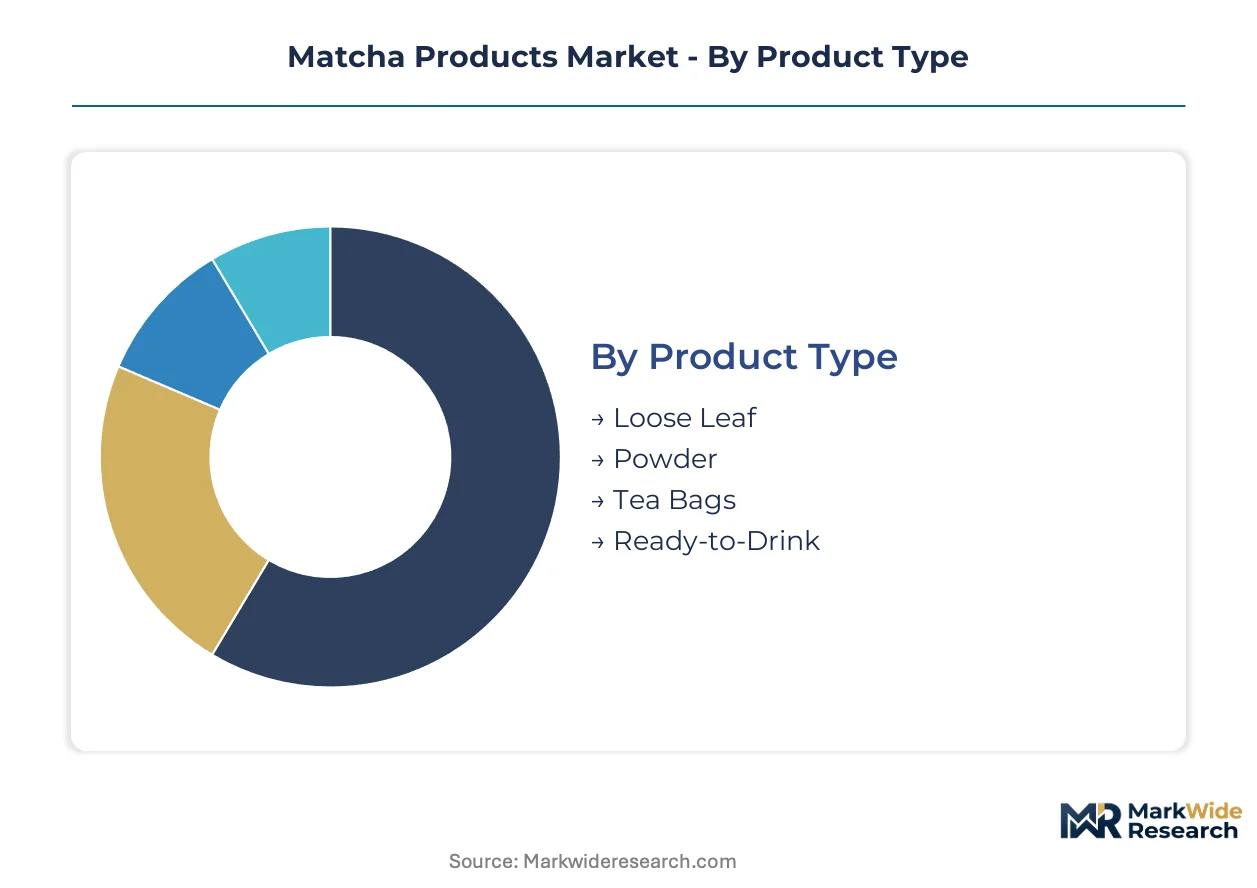
Matcha product segmentation reveals how shade-grown tea processing bifurcates between ritual preparation and industrial ingredient supply. Category boundaries blur as café chains source ceremonial-grade powder for beverage programs while food manufacturers procure culinary grades for confectionery applications.
Product Type:
Customization-to-standardization tension peaks in this category, with traditional preparation formats competing against convenience-engineered alternatives for shelf space and menu placement.
- Loose Leaf:Unprocessed tencha leaves requiring home grinding retain highest catechin integrity. Specialty tea retailers in Japan and select US metropolitan markets serve enthusiasts seeking granular control over particle size and oxidation timing.
- Powder:Granite-milled particles below 10 microns deliver optimal suspension and bioactive retention. Café procurement teams across California and New York metropolitan areas concentrate vendor consolidation here, demanding certified organic ceremonial grades at industrial scale.
- Tea Bags:Pre-portioned sachets containing lower-grade fannings target convenience-oriented retail channels. This format sacrifices some L-theanine concentration for preparation speed.
- Ready-to-Drink:Shelf-stable lattes and energy formulations capture US and UK convenience retail expansion. Cold-brew soluble technologies are eliminating traditional whisking requirements for foodservice adoption.
Most installed capacity flows through Powder. Expansion is steepest in Ready-to-Drink.
End User:
Cost tier stratification separates premium ceremonial procurement from commodity-grade industrial sourcing, with channel-specific certification requirements driving supplier selection.
- Food Service:Chain procurement teams at specialty coffee and wellness-focused quick-service restaurants demand traceable tencha supply with JAS organic certification. Direct estate relationships are displacing traditional import intermediaries for volume purchasers.
- Retail Consumers:Single-estate brands leverage proprietary e-commerce platforms to bypass distributors. Subscription models concentrate in the United States among urban professionals seeking ceremonial-grade authenticity markers.
- E-commerce:Digital-native brands compete on organic certification density and origin storytelling. Logistics infrastructure favors shelf-stable powder over temperature-sensitive ready-to-drink alternatives.
- Health Stores:Functional positioning around EGCG and L-theanine content drives premium pricing. Staff education requirements favor brands with substantiated health claim documentation.
Food Service commands the largest procurement volumes. E-commerce climbs the fastest as direct-to-consumer brands capture margin previously allocated to import distributors.
Form:
Application-driven specifications create four distinct quality grades, each with discrete customer qualification criteria and pricing benchmarks.
- Organic:Dual JAS and USDA Organic certification requires 3-5 year field conversion periods. Export eligibility under Japan's Ministry of Agriculture standards unlocks premium European specialty foodservice tiers.
- Natural:Minimally processed without synthetic inputs but lacking formal certification. This segment serves price-sensitive retail channels where organic premiums face resistance.
- Culinary:Coarser grind tolerances and higher bitterness profiles optimize for industrial bakery and confectionery manufacturing. Bavarian and North Rhine-Westphalia processors represent underpenetrated demand.
- Traditional:Centuries-old stone-grinding expertise from Uji estates anchors the high-end segment. Direct-to-consumer distribution preserves margin and provenance narrative control.
Traditional commands the highest unit economics. Organic expands most quickly as regulatory compliance becomes a procurement gate.
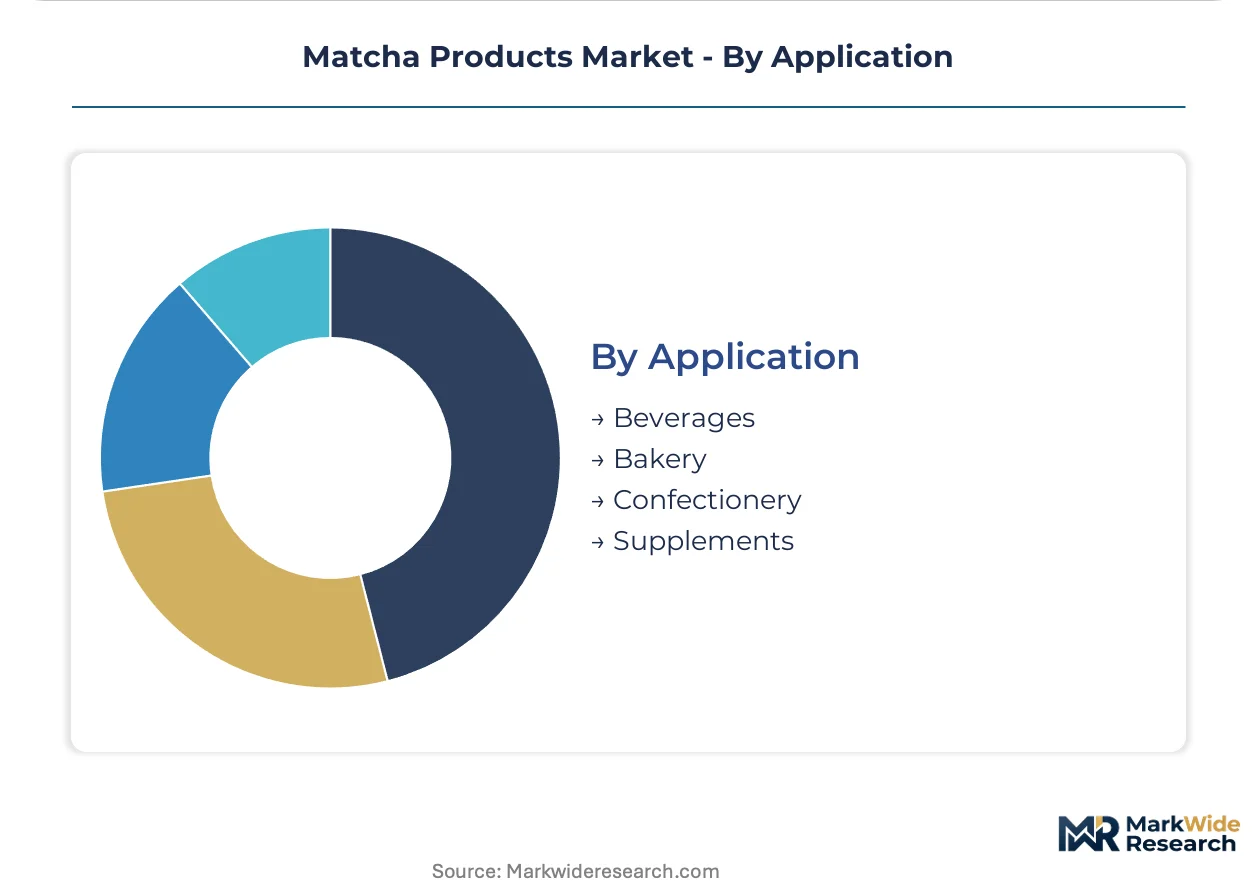
Application:
Customer type differentiation separates ritual consumption from functional ingredient deployment, with formulation requirements dictating powder specification and supplier technical support intensity.
- Beverages:Latte and energy drink formulations demand cold-brew soluble powder for equipment compatibility. US café chains adopt instant-dissolve formats for labor cost reduction.
- Bakery:Heat-stable matcha powders with adjusted particle distribution prevent color degradation during oven processing. Industrial manufacturers prioritize consistent batch performance over origin prestige.
- Confectionery:Fine chocolate and patisserie applications require precise fat compatibility and moisture control. Japanese supply chain integration ensures consistent tencha leaf access for premium chocolate houses.
- Supplements:EFSA health claim substantiation under the Nutrition and Health Claims Regulation shapes permissible marketing language. EGCG concentration thresholds and consumption quantity disclaimers restructure product specifications for European functional food developers.
Beverages absorb the greatest powder volumes. Supplements gain share fastest as nutraceutical channel expansion hinges on regulatory approval.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States buyers command premium ceremonial-grade volumes while German foodservice channels remain underpenetrated for industrial-grade procurement. Japan's export regulatory framework constrains supply elasticity for both markets.
United States
Specialty coffee chains in California and New York metropolitan areas consolidate vendor lists around JAS-certified ceremonial-grade suppliers. The FDA's Food Safety Modernization Act mandates preventive controls for powdered green tea importers. Functional beverage startups in Los Angeles and Austin drive ready-to-drink formulation demand.
Japan
Domestic tencha cultivation concentrates in Uji, Kagoshima, and Shizuoka prefectures with weather-dependent output volatility. The Ministry of Agriculture, Forestry and Fisheries enforces JAS organic standards that constrain export volumes from non-certified processors. Traditional stone-grinding estates in Kyoto prefecture anchor the high-end segment through direct-to-consumer channels.
Germany
Bakery and confectionery manufacturers in Bavaria and North Rhine-Westphalia represent untapped industrial-grade powder demand. EFSA evaluates health claim substantiation under the Nutrition and Health Claims Regulation. Wellness-focused quick-service restaurants in Berlin and Munich are adding matcha-based items to permanent menus.
United Kingdom
Ready-to-drink matcha lattes capture shelf space from conventional coffee SKUs in London convenience retail channels. The Food Standards Agency aligns with EFSA guidance on catechin product marketing language. Premium café density in Greater Manchester supports dedicated supply line development.
France
Health-focused chains across Paris and Lyon expand matcha dessert and beverage offerings. ANSM monitors novel food ingredient safety assessments alongside EFSA coordination. Fine chocolate houses in Île-de-France source Japanese supply chain-integrated powders for patisserie applications.
Matcha Products Market Competitive Environment
Japanese producers anchor the premium tier; North American specialists hold distribution and formulation capabilities. Market structure concentrates around vertically integrated estates with direct tencha cultivation control, compressing margins for mid-tier blenders. Three archetypes dominate: heritage Japanese estates with centuries-old processing expertise, organic-certified single-estate brands, and scale-oriented distributors serving industrial foodservice. Competitive moves center on backward integration into tencha cultivation and multi-year procurement agreements with price collars.
Within the heritage estate tier, Marukyu Koyamaen and Ippodo Tea Co. exemplify traditional stone-grinding expertise and direct-to-consumer positioning. ITO EN Ltd. occupies a scale-driven position with integrated Japanese supply chain coverage across North American retail channels. Among organic-certified specialists, Encha represents single-estate sourcing density from Uji and Kagoshima regions.
| Leading Market Players |
|---|
| AIYA America Inc. |
| The AOI Tea Company |
| ITO EN Ltd. |
| Marukyu Koyamaen |
| DoMatcha |
| Encha |
| Ippodo Tea Co. |
| Midori Spring Ltd. |
| Vivid Vitality Ltd. |
| Others |
Value Chain & Pricing Dynamics
Cold-brew soluble powder technology is compressing traditional stone-grinding premiums while concentrating procurement power among US café chains capable of specifying instant-dissolve performance metrics. This shift simultaneously erodes margins for heritage Japanese estates and rewards vertically integrated suppliers with laboratory-scale formulation capabilities, restructuring how certification premiums translate into delivered cost.
Pricing Analysis
Capacity additions in Vietnam and Indonesia are reshaping price floors for culinary-grade powder entering European industrial channels. Three-tier pricing structure across ceremonial, premium, and culinary grades anchors the market, with JAS organic certification and particle size distribution serving as primary price differentiation drivers. Cost compression in mid-tier blends is intensifying because North American chain procurement teams are consolidating vendor lists around certified suppliers at industrial scale. Foodservice buyers exhibit lowest price sensitivity, while private-label retail channels face margin pressure from organic certification compliance costs.
Supply Chain Analysis
Single-source vulnerability sits with Japanese tencha cultivation concentrated in Uji, Kagoshima, and Shizuoka prefectures. Geographic supply concentration centers on Japan for ceremonial-grade leaf, Vietnam for culinary-grade processing, and the United States for ready-to-drink formulation. Raw material dependencies include shade-grown tencha leaf, granite mill grinding equipment, and cold-brew soluble processing chemicals. Tariff exposure on Japanese agricultural imports into the EU threatens sourcing flexibility. Distribution runs through direct estate relationships displacing traditional import intermediaries for volume purchasers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The matcha market reads as a late-cycle quality story where café procurement teams are pivoting toward premium ceremonial-grade specifications as chain beverage programs upgrade from culinary-grade inputs. This demand-shift rewards suppliers with demonstrable tencha cultivation control and JAS organic certification density.
For Market Incumbents: Deepen backward integration into shade-grown tencha cultivation to secure captive supply against weather-dependent output volatility in Japanese prefectures. Invest in cold-brew soluble processing capabilities to defend position against instant-dissolve specialists capturing US foodservice procurement. Certification investment in dual JAS-USDA Organic standards remains essential for European export eligibility. For New Entrants and Emerging Players: Blockchain-enabled traceability platforms offer a technology-first wedge into transparency-starved segments where traditional tea cooperatives lack technical deployment expertise. Target German bakery and confectionery manufacturers in Bavaria and North Rhine-Westphalia as the most penetrable industrial-grade demand pocket. A direct-to-consumer subscription model with single-estate origin storytelling bypasses margin-stacked import distribution channels. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier blenders without direct tencha cultivation control facing margin compression from vendor list consolidation. Long-term viability over a multi-year window favors estates with Kyoto heritage processing expertise and established North American retail channel relationships. The signal to watch is EFSA catechin health claim substantiation progress, which would unlock pharmaceutical channel expansion and re-rate functional ingredient suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tencha Cultivation | Captive shade-grown leaf supply secures JAS organic certification pipeline for North American chain procurement. |
| Cold-Brew Soluble Processing Investment | Labor cost reduction for US café chains eliminates traditional whisking equipment compatibility barriers. |
| Dual JAS-USDA Organic Certification | Export eligibility under Japan's Ministry of Agriculture standards unlocks European specialty foodservice tiers. |
| Direct-to-Consumer Subscription Launch | Single-estate brands bypass traditional import distributors to capture margin in US urban professional segments. |
| EFSA Health Claim Substantiation Partnership | Successful catechin-related claims would restructure product specifications for European nutraceutical channel expansion. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with Japanese tea estate operators, North American café chain procurement directors, European specialty foodservice buyers, and organic certification auditors with secondary validation. Trade data from Japan's Ministry of Agriculture, US FDA import records, EFSA guidance documents, and customs filings across German and UK ports anchored volume estimates. Bottom-up tencha cultivation area modeling and top-down beverage formulation demand triangulation cross-checked segment outputs.
Segment-weighting approaches distributed value across product type, end user, form, and application dimensions over the projection horizon. Powder, ready-to-drink, and loose leaf categories carried distinct growth assumptions reflecting convenience-oriented consumer shifts. CAGRs derived from historical trade flow analysis, procurement contract tenor examination, and chain menu expansion tracking. Forecast inputs included JAS organic certification timeline constraints, EFSA regulatory decision pipelines, and cold-brew soluble technology adoption curves in US foodservice.
The model holds under stable Japanese agricultural export policy and consistent EFSA regulatory interpretation; deviation in tencha harvest yields or Novel Food substantiation delays would shift volume trajectories. Forecasts reflect documented assumptions about chain procurement consolidation rates and wellness-oriented quick-service restaurant expansion. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tea
Green Tea Market
Tea
Global Ready-To-Drink Green Tea Market
Tea
Rooibos Tea Market
Tea
Matcha Tea Market
Tea
Organic Tea Market
Tea
Camellia Sinensis Leaf Extract Market
Tea
Light-Fermented Tea Market
Tea
Edible Tea Market
Tea
Europe Ready-To-Drink Tea Market
Tea
Detox Tea Market
Tea
Asia-Pacific Tea Market
Tea
Global Fruit Tea Market
Tea
Nitro Tea Market
Tea
Herbal Tea Market
Tea
Asia-Pacific Green Tea Market
Tea
US Ready to Drink Tea Market