
 Africa Tea Market | 2026-2036
Africa Tea Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Tea Market Outlook
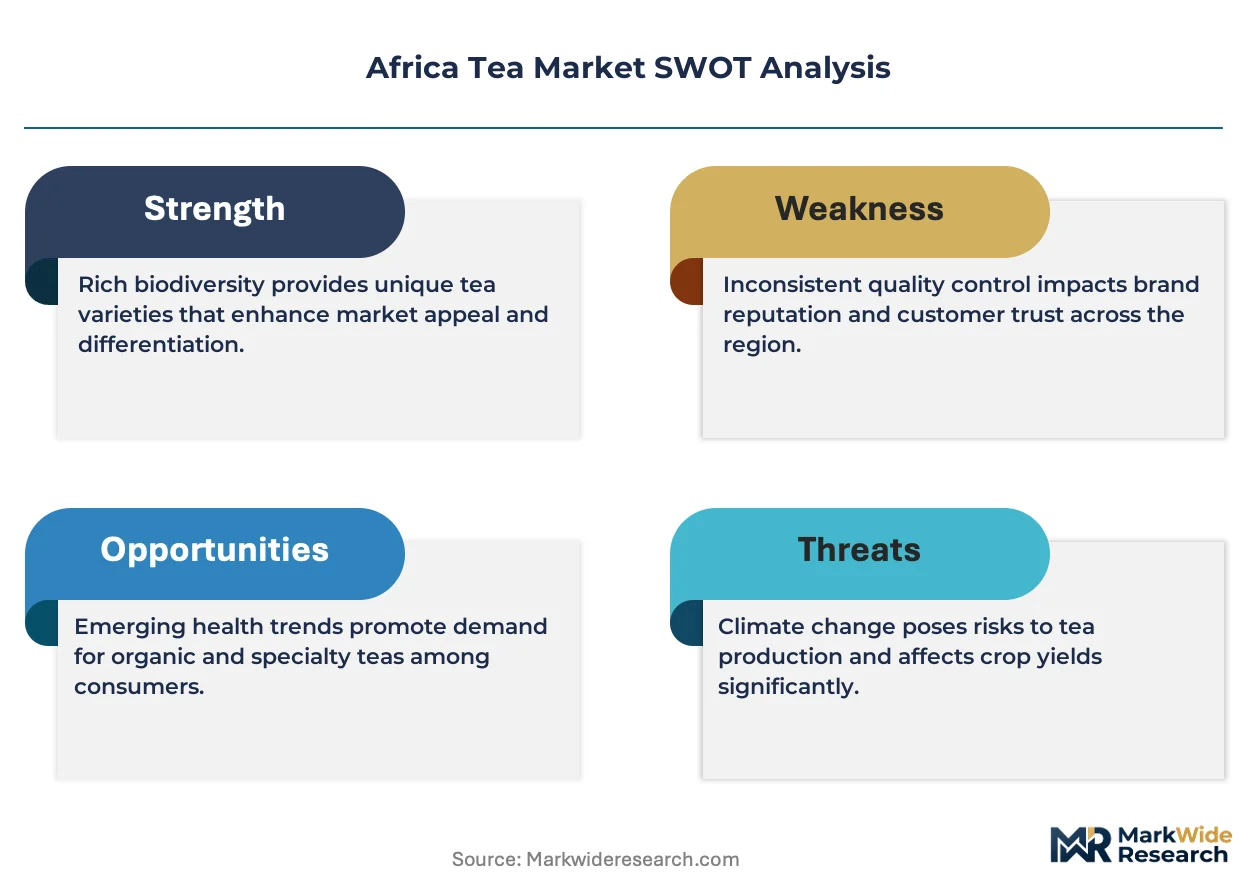
The Africa tea trade is rebalancing between premium single-origin offerings and bulk commodity auctions, with quality premiums widening as specialty buyers bypass traditional Mombasa exchange channels. James Finlay (Africa) Ltd anchors its East African supply base through integrated estate operations spanning Kenya and Tanzania. KTDA sustains the world's largest smallholder network, leveraging cooperative processing factories to control leaf quality from farm to export. Unilever plc competes across mass-market black tea segments, extending its Lipton brand presence through regional packaging facilities.
Africa tea comprises processed leaf from Camellia sinensis cultivated across high-altitude equatorial zones, with black tea dominating through full oxidation protocols yielding robust theaflavin content for color and body. Green tea retains minimal oxidation, preserving catechins for health-positioned product lines. Black tea occupies the mature volume core, while herbal tea derived from rooibos, honeybush, and moringa represents the fastest-growing category as functional wellness positioning expands. Specialty stores channel premium loose-leaf and canister formats, whereas supermarkets move standard tea bags at compressed margins.
Kenya's Tea Act and the East African Community's harmonized standards shape phytosanitary export requirements, while the country's national agricultural regulator enforces maximum residue limits for pesticide compliance in EU-bound shipments. Rwanda's national standards body and Uganda's UNBS certification frameworks increasingly influence regional quality benchmarks. Stakeholders must monitor climate adaptation funding flows and smallholder credit access as determinants of future supply elasticity.
Market Dynamics
Kenya's Agricultural Finance Corporation credit programs and KTDA smallholder consolidation are compressing supply structures while quality premiums widen between auction and direct-trade channels.
Growth Catalysts
- EU Green Deal residue protocols:Kenya's national agricultural regulator enforces maximum residue limits that unlock premium export pricing for compliant smallholders.
- Specialty café procurement:Single-origin African teas command widening quality premiums as hospitality chains bypass Mombasa auction floors.
- Rwanda's mountainous highlands:Concentrated demand in elevated growing zones produces distinctive terroir profiles that attract specialty buyers.
Market Restraints
- Phytosanitary compliance costs:East African Community harmonized standards impose testing burdens that disadvantage smaller processors lacking in-house laboratories.
- Climate input volatility:Erratic rainfall patterns in Kenya's highland counties destabilize leaf volume predictability for factory scheduling.
- Herbal substitution pressure:Rooibos and honeybush functional wellness positioning captures health-conscious consumers from traditional black tea occasions.
Strategic Opportunities
- Uganda's UNBS certification framework:Emerging quality benchmarks create first-mover advantage for exporters establishing compliant processing infrastructure.
- Direct-trade channel innovation:Specialty stores and hospitality procurement teams source traceable single-origin lots outside auction structures.
- Green tea oxidation technology:Minimal processing protocols preserve catechins for health-positioned product lines targeting wellness segments.
Industry Challenges
- Smallholder credit access gaps:KTDA cooperative structures struggle to extend working capital to peripheral growers outside factory catchment zones.
- Factory equipment modernization:Aging withering and rolling machinery in Kenya's highland processing plants requires capital deployment for quality consistency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Tea Market |
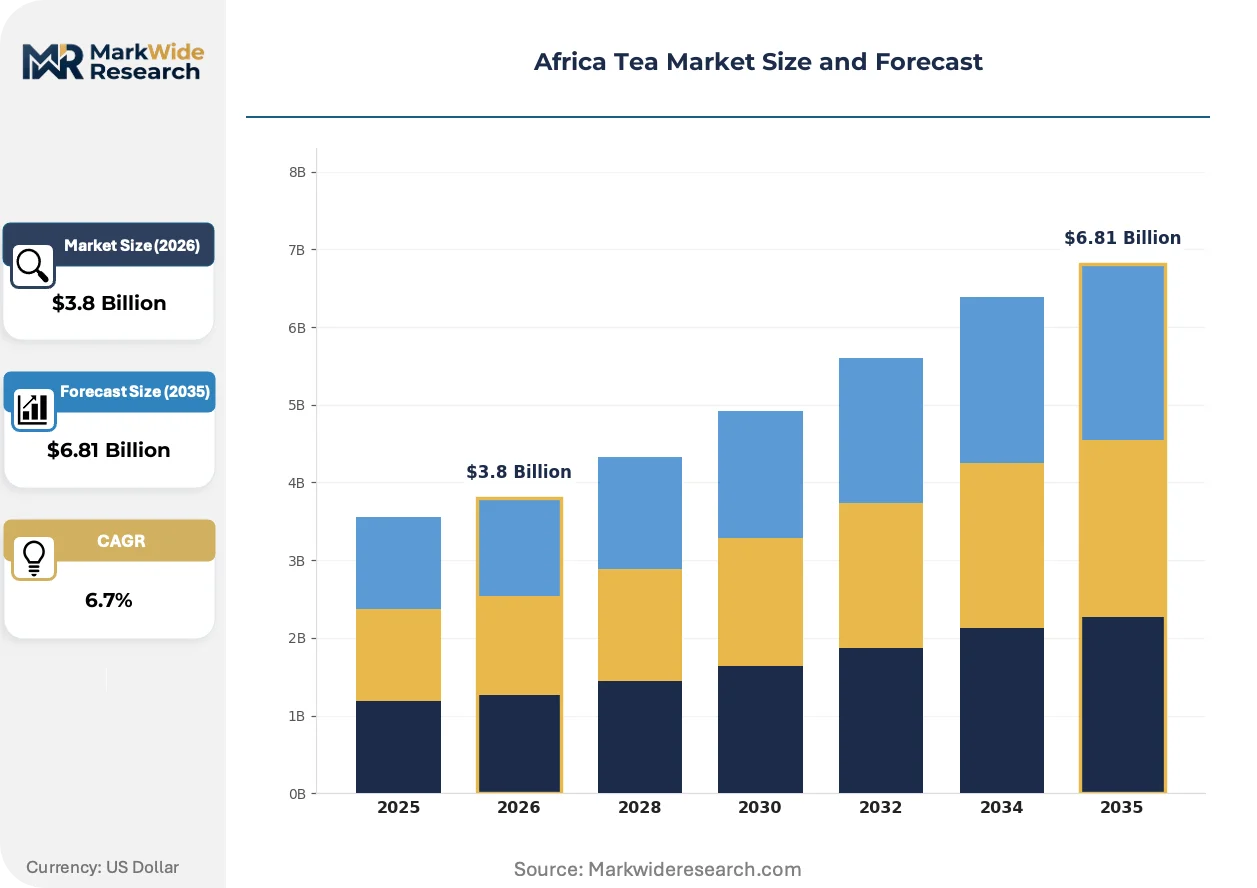
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Green Tea, Black Tea, Herbal Tea, White Tea End User: Household, Food Service, Retail, Online Distribution Channel: Supermarkets, Specialty Stores, E-commerce, Wholesale Packaging Type: Loose Leaf, Tea Bags, Canisters, Tins |
| Companies Covered | Tata Consumer Products Limited, Unilever plc, The Coca-Cola Company, PepsiCo, Inc., James Finlay (Africa) Ltd, Kenya Tea Development Agency (KTDA), Dilmah Ceylon Tea Company PLC, JDE Peet's, Hain Celestial, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Tea Market Strategic Shifts
Quality traceability systems and climate adaptation protocols are compressing traditional auction intermediation while functional wellness positioning expands category boundaries beyond conventional oxidation grades.
Blockchain-enabled provenance tracking is integrating with cooperative factory operations to document leaf origin from smallholder to export. Specialty buyers in European hospitality and North American retail are adopting these verification layers at accelerating pace. This transparency infrastructure is integrating previously fragmented smallholder supply into premium direct-trade channels that bypass Mombasa auction floors entirely.
Kenya's Tea Act enforcement mechanisms and East African Community harmonized standards are tightening phytosanitary documentation requirements for EU-bound shipments. Industrial consequence falls heaviest on processors lacking in-house testing capacity who must rely on third-party certification delays. Rwanda's national standards body and Uganda's UNBS frameworks are responding with regional laboratory capacity investments to reduce clearance friction.
Certification-driven preference shifts are displacing commodity-grade procurement in European specialty channels where organic and Rainforest Alliance credentials function as table stakes. Direct-trade relationships between Kenyan highland factories and Scandinavian hospitality groups are replacing traditional importer-mediated supply. This disintermediation is most visible in Germany's loose-leaf retail segment and Nordic hotel procurement programs.
Africa Tea Market Segmentation
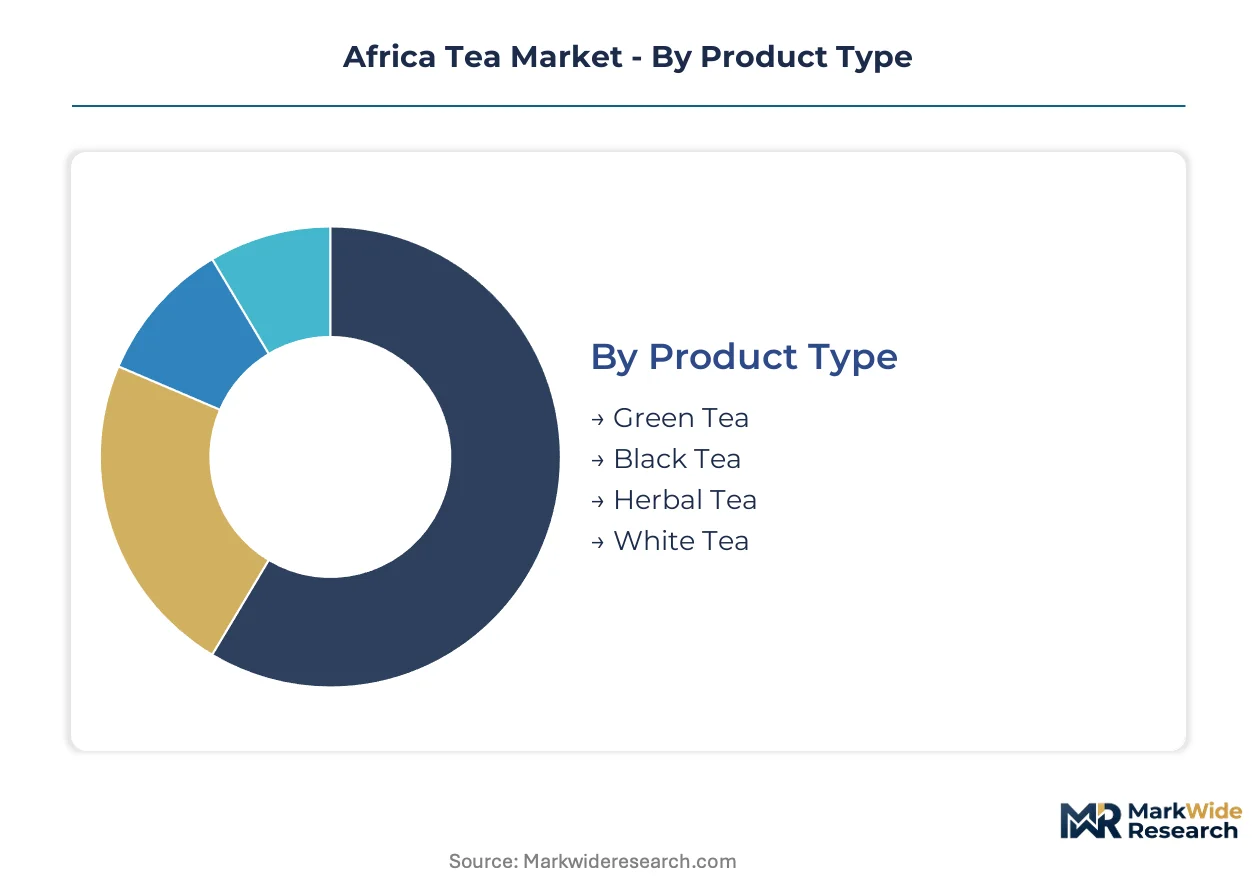
African tea procurement decisions pivot on oxidation grade, end-use occasion, and traceability requirements. Buyers segment offerings across functional wellness positioning, hospitality channel specifications, and packaging formats that signal quality tier.
Product Type:
Buyers select oxidation grades based on flavor intensity requirements and health-attribute positioning.
- Black Tea:Full oxidation protocols yield elevated theaflavin content for color depth and astringent body. Procurement concentrates in Kenya's highland counties where KTDA cooperative factories supply volume to European retail and Mombasa auction floors; EU Green Deal residue compliance unlocks premium export pricing.
- Herbal Tea:Rooibos, honeybush, and moringa formulations operate outside Camellia sinensis taxonomy, preserving functional wellness narratives around antioxidant and adaptogenic properties. Demand clusters in German and Nordic specialty retail where organic certification functions as table stakes; wellness-positioned SKUs displace conventional black tea occasions among health-conscious demographics.
- Green Tea:Minimal oxidation preserves catechin compounds for antioxidant-focused product lines.
- White Tea:Bud-only harvesting and minimal processing commands scarcity pricing in boutique hospitality channels.
Volume sits with Black Tea; growth tilts toward Herbal Tea.
End User:
Channel specifications dictate leaf grade, packaging format, and certification requirements.
- Food Service:Hotels, restaurants, and café chains source single-origin lots with documented provenance for menu differentiation. Procurement concentrates in Rwanda's mountainous highlands where distinctive terroir profiles attract Scandinavian hospitality groups; direct-trade relationships bypass Mombasa auction intermediaries entirely.
- Retail:Supermarkets and specialty stores stock packaged formats across price tiers, with private-label programs compressing margins on standard grades. Shelf-space allocation favors Rainforest Alliance-certified SKUs in German and British multiples; loose-lead positioning gains traction in premium urban outlets.
- Household:Individual consumers purchase through retail and e-commerce for at-home consumption.
- Online:Direct-to-consumer platforms serve subscription and gift-market segments.
Volume concentrates in Retail; Food Service climbs fastest on premium direct-trade expansion.
Distribution Channel:
Channel selection determines margin structure and buyer relationship depth.
- Supermarkets:High-volume, low-margin throughput of standard tea bags dominates mass-market penetration. Kenya's highland factory output flows primarily into British and German retail multiples where price competition intensifies; compressed margins force scale-dependent processor consolidation.
- Specialty Stores:Curated loose-leaf and canister formats serve connoisseur segments with education-intensive service models. Urban centers in Nairobi, Kigali, and Kampala host emerging boutique retail; single-origin storytelling commands 3-5x price multiples over auction-grade commodity.
- E-commerce:Digital platforms extend reach to diaspora and wellness-focused demographics.
- Wholesale:Bulk supply to processors, blenders, and private-label packagers.
Supermarkets anchor volume; Specialty Stores gain share fastest on experience-driven purchasing.
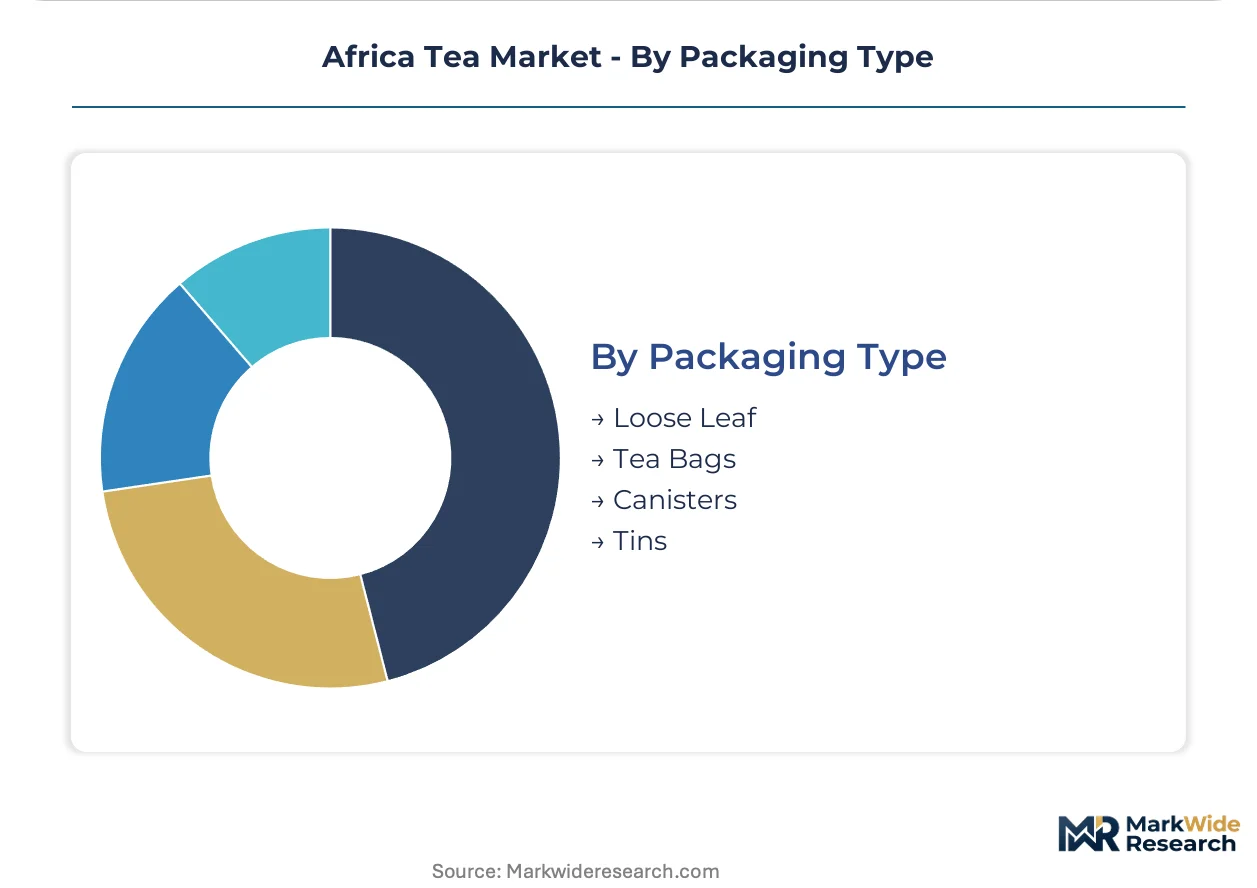
Packaging Type:
Format signals quality tier and occasions consumption context.
- Loose Leaf:Unpacked leaf preserves aroma integrity and supports ritual preparation occasions. Demand concentrates in German loose-leaf retail and Nordic hotel procurement where brewing ceremony differentiates hospitality experience; specialty buyers pay provenance premiums for factory-direct supply.
- Tea Bags:Convenience formats dominate mass-market household penetration and food-service back-of-house operations. KTDA cooperative factories supply volume to Unilever regional packaging facilities; standard grades face herbal substitution pressure from functional wellness alternatives.
- Canisters:Airtight metal packaging extends shelf life for premium gifting segments.
- Tins:Decorative formats serve tourist retail and ceremonial gift markets.
Tea Bags hold volume dominance; Loose Leaf expands most quickly on specialty channel growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nairobi anchors East African tea trade through its highland factory network and Mombasa port infrastructure. Specialty buyers now source directly from Kenyan and Rwandan highlands, bypassing traditional auction channels.
Kenya
KTDA cooperative factories in Nyeri and Kericho counties supply volume to European retail multiples. The country's Tea Act enforcement mechanisms tighten phytosanitary documentation for EU-bound shipments. Mombasa auction floors face disintermediation as Scandinavian hospitality groups establish direct-trade relationships with highland processors.
Rwanda
Mountainous highlands around Gisenyi produce distinctive terroir profiles attracting premium buyers. The national standards body invests in regional laboratory capacity to reduce certification clearance friction. Kigali-based exporters bypass Mombasa entirely, shipping factory-direct to German specialty retail.
Tanzania
Southern highland estates in Mbeya and Iringa regions supply black tea to regional blending operations. The Tanzania Tea Board enforces quality grading protocols aligned with East African Community harmonized standards. Dar es Salaam port infrastructure handles bulk shipments to Pakistan and Middle Eastern markets.
Uganda
Western districts around Fort Portal concentrate smallholder production for regional export. The UNBS certification framework creates compliance pathways for processors seeking EU market access. Kampala-based packagers supply domestic retail and cross-border trade into South Sudan and eastern DRC.
Malawi
Thyolo and Mulanje districts in the Shire Highlands sustain estate-based production for commodity auctions. The country's national agricultural regulator enforces residue limits for pesticide compliance in European shipments. Blantyre processors face equipment modernization pressures to maintain quality consistency.
Africa Tea Market Competitive Environment
Premium-margin players sit above commodity-margin players across traceability and certification tiers. The market structures around integrated estate operators, cooperative smallholder networks, and multinational branded packagers. Three archetypes dominate: vertically integrated plantation owners controlling leaf-to-export supply chains; cooperative aggregators consolidating thousands of smallholders through factory networks; and brand licensors sourcing through third-party processors. Competitive moves concentrate on direct-trade channel development and sustainability certification acquisition.
Within the cooperative aggregator tier, Kenya Tea Development Agency and James Finlay (Africa) Ltd exemplify divergent supply models. KTDA represents the world's largest smallholder network, leveraging cooperative processing factories to control quality from farm to export. James Finlay anchors East African supply through integrated estate operations spanning Kenya and Tanzania. Unilever plc occupies the mass-market branded position, extending its Lipton presence through regional packaging facilities.
| Leading Market Players |
|---|
| Tata Consumer Products Limited |
| Unilever plc |
| The Coca-Cola Company |
| PepsiCo, Inc. |
| James Finlay (Africa) Ltd |
| Kenya Tea Development Agency (KTDA) |
| Dilmah Ceylon Tea Company PLC |
| JDE Peet's |
| Hain Celestial |
| Others |
Value Chain & Pricing Dynamics
Captive supply from KTDA cooperative factories anchors both procurement reliability and quality-premium capture for exporters serving European retail multiples. This backward integration into smallholder leaf collection compresses intermediary margins while concentrating pricing power at the factory gate for compliant grades.
Pricing Analysis
Outcome-based pricing tied to EU Green Deal residue compliance anchors premium realization for Kenyan highland processors. Three-tier pricing structure across Rainforest Alliance-certified, standard auction-grade, and commodity bulk levels separates compliance investment returns. Cost compression in standard tea bag tiers intensifies because supermarket private-label programs consolidate procurement volumes. Food service buyers in Scandinavian hospitality show least price sensitivity, while British retail multiples exhibit highest elasticity.
Supply Chain Analysis
Regional distribution centers in Mombasa and Dar es Salaam handle hub-and-spoke consolidation before European port entry. Leaf supply concentrates in Kenya, Rwanda, and Tanzania where highland factory networks process Camellia sinensis harvests. Input dependencies center on fertilizer imports, fuel for withering operations, and packaging materials from Asian suppliers. Single-source vulnerability runs through Mombasa port congestion during peak export windows. Distribution runs through auction floors for commodity grades and direct container shipment for specialty contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from EU phytosanitary compliance costs will force smaller processors lacking laboratory capacity to exit or sell. Quality-traceability investments now function as survival thresholds rather than differentiation levers.
For Market Incumbents: Extend certification coverage across factory networks to preempt compliance-driven customer defection. Capture direct-trade relationships with German and Nordic hospitality groups before specialty buyers complete supplier rationalization. Channel control through owned packaging facilities in Nairobi and Kampala reduces exposure to third-party margin extraction.
For New Entrants and Emerging Players: Capture white-space in Uganda's UNBS-certified supply segment where compliant processing infrastructure remains underdeveloped. Target Rwanda's mountainous highlands for single-origin positioning with Scandinavian buyers seeking distinctive terroir profiles. A traceability-first go-to-market approach bypasses auction intermediaries entirely.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated estate operators seeking cooperative factory network expansion. Long-term viability favors processors with captive smallholder supply and in-house testing capacity. Watch climate adaptation funding disbursement velocity as inflection indicator for supply elasticity and quality consistency.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-Trade Channel Development | Bypasses Mombasa auction floors to capture quality premiums from European hospitality buyers. |
| Sustainability Certification Acquisition | Rainforest Alliance and organic credentials unlock shelf-space allocation in German retail multiples. |
| Processing Equipment Modernization | Replaces aging withering and rolling machinery in Kenya's highland factories for quality consistency. |
| Blockchain Provenance Integration | Documents leaf origin from smallholder to export for specialty buyer verification requirements. |
| Climate Adaptation Investment | Secures irrigation and shade-tree infrastructure against rainfall volatility in highland counties. |
Study Parameters
Trade databases, cooperative factory production records, and East African Community regulatory filings formed the secondary backbone for volume and trade flow calibration. Primary interviews with KTDA factory managers, European specialty tea buyers, Nairobi-based export logistics coordinators, and phytosanitary compliance officers supplied operational detail. Bottom-up factory output aggregation and top-down import demand reconciliation enabled cross-validation.
Historical auction price trendlines and direct-trade contract premiums informed growth trajectory modeling across the projection horizon. Segmentation dimensions included oxidation grade, end-use channel, certification tier, and regional processing hub. CAGRs derived from fitted trend extrapolation adjusted for structural shifts in procurement channel preference. Forecast inputs incorporated EU Green Deal implementation pace and smallholder credit access expansion rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to climate adaptation funding flows and phytosanitary standard harmonization delays. Outputs reflect documented assumptions around cooperative consolidation continuity and specialty buyer channel migration. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tea
Out of Home Tea Market
Tea
Black Tea Market
Tea
Organic Tea Market
Tea
Tea Polyphenols Market
Tea
China Tea Market
Tea
Spray-Dried Tea Products Market
Tea
US RTD Organic Tea Market
Tea
South America Tea Market
Tea
Europe Green Tea Market
Tea
Plant Based New Tea Drink Market
Tea
Light-Fermented Tea Market
Tea
High Protein Tea Market
Tea
Moringa Tea Market
Tea
Global Fruit Tea Market
Tea
Tea Essence Market
Tea
North America Tea Market