
 US RTD Organic Tea Market | 2026-2036
US RTD Organic Tea Market Size, Share, and Industry Trends Forecast 2026-2036
US RTD Organic Tea Market Intelligence
The consumer shift towards unsweetened and minimally processed formulations is unwinding the market's historical reliance on high-sugar content. The Coca-Cola Company leverages its extensive distribution network to push organic offerings into mass-market channels. In contrast, Hain Celestial differentiates with a portfolio dedicated to natural food stores. ITO EN (North America) Inc. anchors its position by specializing in authentic Japanese green tea varieties.
US ready-to-drink organic tea consists of pre-brewed teas packaged for immediate consumption and certified organic under USDA regulations. This certification mandates production without synthetic pesticides or fertilizers, ensuring a clean-label product for consumers. Within product types, green and herbal teas are expanding faster than traditional black tea. Supermarkets and health stores constitute the core distribution channels, though online retail is accelerating its share of sales.
The USDA's National Organic Program provides the foundational regulatory framework, defining the stringent criteria for organic certification. The FDA governs all labeling for health claims and nutritional information, directly influencing marketing messages. Adherence to these standards is non-negotiable for market access. Consequently, brand success will depend on navigating the trade-off between sustainable packaging like glass bottles and the cost pressures of mainstream retail.
Market Dynamics
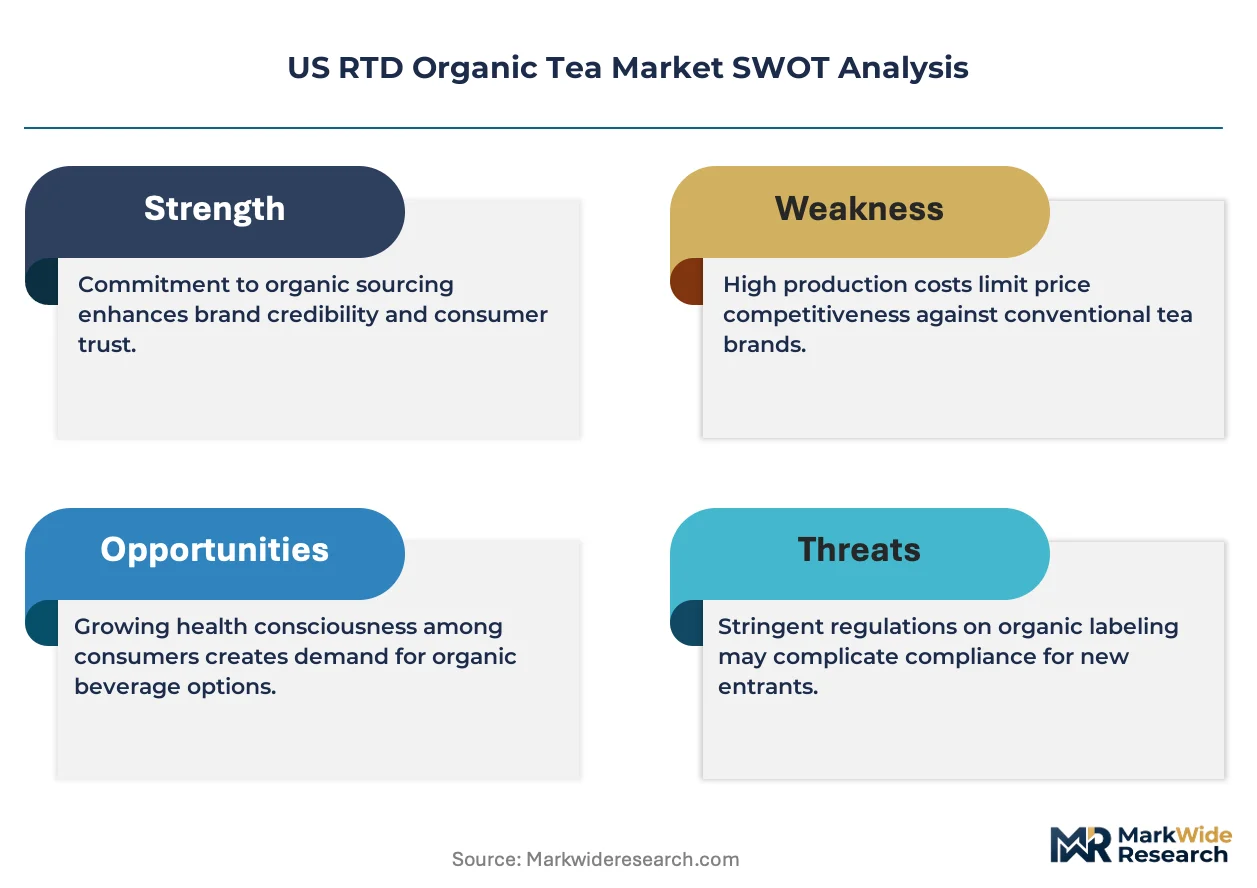
The US RTD organic tea market is shaped by the fundamental tension between the premium costs of USDA-certified organic ingredients and the price sensitivity of mass-market retail channels. This dynamic forces brands to balance clean-label purity with scalable production and distribution economics.
Growth Catalysts
- Corporate Wellness Initiatives:Employer-sponsored health programs are encouraging employees to select healthier beverage options, directly fueling demand for unsweetened and low-sugar organic teas in workplace micro-markets and cafeterias across the US.
- USDA Organic Seal:The USDA's stringent certification provides a trusted, federally backed guarantee of product integrity. This seal acts as a powerful purchasing catalyst for health-conscious consumers navigating crowded beverage aisles.
- Mainstream Retailer Adoption:The expansion of dedicated organic sections within national supermarket chains and mass merchandisers is increasing product visibility and accessibility beyond traditional natural food stores, reaching a broader consumer base.
Market Restraints
- Organic Ingredient Sourcing:The supply of USDA-certified organic tea leaves and botanicals is subject to greater price volatility and tighter availability than conventional inputs, constraining production scalability and margin stability.
- Packaging Cost Pressures:Consumer preference for sustainable materials like glass bottles conflicts with the lower cost and lighter weight of PET plastic, creating a trade-off that impacts shipping costs and retail price points.
- Reduced Shelf Stability:The avoidance of synthetic preservatives in organic formulations results in a shorter shelf life. This complicates inventory management and increases the risk of spoilage and waste for distributors and retailers.
Strategic Opportunities
- Functional Ingredient Fortification:There is a significant opportunity to incorporate functional ingredients like adaptogens, probiotics, and nootropics into organic tea formulations, targeting consumers seeking specific health benefits beyond simple refreshment.
- Geographic Market Expansion:While demand is concentrated on the West Coast, significant white space exists in developing markets in major metropolitan areas throughout the US Midwest and Southeast regions.
- Direct-to-Consumer Channels:Building subscription-based e-commerce platforms allows brands to foster direct relationships with loyal consumers, capture valuable data, and improve margins by bypassing traditional retail intermediaries.
Industry Challenges
- Certification and Compliance Burden:Navigating the rigorous documentation, inspection, and record-keeping requirements to obtain and maintain USDA organic certification presents a continuous operational and administrative challenge, particularly for smaller brands.
- Cold Chain Logistics Management:Ensuring product integrity for preservative-free organic teas necessitates an unbroken and costly cold chain from manufacturing to the point of sale, adding complexity and expense to the supply chain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US RTD Organic Tea Market |
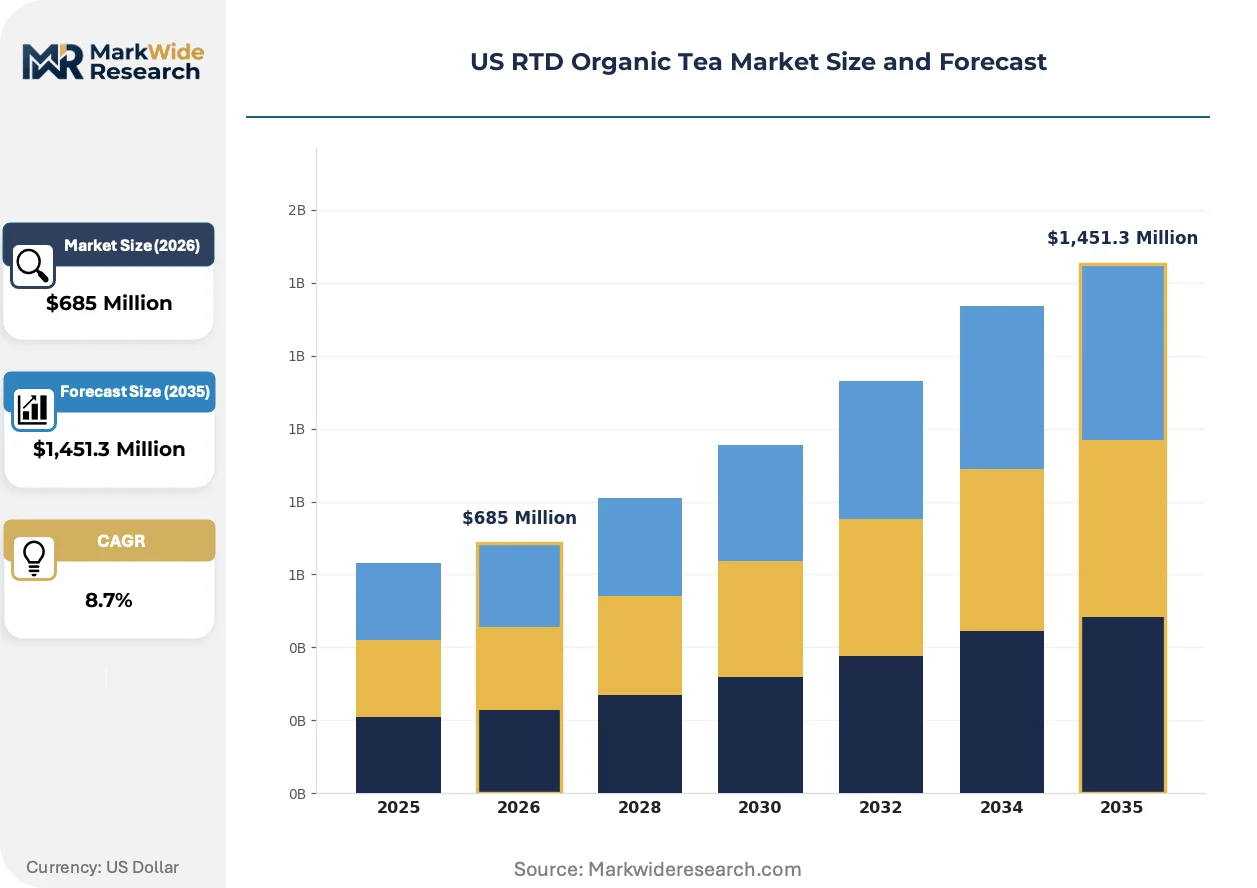
| Market Size in 2026 | $685 Million |
| Market Size in 2035 | $1,451.3 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Green Tea, Black Tea, Herbal Tea, Mixed Tea Packaging Type: Glass Bottles, PET Bottles, Tetra Packs, Cans Flavor Profile: Citrus, Berry, Mint, Lavender Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Health Stores |
| Companies Covered | Numi, Inc., Hain Celestial, Unilever, Teatulia, PBC, Guayakí Yerba Mate, The Coca-Cola Company, ITO EN (North America) Inc., Harney & Sons Fine Teas, AriZona Beverages USA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US RTD Organic Tea Market Strategic Shifts & Innovations
Product formulation and packaging sustainability are at the forefront of innovation, as brands seek to differentiate on more than just organic certification. The market is maturing, with a clear divergence between craft-oriented, premium products and value-focused, mass-market offerings.
Cold brew processing, a non-thermal extraction method, preserves the delicate aromatic and flavor compounds of tea leaves that are often lost during hot brewing. Premium brands are adopting this technique to create exceptionally smooth, less bitter products, particularly for green and white tea varieties. This technology's adoption is bifurcating the market between high-end, craft-style cold brews and conventional, hot-brewed teas designed for mass production.
The FDA is increasing its scrutiny of nutrient content claims and the definition of "healthy" on beverage labels, directly influencing marketing strategies. This regulatory pressure forces brands to align their on-pack messaging with precise nutritional facts, particularly concerning sugar content. Formulations with zero added sugar or those using natural, non-caloric sweeteners are gaining a distinct advantage in this environment.
Consumers are increasingly shifting from single-unit, impulse buys to planned, multi-pack purchases via online platforms and subscription services. This trend disrupts the traditional sales velocity models of supermarkets and convenience stores, favoring brands with robust direct-to-consumer capabilities. The shift is most pronounced among urban millennials who prioritize convenience and value for routine pantry stocking.
US RTD Organic Tea Market Segmentation
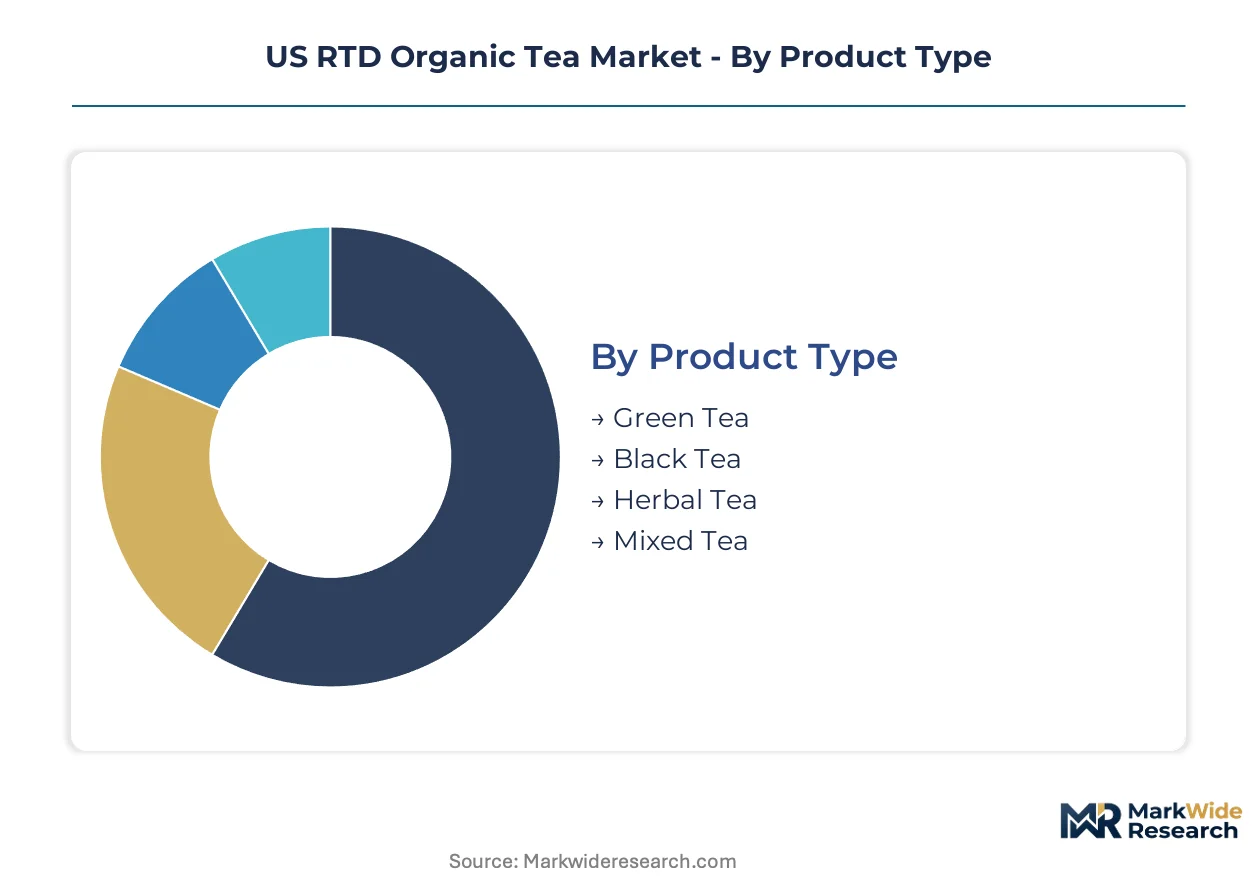
The US RTD organic tea market exhibits distinct segmentation across product types, packaging formats, flavor profiles, and distribution channels. Understanding these segments is critical for brands to tailor product development and market entry strategies within the competitive US beverage landscape.
Product Type:
The flow of organic tea products into various distribution channels often depends on their perceived health benefits and consumer appeal. Green tea and herbal tea varieties frequently appear in health stores and online retail, targeting wellness-focused consumers.
- Green Tea:This product type consists of minimally oxidized tea leaves, known for its high antioxidant content and often unsweetened profile. Demand concentrates in metropolitan areas on the West Coast, driven by consumers seeking functional health benefits and authentic Japanese varieties.
- Black Tea:Fully oxidized tea leaves characterize this traditional tea, offering a robust flavor profile often associated with classic RTD formulations. This segment maintains a stable consumer base across general supermarkets, appealing to those seeking familiar beverage options.
- Herbal Tea:Formulations without true tea leaves, using botanicals, fruits, and spices, define herbal teas, catering to diverse taste preferences and functional needs. This category is experiencing significant growth among health-conscious consumers in urban centers across the US.
- Mixed Tea:This segment includes blends of various tea types or combinations with other ingredients like fruit juices or functional additives.
Black tea dominates the installed base of traditional RTD tea consumption. Herbal tea is where expansion concentrates, driven by functional ingredient innovation.
Packaging Type:
The cost structure for various packaging types significantly influences their adoption across different retail price points and consumer segments. Sustainable options like glass bottles command a premium, while PET bottles offer a more economical solution for mass-market brands.
- Glass Bottles:These premium containers offer superior product protection and a perception of quality, aligning with sustainable consumer preferences. This packaging type is prevalent in natural food stores and specialty retailers, appealing to consumers willing to pay more for environmental considerations.
- PET Bottles:Lightweight and shatter-resistant, PET plastic bottles provide a cost-effective and convenient packaging solution for mass-market distribution. Their widespread use in supermarkets and convenience stores makes them accessible to a broad consumer base across the US.
- Tetra Packs:Aseptic carton packaging provides extended shelf life without refrigeration, often used for organic products targeting children or on-the-go consumption.
- Cans:Aluminum cans offer durability and recyclability, gaining traction for single-serve portions and cold brew organic tea varieties.
PET bottles currently hold the largest volume share in the market. Glass bottles represent the packaging type with the highest growth in premium segments.
Flavor Profile:
Consumer preferences for specific flavor profiles often dictate product development and marketing efforts within the US RTD organic tea market. Brands continually innovate to capture evolving tastes and introduce novel sensory experiences.
- Citrus:These flavors, including lemon, orange, and grapefruit, offer a refreshing and universally appealing taste profile. Citrus-infused organic teas maintain strong demand in convenience stores and supermarkets due to their broad consumer acceptance.
- Berry:Flavors such as strawberry, raspberry, and blueberry provide a sweet and fruity dimension to organic tea formulations. This profile is popular among younger demographics and is gaining traction in health-conscious retail channels.
- Mint:Mint flavors offer a cooling and invigorating sensation, often associated with digestive benefits and freshness.
- Lavender:This floral flavor provides a unique and calming profile, appealing to consumers seeking relaxation or botanical sophistication.
Citrus flavor profiles are widely accepted across all consumer groups. Berry flavors are gaining significant traction among younger consumers.
Distribution Channel:
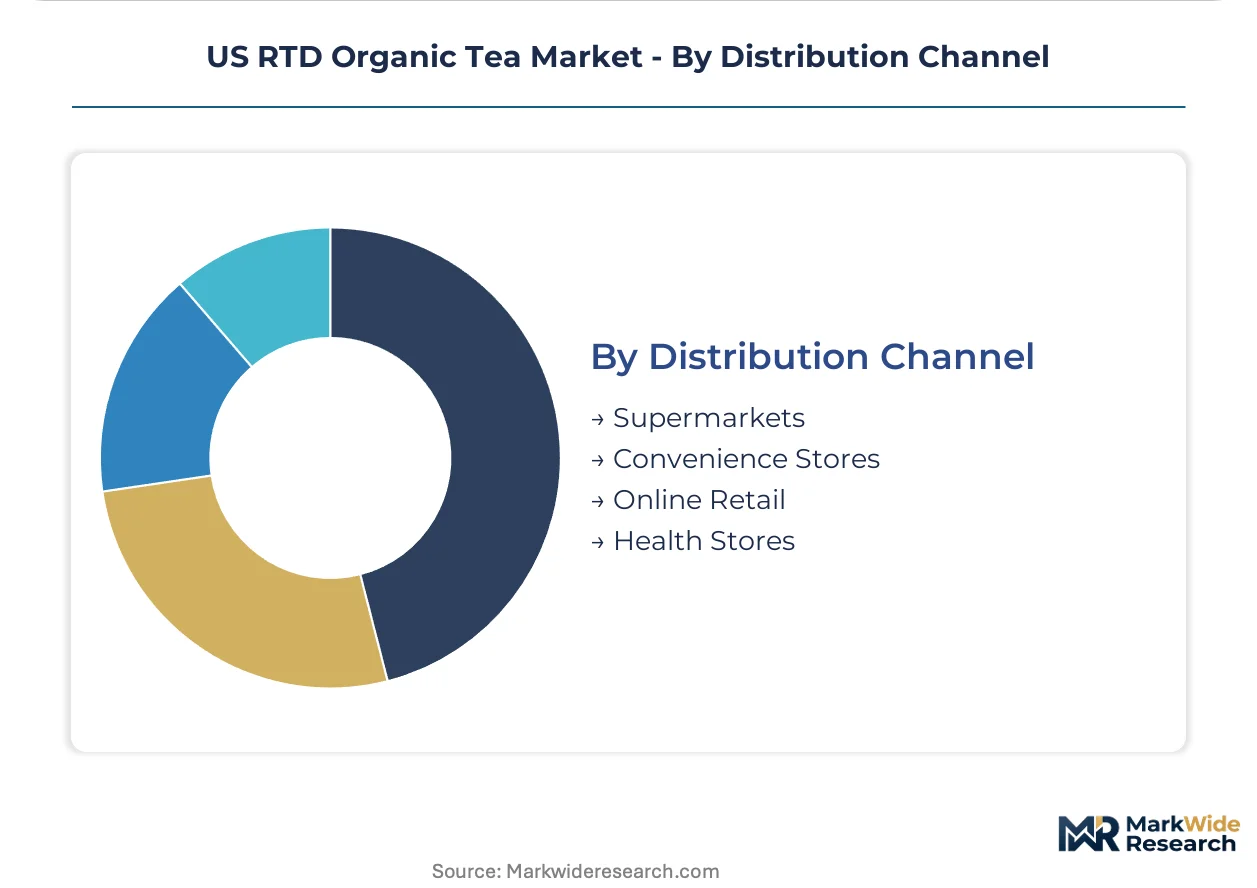
Market accessibility and consumer purchasing habits are fundamentally shaped by the available distribution channels for US RTD organic tea. Each channel caters to distinct consumer needs and purchasing occasions.
- Supermarkets:These large retail formats serve as the primary channel for mass-market organic tea sales, offering broad selection and competitive pricing. Supermarkets provide significant visibility for established and emerging brands, reaching a vast segment of US households.
- Convenience Stores:Catering to impulse purchases and immediate consumption, convenience stores offer single-serve organic tea options. This channel is critical for on-the-go consumers in urban and suburban areas across the US.
- Online Retail:E-commerce platforms facilitate planned, multi-pack purchases and subscription services, expanding geographic reach and direct consumer engagement.
- Health Stores:Specializing in natural and organic products, health stores attract consumers prioritizing clean labels and specific dietary needs.
Supermarkets account for the largest volume of sales. Online retail is the channel experiencing the most rapid expansion in terms of market share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US RTD organic tea market sees significant product flow from California-based producers to consumers across the nation. This dynamic underscores the importance of regional consumer preferences and distribution networks. Demand is particularly strong in health-conscious urban centers.
California
California leads US demand for organic RTD tea, driven by a strong health and wellness culture. The USDA organic certification provides a crucial trust signal for consumers in this state. Urban centers like San Francisco and Los Angeles show high concentrations of specialty organic tea retailers and health food stores.
New York Metro
The New York metropolitan area exhibits robust demand for premium organic RTD teas, fueled by diverse consumer tastes. FDA labeling regulations influence marketing messages for these products within the dense urban environment. Manhattan and Brooklyn feature numerous corporate wellness programs encouraging healthier beverage choices.
Southeast
Growth in the Southeast, particularly Florida and Georgia, reflects increasing consumer awareness of clean-label products. State-level health initiatives are beginning to promote organic food and beverage options. Major cities such as Atlanta and Miami are expanding their natural food store footprints.
Midwest
Midwest regions like Illinois and Ohio are experiencing rising interest in organic RTD teas, supported by supermarket adoption of organic sections. The USDA's National Organic Program ensures product integrity for new brands entering these markets. Chicago and Columbus are seeing increased availability in both mass-market and specialty retail channels.
US RTD Organic Tea Market Key Industry Players
Listed leaders compete with private specialists across distribution reach and product innovation within the US RTD organic tea market. The landscape features a mix of large beverage conglomerates and dedicated organic brands. Companies employ strategies such as portfolio diversification and geographic expansion to capture market share.
Specialists in authentic Japanese green tea, such as ITO EN (North America) Inc., anchor a niche segment focused on traditional quality. The Coca-Cola Company exemplifies mass-market penetration, leveraging its extensive network for broad organic offerings. Hain Celestial occupies a position among natural food specialists, differentiating with a dedicated organic portfolio.
| Leading Market Players |
|---|
| Numi, Inc. |
| Hain Celestial |
| Unilever |
| Teatulia, PBC |
| Guayakí Yerba Mate |
| The Coca-Cola Company |
| ITO EN (North America) Inc. |
| Harney & Sons Fine Teas |
| AriZona Beverages USA |
| Others |
Cost & Logistics Intelligence
Reduced shelf stability due to preservative-free formulations drives inventory management complexities, impacting both supply chain efficiency and retail pricing strategies. This dynamic forces brands to manage product flow carefully to minimize spoilage and maintain margin integrity.
Pricing Analysis
Supermarket buyers anchor tiered pricing structures across premium, standard, and economy levels within the US RTD organic tea market. Price differentiation stems from USDA organic certification levels and brand premium, alongside volume scale for larger retailers. Pricing softness runs through mass-market channels due to intense competition from conventional beverages. Mass-market consumers exhibit the highest price sensitivity, while health store patrons demonstrate greater willingness to pay for certified organic products.
Supply Chain Analysis
Cold chain logistics infrastructure represents a critical chokepoint for preservative-free organic teas, adding significant expense and complexity. Supply for organic tea leaves and botanicals largely concentrates in China, India, and Japan. Raw material dependencies include USDA-certified organic tea leaves and various functional botanicals. Commodity price volatility for organic inputs poses a structural risk to margin stability. Downstream distribution runs primarily through established supermarket networks and rapidly expanding online retail platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US RTD organic tea market requires a substitution defense, as incumbents must navigate the threat posed by conventional RTD teas and other healthy beverage alternatives. Strategic positioning against these substitutes is crucial for sustained market share.
For Market Incumbents: Fortify existing distribution networks by deepening relationships with national supermarket chains and expanding into corporate wellness micro-markets. Invest in sustainable packaging innovations like glass bottles to align with consumer preferences and enhance brand perception. Leverage USDA organic certification as a core trust signal against less regulated health beverages. Expand functional ingredient fortification to meet evolving consumer health demands.
For New Entrants and Emerging Players: Differentiate on unique flavor profiles and specialized functional benefits, targeting health-conscious consumers in underserved urban centers. Significant white space exists for focused market entry in major metropolitan areas across the US Midwest and Southeast regions. Build subscription-based e-commerce platforms to foster direct consumer relationships and capture valuable first-party data. Position products as premium, craft-oriented alternatives to mass-market offerings.
For Investors and Strategic Acquirers: Long-term, this sits as a growth play driven by persistent health and wellness trends among US consumers. Target acquisition archetypes include agile, craft-oriented brands with strong direct-to-consumer capabilities and innovative functional product portfolios. The signal to watch is the continued expansion of dedicated organic sections within national supermarket chains, indicating broader consumer acceptance and scalable retail access.
| Strategic Initiative | Industry Significance |
|---|---|
| Brand Extension into Functional Teas | This expands product offerings to capture consumers seeking specific health benefits beyond basic refreshment. |
| Direct-to-Consumer Platform Launch | This fosters direct relationships with loyal consumers and bypasses traditional retail intermediaries for improved margins. |
| Premium Tier Introduction with Cold Brew | This targets discerning consumers willing to pay more for superior taste and craft processing techniques. |
| Distribution Channel Expansion into Corporate Wellness | This accesses a growing segment of health-conscious employees through workplace micro-markets and cafeterias. |
| Sustainability Repositioning via Glass Packaging | This aligns brand values with environmental consumer preferences, enhancing perception and command a premium price. |
Research Approach
Two parallel data streams informed the analysis: extensive primary interviews and robust secondary research. Primary research involved conversations with brand managers, retail buyers, organic tea producers, and distribution managers to gather qualitative insights. Secondary validation drew from USDA National Organic Program reports, FDA labeling guidelines, industry association publications, and market trend analyses. This approach allowed for both bottom-up and top-down triangulation of market data.
The analysis period spans the forecast horizon, employing a comprehensive analytical framework. Segmentation dimensions modeled include product types such as green and herbal teas, packaging formats like glass and PET bottles, and key distribution channels including supermarkets and online retail. Compound annual growth rates were derived from historical data extrapolation, informed by expert consensus. Key forecast inputs include consumer health trend adoption and the expansion of organic certification across beverage categories.
The analysis sits within stated boundaries; outcomes outside significant shifts in consumer health priorities or major regulatory changes would require recalibration. Forecasts reflect assumptions regarding market dynamics and competitive landscapes. Practitioners should keep alternative scenarios live as USDA and FDA regulatory environments evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tea
Green Tea Market
Tea
Tea Infuser Market
Tea
APAC RTD Tea Market
Tea
Europe Tea Market
Tea
Detox Tea Market
Tea
Black Tea Base Bubble Tea Market
Tea
Tea Concentrate Market
Tea
Africa Ready to Drink Tea Market
Tea
Global Tea Bag Market
Tea
Fermented Tea Market
Tea
Bottled Milk Tea Market
Tea
Camellia Sinensis Leaf Extract Market
Tea
Middle East Ready to Drink Tea Market
Tea
Nitro Tea Market
Tea
Tea Pitchers Market
Tea
Kombucha Tea Market