
 Matcha Market | 2026-2036
Matcha Market Size, Share, and Industry Trends Forecast 2026-2036
Matcha Market Analysis
Specialty café procurement is consolidating around fewer high-volume matcha buyers with stringent origin requirements. Ito En leverages its vertical integration from Japanese tea gardens to packaged retail, sustaining quality consistency across channels. Tata Consumer Products competes through its distribution depth in emerging markets, while Aoi Tea Company specializes in ceremonial-grade production from Uji-region cultivars.
Matcha denotes shade-grown green tea leaves stone-ground into a fine, vibrant powder with particle sizes below 20 microns, delivering concentrated L-theanine and catechin content for beverages, confectionery, and nutraceutical applications. Ceremonial matcha commands the highest margin pool due to limited first-harvest supply and ritual-grade specifications, while culinary matcha dominates volume through bakery and dairy integrations. Instant matcha formats are gaining traction in single-serve sachets distributed through online retail channels targeting convenience-oriented individual consumers.
Japan's Ministry of Agriculture, Forestry and Fisheries enforces JAS organic certification for exported matcha, while the FDA governs import safety and labeling claims for the United States market. The EU's EFSA evaluates health claim substantiation for matcha-infused functional foods under novel food regulations. Stakeholders must monitor evolving pesticide maximum residue limits and traceability mandates that will determine market access for non-Japanese origin suppliers.
Market Dynamics
Specialty café procurement consolidation around Japanese-origin ceremonial-grade matcha is tightening supply access and compressing margins for mid-tier suppliers lacking direct garden relationships.
Growth Catalysts
- JAS Organic Certification:Japan's Ministry of Agriculture, Forestry and Fisheries enforces stringent shade-grown standards that command premium positioning in US and European retail channels.
- Functional Beverage Formulation:Clean-label energy drinks and ready-to-drink lattes incorporate matcha for L-theanine positioning, expanding foodservice procurement volumes.
- Uji-Region Cultivar Concentration:First-harvest tencha from Kyoto Prefecture's designated growing districts supplies ritual-grade material for wellness-focused beverage chains.
Market Restraints
- Shade-Grown Labor Intensity:Hand-picking under black shade cloth requires 20-30 days of pre-harvest coverage, constraining scalable supply expansion.
- Single-Origin Dependency:Authentic ceremonial-grade production concentrates in Japan's Kansai region, exposing buyers to climatic yield volatility and currency fluctuation.
- Stone-Grinding Throughput Limits:Traditional granite mill processing achieves only 40 grams per hour, creating production bottlenecks for fine-particle matcha below 10 microns.
Strategic Opportunities
- Instant Single-Serve Formats:Soluble matcha sachets distributed through direct-to-consumer channels target convenience-oriented individual buyers in North America.
- Nutraceutical Ingredient Positioning:EFSA novel food evaluation pathways for catechin-rich extracts open functional food applications in European markets.
- Culinary-Grade Volume Expansion:Bakery and dairy integrations in emerging Asian markets absorb lower-grade tencha that fails ceremonial specifications.
Industry Challenges
- Certified Tea Master Scarcity:Traditional chadō training requires years of apprenticeship, limiting quality-control personnel for export-oriented processing facilities.
- Pesticide Residue Testing Complexity:Evolving maximum residue limits across FDA, EFSA, and Japan's positive list system demand multi-jurisdictional compliance infrastructure.
- Cold-Chain Integrity for Fresh Tencha:Pre-ground leaf degradation accelerates above refrigerated temperatures, complicating logistics for non-Japanese processing locations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Matcha Market |
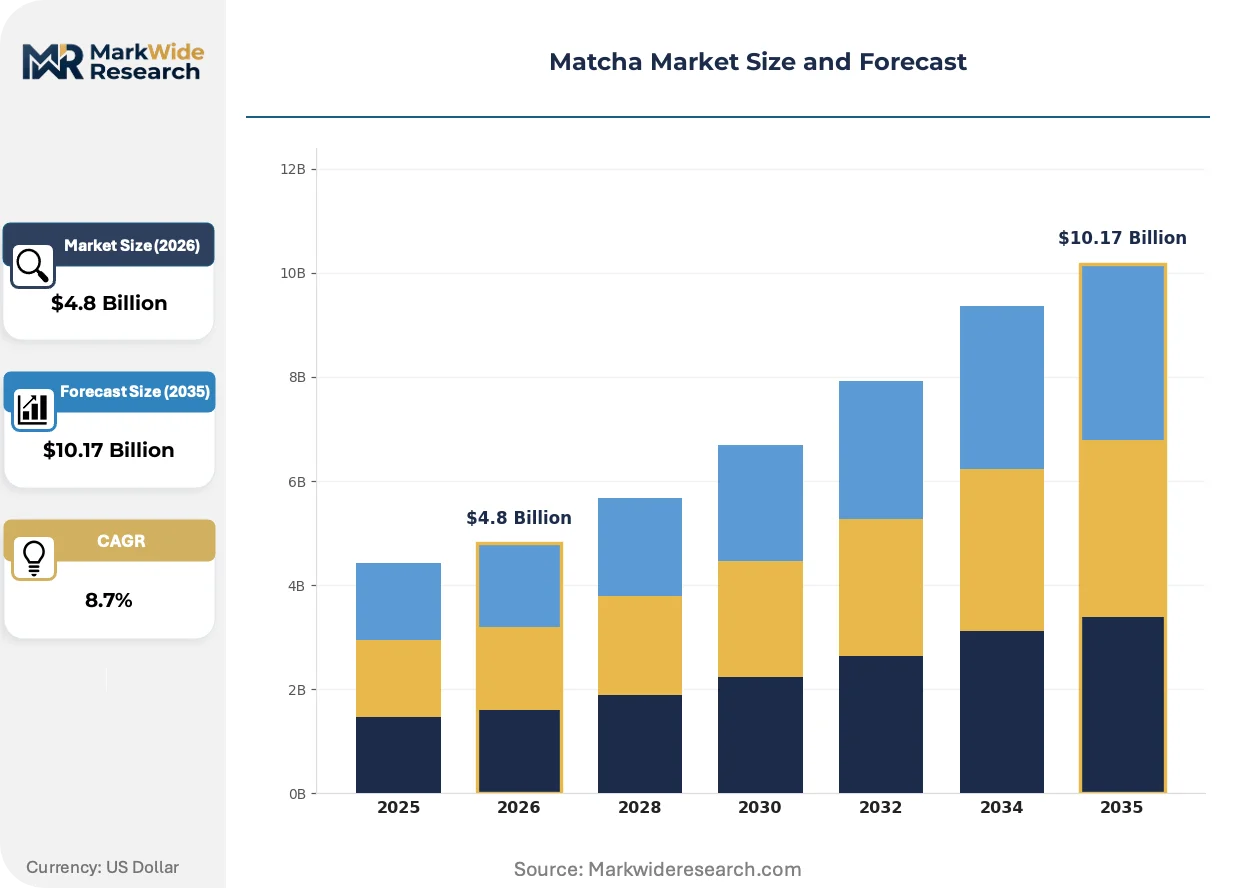
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Matcha, Culinary Matcha, Ceremonial Matcha, Instant Matcha End User: Restaurants, Cafés, Health Stores, Individual Consumers Packaging Type: Loose Leaf, Tea Bags, Sachets, Bulk Packs Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesalers |
| Companies Covered | Green Foods Corporation, Unilever, Ito En, Grace & Green, Tata Consumer Products, Aoi Tea Company, Hain Celestial Group, Azayaka, Encha, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Matcha Market Emerging Trajectories
Processing technology and procurement models are restructuring how matcha moves from shaded tea gardens to end-use formulations, with implications for quality verification and channel access.
Stone-grinding automation with temperature-controlled granite mills is rewriting particle-size consistency standards for ceremonial-grade production. Specialty café chains in the United States now specify sub-15-micron fineness in procurement contracts, compressing acceptable variance bands and disqualifying traditional manual operations that cannot guarantee thermal stability during extended grinding sessions.
EFSA's evolving novel food regulations for matcha-derived catechin extracts are reshaping functional food entry pathways in Europe. Health claim substantiation requirements now demand clinical trial documentation for antioxidant positioning, forcing reformulation strategies that separate beverage-grade from nutraceutical-grade supply streams.
Direct-to-consumer subscription models for ceremonial-grade matcha are displacing traditional importer-distributor relationships in North America. Wellness-focused individual buyers now source single-cultivar, single-harvest products with provenance documentation, bypassing foodservice and retail intermediaries that previously controlled quality narrative and pricing.
Matcha Market Segmentation
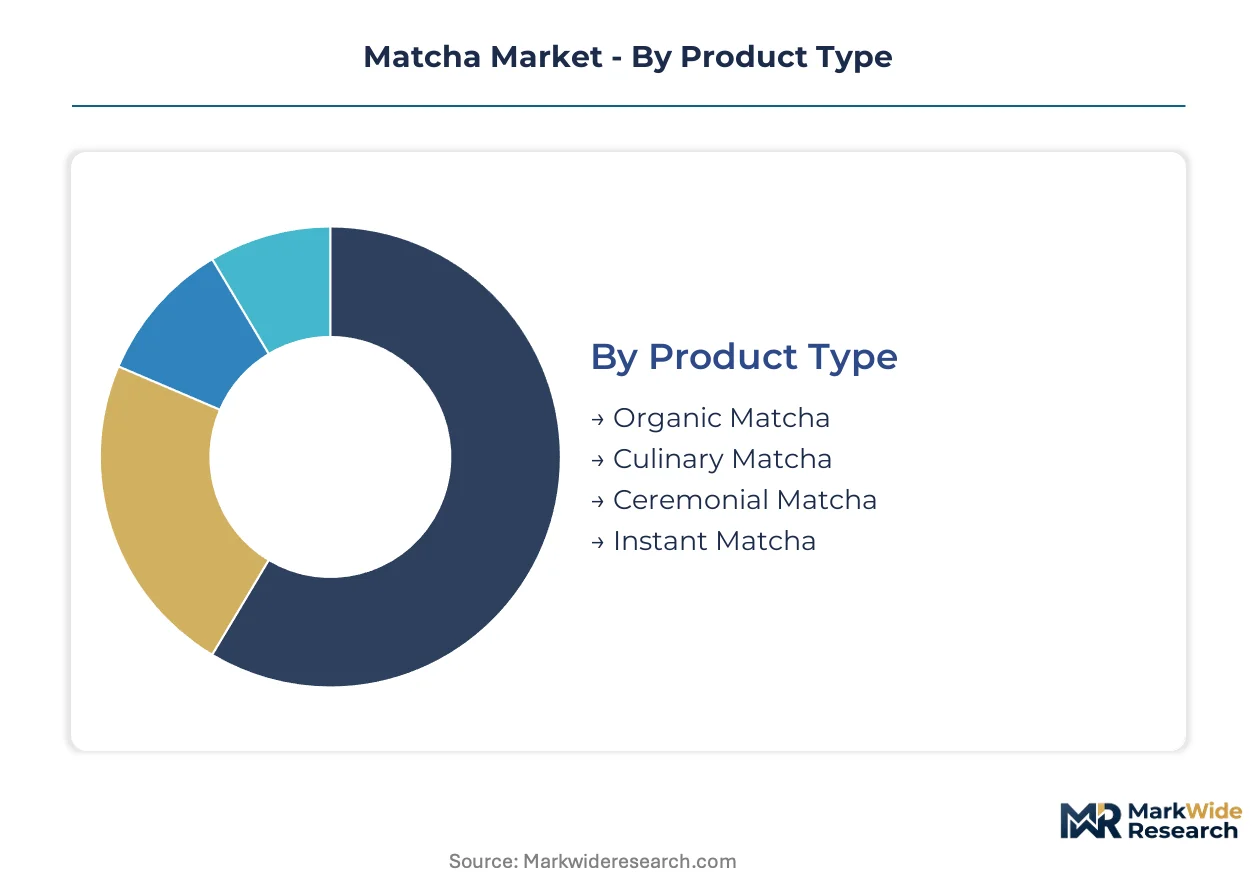
Matcha procurement patterns diverge sharply across product grades and channel structures. Buyers upgrade from culinary to ceremonial formats as quality literacy spreads, while packaging innovation unlocks new consumption occasions.
Product Type:
Upgrade cycles from culinary to ceremonial grades accelerate as café chains and wellness retailers build origin-specific sourcing programs.
- Ceremonial Matcha:First-harvest tencha from shade-grown Uji cultivars delivers sub-15-micron particle fineness and maximum L-theanine concentration. Specialty cafés in the United States now specify single-origin lots with provenance documentation, tightening supply access for ritual-grade material.
- Culinary Matcha:Second and third harvests supply bakery, dairy, and confectionery formulations with acceptable color and catechin levels at lower price points. Volume demand concentrates in emerging Asian markets where local processors absorb tencha that fails ceremonial specifications.
- Organic Matcha:JAS-certified shade-grown production commands premium positioning in European and North American retail channels.
- Instant Matcha:Soluble sachets target convenience-oriented individual consumers through direct-to-consumer subscription channels.
Culinary Matcha sits at the top of the volume ranking, with Instant Matcha climbing the fastest.
End User:
Customer sophistication determines margin capture, with institutional buyers demanding batch traceability while individual consumers prioritize convenience.
- Cafés:Third-wave coffee chains and dedicated matcha bars drive ceremonial-grade procurement with stringent origin requirements and particle-size specifications. These buyers now bypass traditional importer tiers to secure direct garden relationships in Kyoto Prefecture.
- Individual Consumers:Wellness-focused buyers in North America subscribe to single-cultivar, single-harvest products with chadō-grade preparation guidance. This segment absorbs premium pricing for documented provenance and freshness guarantees.
- Restaurants:Fine-dining establishments incorporate matcha into dessert and beverage programs with moderate volume requirements.
- Health Stores:Natural product retailers stock organic-certified formats targeting functional beverage and supplement positioning.
Individual Consumers deliver the steepest expansion trajectory, while Cafés anchor absolute volume throughput.
Packaging Type:
Format selection tracks consumption context, with single-serve solutions gaining share in convenience-oriented channels.
- Sachets:Pre-portioned single-serve packets eliminate measurement error and preserve freshness for occasional users. Direct-to-consumer brands in the United States deploy subscription models around sachet formats with cultivar-specific storytelling.
- Bulk Packs:Foodservice and processing customers procure 500g to 1kg formats for high-throughput operations with controlled storage infrastructure.
- Loose Leaf:Traditional tencha leaf format serves chadō practitioners and premium home preparation segments.
- Tea Bags:Lower-grade matcha in bagged format penetrates mass retail with price-accessible entry points.
Bulk Packs dominate foodservice procurement, with Sachets expanding most quickly in North American direct-to-consumer channels.
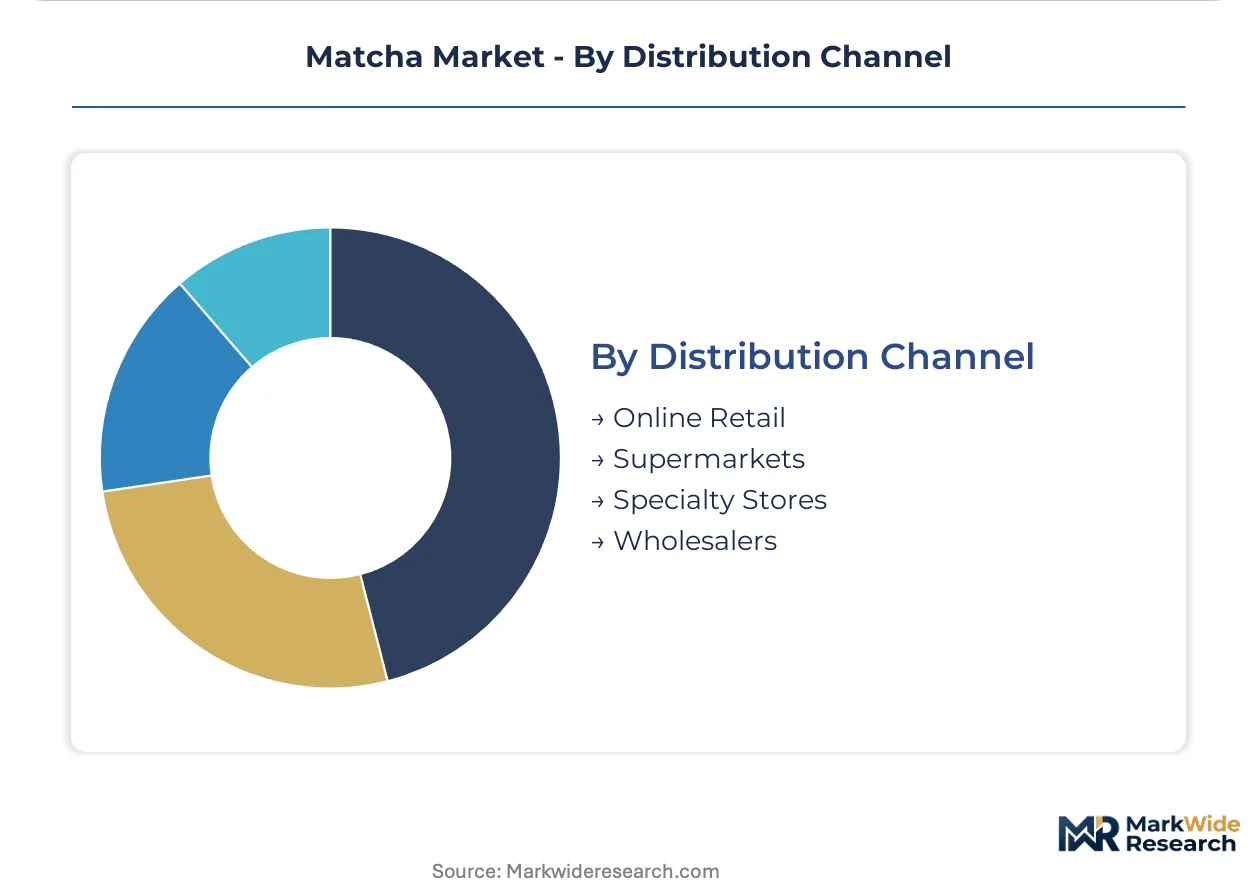
Distribution Channel:
Channel structure determines quality narrative control and margin retention for producers.
- Online Retail:Direct-to-consumer platforms enable single-origin storytelling and subscription relationships that bypass traditional markup layers. Wellness-focused buyers in the United States source ceremonial-grade products with harvest-specific documentation through dedicated matcha portals.
- Specialty Stores:Tea merchants and natural product retailers provide tactile evaluation and preparation education that supports premium pricing for ceremonial grades.
- Supermarkets:Mass retail channels move culinary-grade and instant formats with price-driven merchandising.
- Wholesalers:Traditional importer-distributor relationships persist for foodservice and processing customers with volume requirements.
Online Retail is gaining share fastest, though Wholesalers retain volume leadership in foodservice supply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States buyers pay premiums for documented Uji provenance that Japanese domestic consumers take for granted, while Chinese processors struggle to replicate Kyoto's first-harvest tencha quality despite comparable cultivar investments.
United States
Third-wave café chains in Los Angeles and New York now specify sub-15-micron particle fineness in procurement contracts, bypassing traditional importers for direct Kyoto Prefecture relationships. The FDA governs import safety and labeling claims for matcha-infused functional foods, with particular scrutiny on antioxidant positioning. Brooklyn-based wellness retailers operate subscription models delivering single-cultivar harvests within 48 hours of grinding.
Japan
Domestic consumption concentrates in Kansai region chadō practitioners and Tokyo metropolitan wellness consumers, with first-harvest tencha commanding ritual-grade premiums. The Ministry of Agriculture, Forestry and Fisheries enforces JAS organic certification that shapes export quality benchmarks for shade-grown cultivation. Uji-region stone-grinding operations in Kyoto Prefecture supply ceremonial-grade material with documented cultivar lineage for North American specialty channels.
China
Processing facilities in Zhejiang and Anhui provinces absorb second-harvest tencha for culinary-grade powder targeting bakery and dairy integrations across Southeast Asia. The National Medical Products Administration evaluates matcha-derived catechin extracts under novel food pathways for functional beverage applications. Hangzhou-based distributors now cold-chain fresh tencha to domestic grinding operations, bypassing traditional Japanese export channels for mid-tier restaurant supply.
Germany
Natural product retailers in Berlin and Munich stock JAS-certified organic formats for wellness consumers seeking L-theanine positioning without synthetic additives. EFSA evaluates health claim substantiation for matcha-infused functional foods under evolving novel food regulations, forcing clinical trial documentation for antioxidant marketing. Hamburg importers specialize in ceremonial-grade lots with full traceability documentation for premium foodservice accounts.
United Kingdom
Specialty tea merchants in London and Edinburgh provide tactile evaluation and preparation education that supports premium pricing for chadō-grade material. The Food Standards Agency aligns with EFSA guidance on matcha health claims, constraining marketing language for catechin-rich products. Manchester-based direct-to-consumer brands deploy subscription models targeting convenience-oriented buyers with single-serve sachet formats.
Matcha Market Vendor Landscape
Kyoto Prefecture producers anchor the ceremonial-grade tier; multinational food conglomerates hold volume positions in culinary-grade supply. Market structure concentrates around three strategic archetypes: Japanese garden-to-retail integrated operators, emerging-market distribution-heavy conglomerates, and direct-to-consumer specialty purveyors. Competitive moves center on backward integration into shade-grown cultivation and geographic expansion of cold-chain grinding capacity.
Within the integrated Japanese tier, Ito En exemplifies garden-to-retail control spanning Uji-region cultivation through packaged distribution. Tata Consumer Products occupies a position anchored in emerging-market distribution depth rather than origin-specific production. Aoi Tea Company represents the specialist archetype with concentrated ceremonial-grade output from designated Kyoto growing districts.
| Leading Market Players |
|---|
| Green Foods Corporation |
| Unilever |
| Ito En |
| Grace & Green |
| Tata Consumer Products |
| Aoi Tea Company |
| Hain Celestial Group |
| Azayaka |
| Encha |
| Others |
Supply Flow & Price Mechanics
Certified tea master concentration in Kyoto Prefecture creates labor-cost differentials that widen pricing spreads between ceremonial and culinary grades. JAS organic certification compliance costs in Japan elevate premium-tier positioning against Chinese-processed alternatives.
Pricing Analysis
Capacity additions in Zhejiang province are reshaping price floors for culinary-grade matcha as Chinese processors absorb second-harvest tencha. Three-tier pricing structure across ceremonial, premium culinary, and standard culinary levels stratifies by particle fineness and L-theanine concentration. Price differentiation hinges on shade-grown duration and stone-grinding throughput. Cost compression in mid-tier culinary supply is intensifying because automated grinding investments in China undercut Japanese manual production. Foodservice buyers show highest price sensitivity; direct-to-consumer wellness subscribers demonstrate lowest.
Supply Chain Analysis
Dual-sourcing requirements now mandate that North American specialty cafés qualify both Japanese and secondary-origin suppliers to mitigate single-origin dependency. Geographic supply concentrates in Japan, China, and Vietnam. Raw material dependencies include shade cloth, granite millstones, and refrigerated tencha storage. Supply chain risk centers on climatic yield volatility in Kyoto Prefecture's Uji region. Distribution runs through direct-to-consumer subscription channels, specialty tea importers, and foodservice wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: Japanese-origin ceremonial-grade commands 3-4x pricing multiples over Chinese culinary-grade due to JAS certification labor costs and limited first-harvest supply.
For Market Incumbents: Cement garden-to-retail control through captive shade-grown cultivation in Kyoto Prefecture's designated districts. Lock in multi-year procurement contracts with third-wave café chains before Chinese processors achieve sub-15-micron particle consistency. Threat: Automated temperature-controlled grinding in Zhejiang narrows quality gaps. Lever: Cold-chain grinding capacity expansion in North America reduces freshness degradation. For New Entrants and Emerging Players: EFSA novel food regulations in Europe open a window for catechin extract positioning in functional foods with clinical trial documentation. White-space targets include soluble single-serve formats for convenience-oriented North American subscribers and nutraceutical-grade supply for European health claim applications. Most penetrable segment: Direct-to-consumer subscription with cultivar-specific storytelling. Go-to-market angle: Partner with wellness influencers for chadō preparation education content. For Investors and Strategic Acquirers: Beverage conglomerates with functional drink portfolios are the most active acquirer in this space. Long-term viability favors integrated operators with backward control over shade-grown cultivation rather than pure-play distributors. Acquisition target archetype: Kyoto-based stone-grinding specialists with documented cultivar lineage and existing JAS certification. Signal to watch: FDA enforcement actions on antioxidant labeling claims that would elevate compliance costs for unverified suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Shade-Grown Cultivation | Kyoto Prefecture land leases secure first-harvest tencha access for ceremonial-grade supply. |
| Cold-Chain Grinding Facility Expansion | North American processing locations reduce pre-ground leaf degradation for freshness guarantees. |
| JAS Organic Certification Investment | Japan's Ministry of Agriculture standards unlock premium retail positioning in US and European channels. |
| Direct-to-Consumer Subscription Launch | Single-cultivar storytelling bypasses importer markups and captures wellness buyer premiums. |
| EFSA Novel Food Regulatory Pathway | Clinical trial documentation for catechin extracts opens functional food applications in Europe. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement covered tea garden operators in Kyoto Prefecture, procurement directors at US specialty café chains, Japanese agricultural export regulators, Chinese tencha processors in Zhejiang, and European natural product retailers. Secondary validation drew from Japan's Ministry of Agriculture trade statistics, FDA import refusal data, EFSA novel food register entries, and US customs records. Bottom-up volume modeling triangulated against top-down category spend estimates.
Segment-weighting applied differential growth assumptions across ceremonial, culinary, organic, and instant product types. End-user segmentation modeled cafés, individual consumers, restaurants, and health stores with distinct procurement patterns. Packaging format and distribution channel splits informed volume allocation. CAGRs derived from historical trajectory analysis adjusted for supply constraints and demand catalysts. Forecast inputs included shade-grown acreage expansion limits, stone-grinding throughput capacity, and regulatory approval timelines for novel food applications.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extreme weather events affecting Kyoto Prefecture harvests or abrupt FDA enforcement on antioxidant claims. Deviation in JAS organic certification acceptance rates for non-Japanese origin suppliers would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tea
Instant Tea Market
Tea
Herbal Tea Market
Tea
RTD Tea Market
Tea
Plant Based New Tea Drink Market
Tea
Asia-Pacific Organic Tea Market
Tea
Pu-Erh Tea Market
Tea
Asia-Pacific Ready to Drink Tea Market
Tea
China Tea Market
Tea
Tea Subscription Market
Tea
Organic Tea Market
Tea
Africa Ready to Drink Tea Market
Tea
Green Tea Bag Market
Tea
Slimming Tea Market
Tea
Global Tea Extract Market
Tea
White Tea Market
Tea
White Tea Extract Market