
 Global Tea Extract Market | 2026-2036
Global Tea Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Global Tea Extract Market Foresight
Single-serve sachet and stick-pack formats are expanding across the tea extract landscape, unbundling bulk powder into portion-controlled units that reduce waste and trial friction for new buyers. Martin Bauer Group leverages its vertical integration from field cultivation to extraction to sustain supply security for European nutraceutical clients. Synthite Industries anchors its position through deep backward integration into Kerala and Karnataka tea estates, while ADM competes via global distribution infrastructure spanning North American beverage corridors.
Tea extract comprises concentrated bioactive compounds—principally polyphenols, catechins, and L-theanine—derived through aqueous or solvent extraction of Camellia sinensis leaves, typically standardized to specific EGCG content for reproducible functional dosing. Green tea extract dominates value contribution due to established clinical validation of its antioxidant properties, while dietary supplements represent the fastest-expanding application channel as consumers self-direct preventive health regimens. Powder form retains the largest volume share given its stability in bulk manufacturing, though liquid concentrates command premium positioning within ready-to-drink beverage formulations.
EFSA novel food assessments and EU REACH substance restrictions are elevating documentation burdens for extract importers, while FDA GRAS self-affirmation pathways shape access dynamics for US-bound ingredients. China's SAMR food production licensing and GB standards for tea-derived products add compliance layers for domestic and export-oriented processors alike. Stakeholders must monitor evolving maximum residue limits for pesticides in origin countries and build dual-sourcing strategies that reduce concentration risk in any single growing region.
Market Dynamics
Functional beverage manufacturers are consolidating procurement around catechin-standardized extracts, forcing processors to retrofit aqueous extraction lines for EGCG concentration consistency while EFSA novel food assessments extend validation timelines for new entrants.
Growth Catalysts
- EU REACH substance restrictions:Purity benchmarks for pesticide residues and solvent traces are filtering out commodity-grade suppliers, concentrating volume with certified processors capable of full documentation chains.
- Ready-to-drink formulations:Beverage corridors in North America and Western Europe are absorbing liquid concentrate volumes that command premium positioning over bulk powder alternatives.
- Zhejiang and Yunnan provinces:China's dual role as raw material source and processing hub shortens lead times for export-oriented extractors serving nutraceutical clients.
Market Restraints
- Camellia sinensis leaf price volatility:Weather-driven harvest fluctuations in Kerala and Karnataka estates transmit directly to extract input costs, compressing processor margins during poor monsoon cycles.
- EFSA novel food authorization timelines:Extended safety assessment periods for non-traditional extraction methods delay product launches by 18-36 months, freezing capital in pending applications.
- Synthetic antioxidant substitutes:Butylated hydroxytoluene and tert-butylhydroquinone retain cost advantages in mass-market food preservation, capping tea extract penetration in price-sensitive categories.
Strategic Opportunities
- Brazil's ANVISA regulatory pathway:Simplified botanical ingredient notifications relative to EFSA complexity creates a faster commercialization route for South American functional beverage launches.
- Stick-pack single-serve formats:Portion-controlled sachets reduce trial friction for new buyers while opening direct-to-consumer channels that bypass traditional ingredient distributor markups.
- L-theanine and caffeine synergy positioning:Calm-alertness functional claims are penetrating cognitive performance supplements, extending extract demand beyond antioxidant applications into nootropic formulations.
Industry Challenges
- Phytochemist talent scarcity:Standardization of polyphenol profiles requires analytical chemists capable of HPLC method development, a skill set concentrated in pharmaceutical rather than food ingredient labor pools.
- Dual carbon compliance documentation:China's MEE emission tracking and EU CBAM carbon border adjustments impose parallel accounting systems that smaller processors lack infrastructure to satisfy simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Tea Extract Market |
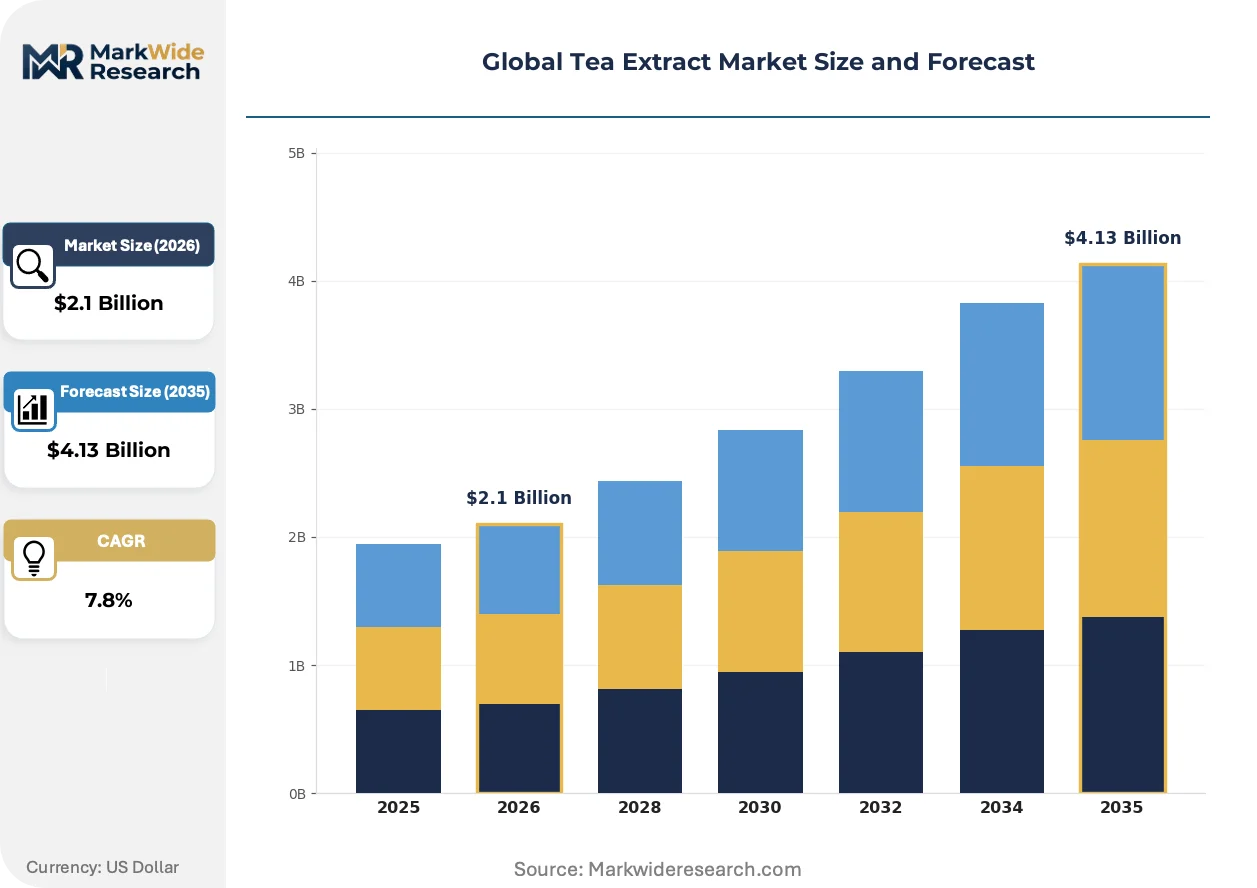
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.13 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Green Tea Extract, Black Tea Extract, Oolong Tea Extract, White Tea Extract, Pu-erh Tea Extract Application: Beverages, Dietary Supplements, Cosmetics, Pharmaceuticals, Food & Bakery Form: Liquid, Powder, Capsule, Tablet, Granule End User: Manufacturers, Retailers, Healthcare Providers, Personal Care Brands, Nutraceutical Companies |
| Companies Covered | Martin Bauer Group, Synthite Industries Ltd., ADM, Finlays, International Flavors & Fragrances Inc., Kemin Industries, Inc., Givaudan, Taiyo International, Indena S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Tea Extract Market Shifts & Advancements
Extraction technology and format engineering are converging to unbundle bulk commodity supply into precision-dosed, application-specific ingredients that reduce formulation friction for end-product manufacturers.
Supercritical CO2 extraction systems are modularizing downstream from traditional aqueous and ethanol-based methods, enabling processors to isolate specific catechin fractions without thermal degradation. Dietary supplement manufacturers in Germany and Switzerland are adopting these systems to produce EGCG isolates above 95% purity. The capital intensity of these installations is modularizing competitive tiers, separating integrated processors with captive extraction assets from toll-dependent competitors.
EFSA's 2023 updated guidance on botanical safety assessments is extending toxicological study requirements for novel extraction solvents, forcing reformulators to revert to aqueous methods or commission expensive 90-day rodent studies. The industrial consequence is a freeze on supercritical fluid innovation for EU-bound ingredients until validation costs amortize across sufficient volume. Green tea extract destined for novel food applications bears the heaviest documentation burden, with applicants absorbing six-figure certification investments before first commercial shipments.
Ingredient buyers are consolidating supplier relationships around processors offering integrated regulatory dossiers rather than commodity spot purchasing. Functional beverage formulators in California and New York are negotiating multi-year offtake agreements that bundle extract supply with GRAS self-affirmation support, displacing transactional procurement through distributor intermediaries. This bundling is most visible in North American markets where FDA enforcement discretion creates incentive for documented safety packages over minimal compliance.
Global Tea Extract Market Segmentation
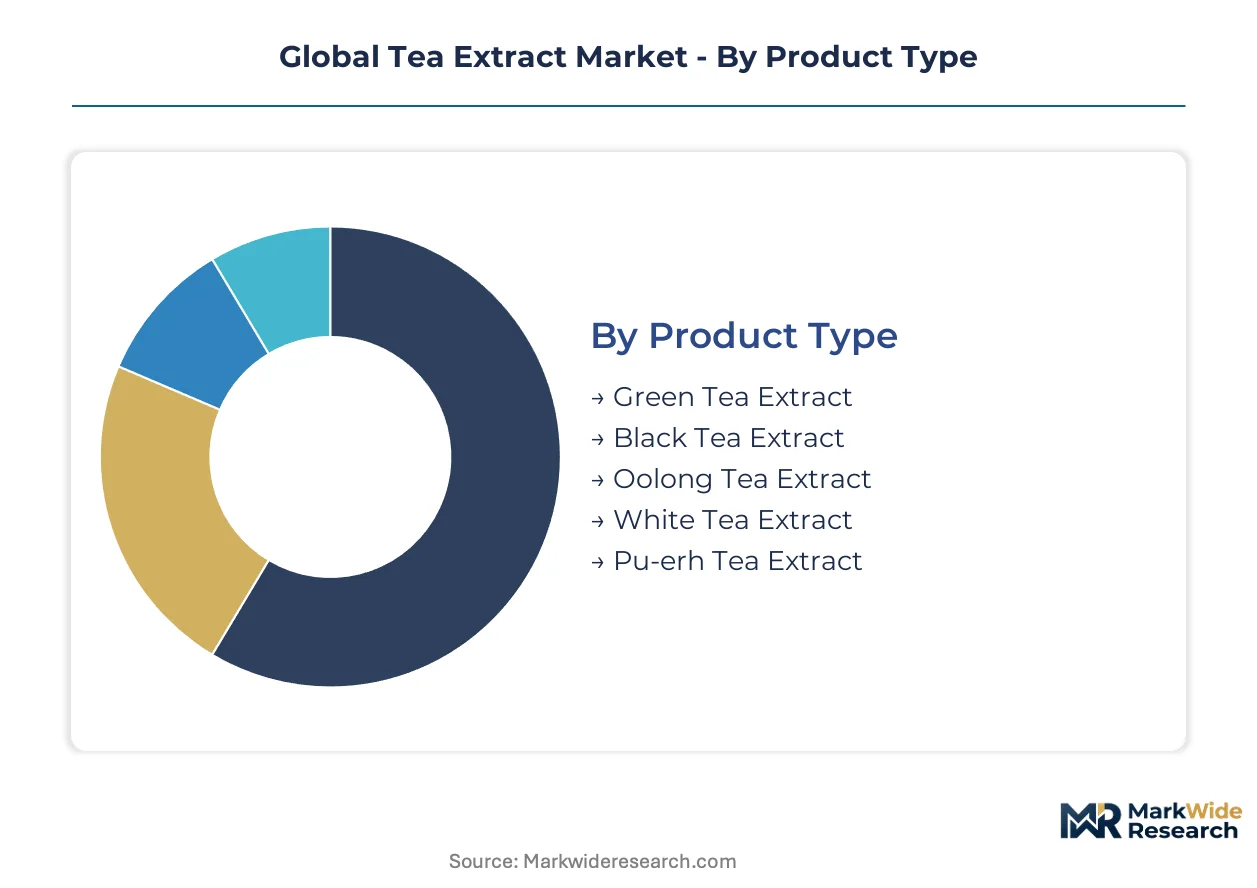
Tea extract segmentation reveals how functional ingredient buyers prioritize standardization grade over commodity sourcing. Product type and application splits determine which extraction technologies processors must deploy, while form factors dictate packaging investments and shelf-stability requirements.
Product Type:
Upgrade cycles in extraction technology are pushing processors toward higher-purity isolates that command premium positioning in nutraceutical formulations.
- Green Tea Extract:Standardized EGCG concentrations between 50% and 98% purity serve antioxidant and metabolic health applications. Beverage manufacturers in Germany and Switzerland absorb volumes for functional ready-to-drink lines where EFSA novel food dossiers require documented catechin profiles.
- Black Tea Extract:Theaflavin-rich fractions target cardiovascular positioning with distinct color and astringency profiles. Demand concentrates in North American dietary supplement channels where FDA GRAS self-affirmation pathways favor established extraction methods over novel solvent systems.
- Oolong Tea Extract:Partial oxidation delivers intermediate polyphenol complexity for traditional medicine applications in Taiwan and Fujian province processing clusters.
- White Tea Extract:Minimal processing preserves delicate catechin ratios for premium cosmetic formulations targeting sensitive skin segments.
- Pu-erh Tea Extract:Fermentation-derived statin-like compounds attract metabolic health positioning in Chinese domestic nutraceutical markets.
Green tea extract sits at the top of the volume ranking, with black tea extract climbing the fastest as cardiovascular claims gain regulatory traction in multiple jurisdictions.
Application:
Cost tier stratification separates commodity food preservation from premium therapeutic positioning, with documentation requirements widening the gap.
- Beverages:Liquid concentrates and water-dispersible powders enable clean-label fortification without sedimentation. Ready-to-drink corridors in California and New York negotiate multi-year offtake agreements that bundle supply with regulatory dossier support.
- Dietary Supplements:Capsule and tablet manufacturers demand certificate of analysis packages with HPLC-verified polyphenol standardization. This channel absorbs the highest purity grades as consumers self-direct preventive health regimens with specific milligram dosing expectations.
- Cosmetics:Topical antioxidant claims drive demand for low-odor, color-stable extracts compatible with emulsion stability requirements.
- Pharmaceuticals:Investigational drug applications require GMP-grade material with full traceability from Camellia sinensis cultivar through final extraction.
- Food & Bakery:Cost-sensitive preservation applications compete with synthetic alternatives where clean-label premiums fail to justify ingredient cost multiples.
Dietary supplements command the highest purity tier, while beverages deliver the steepest volume expansion trajectory as functional positioning penetrates mass-market distribution.
Form:
Customer type determines packaging investment priorities, with institutional buyers favoring bulk efficiency and direct-to-consumer channels demanding unit-dose convenience.
- Liquid:Concentrates and ready-to-use solutions reduce formulation friction for beverage manufacturers. Thermal stability challenges limit shelf life without aseptic processing investments.
- Powder:Spray-dried and freeze-dried variants dominate bulk manufacturing for dietary supplements and food fortification. Flowability and hygroscopicity specifications vary by end-use blending requirements.
- Capsule:Pre-filled hard gelatin and vegetarian shells eliminate dust exposure and dosing variability for supplement brands without encapsulation capacity.
- Tablet:Direct compression grades require specific particle size distributions and lubricant compatibility for high-speed manufacturing lines.
- Granule:Intermediate form factor bridges powder handling efficiency with liquid reconstitution convenience for instant beverage applications.
Powder retains volume leadership across manufacturing channels, with liquid concentrates gaining share fastest in beverage corridors where formulation speed determines product launch timelines.
End User:
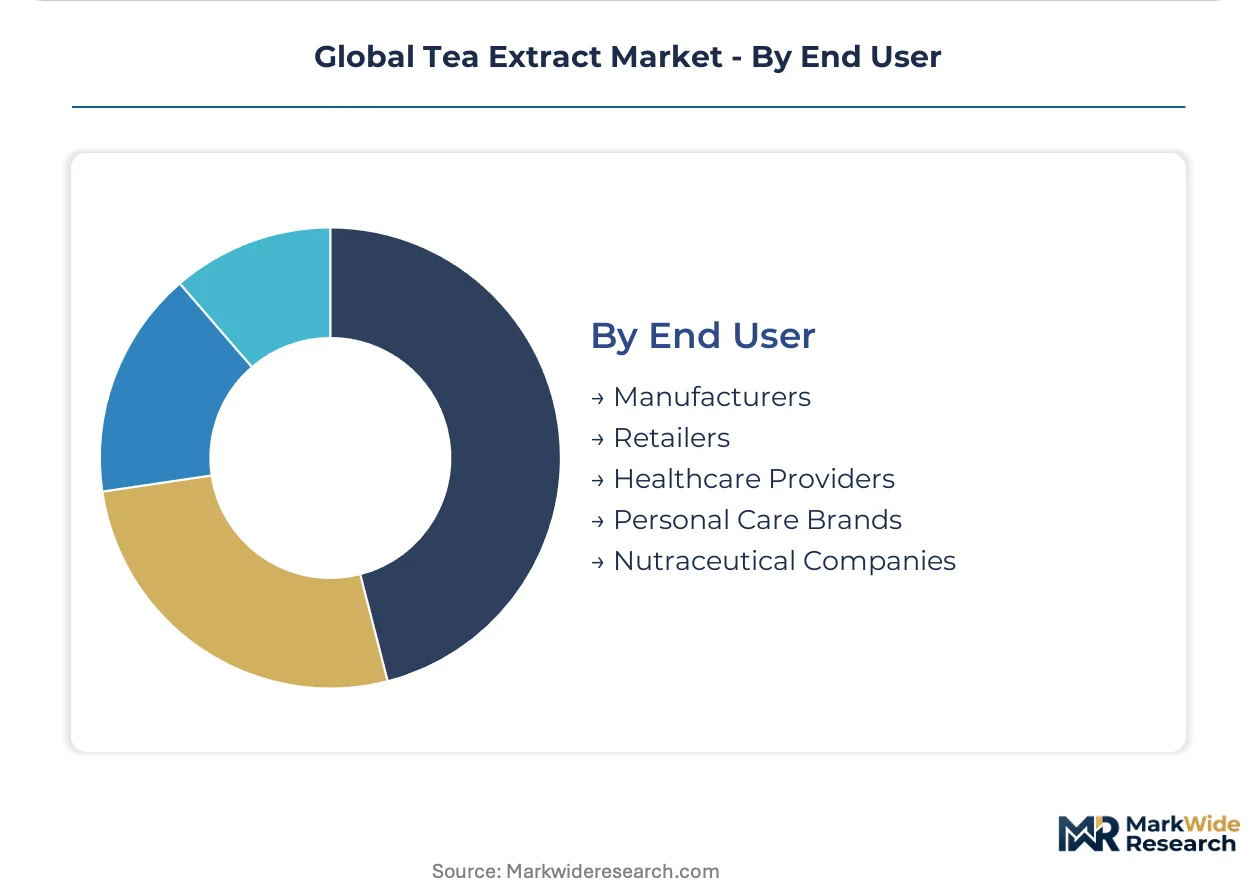
Supply concentration among nutraceutical specialists and personal care brands is reshaping procurement relationships toward integrated regulatory support rather than transactional spot purchasing.
- Manufacturers:Functional food and beverage producers require batch-to-batch consistency for production line integration, driving consolidation around processors with captive extraction assets.
- Retailers:Private-label supplement programs demand turnkey ingredient packages with pre-approved marketing claims and compliant labeling support.
- Healthcare Providers:Clinical nutrition and compounding pharmacy applications require pharmaceutical-grade documentation exceeding standard food ingredient specifications.
- Personal Care Brands:Cosmetic formulators prioritize color stability and odor neutrality over maximum polyphenol concentration for sensory acceptance.
- Nutraceutical Companies:Integrated brand-marketers source directly from origin processors, bypassing distributor markups while capturing margin from finished product positioning.
Manufacturers absorb the largest volume flows, with nutraceutical companies expanding procurement most aggressively as backward integration strategies consolidate supply security.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Camellia sinensis cultivation and industrial-scale extraction trace their modern commercial origins to 19th-century British colonial operations in India and Ceylon, with contemporary processing infrastructure now distributed across five dominant national markets.
China
Zhejiang and Yunnan provinces anchor both raw material supply and extraction capacity for export-oriented nutraceutical clients. SAMR food production licensing and GB standards for tea-derived products impose compliance layers on domestic processors serving international markets. Hangzhou and Kunming processing clusters shorten lead times for European and North American ingredient buyers.
United States
California and New York beverage corridors drive liquid concentrate procurement for ready-to-drink functional formulations. FDA GRAS self-affirmation pathways shape access dynamics, with formulators negotiating multi-year offtake agreements that bundle extract supply with documented safety packages. Los Angeles and Brooklyn manufacturing hubs concentrate blending and bottling operations for catechin-fortified product lines.
Germany
EFSA novel food assessments and REACH substance restrictions elevate documentation burdens for extract importers, filtering volume toward certified processors with full supply chain traceability. Martin Bauer Group leverages vertical integration from field cultivation to extraction to sustain supply security for European nutraceutical clients. Hamburg and Hamburg-adjacent logistics infrastructure facilitates distribution across the EU single market.
India
Kerala and Karnataka tea estates supply raw material to domestic extraction operations, with weather-driven harvest fluctuations transmitting directly to processor margins during poor monsoon cycles. FSSAI food safety standards govern domestic market entry, while export-oriented processors navigate EU and US regulatory parallel requirements. Kochi and Bengaluru processing clusters serve both regional Ayurvedic applications and international dietary supplement channels.
Brazil
ANVISA regulatory pathways offer simplified botanical ingredient notifications relative to EFSA complexity, creating faster commercialization routes for South American functional beverage launches. São Paulo and Rio de Janeiro formulation hubs absorb extract volumes for local brand development targeting cognitive performance and antioxidant positioning. Domestic demand concentrates in nutraceutical applications as preventive health regimens expand among urban consumers.
Global Tea Extract Market Competitive Landscape
Premium-margin players sit above commodity-margin players across extraction technology and regulatory dossier capabilities. The vendor base stratifies into three tiers: integrated processors with captive cultivation assets, toll-dependent specialists leasing extraction capacity, and commodity traders lacking standardization infrastructure. Strategic archetypes include backward-integrated agricultural operators, pharmaceutical-grade purity specialists, and global distribution conglomerates. Competitive moves center on multi-year offtake bundling with regulatory support and geographic expansion into faster-authorization jurisdictions.
Among integrated agricultural operators, Martin Bauer Group and Synthite Industries Ltd. exemplify backward integration strategies spanning field cultivation through final extraction. ADM represents the global distribution archetype, leveraging North American beverage corridor infrastructure to displace transactional procurement. These three anchors demonstrate how supply security and regulatory documentation capabilities separate premium-tier positioning from commodity-grade competition.
| Leading Market Players |
|---|
| Martin Bauer Group |
| Synthite Industries Ltd. |
| ADM |
| Finlays |
| International Flavors & Fragrances Inc. |
| Kemin Industries, Inc. |
| Givaudan |
| Taiyo International |
| Indena S.p.A. |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between EFSA novel food dossiers and commodity-grade spot supply splits the market into parallel pricing architectures. Premium processors commanding full documentation chains capture 40-60% price multiples over undifferentiated bulk powder, while procurement officers at functional beverage manufacturers in California and New York trade margin for regulatory security.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs extract transactions, with EGCG purity percentage and EFSA dossier completeness as the primary price differentiation drivers. Pricing pressure stems from synthetic antioxidant substitutes like butylated hydroxytoluene undercutting clean-label premiums in mass-market food preservation. Beverage manufacturers exhibit the highest price sensitivity due to formulation cost targets, while pharmaceutical-grade buyers absorb premium multiples for GMP documentation.
Supply Chain Analysis
Single-source vulnerability sits with Zhejiang and Yunnan provinces, where drought-induced harvest compression in 2023-2024 exposed procurement officers to 15-20 week lead time extensions. Raw material dependencies center on Camellia sinensis leaf from Kerala and Karnataka estates, aqueous extraction solvents, and spray-drying capacity. Tariff exposure through EU CBAM carbon border adjustments threatens smaller processors lacking dual carbon compliance infrastructure. Distribution runs through Hamburg and Rotterdam port clusters for European nutraceutical clients, with Los Angeles and Long Beach anchoring North American beverage corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Tea Extract Market functions as a stable compounder anchored by irreversible clean-label substitution trends in functional beverages and preventive health regimens.
For Market Incumbents: Extend backward integration into Kerala and Karnataka tea estates to secure captive raw material supply against monsoon-driven price volatility. Commission supercritical CO2 extraction assets in Germany or Switzerland to isolate 95%+ EGCG fractions for pharmaceutical-grade positioning, locking out toll-dependent competitors. EFSA's extended novel food timelines favor incumbents with amortized validation investments. For New Entrants and Emerging Players: Direct-to-consumer nutraceutical brands without encapsulation capacity represent the most penetrable buyer archetype. Stick-pack single-serve formats bypass distributor markups while reducing trial friction for cognitive performance positioning. Brazil's ANVISA regulatory pathway offers faster commercialization than EFSA complexity, enabling South American market entry before EU dossier completion. For Investors and Strategic Acquirers: Consolidation pressure builds where phytochemist talent scarcity constrains standardization capabilities at mid-scale processors. The 5-10 year viability window favors targets with captive extraction assets and pre-built regulatory dossiers over commodity traders. Watch for EFSA novel food authorization backlogs as an inflection signal—processors with cleared portfolios will command acquisition premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Origin Estates | Synthite Industries' Kerala cultivation control insulates margin from weather-driven leaf price spikes. |
| Supercritical CO2 Extraction Deployment | German and Swiss processors isolate 95%+ EGCG fractions without thermal degradation for pharmaceutical clients. |
| EFSA Novel Food Dossier Bundling | Multi-year offtake agreements with GRAS self-affirmation support displace transactional procurement in California corridors. |
| Stick-Pack Single-Serve Format Launch | Portion-controlled sachets open direct-to-consumer channels that bypass traditional ingredient distributor markups. |
| ANVISA Regulatory Pathway Exploitation | Simplified botanical notifications enable faster South American commercialization than EFSA validation timelines permit. |
Research Methodology
Bottom-up beverage and dietary supplement modeling reconciled against top-down extraction capacity tracking forms the analytical core of this study. Primary interviews with procurement directors at functional beverage manufacturers, regulatory affairs leads at extract processors, and category buyers at nutraceutical retailers combined with secondary validation from EFSA novel food registers, SAMR production licensing databases, FDA GRAS notification files, and EU REACH substance restriction updates.
Historical trendline analysis across EGCG standardization grades, extraction technology adoption curves, and regional regulatory authorization timelines anchored the projection framework. Segmentation dimensions modeled include product type purity tier, application channel documentation requirements, form factor packaging investment, and end-user procurement consolidation patterns. CAGRs derived from slope consistency analysis across the modeling period, with specific inputs from Camellia sinensis harvest yield variability and EFSA assessment queue depth.
Underlying measurement precision varies by segment; dietary supplement channel data carries tighter precision than cosmetic applications due to certificate of analysis standardization. Forecasts reflect assumptions around EFSA authorization velocity, monsoon cycle recurrence patterns, and synthetic substitute pricing elasticity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tea
Rooibos Tea Market
Tea
Asia-Pacific Tea Market
Tea
Light-Fermented Tea Market
Tea
Mate Tea Market
Tea
Tea Concentrate Market
Tea
Instant Tea Premixes Market
Tea
White Tea Extract Market
Tea
Global Ready-To-Drink Green Tea Market
Tea
Black Tea Base Bubble Tea Market
Tea
Green Tea Market
Tea
Africa Ready to Drink Tea Market
Tea
Matcha Products Market
Tea
Global Tea Bag Market
Tea
North America Tea Market
Tea
Smart Tea Set Market
Tea
Fermented Tea Market