
 Global Tea Bag Market | 2026-2036
Global Tea Bag Market Size, Share, and Industry Trends Forecast 2026-2036
Global Tea Bag Market Outlook
Premium single-origin and whole-leaf specification tiers is unwinding commodity-grade volume dominance across developed markets. Unilever Plc leverages its Lipton and Tazo portfolios to sustain mass-market shelf presence in North American grocery channels. Tata Consumer Products Ltd anchors South Asian supply chains through vertical integration into Assam and Darjeeling estates. Harney & Sons Fine Teas differentiates via direct-to-consumer specialization in rare Orthodox varieties.
A tea bag is a porous, sealed sachet containing measured dried tea leaves or herbal infusions, typically constructed from filter paper, food-grade nylon mesh, or natural silk fibers, designed for single-use immersion in hot water to extract soluble compounds. The product serves commercial food service, retail grocery, and direct-to-consumer channels requiring portion control, convenience, and standardized brew strength. Pyramid bag formats lead value generation due to expanded leaf expansion space and perceived quality signaling, while paper material segments face structural pressure from EU single-use plastic directives and consumer preference shifts toward compostable alternatives. Black tea flavor profiles retain mature volume dominance, though herbal and green segments capture faster growth in wellness-oriented channels.
FDA food contact substance regulations govern nylon and silk material approvals in the United States, while EFSA and EU Packaging and Packaging Waste Directive frameworks mandate recyclability thresholds and biodegradable migration timelines across European markets. China's SAMR enforces GB standards for food-contact paper and plastic materials, creating compliance complexity for multinational suppliers operating dual material platforms. Stakeholders must monitor evolving compostability certification requirements and regional material bans to optimize formulation pipelines and avoid stranded inventory positions.
Market Dynamics
The EU Green Deal's packaging waste directives are forcing immediate material transitions across European supply chains, compressing lead times for biodegradable tea bag substrate certification while hospitality buyers in China and North America simultaneously upgrade to whole-leaf pyramid formats.
Growth Catalysts
- EU Packaging and Packaging Waste Directive:Mandates for recyclability thresholds accelerate compostable fiber adoption among European converters.
- Hospitality channel premiumization:Hotel and food service buyers in Shanghai and Dubai specify single-origin sachet formats for in-room and table service.
- Pyramid bag technology:Expanded leaf expansion chambers enable whole-leaf brewing parity with loose-leaf methods in convenience formats.
Market Restraints
- Filter paper pulp volatility:Abaca and Manila hemp fiber prices fluctuate with Philippine and Ecuador weather patterns.
- Biodegradable certification timelines:Industrial compostability standards under ASTM D6400 and EN 13432 extend product launch cycles by 8-14 months.
- Silk and nylon substitution pressure:Food-grade synthetic mesh faces consumer backlash and regulatory scrutiny under France's AGEC law and emerging state-level US restrictions.
Strategic Opportunities
- Chinese domestic premium segment:Urban consumers in Chengdu and Hangzhou shift from bulk loose-leaf to portion-controlled sachets for office consumption.
- Direct-to-subscription channels:Curated Orthodox variety boxes bypass traditional grocery slotting fees and capture lifetime value through recurring revenue.
- Carbon labeling alignment:EU CSRD disclosure requirements create first-mover advantage for brands with verified Scope 3 supply chain data.
Industry Challenges
- Composting infrastructure gap:Home compostable films require municipal facility expansion that lags product availability in most US and European markets.
- Dual material platform complexity:Maintaining both plastic-based and fiber-based production lines strains working capital and quality assurance protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Tea Bag Market |
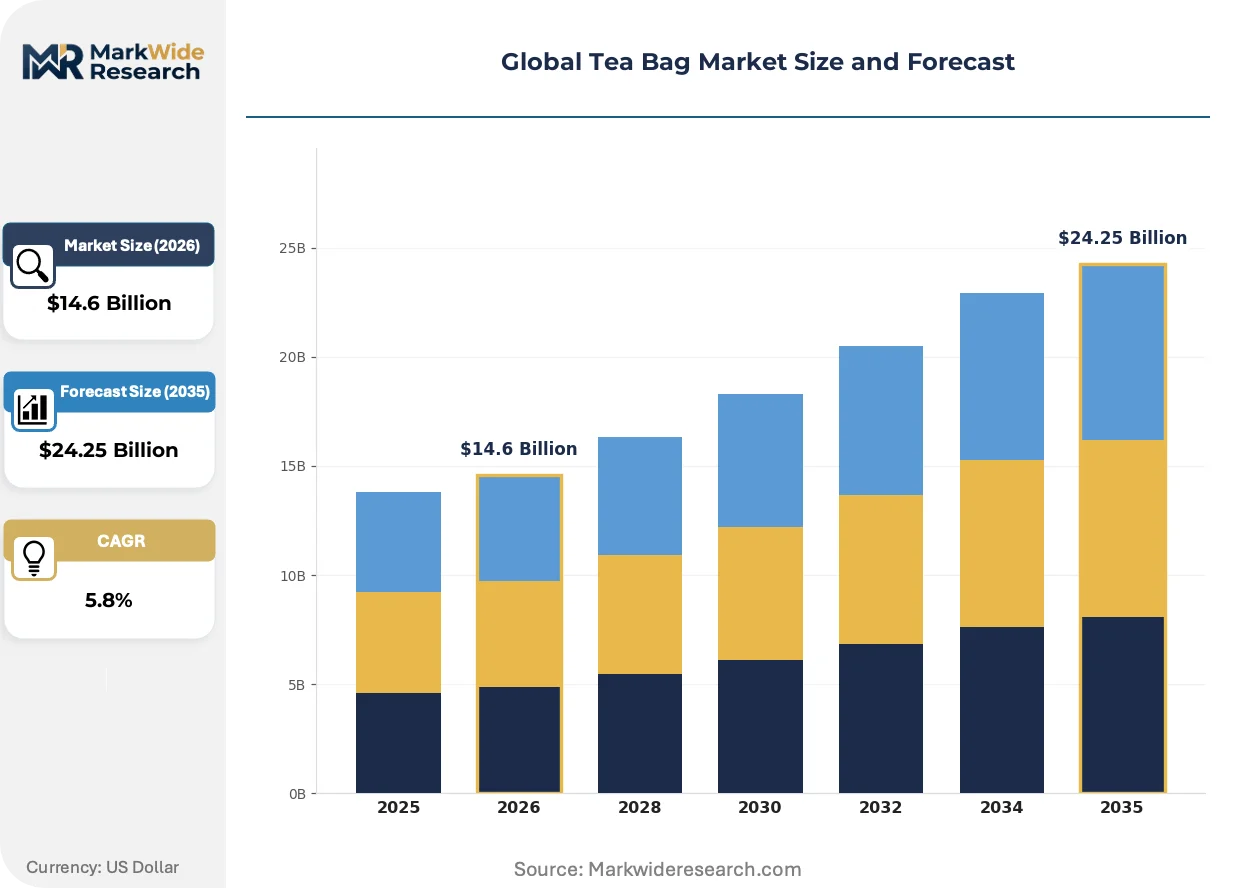
| Market Size in 2026 | $14.6 Billion |
| Market Size in 2035 | $24.25 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: String Bags, Pyramid Bags, Flat Bags, Sachets Material: Paper, Nylon, Cotton, Silk End User: Household, Food Service, Retail, Online Stores Flavor Profile: Herbal, Green, Black, Oolong |
| Companies Covered | Unilever Plc, Associated British Foods Plc, Tata Consumer Products Ltd, Bigelow Tea, Tetley, Dilmah Ceylon Tea Company Plc, The Republic of Tea, Harney & Sons Fine Teas, Celestial Seasonings Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Tea Bag Market Strategic Shifts
Material science breakthroughs and regulatory disclosure mandates are restructuring competitive advantage around verifiable sustainability credentials rather than flavor differentiation alone.
Plant-derived polylactic acid (PLA) mesh is decomposing the traditional nylon dominance in premium pyramid construction. Specialty tea houses in London and Melbourne specify PLA for whole-leaf formats. The technology is decomposing incumbent synthetic suppliers' grip on hospitality procurement specifications.
REACH substance restrictions and EFSA migration limits on food-contact materials tighten acceptable substance lists annually. European converters face reformulation costs for heat-seal coatings and ink systems. Black tea and herbal segments absorb disproportionate compliance burden due to higher brew temperatures accelerating compound migration.
Wellness-oriented buyers now demand ingredient provenance transparency exceeding traditional country-of-origin labeling. Direct-to-consumer platforms replace supermarket impulse purchases for functional herbal blends. Germany and California exhibit the sharpest channel rotation toward subscription and specialty retail.
Global Tea Bag Market Segmentation
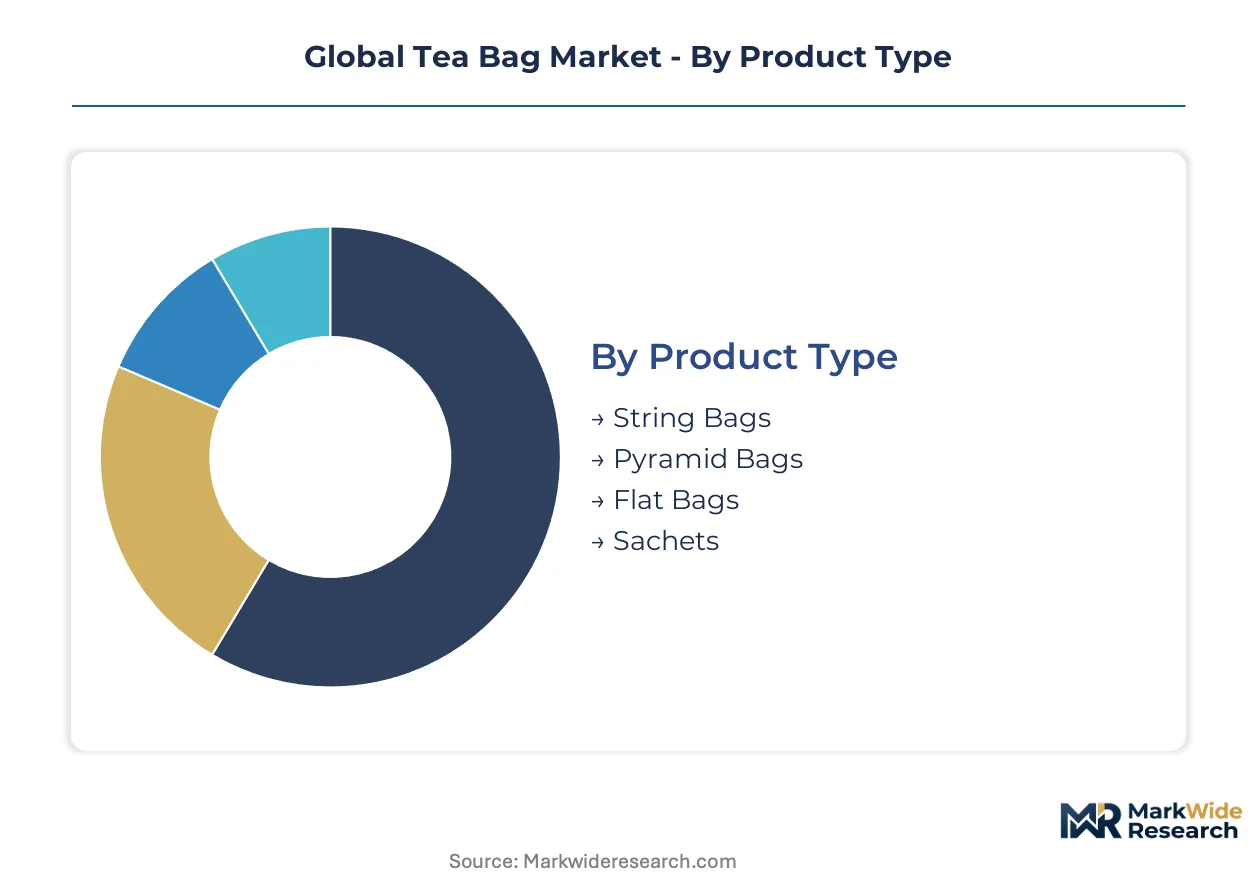
Product configuration and material composition determine channel access and margin capture in tea bag manufacturing. Format selection directly constrains which retail tiers and hospitality accounts converters can serve.
Product Type:
Retail shelf placement and hospitality procurement specifications diverge sharply across bag geometries, with premium food service channels rejecting legacy formats outright.
- Pyramid Bags:Three-dimensional sachets with expanded internal volume accommodate whole-leaf expansion during brewing. Shanghai luxury hotels and Dubai resort operators specify pyramid formats for in-room amenities, treating bag shape as a quality signal visible to guests.
- Sachets:Sealed envelope-style pouches containing premium loose-leaf portions bridge convenience and quality positioning. Direct-to-consumer subscription services in Germany and California curate single-origin sachet assortments, bypassing traditional grocery slotting fees.
- String Bags:Traditional double-chamber paper bags with attached tags dominate commodity retail in South Asian mass markets and institutional catering.
- Flat Bags:Single-chamber compressed paper formats occupy economy grocery tiers and vending machine channels where unit cost minimization overrides brew quality.
Pyramid bags dominate installed base in premium channels. Sachets are where expansion concentrates.
Material:
Regulatory compliance timelines and composting infrastructure availability segment material adoption by geography, with EU converters facing the most compressed transition schedules.
- Paper:Abaca and Manila hemp fiber substrates carry decades of production heritage but face structural pressure from EU single-use plastic directives. Philippine weather volatility disrupts pulp supply, forcing European converters to maintain dual inventory positions.
- PLA Mesh:Plant-derived polylactic acid decomposes under industrial composting conditions, satisfying EFSA migration limits and France's AGEC law restrictions on synthetic food contact materials. London specialty tea houses specify PLA for whole-leaf pyramid construction.
- Silk:Natural protein fiber commands ultra-premium positioning in gift and ceremonial segments, limited by harvest volume constraints and protein allergen labeling requirements.
- Nylon:Food-grade synthetic mesh retains cost advantages in high-temperature brewing applications but faces consumer backlash and emerging state-level US restrictions.
Paper substrates retain volume leadership. PLA mesh is climbing the fastest among material transitions.
End User:
Channel-specific quality thresholds and portion control requirements fragment demand, with hospitality buyers imposing specification rigor unavailable in mass retail.
- Food Service:Hotels, airlines, and restaurant chains standardize brew strength and brand presentation through portion-controlled formats. Procurement teams in Chengdu and Hangzhou specify single-origin sachets for office consumption upgrades.
- Online Stores:Subscription platforms capture lifetime value through curated variety boxes, replacing supermarket impulse purchases with recurring revenue models.
- Household:Grocery retail and pantry stocking drive volume through multi-count paper bag cartons, with wellness-oriented buyers shifting toward compostable alternatives.
- Retail:Supermarket and specialty store channels require slotting fee investments and standardized packaging formats, constraining small-batch Orthodox variety access.
Food service channels dominate specification-setting power. Online stores are gaining share fastest in developed markets.
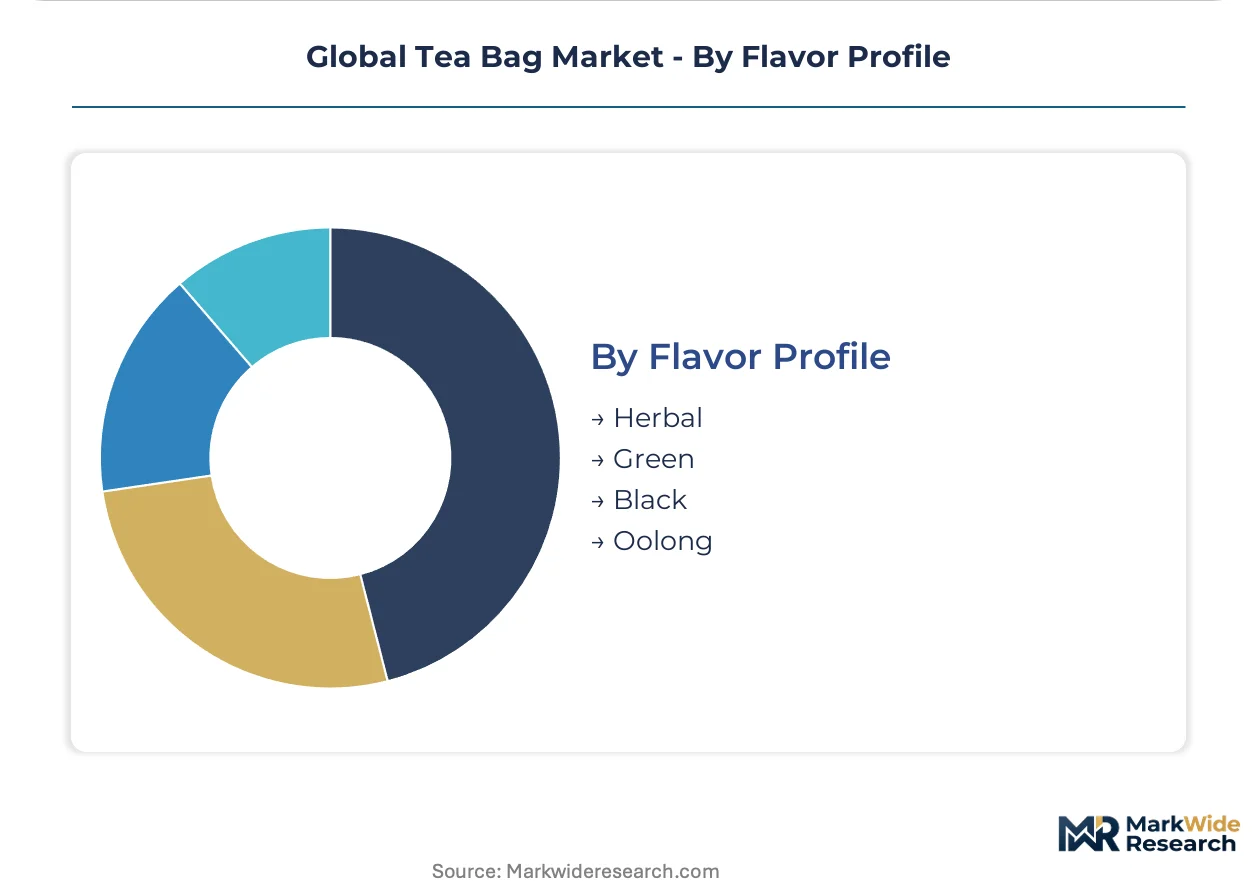
Flavor Profile:
Wellness positioning and brew temperature requirements segment material compatibility and geographic demand concentration.
- Black Tea:Fully oxidized Camellia sinensis leaves retain mature volume dominance across European and North American grocery channels, with higher brew temperatures accelerating compliance burden for heat-seal coating migration limits.
- Herbal:Non-camellia botanical infusions capture functional wellness positioning in Germany and California subscription channels, requiring ingredient provenance transparency exceeding traditional country-of-origin labeling.
- Green Tea:Minimally oxidized leaves align with antioxidant health claims in East Asian domestic markets and Western wellness retail.
- Oolong:Partially oxidized varieties occupy niche premium positioning in Chinese and Taiwanese specialty channels, with processing complexity limiting scale.
Black tea retains installed base dominance. Herbal blends are expanding most quickly in wellness-oriented channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Material sourcing clusters concentrate in Southeast Asian fiber plantations and European conversion facilities, while demand dispersion spans high-volume grocery retail in North America, premium hospitality procurement in the Middle East, and wellness subscription growth in Western Europe.
China
Domestic premium consumption is shifting urban buyers in Chengdu and Hangzhou from bulk loose-leaf toward portion-controlled sachets for office environments. SAMR enforces GB standards for food-contact paper and plastic materials, creating compliance complexity for multinational suppliers. The Yangtze River Delta hosts the densest concentration of biodegradable substrate converters serving both domestic food service and export markets.
Germany
Wellness-oriented buyers in Berlin and Munich drive subscription channel rotation toward curated herbal variety boxes with ingredient provenance transparency. ECHA REACH substance restrictions tighten acceptable substance lists annually for heat-seal coatings and ink systems. The North Rhine-Westphalia industrial corridor anchors European compostable fiber certification and testing infrastructure.
United States
FDA food contact substance regulations govern nylon and silk material approvals while state-level restrictions on synthetic food-contact materials emerge in California and New York. The Pacific Northwest and Northeast Corridor exhibit the sharpest channel rotation toward direct-to-consumer specialty retail. Mass-market grocery dominance in the Midwest and Southeast sustains paper bag volume through multi-count carton formats.
United Kingdom
London specialty tea houses specify PLA mesh for whole-leaf pyramid construction, decomposing incumbent synthetic suppliers' grip on hospitality procurement. EFSA migration limits on food-contact materials drive annual reformulation costs for European converters serving UK retail. The Midlands and Scotland retain legacy paper bag production heritage for institutional catering and economy grocery tiers.
United Arab Emirates
Dubai resort operators specify pyramid formats for in-room amenities, treating bag shape as a visible quality signal to international guests. MOHAP food safety standards align with Gulf Cooperation Council technical regulations for imported tea contact materials. The emirate's logistics hub function concentrates re-export trade serving Saudi Arabia and broader Middle East hospitality markets.
Global Tea Bag Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across material science, flavor formulation, and supply chain scale dimensions. The vendor base stratifies into three tiers: multinational FMCG conglomerates with mass-market shelf presence, regional estate-integrated operators with origin-controlled supply, and direct-to-consumer specialists with curated variety positioning. Dominant competitive moves include backward integration into fiber sourcing and captive supply of estate-grown leaf, alongside portfolio diversification into compostable material platforms.
Within the multinational tier, Unilever Plc and Associated British Foods Plc occupy positions defined by grocery channel scale and brand portfolio breadth. Tata Consumer Products Ltd anchors South Asian supply chains through upstream control over Assam and Darjeeling estates. Harney & Sons Fine Teas exemplifies the direct-to-consumer specialist archetype with Orthodox variety curation bypassing traditional retail slotting structures.
| Leading Market Players |
|---|
| Unilever Plc |
| Associated British Foods Plc |
| Tata Consumer Products Ltd |
| Bigelow Tea |
| Tetley |
| Dilmah Ceylon Tea Company Plc |
| The Republic of Tea |
| Harney & Sons Fine Teas |
| Celestial Seasonings Inc |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between Philippine abaca fiber cooperatives and European converters lock in both raw material access and eighteen-month price visibility against Manila hemp pulp volatility. These arrangements insulate biodegradable substrate producers from spot market swings while committing buyers to minimum volume thresholds that strain working capital during demand troughs.
Pricing Analysis
The EU Packaging and Packaging Waste Directive dictates the pricing tier structure across European supply chains, forcing converters to absorb certification costs that separate compostable PLA mesh from commodity paper formats. Three-tier pricing structure across premium pyramid, standard sachet, and economy flat bag levels reflects material compliance burden and brew temperature performance. Pricing pressure stems from biodegradable certification timelines extending product launch cycles. Mass-market grocery buyers in the US Midwest exhibit highest price sensitivity, while Dubai hospitality procurement teams prioritize quality signaling over unit cost.
Supply Chain Analysis
Port congestion at Manila and Davao elevates inbound logistics costs for abaca and hemp fiber shipments moving through the transpacific trade lane toward European conversion facilities. Raw material sourcing draws from Philippine fiber plantations, Chinese PLA resin production, and Indian silk harvesting. Supply chain risk centers on single-source vulnerability for food-grade nylon mesh facing France's AGEC law restrictions. Distribution runs through Rotterdam and Hamburg logistics hubs serving hospitality buyers across Western Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Tea Bag Market sits in a cyclical recovery phase driven by post-pandemic hospitality channel restocking and premiumization tailwinds. Material transition investments and certification backlogs create temporary margin compression that will reverse as compostable infrastructure matures.
For Market Incumbents: Secure backward integration into Assam and Darjeeling estate operations to anchor origin-controlled supply against emerging direct-to-consumer specialists. Lock in multi-year PLA resin offtake agreements before capacity constraints tighten. Channel control through captive hospitality distribution networks defends against subscription platform disintermediation.
For New Entrants and Emerging Players: Differentiate on compostable material science credentials that bypass legacy converters' dual-platform complexity. Target white-space opportunity in Chinese urban office consumption, where Chengdu and Hangzhou buyers shift from bulk loose-leaf to portion-controlled sachets. Launch through curated direct-to-subscription channels to avoid grocery slotting fee barriers.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors estate-integrated operators with captive fiber and leaf supply. Long-term viability hinges on Scope 3 carbon data infrastructure that satisfies EU CSRD disclosure requirements. Watch biodegradable certification approval velocity as the inflection signal for material transition winners.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Estate Operations | Captive supply of Assam and Darjeeling leaf secures origin-controlled premium positioning against commodity competitors. |
| Compostable Material Platform Transition | PLA mesh adoption satisfies EFSA migration limits and France's AGEC law while unlocking hospitality procurement specifications. |
| Direct-to-Consumer Subscription Launch | Curated Orthodox variety boxes bypass supermarket slotting fees and capture lifetime value through recurring revenue. |
| Carbon Labeling Infrastructure Investment | Verified Scope 3 supply chain data creates first-mover advantage under EU CSRD disclosure mandates. |
| Hospitality Channel Specification Capture | Pyramid format approval by Dubai and Shanghai luxury hotels treats bag geometry as visible quality signaling. |
Study Parameters
A spread of perspectives from procurement managers at hospitality chains, category buyers at grocery retailers, technical directors at fiber converters, and regulatory affairs leads at multinational FMCG firms converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through customs records, FDA food contact substance filings, EFSA migration limit documentation, and SAMR GB standard publications. Bottom-up demand modeling triangulated against top-down macroeconomic indicators.
Segmentation dimensions modeled include bag format geometry, substrate material composition, flavor profile category, and end-user channel across the analysis window. CAGRs were derived from trend extrapolation of premiumization rates and material substitution velocities. Forecast inputs incorporated EU Green Deal packaging waste directive compliance timelines and Chinese domestic consumption shift patterns.
Forecasts assume regulatory continuity in EU REACH substance restrictions, FDA nylon approval frameworks, and China's SAMR food-contact standards; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tea
Mate Tea Market
Tea
Probiotic Tea Market
Tea
Kombucha Tea Market
Tea
Out of Home Tea Market
Tea
Organic Tea Market
Tea
Black Tea Market
Tea
Smart Tea Maker Market
Tea
Tea Pitchers Market
Tea
Global Fruit Tea Market
Tea
Global Tea Extract Market
Tea
Europe Green Tea Market
Tea
Europe Tea Market
Tea
Green Tea Market
Tea
Pyramid Tea Bags Market
Tea
Middle East Ready to Drink Tea Market
Tea
White Tea Extract Market