
 Tea Packaging Market | 2026-2036
Tea Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Tea Packaging Market Outlook
Capital-intensity divergence between integrated film producers and regional converters is redrawing competitive boundaries in tea packaging. Amcor plc leverages global extrusion capacity to supply multilayer barrier films for premium tea pouches. WestRock Company anchors North American demand through its recycled paperboard supply chain for retail tea boxes. Mondi competes with integrated kraft paper operations serving European private-label tea brands.
Tea packaging encompasses primary and secondary enclosures designed to preserve aroma, moisture content, and shelf stability for dried Camellia sinensis leaves and herbal infusions, typically employing aluminum oxide-coated films or greaseproof paper laminates with moisture vapor transmission rates below 0.5 g/m²/day. The packaging type dimension shows pouches capturing the fastest growth as single-serve and loose-leaf formats expand in specialty channels, while tins retain margin concentration in gift and ceremonial segments. Material selection is shifting structurally as paper-based laminates displace conventional plastic windows in response to producer sustainability commitments.
The EU Packaging and Packaging Waste Regulation and FDA food-contact substance notifications govern material compliance across Atlantic trade lanes, with BIS certification requirements affecting Indian export-oriented tea packers. China's GB standards for composite food packaging and Japan's Food Sanitation Act shape access protocols in Asia-Pacific supply chains. Stakeholders must monitor evolving extended producer responsibility schemes and fiber sourcing certification thresholds to secure formulation approvals ahead of seasonal procurement cycles.
Market Dynamics
Material transition pressure from the EU Packaging and Packaging Waste Regulation is compressing lead times for tea packers sourcing fiber-based alternatives, forcing simultaneous reformulation of barrier properties and supply chain requalification ahead of seasonal procurement windows.
Growth Catalysts
- EU regulatory mandate:The EU Packaging and Packaging Waste Regulation accelerates fiber-based laminate adoption across European private-label tea brands, creating compliance-driven demand for moisture-barrier paper solutions.
- Specialty channel expansion:Single-serve and loose-leaf formats in United States specialty tea retail are pulling premium pouch demand with extended shelf-life requirements.
- China coastal clustering:Export-oriented tea processors in Zhejiang and Fujian provinces concentrate procurement volume, enabling scale economies for regional converters serving international brands.
Market Restraints
- Aluminum oxide coating supply:Thin-film metallization capacity concentrates among a limited set of European and Japanese equipment operators, creating input bottlenecks for high-barrier tea pouches.
- Technical barrier floor:Fiber-based laminates struggle to achieve moisture vapor transmission rates below 0.5 g/m²/day without plastic interlayers, limiting full material substitution in premium aroma-sensitive segments.
- BIS certification friction:Indian export-oriented tea packers face extended timeline uncertainty from evolving Bureau of Indian Standards composite food packaging requirements.
Strategic Opportunities
- Extended producer responsibility tailwinds:Deposit-return scheme expansion across Germany, France, and the Netherlands creates preferential access for fiber-certified tea packaging suppliers.
- Ceremonial gift segment:Tin and rigid box formats in East Asian ceremonial tea culture command sustained margin premiums resistant to material cost compression.
- Direct-to-specialty-retail channels:Subscription tea services bypass traditional wholesale distribution, enabling packers to capture value from customized short-run packaging.
Industry Challenges
- Barrier chemist scarcity:Formulation expertise spanning paper science and polymer adhesion remains concentrated among retiring specialists at European laminate producers.
- Dual certification timelines:Simultaneous FDA food-contact substance notification and EU compliance documentation stretches product development cycles for Atlantic-crossing tea brands.
- Legacy equipment retrofit costs:Converting lines optimized for plastic window cartons require capital-intensive reconfiguration to handle fiber-based structures at commercial speeds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tea Packaging Market |
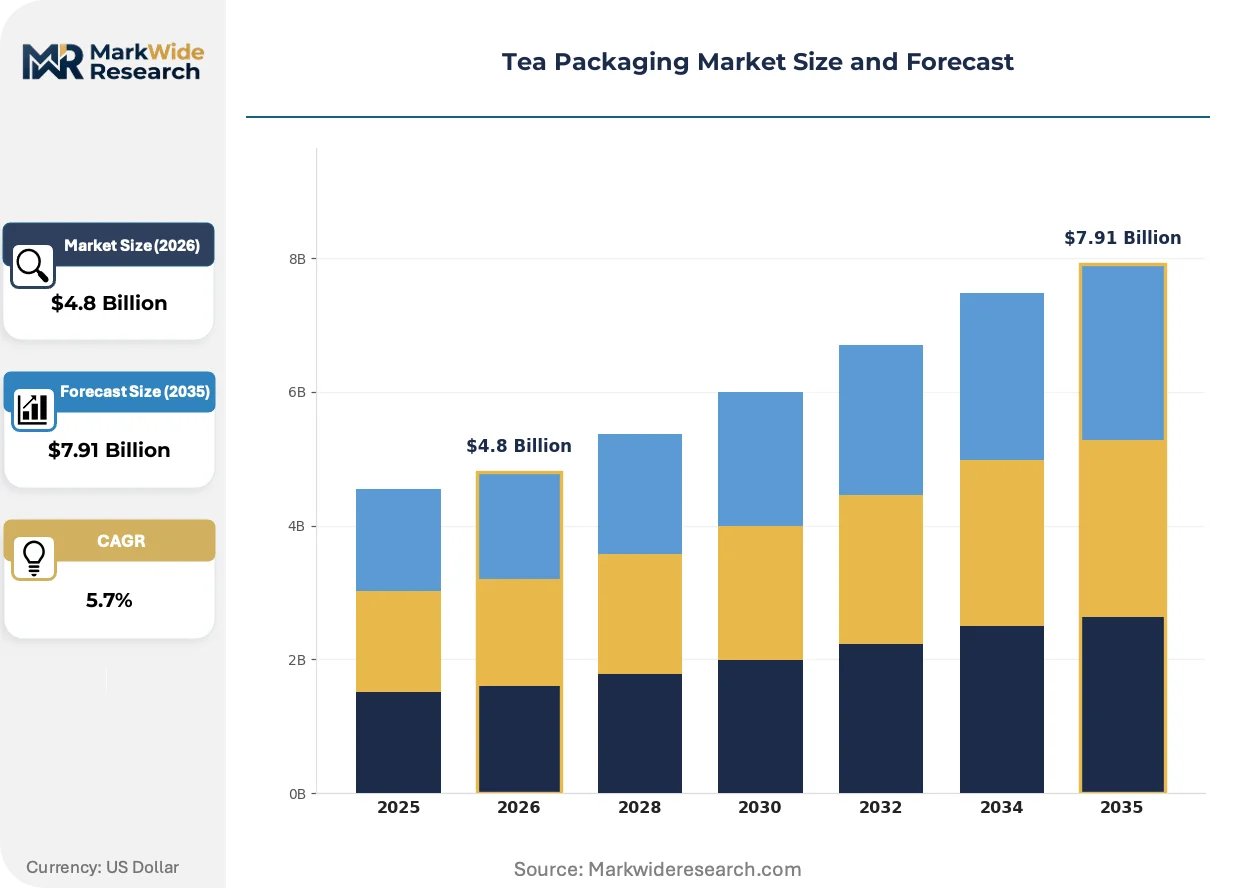
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Bags, Pouches, Boxes, Tins Material: Paper, Plastic, Metal, Glass Closure Type: Label, Ziplock, Seal, Twist-Off End User: Retailers, HoReCa, Distributors, Wholesalers |
| Companies Covered | Amcor plc, WestRock Company, Sonoco Products Company, Huhtamaki, Constantia Flexibles, Berry Global Inc., Mondi, Printpack, ProAmpac, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tea Packaging Market Strategic Shifts
Active material innovation and regulatory compliance automation are restructuring competitive capability requirements, separating packers with in-house barrier development from those dependent on external laminate suppliers.
Oxygen-scavenging adhesive laminates are bifurcating the specialty tea segment. Premium organic and white tea brands in the United States and United Kingdom specify these structures for eighteen-month shelf-life claims without nitrogen flushing. The technology is compressing demand for conventional aluminum-foil laminates in mid-premium positioning while enabling smaller regional roasters to compete on freshness parity with multinational brands.
REACH SVHC disclosure automation is reshaping European supply chain documentation. Tea packers serving EU retail must now track Substances of Very High Concern through multi-tier laminate supply chains, with ECHA database integration becoming a procurement gate. Private-label brands with limited compliance infrastructure are consolidating supplier bases to reduce traceability burden, favoring integrated film producers over regional converters.
Certification-driven procurement is concentrating buyer preference around FSC and PEFC fiber sourcing credentials. Specialty tea retailers in Scandinavia and German-speaking Europe now require chain-of-custody documentation as a contract condition, displacing uncertified paperboard options regardless of price position. This preference shift is most visible in the Nordic organic tea channel, where shelf placement depends on packaging sustainability scoring integrated into retail buyer evaluation systems.
Tea Packaging Market Segmentation
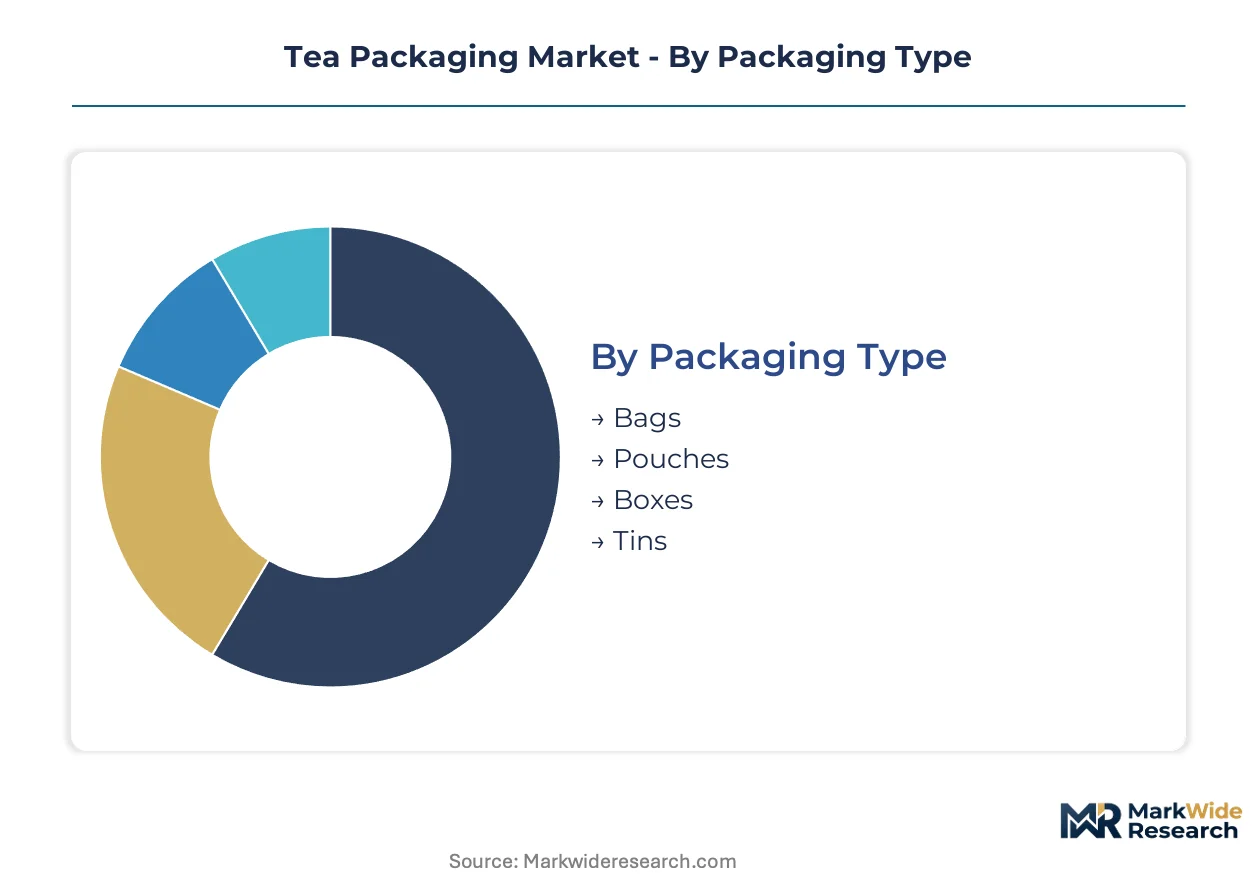
Tea packaging segmentation reveals how format, material, and channel choices map to distinct margin profiles and supply chain requirements. Each dimension carries specific regulatory and technical constraints that determine competitive positioning for converters and brand owners.
Packaging Type:
Export-oriented tea processors in China's coastal provinces favor formats optimized for ocean freight durability and retail shelf presence in destination markets, while domestic consumption patterns sustain distinct regional preferences.
- Pouches:Multilayer barrier structures with aluminum oxide coatings achieve moisture vapor transmission rates below 0.5 g/m²/day. Specialty tea brands in the United States and United Kingdom specify these for single-serve and loose-leaf formats with extended shelf-life claims, pulling premium demand through specialty retail channels.
- Boxes:Recycled paperboard constructions with fiber-based windows serve European private-label tea brands facing EU Packaging and Packaging Waste Regulation compliance deadlines. German and French retailers now mandate FSC or PEFC chain-of-custody documentation as a contract condition.
- Bags:Heat-sealed filter paper envelopes dominate mass-market black tea in South Asia and East Africa, with BIS certification requirements affecting Indian export-oriented packers.
- Tins:Rigid metal containers command sustained margin premiums in East Asian ceremonial tea culture, particularly for gift segments in China and Japan.
Boxes command the established base. The steepest expansion runs through pouches.
Material:
Cost tier differentiation separates commodity converters from integrated producers with captive barrier development capabilities.
- Paper:Greaseproof laminates and kraft-based structures are displacing conventional plastic windows as EU regulations compress lead times for fiber-based alternatives. Nordic organic tea retailers now integrate packaging sustainability scoring into buyer evaluation systems.
- Plastic:Multilayer films with ethylene vinyl alcohol interlayers retain dominance in premium aroma-sensitive segments where fiber-based laminates struggle to achieve technical barrier floors without plastic interlayers.
- Metal:Tinplate and aluminum formats serve ceremonial gift segments with resistance to material cost compression, particularly in Japanese and Chinese premium channels.
- Glass:Limited adoption concentrates in specialty herbal infusion displays where visual product presentation outweighs logistics efficiency considerations.
Plastic retains the highest value concentration. Paper gains share fastest on regulatory tailwinds.
Closure Type:
Application-specific sealing requirements drive specification divergence between retail shelf-stable formats and foodservice bulk handling.
- Ziplock:Reclosable polyethylene tracks serve loose-leaf specialty formats in United States subscription tea services, enabling repeated access without compromising moisture barriers.
- Seal:Heat-sealed fin or lap seals dominate high-volume bagged tea production for retail and HoReCa channels across South Asia and East Africa.
- Twist-Off:Metal lug closures on glass or tin containers target premium gift and ceremonial segments with resealability requirements.
- Label:Adhesive-backed paper or film closures on filter bags serve cost-optimized mass-market black tea with minimal reclosure functionality.
Seal formats anchor volume throughput. Ziplock specifications climb fastest on specialty channel expansion.
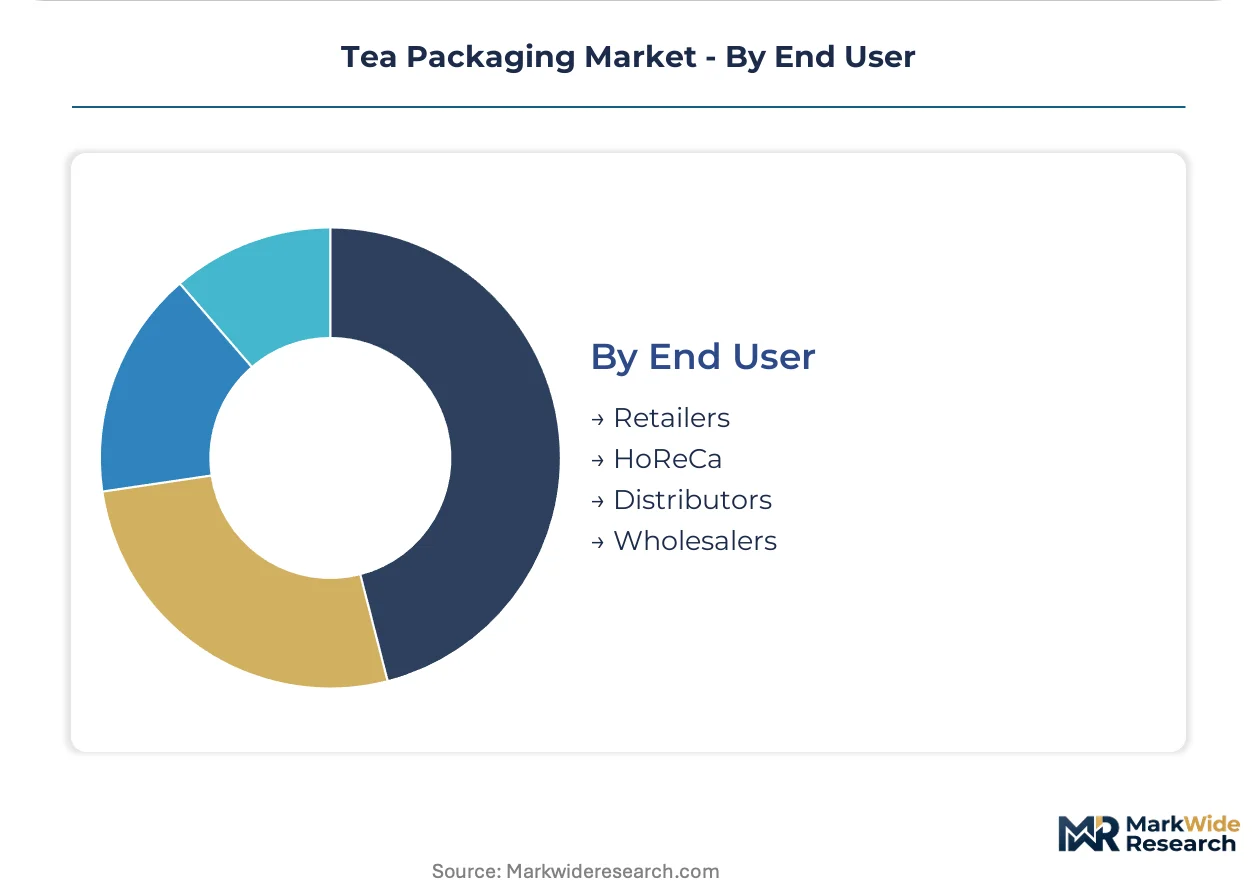
End User:
Customer type determines order scale, customization tolerance, and certification documentation burden.
- Retailers:Supermarket and specialty tea chains in Germany, France, and the Netherlands drive REACH SVHC disclosure automation and extended producer responsibility compliance, consolidating supplier bases to reduce traceability burden.
- HoReCa:Hotel, restaurant, and café procurement in the United States and United Kingdom favors portion-controlled formats with brand co-packing services for private-label tea programs.
- Distributors:Regional tea importers in Scandinavia and German-speaking Europe concentrate volume for private-label brands with limited compliance infrastructure.
- Wholesalers:Bulk tea traders in India's auction markets and China's Anhui province supply unpackaged leaf to downstream packers, with minimal value capture at the packaging stage.
Retailers concentrate compliance-driven specification power. HoReCa expands most quickly on direct-to-specialty-channel bypass of traditional wholesale distribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty tea brands in the United States favor premium pouches with extended shelf-life claims, while European retailers prioritize fiber-based boxes under compliance mandates. Chinese coastal processors concentrate export volume, creating distinct procurement patterns across consumption zones.
United States
Single-serve and loose-leaf formats in specialty tea retail pull premium pouch demand with moisture-barrier specifications. FDA food-contact substance notifications govern material compliance for Atlantic-crossing brands. Subscription tea services in direct-to-specialty-retail channels bypass traditional wholesale distribution, enabling customized short-run packaging.
Germany
Supermarket and specialty tea chains drive REACH SVHC disclosure automation and extended producer responsibility compliance. Deposit-return scheme expansion creates preferential access for fiber-certified suppliers. Private-label brands consolidate supplier bases to reduce traceability burden, favoring integrated film producers.
China
Export-oriented tea processors in Zhejiang and Fujian provinces concentrate procurement volume for international brands. GB standards for composite food packaging shape access protocols in Asia-Pacific supply chains. Coastal manufacturing clusters enable scale economies for regional converters serving specialty channels.
United Kingdom
Premium organic and white tea brands specify oxygen-scavenging adhesive laminates for eighteen-month shelf-life claims. ECHA database integration becomes a procurement gate for laminate supply chains. Specialty tea retailers in London and Southeast England require FSC and PEFC fiber sourcing credentials as contract conditions.
India
Heat-sealed filter paper envelopes dominate mass-market black tea production for retail and HoReCa channels. BIS certification requirements affect export-oriented tea packers with extended timeline uncertainty. Bulk tea traders in auction markets supply unpackaged leaf to downstream packers with minimal value capture at the packaging stage.
Tea Packaging Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in tea packaging supply. Integrated film producers with global extrusion capacity compete against regional converters with limited barrier development capabilities. Strategic archetypes include multinational packaging conglomerates with captive laminate operations, paperboard specialists with recycled fiber supply chains, and flexible packaging converters serving private-label tea brands. Dominant competitive moves center on backward integration into barrier film production and geographic expansion into China's coastal manufacturing provinces.
Within the integrated conglomerate tier, Amcor plc and Mondi exemplify scale-driven positions with extrusion and kraft paper operations respectively. WestRock Company anchors North American demand through recycled paperboard supply chains for retail tea boxes. These three entities occupy positions that separate capital-intensive integrated producers from regional converters dependent on external laminate suppliers.
| Leading Market Players |
|---|
| Amcor plc |
| WestRock Company |
| Sonoco Products Company |
| Huhtamaki |
| Constantia Flexibles |
| Berry Global Inc. |
| Mondi |
| Printpack |
| ProAmpac |
| Others |
Value Chain & Pricing Dynamics
Sixty-day lead times for aluminum oxide-coated barrier laminates concentrate pricing power among European and Japanese equipment operators, while fiber-based alternatives face compressed procurement windows under EU regulatory deadlines. Inventory carrying costs for tea packers sourcing multilayer films now compete directly with reformulation expenses for moisture-barrier paper solutions.
Pricing Analysis
Long-term offtake contracts dominate procurement between integrated film producers and multinational tea brands, insulating premium tier pricing from spot market volatility in metallized film inputs. Three-tier pricing structure across premium, standard, and economy levels separates oxygen-scavenging adhesive laminates from conventional aluminum-foil constructions and commodity filter paper. Cost compression in fiber-based boxes is intensifying because FSC certification premiums cannot fully offset plastic interlayer elimination. Private-label brands in European retail exhibit highest price sensitivity, while ceremonial gift segments in East Asia show least elasticity.
Supply Chain Analysis
Just-in-time inventory strategies prevail among United States specialty tea subscription services, whereas export-oriented processors in Zhejiang and Fujian provinces maintain strategic stockpiles of barrier films ahead of seasonal procurement cycles. Supply concentrates in China, Germany, and Japan for metallization equipment and high-barrier polymer inputs. Raw material dependencies center on ethylene vinyl alcohol resins, kraft pulp certified to FSC standards, and aluminum oxide coating chemicals. Single-source vulnerability runs through thin-film metallization capacity. Distribution runs through direct-to-specialty-retail channels bypassing traditional wholesale tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as fiber-based laminates displace conventional plastic windows and oxygen-scavenging adhesives erode aluminum-foil dominance in mid-premium positioning.
For Market Incumbents: Shield core barrier film margins by accelerating backward integration into metallization capacity or securing captive supply agreements with Japanese equipment operators. Prioritize certification investment in FSC chain-of-custody documentation to defend European retail shelf placement against insurgent fiber-based competitors. Channel control through direct-to-specialty-retail relationships provides defensive moats against private-label consolidation. For New Entrants and Emerging Players: BIS certification fast-track for Indian export-oriented tea packers creates white-space opportunity as incumbent suppliers face extended timeline uncertainty. Target Scandinavian organic tea retailers with uncertified paperboard displacement strategies. HoReCa portion-controlled formats in United States and United Kingdom offer penetrable entry point through brand co-packing services. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because barrier chemist scarcity and dual certification timelines favor integrated producers with in-house formulation expertise over regional converters. Acquisition target archetype: mid-cap flexible packaging converters in China's coastal provinces with established relationships to Zhejiang and Fujian export processors. Signal to watch is ECHA database integration speed as procurement gate for laminate supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Barrier Film Production | Captive supply of aluminum oxide coatings insulates against Japanese equipment operator bottlenecks. |
| FSC Certification Program Expansion | Chain-of-custody documentation secures contract eligibility with German and French retail buyers. |
| Direct-to-Specialty-Retail Channel Development | Subscription tea services bypass wholesale distribution and capture customized short-run packaging value. |
| Oxygen-Scavenging Adhesive R&D Investment | Eighteen-month shelf-life claims without nitrogen flushing compress aluminum-foil laminate demand. |
| Geographic Expansion into Coastal China | Zhejiang and Fujian province clustering enables scale economies for export-oriented processor relationships. |
Study Parameters
Desk research of EU regulatory filings, BIS certification documentation, and FSC chain-of-custody databases preceded structured interviews with tea packaging procurement managers, barrier film R&D directors, retail category buyers, and regulatory compliance officers at laminate producers. Secondary validation drew from customs trade data, SEC filings of integrated packaging conglomerates, and ECHA SVHC disclosure records. Bottom-up volume estimates from converter capacity utilization were triangulated against top-down brand procurement surveys.
Variance decomposition across packaging type, material substrate, closure mechanism, and end-user channel dimensions structured the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against aggregate market trajectory. Industry-specific forecast inputs included seasonal procurement cycle timing for tea harvests and EU Packaging and Packaging Waste Regulation compliance deadline phasing.
The analysis sits within stated boundaries; outcomes outside sustained specialty channel expansion or accelerated fiber-based material transition would require recalibration. Forecasts reflect assumptions regarding metallization capacity availability and certification timeline stability. Revision becomes warranted when BIS certification uncertainty or aluminum oxide supply bottlenecks cross thresholds that compress lead times beyond seasonal procurement windows.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tea
Smart Tea Set Market
Tea
Moringa Tea Market
Tea
Africa Tea Market
Tea
Matcha Tea Market
Tea
New Style Tea Drink Market
Tea
Tea Essence Market
Tea
North America Tea Market
Tea
White Tea Market
Tea
North America Ready-To-Drink Tea Market
Tea
China Tea Market
Tea
Black Tea Extracts Market
Tea
Spray-Dried Tea Products Market
Tea
US RTD Organic Tea Market
Tea
Out of Home Tea Market
Tea
Instant Tea Premix Consumption Market
Tea
Middle East Ready to Drink Tea Market