
 Chromium Carbide Overlay Plate Market | 2026-2036
Chromium Carbide Overlay Plate Market Size, Share, and Industry Trends Forecast 2026-2036
Chromium Carbide Overlay Plate Market Insights
Buyer concentration among North American mining operators is pivoting toward long-term supply agreements with certified overlay plate fabricators. Kennametal Inc. leverages its cemented-carbide expertise to anchor premium product lines for extreme abrasion environments. JADCO Manufacturing Inc. competes through specialized fabrication capabilities and rapid custom-shape turnaround. ArcelorMittal S.A. extends its steelmaking upstream control into overlay plate production, securing captive raw material flows.
Chromium carbide overlay plate consists of a mild steel base fused with a hardfacing layer containing chromium carbide precipitates, typically achieving hardness values of 58-62 HRC through submerged arc welding deposition. The composite structure delivers extended service life in high-abrasion environments such as chutes, hoppers, and crusher liners where unprotected carbon steel would erode rapidly. Flat plates dominate current volume owing to standardized dimensional formats and ease of field installation across mining and steel manufacturing end users. Custom shapes capture expanding margin pools as OEMs specify complex geometries for retrofit compatibility with existing equipment. Wear liners represent the fastest-growing product category, driven by shovel bucket and truck bed refurbishment cycles in open-pit operations.
MSHA workplace safety standards and EPA particulate emissions frameworks govern material selection and surface durability requirements in US mining and steel production facilities. REACH substance restrictions in Europe limit hexavalent chromium exposure during welding fabrication, pushing suppliers toward controlled-atmosphere deposition processes. ASTM wear-test protocols and ISO hardness certification schemes define procurement qualification thresholds for industrial buyers. Stakeholders must monitor evolving alloy-composition regulations and deposition-process certifications to maintain specification compliance across jurisdictional markets.
Market Dynamics
Long-term supply agreements between mining operators and certified overlay plate fabricators are compressing spot-market liquidity and favoring vertically integrated producers with captive steelmaking capacity.
Growth Catalysts
- Pilbara iron ore expansion:Australian mining operators are accelerating shovel bucket and truck bed refurbishment cycles, driving wear liner procurement volumes for bulk-material handling equipment.
- EPA emissions enforcement:Tightening particulate standards for heavy-industrial facilities in the United States are mandating durable lining materials that reduce dust generation during ore processing.
- Submerged arc welding automation:Advanced deposition systems are improving chromium carbide layer consistency and reducing fabrication lead times for custom-shaped overlay plates.
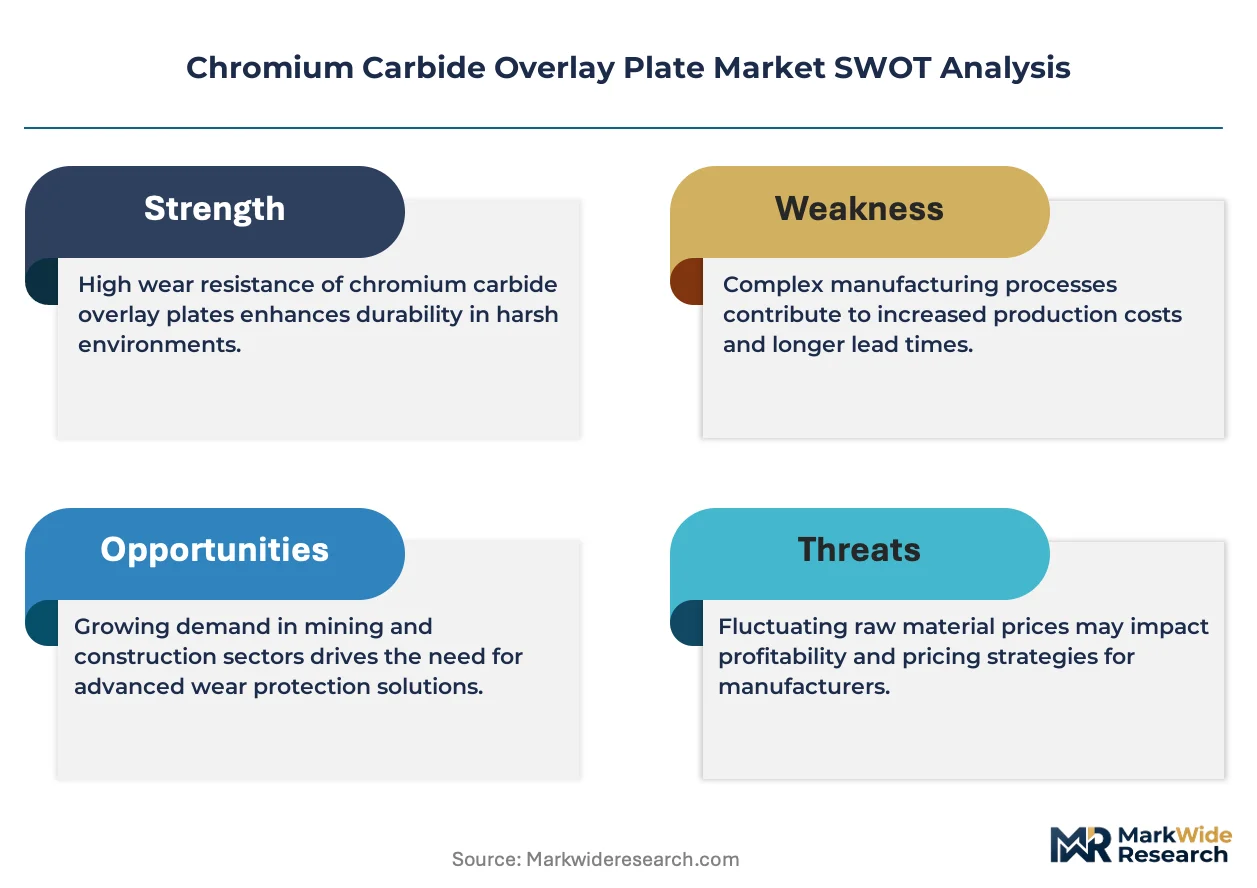
Market Restraints
- Chromium price volatility:Ferrochrome input costs fluctuate with South African supply disruptions and electricity tariff instability, compressing fabricator margins.
- REACH compliance friction:European hexavalent chromium exposure limits during welding fabrication are forcing costly controlled-atmosphere process upgrades or market exit.
- Tungsten carbide substitution:Extreme abrasion environments in some mining applications are shifting specification toward cemented-carbide alternatives with superior hardness retention.
Strategic Opportunities
- Brazilian Carajás complex:Vale's expansion of iron ore capacity in Pará state is creating demand for localized overlay plate fabrication and field installation services.
- MSHA dust standard alignment:Compliance-driven specification upgrades for surface durability present margin expansion for certified suppliers serving US underground operations.
- Digital wear monitoring integration:Sensor-equipped liner systems that predict replacement timing are enabling outcome-based service contracts with predictive maintenance bundling.
Industry Challenges
- Qualified welder scarcity:Submerged arc welding certification for chromium carbide deposition requires specialized training programs that lag current demand in mining regions.
- ASTM wear-test backlog:Procurement qualification timelines extend 12-16 weeks due to laboratory capacity constraints for standardized abrasion testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chromium Carbide Overlay Plate Market |
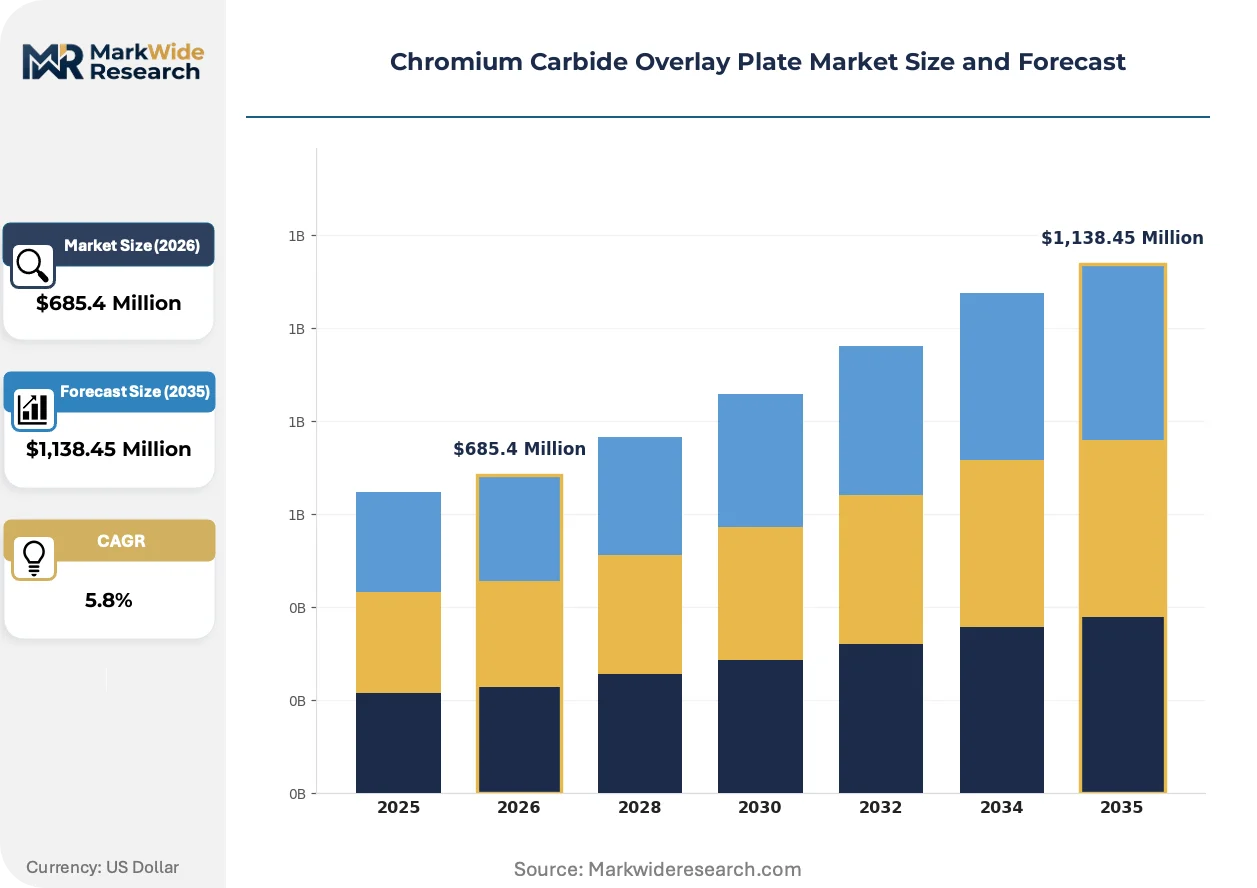
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Plates, Custom Shapes, Wear Liners, Pipe Protection End User: Mining, Construction, Oil & Gas, Steel Manufacturing Material Grade: High Carbon Steel, Low Alloy Steel, Stainless Steel, Others Thickness: 4mm, 6mm, 10mm, 12mm |
| Companies Covered | Kennametal Inc., JADCO Manufacturing Inc., ArcelorMittal S.A., Sinosteel Corporation Limited, Foothills Steel, SSAB AB, Voestalpine AG, Carpenter Technology Corporation, Sandvik AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chromium Carbide Overlay Plate Market Trends and Innovations
Overlay plate fabrication is pivoting toward precision-deposition automation and digital integration, compressing the gap between standardized flat-plate production and complex custom-geometry delivery.
Controlled-atmosphere submerged arc welding is expanding into European fabrication facilities as REACH hexavalent chromium restrictions tighten. German and French steel service centers are retrofitting deposition booths with argon-shielded environments to maintain market access. This process shift is expanding into premium product lines where certification documentation commands price premiums over conventional open-arc deposition.
EPA particulate emissions frameworks are forcing specification upgrades for chute and hopper linings in US coal and iron ore processing facilities. Compliance officers now require surface roughness metrics that demonstrate dust suppression performance, not merely hardness certification. Steel manufacturers in Pennsylvania and Minnesota are responding by qualifying overlay plates through third-party emissions testing protocols before facility installation.
Buyer concentration among Australian and Brazilian mining operators is compressing supplier negotiation leverage and extending contract durations. Spot-market purchasing for emergency liner replacement is giving way to multi-year framework agreements with volume commitments and dedicated fabrication capacity. Western Australia's Pilbara district exhibits this pattern most acutely, with Rio Tinto and BHP consolidating vendor panels to three certified fabricators per wear category.
Chromium Carbide Overlay Plate Market Segmentation
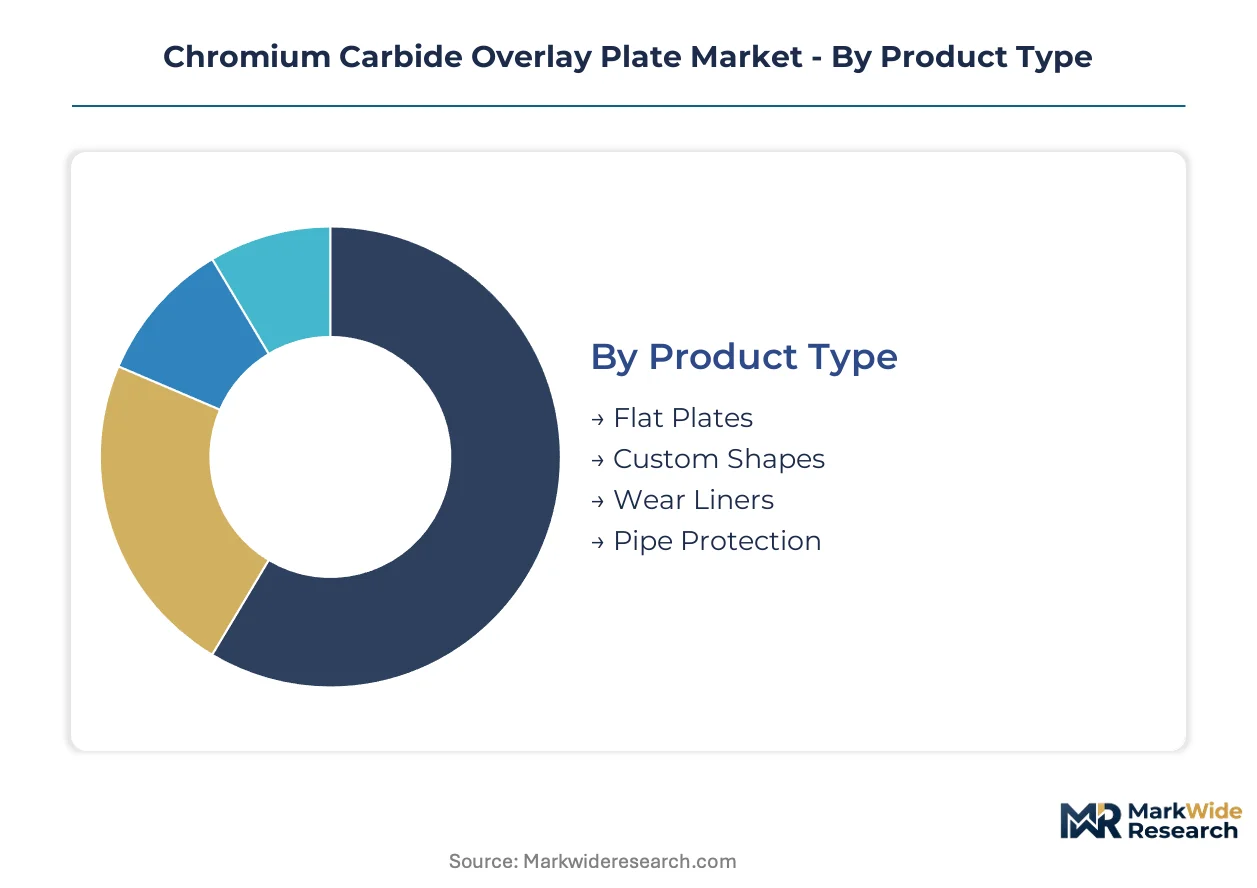
Overlay plate procurement patterns diverge sharply across product formats and end-use environments. Material handling severity and refurbishment cycle timing determine specification priorities for mining operators versus steel manufacturers.
Product Type:
Equipment geometry and installation labor costs differentiate buyer preferences across fabrication formats.
- Flat Plates:Standardized dimensional formats enable rapid field cutting and welding during chute and hopper refurbishment. Australian Pilbara iron ore operators specify flat plates for shovel bucket liner replacement cycles driven by abrasive ore throughput volumes.
- Custom Shapes:Complex geometries are engineered for retrofit compatibility with existing crusher housings and transfer points. Brazilian Carajás mining complex procurement increasingly mandates pre-fabricated shapes to compress installation downtime during scheduled maintenance windows.
- Wear Liners:Modular bolt-on systems dominate truck bed and bucket applications where rapid replacement preserves fleet utilization rates.
- Pipe Protection:Cylindrical and elbow configurations protect slurry pipeline infrastructure from particle erosion in tailings transport systems.
Flat plates lead volumes today; custom shapes are gaining share fastest.
End User:
Operational intensity and abrasive exposure severity separate specification requirements across industrial sectors.
- Mining:Open-pit iron ore and copper operations generate concentrated demand for extreme abrasion resistance in bulk-material handling equipment. Western Australia's Pilbara district and Brazil's Carajás complex anchor procurement volumes through fleet refurbishment programs.
- Steel Manufacturing:Sinter plant chutes and blast furnace charge buckets require thermal cycling resistance alongside abrasion protection. US EPA particulate emissions enforcement is tightening surface durability specifications for dust suppression compliance.
- Construction:Aggregate processing and concrete recycling applications drive seasonal demand patterns tied to infrastructure project cycles.
- Oil & Gas:Tar sands extraction and hydraulic fracturing sand handling create niche demand for pipe protection and separator vessel linings.
Mining commands the dominant revenue share; steel manufacturing is expanding most quickly on regulatory-driven specification upgrades.
Material Grade:
Base metal chemistry governs weldability, impact resistance, and cost positioning for overlay deposition.
- High Carbon Steel:Base plates with elevated carbon content deliver hardness compatibility with chromium carbide overlay layers. Mining operators in high-impact environments specify this grade for shovel bucket and truck bed applications where deformation resistance matters.
- Low Alloy Steel:Controlled manganese and molybdenum additions improve toughness in sub-zero operating conditions. Canadian oil sands and Russian mining operations prioritize this specification for winter operational reliability.
- Stainless Steel:Corrosion-resistant base metals serve chemical processing and marine material handling where moisture exposure accelerates substrate deterioration.
- Others:Specialized formulations including quenched and tempered grades address niche ballistic and extreme impact applications.
High carbon steel dominates current procurement; low alloy steel is climbing the fastest on cold-climate mining expansion.
Thickness:
Service life targets and equipment weight constraints shape dimensional selection for specific wear applications.
- 10mm:Intermediate thickness balances extended service intervals against structural load limits. Standard specification for secondary crusher feed chutes where moderate abrasion combines with impact loading from falling ore.
- 12mm:Maximum thickness category delivers multi-year service life in primary gyratory crusher feed openings and severe-duty truck bed floors. Premium pricing reflects extended fabrication time and elevated ferrochrome consumption.
- 6mm:Reduced weight enables high-wear-area patching and curved surface applications where thicker deposits would constrain forming.
- 4mm:Thin-profile overlays serve low-clearance retrofit situations and preview liner systems for wear monitoring integration.
10mm thickness leads current volume; 12mm is expanding most rapidly on premium service life contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified welders for submerged arc chromium carbide deposition concentrate in Western Australia's mining districts, Germany's steel service centers, and Brazil's Pará state fabrication corridors.
Australia
Rio Tinto and BHP consolidate vendor panels to three certified fabricators per wear category across the Pilbara iron ore district. MSHA-aligned dust suppression standards from the country's workplace safety regulator tighten surface durability specifications for bulk-material handling equipment. Perth-based fabrication shops face 12-16 week ASTM wear-test backlogs as shovel bucket refurbishment cycles accelerate.
Brazil
Vale's Carajás complex expansion drives localized overlay plate demand for truck bed and crusher liner replacement programs. ANVISA workplace exposure frameworks govern hexavalent chromium limits during welding fabrication in Pará state service centers. São Luís fabrication corridors attract investment from international overlay plate specialists seeking proximity to iron ore export infrastructure.
United States
Pennsylvania and Minnesota steel manufacturers qualify overlay plates through third-party emissions testing before facility installation under EPA particulate frameworks. OSHA and MSHA dual compliance requirements compress supplier qualification timelines for underground mining operations. Pittsburgh-area steel service centers retrofit deposition booths to capture premium pricing from certified product lines.
Germany
REACH hexavalent chromium restrictions push Ruhr Valley fabrication facilities toward controlled-atmosphere submerged arc welding upgrades. ECHA substance documentation requirements extend procurement qualification periods for overlay plate imports from non-EU suppliers. Duisburg steel service centers anchor premium product lines where certification documentation commands price premiums over conventional open-arc deposition.
China
Domestic mining operators in Shanxi and Inner Mongolia drive volume demand for standardized flat-plate formats in coal processing infrastructure. GB standards for wear-resistant materials align with ISO hardness certification schemes for export qualification to Australian and Brazilian markets. Zhengzhou-based machinery clusters supply intermediate-thickness overlay plates for secondary crusher feed chute applications.
Chromium Carbide Overlay Plate Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the chromium carbide overlay plate market. ArcelorMittal S.A. leverages captive steelmaking capacity to secure raw material flows, while Kennametal Inc. anchors premium positioning through cemented-carbide expertise. Three archetypes dominate: vertically integrated steelmakers with backward integration into overlay production, specialized fabrication houses with rapid custom-shape turnaround capabilities, and diversified hard materials companies with cross-sector technology transfer. Competitive moves concentrate on long-term supply agreement capture with mining operators and controlled-atmosphere deposition process certification for European market access.
Among diversified materials conglomerates, Kennametal Inc. and Sandvik AB occupy positions where cemented-carbide expertise transfers into extreme abrasion product positioning. ArcelorMittal S.A. exemplifies the steelmaker-integrated archetype through upstream control over base plate supply chains. JADCO Manufacturing Inc. sits within the specialized fabrication tier where custom geometry capabilities differentiate against standardized flat-plate competitors. SSAB AB and Voestalpine AG represent European steel service center models adapting to REACH compliance through process retrofit investments. Sinosteel Corporation Limited anchors Chinese supply into Australian and Brazilian mining procurement frameworks.
| Leading Market Players |
|---|
| Kennametal Inc. |
| JADCO Manufacturing Inc. |
| ArcelorMittal S.A. |
| Sinosteel Corporation Limited |
| Foothills Steel |
| SSAB AB |
| Voestalpine AG |
| Carpenter Technology Corporation |
| Sandvik AB |
| Others |
Pricing and Supply Chain Analysis
Long-term supply agreements between Australian and Brazilian mining operators are compressing spot-market liquidity and forcing suppliers toward dedicated fabrication capacity commitments that elevate fixed-cost absorption and reshape contract pricing structures.
Pricing Analysis
Capacity additions in Germany and Brazil are reshaping price floors for REACH-certified overlay plate production. Three-tier pricing structure across premium, standard, and economy levels separates controlled-atmosphere deposition from open-arc fabrication from unqualified imports. Price differentiation hinges on ASTM wear-test certification status and volume commitment scale. Cost compression in the economy tier is intensifying because South African ferrochrome supply disruptions feed raw material volatility. Steel manufacturers in Pennsylvania exhibit lowest price sensitivity; spot-market buyers in Chinese coal processing show highest.
Supply Chain Analysis
Domestic-content mandates in Brazil's Pará state and Western Australia's Pilbara district are reshaping sourcing patterns toward localized fabrication corridors. Supply concentrates in South Africa for ferrochrome feedstock, China for base steel plate, and Germany for controlled-atmosphere welding equipment. Raw material flows draw from chromium ore deposits, mild steel hot-rolled coil, and welding consumables. Single-source vulnerability runs through South African electricity-dependent ferrochrome smelters. Distribution runs through steel service centers with certified deposition booths and direct-to-mine logistics contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in premium-tier certification investments and submerged arc welding automation that compresses fabrication lead times and elevates throughput per qualified welder.
For Market Incumbents: Anticipate tungsten carbide substitution threats in extreme abrasion applications by anchoring premium positioning through controlled-atmosphere process certification and ASTM wear-test documentation. Backward integration into captive ferrochrome sourcing hedges against South African supply disruptions. Defend long-term supply agreement capture with dedicated fabrication capacity commitments in Pilbara and Carajás corridors. For New Entrants and Emerging Players: Digital wear monitoring integration offers a channel route around incumbent fabrication relationships through outcome-based service contracts with predictive maintenance bundling. White-space targets include sensor-equipped liner systems for Australian shovel bucket fleets and rapid-custom-shape turnaround for Brazilian crusher retrofit programs. Target MSHA-aligned specification upgrades in US underground mining as the most penetrable compliance-driven segment. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized fabrication houses possessing rapid custom-geometry capabilities and existing ASTM certification infrastructure. Long-term viability over a multi-year horizon favors suppliers with demonstrated REACH compliance and mining-operator framework agreement tenure. Watch for ferrochrome price stabilization signals as inflection indicators for margin recovery in the premium tier.| Strategic Initiative | Industry Significance |
|---|---|
| Controlled-Atmosphere Welding Upgrade | REACH compliance in Duisburg and Ruhr Valley secures European market access against open-arc competitors. |
| Long-Term Supply Agreement | Rio Tinto and BHP vendor panel consolidation in Pilbara locks out spot-market rivals from volume commitments. |
| Digital Wear Monitoring Integration | Sensor-equipped liner systems enable predictive maintenance bundling with Australian mining operators. |
| Backward Integration into Ferrochrome | Captive raw material flows hedge ArcelorMittal and integrated steelmakers against South African electricity volatility. |
| Custom-Shape Fabrication Capacity | Rapid turnaround capabilities capture Brazilian Carajás expansion demand for retrofit-compatible crusher liners. |
Research Methodology
Direct dialogue with overlay plate fabrication plant managers, mining procurement leads at Rio Tinto and Vale, steel service center technical directors, and MSHA compliance officers grounded qualitative insights. Secondary validation drew from EPA emissions enforcement records, REACH substance restriction documentation, ASTM wear-test protocol publications, and ferrochrome trade flow data. Bottom-up and top-down triangulation cross-checked fabrication capacity estimates against mining fleet refurbishment cycle timing.
Bottom-up modeling built from individual product segment volume assumptions across flat plates, custom shapes, wear liners, and pipe protection formats. Top-down constraints applied macro-level mining capital expenditure patterns and steel manufacturing facility upgrade cycles. Segmentation dimensions included product geometry complexity, end-use abrasion severity, material grade chemistry, and overlay thickness specifications. CAGRs derived from weighted average of historical procurement trend extrapolation and regulatory-driven replacement cycle acceleration. Ferrochrome price volatility scenarios and REACH compliance timeline assumptions shaped sensitivity ranges.
The model assumes a particular technology adoption path for submerged arc welding automation; alternative pathways for laser cladding deposition would alter the outlook for lead time compression and custom-geometry economics. Forecasts reflect assumptions about MSHA dust standard enforcement intensity and Brazilian mining expansion cadence. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Alloys
Welding Alloys Market
Advanced Alloys
North America Braze Alloys Market
Advanced Alloys
Middle East and Africa Aluminum Casting Market
Advanced Alloys
Cobalt Alloy Powder Market
Advanced Alloys
Titanium Alloys Market
Advanced Alloys
Battery Alloys Market
Advanced Alloys
Automotive Aluminum Alloy (OE) Market
Advanced Alloys
Chromium Carbide Market
Advanced Alloys
Lithium Nitride Market
Advanced Alloys
Tantalum Carbide Market
Advanced Alloys
High Temperature Alloys Market
Advanced Alloys
Nickel Boride Alloy Market
Advanced Alloys
Medium Entropy Alloys Market
Advanced Alloys
Global Quartz Countertops Market
Advanced Alloys
Tungsten Titanium Carbide Market
Advanced Alloys
Iron Gallium Alloy (Galfenol) Market