
 Blue-Green Algae Market | 2026-2036
Blue-Green Algae Market Size, Share, and Industry Trends Forecast 2026-2036
Blue-Green Algae Market Insights
The split between pharmaceutical-grade phycocyanin extracts and bulk spirulina powder for animal feed is hardening as buyers demand certificate-of-analysis documentation at diverging price points. Algenol leverages its closed photobioreactor systems to sustain premium positioning in high-purity markets. Global Algae anchors commodity volume through open-pond operations in North American climates. Algaenergy S.A. differentiates via integrated cultivation-to-extraction capabilities across Iberian facilities.
Blue-green algae denotes oxygenic photosynthetic prokaryotes—primarily cyanobacteria such as Arthrospira platensis and Aphanizomenon flos-aquae—cultivated in open raceways or closed tubular photobioreactors at controlled pH and light intensity, then harvested for protein content exceeding 60% dry weight, phycobiliprotein pigments, or omega-3 fatty acids for human and animal nutrition. Spirulina dominates current tonnage within the product type dimension while chlorella captures accelerating demand from vegan protein formulators seeking higher nucleic acid profiles. The nutraceuticals application segment pools the densest margins as finished brands command shelf-price premiums for organic-certified and broken-cell variants.
FDA dietary supplement cGMP rules and EU Novel Food catalog listings shape market access timelines for new cyanobacterial strains entering commercial channels. EFSA health claim evaluations further filter which bioactive statements survive regulatory scrutiny across member states. Stakeholders must monitor evolving heavy-metal testing protocols and carbon-accounting requirements that will determine which cultivation geographies retain cost-competitive supply positions.
Market Dynamics
The divergence between pharmaceutical-grade phycocyanin extraction and commodity spirulina cultivation is forcing capital allocation decisions across the value chain, as certification requirements and margin structures harden into distinct operational models.
Growth Catalysts
- EU Novel Food catalog expansion:EFSA approvals for new cyanobacterial strains accelerate commercialization timelines for Nordic supplement brands seeking differentiated positioning in functional foods.
- Closed photobioreactor diffusion:Controlled-environment cultivation systems reduce heavy-metal contamination risks, enabling compliance with FDA dietary supplement cGMP rules for premium nutraceutical applications.
- California cultivation clustering:Coastal photobioreactor facilities concentrate technical expertise and carbon-accounting infrastructure, attracting procurement from US-based organic-certified formulators.
Market Restraints
- Input cost volatility:Nitrogen and phosphorus fertilizer prices fluctuate with agricultural commodity cycles, squeezing margins for open-pond operators dependent on external nutrient sourcing.
- Supply concentration risk:Danish photobioreactor facilities control a disproportionate share of EU pharmaceutical-grade biomass, creating single-point vulnerabilities for Nordic supplement brands.
- Technical limitation:Broken-cell processing for chlorella bioavailability requires energy-intensive mechanical disruption, limiting scale economics against intact-cell spirulina alternatives.
Strategic Opportunities
- Underpenetrated geography:Iberian Peninsula cultivation sites offer year-round solar irradiance advantages for producers serving EU southern markets currently supplied by northern imports.
- Regulatory tailwind:EU Green Deal carbon-accounting requirements favor domestic European biomass over Asian imports, rewarding facilities with verified low-carbon cultivation protocols.
- Technology convergence:Integration of AI-driven light-optimization algorithms with closed photobioreactor design promises yield improvements for high-purity phycocyanin extraction.
Industry Challenges
- Certification timeline compression:FDA dietary supplement labeling audits and EU heavy-metal retesting protocols extend batch-release cycles, straining working capital for mid-scale processors.
- Talent scarcity in phycobiliprotein chemistry:Specialized extraction expertise concentrates in German and Danish research clusters, limiting expansion capacity for facilities in emerging cultivation regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blue-Green Algae Market |
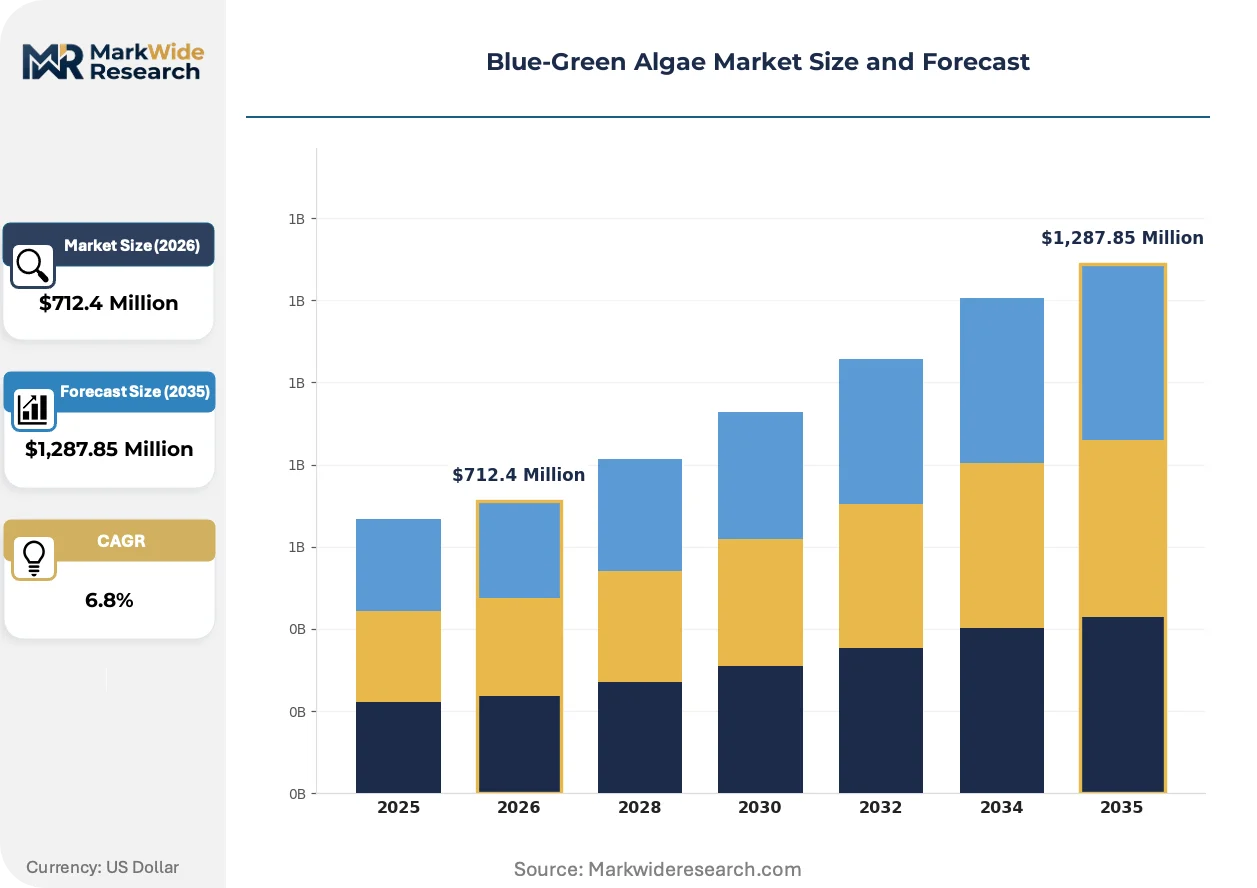
| Market Size in 2026 | $712.4 Million |
| Market Size in 2035 | $1,287.85 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spirulina, Chlorella, Aphanizomenon, Arthrospira Application: Food & Beverages, Nutraceuticals, Pharmaceuticals, Cosmetics End User: Agriculture, Health & Wellness, Research Institutions, Aquaculture Form: Powder, Tablets, Liquid, Flakes |
| Companies Covered | Algenol, AlGIX LLC, Cyamonia Bio, Algaenergy S.A., AlgEnerg Pvt Ltd, ALGAE Biotecnologia, Aurora Algae, Global Algae, Pond Technologies Holdings Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blue-Green Algae Market Trends and Innovations
Automation and sensor integration are compressing the gap between laboratory cultivation protocols and industrial-scale photobioreactor operations, reshaping how producers balance purity against throughput.
Closed tubular photobioreactor systems with real-time dissolved-oxygen monitoring are absorbing capital investment from open-pond operators seeking FDA pharmaceutical-grade compliance. Nutraceutical formulators in Germany and California specify these systems for organic-certified spirulina procurement. The technology is absorbing market share from raceway producers unable to document heavy-metal thresholds below regulatory minimums.
EFSA health claim evaluation protocols for cyanobacterial bioactives are tightening evidentiary standards for protein and antioxidant marketing statements. Finished supplement brands now commission clinical trials before launch, extending product development timelines. Nordic and German markets exhibit the most pronounced compliance response, with reformulation toward generic nutritional labeling.
Direct procurement contracts between Danish photobioreactor facilities and US supplement distributors are shortening traditional ingredient broker channels. Large formulators in California and New York bypass wholesale importers to secure certificate-of-analysis documentation and traceability. This pattern concentrates purchasing power among coastal cultivation clusters with established carbon-accounting protocols.
Blue-Green Algae Market Segmentation
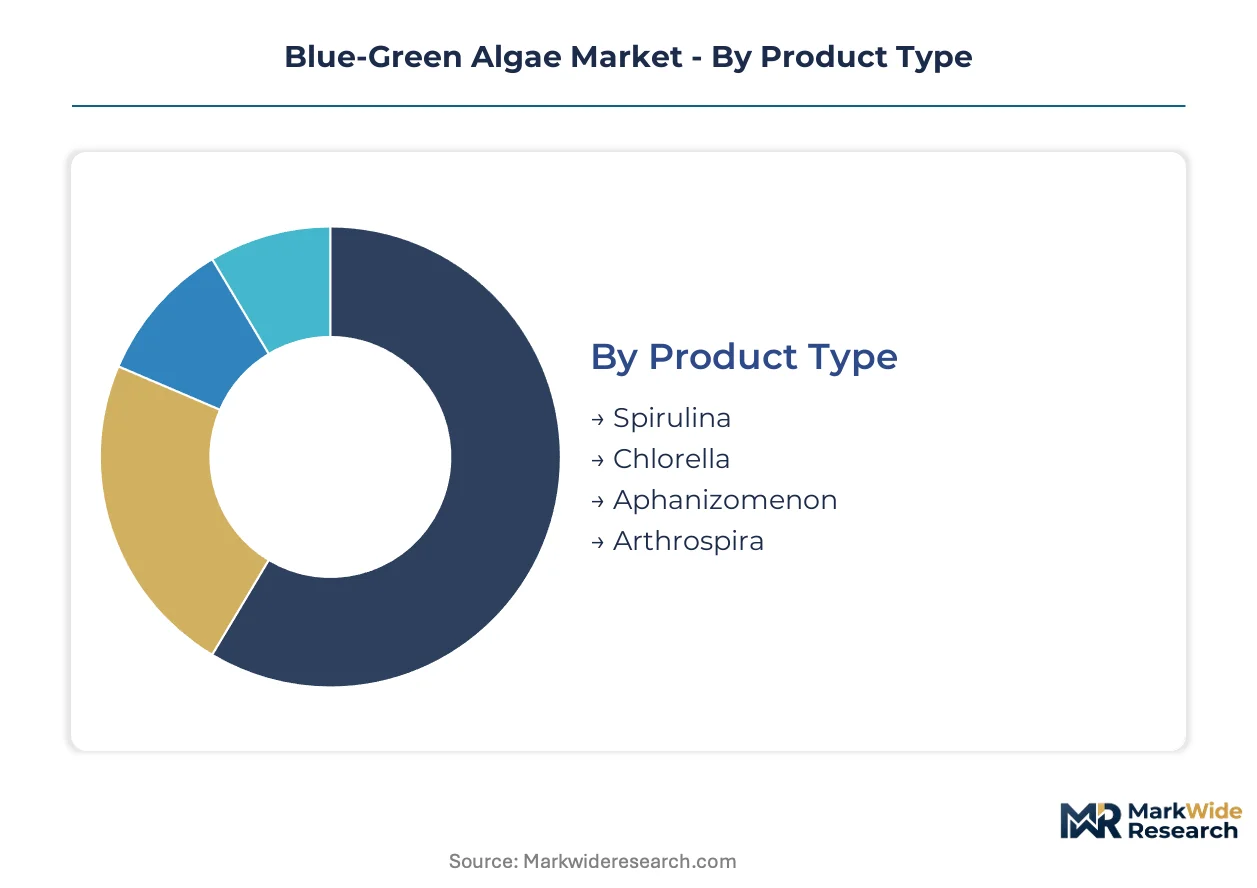
Blue-green algae producers face divergent capital requirements across product types, applications, and processing formats. Segmentation reveals where photobioreactor investments yield premium returns versus where open-pond scale economics dominate procurement decisions.
Product Type:
Capital intensity peaks with pharmaceutical-grade phycocyanin extraction facilities, while commodity protein powders absorb lower upfront costs at higher volume throughput.
- Spirulina:Arthrospira platensis biomass exceeds 60% protein dry weight with established broken-cell processing infrastructure. Danish photobioreactor facilities and California coastal clusters supply Nordic and US organic-certified formulators seeking FDA cGMP compliance documentation.
- Chlorella:Higher nucleic acid profiles and intact-cell walls demand energy-intensive mechanical disruption for bioavailability. Vegan protein formulators in Germany specify this strain despite processing cost penalties.
- Aphanizomenon:Wild-harvested Klamath Lake biomass serves niche nutraceutical channels with distinct mineral composition profiles.
- Arthrospira:Taxonomic synonym for commercial spirulina strains, relevant for EU Novel Food catalog regulatory filings.
Most installed capacity flows through Spirulina. Expansion is steepest in Chlorella.
Application:
Margin structures separate pharmaceutical extraction from bulk commodity supply, with certification thresholds determining facility investment recovery timelines.
- Nutraceuticals:Densest margin pool where finished brands command shelf-price premiums for organic-certified and broken-cell variants. EFSA health claim evaluations filter which bioactive statements survive regulatory scrutiny across EU member states.
- Food & Beverages:Functional food formulators in Germany and the United States expand procurement of powders for protein fortification applications. EU Novel Food regulations tighten purity thresholds for cyanobacterial biomass entering commercial channels.
- Pharmaceuticals:Phycocyanin extracts for therapeutic applications require certificate-of-analysis documentation at diverging price points from commodity grades.
- Cosmetics:Pigment and antioxidant applications leverage phycobiliprotein properties for topical formulation markets.
Revenue concentrates in Nutraceuticals. Food & Beverages is gaining share fastest.
End User:
Procurement sophistication varies from institutional research specifications to agricultural commodity purchasing with minimal documentation requirements.
- Health & Wellness:Direct-to-consumer supplement brands in California and New York bypass wholesale importers to secure traceability documentation from Danish and Iberian facilities.
- Agriculture:Animal feed applications anchor volume demand for bulk spirulina powder with lower purity thresholds and price-sensitive procurement.
- Aquaculture:Hatchery nutrition specifications drive demand for specific fatty acid profiles and particle size distributions.
- Research Institutions:Clinical trial material requirements and strain development contracts support specialized cultivation facilities.
Health & Wellness commands premium pricing. Agriculture absorbs the greatest tonnage.
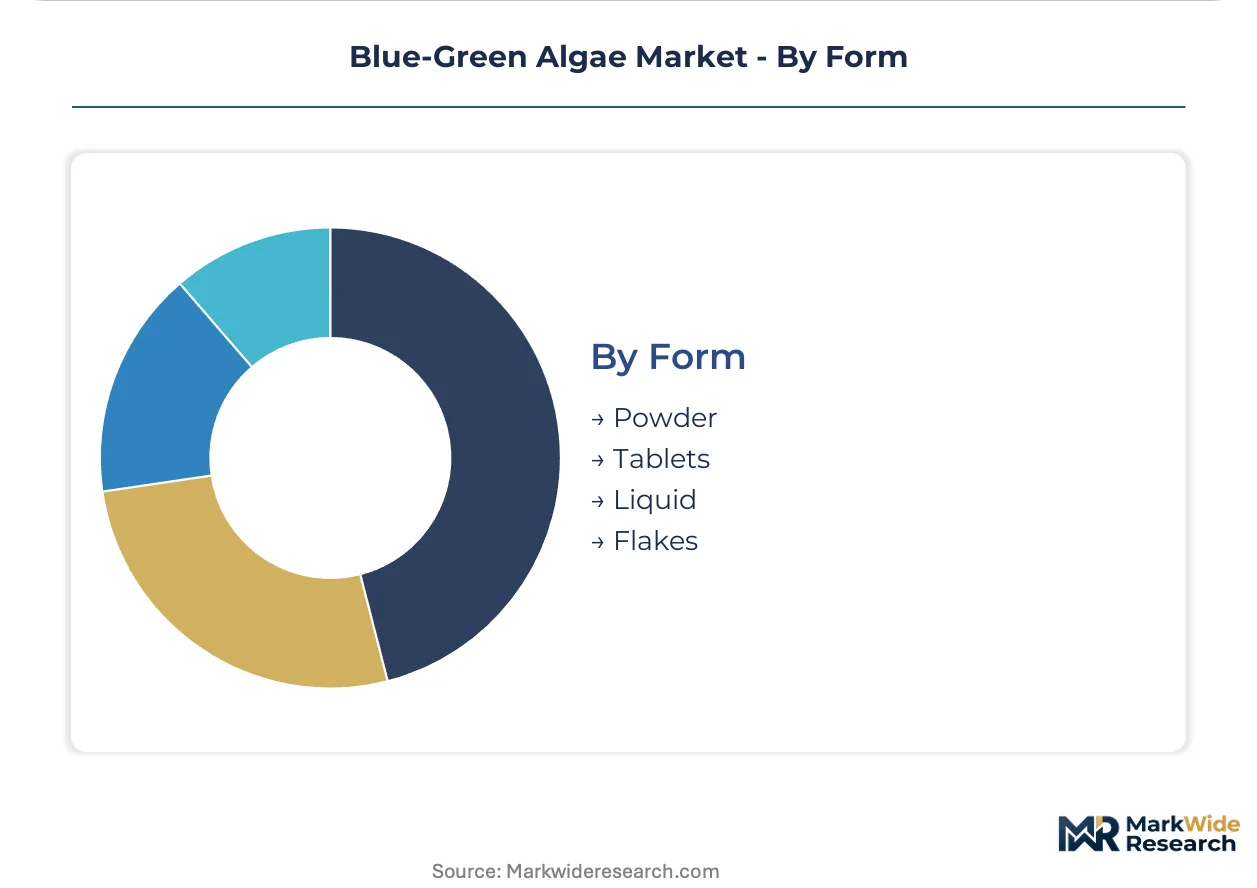
Form:
Processing intensity and packaging requirements create tiered cost structures from raw biomass to finished consumer units.
- Powder:Bulk ingredient standard for nutraceutical formulators and food manufacturers with in-house encapsulation capabilities. Coastal California clusters specialize in organic-certified powder supply.
- Tablets:Compressed delivery formats require additional excipient and tableting equipment investment, capturing value-add margin from finished supplement brands.
- Liquid:Extract and suspension formats for functional beverage applications with shorter shelf-life constraints and cold-chain distribution requirements.
- Flakes:Specialty food ingredient format for direct consumption and culinary applications with distinct texture and dissolution properties.
Powder moves the greatest volume. Tablets capture the highest per-unit margin.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands premium nutraceutical procurement volumes while the United States anchors open-pond commodity scale, revealing divergent cultivation economics across Atlantic markets.
United States
California coastal clusters concentrate photobioreactor expertise for organic-certified spirulina supply to domestic supplement brands. FDA dietary supplement cGMP rules tighten batch-release documentation requirements, extending working capital cycles for mid-scale processors. Open-pond operations in southwestern states anchor animal feed volume through lower-cost biomass production.
Germany
Vegan protein formulators in Berlin and Hamburg drive accelerating chlorella demand despite energy-intensive broken-cell processing costs. EFSA health claim evaluations filter bioactive marketing statements, forcing reformulation toward generic nutritional labeling. Bavarian research clusters concentrate specialized phycobiliprotein chemistry expertise that limits expansion capacity elsewhere.
Denmark
Nordic supplement brands source pharmaceutical-grade biomass from domestic photobioreactor facilities with established carbon-accounting protocols. EU Green Deal requirements favor verified low-carbon cultivation, rewarding facilities with documented sustainability credentials. Copenhagen-area technical infrastructure attracts direct procurement contracts from US distributors seeking traceability documentation.
Spain
Iberian Peninsula cultivation sites exploit year-round solar irradiance advantages for producers serving EU southern markets. Algaenergy S.A. leverages integrated cultivation-to-extraction capabilities across regional facilities. EU Novel Food catalog expansion accelerates commercialization timelines for new cyanobacterial strains entering Spanish processing channels.
China
Domestic spirulina production serves both export commodity markets and growing domestic nutraceutical consumption. SAMR dietary supplement regulations tighten purity thresholds for biomass entering commercial channels. Shandong and Yunnan provinces concentrate open-pond cultivation infrastructure with cost advantages in nitrogen and phosphorus sourcing.
Blue-Green Algae Market Competitive Landscape
Top-tier vendors anchor closed-system pharmaceutical-grade extraction, while mid-scale operators compete on open-pond commodity volume and regional certification compliance. The vendor base stratifies across three strategic archetypes: integrated cultivation-to-extraction specialists, pure-play photobioreactor technology licensors, and commodity-scale open-pond producers. Dominant competitive moves include capacity expansion in coastal California and Danish clusters, plus technology licensing agreements that transfer closed-system designs to emerging cultivation regions.
Within the integrated specialist tier, Algaenergy S.A. exemplifies European cultivation-to-extraction positioning, while Global Algae represents North American open-pond scale economics. Algenol occupies a position on the technology-licensor vector, reflecting closed photobioreactor system expertise. These three anchors illustrate how geographic clustering and system architecture choices determine competitive positioning across purity-graded market segments.
| Leading Market Players |
|---|
| Algenol |
| AlGIX LLC |
| Cyamonia Bio |
| Algaenergy S.A. |
| AlgEnerg Pvt Ltd |
| ALGAE Biotecnologia |
| Aurora Algae |
| Global Algae |
| Pond Technologies Holdings Inc. |
| Others |
Pricing and Supply Chain Analysis
Phycobiliprotein chemistry expertise clustering in Bavarian and Copenhagen research corridors feeds labor-cost differentials that widen spreads between pharmaceutical-grade phycocyanin and commodity spirulina powder. Danish photobioreactor facilities command premium positioning through FDA cGMP documentation capabilities while open-pond operators in southwestern US states compete on nitrogen-sourced cost minimization for animal feed biomass.
Pricing Analysis
Certificate-of-analysis bundling versus unbundled commodity procurement separates pricing architectures across purity grades. Three-tier pricing structure across pharmaceutical extraction, organic-certified nutraceutical, and bulk feed-grade biomass reflects certification investment recovery timelines. Pricing pressure stems from nitrogen and phosphorus fertilizer volatility squeezing open-pond margins. Animal feed buyers exhibit highest price sensitivity while Nordic supplement brands absorb premiums for carbon-accounted Danish biomass.
Supply Chain Analysis
EU Novel Food catalog qualification and FDA dietary supplement cGMP certification gate market access timelines and batch-release cycles. Supply concentrates in Denmark, California, and Spain for premium biomass with China and southwestern US states anchoring commodity volume. Nitrogen fertilizers, phosphorus inputs, and photobioreactor glass tubing constitute critical dependencies. Single-source vulnerability runs through Danish facilities supplying Nordic brands. Distribution runs through direct procurement contracts shortening traditional ingredient broker channels for traceability documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Blue-Green Algae Market functions as a regulatory compounder where EU Green Deal carbon-accounting requirements and FDA cGMP documentation mandates accelerate demand for verified low-carbon cultivation protocols and heavy-metal compliance infrastructure.
For Market Incumbents: Hedge against Asian import displacement by deepening backward integration into nitrogen sourcing and expanding photobioreactor capacity in California coastal clusters. Certification investment in EU Novel Food catalog pre-approval for emerging cyanobacterial strains defends against Nordic supplement brand supplier switches. Carbon-accounting protocol documentation protects margin position as EU Green Deal enforcement tightens. For New Entrants and Emerging Players: Launch via direct-to-brand distribution bypassing wholesale importers to capture traceability premium from California and New York formulators. Iberian Peninsula cultivation sites offer white-space positioning for EU southern markets currently supplied by northern imports. AI-driven light-optimization licensing agreements provide technology-leverage entry without capital-intensive facility construction. For Investors and Strategic Acquirers: Nutraceutical formulators with established brand equity are the most active acquirer in this space, seeking captive spirulina and chlorella supply for organic-certified product lines. Five-to-ten year viability hinges on regulatory compliance infrastructure rather than cultivation scale alone. The signal to watch is EFSA health claim evaluation outcomes for protein and antioxidant marketing statements, which determine finished-brand pricing power and reformulation requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Closed Photobioreactor Capacity Expansion | Danish and California facilities absorb investment to meet FDA cGMP pharmaceutical-grade documentation requirements. |
| Integrated Cultivation-to-Extraction Buildout | Iberian sites exploit solar irradiance advantages for EU Novel Food catalog-compliant processing infrastructure. |
| Carbon-Accounting Protocol Certification | EU Green Deal compliance documentation rewards facilities with verified low-carbon biomass cultivation credentials. |
| Direct Procurement Channel Development | US supplement distributors bypass wholesale importers to secure certificate-of-analysis traceability from coastal clusters. |
| AI-Driven Light Optimization Licensing | Technology transfer agreements compress yield gaps between laboratory protocols and industrial photobioreactor operations. |
Research Methodology
Direct dialogue with photobioreactor operations managers, nutraceutical formulators, regulatory affairs specialists at FDA and EFSA, and Nordic supplement brand procurement directors grounded qualitative assessment. Secondary validation drew from FDA dietary supplement cGMP filings, EFSA Novel Food catalog submissions, EU Green Deal implementation guidelines, and customs trade data for cyanobacterial biomass imports. Bottom-up facility capacity modeling triangulated against top-down nutraceutical ingredient demand projections.
Bottom-up segmentation by product type, application, and cultivation system architecture anchored volume and value outputs across the analysis window. Modeled dimensions included pharmaceutical-grade versus commodity purity tiers, open-pond versus closed photobioreactor production systems, and regional regulatory cluster differentiation. CAGRs derived from facility-level capacity expansion announcements correlated with EFSA approval timelines and FDA inspection frequency data.
Several conditions sit outside the modeled scope, including abrupt fertilizer commodity price shocks, unscheduled FDA facility inspection outcomes, and EFSA health claim evaluation reversals. Forecasts reflect assumptions regarding carbon-accounting protocol adoption rates and EU Novel Food catalog expansion timelines. A model refresh is warranted upon material change in EU Green Deal enforcement stringency or FDA dietary supplement labeling audit protocols.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environment & Sustainability
Paper Recycling Market
Environment & Sustainability
Emission Management Market
Environment & Sustainability
Pollution Monitoring Equipment Market
Environment & Sustainability
APAC E-Waste Management Market
Environment & Sustainability
Product Stewardship Market
Environment & Sustainability
Smart Waste Collection Market
Environment & Sustainability
Green Waterproofing Products Market
Environment & Sustainability
Green Mining Market
Environment & Sustainability
Animal Waste Incinerator Market
Environment & Sustainability
Carbon Management System Market
Environment & Sustainability
Atmospheric Water Generator (AWG) Market
Environment & Sustainability
Industrial Solid Waste Management Market
Environment & Sustainability
Global Enhanced Water Market
Environment & Sustainability
Asia-Pacific Green Carbon Market
Environment & Sustainability
Emission Monitoring Systems Market
Environment & Sustainability
Vietnam Waste Management Market