
 Global Eco-Friendly Green Roofs Market | 2026-2036
Global Eco-Friendly Green Roofs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Eco-Friendly Green Roofs Market Analysis
The EU Green Deal is realigning the cost-of-entry calculus for green roof suppliers across European construction markets. ZinCo leverages its pre-vegetated system expertise to dominate commercial project pipelines in German-speaking markets. Sika AG anchors its position through backward integration into waterproofing membranes and growing media chemistry. American Hydrotech competes on extensive vegetative coverage for North American institutional clients.
Eco-friendly green roofs are engineered vegetative systems installed atop building envelopes, typically comprising a root-resistant membrane, drainage layer, engineered soil substrate, and selected plant species designed to manage stormwater, reduce urban heat island effects, and extend roof membrane lifespan. Intensive systems with deeper soil profiles and diverse plantings command premium pricing but require greater structural loading capacity, while modular plug-and-play formats are gaining traction in retrofit applications where speed and minimal disruption matter most. Build-up systems remain the largest installed base across commercial buildings, though pre-vegetated mats represent the fastest-growing installation method for residential and light commercial projects.
Germany's F-Gas Regulation and the EU's Energy Performance of Buildings Directive shape product specifications by mandating thermal performance improvements that green roofs help deliver. The US EPA stormwater management guidelines and Japan's METI building efficiency standards create parallel compliance pathways that expand addressable demand. Stakeholders must monitor how evolving substrate weight standards and biodiversity certification criteria reshape supplier qualification requirements.
Market Dynamics
The EU Green Deal's building energy performance mandates are compressing installation timelines and forcing suppliers to pre-certify complete vegetative systems rather than sell component layers separately.
Growth Catalysts
- Stormwater Mandates:The US EPA's National Pollutant Discharge Elimination System requires commercial properties in Philadelphia, New York, and Washington to retain rainfall on-site. Green roofs satisfy these volume-based targets where underground detention proves infeasible.
- Japan METI Efficiency Standards:Building efficiency codes in Tokyo, Osaka, and Yokohama now credit vegetative envelopes toward cooling load reductions. Developers exploit this pathway to avoid costly mechanical system upgrades.
- Modular Retrofit Formats:Pre-vegetated mat systems cut installation time by seventy percent on existing structures. Property managers in dense German urban cores favor these formats to minimize tenant disruption.
Market Restraints
- Structural Loading Constraints:Intensive systems with soil depths exceeding fifteen centimeters demand reinforced concrete decks. Older commercial buildings in Japan and Germany lack the capacity without expensive structural retrofit.
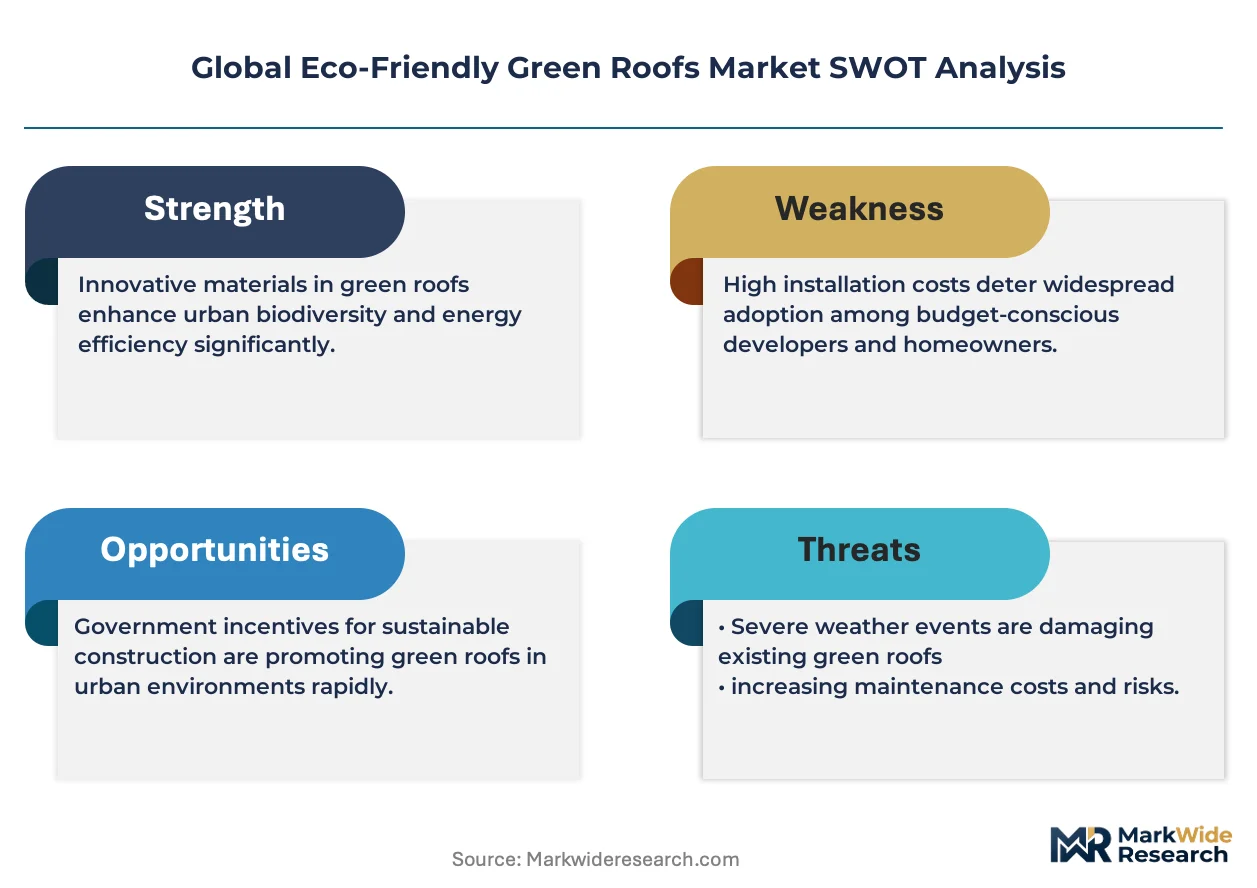
- Waterproofing Membrane Supply Concentration:Three chemical conglomerates control the root-resistant membrane substrate market. This concentration exposes installers to price volatility when polymer feedstock costs fluctuate.
- F-Gas Regulatory Friction:The EU's phasedown of hydrofluorocarbon blowing agents complicates membrane manufacturing. Producers must reformulate insulation layers without sacrificing puncture resistance.
Strategic Opportunities
- Underpenetrated US Secondary Cities:Denver, Portland, and Toronto lack stringent vegetative mandates but face worsening urban heat island effects. Early entrants can shape municipal code development before competitors establish specification relationships.
- Biodiversity Certification Tailwinds:Germany's DIN 18035-1 standard for species-rich extensive systems creates premium pricing tiers. Installers achieving native plant density thresholds command twenty to thirty percent price premiums over conventional sedum monocultures.
- Sensor-Substrate Convergence:Moisture and nutrient monitoring hardware embedded in growing media enables predictive maintenance contracts. Technology suppliers partner with vegetative system installers to capture recurring revenue streams.
Industry Challenges
- Horticultural-Engineering Skill Gap:Successful installation requires fluency in both waterproofing integrity and plant establishment protocols. Training programs in Germany and Japan lag behind installation volume growth.
- Multi-Layer Warranty Complexity:Disputes arise when membrane failures occur beneath established vegetation. Insurers struggle to attribute root intrusion damage versus installation defects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Eco-Friendly Green Roofs Market |
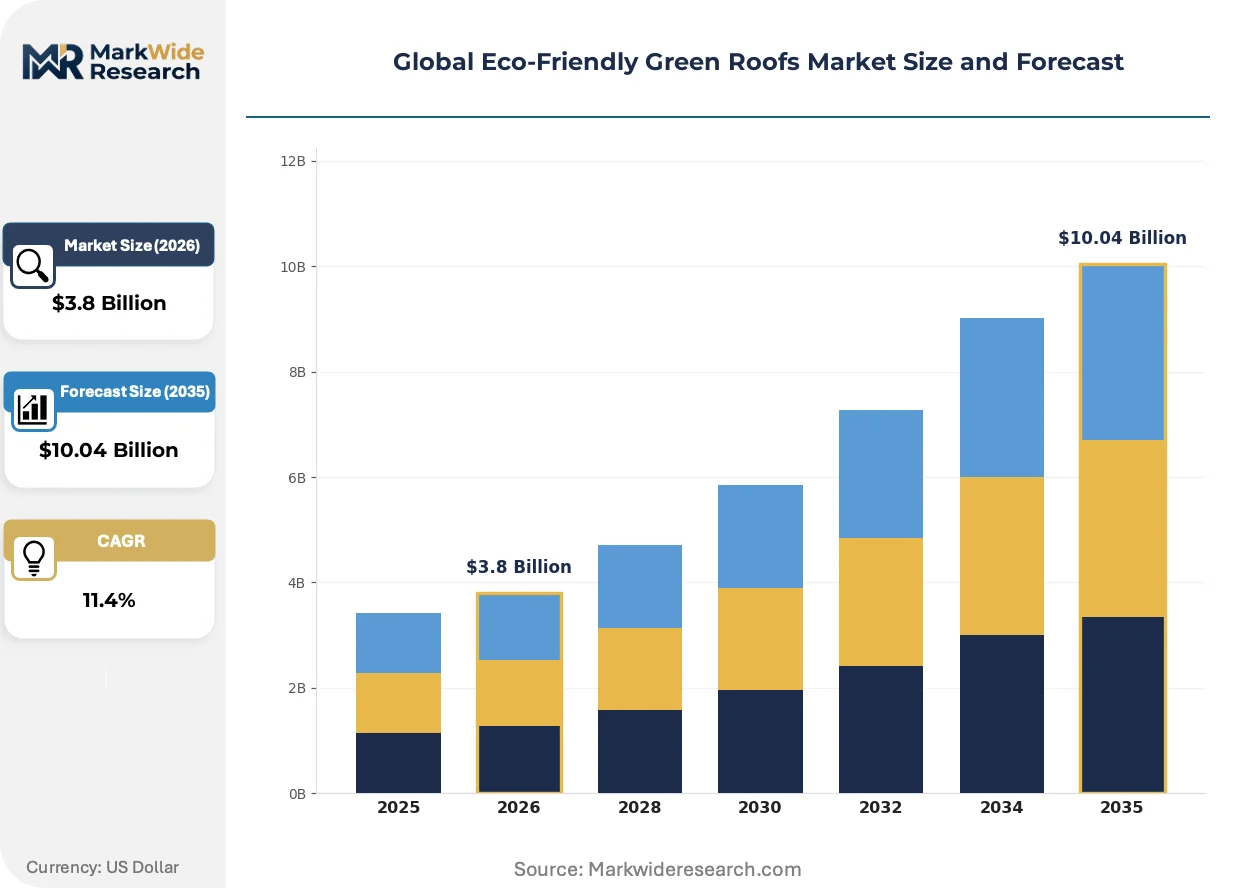
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Vegetative, Modular, Semi-Intensive, Intensive Material: Soil Substrate, Metal, Concrete, Bitumen Application: Commercial Buildings, Residential, Industrial Facilities, Urban Green Spaces Installation Method: Pre-vegetated Systems, Build-Up Systems, Plug & Play Systems, Custom Solutions |
| Companies Covered | Sempergreen, ZinCo, LiveRoof, Optigreen, American Hydrotech, Green Roof Blocks, Sika AG, GAF, Tajima Roofing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Eco-Friendly Green Roofs Market Emerging Trajectories
Vegetative envelope technology is converging with building automation and material science in ways that reshape supplier value propositions and buyer procurement criteria.
Self-healing polymer membranes are unifying waterproofing and root-barrier functions into single-layer systems. German commercial developers specify these materials to eliminate separate membrane installation phases. The technology compresses project timelines from twelve weeks to seven while reducing labor cost exposure.
The EU F-Gas Regulation and Energy Performance of Buildings Directive are tightening thermal conductivity requirements for roof assemblies. Green roof suppliers respond by engineering lighter substrate blends that retain insulation value without adding dead load. Intensive system designers in Stuttgart and Munich now specify these reformulated media to satisfy both structural engineers and energy auditors.
Institutional buyers in the United States are consolidating vegetative envelope procurement under facilities management rather than construction divisions. This shift extends evaluation horizons from first-cost to twenty-year lifecycle performance. University and hospital systems in California and Illinois now require predictive maintenance clauses and performance guarantees in vegetative roof contracts.
Global Eco-Friendly Green Roofs Market Segmentation
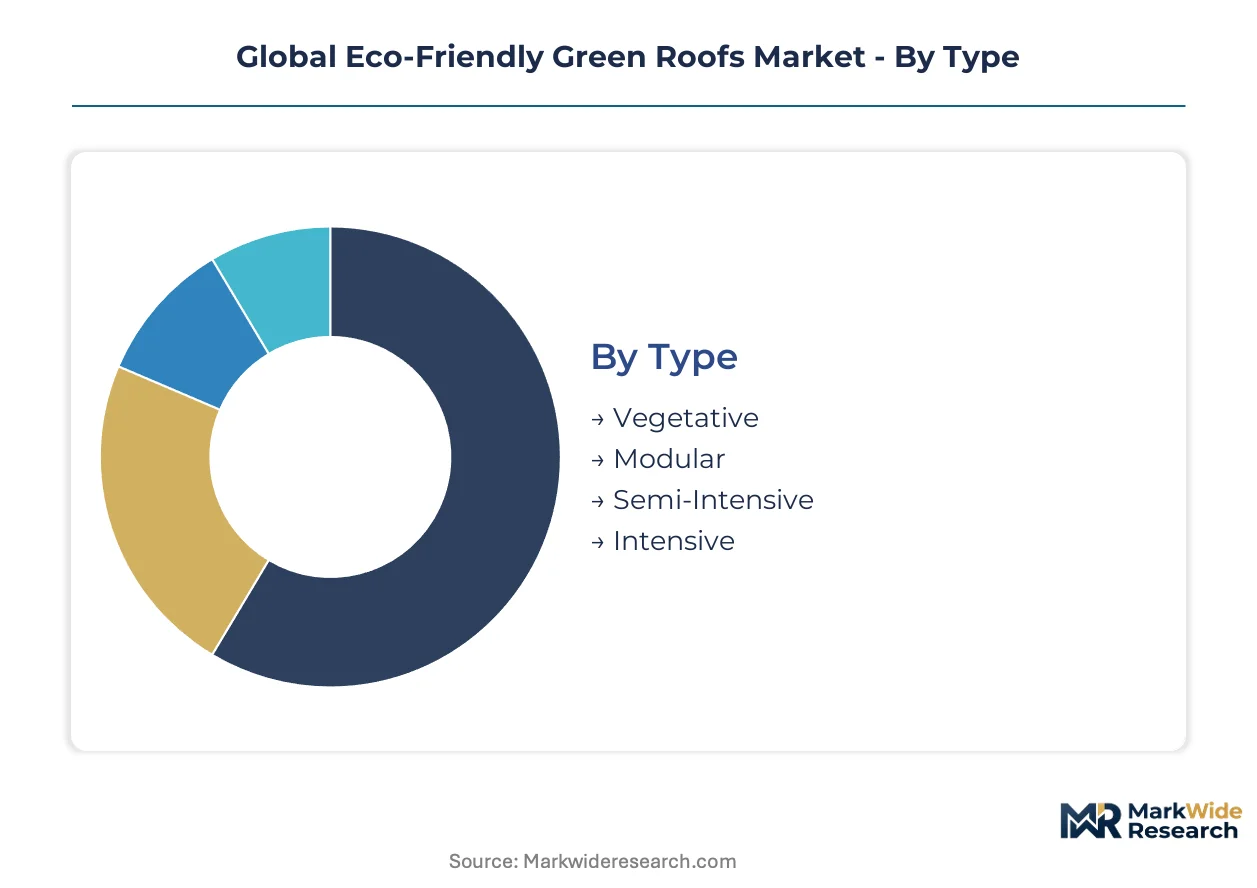
Green roof procurement decisions hinge on structural capacity, regulatory compliance pathways, and lifecycle cost horizons. Understanding how these dimensions fragment demand reveals where suppliers must configure specialized system architectures versus scalable platform approaches.
Type:
Structural loading thresholds and maintenance commitment horizons drive type selection more than upfront cost differentials.
- Vegetative:Lightweight sedum-based systems dominate extensive installations across German commercial retrofits. Municipal stormwater credits in Philadelphia and Washington accelerate specification where structural capacity limits intensive alternatives.
- Intensive:Deep soil profiles exceeding 20 centimeters enable diverse plantings and recreational access. Tokyo developers exploit METI efficiency standards to justify structural reinforcement costs for premium office and hospitality projects.
- Modular:Pre-cultivated trays minimize installation disruption in dense urban cores. Property managers favor rapid deployment without crane access.
- Semi-Intensive:Intermediate profiles balance biodiversity goals with structural constraints. German mid-rise residential projects specify these for terrace amenity spaces.
Volume sits with Vegetative systems; growth tilts toward Modular formats.
Material:
Substrate chemistry and membrane compatibility determine warranty validity and long-term performance guarantees.
- Soil Substrate:Engineered blends of expanded clay, compost, and volcanic rock balance water retention with drainage. German DIN standards mandate specific grain size distributions for extensive systems. Reformulated lightweight variants address F-Gas thermal conductivity requirements without adding dead load.
- Bitumen:Root-resistant modified bitumen membranes anchor waterproofing integrity in build-up systems. Sika AG and competing chemical conglomerates control substrate supply, exposing installers to polymer feedstock volatility.
- Metal:Aluminum and steel drainage components provide structural longevity in intensive systems. Japanese commercial developers specify corrosion-resistant alloys for coastal exposure.
- Concrete:Precast elements form protective curbs and access pathways. Institutional buyers in California require seismic-rated configurations.
Soil Substrate commands installed volume; Bitumen faces reformulation pressure from F-Gas phasedown.
Application:
Regulatory compliance intensity and available incentive structures vary sharply across building use categories.
- Commercial Buildings:Office towers and retail complexes drive specification volume in Germany and Japan. EU Green Deal energy performance mandates compress installation timelines and favor pre-certified complete systems.
- Urban Green Spaces:Municipal parks and plaza roofs expand addressable demand beyond traditional building envelopes. Denver and Portland explore vegetative mandates as heat island mitigation strategies.
- Residential:Multi-family housing in German urban cores adopts modular formats for speed. Single-family penetration remains limited by structural assessment costs.
- Industrial Facilities:Warehouse and manufacturing roofs present large surface areas but face contamination concerns from process emissions.
Commercial Buildings anchor current volume; Urban Green Spaces offer the steepest expansion trajectory as municipalities harden climate adaptation codes.
Installation Method:
Project timeline constraints and existing structural conditions dictate method selection more than system performance differentiation.
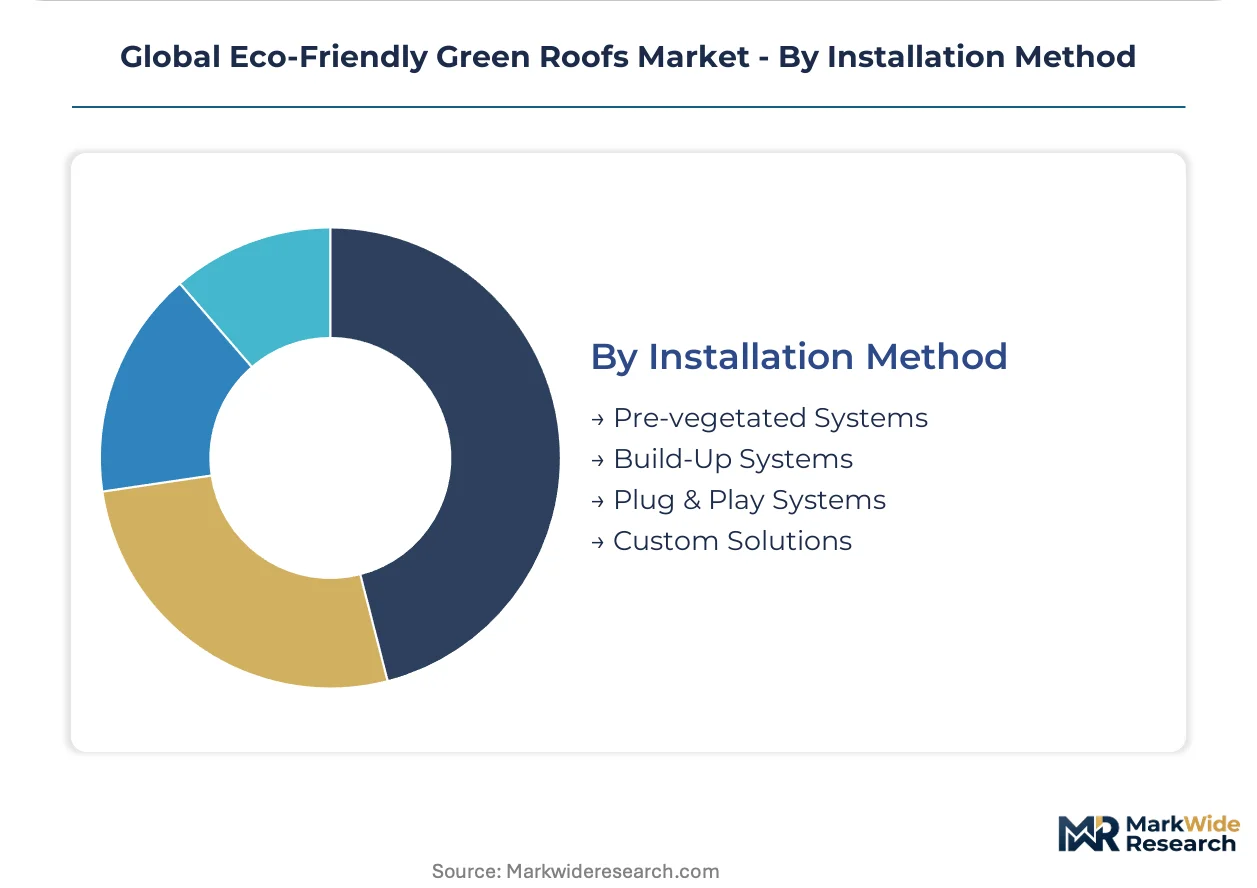
- Pre-vegetated Systems:Factory-cultivated mats arrive site-ready with established plant cover. German property managers specify these for tenant-occupied retrofits where disruption minimization outweighs premium pricing.
- Build-Up Systems:Layer-by-layer installation remains the largest installed base across commercial new construction. Component sourcing flexibility appeals to general contractors with established supplier relationships.
- Plug & Play Systems:Interlocking trays enable rapid deployment without specialized horticultural labor. US institutional buyers favor standardized formats for multi-site portfolio consistency.
- Custom Solutions:Bespoke designs address unique architectural geometries or biodiversity certification requirements. German DIN 18035-1 native plant density thresholds command specialist installation expertise.
Build-Up Systems retain volume dominance; Pre-vegetated Systems gain share fastest where retrofit activity concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German free-economic zones and municipal stormwater credit programs concentrate specification activity across Düsseldorf, Stuttgart, and Berlin. Tokyo's special building efficiency districts accelerate intensive system adoption. Philadelphia and Washington anchor US demand through EPA-mandated retention requirements.
United States
Philadelphia and New York commercial developers exploit EPA stormwater credits to offset underground detention costs. The National Pollutant Discharge Elimination System mandates volume-based retention for properties exceeding defined impervious surface thresholds. Denver and Portland municipalities explore voluntary vegetative envelope incentives as urban heat island effects intensify.
Germany
Stuttgart and Munich intensive system specifications satisfy both EU Green Deal energy performance mandates and F-Gas thermal conductivity requirements. The DIN 18035-1 biodiversity certification standard creates premium pricing tiers for native plant density thresholds. Düsseldorf commercial retrofits favor pre-vegetated mats to minimize tenant disruption in dense urban cores.
Japan
Tokyo and Osaka developers leverage METI building efficiency standards to justify structural reinforcement costs for premium office projects. The cooling load reduction credits enable avoidance of costly mechanical system upgrades. Yokohama commercial towers specify corrosion-resistant drainage alloys for coastal exposure conditions.
Canada
Toronto municipal codes increasingly reference vegetative envelope performance for stormwater management compliance. The city's green roof bylaw expansion creates specification pathways for mid-rise residential and commercial projects. Vancouver developers explore lightweight substrate blends to address seismic loading constraints.
United Kingdom
London commercial developers navigate post-Brexit alignment with EU Green Deal energy performance trajectories. The Greater London Authority's urban greening factor policies accelerate vegetative envelope specification for planning permission. Manchester and Birmingham explore modular retrofit formats for aging commercial stock.
Global Eco-Friendly Green Roofs Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across the vegetative envelope value chain. Chemical conglomerates with captive waterproofing membrane production anchor the substrate supply tier, while horticultural specialists dominate pre-vegetated system cultivation. Three strategic archetypes emerge: integrated membrane-substrate suppliers, modular system assemblers, and cultivation-focused horticultural operators. Competitive intensity concentrates on pre-certification of complete vegetative systems and specification relationships with institutional facilities management divisions.
Within the integrated supplier tier, Sika AG and ZinCo exemplify divergent geographic anchoring strategies. Sika AG occupies a position reflecting Swiss chemical conglomerate origins with backward integration into waterproofing membrane chemistry. ZinCo represents German-speaking market concentration through pre-vegetated system expertise. American Hydrotech sits within the North American institutional specialist archetype, while Sempergreen anchors the horticultural cultivation-focused tier with Dutch propagation capabilities.
| Leading Market Players |
|---|
| Sempergreen |
| ZinCo |
| LiveRoof |
| Optigreen |
| American Hydrotech |
| Green Roof Blocks |
| Sika AG |
| GAF |
| Tajima Roofing |
| Others |
Supply Flow & Price Mechanics
Polymer feedstock indices for ethylene-propylene-diene monomer and modified bitumen resins cascade directly into green roof membrane pricing tiers, compressing margins for installers when chemical conglomerates pass through raw material volatility. Buyers in Germany and Japan face escalating substrate costs as F-Gas reformulation requirements tighten supply for root-resistant barriers.
Pricing Analysis
Short lead-time premiums dominate pricing negotiations, with German property managers paying substantial markups for pre-vegetated mats that compress installation windows in tenant-occupied retrofits. Project-based contracting anchors the market, with price differentiation hinging on biodiversity certification grade under DIN 18035-1 standards and volume scale for multi-site portfolio deployments. Cost compression in standard sedum monocultures is intensifying because modular system assemblers are flooding mid-market segments with plug-and-play alternatives. Municipal stormwater credit eligibility renders institutional buyers least price-sensitive, while residential retrofit clients exhibit acute sensitivity to structural assessment and reinforcement costs.
Supply Chain Analysis
Dual-sourcing mandates from US institutional buyers and Japanese commercial developers require qualification of at least two membrane substrate suppliers, forcing installers to maintain redundant relationships with Sika AG and competing chemical conglomerates. Manufacturing concentrates in Germany, Switzerland, and Japan for waterproofing membranes, while engineered soil substrate production draws from expanded clay quarries in Germany and volcanic rock processors in Japan. Single-source vulnerability persists for root-resistant polymer formulations. Distribution runs through specialized vegetative envelope contractors rather than general building material distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Root-resistant membrane manufacturing capacity is bottlenecked by F-Gas reformulation timelines, propping pricing power for qualified suppliers who have secured regulatory pre-approval for alternative blowing agents.
For Market Incumbents: Cement specification relationships with institutional facilities management divisions before procurement consolidation accelerates. Defend against modular system assemblers by securing exclusive cultivation partnerships with Dutch and German horticultural propagators. Prioritize backward integration into engineered substrate chemistry to capture margin from reformulated lightweight blends. For New Entrants and Emerging Players: Launch via direct contractor partnerships in Denver, Portland, and Toronto before municipal code development hardens. Target biodiversity-certified intensive systems for German mid-rise residential terrace projects, where native plant density thresholds create specialist barriers. Exploit the horticultural-engineering skill gap by offering predictive maintenance subscriptions bundled with sensor-embedded substrates. For Investors and Strategic Acquirers: The window for entry favors cultivation-focused horticultural operators with established DIN 18035-1 certification track records. Long-term viability rests on consolidation of fragmented regional installers into platform-scale service networks. Watch for inflection when sensor-substrate convergence produces recurring revenue multiples that reshape valuation benchmarks.| Strategic Initiative | Industry Significance |
|---|---|
| Pre-Certified System Investment | EU Green Deal compression of installation timelines favors suppliers with complete vegetative system pre-approval. |
| Sensor-Substrate Partnership | Moisture monitoring hardware embedded in growing media enables predictive maintenance revenue capture. |
| Biodiversity Certification Acquisition | DIN 18035-1 native plant density thresholds command twenty to thirty percent price premiums in Germany. |
| Lightweight Substrate R&D | F-Gas thermal conductivity mandates require reformulated media that retains insulation without structural load penalties. |
| Modular Retrofit Format Scale-Up | Pre-vegetated mats cut installation time by seventy percent, dominating dense urban core retrofit demand. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with green roof system installers, waterproofing membrane procurement leads at commercial developers, facilities management directors at university and hospital systems, and horticultural cultivation specialists. Bottom-up triangulation across installation volume data from German FLL and American GRHC associations reconciled with top-down construction spending flows from national statistical agencies.
Data-stream reconciliation between substrate chemistry cost indices, municipal stormwater credit program enrollment figures, and vegetative envelope specification databases shaped the analytical framework across the analysis window. Segmentation dimensions modeled include system type intensity, installation method format, substrate material chemistry, and application building use category. CAGRs derived from regression against regulatory mandate implementation schedules and thermal performance standard tightening trajectories.
Feedstock price volatility, F-Gas regulatory implementation delays, and structural loading assessment cost inflation are the dominant revision risks. Deviation in polymer membrane supply concentration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Green Building Materials
GCC Green Cement Market
Green Building Materials
Green Roof Market
Green Building Materials
North America Green Cement Market
Green Building Materials
China Green Building Materials Market
Green Building Materials
Energy Efficient Window and Door Market
Green Building Materials
Green Building Materials Market
Green Building Materials
Artificial Green Wall Market
Green Building Materials
Sustainable Construction Market
Green Building Materials
North America Green Buildings Market
Green Building Materials
Global Green Walls Market
Green Building Materials
Green Building Market
Green Building Materials
Sustainable and Green Building Materials Market
Green Building Materials
Green Cement and Concrete Market
Green Building Materials
Green Coatings Market
Green Building Materials
Green Rebar Market
Green Building Materials
Green Waterproofing Products Market