
 Green Rebar Market | 2026-2036
Green Rebar Market Size, Share, and Industry Trends Forecast 2026-2036
Green Rebar Market Insights
A capital-intensity divergence between integrated composite manufacturers and regional rebar distributors is rotating competitive advantage toward firms controlling raw resin supply and pultrusion automation. Pultrall Inc. leverages captive glass-fiber roving contracts to stabilize input costs across Quebec and the US Northeast. Hughes Brothers anchors its position through specialized epoxy-coated and fiberglass product lines serving Department of Transportation-qualified projects. Schöck Bauteile GmbH differentiates via precision-engineered thermal-break and corrosion-resistant reinforcement systems for European building codes.
Green rebar denotes reinforcement bars manufactured with reduced embodied carbon, recycled content, or non-corrosive composite matrices—typically glass-fiber-reinforced polymer (GFRP) with vinyl ester or epoxy resin binding, exhibiting tensile strengths of 700–1,200 MPa and zero conductivity. Its primary purpose is to eliminate concrete spalling and structural degradation in environments exposed to de-icing salts, marine atmospheres, or electromagnetic interference. Fiber-Reinforced and Composite material grades command premium positioning where lifecycle cost analysis overrides first-cost procurement, while Steel variants retaining recycled content and electric-arc-furnace origin dominate volume in markets with nascent green building codes. Infrastructure and Bridges applications concentrate the highest specification stringency, with Contractors and Government end users driving qualification protocols that lock out unproven suppliers.
The US Federal Highway Administration, Germany's KBA-adjacent infrastructure certification bodies, and California's Air Resources Board collectively enforce low-carbon procurement thresholds and corrosion-resistance performance standards that determine market access for green rebar suppliers. EPD declarations and ISO 14040-series lifecycle assessments now function as de facto bidding prerequisites across public infrastructure tenders in these jurisdictions. Stakeholders must monitor evolving Buy Clean mandates and harmonization gaps between North American and European material certification protocols to anticipate qualification barriers.
Market Dynamics
Pultrusion automation and captive resin supply are concentrating competitive advantage among composite manufacturers capable of stabilizing input costs against volatile petrochemical feedstock markets.
Growth Catalysts
- California Buy Clean mandates:Low-carbon procurement thresholds for public infrastructure are disqualifying traditional steel rebar from state-funded bridge and highway tenders.
- Marine megaproject concentration:Coastal developments in Florida and the Persian Gulf are specifying GFRP reinforcement to eliminate chloride-induced spalling in high-salinity environments.
- Epoxy vinyl ester resin advances:Improved UV resistance and alkali tolerance in next-generation polymer matrices are extending service-life guarantees beyond 75 years.
Market Restraints
- Glass-fiber roving supply concentration:Three Chinese state-owned enterprises control 60% of global E-glass output, creating input vulnerability for Western pultruders.
- First-cost penalty structure:GFRP rebar carries 2-3x upfront cost versus black steel, compressing adoption in markets without lifecycle-cost procurement mandates.
- Steel industry lobbying:Electric-arc-furnace producers are securing recycled-content carveouts in nascent green building codes, slowing composite penetration in commercial construction.
Strategic Opportunities
- India's coastal infrastructure buildout:The country's National Maritime Agenda is generating tender volume for corrosion-resistant reinforcement in port modernization projects.
- Thermal-break integration:Combining GFRP rebar with structural thermal breaks addresses envelope performance requirements in Passivhaus-certified buildings.
- Direct-to-contractor digital channels:Bypassing traditional rebar distributors through specification software embedded in BIM platforms reduces qualification friction for qualified suppliers.
Industry Challenges
- Pultrusion technician scarcity:The specialized skill set for continuous-profile manufacturing with tight tolerance control is concentrated in Quebec and Bavaria, limiting geographic production expansion.
- ACI 440 certification timelines:The American Concrete Institute's qualification protocol for FRP reinforcement requires 18-24 months of testing documentation, locking out new entrants from DOT-approved project lists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Green Rebar Market |
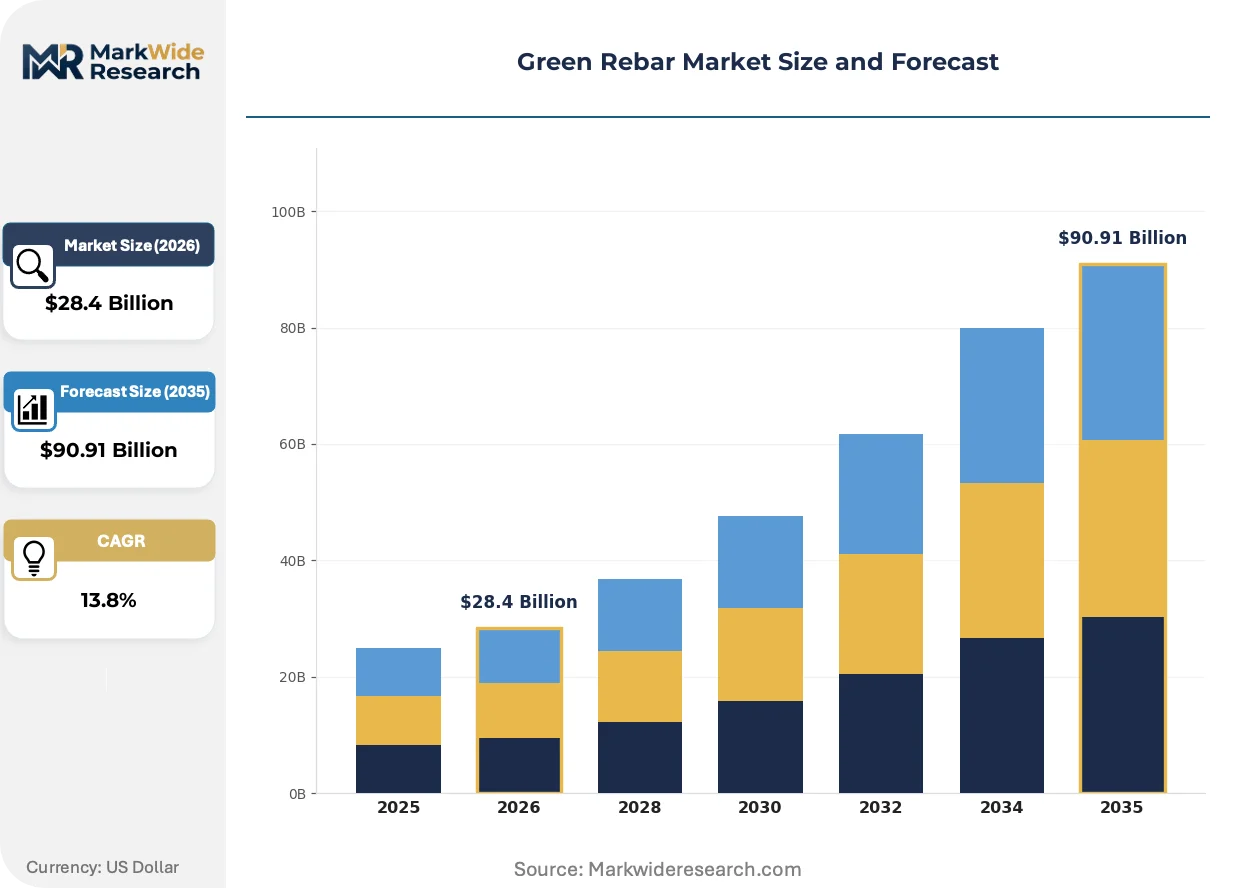
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $90.91 Billion |
| CAGR (2026 – 2036) | 13.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Steel, Fiber-Reinforced, Composite, Thermoplastic Application: Construction, Infrastructure, Roadways, Bridges End User: Contractors, Builders, Government, Industrial Distribution Channel: Direct Sales, Wholesalers, Online Retail, Distributors |
| Companies Covered | Pultrall Inc., Sireg Geotech, Dextra Group, Aslan FRP, Hughes Brothers, Pultron Composites, Kodiak Fiberglass Rebar, Composite Rebar Technologies, Schöck Bauteile GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Green Rebar Market Trends and Innovations
Material substitution logic is migrating from corrosion avoidance toward embodied-carbon accounting, with procurement algorithms now weighting lifecycle emissions alongside structural performance metrics.
Continuous basalt fiber reinforcement is supplanting E-glass roving in high-pH concrete environments where alkali-silica reaction risks degrade traditional glass fibers over decades. German bridge engineers are specifying basalt-GFRP hybrid bars for autobahn expansion joints exposed to de-icing salt and dynamic loading. This substitution is compressing the addressable market for conventional E-glass pultruders lacking basalt fiber sourcing relationships or process retrofit capital.
REACH-compliant vinyl ester formulations are displacing legacy styrene-based resins across European infrastructure tenders as ECHA restrictions on volatile organic compound emissions tighten manufacturing standards. Pultrusion facilities in Portugal and Poland are investing in closed-mold systems to maintain access to German and Dutch public works contracts. The regulatory pressure is fragmenting supplier compliance tiers, with non-adapted producers retreating to Middle Eastern and African markets with weaker chemical safety enforcement.
Lifecycle cost analysis is displacing first-cost bidding as the dominant selection criterion among transportation agency procurement officers with access to 50-year maintenance databases. Contractors in Florida and British Columbia are bundling GFRP rebar with extended warranty provisions that transfer spalling liability from public agencies to material suppliers. This behavioral shift is most visible in coastal US states where freeze-thaw cycling and salt exposure have generated documented failure cost data for black steel reinforcement.
Green Rebar Market Segmentation
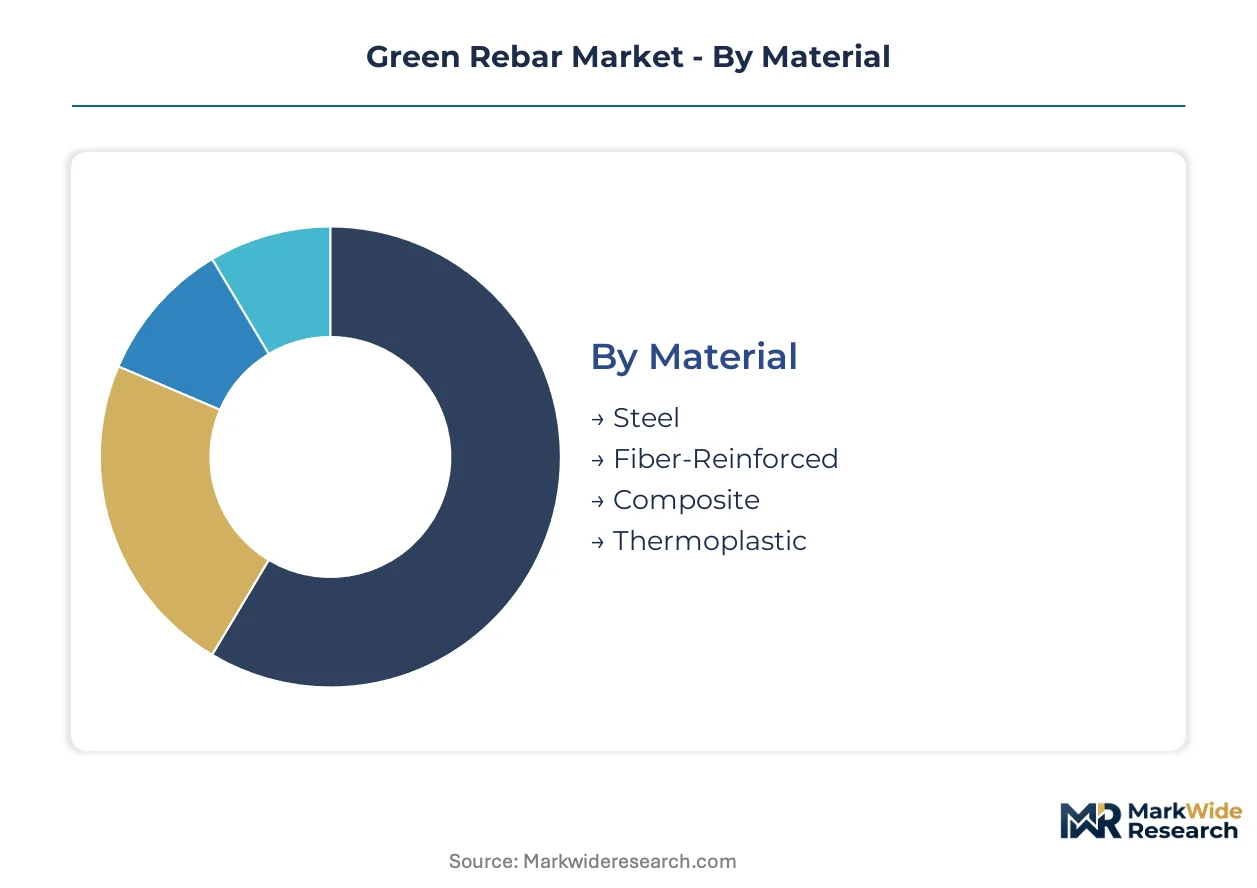
Material composition and procurement channel determine pricing power and qualification barriers in green rebar markets. Specification-grade segments command premium positioning through DOT certification protocols, while commodity variants compete on recycled-content credentials and regional availability.
Material:
Channel mix diverges sharply: composite and thermoplastic grades flow through specialized distributors with pultrusion expertise, while steel variants dominate wholesaler networks serving volume contractors.
- Steel:Electric-arc-furnace production with recycled scrap content satisfies California Buy Clean thresholds and Germany's low-carbon procurement mandates. Volume concentrates in commercial construction where first-cost bidding still predominates and EAF producers leverage recycled-content carveouts in nascent green building codes.
- Fiber-Reinforced:Glass-fiber-reinforced polymer bars with vinyl ester or epoxy matrices eliminate chloride-induced corrosion in marine environments. Demand clusters in Florida coastal megaprojects and Persian Gulf infrastructure where lifecycle cost analysis overrides upfront expenditure, with Pultrall and Hughes Brothers controlling qualified distribution.
- Composite:Hybrid reinforcement systems combining basalt and glass fibers address alkali-silica reaction risks in high-pH concrete.
- Thermoplastic:Emerging polymer matrices with improved UV resistance target temporary structural applications and repair scenarios.
By volume, Steel leads. By growth pace, Fiber-Reinforced is climbing the fastest.
Application:
Cost tier stratification separates specification-intensive bridge work from commodity commercial construction, with margin structures inversely correlating to project scale and public oversight intensity.
- Construction:Commercial and residential building codes drive specification through LEED and BREEAM certification pathways, with thermally efficient envelope designs integrating GFRP reinforcement to reduce thermal bridging.
- Infrastructure:Public agency procurement with 50-year maintenance databases weights lifecycle cost analysis heavily, favoring non-corrosive alternatives in salt-exposed environments despite 2-3x first-cost penalties.
- Roadways:Highway expansion and rehabilitation projects specify epoxy-coated or composite reinforcement where de-icing salt exposure accelerates traditional steel degradation.
- Bridges:Federal Highway Administration and state DOT qualification protocols lock out unproven suppliers through ACI 440 certification requirements spanning 18-24 months.
By project count, Construction dominates. By specification stringency, Bridges sets the standard.
End User:
Customer type determines procurement sophistication, with government agencies enforcing EPD declarations and ISO 14040-series lifecycle assessments as de facto bidding prerequisites.
- Contractors:Prime infrastructure contractors in Florida and British Columbia bundle GFRP rebar with extended warranty provisions transferring spalling liability to material suppliers, requiring documented performance data and ACI certification.
- Builders:Commercial construction firms balance green building code compliance against first-cost constraints, often defaulting to EAF steel where recycled-content thresholds suffice.
- Government:Transportation agencies with access to long-term maintenance cost data drive fastest adoption of lifecycle-cost procurement, disqualifying black steel from coastal tenders.
- Industrial:Petrochemical and power generation facilities specify non-conductive reinforcement for electromagnetic interference-sensitive structures.
By procurement volume, Contractors lead. By mandate-driven specification change, Government is gaining share fastest.
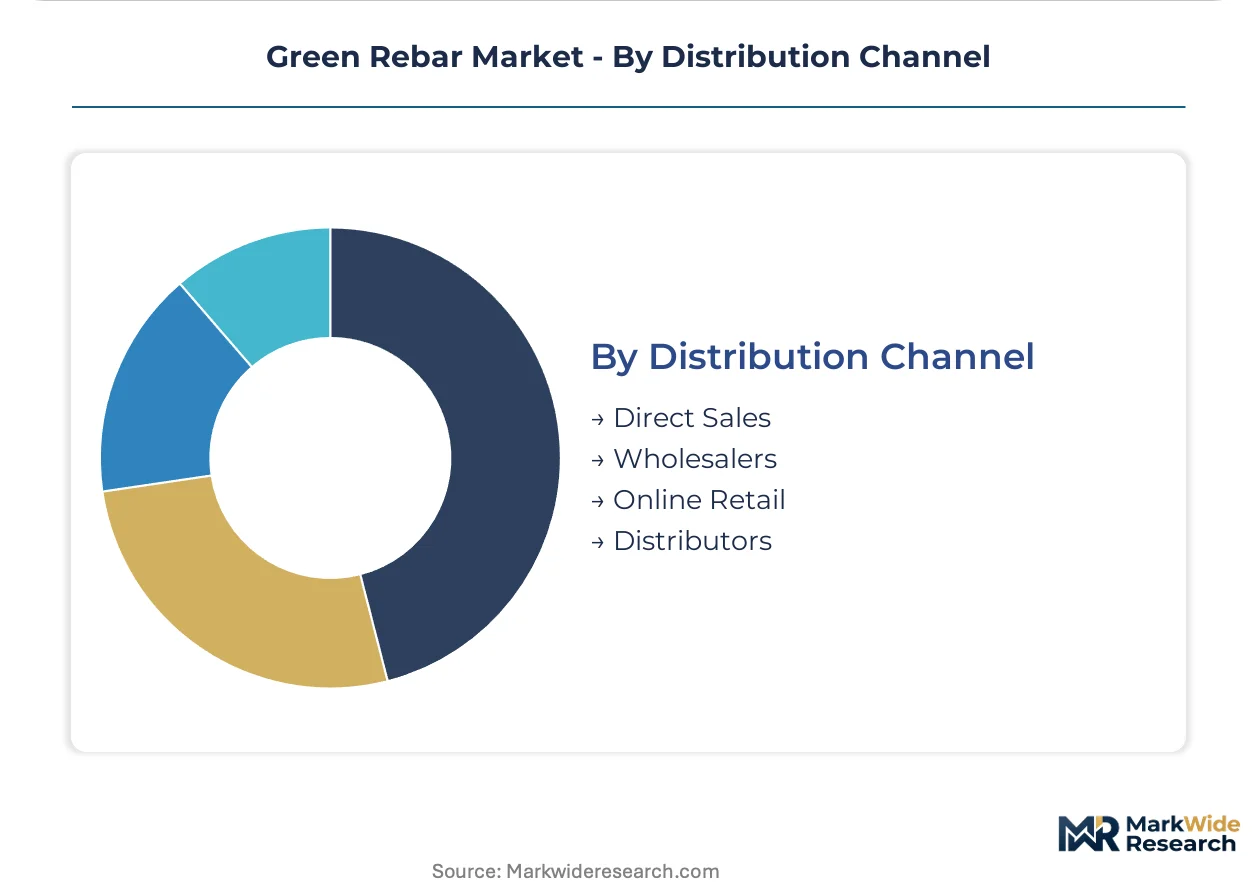
Distribution Channel:
Maturity gradients separate established rebar distribution networks from emerging digital specification pathways embedded in BIM platforms.
- Direct Sales:Pultruders with captive resin supply and automated production maintain margin control through specification relationships with DOT-qualified contractors, bypassing traditional distributor markups.
- Wholesalers:Regional rebar distributors handle volume steel grades serving commercial construction markets with standardized procurement protocols and limited technical specification requirements.
- Online Retail:Digital channels remain nascent for specification-grade reinforcement but emerging for repair-grade thermoplastic and small-diameter composite products.
- Distributors:Specialized composite distributors with pultrusion technical expertise concentrate in Quebec and Bavaria, limiting geographic expansion due to technician scarcity.
By transaction volume, Wholesalers lead. By margin preservation, Direct Sales shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and Californian procurement corridors where lifecycle-cost mandates override first-cost bidding, while volume growth accelerates in coastal megaprojects across Florida and the Persian Gulf where chloride exposure drives specification shifts.
United States
Bridge rehabilitation in Florida and highway expansion in California dominate specification-grade demand. The Federal Highway Administration enforces corrosion-resistance standards that disqualify traditional steel from salt-exposed tenders. Miami-Dade County infrastructure clusters concentrate GFRP procurement for marine deck applications.
Germany
Autobahn expansion joints and thermal-break building systems anchor European composite reinforcement consumption. KBA-adjacent infrastructure certification bodies mandate REACH-compliant vinyl ester formulations in public works contracts. Bavarian pultrusion facilities supply precision-engineered bars to Dutch and Austrian cross-border projects.
Canada
Quebec's captive glass-fiber roving contracts stabilize input costs for Northeast US bridge projects. Provincial transportation agencies in British Columbia bundle extended warranty provisions with GFRP specifications. Montreal-area manufacturing clusters address freeze-thaw degradation in maritime infrastructure.
India
Port modernization under the National Maritime Agenda generates tender volume for corrosion-resistant reinforcement. The Central Electricity Authority influences material standards for coastal power generation facilities. Gujarat and Maharashtra industrial corridors concentrate early contractor engagement for marine pile applications.
United Arab Emirates
Persian Gulf coastal developments specify non-conductive reinforcement for electromagnetic interference-sensitive structures. Dubai's building codes increasingly reference lifecycle cost analysis for subterranean parking and marine foundations. Abu Dhabi infrastructure procurement is embedding sustainability-weighted scoring for reinforcement materials.
Green Rebar Market Competitive Landscape
Concentration sits with integrated composite manufacturers controlling captive resin supply and automated pultrusion capacity. The vendor base stratifies across three tiers: global specialists with DOT qualification portfolios, regional fabricators serving niche geographic markets, and steel incumbents securing recycled-content carveouts in nascent green codes. Dominant competitive moves include backward integration into glass-fiber roving supply and strategic partnerships with BIM platform providers to embed specification software.
Within the integrated manufacturing tier, Pultrall Inc. and Pultron Composites exemplify archetypes combining captive raw material contracts with automated production scale. Schöck Bauteile GmbH anchors the European precision-engineering segment. Hughes Brothers occupies a position bridging specialized distribution and qualification-heavy infrastructure procurement in North American transportation markets.
| Leading Market Players |
|---|
| Pultrall Inc. |
| Sireg Geotech |
| Dextra Group |
| Aslan FRP |
| Hughes Brothers |
| Pultron Composites |
| Kodiak Fiberglass Rebar |
| Composite Rebar Technologies |
| Schöck Bauteile GmbH |
| Others |
Pricing and Supply Chain Analysis
ACI 440 certification protocols simultaneously gate supplier qualification and stratify price tiers, embedding cost premiums for DOT-approved composite bars while compressing margins for uncertified commodity alternatives. This regulatory chokepoint forces buyers to navigate a bifurcated market where lifecycle-cost procurement mandates in Florida and California sustain premium positioning, while first-cost bidding in commercial construction channels erodes pricing power for standard grades.
Pricing Analysis
Configured-to-order pricing for ACI 440-certified GFRP bars commands spreads of 40-60% above standard catalog grades, with certification tier and resin formulation grade driving differentiation. Project-based contract structures dominate infrastructure procurement, though spot purchasing persists for repair-grade thermoplastic products. Cost compression in uncertified steel-alternative tiers intensifies as electric-arc-furnace producers secure recycled-content carveouts in nascent green building codes. Government transportation agencies exhibit lowest price sensitivity due to 50-year maintenance database access, while commercial builders remain most cost-constrained.
Supply Chain Analysis
Strait of Hormuz transit vulnerability underwrites Persian Gulf logistics costs for glass-fiber roving shipments, amplifying input price volatility for regional pultruders. Manufacturing concentrates in China, Germany, and Quebec, with E-glass roving supply anchored in Chinese state-owned enterprises and vinyl ester resin production centered in German chemical corridors. Raw material dependencies span petrochemical feedstocks, borosilicate glass batches, and epoxy hardener additives. Single-source vulnerability in E-glass output creates structural risk. Distribution runs through specialized composite distributors with pultrusion technical expertise, bypassing traditional steel rebar wholesaler networks for specification-grade volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in digital specification channels and thermal-break integration niches, as lifecycle-cost procurement algorithms displace first-cost bidding across coastal infrastructure markets. This demand-side shift creates defendable positions for specialists controlling certification timelines and captive resin supply.
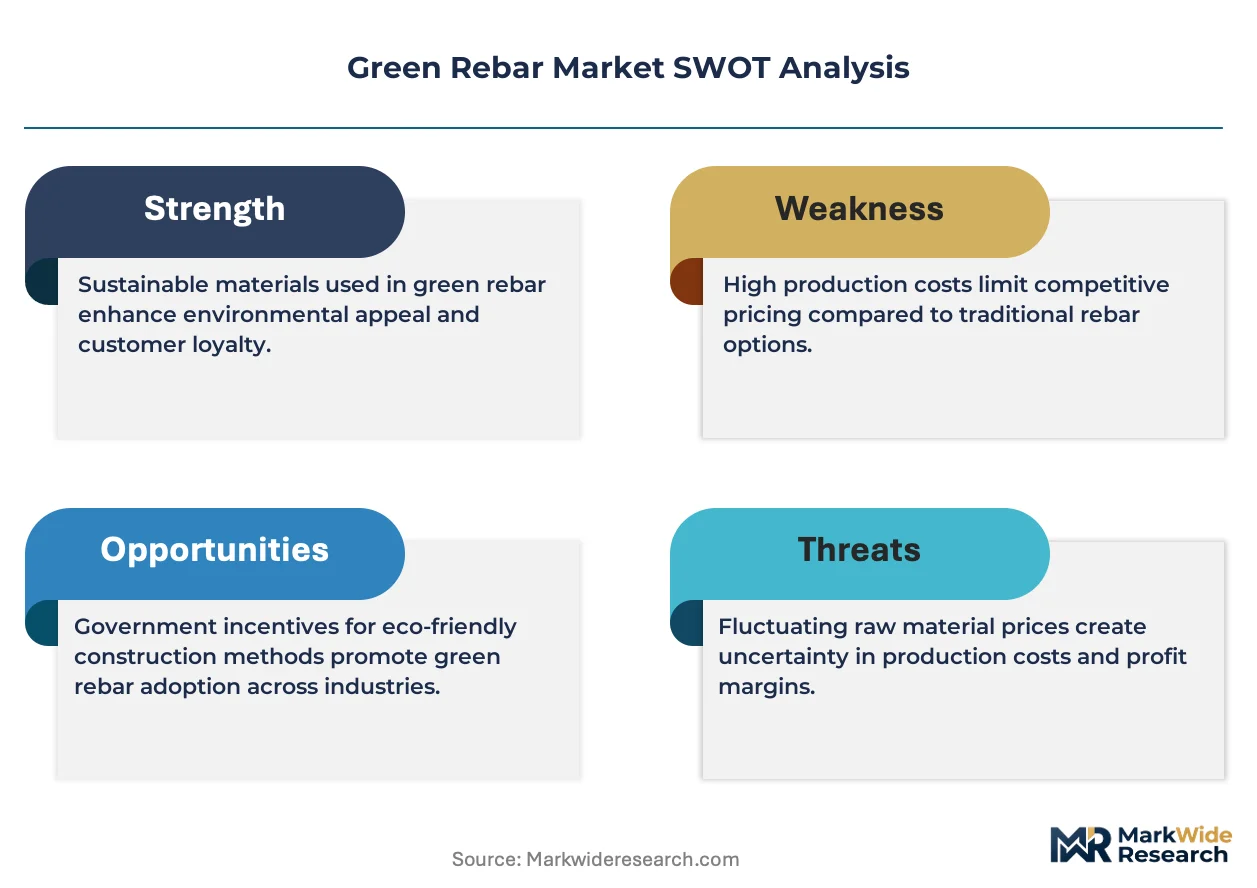
For Market Incumbents: Compound qualification advantages by extending ACI 440 certification coverage into basalt-GFRP hybrid formulations before alkali-silica reaction risks displace conventional glass-fiber positioning. Lock in backward integration into glass-fiber roving contracts to neutralize Chinese supply concentration, while embedding specification software in BIM platforms to capture contractor workflow dependency. Basalt fiber substitution and pultrusion technician scarcity represent imminent threats requiring capacity investment in Quebec and Bavaria training pipelines. For New Entrants and Emerging Players: Digital specification workflow gaps where incumbent pultruders under-serve mid-tier contractors with limited DOT pre-qualification access offer immediate white-space entry. Target India's port modernization tender flow under the National Maritime Agenda, where corrosion-resistant reinforcement demand outpaces qualified local supply. Bundle extended warranty provisions with GFRP specifications to transfer spalling liability, mirroring Florida and British Columbia procurement innovations. Direct-to-contractor channels via BIM-embedded software reduce 18-24 month ACI 440 friction for repair-grade and thermoplastic product lines. For Investors and Strategic Acquirers: California Buy Clean mandate expansion reshapes the acquisition landscape toward pultruders with captive resin supply and automated production scale. Long-term viability across the projection horizon favors integrated manufacturers with DOT qualification portfolios over regional fabricators lacking certification depth. Acquisition target archetype: mid-cap Quebec or Bavarian pultruders with glass-fiber roving contracts and ACI 440 approval in progress. Signal to monitor: harmonization gaps between North American and European material certification protocols narrowing or widening.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Glass-Fiber Roving Supply | Captive E-glass contracts with Chinese state-owned enterprises stabilize input costs against petrochemical volatility. |
| ACI 440 Certification Expansion | Extended qualification coverage into basalt-GFRP hybrids preempts alkali-silica reaction substitution threats. |
| BIM Platform Specification Embedding | Software integration with Autodesk and Bentley workflows captures contractor procurement dependency. |
| REACH-Compliant Vinyl Ester Transition | Closed-mold system investment maintains German and Dutch public works contract access under ECHA restrictions. |
| Extended Warranty Liability Transfer | Spalling risk bundling with GFRP specifications aligns with Florida DOT lifecycle-cost procurement algorithms. |
Research Methodology
Initial hypotheses were tested against primary input from pultrusion plant managers, DOT procurement officers, composite distributor technical directors, and EPC contractor materials engineers, then refined through secondary validation. Primary fieldwork combined structured interviews across Quebec, Florida, and Bavaria manufacturing clusters with trade data analysis from USITC import records and German KBA-adjacent certification body filings. Secondary sources encompassed ACI 440 test documentation, ECHA REACH compliance registries, and California Air Resources Board Buy Clean procurement thresholds. Bottom-up volume estimates from pultruder capacity utilization were triangulated against top-down infrastructure tender flow analysis.
Variance decomposition across material grade, application intensity, and end-user procurement sophistication anchored the analytical framework. Segmentation dimensions modeled span material composition, project scale tier, certification status, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating chloride-exposure degradation rates and lifecycle-cost algorithm adoption curves. Industry-specific forecast inputs included Florida DOT bridge rehabilitation pipeline tracking and Persian Gulf coastal megaproject development databases.
Material uncertainties — glass-fiber supply disruption, ACI 440 timeline compression, and steel industry lobbying success in green code carveouts — sit outside the modeled envelope. Forecasts reflect assumptions regarding continued lifecycle-cost procurement mandate expansion and stable E-glass roving trade flows. Practitioners should keep alternative scenarios live as harmonization between North American and European certification protocols evolves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Green Building Materials
Eco-Friendly Bitumen Market
Green Building Materials
China Green Building Materials Market
Green Building Materials
Global Eco-Friendly Green Roofs Market
Green Building Materials
Green Coatings Market
Green Building Materials
Eco-Friendly Tiles Market
Green Building Materials
Green Silica Market
Green Building Materials
Solar Glass Market
Green Building Materials
Artificial Green Wall Market
Green Building Materials
Global Green Walls Market
Green Building Materials
Green Cement Market
Green Building Materials
United States Green Cement Market
Green Building Materials
GCC Green Cement Market
Green Building Materials
Green Waterproofing Products Market
Green Building Materials
Europe Green Cement Market
Green Building Materials
Sustainable and Green Building Materials Market
Green Building Materials
Green Roof Market