
 Global Succulent Plant Market | 2026-2036
Global Succulent Plant Market Size, Share, and Industry Trends Forecast 2026-2036
Global Succulent Plant Market Outlook
REACH compliance is pivoting the cost-of-entry calculus for European succulent importers, forcing upstream investment in certified propagation and chemical disclosure documentation. Costa Farms leverages its integrated tissue-culture labs to sustain year-round supply consistency across North American retail channels. Altman Plants anchors the mass-market segment through controlled-environment agriculture at its California and Florida facilities. Dümmen Orange differentiates via proprietary breeding programs that extend color and form variety beyond commodity generics.
Succulent plants are drought-adapted angiosperms with specialized CAM photosynthesis, water-storing parenchyma tissues, and thickened cuticles that enable survival in arid conditions; commercial propagation employs unrooted cuttings, tissue culture, and offset division to achieve scale. The ornamental trade values these species for low-maintenance interiorscaping, xeriscape landscaping, and corporate wellness programs. Aloe Vera dominates product-type revenue due to dual ornamental and cosmetic-ingredient demand, while Echeveria leads volume growth among millennial homeowner segments. Online Retail channels capture the fastest expansion in distribution, though Garden Centers retain margin concentration through higher-attachment accessories and repotting services.
The EU Green Deal and REACH framework impose substance restriction and carbon-footprint documentation burdens on non-European nursery exporters. The USDA's APHIS division enforces phytosanitary certification for interstate and international shipments, shaping propagation-location decisions among major suppliers. China's GB standards for agricultural product labeling create additional compliance layers for Asian-origin imports. Stakeholders must monitor evolving biosecurity protocols and carbon-border adjustment mechanisms to determine propagation-site investments and certification timelines.
Market Dynamics
Propagation-site certification under REACH and USDA APHIS phytosanitary protocols is forcing nursery operators to consolidate tissue-culture capacity near end-markets, compressing lead times while raising fixed-cost thresholds for new entrants.
Growth Catalysts
- EU Green Deal carbon-border documentation:Mandatory lifecycle footprint disclosure for ornamental imports is accelerating investment in Dutch and Spanish propagation facilities to bypass border-adjustment costs.
- Xeriscape landscaping mandates:Municipal water-use restrictions across Arizona, Nevada, and California are mandating drought-tolerant plantings in new commercial and residential developments.
- Controlled-environment agriculture:LED-optimized growth chambers and automated climate systems are extending production seasons and reducing per-unit propagation losses in North American facilities.
Market Restraints
- Phytosanitary compliance costs:USDA APHIS certification requirements for interstate shipments impose documentation burdens and inspection delays that scale disproportionately for small-batch exporters.
- Peat substrate price volatility:Sphagnum peat harvesting restrictions in Ireland and Baltic states are compressing margins for soil-dependent propagation operations.
- Single-source genetics concentration:Proprietary cultivar licensing from Dutch and German breeding houses limits varietal diversity accessible to independent nurseries.
Strategic Opportunities
- South Korean corporate wellness interiorscaping:MFDS-permitted cosmetic-ingredient pathways for Aloe-derived compounds are opening dual-use cultivation contracts with Seoul-based facility management firms.
- Direct-to-consumer subscription channels:Monthly succulent delivery services bypass garden-center intermediaries and capture higher lifetime value through automated repotting supply bundles.
- India PLI scheme for floriculture:Production-linked incentives for controlled-environment agriculture are attracting tissue-culture joint ventures in Karnataka and Maharashtra greenhouse clusters.
Industry Challenges
- Certified propagator talent scarcity:Skilled technicians capable of maintaining sterile tissue-culture protocols command premium wages that strain mid-scale nursery operating budgets.
- Multi-jurisdiction documentation synchronization:Reconciling EU REACH substance disclosures, USDA APHIS phytosanitary certificates, and China GB labeling standards extends shipment preparation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Succulent Plant Market |
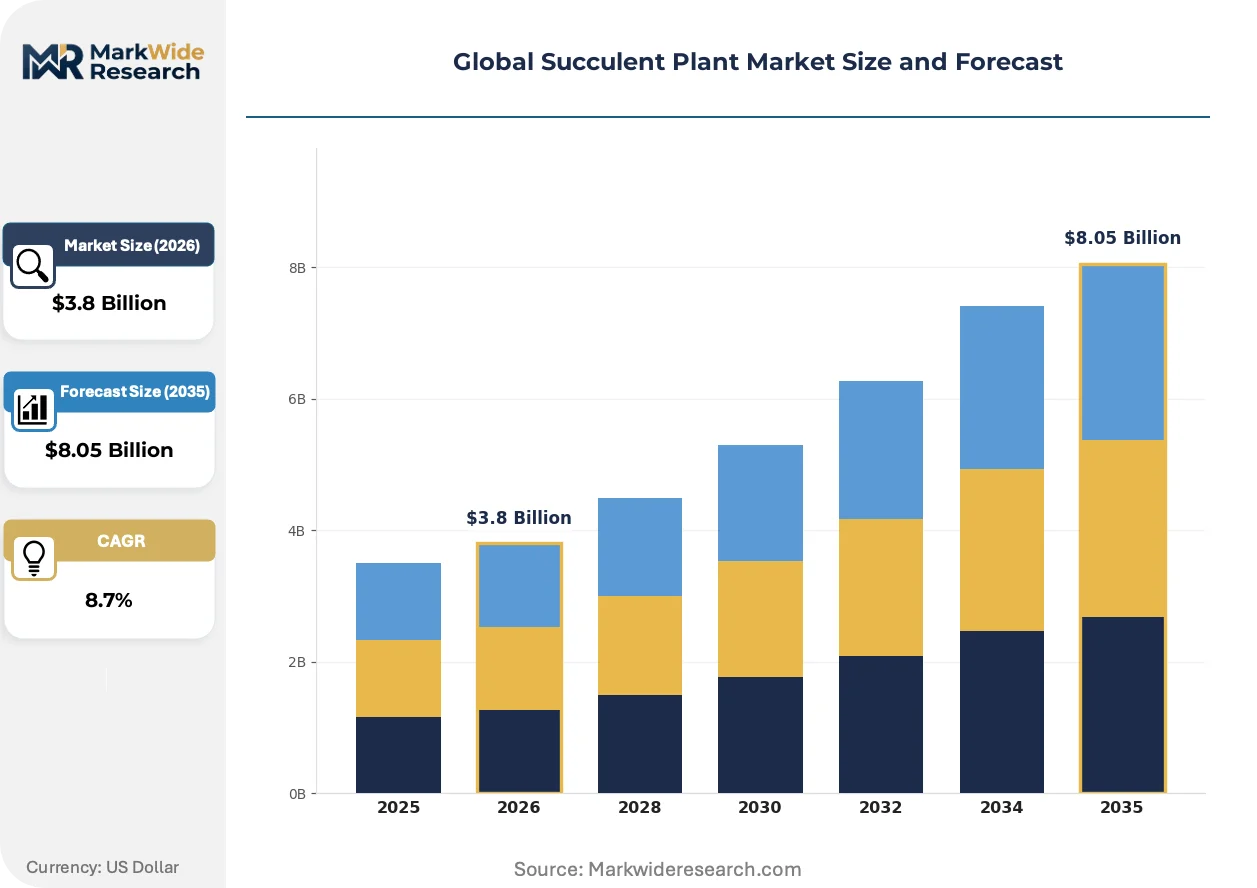
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aloe Vera, Echeveria, Sedum, Haworthia End User: Homeowners, Retail Nurseries, Landscaping Companies, Botanical Gardens Distribution Channel: Online Retail, Garden Centers, Wholesale Suppliers, Supermarkets Size: Small Pots, Medium Pots, Large Pots, Bulk Packaging |
| Companies Covered | Costa Farms, Altman Plants, AdeniumRose Company, Dümmen Orange, Zhejiang Wanxiang Flowers, Qingdao Flowery Crafts Co., Ltd., From You Flowers, Succulents Box LLC, Mountain Crest Gardens, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Succulent Plant Market Strategic Shifts
Automation in propagation facilities and regulatory digitization are compressing production cycles while fragmenting traditional distribution hierarchies across the ornamental supply chain.
LED-optimized spectral tuning for CAM photosynthesis is electrifying year-round production consistency in vertical propagation systems. Dutch and Californian nursery operators are retrofitting growth chambers with tunable diode arrays that accelerate offset development. This technology is electrifying margin structures by reducing seasonality-driven inventory write-downs and enabling just-in-time contract fulfillment for retail chains.
REACH substance restriction expansions under the EU Green Deal are tightening chemical disclosure requirements for imported ornamental substrates. Nursery exporters must now document fertilizer and pesticide residues across propagation-to-shipment intervals. Small-scale Latin American suppliers face the steepest compliance burden and are ceding shelf space to vertically integrated European propagators with in-house laboratory certification.
Corporate procurement teams are consolidating interior-planting contracts under single-source facility management agreements. Multi-location employers in technology and financial services are replacing decentralized local nursery relationships with national subscription programs. This concentration is most visible across United States headquarters clusters in Austin, Denver, and Raleigh-Durham, where standardized species palettes and automated replacement guarantees dominate vendor selection criteria.
Global Succulent Plant Market Segmentation
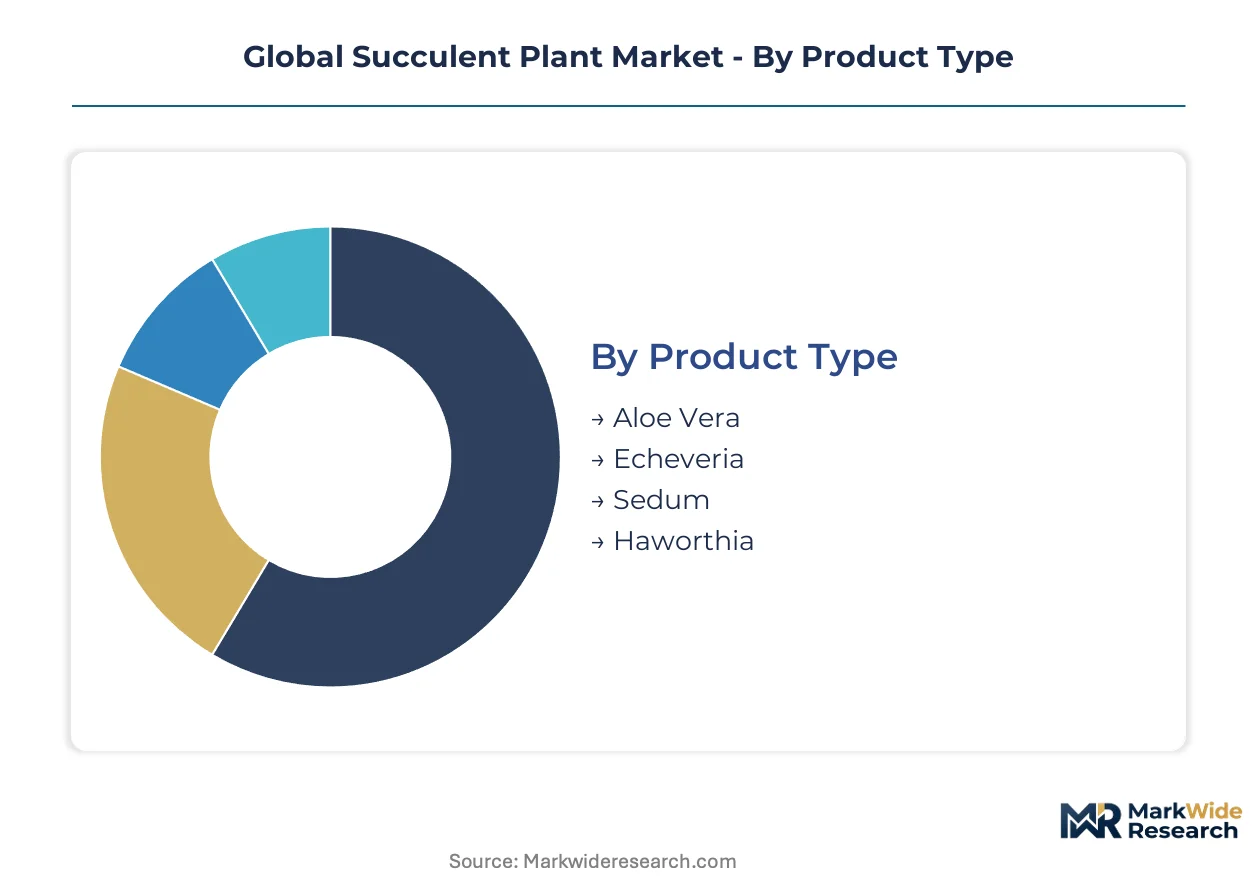
Succulent market segmentation reveals distinct upgrade cycles across product types and distribution channels. Understanding these replacement patterns enables suppliers to align propagation schedules with predictable refresh demand from interiorscaping contracts and homeowner collections.
Product Type:
Replacement cycles vary sharply across species, with cosmetic-ingredient cultivars demanding faster turnover than ornamental generics.
- Aloe Vera:Dual-use species harvested for gel extraction drives shorter replacement cycles in cosmetic supply chains. Korean MFDS-permitted cultivation contracts and California wellness product manufacturers concentrate demand for certified organic propagation stock.
- Echeveria:Rosette-forming Mexican natives dominate millennial homeowner collections with rapid color-variant churn. Instagram-driven aesthetic refresh cycles in United States urban markets accelerate offset purchases for seasonal palette rotation.
- Sedum:Cold-hardy groundcover species serve xeriscape landscaping mandates across Arizona and Nevada municipal contracts.
- Haworthia:Compact South African species suit desktop interiorscaping in Japanese and German corporate environments with low-light tolerance.
Aloe Vera sits at the top of the volume ranking, with Echeveria climbing the fastest.
End User:
Cost tier differentiation separates high-touch institutional buyers from price-sensitive mass consumers.
- Homeowners:Direct-to-consumer subscription services capture repeat purchase loyalty through automated repotting supply bundles. United States millennial segments in Austin and Denver drive premium cultivar demand via Instagram-native retailers.
- Retail Nurseries:Independent garden centers in California and Florida clusters rely on margin concentration through higher-attachment accessories and seasonal display rotations.
- Landscaping Companies:Commercial xeriscape installers across southwestern United States states face municipal water-use restrictions mandating drought-tolerant plantings in new developments.
- Botanical Gardens:Conservation-focused institutions in Netherlands and Singapore prioritize certified disease-free propagation stock for public collection integrity.
Landscaping Companies command the highest contract values, with Homeowners expanding most quickly through digital channels.
Distribution Channel:
Volume concentration shifts toward direct fulfillment as traditional wholesale hierarchies fragment.
- Online Retail:Monthly subscription services bypass garden-center intermediaries and capture higher lifetime value through automated care supply bundles. Seoul-based facility management firms and United States direct-to-consumer platforms drive fastest channel expansion.
- Garden Centers:Physical retail retains margin concentration through repotting services and ceramic accessory attachment in California and Florida nursery clusters.
- Wholesale Suppliers:Bulk propagation houses in Netherlands and Spain serve European retail chains with REACH-compliant certified stock.
- Supermarkets:Mass-market grocery channels in Germany and United Kingdom prioritize low-price Echeveria and Haworthia impulse displays.
Online Retail captures the steepest expansion trajectory, with Garden Centers defending margin density through service attachment.
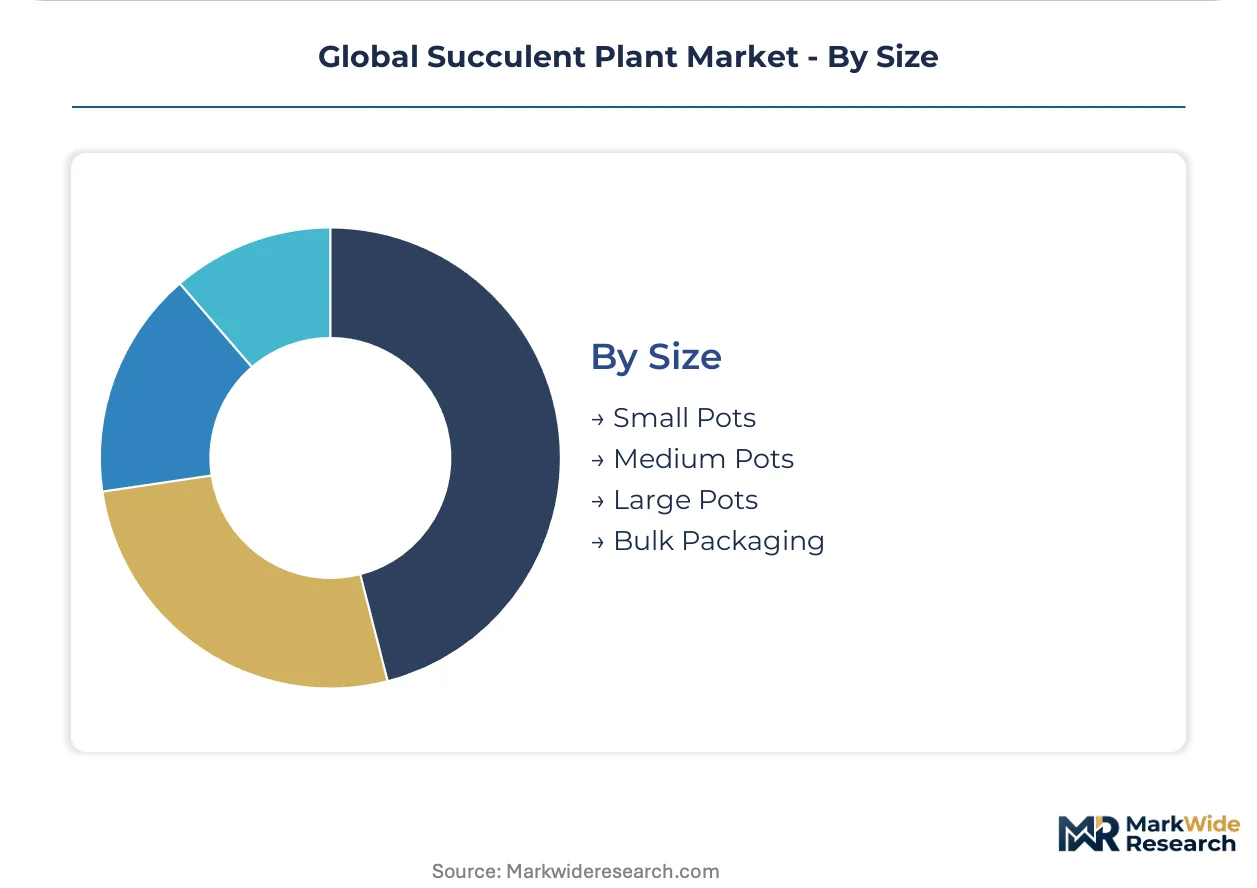
Size:
Customer type and application maturity determine packaging format demand across residential and commercial segments.
- Small Pots:Desktop-scale specimens dominate corporate wellness interiorscaping in technology sector headquarters across Austin, Denver, and Raleigh-Durham. Standardized 2-inch and 4-inch formats suit automated replacement guarantees in facility management contracts.
- Medium Pots:Residential entryway and patio applications in drought-prone southwestern United States states favor 6-inch to 8-inch specimens for immediate landscape impact.
- Large Pots:Specimen-grade Aloe Vera and agave relatives serve commercial atrium installations in Singapore and Dubai hospitality developments.
- Bulk Packaging:Unrooted cuttings and tissue-culture trays supply propagation houses in Karnataka and Maharashtra greenhouse clusters under India PLI scheme incentives.
Small Pots lead unit volume through corporate procurement consolidation, with Bulk Packaging gaining share fastest in Asian propagation joint ventures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled propagators and tissue-culture technicians concentrate in the Netherlands, California, and China's Zhejiang province. These talent clusters anchor commercial-scale succulent production for export markets. Regional regulatory divergence is reshaping propagation-site investment decisions.
United States
Municipal xeriscape mandates across Arizona, Nevada, and California drive commercial landscaping demand. USDA APHIS phytosanitary certification requirements shape interstate shipment protocols. California's Central Valley and Florida nursery clusters host Costa Farms and Altman Plants facilities serving mass-market retail channels.
Netherlands
EU Green Deal carbon-border documentation accelerates investment in Dutch propagation facilities. REACH substance disclosure requirements tighten chemical documentation for imported substrates. Westland and Aalsmeer greenhouse complexes concentrate tissue-culture capacity serving European retail chains.
Germany
Corporate wellness interiorscaping contracts from technology and financial services firms concentrate demand. ECHA REACH enforcement tightens fertilizer residue documentation for ornamental imports. Bavarian and North Rhine-Westphalian facility management firms consolidate national succulent procurement under single-source agreements.
China
Domestic millennial homeowner demand and export processing contracts drive propagation scale. GB standards for agricultural product labeling create compliance layers for Asian-origin shipments. Zhejiang and Shandong greenhouse clusters supply unrooted cuttings and tissue-culture trays to international buyers.
South Korea
MFDS-permitted cosmetic-ingredient pathways for Aloe-derived compounds open dual-use cultivation contracts. Corporate facility management firms in Seoul drive standardized interiorscaping procurement. Gyeonggi-do and Chungcheongnam-do greenhouse operations serve wellness product manufacturers and office-plant service providers.
Global Succulent Plant Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across propagation, breeding, and distribution tiers. The vendor base separates into three strategic archetypes: vertically integrated mass-market propagators, proprietary breeding houses, and direct-to-consumer subscription specialists. Consolidation pressure intensifies as REACH and USDA APHIS certification costs favor scaled operators with in-house laboratory capacity. Competitive moves center on tissue-culture technology licensing and geographic propagation-site expansion.
Among North American mass-market propagators, Costa Farms and Altman Plants occupy positions exemplifying integrated tissue-culture and controlled-environment agriculture scale. Dümmen Orange represents the proprietary breeding house archetype with Dutch and German cultivar development heritage. These three anchors illustrate the structural divide between commodity propagation and differentiated genetics licensing.
| Leading Market Players |
|---|
| Costa Farms |
| Altman Plants |
| AdeniumRose Company |
| Dümmen Orange |
| Zhejiang Wanxiang Flowers |
| Qingdao Flowery Crafts Co., Ltd. |
| From You Flowers |
| Succulents Box LLC |
| Mountain Crest Gardens |
| Others |
Value Chain & Pricing Dynamics
Sphagnum peat harvesting restrictions in Ireland and Baltic states cascade through propagation economics, compressing margins for soil-dependent operations while rewarding facilities with in-house substrate formulation and certified tissue-culture capacity.
Pricing Analysis
Service bundling separates subscription-based succulent delivery programs from transactional garden-center purchases. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and after-sales care attachment, with REACH-compliant certified stock commanding substantial premiums over uncertified Latin American imports. Pricing pressure stems from peat substrate volatility and rising sterile-technician wages. Mass-market homeowners exhibit highest price sensitivity, while corporate facility management contracts show lowest sensitivity due to standardized replacement guarantee requirements.
Supply Chain Analysis
Certification gating under REACH and USDA APHIS protocols concentrates propagation capacity in Netherlands, United States, and China. Supply chains draw from sphagnum peat deposits, LED growth chamber components, and proprietary cultivar licenses. Single-source genetics concentration from Dutch and German breeding houses creates vulnerability for independent nurseries. Distribution runs through wholesale propagation houses serving retail chains, with direct-to-consumer subscription channels fragmenting traditional hierarchies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as corporate procurement teams consolidate interiorscaping contracts under single-source agreements demanding certified disease-free propagation stock and automated replacement guarantees.
For Market Incumbents: Deploy backward integration into tissue-culture laboratory capacity to defend against emerging pure-play subscription specialists and regulatory documentation burdens. Costa Farms and Altman Plants illustrate this lever through integrated controlled-environment agriculture. Certification investment under REACH and USDA APHIS protocols raises fixed-cost thresholds that disadvantage small-batch competitors. For New Entrants and Emerging Players: The price-point gap between premium certified stock and economy uncertified imports offers entry space. Target South Korean corporate wellness interiorscaping and India PLI scheme greenhouse clusters as most penetrable geographies. A direct-to-consumer subscription angle with automated repotting supply bundles bypasses garden-center intermediaries and captures higher lifetime value. For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated propagators with in-house laboratory certification and proprietary breeding programs. Long-term viability favors operators controlling genetics licensing and multi-jurisdiction compliance documentation. Watch for carbon-border adjustment mechanism implementation as inflection indicator accelerating Dutch and Spanish propagation facility investment.| Strategic Initiative | Industry Significance |
|---|---|
| Controlled-Environment Agriculture Scale-Up | LED-optimized growth chambers at Costa Farms and Altman Plants reduce seasonality-driven inventory write-downs. |
| Proprietary Breeding Program Investment | Dümmen Orange's cultivar development extends color and form variety beyond commodity generics for premium positioning. |
| Direct-to-Consumer Subscription Launch | Monthly delivery services bypass garden-center intermediaries and capture higher lifetime value through care supply bundles. |
| REACH Compliance Certification | EU Green Deal substance disclosure requirements favor vertically integrated European propagators with in-house laboratory capacity. |
| India PLI Scheme Joint Venture | Production-linked incentives attract tissue-culture partnerships in Karnataka and Maharashtra greenhouse clusters. |
Study Parameters
Direct dialogue with nursery operations directors, tissue-culture laboratory managers, corporate facility management procurement leads, and garden-center category buyers grounded qualitative findings. Secondary validation drew from USDA APHIS phytosanitary certification databases, EU ECHA REACH substance disclosure registries, customs and trade flow records, and controlled-environment agriculture equipment manufacturer disclosures. Bottom-up propagation capacity estimates triangulated against top-down retail channel shipment data.
Segmented outputs across product type, end user, distribution channel, and size dimensions structured the analytical framework throughout the projection horizon. CAGRs derived from propagation volume trajectories, replacement cycle frequencies, and channel shift elasticity parameters. Industry-specific inputs included municipal xeriscape mandate adoption curves, corporate wellness interiorscaping contract consolidation rates, and LED growth chamber penetration in propagation facilities.
Caveats apply where regulatory enforcement intensity, peat substrate supply disruptions, or cultivar licensing terms could materially shift the outlook. Forecasts reflect documented assumptions about certification timeline compliance and channel migration velocity. A model refresh is warranted upon material change in carbon-border adjustment mechanism implementation schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environment & Sustainability
Carbon Monoxide Analyzers Market
Environment & Sustainability
Extended Producer Responsibility (EPR) Advisory Services Market
Environment & Sustainability
Municipal Solid Waste Incineration Market
Environment & Sustainability
Eco Funnel Market
Environment & Sustainability
Solar Water Purifiers Market
Environment & Sustainability
Marine Waste Handling Equipment Market
Environment & Sustainability
Green Cement and Concrete Market
Environment & Sustainability
Green Emissions Analyzers Market
Environment & Sustainability
Air Scrubber Market
Environment & Sustainability
Water Trading Market
Environment & Sustainability
Track Carbon Footprint App Market
Environment & Sustainability
Indoor Air Purification Market
Environment & Sustainability
Europe Green Cement Market
Environment & Sustainability
China Waste Management Market
Environment & Sustainability
MENA Point of Use Water Purifiers Market
Environment & Sustainability
Blue-Green Algae Market