
 Green Cement and Concrete Market | 2026-2036
Green Cement and Concrete Market Size, Share, and Industry Trends Forecast 2026-2036
Green Cement and Concrete Market Analysis
Carbon capture curing technology is reconfiguring production economics across the green concrete value chain. Holcim Ltd leverages integrated quarry-to-concrete operations to control feedstock quality for low-clinker blends. HeidelbergCement AG anchors European supply through specialized grinding capacity for blast furnace slag cements. CEMEX S.A.B. de C.V. competes in North American infrastructure bids with verified environmental product declarations.
Green cement and concrete encompasses binders and composite materials formulated with reduced clinker content, incorporating supplementary cementitious materials such as fly ash, ground granulated blast-furnace slag, or calcined clays to achieve embodied carbon below conventional Portland cement thresholds. These materials serve structural applications where compressive strength ratings and durability parameters must satisfy building code requirements while meeting procurement mandates for carbon disclosure. Geopolymer cement commands premium positioning where extreme chemical resistance or thermal stability justifies formulation complexity, while fly ash cement dominates volume in markets with established coal combustion residuals supply chains. Blended cement occupies the broadest addressable base as procurement specifications standardize on performance-based rather than prescriptive compositional limits.
EPA emissions standards, EU Green Deal taxonomy criteria, and India's BIS certification protocols for blended cements collectively reshape product qualification and market access across major demand centers. Compliance with these frameworks determines eligibility for public infrastructure tenders and green building certification pathways. Stakeholders must monitor evolving threshold definitions for embodied carbon as procurement rules shift from voluntary disclosure toward mandatory compliance.
Market Dynamics
Carbon capture curing technology is virtualizing production economics by compressing curing cycles from 28 days to under 24 hours while sequestering process emissions directly into concrete matrices, forcing capital reallocation across the entire value chain from quarry operations to ready-mix distribution.
Growth Catalysts
- EU Green Deal taxonomy criteria:Building product manufacturers must meet embodied carbon thresholds to qualify for green financing and public tenders across Germany, France, and the Netherlands.
- Fly ash cement formulations:Coal combustion residuals supply chains in India and China enable cost-competitive low-clinker blends for mass infrastructure applications.
- Commercial structures in Vietnam:Building code revisions in Ho Chi Minh City and Hanoi mandate carbon disclosure for projects exceeding 20,000 square meters.
Market Restraints
- Ground granulated blast-furnace slag supply concentration:European steel production declines threaten feedstock availability for slag cement manufacturers in Germany and Poland.
- Calcined clay activation energy costs:Thermal processing of kaolinite-rich clays requires natural gas inputs that expose margins to commodity price volatility.
- Geopolymer cement technical limitations:Alkali-activated formulations exhibit unpredictable shrinkage behavior that limits acceptance in structural load-bearing applications.
Strategic Opportunities
- Carbon capture utilization credits under IRA:US Section 45Q tax incentives reward permanent mineralization of CO2 in concrete products, creating margin expansion for domestic producers.
- 3D printing construction integration:Layer-deposition systems for architectural concrete enable complex geometries with optimized material usage in Dubai and Riyadh.
- Rural infrastructure in Indonesia:National strategic projects outside Java Island lack established supply chains for conventional Portland cement, opening entry for mobile geopolymer batching systems.
Industry Challenges
- Carbon accounting skill gaps:Life cycle assessment expertise remains scarce among quality control laboratories responsible for environmental product declaration verification.
- Legacy equipment retrofit complexity:Existing precast concrete plants require kiln modifications to handle low-clinker blends without production throughput degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Green Cement and Concrete Market |
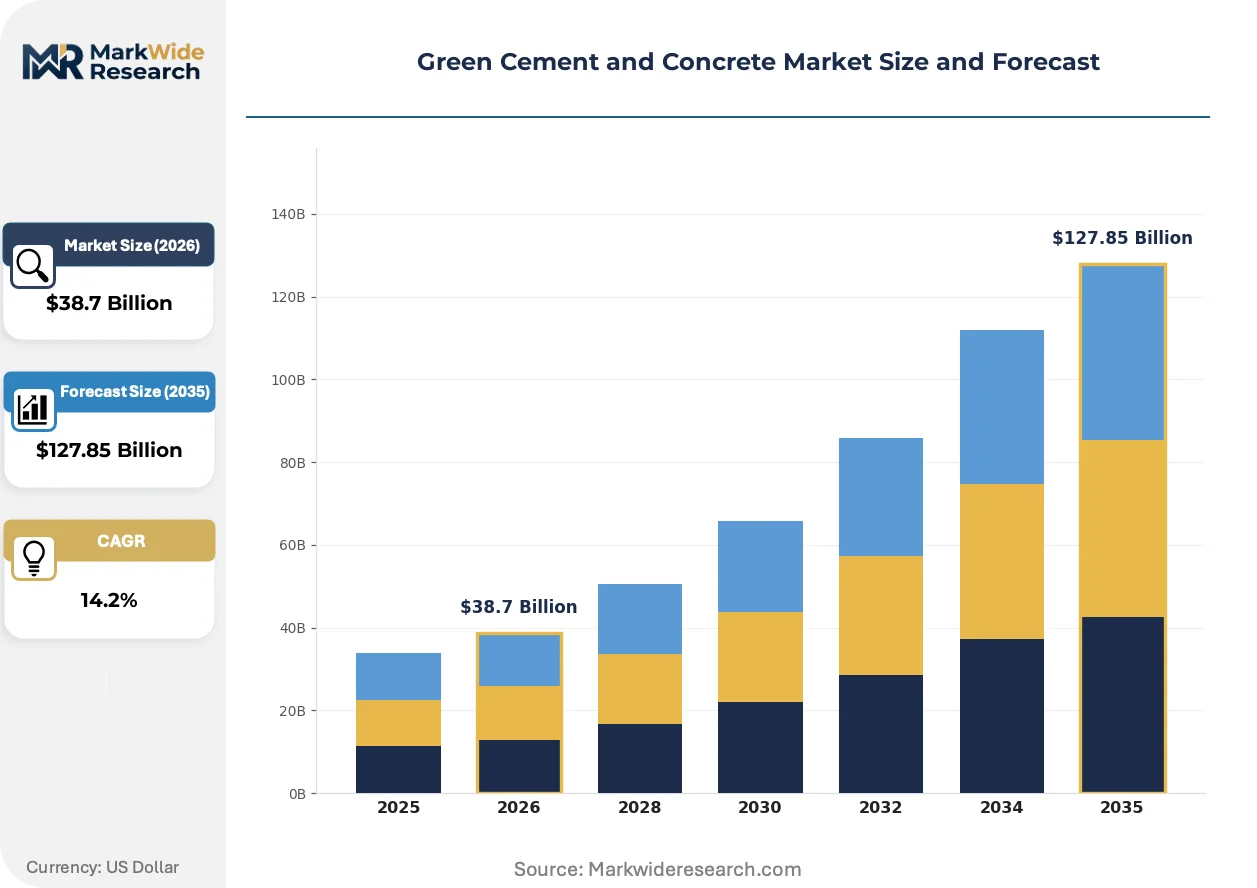
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $127.85 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Recycled Aggregate, Fly Ash Cement, Geopolymer Cement, Blended Cement Application: Residential Buildings, Commercial Structures, Roads, Bridges End User: Construction Companies, Infrastructure Developers, Government Projects, DIY Enthusiasts Distribution Channel: Online Retail, Direct Sales, Wholesalers, Specialty Stores |
| Companies Covered | Holcim Ltd, HeidelbergCement AG, CEMEX S.A.B. de C.V., CRH plc, UltraTech Cement Ltd, Anhui Conch Cement Company Limited, Taiheiyo Cement Corporation, CarbonCure Technologies Inc., Calera Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Green Cement and Concrete Market Emerging Trajectories
Digital twin modeling of concrete mix designs is compressing formulation development cycles from months to weeks while enabling real-time optimization of supplementary cementitious material ratios based on feedstock variability.
Carbon capture curing technology is virtualizing the traditional time-value tradeoff in concrete production. Infrastructure contractors in California and Texas are adopting accelerated curing systems for bridge deck precasting. This compression is virtualizing working capital requirements and enabling just-in-time delivery models that were previously uneconomical for structural concrete.
India's BIS certification protocols for blended cements are mandating performance-based testing rather than prescriptive composition limits. Manufacturers must now demonstrate 28-day compressive strength and sulfate resistance through standardized trials. The blended cement segment faces the steepest compliance burden as legacy formulations require reformulation to meet new durability benchmarks.
Public procurement authorities in Singapore and Sydney are unbundling concrete supply contracts from construction management agreements, creating direct purchasing relationships with certified low-carbon suppliers. Engineering firms are responding by establishing dedicated sustainable materials procurement functions that bypass traditional ready-mix intermediaries. This disintermediation is most pronounced in transit-oriented development projects where carbon disclosure carries premium weighting in bid scoring.
Green Cement and Concrete Market Segmentation
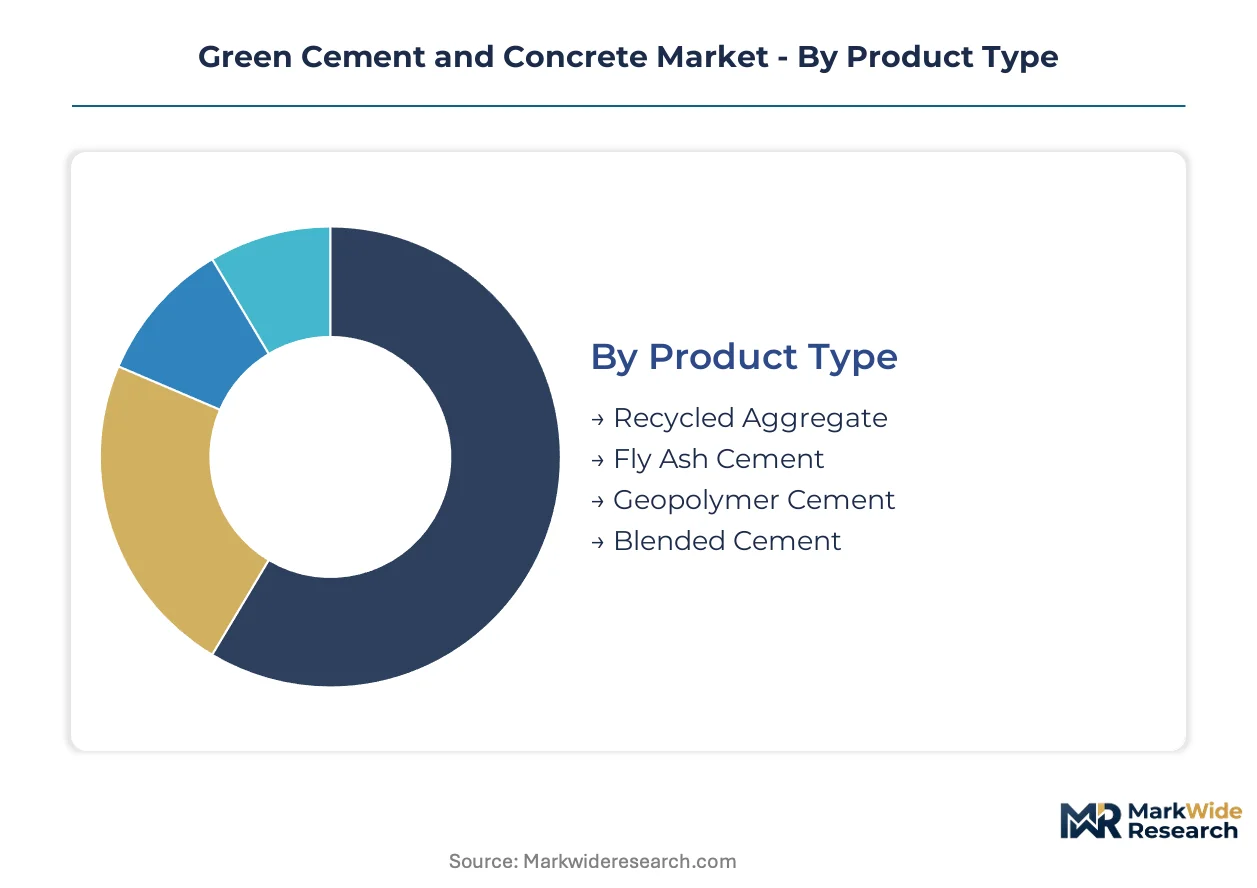
Segmentation in green cement and concrete reveals divergent procurement rhythms. Product types cycle through qualification protocols at different speeds, while applications and end users impose distinct technical and commercial requirements that reshape supplier priorities.
Product Type:
Cycle times vary sharply across formulations. Blended cement moves through prescriptive approval pathways in months, while geopolymer cement faces extended performance verification that stretches commercialization timelines.
- Blended Cement:Formulations combine Portland clinker with supplementary cementitious materials at 15-50% replacement rates. Infrastructure tenders in India and Vietnam specify blended cement for mass concrete applications where BIS and local building codes mandate reduced embodied carbon thresholds.
- Fly Ash Cement:Coal combustion residuals enable clinker replacement up to 35% by mass. Procurement concentrates in thermal power corridor regions where established ash supply chains support cost-competitive production for government highway projects.
- Geopolymer Cement:Alkali-activated binders using metakaolin or slag achieve near-zero clinker content. Technical complexity limits adoption to specialized precast applications with extended curing protocols.
- Recycled Aggregate:Crushed concrete from demolition debris replaces virgin aggregate in non-structural applications. Contamination control requirements restrict specification in load-bearing concrete.
Blended cement dominates installed base. Geopolymer cement is where expansion concentrates.
Application:
Volume concentration follows infrastructure spending patterns. Commercial structures impose the most stringent carbon disclosure requirements, while residential applications lag in specification adoption.
- Commercial Structures:High-rise buildings and office complexes in Ho Chi Minh City, Singapore, and Sydney now mandate environmental product declarations for concrete supply. Procurement teams unbundle material contracts from construction management to secure verified low-carbon sources.
- Roads:National highway authorities in India and China specify fly ash cement for pavement and sub-base applications where flexural strength requirements accommodate higher supplementary cementitious material ratios.
- Residential Buildings:Single-family and mid-rise construction relies on conventional ready-mix supply chains with limited green premium absorption. Cost sensitivity slows specification uptake outside subsidy zones.
- Bridges:Structural load requirements and durability exposure classes restrict low-clinker blends in deck and superstructure elements. Carbon capture curing is gaining traction in precast girder production.
Roads anchor current procurement volume. Commercial structures represent the steepest expansion trajectory.
End User:
Contracting sophistication determines technology access. Large infrastructure developers maintain direct supplier relationships, while fragmented construction companies rely on distributor intermediaries.
- Infrastructure Developers:Toll road concessionaires and airport authorities issue performance-based concrete specifications with embodied carbon caps. Technical teams conduct independent mix design validation.
- Government Projects:Public works departments in Vietnam, India, and Indonesia enforce mandatory blended cement quotas for state-funded construction. Procurement rules increasingly reference EU Green Deal taxonomy criteria for international financing eligibility.
- Construction Companies:Mid-tier contractors face working capital constraints that favor conventional Portland cement with established supply terms. Green cement adoption tracks contract bundling with design-build mandates.
- DIY Enthusiasts:Retail bagged cement purchasers show minimal price tolerance for green premiums. Market presence limited to specialty channels in developed urban markets.
Infrastructure developers command specification authority. Government projects concentrate procurement volume.
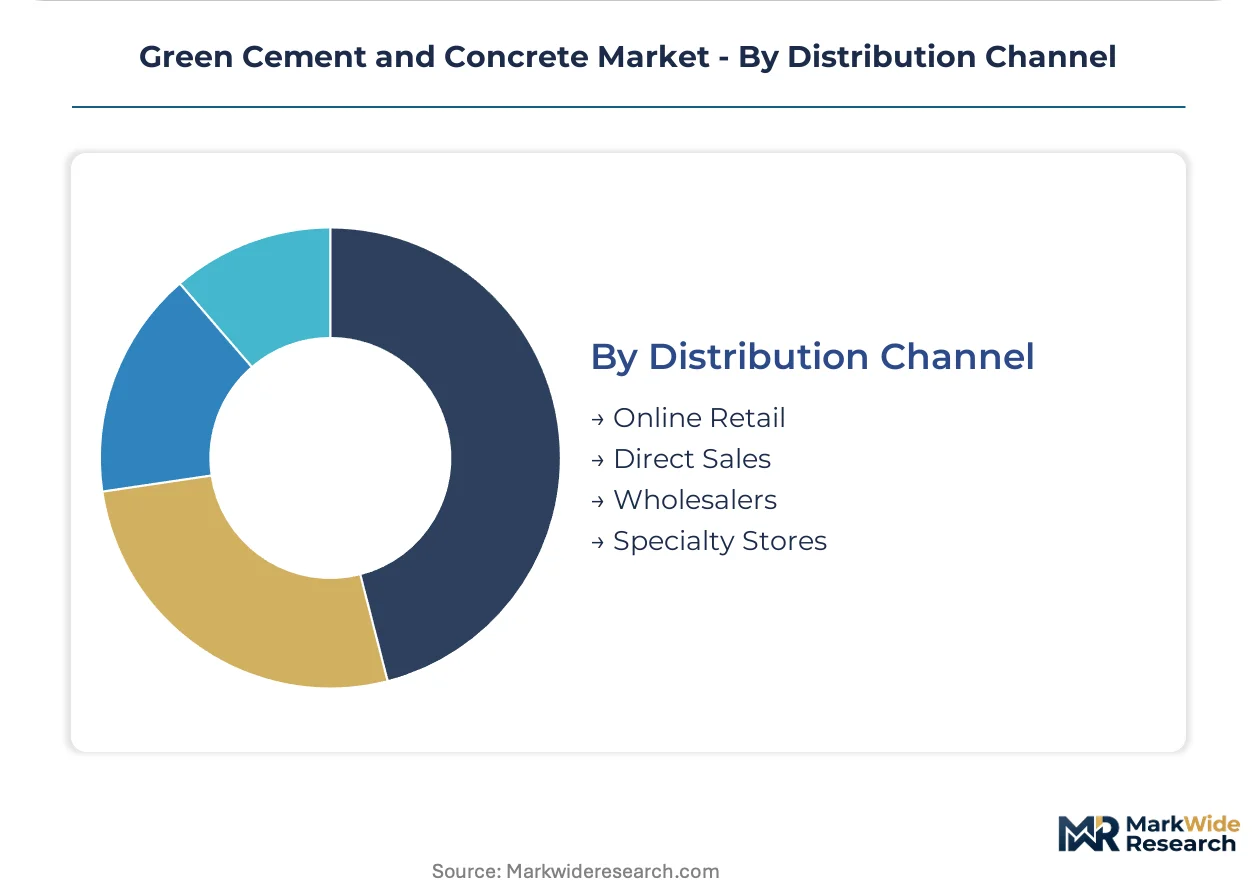
Distribution Channel:
Channel economics reflect batching logistics and technical support requirements. Direct sales capture bulk infrastructure contracts, while wholesalers serve fragmented construction demand.
- Direct Sales:Major producers negotiate multi-year supply agreements with infrastructure developers and ready-mix operators. Contracts include technical service provisions for mix optimization and carbon accounting documentation.
- Wholesalers:Regional distributors aggregate demand from small and mid-sized contractors. Inventory positions favor fast-moving blended cement grades with predictable turnover.
- Specialty Stores:Urban retail outlets in Singapore, Sydney, and Dubai serve architects and sustainable construction consultants with curated low-carbon product portfolios and environmental certification support.
- Online Retail:Digital platforms facilitate specification comparison and carbon disclosure document retrieval. Transaction volume remains constrained by bulk logistics requirements and just-in-time delivery expectations.
Direct sales capture margin. Wholesalers handle throughput.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnamese producers export low-carbon concrete formulations to Singapore and Australian infrastructure projects, establishing a trade-flow corridor that channels Southeast Asian manufacturing capacity into high-specification procurement markets.
China
Provincial infrastructure budgets in Jiangsu and Guangdong prioritize blended cement for high-speed rail expansion. The Ministry of Ecology and Environment enforces dual carbon goals that mandate clinker ratio reductions in state-funded construction. Tianjin's industrial corridor hosts integrated grinding facilities serving Beijing's transit-oriented development projects.
India
National highway authority contracts specify fly ash cement for pavement applications across the Golden Quadrilateral network. BIS certification protocols now require performance-based durability testing rather than prescriptive composition limits. Gujarat's cement belt concentrates slag grinding capacity feeding Mumbai's commercial high-rise construction.
Vietnam
Ho Chi Minh City building codes mandate carbon disclosure for commercial structures exceeding 20,000 square meters. The Ministry of Construction implements green building standards aligned with EU Green Deal taxonomy criteria for international financing access. Northern cement clusters around Hai Phong supply low-clinker blends to Hanoi airport expansion and seaport modernization.
Germany
Federal transport infrastructure plans specify blast furnace slag cement for bridge deck applications where sulfate resistance requirements apply. The EU Green Deal taxonomy determines eligibility for green financing and public tender participation. The Rhine-Ruhr industrial region maintains specialized grinding infrastructure despite declining domestic steel slag availability.
United States
Infrastructure Investment and Jobs Act disbursements prioritize environmental product declaration verification for concrete procurement in California and Texas bridge projects. EPA emissions standards shape state-level low-carbon material specifications. Precast concrete producers in the Pacific Northwest adopt carbon capture curing systems for accelerated girder production cycles.
Green Cement and Concrete Market Vendor Landscape
On the supply side, the industry is consolidating around integrated quarry-to-concrete operators with captive supplementary cementitious material sourcing. Tiered competitive positioning separates multinational building materials conglomerates from regional specialists and technology licensors. Dominant competitive moves include strategic partnerships for carbon capture technology licensing and vertical integration into fly ash and slag supply chains.
Within the multinational tier, Holcim Ltd, HeidelbergCement AG, and CEMEX S.A.B. de C.V. exemplify integrated operators controlling feedstock quality through backward integration into quarry and supplementary material sourcing. These companies occupy positions defined by geographic footprint breadth and grinding infrastructure specialization rather than product differentiation alone.
| Leading Market Players |
|---|
| Holcim Ltd |
| HeidelbergCement AG |
| CEMEX S.A.B. de C.V. |
| CRH plc |
| UltraTech Cement Ltd |
| Anhui Conch Cement Company Limited |
| Taiheiyo Cement Corporation |
| CarbonCure Technologies Inc. |
| Calera Corporation |
| Others |
Supply Flow & Price Mechanics
Overcapacity in China's cement belt compresses export pricing for low-clinker blends while tightening margins for regional producers in Vietnam and Indonesia. Utilization rates below 65 percent in Shandong and Jiangsu provinces force integrated operators to absorb supplementary cementitious material cost volatility rather than pass through to infrastructure tenders.
Pricing Analysis
Conventional Portland cement trades at commodity spot benchmarks while carbon capture cured products command project-based premiums tied to environmental product declaration verification. Pricing stratifies across premium, standard, and economy tiers based on clinker replacement ratios and BIS or EU Green Deal taxonomy compliance grade. Cost compression in standard-grade blended cement is intensifying because fly ash supply chain disruptions in India's thermal power corridor expose margins to fuel price pass-through. Government highway authorities exhibit lowest price sensitivity due to mandated low-carbon procurement quotas, while residential construction companies absorb minimal green premiums outside subsidy zones.
Supply Chain Analysis
Upstream feedstock availability draws from coal combustion residuals in India and China, blast furnace slag in Germany and Poland, and calcined clay deposits in Vietnam and Indonesia. The supply chain rests on clinker, fly ash, ground granulated blast-furnace slag, and alkali activators as core inputs. Single-source vulnerability concentrates in European steel slag as domestic production declines threaten German cement grinding capacity. Distribution runs through direct sales channels for bulk infrastructure contracts and regional wholesalers serving fragmented ready-mix operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
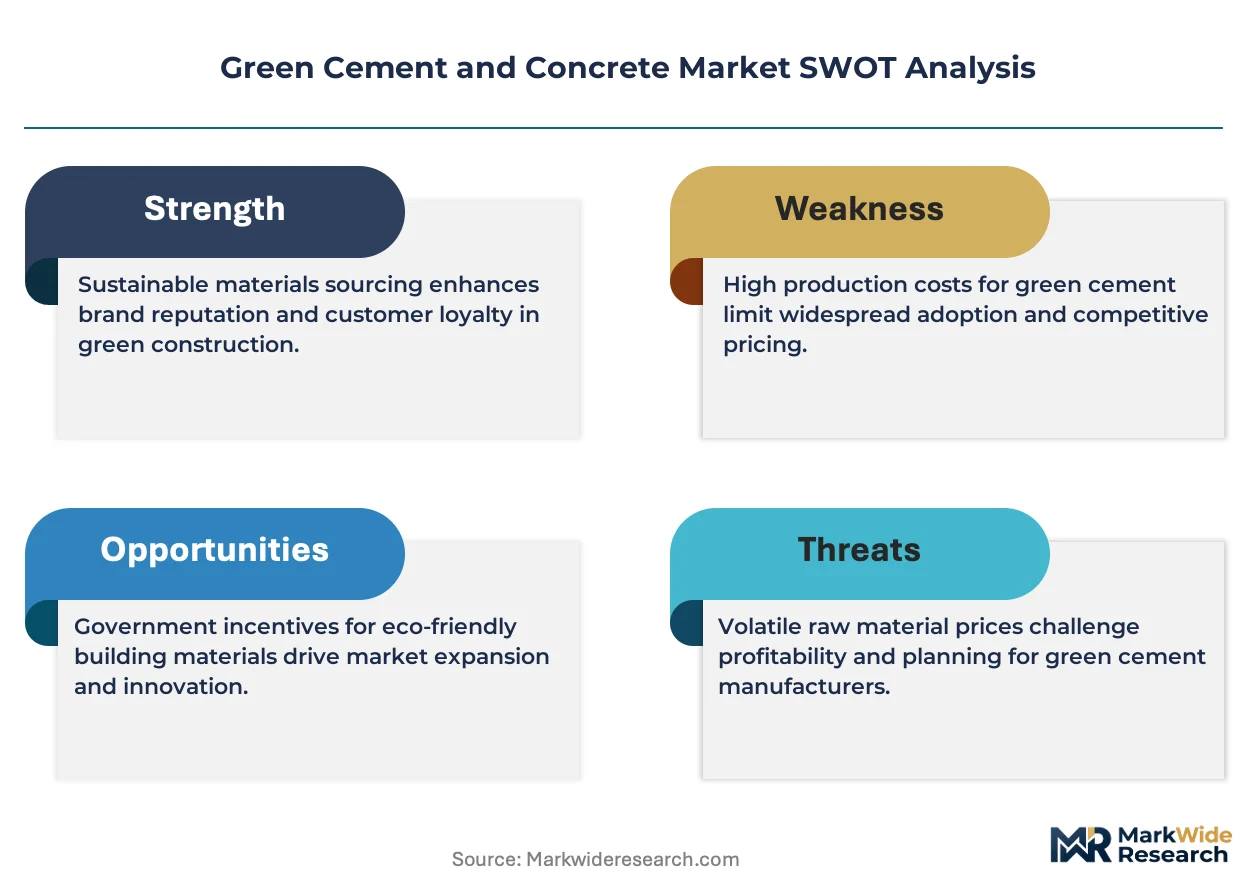
This market functions as a regulatory entrenchment story where BIS certification protocols and EU Green Deal taxonomy criteria create switching costs that cement incumbent positions. Network effects concentrate in integrated quarry-to-concrete operations with captive supplementary material sourcing.
For Market Incumbents: Build regulatory moats through early BIS and EU taxonomy certification investment ahead of mandatory disclosure expansion. Secure backward integration into fly ash and slag supply chains to insulate margins from steel production decline in Europe. Carbon capture technology licensing from specialists like CarbonCure Technologies Inc. represents the critical capability gap threatening operators without R&D partnerships. For New Entrants and Emerging Players: Pursue mobile geopolymer batching systems for Indonesia's rural infrastructure projects outside Java Island where conventional supply chains remain undeveloped. Target carbon capture curing equipment leasing to precast concrete producers in California and Texas seeking accelerated curing cycles without capital commitment. Partner with engineering firms establishing dedicated sustainable materials procurement functions to bypass entrenched ready-mix intermediaries. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among carbon capture technology licensors with equipment-plus-chemistry subscription models rather than commodity cement producers. Long-term viability favors operators with integrated quarry positions and diversified supplementary material sourcing across multiple geographies. Monitor EPA emissions standard threshold revisions and India's BIS protocol expansion as inflection signals for mandatory compliance acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Supplementary Materials | Captive fly ash and slag sourcing insulates Holcim and HeidelbergCement from European steel decline and Indian power sector volatility. |
| Carbon Capture Technology Licensing | Equipment-plus-chemistry subscriptions create recurring revenue streams for technology licensors serving precast infrastructure producers. |
| Performance-Based Certification Investment | Early BIS and EU Green Deal compliance secures eligibility for public tenders as procurement rules shift from voluntary to mandatory. |
| Mobile Batching System Deployment | Containerized geopolymer production enables market entry in Indonesia's underserved outer islands lacking conventional cement supply chains. |
| Direct Procurement Relationship Establishment | Bypassing ready-mix intermediaries captures margin from Singapore and Sydney commercial projects with unbundled material contracts. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade association data, and environmental product declaration databases. Interviews with cement plant operations managers, infrastructure procurement officers at national highway authorities, ready-mix distribution channel partners, and technical directors at carbon capture technology firms informed demand-side validation. Secondary sources include BIS certification records, EU taxonomy compliance disclosures, EPA emissions filings, and customs data on clinker and supplementary cementitious material trade flows. Bottom-up volume modeling triangulates against top-down infrastructure spending projections.
Forecast inputs incorporate product type segmentation across blended cement, fly ash cement, geopolymer cement, and recycled aggregate formulations. Application dimensions model commercial structures, roads, residential buildings, and bridges with distinct technical specifications and carbon disclosure requirements. End-user segmentation captures infrastructure developers, government projects, construction companies, and retail channels with divergent contracting sophistication. CAGRs derive from elasticity modeling against clinker ratio reduction mandates and supplementary material availability curves. Carbon capture curing adoption rates and BIS protocol expansion timelines serve as industry-specific demand shapers across the projection horizon.
Macroeconomic conditions sit as an overlay; deviation in infrastructure spending execution, steel production trajectories affecting slag supply, or natural gas price volatility impacting calcined clay activation costs would shift the trajectory. Forecasts reflect assumptions on regulatory enforcement consistency and technology cost reduction curves. Cross-checking against national cement association production statistics and environmental product declaration registry growth is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Green Building Materials
Outdoor Flooring Market
Green Building Materials
Green Building Market
Green Building Materials
Green Roof Market
Green Building Materials
Green Coatings Market
Green Building Materials
Green Silica Market
Green Building Materials
Asia Pacific Green Cement Market
Green Building Materials
Green Cement Market
Green Building Materials
Global Eco-Friendly Green Roofs Market
Green Building Materials
Green Building Materials Market
Green Building Materials
Green Concrete Market
Green Building Materials
Sustainable Construction Market
Green Building Materials
North America Green Buildings Market
Green Building Materials
China Green Building Materials Market
Green Building Materials
Europe Green Cement Market
Green Building Materials
Green Waterproofing Products Market
Green Building Materials
Energy Efficient Window and Door Market