
 Asia-Pacific Food and Environment Manual Testing Market | 2026-2036
Asia-Pacific Food and Environment Manual Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Food and Environment Manual Testing Market Outlook
Food safety inspection among packaged food manufacturers is consolidating demand toward accredited third-party manual testing providers. SGS leverages its pan-Asian laboratory network to anchor compliance workflows for multinational food brands entering Vietnam and Indonesia. Eurofins Scientific competes through specialized mycotoxin and pesticide residue testing protocols tailored to ASEAN agricultural export requirements. Bureau Veritas sustains market presence by controlling certification pipelines linked to European Union import standards for Thai and Filipino seafood processors.
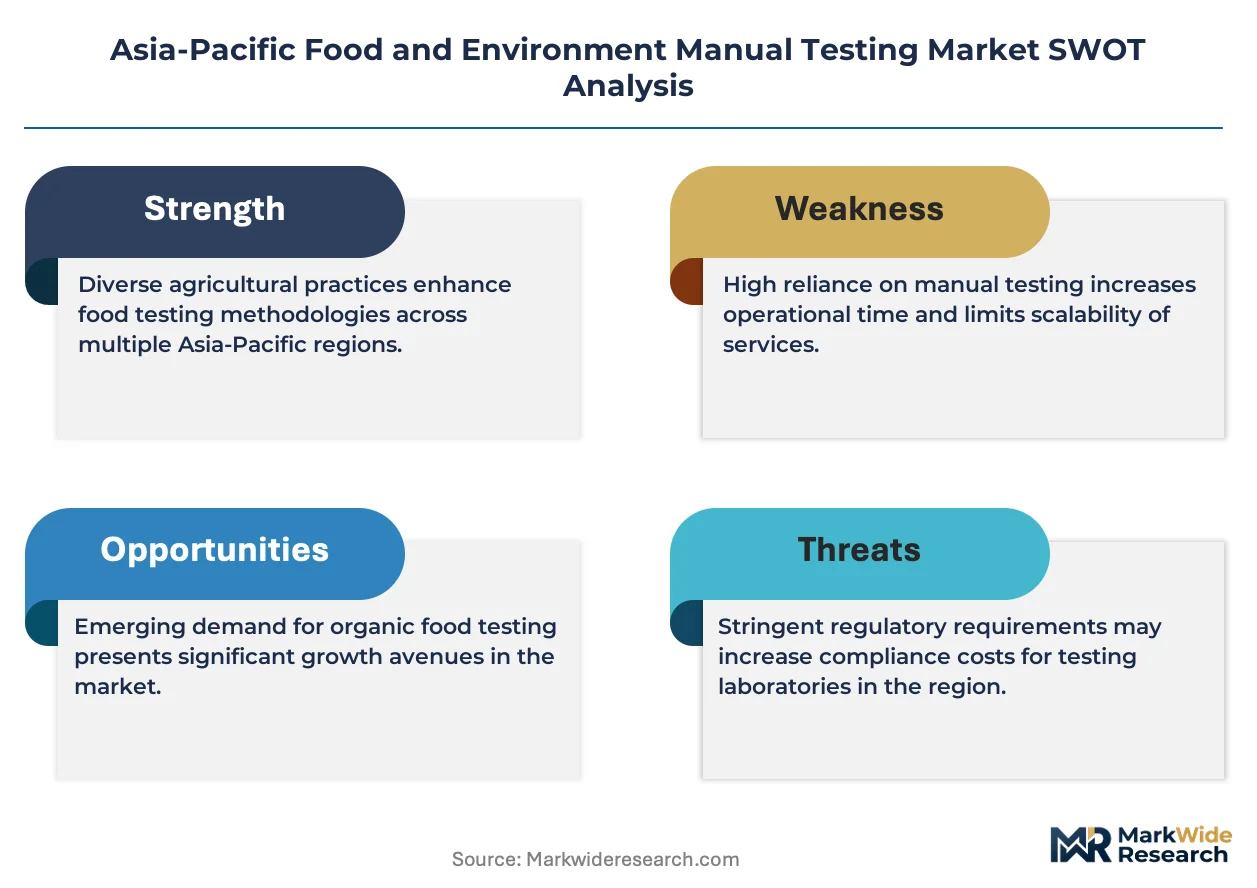
Asia-Pacific Food and Environment Manual Testing encompasses qualitative and quantitative analytical procedures performed without automated instrumentation to detect contaminants, pathogens, and chemical residues in food matrices and environmental samples. Colorimetric analysis using reagent-based visual comparison remains prevalent for field-level water quality and soil pH assessment across rural testing stations. Water quality testing generates the most stable revenue pool due to persistent groundwater monitoring obligations under China's MEE directives and India's CEA mandates. Laboratory analysis commands premium pricing through chain-of-custody documentation required by FSSAI and Japan's Ministry of Health, Labour and Welfare for imported food clearance. Field testing occupies the fastest-expanding segment as agricultural producers in Australia's Murray-Darling Basin and Indonesia's palm oil regions adopt portable manual kits for real-time irrigation and effluent checks.
FSSAI in India, China's MEE, and Japan's Ministry of Health, Labour and Welfare collectively shape product standards through mandatory residue limits and accreditation requirements for manual testing laboratories. REACH-aligned substance restrictions and EU MDR cross-referencing force Asian exporters to maintain dual-compliance manual testing protocols for European-bound food and environmental product shipments. Stakeholders must monitor divergence between India's forthcoming unified food safety code and China's evolving GB standard revisions to avoid stranded testing investments.
Market Dynamics
Accreditation consolidation is compressing vendor margins across Asia-Pacific food and environment manual testing, as FSSAI, China's MEE, and Japan's Ministry of Health, Labour and Welfare tighten laboratory certification requirements and procurement centralizes toward pan-regional providers.
Growth Catalysts
- FSSAI vendor certification mandate:India's street food vendor licensing program generates recurring manual testing volume for pathogen and adulteration screening across urban food corridors.
- ASEAN aquaculture export protocols:European Union import standards for Thai and Vietnamese seafood processors sustain demand for manual histamine and heavy metal verification.
- Portable colorimetric kit adoption:Agricultural producers in Indonesia's palm oil regions deploy field-level reagent-based testing for real-time effluent compliance.
Market Restraints
- Reagent supply concentration:Specialty chemical inputs for chromatographic confirmation concentrate among Japanese and German suppliers, exposing testing laboratories to currency and shipping volatility.
- Skilled technician scarcity:Microbiological plating and gravimetric analysis require certified personnel that India's urban food processing corridors struggle to retain.
- Automated rapid testing substitution:PCR and immunoassay automation threatens manual pathogen detection economics in high-volume Australian dairy and meat operations.
Strategic Opportunities
- Philippine fishery zone penetration:Mindanao and Visayas aquaculture clusters remain underserved for manual antibiotic residue and histamine testing.
- Dual-compliance service bundling:REACH-aligned substance documentation bundled with FSSAI clearance creates premium positioning for exporters to European markets.
- Blockchain-secured chain-of-custody:Distributed ledger integration with manual sampling protocols differentiates accredited laboratories competing for multinational food brand contracts.
Industry Challenges
- Cross-border sample logistics:Temperature-controlled transport of environmental specimens across ASEAN member states faces customs delays and documentation fragmentation.
- Laboratory accreditation timelines:FSSAI and China's MEE certification renewal cycles extend 12-18 months, freezing expansion capacity for mid-tier testing providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Food and Environment Manual Testing Market |
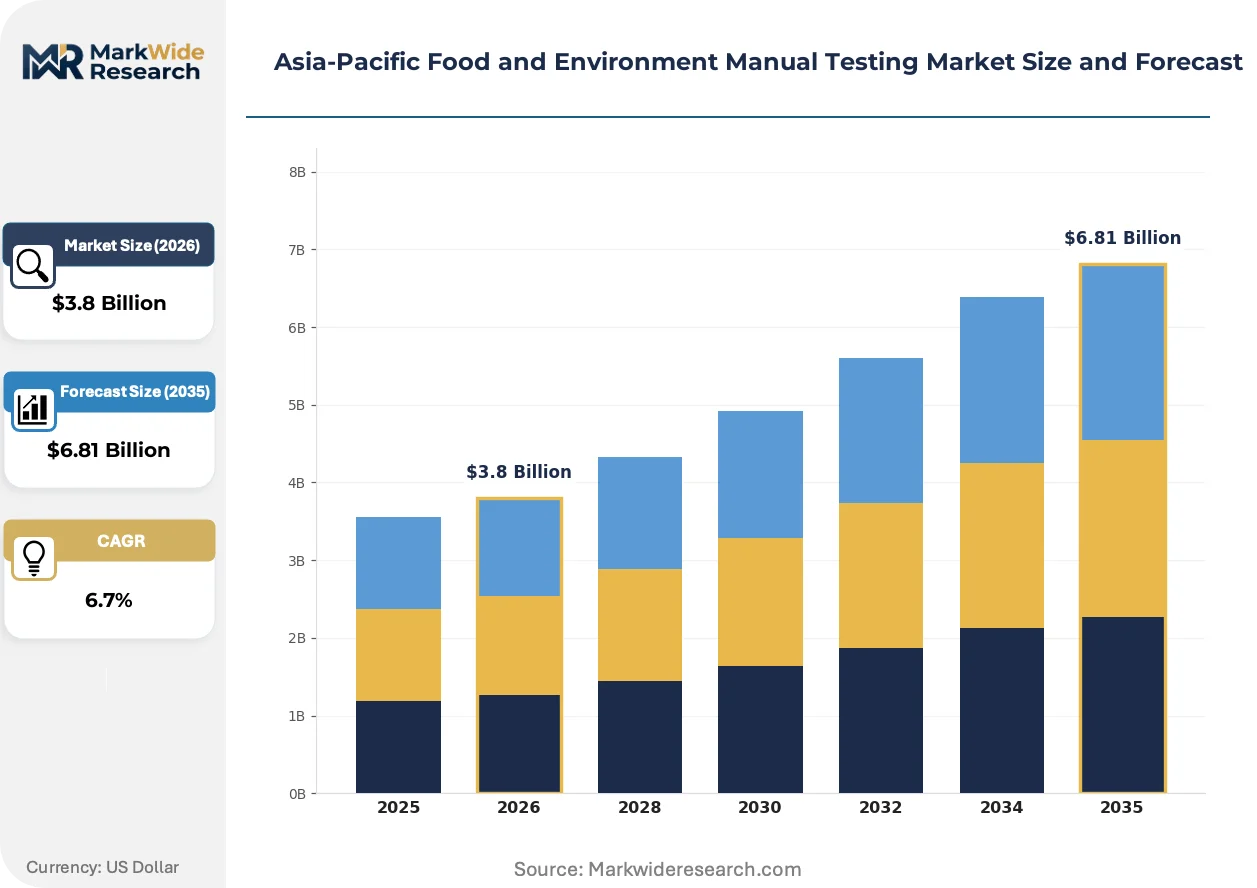
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Water Quality Testing, Soil Analysis, Food Safety Inspection, Pest Control End User: Agricultural Producers, Food Manufacturers, Environmental Agencies, Research Institutions Service Type: Consultative Testing, Field Testing, Laboratory Analysis, Compliance Monitoring Technology: Manual Methods, Visual Inspection, Sampling Techniques, Colorimetric Analysis |
| Companies Covered | Eurofins Scientific, SGS, Intertek Group, Bureau Veritas, Hach, Anton Paar, Mérieux NutriSciences, Thermo Fisher Scientific, Hanna Instruments, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Food and Environment Manual Testing Market Strategic Shifts
Manual testing methodologies are hybridizing with digital documentation and portable chemistry, reshaping how accredited laboratories compete for food safety and environmental compliance contracts across the region.
Microfluidic paper-based analytical devices are converging with smartphone image analysis for semi-quantitative pesticide residue screening. Smallholder cooperatives in Vietnam's Mekong Delta and Thailand's Central Plains adopt these platforms to pre-clear export-bound produce. The convergence is compressing turnaround times from laboratory dispatch to field-level decision-making.
China's MEE is tightening GB standard revision cycles for agricultural runoff and soil contamination thresholds, forcing testing providers to revalidate manual protocols biannually. The industrial consequence is accelerated obsolescence of legacy reagent formulations. Agricultural testing stations in Shandong and Jiangsu provinces face the steepest compliance recertification burdens.
Buyer concentration among multinational food brands is consolidating vendor panels toward dual-accredited providers. Third-party testing contracts that bundled field sampling with laboratory analysis are unbundling as brands internalize sampling logistics. The shift is most visible in Indonesia's packaged food manufacturing corridors around Jakarta and Surabaya.
Asia-Pacific Food and Environment Manual Testing Market Segmentation
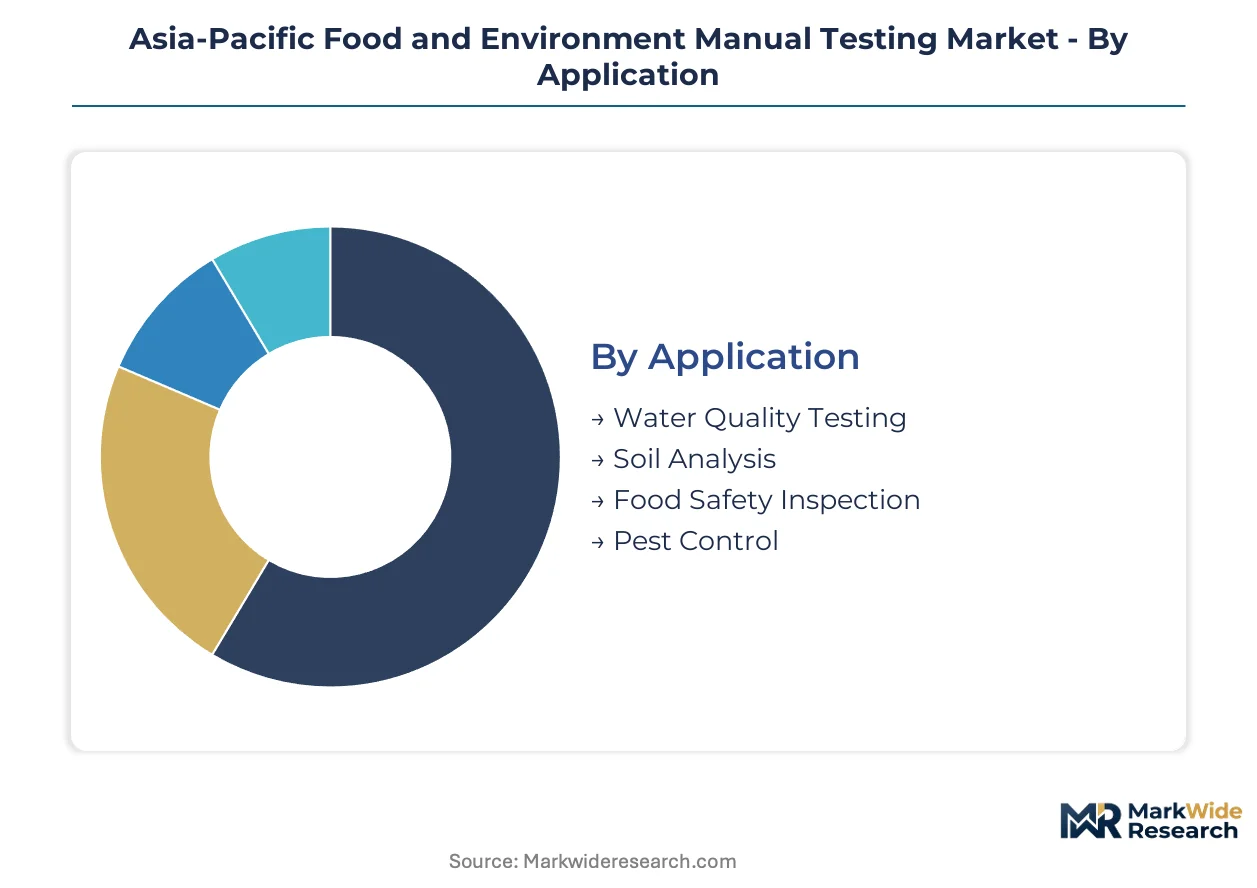
Manual testing procurement across Asia-Pacific food and environment compliance workflows fragments across four distinct category systems. Each dimension reveals different concentration patterns: application type governs regulatory urgency, end-user structure dictates pricing power, service modality determines margin capture, and technology base shapes workforce requirements.
Application:
Supply concentration in reagent manufacturing and certified laboratory capacity tilts revenue capture toward testing categories with the most stable regulatory mandates.
- Water Quality Testing:Groundwater monitoring obligations under China's MEE directives and India's CEA mandates sustain recurring demand for pH, dissolved oxygen, and heavy metal screening. Municipal water authorities in Vietnam's Mekong Delta and Indonesia's Java corridor represent the densest procurement clusters for third-party manual verification.
- Food Safety Inspection:Pathogen detection and adulteration screening for packaged food manufacturers and street food vendors drives volume under India's FSSAI certification requirements. Urban food processing corridors around Mumbai, Delhi, and Bangkok concentrate procurement toward accredited third-party providers.
- Soil Analysis:Agricultural runoff compliance under evolving GB standards in China's Shandong and Jiangsu provinces generates seasonal demand spikes for nutrient and contaminant profiling.
- Pest Control:Residue testing for pesticide application verification serves palm oil and rice cultivation zones across Malaysia and Thailand with lower testing frequency.
Today's leader: Water Quality Testing. Tomorrow's challenger: Food Safety Inspection.
End User:
Cost tier differentiation separates high-volume routine screening from premium-priced forensic and research-grade analysis.
- Food Manufacturers:Packaged food producers across Vietnam and Indonesia consolidate vendor panels toward dual-accredited providers capable of FSSAI clearance and REACH-aligned documentation. Procurement centralization among multinational brands compresses margins for mid-tier laboratories.
- Agricultural Producers:Smallholder cooperatives in Thailand's Central Plains and Indonesia's palm oil regions adopt portable colorimetric kits for real-time field decision-making, bypassing laboratory dispatch costs.
- Environmental Agencies:China's MEE and India's state pollution control boards anchor stable contract volumes for groundwater and effluent monitoring networks.
- Research Institutions:Universities and agricultural extension services in Australia and Japan purchase method development and validation services at premium pricing.
Food Manufacturers command current volume. Agricultural Producers are expanding most quickly as field kit adoption accelerates.
Service Type:
Geography of demand execution—field versus laboratory—determines margin structure and workforce deployment models.
- Laboratory Analysis:Chain-of-custody documentation required by FSSAI and Japan's Ministry of Health, Labour and Welfare for imported food clearance supports premium pricing. Pan-Asian laboratory networks capture multinational brand contracts through accreditation density.
- Field Testing:Portable manual kit deployment across Australia's Murray-Darling Basin and Indonesia's palm oil regions enables real-time irrigation and effluent compliance checks without specimen transport.
- Compliance Monitoring:Recurring audit and certification services for ASEAN aquaculture exporters to European Union standards sustain retainer-based revenue.
- Consultative Testing:Method selection and protocol design for new contaminant categories under GB standard revisions commands project-based fees.
Laboratory Analysis holds revenue concentration. Field Testing is gaining share fastest through kit portability improvements.
Technology:
Customer type—certified technician versus trained operator—segregates service delivery and pricing tiers.
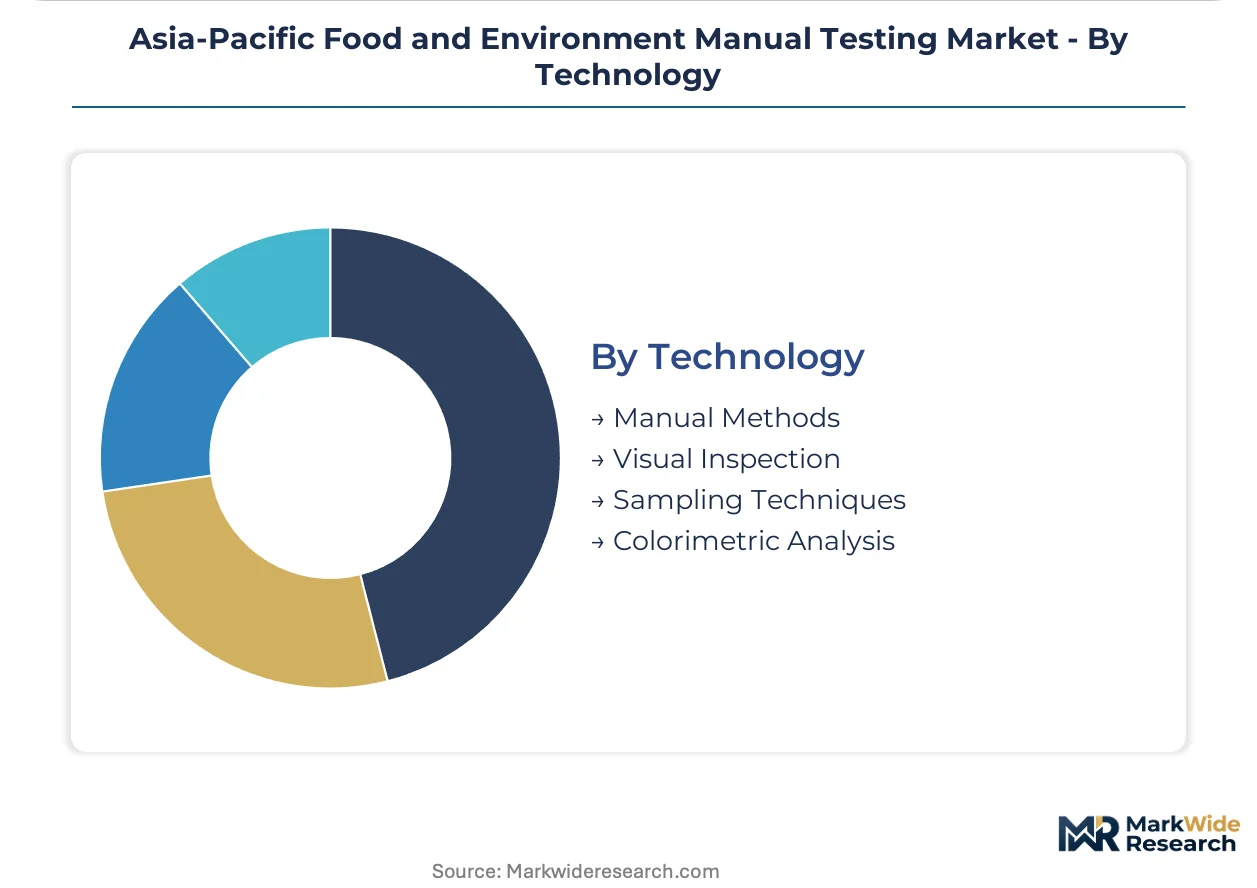
- Colorimetric Analysis:Reagent-based visual comparison dominates field-level water quality and soil pH assessment across rural testing stations in India and Southeast Asia due to minimal equipment requirements.
- Manual Methods:Microbiological plating and gravimetric analysis remain cost-effective for small-batch operations in aquaculture export zones where pathogen detection volume does not justify automation.
- Sampling Techniques:Chain-of-custody protocol execution for regulatory submission requires certified personnel and documentation systems.
- Visual Inspection:Preliminary screening for physical contaminants and packaging integrity serves as a low-cost entry point for informal sector food vendors.
Colorimetric Analysis anchors accessibility. Manual Methods face steepest substitution pressure from PCR automation in high-volume Australian dairy operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping testing demand as food processors migrate toward jurisdictions with lower compliance costs but rising enforcement standards. Cost-of-compliance gaps between mature and emerging markets within the region are narrowing as FSSAI, MEE, and ASEAN regulators synchronize accreditation requirements.
India
Street food vendor certification under FSSAI mandates and packaged food export protocols drive manual testing volume across Mumbai and Delhi corridors. The CEA groundwater monitoring directives sustain municipal contract flows for pH and heavy metal screening. Urban food processing clusters in Maharashtra and Gujarat concentrate procurement toward accredited third-party laboratories capable of dual FSSAI-EU documentation.
China
GB standard revisions for agricultural runoff and soil contamination force biannual protocol revalidation across Shandong and Jiangsu testing stations. MEE directives on groundwater quality anchor stable demand for dissolved oxygen and effluent monitoring networks. Agricultural producers in the Yangtze River Delta adopt portable colorimetric kits to bypass laboratory dispatch delays for real-time compliance decisions.
Indonesia
Palm oil plantation effluent monitoring and packaged food manufacturing consolidation in Jakarta-Surabaya corridors expand field testing adoption. Smallholder cooperatives in Sumatra deploy reagent-based kits for irrigation water checks without specimen transport costs. Multinational food brands internalize sampling logistics while unbundling laboratory analysis contracts toward dual-accredited providers.
Vietnam
Mekong Delta aquaculture export protocols to European Union standards sustain manual histamine and antibiotic residue verification demand. Microfluidic paper-based analytical devices with smartphone integration compress turnaround times for smallholder produce pre-clearance. Ho Chi Minh City-based testing laboratories capture pan-ASEAN contracts through FSSAI-REACH dual compliance bundling.
Australia
Murray-Darling Basin irrigation water quality mandates and dairy export certification sustain premium-priced chain-of-custody documentation. PCR automation threatens manual pathogen detection economics in high-volume meat operations, compressing mid-tier laboratory margins. Field testing growth concentrates in Western Australia mining corridor environmental monitoring where portable manual kits serve remote site compliance.
Asia-Pacific Food and Environment Manual Testing Market Competitive Environment
Accreditation consolidation dominates the current landscape as pan-regional providers absorb mid-tier laboratories facing FSSAI and MEE certification renewal bottlenecks. The vendor base stratifies into three tiers: multinational networks with 10+ accredited facilities, national specialists controlling single-country certification pipelines, and field-kit distributors serving agricultural cooperatives. Strategic archetypes include compliance bundlers, geographic consolidators, and technology hybridizers. M&A activity and certification capacity expansion represent the dominant competitive vectors as procurement centralizes toward vendors with dual FSSAI-EU accreditation density.
Within the multinational network tier, SGS leverages its pan-Asian laboratory footprint to anchor compliance workflows for brands entering Vietnam and Indonesia. Eurofins Scientific and Bureau Veritas occupy positions as specialized protocol providers, with the former representing mycotoxin and pesticide residue archetypes and the latter exemplifying EU import certification linkage for Thai and Filipino seafood processors. These three entities collectively illustrate how accreditation density translates into vendor panel consolidation among multinational food manufacturers.
| Leading Market Players |
|---|
| Eurofins Scientific |
| SGS |
| Intertek Group |
| Bureau Veritas |
| Hach |
| Anton Paar |
| Mérieux NutriSciences |
| Thermo Fisher Scientific |
| Hanna Instruments |
| Others |
Value Chain & Pricing Dynamics
Multinational food brand procurement centralization in Indonesia's Jakarta-Surabaya corridors enforces contract-based long-term offtake pricing with volume-scaled discounts. Laboratory service unbundling compresses margins for standalone field testing providers while dual-accredited pan-Asian networks capture premium chain-of-custody documentation fees.
Pricing Analysis
Distributor margins on Japanese and German specialty reagents absorb 15-25% of laboratory input costs before chromatographic confirmation services reach testing facilities. Three-tier pricing structure across premium, standard, and economy levels separates FSSAI-EU dual-accredited providers from single-jurisdiction laboratories and informal field-kit operators. Cost compression in standard-tier microbiological plating intensifies because PCR automation threatens economics in Australian high-volume dairy operations. Agricultural cooperatives in Indonesia's palm oil regions exhibit highest price sensitivity, while Japan's Ministry of Health, Labour and Welfare import clearance mandates render premium-tier buyers relatively inelastic.
Supply Chain Analysis
Returns of expired reagent batches and refurbishment of portable colorimetric kits flow through Singapore and Hong Kong logistics hubs before reconditioning at original Japanese and German manufacturing sites. Specialty chemical inputs for chromatographic confirmation concentrate among Japanese and German suppliers, with Indian and Vietnamese laboratories drawing from these concentrated sources. Single-source vulnerability in high-purity reagent manufacturing exposes testing networks to currency and shipping volatility. Distribution runs through pan-Asian laboratory networks for multinational brand contracts, while agricultural cooperatives source field kits through regional distributor partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where FSSAI certification timelines in India extend 12-18 months versus China's accelerating GB standard revision cycles, creating divergent compliance cost structures for cross-border testing providers.
For Market Incumbents: Anticipate PCR automation displacement in Australian dairy and meat operations by accelerating portable colorimetric kit hybridization with smartphone documentation platforms. Secure backward integration into reagent formulation through partnerships with Japanese specialty chemical suppliers to defend margin position against currency volatility exposure. Certification pipeline control in Vietnam and Indonesia remains the priority defensive lever against emerging pan-Asian network competitors. For New Entrants and Emerging Players: The premium-economy price-point gap in Philippine fishery zones creates white-space entry opportunity for antibiotic residue and histamine testing services. Mindanao and Visayas aquaculture clusters remain underserved relative to Thai and Vietnamese export corridors. Deploy microfluidic paper-based analytical devices with smartphone integration as the go-to-market angle to compress turnaround times against established laboratory dispatch models. For Investors and Strategic Acquirers: Pan-Asian food safety conglomerates are the most active acquirer in this space, consolidating mid-tier laboratories facing FSSAI and MEE certification renewal bottlenecks. Long-term viability over a 5-10 year window hinges on dual-accreditation density as procurement centralizes. Target acquisition archetype: national specialists controlling single-country certification pipelines with demonstrated FSSAI or MEE renewal track records. Monitor divergence between India's forthcoming unified food safety code and China's evolving GB standard revisions as the critical inflection signal for stranded testing investment risk.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Accreditation Capacity Expansion | FSSAI-EU bundled compliance captures multinational brand vendor panel consolidation in Vietnam and Indonesia. |
| Blockchain Chain-of-Custody Integration | Distributed ledger documentation differentiates accredited laboratories competing for Japanese Ministry of Health, Labour and Welfare import clearance contracts. |
| Microfluidic Field Kit Deployment | Smartphone-integrated paper-based devices compress turnaround times for Mekong Delta smallholder produce pre-clearance. |
| Reagent Supply Backward Integration | Upstream control over Japanese and German specialty chemical inputs mitigates currency and shipping volatility exposure. |
| Philippine Fishery Zone Penetration | Mindanao and Visayas aquaculture clusters remain underserved for manual antibiotic residue and histamine verification. |
Study Parameters
Bottom-up food manufacturer and agricultural producer modeling reconciled against top-down accredited laboratory capacity tracking forms the analytical core of this study. Primary interviews with FSSAI certification officers, MEE groundwater monitoring directors, third-party testing laboratory managers, and multinational food brand procurement heads combined with secondary validation against GB standard revision filings, ASEAN aquaculture export protocol documentation, and India's CEA groundwater monitoring directives. Trade data on specialty reagent imports and pan-Asian laboratory network expansion announcements provided supply-side triangulation against end-use demand signals.
Historical trendline analysis of manual testing contract values across the projection horizon informed base-year calibration and growth trajectory assumptions. Segmentation dimensions modeled include application type, end-user structure, service modality, and technology base, with additional granularity on regulatory jurisdiction clustering. CAGRs were derived through driver elasticity analysis against accreditation mandate expansion rates and field kit adoption curves. Forecast inputs incorporated FSSAI vendor certification program rollout timelines and China's MEE GB standard revision frequency.
Caveats apply where accelerated PCR automation adoption or unanticipated FSSAI-MEE regulatory divergence could materially shift the outlook. Practitioners should monitor blockchain documentation integration rates among accredited laboratories and Philippine fishery zone regulatory enforcement intensity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Monitoring
Food Security Technology Market
Environmental Monitoring
Ecotoxicological Studies Market
Environmental Monitoring
End-Of-Pipe Air Pollution Control Equipment Market
Environmental Monitoring
Global Cloud Seeding Equipment Market
Environmental Monitoring
Industrial Site Carbon Footprint Verification and Metering Test Equipment Market
Environmental Monitoring
Radon Gas Test Kits Market
Environmental Monitoring
Environmental Hazard Monitoring (EHM) Software Market
Environmental Monitoring
Global on-Line Total Organic Carbon (TOC) Analyzer Market
Environmental Monitoring
Environment Monitoring Devices Market
Environmental Monitoring
Asia-Pacific Cloud Seeding Market
Environmental Monitoring
United States Erosion Sediment Control Market
Environmental Monitoring
Environmental Test Equipment Market
Environmental Monitoring
Canada Cloud Seeding Market
Environmental Monitoring
Water Quality Monitoring Systems Market
Environmental Monitoring
Quality Monitoring Sensor for Water Market
Environmental Monitoring
Biofuel Testing Services Market