
 End-Of-Pipe Air Pollution Control Equipment Market | 2026-2036
End-Of-Pipe Air Pollution Control Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
End-Of-Pipe Air Pollution Control Equipment Market Analysis
Aftermarket service revenue is reconfiguring margin pools across the End-Of-Pipe Air Pollution Control Equipment landscape. FLSmidth leverages its global installed base to capture recurring maintenance contracts for scrubber rebuilds. Babcock & Wilcox Enterprises anchors North American utility retrofit demand through specialized precipitator upgrade programs. Valmet competes in pulp and paper emission control with integrated wet scrubbing solutions that extend equipment lifecycle value.
End-of-pipe air pollution control equipment encompasses terminal treatment systems installed downstream of industrial processes to capture particulate matter, acid gases, heavy metals, and volatile organic compounds before stack release, typically operating at temperatures between 120°C and 350°C with removal efficiencies exceeding 99% for fine particulates. Electrostatic precipitators dominate power generation retrofit budgets due to their handling capacity for high-volume flue gas streams, while wet scrubbing technology leads chemical manufacturing applications where simultaneous SOx and particulate removal proves essential. Dry scrubbing systems gain share in waste incineration as operators seek reduced wastewater discharge burdens.
The US EPA Mercury and Air Toxics Standards and China's MEE ultra-low emission directives compel continuous upgrades to precipitator and scrubber performance thresholds. India's CPCB mandates for thermal power plants enforce specific particulate concentration limits that drive electrostatic precipitator rebuild cycles. Stakeholders must monitor regulatory calibration timelines across multiple jurisdictions to align capital deployment with compliance windows.
Market Dynamics
Retrofit cycles in coal-fired power generation are compressing as utilities race to meet mercury and particulate standards ahead of permit renewal deadlines, forcing simultaneous precipitator and scrubber upgrade decisions that vendors must bundle to capture.
Growth Catalysts
- US EPA Mercury and Air Toxics Standards:Coal plant operators face binding compliance timelines that trigger precipitator rebuild contracts and wet scrubber installations across the Midwest and Southeast utility corridors.
- Steel sector wet electrostatic precipitator demand:China's MEE enforcement of ultra-low emission targets for sintering and pelletizing plants drives replacement of dry systems with multi-field wet ESP configurations.
- Refinery sulfur recovery integration:India's CPCB mandates for particulate concentration limits at thermal power and refinery complexes in Gujarat and Maharashtra accelerate combined SOx-particulate control procurement.
Market Restraints
- High-alloy steel price volatility:Superaustenitic stainless grades for scrubber vessels and precipitator electrodes face nickel and molybdenum cost swings that compress fabricator margins on fixed-price EPC contracts.
- Specialized refractory supply concentration:Acid-resistant brick and ceramic lining materials for high-temperature scrubbers concentrate among German and Japanese suppliers, creating procurement bottlenecks.
- Baghouse temperature limitations:Dry filtration media degrade above 260°C, excluding the technology from cement kiln and non-ferrous smelter applications where wet scrubbing dominates despite higher water use.
Strategic Opportunities
- Indonesia nickel processing corridor:Smelter construction for battery-grade nickel creates first-mover openings for integrated acid gas and particulate control systems ahead of forthcoming emission regulations.
- Waste-to-energy dry scrubbing conversion:European incinerator operators seek reduced wastewater discharge burdens, favoring semi-dry lime injection systems over wet scrubbing for flue gas neutralization.
- Digital twin predictive maintenance:Vibration and corona current monitoring systems enable remote precipitator performance optimization, shifting revenue from hardware to recurring diagnostics subscriptions.
Industry Challenges
- High-voltage power supply commissioning:Precipitator transformer-rectifier system startup requires specialized electrical engineers in short supply across Southeast Asian project sites.
- Legacy DCS integration complexity:Modern scrubber control algorithms must interface with decades-old distributed control systems at US and European power plants, extending commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | End-Of-Pipe Air Pollution Control Equipment Market |
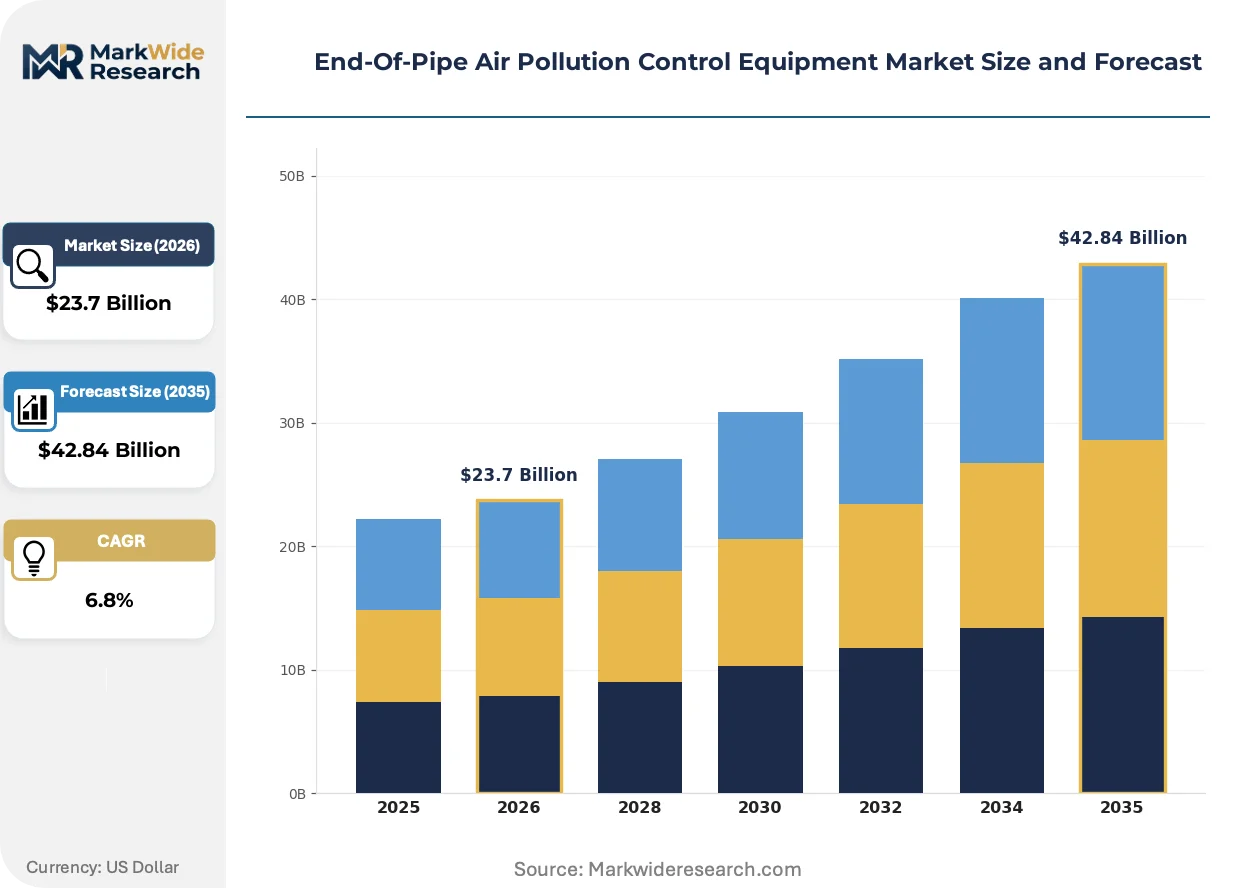
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $42.84 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Scrubbers, Filters, Cyclones, Electrostatic Precipitators Technology: Wet Scrubbing, Dry Scrubbing, Adsorption, Oxidation Application: Industrial Processes, Waste Incineration, Power Generation, Chemical Manufacturing End User: Manufacturing, Energy, Construction, Mining |
| Companies Covered | AAF International, Alstom SA, FLSmidth, Hosokawa Micron Group, Termokimik Corporation, Fisia Babcock Environment GmbH, Valmet, Babcock & Wilcox Enterprises, Wood Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
End-Of-Pipe Air Pollution Control Equipment Market Emerging Trajectories
Equipment architectures are fragmenting between modular skid-mounted systems for new industrial plants and bespoke retrofit configurations for existing utility infrastructure, forcing vendors to maintain dual engineering competencies.
Pulse-jet fabric filtration is migrating from standard needle-felt media to membrane-laminated configurations that achieve sub-10 mg/Nm³ particulate emissions without downstream polishing stages. Cement producers in Germany and Poland are adopting these systems for kiln bypass and clinker cooler exhaust. The technology is compressing demand for electrostatic precipitators in mid-size industrial applications where space constraints favor compact baghouse footprints.
China's MEE ultra-low emission directives now mandate particulate concentrations below 10 mg/Nm³ for steel, cement, and power sectors, a threshold that requires precipitator upgrades to five or six field configurations or hybrid ESP-fabric filter arrangements. Sintering plants in Hebei and Shandong provinces are retrofitting wet ESPs as final polishing stages. Equipment suppliers are reconfiguring project teams to manage the surge in Chinese steel sector procurement.
Power utilities are unbundling aftermarket service contracts from original equipment procurement, creating standalone multi-year maintenance agreements for precipitator rappers, scrubber recirculation pumps, and continuous emission monitoring systems. This shift fragments vendor relationships and opens entry points for specialized service contractors in the US Midwest and Indian thermal power corridors. Procurement teams now evaluate lifecycle service cost separately from capital expenditure in tender evaluations.
End-Of-Pipe Air Pollution Control Equipment Market Segmentation
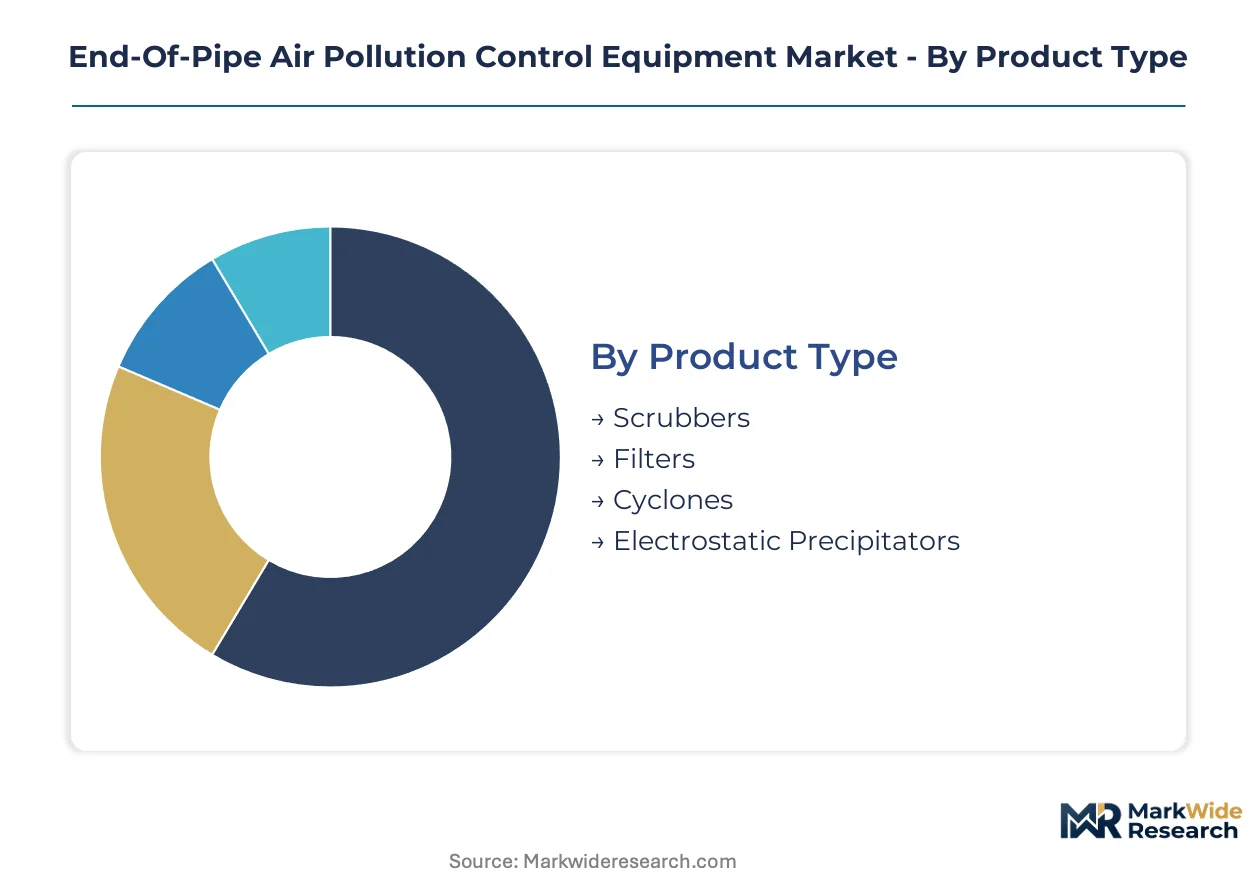
End-of-pipe equipment selection hinges on flue gas temperature, contaminant loading, and regulatory stringency. Procurement teams evaluate capital cost against removal efficiency trade-offs across particulate, acid gas, and heavy metal control requirements. Segmentation reveals where wet versus dry architectures dominate and which industrial verticals drive replacement cycles.
Product Type:
Use-case spectrum spans high-temperature metallurgical off-gas to low-temperature chemical process venting, with each product category optimized for specific particle size distribution and gas chemistry.
- Electrostatic Precipitators:High-voltage ionization fields capture sub-micron particulates in high-volume flue gas streams above 120°C. Coal-fired utilities in India's Gujarat and Maharashtra states deploy five-field configurations to meet CPCB particulate limits, with rebuild cycles accelerating as permit deadlines compress.
- Scrubbers:Liquid-phase absorption systems neutralize acid gases and entrain particulates through venturi or packed-bed contactors. China's steel sector in Hebei province installs wet scrubbers ahead of wet ESP polishing stages to achieve MEE ultra-low emission targets for sintering operations.
- Filters:Fabric media barrier systems operate below 260°C with pulse-jet cleaning for dust cake removal. Membrane-laminated configurations achieve sub-10 mg/Nm³ emissions in German cement kiln bypass applications where space constraints exclude precipitator footprints.
- Cyclones:Centrifugal separation removes coarse particulates above 10 microns as pre-treatment stages. Mining operations in Australia's Pilbara region deploy cyclones upstream of baghouses to reduce filter loading and extend media life in iron ore processing.
Established volume favors electrostatic precipitators; emerging adoption favors membrane-laminated filters.
Technology:
Cost tier differentiation separates water-intensive systems from dry alternatives where discharge constraints dominate project economics.
- Wet Scrubbing:Liquid reagent contact achieves simultaneous SOx and particulate removal with 99%+ efficiency for fine aerosols. Refinery complexes in India's industrial corridor specify wet scrubbing for integrated sulfur recovery and particulate control under tightening CPCB mandates.
- Dry Scrubbing:Semi-dry lime injection systems neutralize acid gases without wastewater generation. European waste-to-energy operators in Poland and Germany convert from wet to dry scrubbing to eliminate effluent treatment burdens and simplify residue handling.
- Adsorption:Activated carbon or zeolite media capture volatile organic compounds and mercury vapor. Activated carbon injection systems in US Midwest coal plants satisfy EPA Mercury and Air Toxics Standards ahead of compliance deadlines.
- Oxidation:Thermal or catalytic processes destroy VOCs and hazardous air pollutants through combustion. Chemical manufacturing facilities in Germany's Rhine-Ruhr region deploy regenerative thermal oxidizers for solvent-laden process vents.
Water-scarce geographies drive dry scrubbing preference; multi-pollutant mandates sustain wet scrubbing dominance in power and metals.
Application:
Customer type segmentation distinguishes utility capital budgets from industrial operating expenditure constraints and compliance timelines.
- Power Generation:Coal and biomass combustion drives the largest installed base with simultaneous precipitator and scrubber upgrade requirements. US Southeast utilities bundle retrofit contracts to meet EPA MATS permit renewal windows, compressing vendor delivery schedules.
- Industrial Processes:Cement, steel, and non-ferrous smelting operations require high-temperature compatibility and abrasive dust handling. China's cement sector in Shandong province retrofits hybrid ESP-fabric filter arrangements to satisfy MEE particulate thresholds below 10 mg/Nm³.
- Chemical Manufacturing:Acid gas and toxic vapor control demands corrosion-resistant materials and integrated safety systems. India's Gujarat chemical cluster procures combined wet scrubbing and oxidation systems for chlor-alkali and pesticide production facilities.
- Waste Incineration:Flue gas from municipal and hazardous waste contains dioxins, furans, and heavy metals requiring multi-stage treatment. European operators prioritize dry scrubbing conversions to reduce wastewater discharge and simplify residue classification.
Utility retrofit cycles concentrate near-term revenue; industrial process expansion drives long-term capacity additions.
End User:
Maturity gradient separates regulated utility procurement from discretionary industrial investment subject to commodity price cycles.
- Energy:Power utilities and refineries operate under binding emission permits with defined compliance timelines. India's thermal power sector in Maharashtra state accelerates precipitator rebuilds as CPCB enforcement tightens particulate concentration limits.
- Manufacturing:Steel, cement, and chemical producers balance environmental compliance against production cost competitiveness. China's steel sector in Hebei province leads wet ESP adoption as MEE ultra-low emission directives eliminate grandfathered emission allowances.
- Construction:Cement and building materials production generates kiln dust and combustion emissions requiring high-temperature control. German cement producers adopt membrane-laminated baghouses for clinker cooler exhaust where precipitator retrofits prove spatially constrained.
- Mining:Mineral processing and smelting operations generate metal-laden dust and sulfur dioxide requiring robust materials handling. Indonesia's nickel processing corridor creates first-mover demand for integrated acid gas and particulate control ahead of forthcoming emission regulations.
Regulated energy sector anchors replacement demand; mining expansion in battery material corridors offers emerging growth vectors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. Indian procurement teams prioritize capital expenditure minimization for precipitator rebuilds, while German operators accept lifecycle cost premiums for integrated scrubber maintenance contracts.
United States
Midwest and Southeast utility corridors drive precipitator and scrubber retrofit bundling. EPA Mercury and Air Toxics Standards compel coal plant operators to meet binding compliance timelines ahead of permit renewals. Ohio River Valley power clusters compress vendor delivery schedules for simultaneous multi-pollutant control upgrades.
China
Hebei and Shandong steel provinces accelerate wet electrostatic precipitator installations. MEE ultra-low emission mandates eliminate grandfathered allowances for sintering and pelletizing operations. Sintering plants in Tangshan retrofit multi-field wet ESP configurations as final polishing stages.
India
Gujarat and Maharashtra industrial corridors concentrate thermal power and refinery procurement. CPCB particulate concentration limits enforce specific rebuild cycles for five-field precipitator configurations. Mundra and Hazira port-adjacent complexes drive combined SOx-particulate control system demand.
Germany
Rhine-Ruhr chemical manufacturers and cement producers anchor high-specification scrubber demand. ECHA REACH compliance and EU Industrial Emissions Directive thresholds sustain premium equipment procurement. Bavarian cement kilns adopt membrane-laminated baghouses where spatial constraints exclude precipitator retrofits.
Indonesia
Maluku and Sulawesi nickel processing corridors create first-mover openings for integrated acid gas control. Forthcoming emission regulations ahead of battery-grade smelter construction drive preemptive procurement. Morowali Industrial Park operators specify combined particulate and sulfur dioxide capture systems.
End-Of-Pipe Air Pollution Control Equipment Market Vendor Landscape
Engineering conglomerates and specialized fabricators split the market between bundled utility retrofits and modular industrial installations. The vendor base concentrates among European and North American incumbents with legacy precipitator expertise, while Asian challengers capture greenfield smelter and cement contracts. Two archetypes dominate: full-service EPC providers with integrated aftermarket arms, and technology licensors partnering with regional construction firms. Competitive moves center on unbundling service contracts from original equipment sales and forming consortium bids for multi-site utility frameworks.
Among European engineering groups, FLSmidth and Valmet occupy positions emphasizing lifecycle service revenue from installed base maintenance. FLSmidth leverages global precipitator and scrubber footprints to capture recurring rebuild contracts. Valmet competes through integrated wet scrubbing solutions targeting pulp and paper emission control. Babcock & Wilcox Enterprises anchors North American utility demand via specialized precipitator upgrade programs, representing the incumbent EPC archetype with deep utility relationships.
| Leading Market Players |
|---|
| AAF International |
| Alstom SA |
| FLSmidth |
| Hosokawa Micron Group |
| Termokimik Corporation |
| Fisia Babcock Environment GmbH |
| Valmet |
| Babcock & Wilcox Enterprises |
| Wood Plc |
| Others |
Supply Flow & Price Mechanics
Nickel and molybdenum cost volatility in superaustenitic stainless grades compresses fabricator margins on fixed-price EPC contracts while simultaneously widening the spread between premium alloy-specified systems and standard carbon-steel alternatives. This raw-material risk vector forces procurement teams to index long-term service contracts against London Metal Exchange pricing bands, reshaping how vendors structure bundled hardware-aftermarket offerings across utility and industrial buyer segments.
Pricing Analysis
Aftermarket service revenue tiers—spanning rapper rebuilds, transformer-rectifier overhauls, and multi-year CEMS maintenance—now drive lifetime value capture more than initial equipment sales. Three-tier pricing structure across premium, standard, and economy levels reflects alloy grade specification, with superaustenitic vessels commanding substantial premiums over 316L configurations. Cost compression in standard-grade precipitator electrodes is intensifying because Chinese stainless overcapacity has eroded base-material quotes. Utility procurement officers in India's thermal power corridor exhibit the sharpest price sensitivity, while German chemical operators accept lifecycle-cost premiums for integrated scrubber maintenance contracts.
Supply Chain Analysis
Specialized refractory contract-manufacturing concentrates among German and Japanese suppliers for acid-resistant brick and ceramic lining materials, creating procurement bottlenecks for high-temperature scrubber vessels. Superaustenitic stainless steel draws from Finnish and Swedish melt shops, while precipitator transformer-rectifier assemblies rest on South Korean and German electrical component sources. Single-source vulnerability in refractory supply threatens project timelines when Hebei steel sector demand surges coincide with European waste-to-energy retrofit waves. Distribution runs through EPC-led turnkey contracting for utility retrofits, with modular skid systems bypassing channel intermediaries for greenfield industrial installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The End-Of-Pipe Air Pollution Control Equipment Market is entering a cyclical recovery phase as coal plant MATS compliance deadlines and China's MEE ultra-low emission enforcement synchronize replacement cycles across major installed bases.
For Market Incumbents: Build switching-cost moats through captive aftermarket service platforms that embed continuous emission monitoring data streams into multi-year maintenance agreements. Incumbents should anchor North American utility relationships via bundled precipitator-scrubber retrofit packages while accelerating digital twin deployment to capture recurring diagnostics subscriptions. Membrane-laminated baghouse technology from pulp and paper adjacent markets threatens electrostatic precipitator incumbency in mid-size industrial applications; vertical integration into high-voltage power supply manufacturing mitigates commissioning bottlenecks. For New Entrants and Emerging Players: Build out Indonesia's nickel processing corridor ahead of forthcoming emission regulations, securing first-mover positioning for integrated acid gas and particulate control systems at Morowali Industrial Park smelters. The most penetrable white-space sits in European waste-to-energy dry scrubbing conversions, where incumbents lack specialized semi-dry lime injection expertise. A go-to-market angle anchored on wastewater elimination narratives—resonating with Polish and German incinerator operators—circumvents entrenched wet scrubbing relationships. For Investors and Strategic Acquirers: Regional aftermarket service specialists with captive transformer-rectifier repair capabilities represent the most compelling acquisition archetype, given high-voltage commissioning engineer scarcity across Southeast Asian project sites. Long-term viability over the coming decade hinges on installed base density in coal-dependent utility corridors rather than greenfield capacity additions. The signal to watch is CPCB enforcement intensity in Maharashtra and Gujarat, where precipitator rebuild acceleration would validate cyclical recovery timing.| Strategic Initiative | Industry Significance |
|---|---|
| Aftermarket Service Unbundling | Standalone maintenance agreements for precipitator rappers and scrubber pumps fragment vendor relationships across US Midwest utility corridors. |
| Digital Twin Predictive Maintenance | Remote corona current monitoring shifts revenue from hardware sales to recurring diagnostics subscriptions at Valmet and FLSmidth. |
| Hybrid ESP-Fabric Filter Deployment | Five and six-field configurations with membrane-laminated polishing stages satisfy China's MEE particulate thresholds below 10 mg/Nm³. |
| Dry Scrubbing Conversion | Semi-dry lime injection systems eliminate wastewater burdens for European waste-to-energy operators in Poland and Germany. |
| Nickel Corridor First-Mover Positioning | Integrated acid gas and particulate control procurement at Indonesia's Morowali Industrial Park precedes binding emission regulations. |
Methodological Framework
Desk research of customs and trade data, SEC 10-K filings, and MEE enforcement bulletins preceded structured interviews with plant maintenance directors, OEM procurement teams, aftermarket service heads, and EPC project managers across the analysis window. Primary fieldwork captured precipitator rebuild cycle timing, scrubber alloy specification trends, and bundled retrofit contracting practices. Secondary validation drew from EPA MATS compliance tracking, CPCB enforcement reports, and EU Industrial Emissions Directive implementation databases. Bottom-up equipment shipment tallies and top-down utility capital expenditure forecasts were triangulated to establish market sizing.
Assumptions held regulatory enforcement timelines and nickel alloy pricing bands within observed historical patterns while varying coal plant retirement rates and battery-material smelter construction schedules across the projection horizon. The analytical framework modeled segmentation across product type, technology, application, and end user dimensions, with additional disaggregation by regional regulatory cluster and compliance deadline phasing. CAGRs were derived from regression analysis of historical retrofit cycle data against permit renewal calendars, incorporating wet ESP adoption curves from China's steel sector and dry scrubbing conversion rates from European waste-to-energy operators.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese engineering conglomerates into Southeast Asian EPC contracting would shift outcomes through price-undercutting on fixed-bid utility frameworks. Quarterly review of CPCB enforcement actions, MEE ultra-low emission compliance certificates, and London Metal Exchange nickel price volatility is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Monitoring
Global on-Line Total Organic Carbon (TOC) Analyzer Market
Environmental Monitoring
Environmental Remediation Technologies Market
Environmental Monitoring
Russia Cloud Seeding Market
Environmental Monitoring
India Cloud Seeding Market
Environmental Monitoring
Ecotoxicological Studies Market
Environmental Monitoring
South America Air Quality Monitoring Market
Environmental Monitoring
LAMEA Emission Monitoring System Market
Environmental Monitoring
Water Quality Analyzer Market
Environmental Monitoring
Environment Testing Services Market
Environmental Monitoring
Water Testing Market
Environmental Monitoring
Quality Monitoring Sensor for Water Market
Environmental Monitoring
Environmental Test Equipment Market
Environmental Monitoring
Testing, Inspection, and Certification for Natural Resources Market
Environmental Monitoring
Canada Cloud Seeding Market
Environmental Monitoring
Water Quality Monitoring Equipment Market
Environmental Monitoring
Air Quality Monitoring Equipment Market