
 Environmental Remediation Technologies Market | 2026-2036
Environmental Remediation Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Environmental Remediation Technologies Market Insights
Industrial property developers are redrawing procurement priorities for environmental remediation technologies, overtaking municipal water authorities as the fastest-growing buyer archetype. Clean Harbors, Inc. leverages its North American hazardous waste infrastructure to dominate turnkey remediation contracts. AECOM sustains engineering-led competitive positioning through integrated site assessment and treatment design capabilities. Jacobs Solutions Inc. anchors its presence in large-scale mining reclamation projects across multiple continents.
Environmental remediation technologies encompass engineered systems and biological processes that remove, neutralize, or contain pollutants in soil, groundwater, sediment, and air matrices, typically achieving contaminant reduction thresholds specified by national environmental quality standards. These technologies serve the primary commercial purpose of restoring impaired sites to regulatory-compliant conditions for redevelopment, operational continuity, or ecological protection. Bioremediation and chemical oxidation represent the most rapidly expanding technology categories, driven by lower energy intensity and compatibility with emerging contaminant classes such as PFAS. Groundwater treatment remains the largest application segment by contract value, though sediment remediation commands premium pricing due to logistical complexity and marine regulatory oversight.
The US EPA enforces Comprehensive Environmental Response, Compensation, and Liability Act (CERCLA) cleanup mandates that directly compel responsible parties to deploy certified remediation technologies, while the EU Green Deal and REACH frameworks impose progressively stricter soil and groundwater quality thresholds across member states. China's Ministry of Ecology and Environment (MEE) enforces dual carbon goals that intersect with brownfield restoration requirements, creating additional compliance-driven demand for low-emission treatment modalities. Stakeholders must monitor evolving PFAS regulatory classification decisions across multiple jurisdictions, as these determinations will abruptly reclassify treatment obligations and redirect technology procurement toward advanced oxidation and thermal destruction systems.
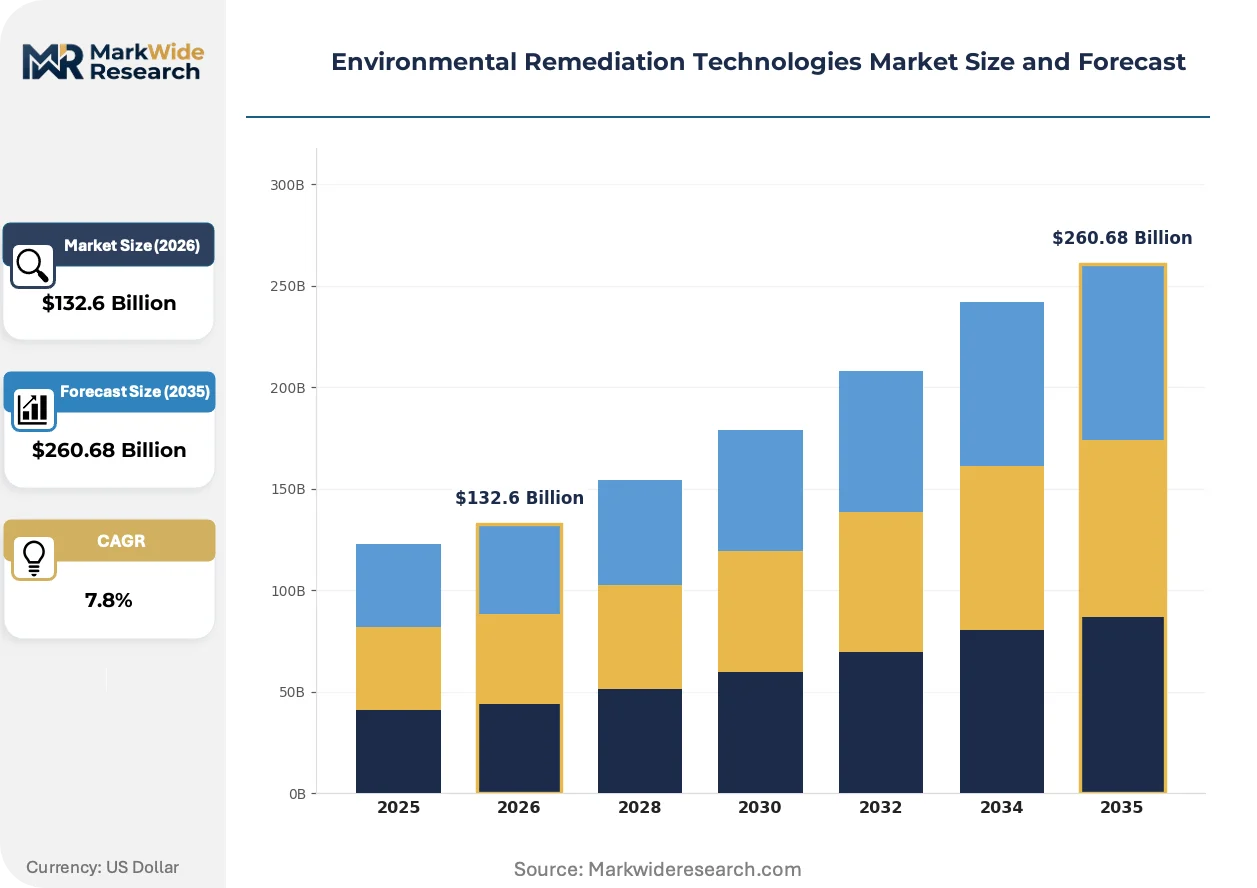
Market Dynamics
The US EPA's CERCLA enforcement and the EU Green Deal's soil health mandates are compressing compliance timelines, forcing asset owners to accelerate remediation technology procurement while simultaneously demanding lower-emission treatment modalities.
Growth Catalysts
- CERCLA Liability Enforcement:The US EPA's strict liability framework compels responsible parties to deploy certified remediation systems without waiting for litigation outcomes, sustaining baseline demand.
- PFAS Regulatory Reclassification:Emerging hazardous substance designations for per- and polyfluoroalkyl substances across multiple jurisdictions are triggering immediate treatment obligations at industrial sites.
- Mining Sector Reclamation Mandates:Large-scale mining operators in Australia and Canada face binding closure obligations that require thermal desorption and chemical oxidation system deployment.
Market Restraints
- Specialized Equipment Lead Times:Thermal desorption units and advanced oxidation reactors face 12-18 month manufacturing backlogs from concentrated German and US fabrication capacity.
- Energy Input Cost Volatility:Thermal treatment modalities remain exposed to natural gas price fluctuations that directly impact project economics and contractor margins.
- Site Characterization Uncertainty:Subsurface heterogeneity and contaminant plume delineation challenges frequently trigger scope revisions that erode fixed-price contract profitability.
Strategic Opportunities
- Brownfield Redevelopment Incentives:The EU Green Deal's soil health targets include direct funding mechanisms for member state brownfield restoration projects.
- Electrokinetic-Phytoremediation Convergence:Hybrid systems combining electrokinetic soil flushing with targeted plant uptake are opening low-energy treatment pathways for metal-contaminated sites.
- Performance-Based Contracting Models:Remediation-as-a-service arrangements are displacing traditional equipment purchase decisions among capital-constrained municipal utilities.
Industry Challenges
- PFAS Analytical Methodology Gaps:The absence of standardized total oxidizable precursor assays creates regulatory acceptance risk for destruction-based treatment claims.
- Cross-Media Transfer Liability:Soil vapor extraction and groundwater pump-and-treat systems generate secondary waste streams that trigger additional permitting obligations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Environmental Remediation Technologies Market |
| Market Size in 2026 | $132.6 Billion |
| Market Size in 2035 | $260.68 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Bioremediation, Phytoremediation, Soil Vapor Extraction, Pump & Treat, Thermal Desorption, Chemical Oxidation Application: Groundwater Treatment, Soil Cleanup, Sediment Remediation, Wastewater Management, Air Pollution Control, Hazardous Waste Disposal End User Industry: Chemical Manufacturing, Mining Operations, Construction Firms, Land Development, Water Authorities, Waste Management Companies Deployment Model: In-Situ, Ex-Situ, Onsite Mobile Units, Fixed Plant Installations |
| Companies Covered | Clean Harbors, Inc., AECOM, Jacobs Solutions Inc., Tetra Tech, Inc., WSP, Veolia Environnement S.A., Arcadis NV, ERM, Ramboll, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Environmental Remediation Technologies Market Trends and Innovations
In-situ chemical oxidation using persulfate and permanganate activators is displacing conventional excavation-based remediation across contaminated industrial parcels. Regulatory agencies are tightening analytical detection limits for emerging contaminants faster than treatment technology validation cycles can accommodate. Asset owners are compressing vendor selection timelines while demanding integrated site assessment and treatment performance guarantees.
Thermal desorption systems equipped with real-time emissions monitoring and automated temperature profiling are displacing batch-operated fixed-hearth units at petroleum hydrocarbon sites. Mid-sized environmental contractors in Texas and Alberta are adopting these systems to secure multi-year mining reclamation contracts. The shift is compressing acceptable treatment timelines from months to weeks while raising capital barriers for smaller service providers.
The EU's REACH framework amendment process is accelerating restriction proposals for persistent organic pollutants in soil matrices, directly affecting treatment technology selection criteria for industrial legacy sites. German regulators are requiring mass balance documentation for all ex-situ thermal processes. Equipment vendors are responding by integrating continuous emissions monitoring systems that automatically generate compliance-ready data packages.
Industrial property developers are consolidating remediation procurement under single-source environmental service contracts that bundle site characterization, treatment design, and regulatory closure support. This behavior is displacing fragmented subcontracting arrangements previously common in commercial real estate transactions. The pattern is most visible in California and New Jersey where transfer liability statutes impose strict cleanup obligations on sellers.
Environmental Remediation Technologies Market Segmentation
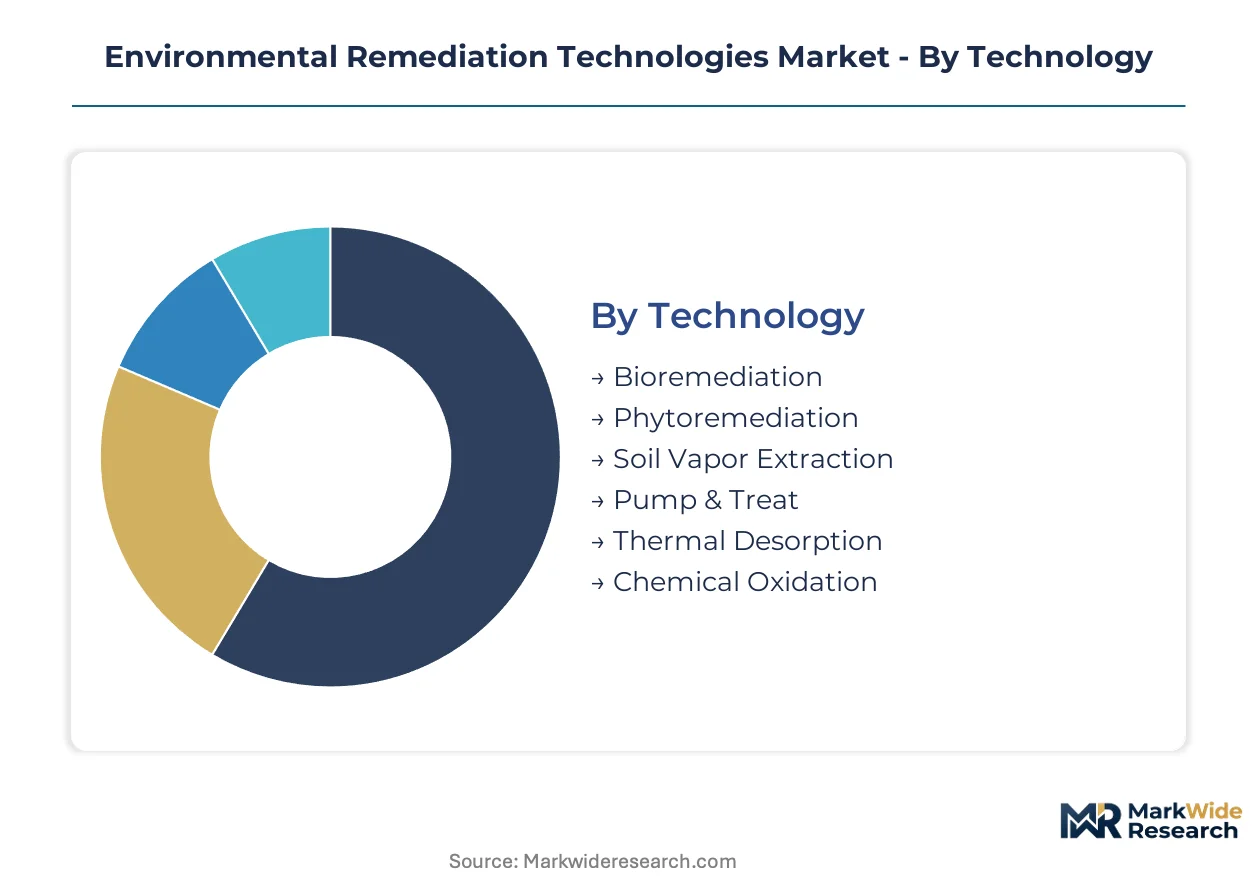
Technology selection in environmental remediation directly determines project economics, regulatory approval timelines, and residual liability exposure. Segmentation reveals where capital concentrates across treatment modalities and which application areas command premium pricing due to technical complexity or enforcement intensity.
Technology:
Premium margins cluster in thermal destruction and advanced oxidation systems where equipment specificity and operational expertise create vendor lock-in effects.
- Chemical Oxidation:Persulfate and permanganate-based systems achieve rapid contaminant mineralization through hydroxyl radical generation. Demand concentrates at PFAS-impacted industrial sites in Germany and the US where EPA and state-level hazardous substance designations mandate destruction-grade treatment. The technology's lower energy footprint versus thermal alternatives attracts procurement from carbon-constrained mining operators in Australia.
- Thermal Desorption:Rotary kiln and infrared systems volatilize organic contaminants from excavated soils at 300-600°C operating temperatures. German industrial legacy site obligations sustain procurement of continuous-feed units with integrated emissions controls. Manufacturing backlogs of 12-18 months from concentrated US and German fabrication capacity protect incumbent vendor pricing power.
- Bioremediation:Engineered microbial consortia degrade petroleum hydrocarbons and chlorinated solvents through aerobic and anaerobic metabolic pathways.
- Phytoremediation:Hyperaccumulator plant species extract heavy metals from shallow soil horizons through root uptake and translocation mechanisms.
- Soil Vapor Extraction:Vacuum-induced volatilization removes volatile organic compounds from unsaturated zone soils through vertical or horizontal well arrays.
- Pump & Treat:Groundwater extraction followed by above-ground separation or destruction remains the default approach for dissolved plume management.
The dominant share belongs to Pump & Treat, while Chemical Oxidation is closing the gap fastest.
Application:
Contract value scales with subsurface complexity and cross-media regulatory oversight rather than contaminant mass alone.
- Sediment Remediation:Dredging, capping, and in-situ treatment of contaminated aquatic sediments requires marine permitting and residual disposal logistics. Premium pricing persists in US harbors and EU waterway restoration projects where REACH and CERCLA frameworks impose strict ecological risk thresholds. Benthic habitat restoration obligations extend project timelines and elevate engineering content.
- Groundwater Treatment:Plume containment and source zone remediation commands the largest absolute contract volume across industrialized economies. US municipal water authorities and German chemical manufacturing clusters sustain baseline procurement of pump-and-treat infrastructure. Regulatory detection limit tightening for emerging contaminants accelerates technology refresh cycles.
- Soil Cleanup:Excavation and in-situ treatment of vadose zone contamination serves property transfer and redevelopment timelines.
- Wastewater Management:Process water and leachate treatment integrates with broader industrial effluent compliance obligations.
- Air Pollution Control:Vapor-phase treatment addresses volatile emissions from remediation operations and industrial sources.
- Hazardous Waste Disposal:Secure landfill and thermal destruction services handle treatment residuals and untreated wastes.
Sediment Remediation captures the highest per-unit margins, though Groundwater Treatment generates the largest aggregate revenue pool.
End User Industry:
Procurement authority is shifting from compliance-driven utilities to value-driven property developers seeking accelerated site closure.
- Mining Operations:Closure and reclamation obligations in Australia, Canada, and Chile require large-scale soil and groundwater remediation. Binding financial assurance mechanisms compel operators to prefund thermal desorption and chemical oxidation system deployment. Procurement concentrates in Western Australia and Alberta where tenure relinquishment hinges on regulatory sign-off.
- Land Development:Brownfield redevelopment projects in California and New Jersey drive demand for integrated assessment-to-closure service contracts. Transfer liability statutes impose strict cleanup obligations that compress vendor selection timelines and favor turnkey providers. Developers are consolidating procurement under single-source environmental service arrangements.
- Chemical Manufacturing:Legacy site obligations and ongoing operational compliance sustain demand for groundwater and soil treatment.
- Construction Firms:Infrastructure projects encounter contaminated soils requiring rapid treatment to maintain schedule adherence.
- Water Authorities:Municipal utilities manage plume containment and drinking water protection at legacy industrial sites.
- Waste Management Companies:Hazardous waste specialists deploy treatment capacity for external remediation residuals.
Water Authorities retain the largest installed base, yet Land Development is expanding most quickly as a buyer archetype.
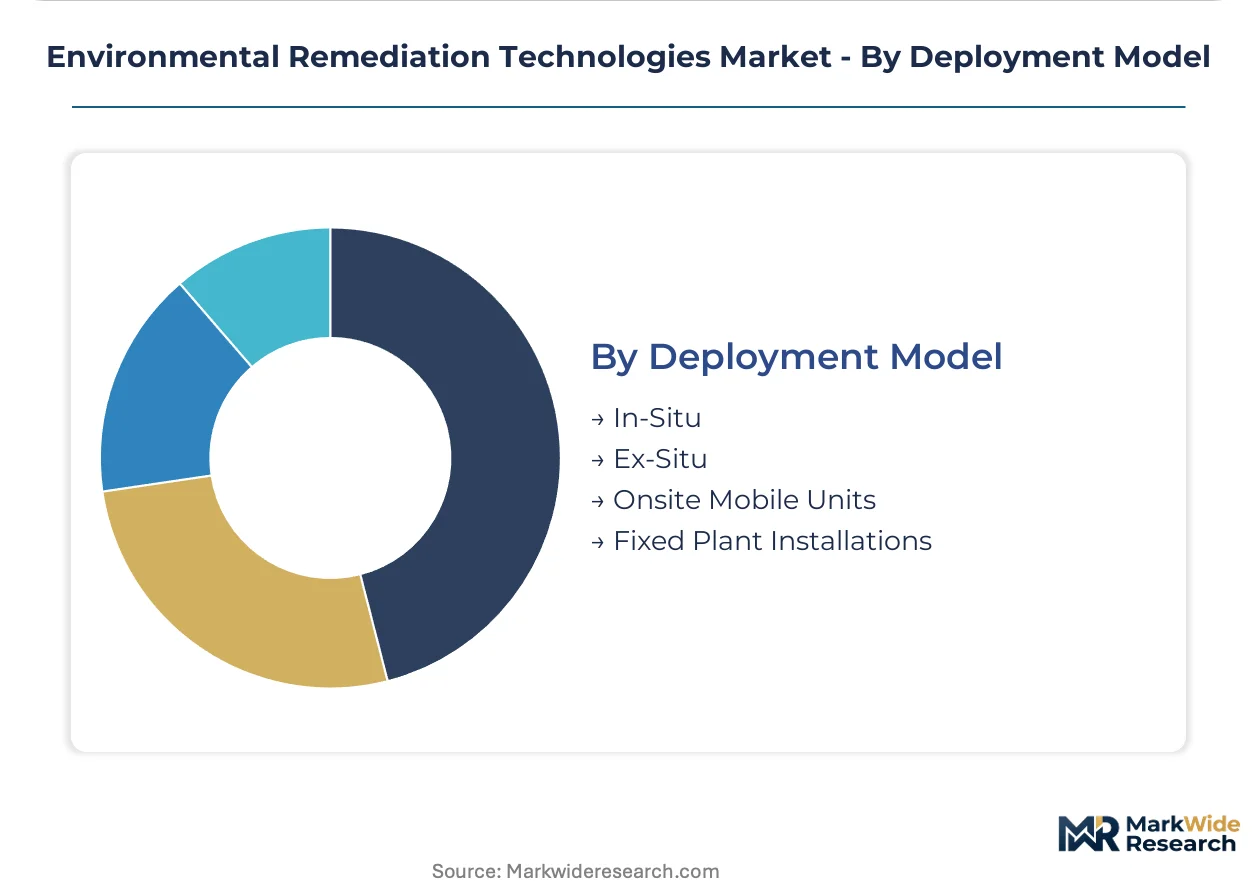
Deployment Model:
Capital efficiency and schedule risk allocation determine selection between permanent infrastructure and mobile service contracts.
- Onsite Mobile Units:Transportable thermal desorption and chemical oxidation systems reduce waste hauling liability and accelerate treatment timelines. Mid-sized contractors in Texas and Alberta deploy these assets to secure multi-year mining reclamation contracts. Equipment mobility allows asset owners to shift treatment capacity across project portfolios.
- In-Situ:Subsurface treatment without excavation minimizes surface disruption and secondary waste generation. Regulatory acceptance of in-situ chemical oxidation is expanding as validation data accumulates for PFAS and petroleum hydrocarbon applications. The approach suits urban brownfield sites where excavation constraints limit ex-situ alternatives.
- Ex-Situ:Excavated material treatment at centralized facilities or temporary staging areas enables process control and mass balance documentation.
- Fixed Plant Installations:Permanent treatment infrastructure serves long-term groundwater plume management at large industrial facilities.
Fixed Plant Installations dominate capital deployment, though Onsite Mobile Units are gaining share fastest among project-based procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's chemical storage and refining infrastructure underwrites the Netherlands' position as Europe's remediation technology gateway, while the Trans-Alaska Pipeline System anchors North American demand for cold-climate soil treatment systems.
United States
Industrial property transfers in California and New Jersey compress vendor selection timelines under strict liability statutes. EPA CERCLA enforcement compels responsible parties to deploy certified thermal desorption and chemical oxidation systems without awaiting litigation outcomes. Houston-Galveston petrochemical corridor operators sustain procurement of mobile treatment units for refinery closure projects.
Germany
Ruhr Valley industrial legacy obligations drive sustained demand for continuous-feed thermal desorption with integrated emissions controls. EU REACH framework amendments accelerate restriction proposals for persistent organic pollutants in soil matrices. Bavarian chemical manufacturing clusters require mass balance documentation for all ex-situ thermal processes, pushing equipment vendors toward automated compliance data systems.
China
MEE dual carbon goals intersect with brownfield restoration mandates in Yangtze River Delta manufacturing zones. National soil pollution prevention law imposes binding cleanup obligations on former industrial site owners. Chongqing municipality's state-owned development corporations prefund low-emission treatment modalities for urban redevelopment parcels.
Australia
Western Australia mining tenement relinquishment hinges on regulatory sign-off for closure and reclamation obligations. Binding financial assurance mechanisms compel operators to deploy thermal desorption and chemical oxidation capacity ahead of schedule risk. Queensland coal seam gas operators integrate groundwater treatment infrastructure with long-term plume management requirements.
Canada
Alberta oil sands reclamation bonds trigger immediate procurement of mobile soil treatment systems for disturbed land restoration. Federal contaminated sites action plan directs funding toward thermal desorption deployment at abandoned mine locations. Vancouver brownfield redevelopment projects demand in-situ chemical oxidation to circumvent excavation constraints in dense urban cores.
Environmental Remediation Technologies Market Competitive Landscape
Concentration sits with integrated environmental service conglomerates that bundle site assessment, treatment design, and regulatory closure support. The vendor base spans three tiers: multinational engineering firms with hazardous waste infrastructure, mid-sized contractors deploying mobile thermal units, and specialized technology licensors. Dominant competitive moves include vertical integration into equipment fabrication and geographic expansion through mining sector reclamation contracts.
Among North American service providers, Clean Harbors, Inc. and AECOM exemplify the integrated conglomerate archetype, while Jacobs Solutions Inc. occupies a position in large-scale project execution. These entities represent contrasting strategic postures—hazardous waste infrastructure leverage versus engineering-led design capabilities—within a market where turnkey procurement is displacing fragmented subcontracting arrangements.
| Leading Market Players |
|---|
| Clean Harbors, Inc. |
| AECOM |
| Jacobs Solutions Inc. |
| Tetra Tech, Inc. |
| WSP |
| Veolia Environnement S.A. |
| Arcadis NV |
| ERM |
| Ramboll |
| Others |
Pricing and Supply Chain Analysis
Twelve-to-eighteen-month manufacturing backlogs for thermal desorption units and advanced oxidation reactors concentrate pricing power among German and US equipment fabricators, compressing margins for mid-sized contractors while elevating premiums for turnkey service bundling. This lead-time asymmetry shapes procurement behavior across mining reclamation and brownfield redevelopment verticals, forcing asset owners toward long-term equipment reservation contracts or performance-based service arrangements.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates integrated turnkey providers from equipment-only vendors and mobile unit operators. Premium tiers command valuation through bundled site assessment, regulatory closure support, and performance guarantees, while standard tiers compete on equipment availability and economy tiers on per-ton treatment rates. Cost compression in mobile chemical oxidation services is intensifying because Alberta and Texas contractors are saturating mining reclamation markets with comparable unit deployments. Municipal water authorities exhibit highest price sensitivity due to capital budget constraints, whereas industrial property developers prioritize schedule certainty over unit economics.
Supply Chain Analysis
Strategic stockpile preferences dominate among German and Australian operators facing binding closure timelines, while just-in-time procurement persists in US commercial real estate where project contingencies remain fluid. Equipment fabrication concentrates in Germany, the United States, and China, with specialized reactor vessels and emissions control systems drawing from stainless steel foundries in North Rhine-Westphalia and Pennsylvania. Single-source vulnerability concentrates in German thermal desorption component suppliers, where regulatory certification requirements lock in incumbent vendor relationships. Distribution runs through regional environmental service conglomerates that maintain captive equipment fleets and subcontractor networks across North America and Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The environmental remediation technologies sector is recovering from a cyclical trough driven by deferred mining sector capital expenditure during commodity price weakness, with procurement momentum now accelerating as closure bond enforcement tightens across Australia and Canada.
For Market Incumbents: Shield installed base relationships by embedding continuous emissions monitoring systems that automate compliance documentation for German mass balance requirements. Deepen backward integration into persulfate activator supply chains to secure input cost stability against chemical feedstock volatility. Prioritize capacity reservation agreements with fabrication partners to maintain equipment availability advantages over mid-sized competitors bidding for multi-year mining contracts.
For New Entrants and Emerging Players: Performance-based contracting gaps in municipal groundwater treatment represent the most penetrable service layer, where capital-constrained utilities seek remediation-as-a-service alternatives to equipment ownership. Target electrokinetic-phytoremediation hybrid deployments for metal-contaminated sites in Eastern European brownfield portfolios where incumbent coverage remains sparse. Lead with integrated regulatory closure support to differentiate from equipment-only vendors and accelerate contract velocity.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified engineering conglomerates seeking to divest non-core environmental service units amid portfolio rationalization pressures. Long-term viability hinges on exposure to PFAS treatment obligations where regulatory reclassification is expanding addressable market scope. Monitor EPA hazardous substance designation timelines for per- and polyfluoroalkyl substances as the critical inflection signal for thermal destruction and advanced oxidation demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chemical Feedstock Supply | Captive persulfate and permanganate sourcing insulates margins from commodity volatility in oxidation system deployment. |
| Mobile Unit Fleet Expansion | Transportable thermal desorption capacity secures multi-year mining reclamation contracts in Western Australia and Alberta. |
| Performance-Based Contracting Model Development | Remediation-as-a-service arrangements unlock municipal utility procurement previously constrained by capital budget limitations. |
| Continuous Emissions Monitoring Integration | Automated compliance data packages satisfy German regulatory mass balance documentation requirements for thermal processes. |
| PFAS Treatment Technology Validation Investment | Advanced oxidation and thermal destruction certification positions vendors for emerging hazardous substance designation enforcement. |
Research Methodology
A standing panel of remediation project managers, environmental compliance officers at mining operators, thermal desorption equipment fabricators, and brownfield redevelopment directors provided ongoing calibration against field deployment realities. Primary interview intelligence combined with secondary validation from EPA CERCLA site tracking databases, EU EIONET soil contamination inventories, and state-level financial assurance bond filings. Bottom-up project pipeline analysis triangulated against top-down regulatory obligation modeling across the analysis window.
Consistency checks validated volume and value outputs against external benchmarks including equipment manufacturing order backlogs, municipal procurement contract awards, and mining sector closure expenditure disclosures. The analytical framework modeled technology category, application matrix, end-user industry, and deployment modality segments throughout the forecast period. CAGRs were derived from regression analysis of historical contract value progression and forward projection of regulatory enforcement intensity, with PFAS treatment obligation expansion and mining tenure relinquishment timelines serving as primary demand drivers.
Underlying assumptions cover sustained EPA CERCLA enforcement rigor, EU Green Deal soil health target adherence, and mining sector financial assurance mechanism integrity, with deviation risk concentrated in PFAS regulatory classification timing and thermal treatment energy input cost trajectories. Revision becomes warranted when hazardous substance designation thresholds or carbon pricing regimes cross materiality thresholds for project economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Monitoring
Smart Water Monitoring Market
Environmental Monitoring
US Cloud Seeding Market
Environmental Monitoring
Green Mining Market
Environmental Monitoring
End-Of-Pipe Air Pollution Control Equipment Market
Environmental Monitoring
Environment Testing Services Market
Environmental Monitoring
Asia-Pacific Cloud Seeding Market
Environmental Monitoring
Global Indoor Air Quality Solutions Market
Environmental Monitoring
Environmental Technology Market
Environmental Monitoring
Water Quality Analyzer Market
Environmental Monitoring
Ecotoxicological Studies Market
Environmental Monitoring
Global Water Quality Monitoring Market
Environmental Monitoring
Cloud Seeding System Market
Environmental Monitoring
Indoor Air Quality Service Market
Environmental Monitoring
Food Security Technology Market
Environmental Monitoring
Water Pipeline Leak Detection System Market
Environmental Monitoring
Environmental Monitoring (Surface Water) Market