
 Soil Remediation Technologies Market | 2026-2036
Soil Remediation Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Soil Remediation Technologies Market Analytics
Market Context
The soil remediation sector is recalibrating around a sharp split between high-precision in-situ thermal treatment and commoditized ex-situ excavation services. Clean Harbors leverages its hazardous waste infrastructure to control disposal-linked remediation workflows. Tetra Tech anchors large-scale federal site contracts through engineering-procurement capabilities. AECOM competes on integrated design-build models that compress project timelines for urban brownfield redevelopment.
Technical Definition and Structural Segments
Soil remediation technologies encompass engineered processes that reduce contaminant concentration in soil matrices to regulatory thresholds, typically employing thermal desorption at 300–600°C, oxidative chemical injection, or microbial biodegradation pathways. These systems restore land usability for residential, commercial, or ecological purposes. Bioremediation dominates volume deployment for petroleum hydrocarbon sites where indigenous microbial activity reduces operational cost. Chemical oxidation captures premium pricing at chlorinated solvent plumes where rapid mass destruction matters. Phytoremediation occupies niche agricultural restoration segments with multi-year treatment horizons but minimal energy input.
Regulatory Framework and Outlook
The US EPA enforces Comprehensive Environmental Response, Compensation, and Liability Act obligations that directly create remediation demand and liability-driven project initiation timelines. The EU Soil Monitoring Law and REACH contaminant thresholds shape product standards for treated soil reuse across member states. China's MEE soil pollution prevention law mandates risk management for agricultural land conversions. Stakeholders must monitor evolving per- and polyfluoroalkyl substances standards, as emerging contaminant designations will redefine project scopes and technology selection criteria.
Market Dynamics
Legacy contamination liabilities are accelerating the shift from dig-and-haul excavation toward in-situ treatment modalities, compressing project timelines and altering contractor capability requirements across brownfield redevelopment portfolios.
Growth Catalysts
- EPA Superfund Enforcement:CERCLA liability provisions compel responsible parties to initiate remediation at abandoned industrial sites, creating guaranteed project pipelines for qualified contractors.
- Petroleum Hydrocarbon Biodegradation:Indigenous microbial pathways deliver cost-effective mass reduction at former refinery and terminal facilities without energy-intensive thermal processing.
- German Federal Soil Protection Act:Rigorous cleanup standards for former industrial zones in the Ruhr and Saxony regions mandate comprehensive remediation before land transfer.
Market Restraints
- Specialized Equipment Capital Intensity:Thermal desorption units requiring 300–600°C operating ranges demand seven-figure capital commitments that constrain mid-tier contractor entry.
- Treated Soil Disposal Concentration:Hazardous waste landfill capacity concentrates in North American and Western European corridors, creating logistics bottlenecks for remote site projects.
- Chlorinated Solvent Treatment Limitations:Dense non-aqueous phase liquid plumes resist conventional bioremediation, forcing reliance on premium chemical oxidation with higher unit economics.
Strategic Opportunities
- PFAS Regulatory Designation:Emerging contaminant status for per- and polyfluoroalkyl substances under EPA and ECHA frameworks will expand addressable project scopes requiring specialized destruction technologies.
- Phytoremediation Agricultural Expansion:Multi-year treatment horizons with minimal energy input suit large-scale farmland restoration where immediate reuse pressure is low.
- Integrated Design-Build Contracts:Urban brownfield developers are compressing procurement cycles by awarding single-source engineering-procurement-construction packages rather than segmented bids.
Industry Challenges
- Thermal Treatment Specialist Scarcity:Operators capable of managing ex-situ thermal desorption at 300–600°C with emission compliance represent a constrained talent pool.
- Multi-Jurisdictional Certification Timelines:Treated soil reuse approvals require navigation of state-level beneficial use determinations that extend project closeout schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soil Remediation Technologies Market |
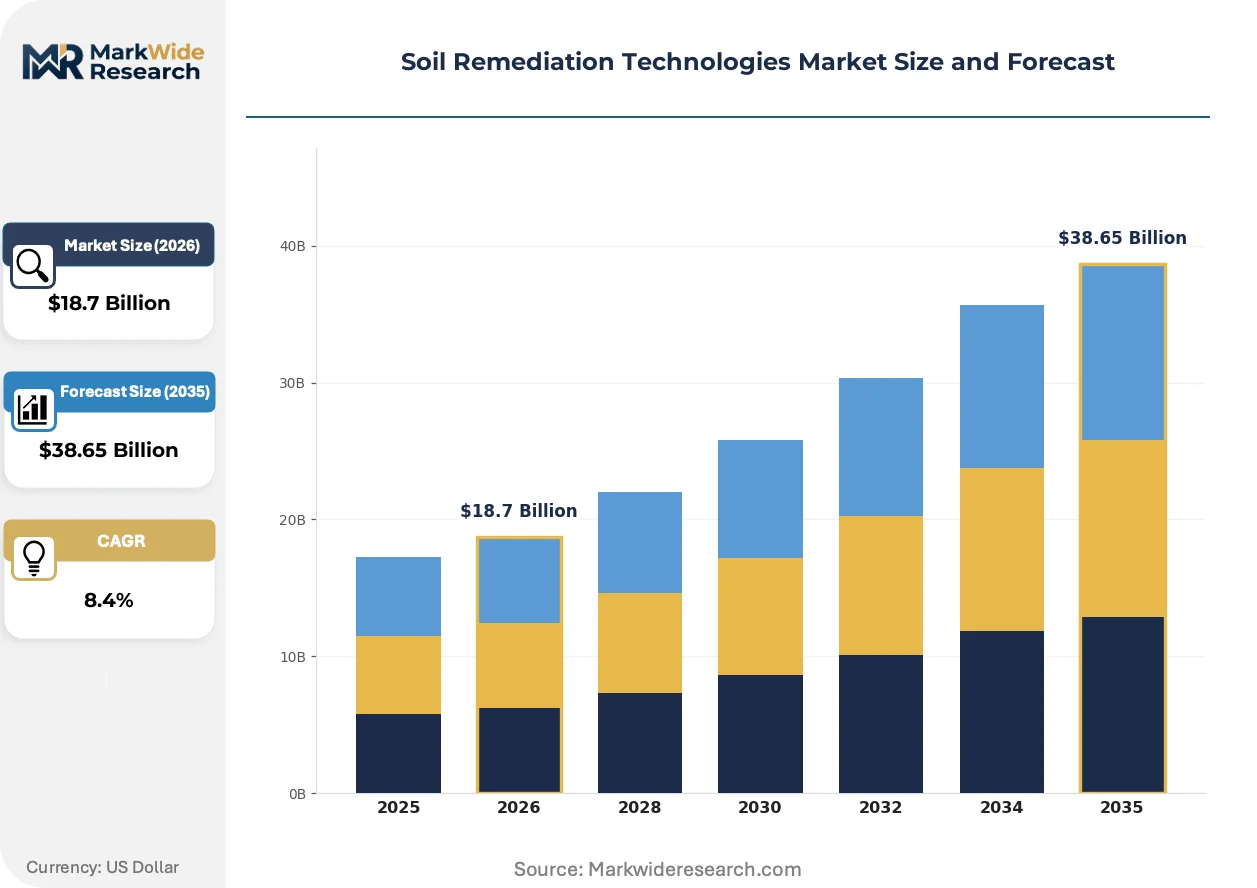
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Bioremediation, Phytoremediation, Chemical Oxidation, Soil Washing Application: Industrial Cleanup, Agricultural Restoration, Urban Redevelopment, Hazardous Waste Management End User: Environmental Agencies, Construction Firms, Agricultural Producers, Government Bodies Deployment: On-site Treatment, Off-site Treatment, In-situ Restoration, Ex-situ Restoration |
| Companies Covered | Tetra Tech, TerraTherm, Clean Harbors, Allonnia, Antea Group, AECOM, WSP, ecoSPEARS, Jacobs Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soil Remediation Technologies Market Evolving Landscape
Remediation technology portfolios are converging around real-time monitoring integration and modular treatment systems that reduce mobilization costs for distributed contamination footprints.
Electrokinetic remediation is unifying soil and groundwater treatment at heavy metal sites by applying direct current gradients to mobilize charged contaminants toward extraction electrodes. Mining legacy operators in Australia and Canada are piloting these systems for arsenic and lead removal where conventional excavation proves economically prohibitive. This convergence is compressing the traditional separation between soil and groundwater remediation contracts into single-scope deliverables.
REACH contaminant thresholds are tightening soil reuse criteria across EU member states, particularly for polycyclic aromatic hydrocarbons and petroleum fractions in construction fill applications. Industrial developers in the Netherlands and Belgium now face mandatory pre-construction soil screening that triggers remediation obligations prior to ground disturbance. The construction materials segment is responding by investing in on-site soil washing infrastructure to achieve regulatory thresholds without off-site disposal.
Performance-guaranteed remediation contracts are displacing unit-rate pricing structures at complex industrial sites where cost certainty outweighs initial bid premiums. Major petroleum and chemical operators in the US Gulf Coast region are transferring completion risk to contractors through fixed-price remediation with long-term monitoring obligations. This restructuring concentrates execution risk among specialized remediation firms with balance sheet capacity to absorb cost overruns.
Soil Remediation Technologies Market Segmentation
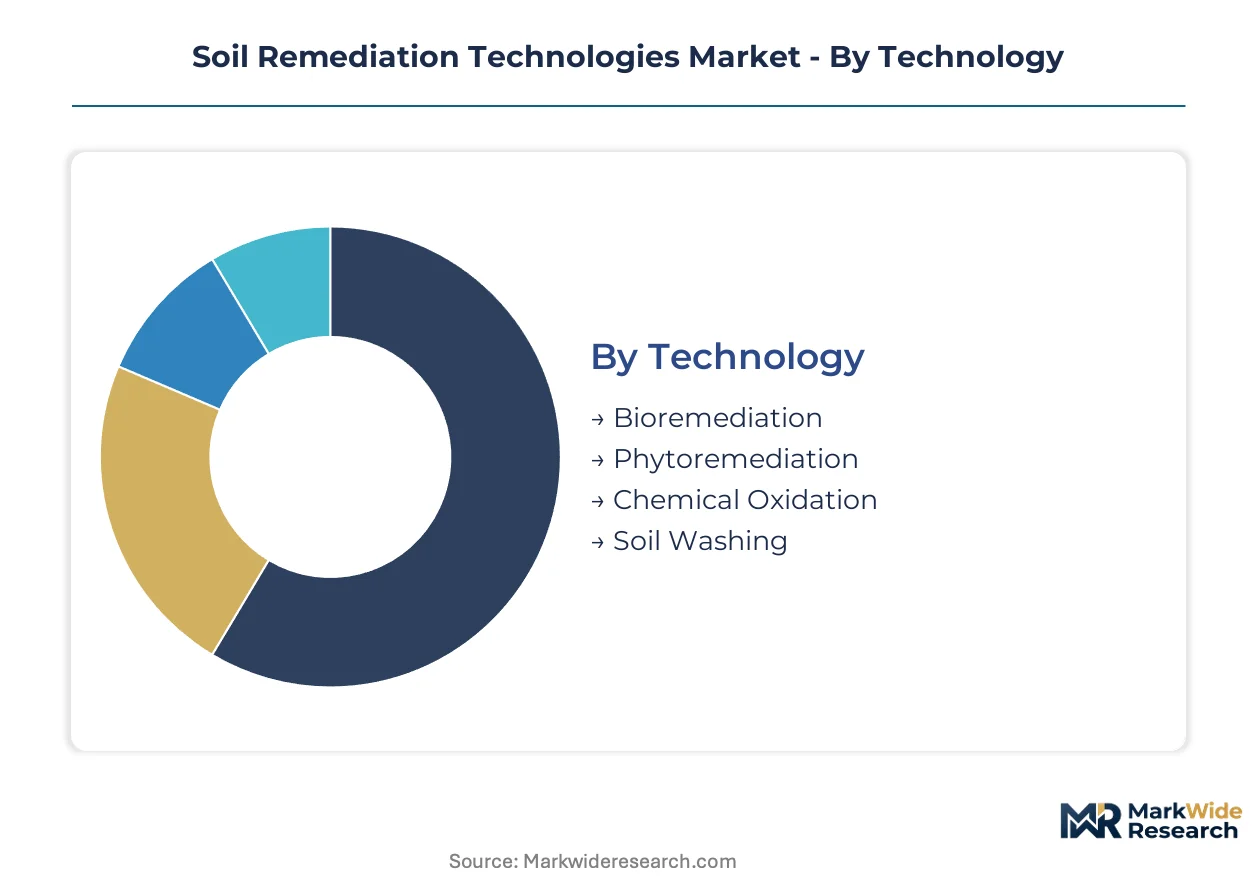
Technology selection in soil remediation directly determines project economics, regulatory approval pathways, and contractor capability requirements. Segmentation reveals where capital intensity concentrates and which modalities offer entry points for specialized service providers.
Technology:
Bioremediation and chemical oxidation carry divergent certification burdens under EPA and ECHA frameworks, with the former qualifying for streamlined beneficial use determinations while the latter triggers hazardous waste permit requirements.
- Bioremediation:Leverages indigenous microbial consortia to mineralize petroleum hydrocarbons and select pesticides without external energy input. Demand concentrates at former refinery sites in Texas and Louisiana where CERCLA timelines favor low-cost mass reduction over rapid closure.
- Chemical Oxidation:Deploys permanganate or persulfate injections to destroy chlorinated solvent DNAPL plumes through radical-mediated bond cleavage. Premium pricing persists at former dry cleaning and electronics manufacturing facilities in Germany's industrial corridor where REACH thresholds mandate aggressive treatment.
- Phytoremediation:Uses hyperaccumulator plant species to extract heavy metals from agricultural soils across China's Hunan province under MEE risk management mandates.
- Soil Washing:Applies mechanical separation and aqueous extraction to reduce contaminant concentrations in coarse-grained soils for construction fill reuse in Dutch brownfield projects.
Leading the category by volume: bioremediation. Growing fastest: chemical oxidation.
Application:
Cost tier stratification separates high-budget federal Superfund sites from municipally funded urban redevelopment and privately financed agricultural restoration.
- Industrial Cleanup:Addresses legacy contamination at abandoned manufacturing, chemical, and petroleum facilities where CERCLA liability provisions guarantee funding streams. Project scales in the US Gulf Coast region routinely exceed $50 million with decade-long remediation horizons.
- Urban Redevelopment:Compresses timelines for brownfield-to-residential conversions in cities like Detroit and Cleveland where EPA brownfield grants supplement private capital. Design-build procurement models dominate this segment.
- Agricultural Restoration:Targets cadmium and arsenic contamination in China's rice-growing regions under soil pollution prevention law mandates for safe crop production.
- Hazardous Waste Management:Integrates remediation with RCRA-permitted treatment, storage, and disposal facilities operated by specialized waste handlers.
Industrial cleanup commands the highest absolute spending. Urban redevelopment is expanding most quickly as municipal bond financing for brownfield programs proliferates.
End User:
Customer type determines procurement sophistication, with environmental agencies mandating performance guarantees and construction firms prioritizing schedule certainty.
- Environmental Agencies:EPA regional offices and state environmental departments enforce CERCLA and state-equivalent statutes, awarding cost-plus contracts with extensive oversight requirements.
- Construction Firms:Commercial developers in Germany's Ruhr region acquire remediated parcels for logistics and residential projects under Federal Soil Protection Act transfer conditions.
- Agricultural Producers:Chinese farming cooperatives fund phytoremediation pilots to qualify for MEE agricultural land safety certifications.
- Government Bodies:Municipal authorities in Belgium and the Netherlands execute soil screening obligations prior to infrastructure construction permits.
Environmental agencies remain the largest contract source by value. Construction firms are gaining share fastest through integrated design-build awards.
Deployment:
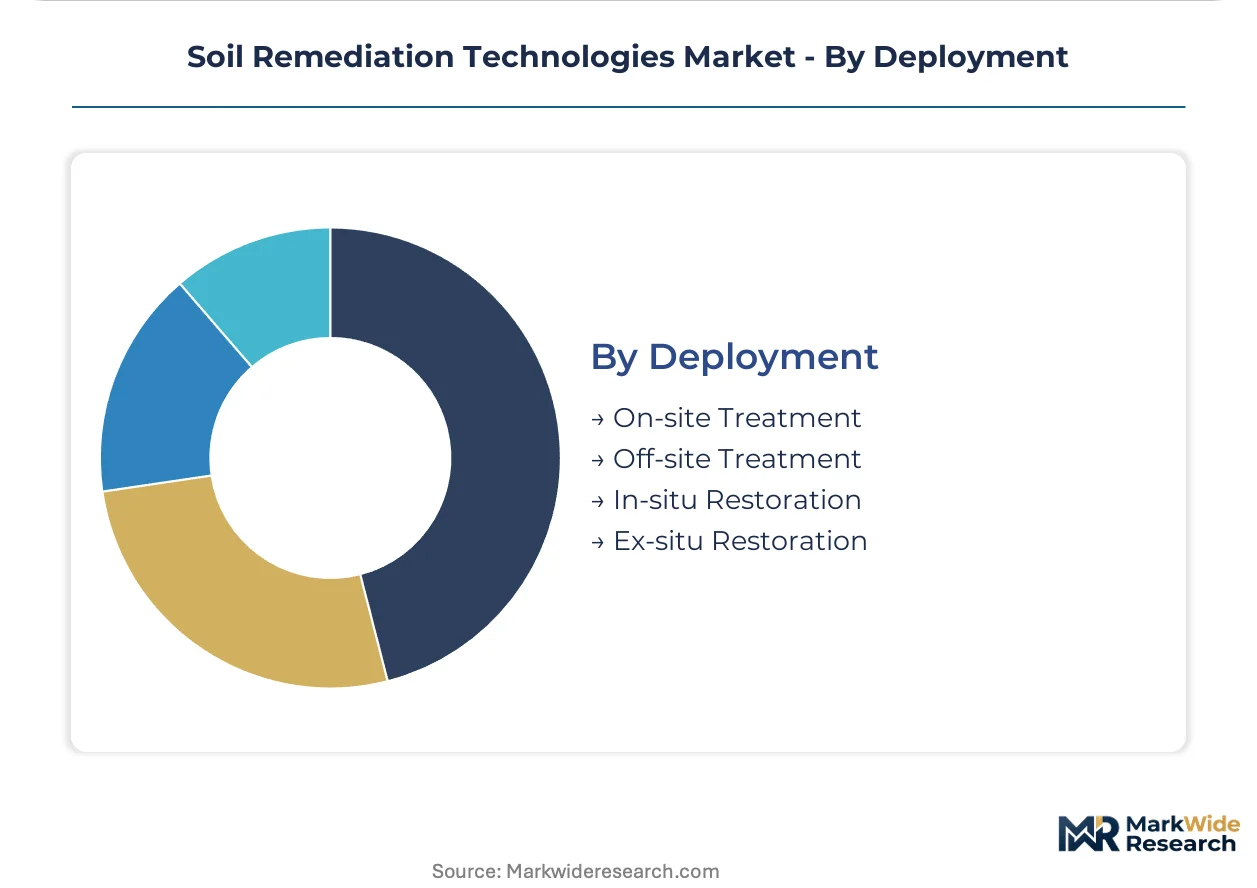
Volume concentration favors in-situ modalities that eliminate excavation and transportation costs, while ex-situ approaches retain relevance for complex contaminant mixtures requiring thermal treatment.
- In-situ Restoration:Injects amendments directly into contaminated matrices without soil removal, minimizing community disruption in dense urban environments like New York and London.
- On-site Treatment:Processes excavated soils through mobile thermal desorption or biopile systems at the contamination source, reducing off-haul volumes for petroleum sites.
- Ex-situ Restoration:Transports soils to fixed-base treatment facilities with controlled emission management, required for persistent organic pollutant destruction.
- Off-site Treatment:Relies on commercial hazardous waste infrastructure where landfill capacity constraints in Western Europe create logistics bottlenecks.
In-situ restoration dominates new project awards. On-site treatment shows the steepest expansion trajectory as modular equipment reduces mobilization costs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Houston Ship Channel anchors North American remediation contracting, where petrochemical legacy sites generate sustained thermal treatment demand under EPA enforcement timelines.
United States
Superfund liability provisions drive project initiation at abandoned manufacturing corridors across Michigan and New Jersey. EPA regional offices enforce CERCLA-mandated cleanup schedules that guarantee multi-year contracting pipelines. The Passaic River basin exemplifies concentrated chlorinated solvent remediation requiring chemical oxidation expertise.
Germany
Ruhr Valley brownfield conversions trigger rigorous soil screening under Federal Soil Protection Act transfer conditions. ECHA REACH thresholds for polycyclic aromatic hydrocarbons tighten construction fill reuse criteria. Leipzig's former lignite mining districts demonstrate integrated design-build procurement for residential redevelopment.
China
Agricultural land safety certifications in Hunan province mandate cadmium phytoremediation for rice-growing cooperatives. MEE soil pollution prevention law enforcement accelerates industrial site assessments prior to zoning changes. The Yangtze River Delta manufacturing belt generates petroleum hydrocarbon bioremediation volume.
Netherlands
Randstad urban densification compresses brownfield-to-residential timelines through mandatory pre-construction soil screening. National beneficial use determinations for treated soil create multi-jurisdictional certification complexity. Rotterdam port hinterland sites deploy on-site soil washing infrastructure to avoid off-haul logistics.
Canada
Electrokinetic remediation pilots target arsenic contamination at British Columbia mining legacy sites where excavation economics fail. Provincial environmental ministries enforce site-specific risk-based cleanup objectives. Alberta's oil sands region generates petroleum hydrocarbon treatment demand through indigenous microbial pathway deployment.
Soil Remediation Technologies Market Competitive Landscape
Capital-heavy thermal treatment operators compete with asset-light engineering consultancies for project origination and execution control. The vendor base stratifies around three functional tiers: integrated design-build contractors, specialized remediation technology licensors, and hazardous waste infrastructure owners. Market consolidation proceeds through vertical acquisition of treatment equipment fleets and geographic expansion into state-level brownfield program administration.
Among North American integrated service providers, Tetra Tech and AECOM exemplify engineering-procurement-construction bundling that compresses municipal procurement cycles. Clean Harbors occupies a position within the hazardous waste infrastructure tier, leveraging disposal-linked remediation workflows. These three entities represent distinct competitive archetypes: federal contracting scale, urban redevelopment speed, and waste logistics integration.
| Leading Market Players |
|---|
| Tetra Tech |
| TerraTherm |
| Clean Harbors |
| Allonnia |
| Antea Group |
| AECOM |
| WSP |
| ecoSPEARS |
| Jacobs Solutions |
| Others |
Value Network & Pricing Analysis
Backward integration into thermal desorption equipment fleets anchors pricing power for contractors serving EPA Superfund sites, while outsourced bioremediation substrate sourcing leaves mid-tier operators exposed to agricultural commodity volatility. This structural split concentrates margin capture among hazardous waste infrastructure owners and fragments profitability across equipment-rental dependent service providers.
Pricing Analysis
Outcome-based pricing tied to regulatory closure certificates dominates complex chlorinated solvent projects where CERCLA liability transfer justifies premium rates. Price differentiation rests on EPA treatment facility permitting tier and guaranteed throughput volume commitments. Cost compression in commoditized excavation services is intensifying as municipal brownfield programs cap unit-rate bids. Environmental agencies demonstrate lowest price sensitivity due to mandated liability obligations, while agricultural cooperatives in China exhibit highest sensitivity given multi-year phytoremediation horizons.
Supply Chain Analysis
Dual-sourcing requirements for thermal oxidizer refractory materials and specialized microbial inoculum strains compel contractors to qualify backup suppliers across Germany and the United States. Equipment manufacturing concentrates in Germany, the United States, and Japan. Raw material dependencies include high-purity hydrogen peroxide for chemical oxidation, specialized ceramic media for thermal desorption, and proprietary bacterial consortia for bioremediation. Single-source vulnerability persists for EPA-certified mobile treatment units. Distribution runs through regional hazardous waste logistics networks with RCRA-permitted transfer facility access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized thermal treatment operator scarcity props pricing across the US Gulf Coast and German industrial corridors, constraining capacity expansion for chlorinated solvent remediation. This bottleneck sustains contractor margin capture where regulatory timelines are non-negotiable.
For Market Incumbents:Acquire fixed-base thermal desorption facilities in EPA Region 5 and Region 2 to consolidate hazardous waste infrastructure control against emerging electrokinetic remediation technology licensors. Secure captive supply of EPA-certified mobile treatment units through exclusive equipment manufacturing partnerships. Expand indigenous microbial consortium cultivation capacity to reduce agricultural substrate cost exposure.
For New Entrants and Emerging Players:Direct-to-municipality digital procurement platforms offer the lowest competitive density for bypassing incumbent engineering-procurement-construction bundling. Target Dutch and Belgian urban brownfield screening contracts where mandatory pre-construction soil assessment creates predictable project origination. Pursue phytoremediation agricultural restoration in China's Hunan province under MEE agricultural land safety certification mandates.
For Investors and Strategic Acquirers:Exit pathways concentrate in trade sales to hazardous waste infrastructure consolidators seeking thermal treatment capabilities. The five-to-ten year viability window favors operators with EPA regional office contracting relationships and balance sheet capacity for performance-guaranteed remediation obligations. Monitor ECHA PFAS regulatory designation timing as inflection indicator for specialized destruction technology demand expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Fixed-base thermal desorption facility buildout in EPA Region 5 secures Superfund contract access. |
| Backward Integration | In-house microbial consortium cultivation reduces agricultural substrate cost volatility exposure. |
| Technology Licensing | Electrokinetic remediation patent portfolios unlock mining legacy site access in Australia and Canada. |
| Long-term Supply Agreement | Exclusive hydrogen peroxide sourcing contracts lock in chemical oxidation input cost stability. |
| Joint Venture | Municipal brownfield program administration partnerships in Detroit and Cleveland accelerate project origination. |
Research Methodology
Document review covered EPA CERCLA site databases, ECHA REACH substance registrations, and MEE soil pollution prevention law enforcement records, complemented by interviews with thermal treatment facility operators, hazardous waste logistics coordinators, brownfield redevelopment project managers, and state environmental agency procurement officers. Secondary validation drew from EPA Superfund expenditure reports, EU Soil Monitoring Law implementation guidance, and customs data on thermal desorption equipment trade flows. Bottom-up project pipeline assessment and top-down regulatory obligation modeling were triangulated to establish market sizing.
Historical remediation contract award patterns were cross-referenced against expert panel input on technology selection criteria across the projection horizon. Segmentation modeling incorporated technology type, application sector, deployment modality, and end-user procurement sophistication. CAGRs were derived from regulatory obligation timelines and treatment capacity expansion trajectories. Industry-specific inputs included EPA regional office enforcement priority shifts and ECHA emerging contaminant designation proceedings.
The model holds under steady EPA Superfund enforcement intensity and ECHA REACH threshold stability; deviation in PFAS regulatory designation timing or hazardous waste landfill capacity constraints would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Monitoring
Environmental Technology Market
Environmental Monitoring
Air Quality Monitoring Equipment Market
Environmental Monitoring
Global Weather Forecasting Services Market
Environmental Monitoring
Environmental Hazard Monitoring (EHM) Software Market
Environmental Monitoring
Asia-Pacific Cloud Seeding Market
Environmental Monitoring
US Environmental Testing Market
Environmental Monitoring
LAMEA Emission Monitoring System Market
Environmental Monitoring
Environmental Testing Market
Environmental Monitoring
Global on-Line Total Organic Carbon (TOC) Analyzer Market
Environmental Monitoring
Canada Cloud Seeding Market
Environmental Monitoring
Environmental Test Equipment Market
Environmental Monitoring
North America Emission Monitoring System Market
Environmental Monitoring
Middle East and Africa Air Quality Monitoring Market
Environmental Monitoring
United States Erosion Sediment Control Market
Environmental Monitoring
Global Environmental Sensor Market
Environmental Monitoring
Asia Pacific Air Quality Monitoring Market