
 Mining Waste Management Market | 2026-2036
Mining Waste Management Market Size, Share, and Industry Trends Forecast 2026-2036
Mining Waste Management Market Intelligence
Australia's significant investment in critical minerals mining capacity is reconfiguring the landscape for specialized waste management services. Veolia Environnement SA leverages its extensive global portfolio to offer integrated water and waste solutions for complex mine sites. Tetra Tech Inc. differentiates through its high-end consulting and engineering services focused on tailings dam safety and environmental compliance. Cleanaway Waste Management Limited dominates the Australian domestic market with its comprehensive collection and disposal infrastructure.
Mining waste management involves the processes for handling materials generated during mineral extraction, including overburden and tailings. The primary purpose is to safely store or reprocess these geochemically complex materials to prevent environmental contamination. Tailings management constitutes the most significant waste type challenge, demanding advanced physical separation and chemical treatment technologies. While disposal services form the market's foundation, monitoring and consulting services are experiencing faster growth.
Regulations from bodies like the US Environmental Protection Agency (EPA) and China's Ministry of Ecology and Environment (MEE) mandate strict controls on waste disposal. The Global Industry Standard on Tailings Management (GISTM) is pushing operators towards safer, more transparent lifecycle planning for waste facilities. Consequently, the strategic choice for mining operators is whether to view waste purely as a liability or as a potential resource for valorization.
Market Dynamics
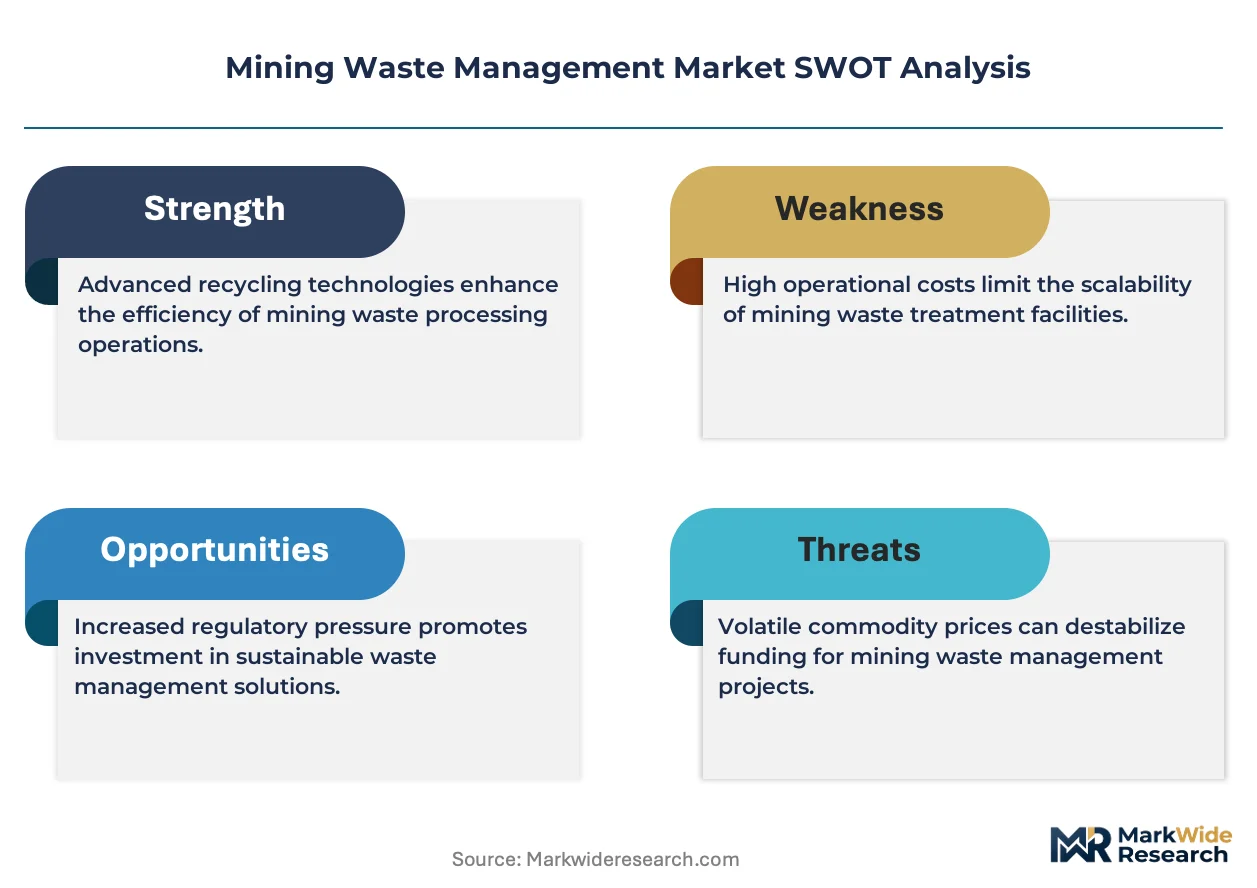
The central force shaping the mining waste management market is the regulatory and investor-led push for circular economy principles. This pressure transforms waste from a liability requiring containment into a potential asset for valorization, altering the service and technology demands from mining operators.
Growth Catalysts
- Global Tailings Standards:The widespread adoption of the Global Industry Standard on Tailings Management (GISTM) compels operators to invest in safer storage designs, advanced monitoring technologies, and transparent lifecycle planning, directly driving demand for specialized engineering and consulting services.
- Energy Transition Minerals:Heightened extraction of copper, lithium, and cobalt to support electric vehicle and renewable energy infrastructure generates vast new quantities of tailings and overburden, creating a baseline expansion for waste handling and disposal services.
- Waste Valorization Economics:Advances in reprocessing technologies, combined with higher commodity prices, make it economically feasible to extract residual metals from historical tailings dumps, creating a new market for specialized mineral recovery services in regions like Australia.
Market Restraints
- High Capital Intensity:The substantial upfront capital expenditure required to construct and line tailings storage facilities (TSFs) and install advanced water treatment plants according to modern standards acts as a significant financial barrier for junior and mid-tier miners.
- Geochemical Complexity:The highly variable and complex geochemistry of waste materials from certain ore bodies makes chemical treatment and metal recovery technically difficult and often uneconomical, limiting the universal applicability of reprocessing solutions.
- Regulatory Fragmentation:A lack of harmonized waste management regulations across different countries creates compliance challenges and investment uncertainty for multinational mining companies operating in jurisdictions with evolving or less stringent environmental enforcement.
Strategic Opportunities
- Digital Twin Monitoring:The development of digital twin platforms that integrate sensor data with geotechnical models offers a significant opportunity to provide predictive analytics for tailings dam stability, creating a new high-value service category.
- Reprocessing-as-a-Service:Service providers can develop business models focused on reprocessing client-owned tailings piles on a tolling or profit-sharing basis, shifting from a cost-center service to a revenue-generating partnership.
- Emerging Mining Frontiers:Expanding sophisticated waste management and environmental compliance services into developing mining regions in Africa and Southeast Asia presents a major growth opportunity as these areas attract investment and face greater environmental scrutiny.
Industry Challenges
- Talent Scarcity:A persistent shortage of experienced geotechnical engineers and hydrogeologists with expertise in modern tailings facility design, risk assessment, and closure planning constrains the industry's capacity to meet rising demand for GISTM-compliant projects.
- Legacy Site Liabilities:Managing and decommissioning orphaned or aging tailings facilities, which often lack proper documentation and were built to lower standards, poses significant technical, financial, and reputational risks for operators and governments.
- Social License to Operate:Gaining community and regulatory approval for new or expanded waste storage facilities is increasingly difficult due to heightened public awareness and concern over potential environmental impacts, leading to protracted project delays and cancellations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mining Waste Management Market |
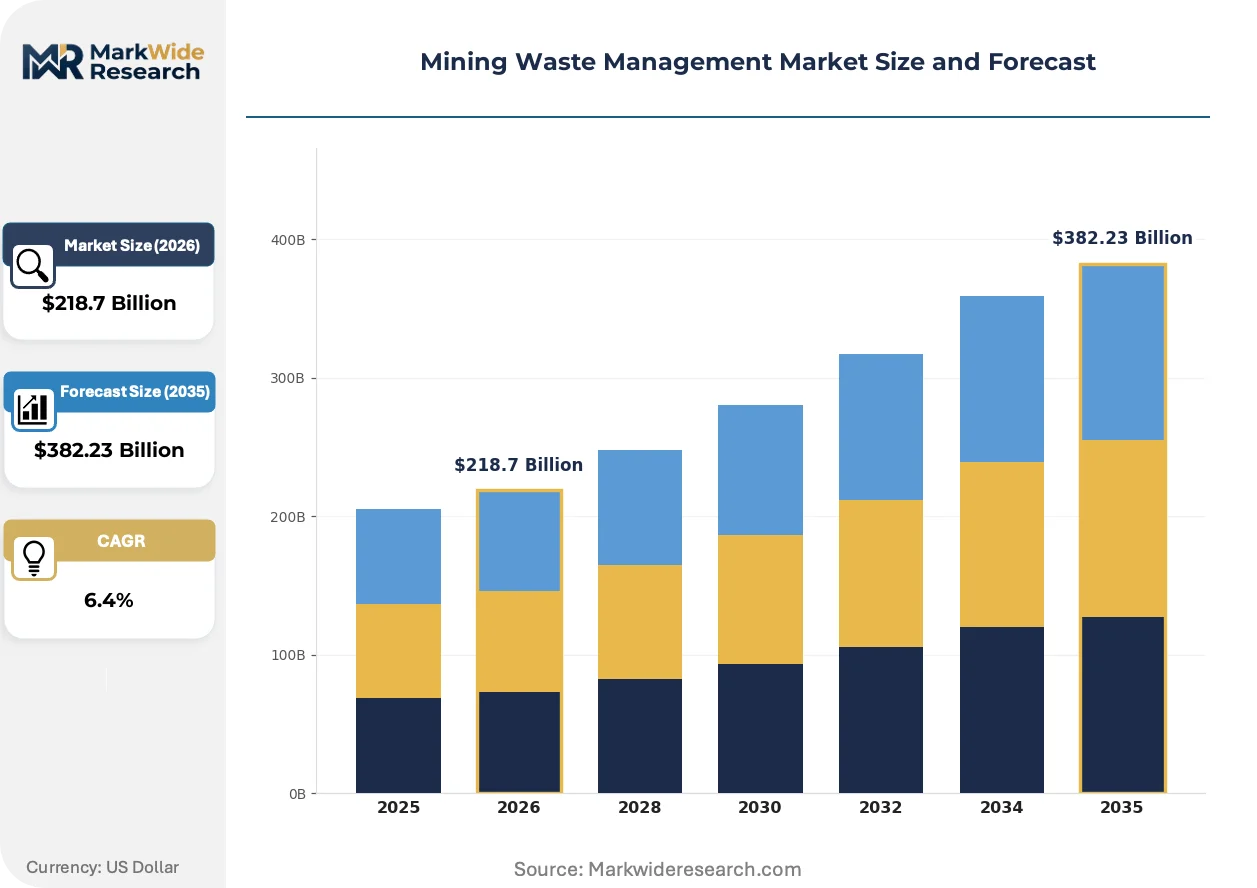
| Market Size in 2026 | $218.7 Billion |
| Market Size in 2035 | $382.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Waste Type: Tailings, Slag, Overburden, Mine Water Technology: Physical Separation, Chemical Treatment, Biological Treatment, Thermal Treatment End User: Mining Companies, Environmental Consultants, Regulatory Agencies, Waste Management Firms Service Type: Disposal Services, Recycling Services, Monitoring Services, Consulting Services |
| Companies Covered | SUEZ Group, Remondis SE & Co. KG, Veolia Environnement SA, Cleanaway Waste Management Limited, Biffa plc, Tetra Tech Inc., Clean Harbors Inc., China Everbright Environment Group, Stantec Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mining Waste Management Market Strategic Shifts & Innovations
The industry's operational paradigm is shifting from containment-focused disposal to resource recovery and risk mitigation. This evolution is driven by the convergence of digital monitoring technologies, stricter global standards, and new commercial models centered on waste valorization.
Sensor-based sorting and advanced physical separation technologies allow for the early segregation of waste rock from valuable ore. Major operators are adopting these systems to boost mill throughput and reduce the volume of material sent to tailings facilities. This pre-concentration at the mine face is rendering obsolete the traditional, energy-intensive practice of grinding and processing large volumes of low-grade, undifferentiated material.
China's "dual carbon" goals and stricter enforcement by the Ministry of Ecology and Environment (MEE) are mandating greater water recycling and reduced solid waste footprints from mining operations. The policy is forcing domestic miners, particularly in the coal and rare earth sectors, to invest heavily in dewatering technologies and dry-stack tailings solutions. Consequently, the dry-stacking equipment and engineering segment is experiencing accelerated adoption within the Chinese market.
A behavioral shift is evident as mining companies increasingly outsource the entire waste management function under long-term, performance-based contracts. This move away from procuring discrete services like construction or monitoring disrupts the fragmented vendor landscape, favoring integrated providers. This model of transferring operational risk is most visible in major mining jurisdictions like Chile and Peru, where water scarcity and seismic risk elevate the complexity of tailings management.
Mining Waste Management Market Segmentation
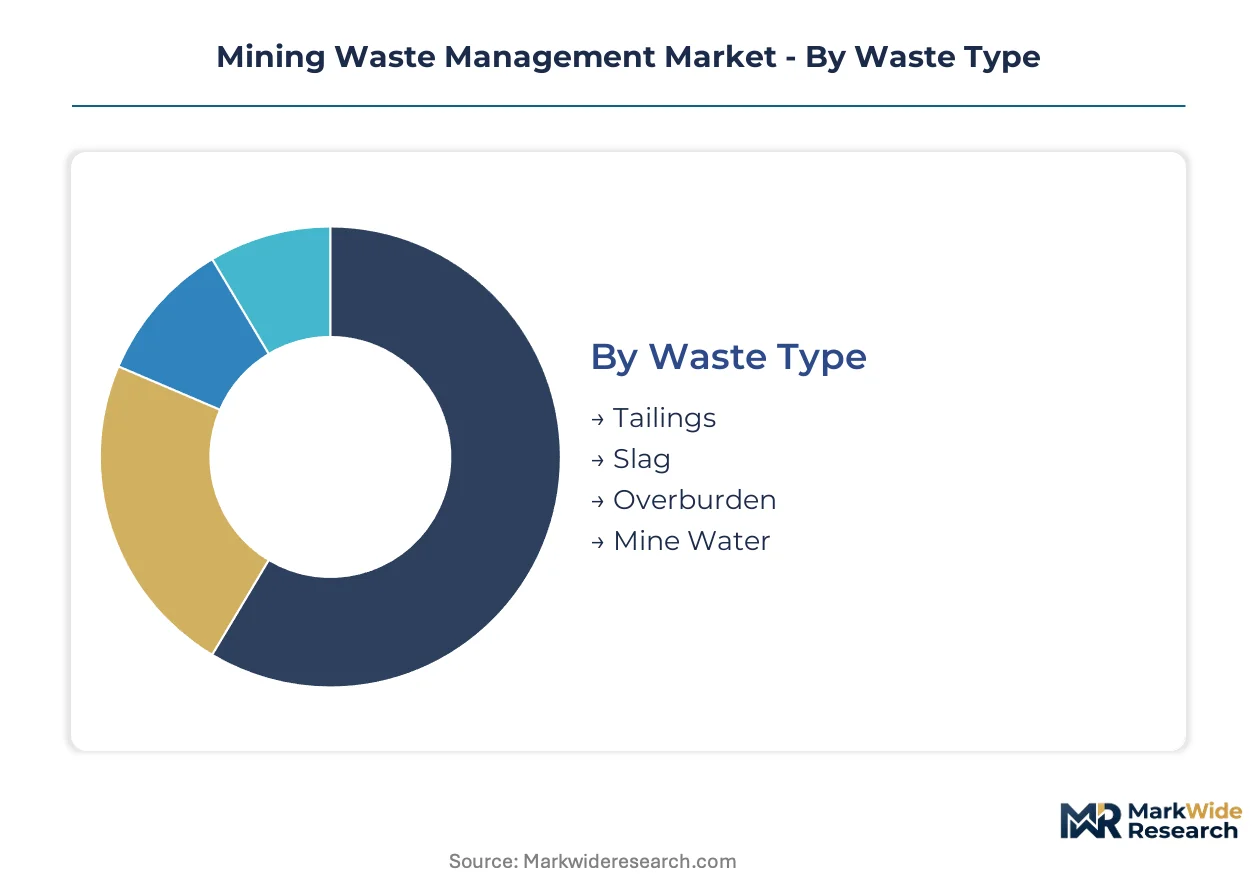
The mining waste management market exhibits diverse operational requirements and strategic priorities, necessitating a granular understanding of its segmented components. This segmentation allows stakeholders to identify specific challenges and opportunities across waste types, technological applications, end-user demands, and service offerings.
Waste Type:
The after-sales service intensity for mining waste management varies significantly based on the specific waste type, influencing the specialized handling and reprocessing requirements.
- Tailings:This geochemically complex slurry consists of fine-grained rock particles and process water, remaining after valuable minerals are extracted. Demand for advanced management concentrates in major mining jurisdictions like Australia and Chile, driven by stringent environmental regulations and high-volume operations.
- Overburden:Unconsolidated rock and soil overlying an ore deposit is removed to access the valuable mineral. Vast quantities are generated globally, particularly in open-pit mines, requiring efficient disposal and land rehabilitation strategies.
- Slag:This vitreous by-product from smelting and refining metallic ores often contains residual metals, presenting opportunities for recovery.
- Mine Water:Water collected from mining operations is frequently contaminated with heavy metals and acidity, needing extensive treatment before discharge.
Tailings holds the largest share; momentum sits with Mine Water as treatment technologies advance.
Technology:
The application of specific technologies directly addresses the diverse physical and chemical properties of mining waste materials.
- Physical Separation:Techniques like sensor-based sorting and gravity separation remove waste rock from valuable ore before processing. This reduces the volume of material sent to tailings facilities and improves mill throughput in regions like China.
- Chemical Treatment:Processes employing reagents neutralize contaminants, precipitate metals, or stabilize hazardous compounds in mine water and tailings. This is essential for environmental compliance in heavily regulated areas such as the EU.
- Biological Treatment:This technology utilizes microorganisms to remove or transform contaminants, particularly effective for acid mine drainage and bioremediation of impacted sites.
- Thermal Treatment:High-temperature processes are used for waste reduction, metal recovery from specific slags, or detoxification of certain hazardous mining wastes.
Physical Separation technologies drive efficiency; Chemical Treatment solutions are expanding most quickly for complex waste streams.
End User:
Different customer types within the mining ecosystem drive distinct service requirements and demand profiles for waste management solutions.
- Mining Companies:As primary generators of mining waste, these operators require comprehensive solutions for tailings, overburden, and mine water management. Their demand is concentrated in Australia and Chile, where large-scale operations necessitate robust waste infrastructure.
- Waste Management Firms:Specialized third-party providers offer integrated services, including collection, disposal, and reprocessing of mining waste. These firms are gaining traction in regions like Chile and Peru through long-term, performance-based contracts.
- Environmental Consultants:These specialists offer expertise in environmental impact assessments, regulatory compliance, and risk management for mining waste facilities.
- Regulatory Agencies:Government bodies like the US EPA and China's MEE establish and enforce environmental standards for mining waste disposal and treatment.
Mining Companies represent the largest end-user segment; Waste Management Firms are experiencing the steepest expansion trajectory due to outsourcing trends.
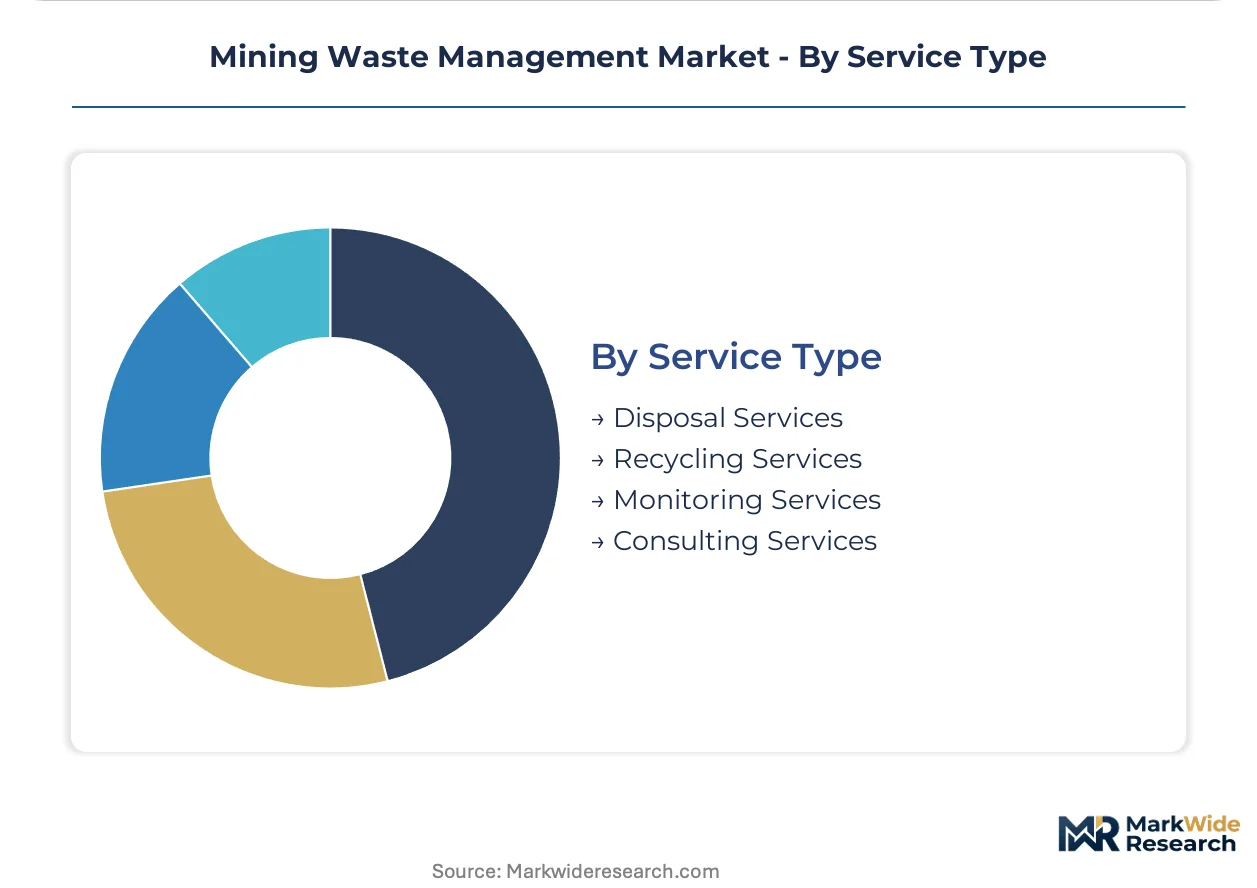
Service Type:
The margin profiles across various service types reflect the differing levels of technical complexity, capital investment, and regulatory compliance required.
- Disposal Services:These services involve the safe and compliant storage of mining waste, primarily in tailings storage facilities and overburden dumps. This foundational service is critical across all mining operations, particularly in regions with high volumes like Australia.
- Consulting Services:These services provide high-end engineering, risk assessment, and environmental compliance advice, often focusing on GISTM implementation and lifecycle planning. Demand for these services is growing rapidly in major mining jurisdictions.
- Recycling Services:These services focus on reprocessing historical or fresh tailings to recover residual metals or other valuable materials, creating new revenue streams.
- Monitoring Services:These services utilize advanced sensors and digital twin platforms to track the stability and environmental performance of waste facilities, especially for tailings dams.
Disposal Services form the market's foundation; Consulting Services are gaining share fastest due to increasing regulatory demands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Global Industry Standard on Tailings Management (GISTM) anchors the global push for enhanced mining waste management practices. This standard compels operators to invest in safer storage designs and advanced monitoring technologies. Regional dynamics reflect diverse regulatory frameworks and mineral extraction intensities, shaping localized demand for specialized services.
Australia
Australia's significant investment in critical minerals mining capacity drives demand for advanced waste management solutions. The country's stringent environmental regulations push for sophisticated tailings reprocessing and land rehabilitation strategies. Western Australia, a major mining hub, sees concentrated activity in waste valorization and digital twin monitoring for tailings facilities.
Chile
Heightened extraction of copper and lithium in Chile generates vast quantities of tailings and overburden. Water scarcity and seismic risk elevate the complexity of tailings management, fostering demand for dewatering technologies. The Atacama Desert region, central to copper mining, actively adopts performance-based contracts for integrated waste management services.
China
China's "dual carbon" goals and stricter enforcement by the Ministry of Ecology and Environment (MEE) mandate greater water recycling and reduced solid waste footprints. Domestic miners invest heavily in dewatering technologies and dry-stack tailings solutions. Inner Mongolia and Xinjiang, key coal and rare earth mining regions, experience accelerated adoption of dry-stacking equipment.
United States
The US Environmental Protection Agency (EPA) mandates strict controls on waste disposal from mining operations. This drives demand for environmental consulting and risk management services, particularly for legacy site liabilities. Nevada, a prominent gold mining state, focuses on advanced monitoring systems and closure planning for waste facilities.
Mining Waste Management Market Key Industry Players
Integrated waste management firms and specialized engineering consultants split the market for mining waste management services. The industry exhibits a tiered structure, with global players offering comprehensive solutions alongside niche technology providers. Companies pursue strategic partnerships to expand geographic reach and diversify their service portfolios.
Within the integrated services tier, Veolia Environnement SA leverages its extensive global portfolio to offer complex water and waste solutions. Tetra Tech Inc. exemplifies high-end consulting, focusing on tailings dam safety and environmental compliance. Cleanaway Waste Management Limited, an Australian-based firm, anchors the domestic market with its comprehensive collection and disposal infrastructure.
| Leading Market Players |
|---|
| SUEZ Group |
| Remondis SE & Co. KG |
| Veolia Environnement SA |
| Cleanaway Waste Management Limited |
| Biffa plc |
| Tetra Tech Inc. |
| Clean Harbors Inc. |
| China Everbright Environment Group |
| Stantec Inc. |
| Others |
Cost & Logistics Intelligence
The Atacama Desert's logistical corridors, vital for copper and lithium operations, heavily influence service pricing due to specialized transport and dewatering equipment costs. This supply concentration affects downstream price differentiation for waste management services.
Pricing Analysis
Geographic price spreads for mining waste management services vary significantly between Australia's regulated market and less mature regions. Project-based contracts with long-term performance clauses dominate, reflecting the capital-intensive nature of infrastructure and specialized equipment. Price differentiation stems from remote site access, stringent regulatory compliance, and integrated after-sales monitoring. Pricing pressure stems from mining operators seeking cost efficiencies, yet GISTM implementation drives higher service costs. Junior miners exhibit high price sensitivity, while major operators prioritize risk mitigation and compliance.
Supply Chain Analysis
Single-source vulnerability for specialized dewatering and dry-stacking equipment dominates the mining waste management supply chain. Key equipment and technology suppliers concentrate in China, Germany, and North America. The supply chain draws from critical components like advanced sensors and chemical reagents, often subject to global commodity price volatility. Distribution runs through integrated service providers and direct sales channels to mining companies, particularly for large-scale projects in Australia and Chile.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mining waste management market is experiencing high-growth disruption, driven by the Global Industry Standard on Tailings Management (GISTM) and advancements in digital twin monitoring. This confluence reshapes operational paradigms and creates new service opportunities.
For Market Incumbents:
Insulate core service lines by acquiring niche technology providers specializing in advanced physical separation and digital monitoring platforms. Expand integrated water and waste solutions, particularly in GISTM-compliant regions, to counter emerging specialized technology firms. Leverage existing client relationships to offer long-term, performance-based contracts in regions like Chile. Invest in R&D for next-generation reprocessing technologies to maintain a competitive edge.
For New Entrants and Emerging Players:
Build out specialized reprocessing-as-a-service models, targeting historical tailings dumps in regions with high commodity prices like Australia. Penetrate the mid-tier mining segment in emerging frontiers such as Africa and Southeast Asia by offering GISTM-compliant consulting services. Focus on digital twin monitoring platforms that provide predictive analytics for tailings dam stability. Emphasize waste valorization and enhanced risk reduction as a core value proposition.
For Investors and Strategic Acquirers:
The Global Industry Standard on Tailings Management (GISTM) reshapes the acquisition landscape, favoring firms with proven compliance and advanced technical expertise. The market offers long-term viability, driven by non-discretionary environmental regulations and critical mineral demand. Target specialized engineering firms and technology providers in dewatering, dry-stacking, and metal recovery. Increased enforcement by China's Ministry of Ecology and Environment (MEE) serves as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Dry-Stacking Technology | Supports China's "dual carbon" goals by reducing water footprints from mining operations. |
| Develop Digital Twin Platforms | Offers predictive analytics for tailings dam stability, enhancing GISTM compliance. |
| Expand Reprocessing-as-a-Service | Creates new revenue streams by extracting residual metals from historical tailings in Australia. |
| Form Strategic Partnerships | Enables integrated waste solutions for complex mine sites in Chile and Peru. |
| Acquire Geotechnical Engineering Firms | Addresses talent scarcity in modern tailings facility design and risk assessment. |
Research Approach
Two parallel data streams informed the analysis: extensive primary interviews and rigorous secondary validation. Primary insights were gathered from mining company executives, waste management firm leaders, environmental consultants, and regulatory officials. Secondary data points were validated against US Environmental Protection Agency (EPA) reports, China's Ministry of Ecology and Environment (MEE) directives, and Global Industry Standard on Tailings Management (GISTM) documentation. Bottom-up and top-down triangulation ensured data integrity.
Forecast inputs considered critical mineral extraction rates, evolving regulatory compliance costs, and technology adoption curves across the analysis window. Segmentation dimensions included waste type, technology application, end-user profiles, service offerings, and regional regulatory stringency. Compound annual growth rates were derived from historical trends and projected technology penetration. Energy transition mineral demand and GISTM adoption rates served as key industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by major mining operators or integrated waste management firms would shift outcomes. Projections reflect current assumptions, but unforeseen geopolitical shifts impacting mineral supply or rapid technological breakthroughs could revise them. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
APAC Bio-Medical Waste Management Market
Waste Management & Pollution Control
Asia Pacific Medical Waste Management Market
Waste Management & Pollution Control
UAE Industrial Waste Management Market
Waste Management & Pollution Control
Industrial Solid Waste Management Market
Waste Management & Pollution Control
Trash Pump Market
Waste Management & Pollution Control
Asia-Pacific Hazardous Waste Handling Automation Market
Waste Management & Pollution Control
South American Waste Management Market
Waste Management & Pollution Control
Europe Waste Recycling Services Market
Waste Management & Pollution Control
India E-Waste Management Market
Waste Management & Pollution Control
Saudi Arabia Waste Management Market
Waste Management & Pollution Control
Paper Recycling Market
Waste Management & Pollution Control
India Plastic Waste Management Market
Waste Management & Pollution Control
Europe Municipal Solid Waste Management Market
Waste Management & Pollution Control
India Municipal Solid Waste Management Market
Waste Management & Pollution Control
Sludge Management Equipment Market
Waste Management & Pollution Control
Global Pharmaceutical Waste Management Market