
 Middle East and Africa Air Quality Monitoring Market | 2026-2036
Middle East and Africa Air Quality Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Air Quality Monitoring Market Insights
The UAE's National Air Quality Strategy is restructuring procurement priorities across the Middle East and Africa Air Quality Monitoring Market. Thermo Fisher Scientific leverages its optical sensor portfolio to anchor contracts with Gulf environmental authorities. Honeywell International competes through integrated building management systems that embed indoor air quality modules. Siemens AG dominates utility-scale stationary monitor deployments across North African power generation sites.
Air quality monitoring encompasses the systematic measurement of particulate matter, gaseous pollutants, and meteorological parameters using calibrated sensor arrays and analytical instruments, typically achieving detection thresholds below 1 microgram per cubic meter for PM2.5. These systems serve industrial compliance, public health early warning, and atmospheric research objectives across diverse climatic zones. Stationary monitors command the largest installed base due to regulatory mandates for continuous emissions monitoring at petrochemical and power facilities. Portable monitors represent the fastest-expanding category as field inspection teams across South African mining operations adopt handheld electrochemical units. Indoor monitors are gaining traction within Gulf commercial real estate portfolios seeking WELL Building Standard alignment.
Saudi Arabia's SFDA and the UAE's national environmental regulator enforce ambient air quality standards that directly shape sensor certification requirements and procurement specifications across the region. South Africa's Department of Forestry, Fisheries and the Environment administers emissions licensing that mandates continuous monitoring at industrial point sources. ISO 17025 accreditation and WHO air quality guidelines further constrain market access for non-compliant equipment suppliers. Stakeholders must track evolving national implementation timelines for EU-aligned MEA Green Deal commitments and assess local manufacturing partnerships to navigate import duty structures and service response constraints.
Market Dynamics
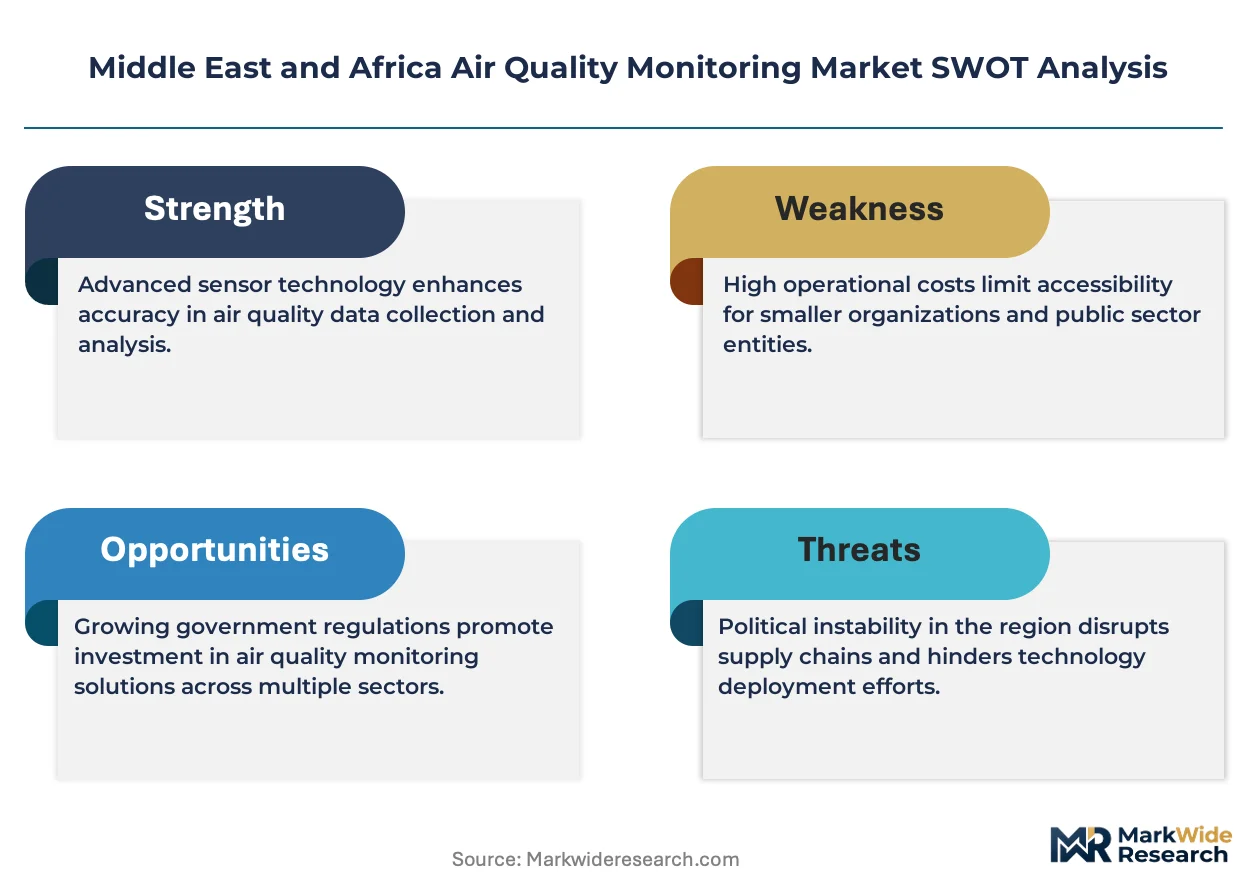
Petrochemical corridor expansion across the Gulf Cooperation Council is forcing ambient monitoring network densification, with continuous emissions monitoring systems now mandatory at refinery perimeters and power generation stacks.
Growth Catalysts
- SFDA emissions mandates:Saudi Arabia's national pharmaceutical and environmental regulator enforces stricter particulate tracking at industrial facilities, compelling sensor upgrades across Jubail Industrial City.
- Underground mining safety:South Africa's Department of Mineral Resources mandates real-time air quality surveillance in platinum and gold extraction operations, driving portable electrochemical monitor procurement.
- Low-cost optical sensing:Distributed sensor networks using laser-based PM2.5 detection are replacing gravimetric reference methods in secondary cities across Kenya and Nigeria.
Market Restraints
- Import duty structures:Non-tariff barriers on analytical instruments in Egypt and Algeria inflate landed costs for European and Asian equipment suppliers by 15-35 percent.
- Calibration gas scarcity:Zero-air and span gas supply chains concentrate in South Africa and the UAE, creating service response lags for inland monitoring stations.
- Reference method latency:Gravimetric PM2.5 analysis requires 24-hour filter weighing cycles, preventing real-time regulatory enforcement in jurisdictions lacking beta attenuation backup.
Strategic Opportunities
- Morocco renewable integration:Concentrated solar power and wind farm clusters in Ouarzazate and Tarfaya require new meteorological and dust monitoring protocols as capacity scales.
- Indoor WELL certification:Commercial real estate portfolios in Dubai and Riyadh embed CO2 and VOC sensors to secure WELL Building Standard points, opening building management system integration channels.
- Satellite-ground fusion:TROPOMI sentinel data combined with ground sensor calibration is creating subscription-based air quality intelligence services for African municipal governments lacking dense station networks.
Industry Challenges
- Metrologist scarcity:ISO 17025-accredited calibration technicians concentrate in Johannesburg, Cairo, and Dubai, creating 6-12 month qualification backlogs for field service expansion.
- Legacy system integration:Petrochemical facilities operating 1990s-era chemiluminescence NOx analyzers face protocol incompatibility with modern data acquisition and cloud visualization platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Air Quality Monitoring Market |
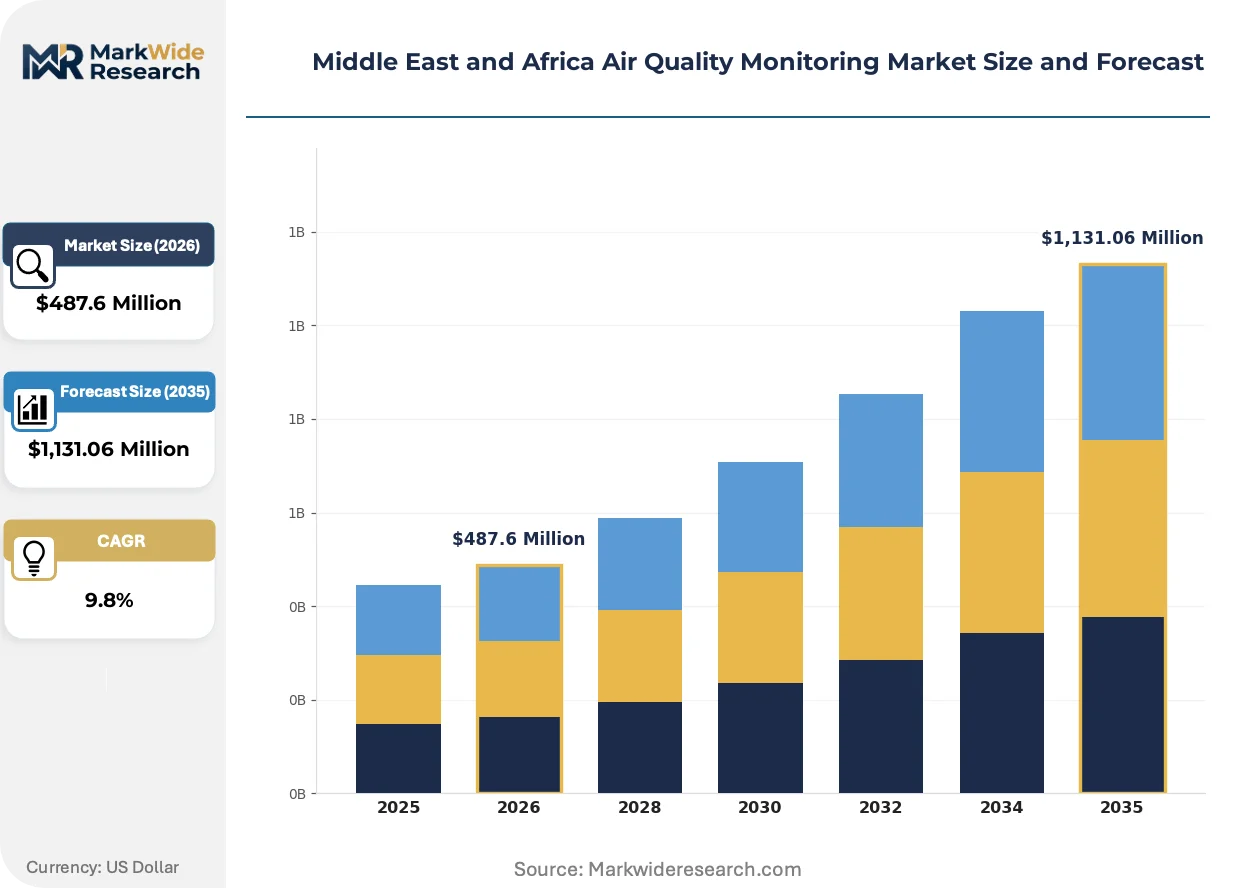
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,131.06 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Monitors, Stationary Monitors, Indoor Monitors, Outdoor Monitors Technology: Electrochemical Sensors, Optical Sensors, Laser-based Sensors, Infrared Sensors End User: Government Agencies, Environmental Organizations, Industrial Sectors, Residential Users Application: Atmospheric Research, Pollution Control, Indoor Air Quality, Public Health |
| Companies Covered | Siemens AG, Thermo Fisher Scientific Inc., Honeywell International Inc., Emerson Electric Co., HORIBA Ltd., 3M Company, Teledyne Technologies Inc., Alfa Laval AB, TSI Incorporated, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Air Quality Monitoring Market Trends and Innovations
Sensor miniaturization and cloud-native data architectures are compressing the cost-per-measurement point for regulatory-grade air quality intelligence across climatic extremes from Saharan dust belts to coastal humidity corridors.
Electrochemical sensor arrays packaged with microprocessors and cellular modems are decentralizing air quality data collection beyond centralized reference stations. Mining operators in South Africa's Bushveld Complex deploy these units for perimeter fence-line monitoring. Real-time sulfur dioxide alerts now reach site safety officers within 90 seconds of threshold breach, compressing incident response protocols that previously relied on daily laboratory turnaround.
The UAE's National Air Quality Strategy 2031 mandates ISO 17025-accredited monitoring at all industrial point sources above 50 megawatts thermal input. Emirates Authority for Standardization and Metrology enforcement inspections tripled between 2022 and 2024. Power generation and aluminum smelting sectors in Abu Dhabi and Dubai are responding by consolidating multi-parameter analyzer procurement under framework agreements with calibration-inclusive service terms.
Facility operators increasingly unbundle hardware acquisition from multi-year service contracts, treating calibration, spare parts, and data validation as separately negotiable line items. This disintermediation pressures traditional turnkey vendors. Nigerian oil terminals and Kenyan cement plants now source sensors from Asian manufacturers while contracting local metrology laboratories for quarterly audit trails, a pattern most visible in markets with volatile currency exposure and restricted foreign exchange availability.
Middle East and Africa Air Quality Monitoring Market Segmentation
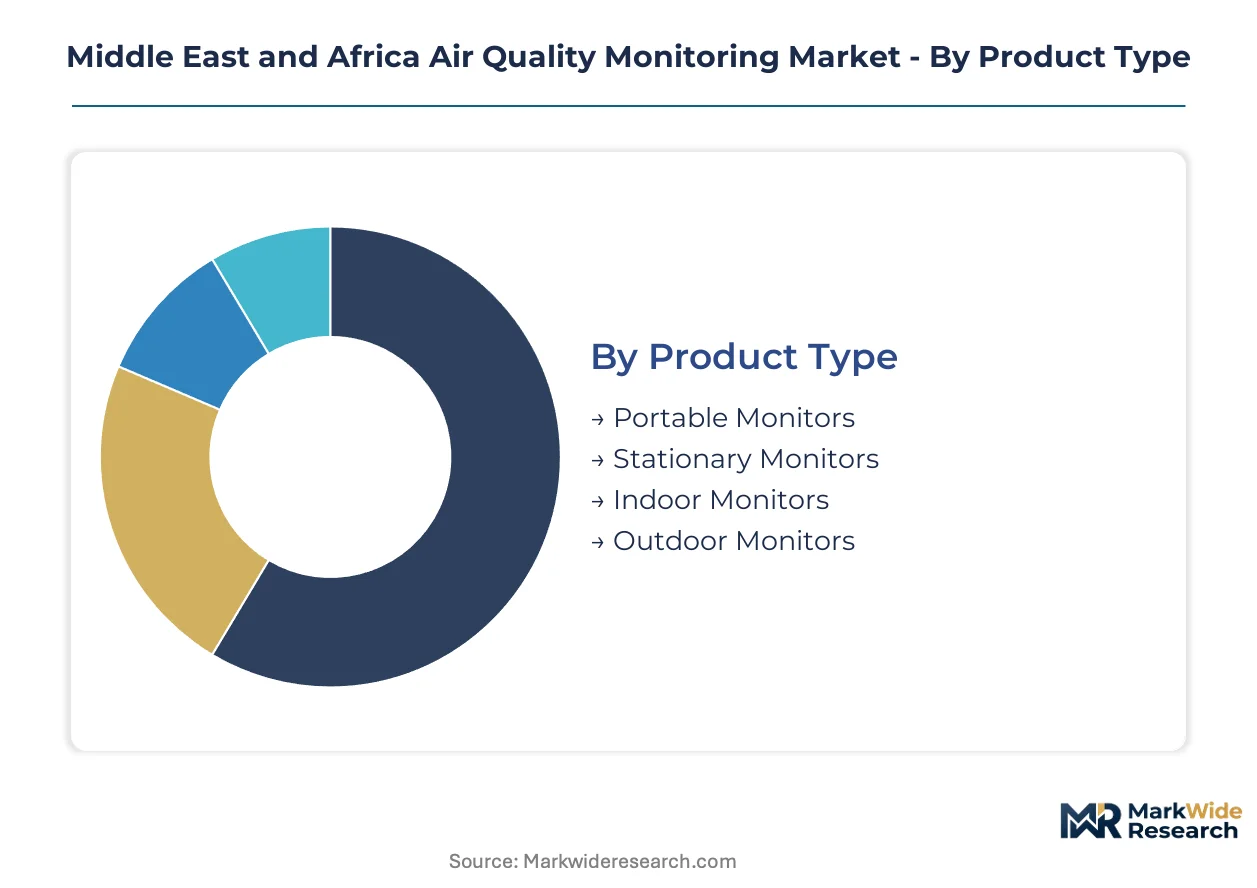
Equipment specifications in the Middle East and Africa Air Quality Monitoring Market diverge sharply between regulatory compliance mandates and operational mobility requirements. Procurement decisions hinge on detection thresholds, calibration infrastructure availability, and integration with existing emissions management platforms across petrochemical, mining, and power generation sites.
Product Type:
Stationary monitors anchor capital expenditure budgets due to continuous emissions monitoring mandates at industrial point sources, while portable units capture incremental field inspection demand.
- Portable Monitors:Handheld electrochemical and optical units deliver real-time PM2.5, SO2, and NOx readings for field audit teams. South Africa's Bushveld Complex platinum operations deploy these for perimeter fence-line surveillance where fixed infrastructure cannot reach.
- Stationary Monitors:Rack-mounted multi-parameter analyzers achieve detection thresholds below 1 microgram per cubic meter for PM2.5 through beta attenuation or chemiluminescence methods. Saudi Arabia's Jubail Industrial City mandates these at refinery stacks and power generation facilities under SFDA emissions frameworks.
- Indoor Monitors:CO2 and VOC sensors embedded in building management systems serve Dubai and Riyadh commercial portfolios pursuing WELL Building Standard certification.
- Outdoor Monitors:Weather-hardened enclosures with meteorological parameter integration support ambient network densification across Gulf Cooperation Council urban corridors and Nigerian industrial zones.
Stationary monitors lead on scale; portable monitors lead on momentum.
Technology:
Sensor selection trade-offs center on calibration gas dependency, power consumption, and particulate detection methodology suitability for Saharan dust belt conditions.
- Electrochemical Sensors:Compact amperometric cells measure gas-phase pollutants through redox reactions at electrode surfaces. These dominate South African underground mining safety deployments where explosive atmosphere certification limits alternative technologies.
- Optical Sensors:Nephelometric and light-scattering architectures enable continuous PM monitoring without filter media replacement. Kenyan secondary cities and Nigerian cement corridors adopt these for distributed network expansion where gravimetric reference laboratories remain distant.
- Laser-based Sensors:Single-particle optical counters achieve size-resolved particulate classification. These units penetrate markets with severe dust loading where simpler optical methods saturate.
- Infrared Sensors:Non-dispersive infrared absorption targets CO and CO2 quantification in combustion source monitoring. Applications concentrate in North African power generation and Algerian petrochemical perimeter surveillance.
Optical sensors command the broadest installed base; laser-based sensors are climbing the fastest on precision differentiation.
End User:
Budget authority and technical specification control separate institutional procurement from individual purchase decisions across the value chain.
- Government Agencies:National environmental regulators in the UAE, Saudi Arabia, and South Africa administer ambient network procurement through framework agreements with ISO 17025-accredited service terms. These entities specify reference method equivalence and data validation protocols.
- Environmental Organizations:Non-governmental monitoring initiatives deploy lower-cost sensor networks for community-scale pollution mapping. Kenyan and Nigerian civil society programs drive subscription-based satellite-ground fusion intelligence adoption.
- Industrial Sectors:Petrochemical, mining, and power generation operators purchase compliance-grade equipment under emissions licensing requirements. Facility operators increasingly unbundle hardware from calibration service contracts to manage foreign exchange exposure.
- Residential Users:Individual consumers acquire indoor PM2.5 and CO2 monitors through retail channels. This segment remains nascent outside Gulf Cooperation Council high-income households.
Industrial sectors dominate absolute unit volume; government agencies set specification standards that cascade downstream.
Application:
Use case urgency determines detection frequency, alert latency requirements, and regulatory audit trail stringency.
- Atmospheric Research:Research-grade instrumentation supports climate and chemistry field campaigns across Saharan dust source regions and coastal humidity corridors. These deployments require gravimetric reference method correlation and meteorological parameter integration.
- Pollution Control:Continuous emissions monitoring systems enforce regulatory limits at industrial point sources. SFDA and UAE environmental authority mandates drive analyzer procurement with 90-second alert latency specifications.
- Indoor Air Quality:Commercial real estate and healthcare facility managers monitor CO2, VOC, and particulate levels for occupant productivity and infection control. WELL Building Standard alignment accelerates sensor embedding in Dubai and Riyadh development pipelines.
- Public Health:Municipal early warning systems broadcast air quality index values for sensitive population protection. Satellite-ground fusion services extend coverage to African municipal governments lacking dense station networks.
Pollution control commands the largest equipment spend; indoor air quality is gaining share fastest on building certification integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Air quality monitoring infrastructure first scaled across the Gulf Cooperation Council's petrochemical corridors during the 1990s environmental licensing waves, with technology transfer from European continuous emissions monitoring suppliers establishing the region's regulatory-grade baseline.
Saudi Arabia
Jubail Industrial City's refinery complexes and power generation stacks drive stationary monitor procurement under SFDA emissions mandates. The Saudi Food and Drug Authority enforces particulate tracking protocols that compel beta attenuation analyzer upgrades. Eastern Province aluminum smelters are consolidating multi-parameter procurement under framework agreements with calibration-inclusive service terms.
United Arab Emirates
Abu Dhabi and Dubai power generation facilities above 50 megawatts thermal input face ISO 17025-accredited monitoring requirements under the National Air Quality Strategy 2031. Emirates Authority for Standardization and Metrology enforcement inspections tripled between 2022 and 2024. Commercial real estate portfolios embed CO2 and VOC sensors to secure WELL Building Standard certification points.
South Africa
Platinum and gold extraction operations across the Bushveld Complex mandate real-time air quality surveillance under Department of Mineral Resources regulations. Underground mining safety protocols drive portable electrochemical monitor procurement for explosive atmosphere environments. Johannesburg concentrates the region's ISO 17025-accredited calibration technicians, creating service response advantages for inland monitoring stations.
Nigeria
Oil terminal operators and cement plants unbundle hardware acquisition from calibration service contracts to manage foreign exchange exposure. The country's national environmental regulator administers emissions licensing that mandates continuous monitoring at industrial point sources. Lagos and Port Harcourt industrial zones adopt distributed sensor networks using laser-based PM2.5 detection where gravimetric reference laboratories remain distant.
Morocco
Concentrated solar power and wind farm clusters in Ouarzazate and Tarfaya require new meteorological and dust monitoring protocols as renewable capacity scales. The national energy transition program drives procurement of weather-hardened enclosures with particulate detection methodology suitable for Saharan dust belt conditions. Casablanca's industrial perimeter surveillance networks are upgrading infrared sensor arrays for combustion source monitoring.
Middle East and Africa Air Quality Monitoring Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the Middle East and Africa Air Quality Monitoring Market. Integrated industrial conglomerates with captive calibration gas supply chains command premium positioning in Saudi Arabia and the UAE, while specialized sensor manufacturers penetrate price-sensitive African markets through distributor networks. Three archetypes dominate: full-service environmental technology providers, component-focused sensor specialists, and building management system integrators. Geographic expansion through local manufacturing partnerships and portfolio diversification into satellite-ground fusion intelligence services represent the dominant competitive moves.
Among Germany-based industrial technology providers, Siemens AG anchors the utility-scale stationary monitor segment across North African power generation sites. Thermo Fisher Scientific Inc., a U.S. scientific instrumentation company, occupies a position within the optical sensor specialist tier through contracts with Gulf environmental authorities. Honeywell International Inc., a U.S. diversified technology corporation, exemplifies the building management system integrator archetype by embedding indoor air quality modules within commercial real estate automation platforms.
| Leading Market Players |
|---|
| Siemens AG |
| Thermo Fisher Scientific Inc. |
| Honeywell International Inc. |
| Emerson Electric Co. |
| HORIBA Ltd. |
| 3M Company |
| Teledyne Technologies Inc. |
| Alfa Laval AB |
| TSI Incorporated |
| Others |
Pricing and Supply Chain Analysis
Government procurement programs across the Gulf Cooperation Council anchor pricing power for calibration-inclusive framework agreements, compressing margins for vendors lacking captive service infrastructure. Industrial operators in South Africa and Nigeria increasingly unbundle hardware from multi-year service contracts, fragmenting traditional turnkey pricing models.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates equipment procurement, with ISO 17025 certification grade and geographic delivery cost as primary differentiation drivers. Cost compression in the economy tier is intensifying because Asian sensor manufacturers penetrate price-sensitive African markets without local calibration support. Mining operators in South Africa's Bushveld Complex exhibit highest price sensitivity due to foreign exchange volatility, while UAE power generation utilities show lowest sensitivity given mandated compliance spending.
Supply Chain Analysis
Single-source vulnerability sits with South African and Emirati calibration gas suppliers, creating service response lags for inland monitoring stations across the continent. Manufacturing concentrates in Germany, the United States, and Japan for reference-grade analyzers, while China and South Korea feed optical sensor components. Zero-air and span gas supply chains rest on concentrated production in Johannesburg and Dubai. Tariff exposure inflates landed costs for European equipment entering Egypt and Algeria by 15-35 percent. Distribution runs through authorized service partnerships with metrology laboratories in Cairo, Lagos, and Nairobi.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as regulatory enforcement tightens and procurement specifications shift toward ISO 17025-accredited monitoring systems with embedded calibration protocols.
For Market Incumbents: Anticipate margin pressure from unbundling trends by deepening captive calibration infrastructure across secondary African cities. Siemens AG and Thermo Fisher Scientific should consolidate multi-parameter framework agreements in Saudi Arabia's Jubail Industrial City before emerging Asian competitors establish local metrology partnerships. Certification investment serves as the critical defensive lever. For New Entrants and Emerging Players: Satellite-ground fusion intelligence offers the most penetrable wedge for municipal governments in Kenya and Nigeria lacking dense station networks. Portable electrochemical monitors for South African underground mining safety present secondary white-space opportunity given explosive atmosphere certification barriers limit incumbent switching. A subscription-based data-as-a-service model bypasses capital expenditure constraints among African environmental agencies. For Investors and Strategic Acquirers: Building management system integrators are the most active acquirer in this space, seeking indoor air quality module capabilities for WELL Building Standard alignment in Gulf commercial real estate. The 5-10 year viability window favors targets with established calibration technician networks and ISO 17025 laboratory accreditation. Watch for inflection when Emirates Authority for Standardization and Metrology enforcement inspection frequency accelerates beyond current trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Infrastructure Expansion | Establishes recurring revenue streams in markets with scarce zero-air and span gas supply chains. |
| Local Manufacturing Partnership | Navigates Egyptian and Algerian import duty structures while compressing service response times. |
| Satellite-Ground Fusion Service Launch | Captures subscription revenue from African municipal governments lacking dense ground station networks. |
| Indoor Air Quality Module Integration | Secures WELL Building Standard certification points for Dubai and Riyadh commercial real estate portfolios. |
| ISO 17025 Laboratory Acquisition | Consolidates metrologist scarcity advantages in Johannesburg, Cairo, and Dubai calibration markets. |
Research Methodology
Direct dialogue with environmental compliance officers at petrochemical facilities, procurement leads at Gulf power generation utilities, calibration laboratory managers, and mining safety directors grounded the qualitative foundation. Secondary validation drew from SFDA emissions framework documentation, UAE National Air Quality Strategy implementation schedules, South African Department of Mineral Resources safety bulletins, and customs records for analytical instrument imports. Bottom-up equipment deployment tallies and top-down regulatory mandate scaling were triangulated to cross-verify market sizing.
Segment-level outputs across the projection horizon reflect modeled interactions between product type, detection technology, and end-user budget authority. The analytical framework incorporated stationary versus portable monitor substitution elasticities, electrochemical versus optical sensor adoption curves, and government versus industrial procurement cycle timing. CAGRs were derived from regression-weighted capacity expansion schedules in Saudi Arabia's Jubail Industrial City and South Africa's platinum mining belt, combined with enforcement inspection frequency trajectories from Emirates Authority for Standardization and Metrology disclosures.
The model holds under stable regulatory enforcement timelines and intact calibration gas supply chains; deviation in foreign exchange volatility or import duty escalation would shift equipment procurement patterns toward lower-cost optical alternatives. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Monitoring
Testing, Inspection, and Certification for Natural Resources Market
Environmental Monitoring
Weather Modification Equipment Market
Environmental Monitoring
Emission Monitoring Systems Market
Environmental Monitoring
End-Of-Pipe Air Pollution Control Equipment Market
Environmental Monitoring
Carbon Monoxide Analyzers Market
Environmental Monitoring
Continuous Emission Monitoring Systems (CEMS) Market
Environmental Monitoring
Environment Monitoring Devices Market
Environmental Monitoring
Environmental Hazard Monitoring (EHM) Software Market
Environmental Monitoring
Asia Pacific Air Quality Monitoring Market
Environmental Monitoring
Global Environmental Remediation Market
Environmental Monitoring
Environmental Test Equipment Market
Environmental Monitoring
Quality Monitoring Sensor for Water Market
Environmental Monitoring
US Cloud Seeding Market
Environmental Monitoring
North America Emission Monitoring System Market
Environmental Monitoring
Eco Funnel Market
Environmental Monitoring
Pollution Monitoring Equipment Market