
 E-Scrap Recycling Market | 2026-2036
E-Scrap Recycling Market Size, Share, and Industry Trends Forecast 2026-2036
E-Scrap Recycling Market Analysis
Component refurbishment revenue is tilting toward precious metal recovery streams as virgin mining costs escalate. Aurubis AG leverages smelter integration to sustain copper and gold output from printed circuit boards. Umicore SA anchors its position through hydrometallurgical expertise in cobalt and rare earth separation. Sims Limited competes across collection logistics, operating dense networks in Australia and North America.
E-scrap recycling encompasses the disassembly, shredding, and material separation of end-of-life electronic equipment containing recoverable fractions of copper, gold, palladium, and rare earth elements, with mechanical shredding typically reducing devices to sub-100mm particles before density-based and magnetic sorting. The process serves primary metal producers, electronics manufacturers, and battery makers seeking compliant feedstock alternatives to mined concentrates. Metals recovery dominates value capture given concentrated precious metal content in circuit boards and connectors. Pyrometallurgy leads processing technology deployment due to proven scalability for complex multi-element feeds. Hydrometallurgy is gaining traction for lithium-ion battery black mass given lower energy intensity and selective leaching capabilities.
The EPA regulates cathode ray tube disposal under hazardous waste rules, while the EU WEEE Directive mandates collection targets and recycling efficiencies for member states. REACH restrictions on substance hazards shape permissible recovery chemistries and residue disposal pathways. Stakeholders must monitor how emerging battery passport requirements and critical raw materials acts reshape feedstock access and recovery economics.
Market Dynamics
Extended producer responsibility mandates are forcing consumer electronics manufacturers to internalize end-of-life collection costs, fundamentally restructuring competitive economics away from pure commodity recovery toward integrated circular service models.
Growth Catalysts
- EU WEEE Directive collection targets:Member states must achieve prescribed recovery rates for electrical and electronic equipment, compelling national infrastructure buildouts and certified recycler accreditation.
- Lithium-ion battery black mass processing:Electric vehicle retirement waves are generating feedstock volumes that hydrometallurgical circuits can selectively leach for cobalt, nickel, and lithium recovery.
- Germany:Dense urban mining clusters around Hamburg and Munich concentrate smelter capacity, mechanical preprocessing, and precious metal refining within 150-kilometer radii.
Market Restraints
- Copper concentrate price volatility:Virgin mining output fluctuations compress secondary smelter margins when primary metal prices collapse below recovery processing thresholds.
- Informal sector concentration in West Africa and Southeast Asia:Uncontrolled manual dismantling of imported e-scrap undercuts compliant recyclers on labor costs while externalizing environmental liabilities.
- Basel Convention cross-border shipment restrictions:Hazardous waste classifications for printed circuit boards create permit bottlenecks that fragment feedstock flows between jurisdictions.
Strategic Opportunities
- India:E-waste management rules mandate phased collection targets for manufacturers, creating first-mover advantages for integrated dismantling-refining operations in Delhi-Mumbai corridors.
- Battery passport mandates:Digital material traceability requirements will privilege recyclers with verified chain-of-custody systems for critical raw materials recovery.
- Robotic disassembly and AI-driven component recognition:Converging automation technologies enable profitable processing of lower-grade mixed electronics previously rejected by manual sorting operations.
Industry Challenges
- Smelter emissions compliance:EPA hazardous waste combustion standards and EU Best Available Techniques reference documents require continuous stack monitoring upgrades that strain mid-scale operator balance sheets.
- Feedstock quality heterogeneity:Rapid product miniaturization and glued-unibody construction in consumer electronics complicate mechanical liberation of target metals without cross-contamination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | E-Scrap Recycling Market |
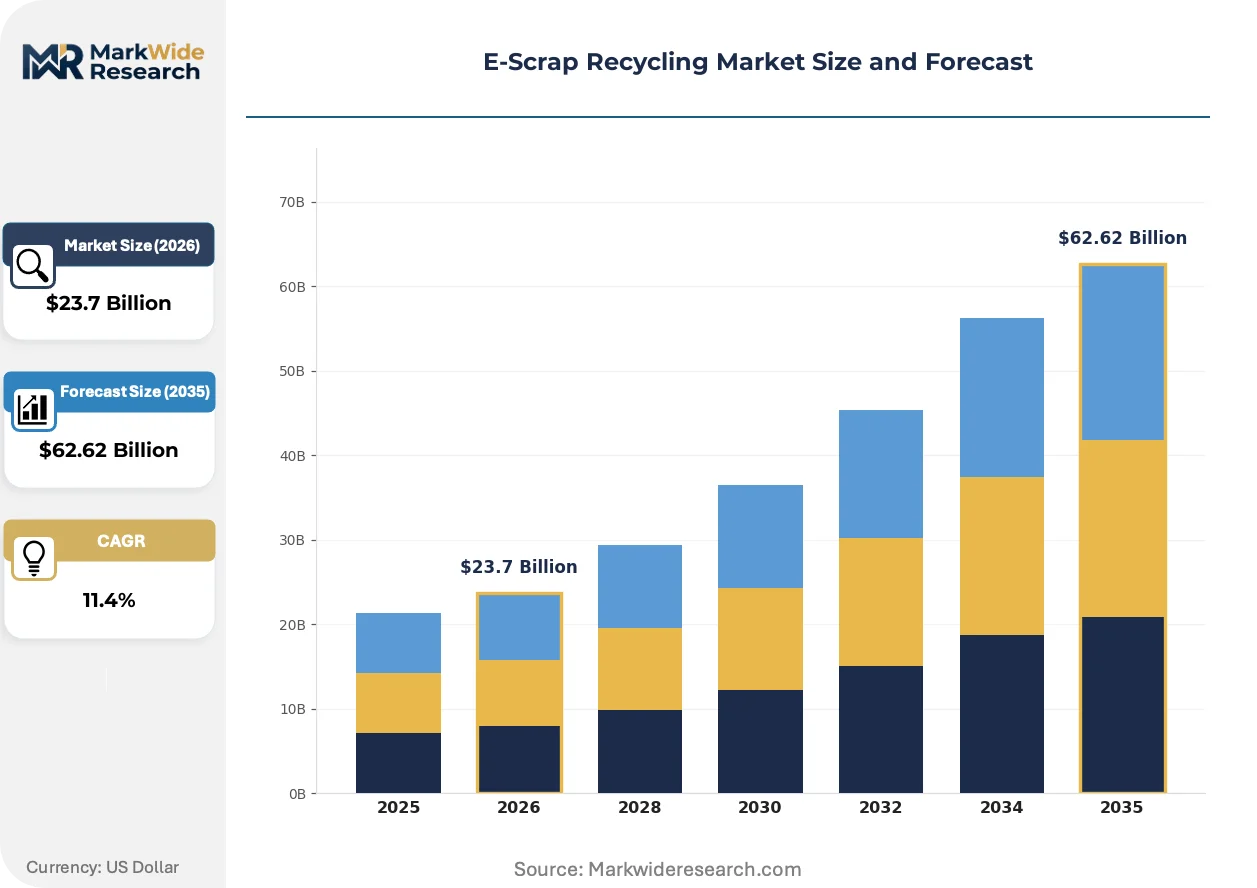
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $62.62 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastics, Metals, Glass, Circuit Boards Collection Method: Curbside Pickup, Drop-off Centers, Collection Events, Industrial Collection End User: Consumers, Businesses, Manufacturers, NGOs Processing Technology: Mechanical Recycling, Pyrometallurgy, Hydrometallurgy, Bioleaching |
| Companies Covered | Umicore SA, Dowa Holdings Co., Ltd., Enviro-Hub Holdings Ltd., Aurubis AG, Boliden Group, Stena Metall AB, Sims Limited, Electronic Recyclers International, Veolia Environment SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
E-Scrap Recycling Market Emerging Trajectories
Processing technology convergence is dissolving traditional boundaries between mechanical preprocessing and metallurgical recovery, enabling closed-loop material returns at higher purities and lower energy intensities than virgin extraction alternatives.
Pyrometallurgical smelting is hybridizing with hydrometallurgical finishing circuits to handle complex multi-element feeds from shredded printed circuit boards. Battery recyclers in South Korea and Germany are deploying this dual-route configuration to extract cobalt and rare earth elements that furnace-only processing would lose to slag. The hybrid approach is compressing capital recovery timelines for integrated urban mining facilities by 20-30 percent compared to standalone pyrometallurgical investments.
REACH substance restrictions are tightening permissible chemistries in leaching and precipitation steps, forcing hydrometallurgical operators to substitute bio-based reagents for conventional mineral acids. The European Chemicals Agency's candidate list expansions for persistent organic pollutants are most acutely affecting brominated flame retardant separation from plastic fractions. Recyclers are responding by accelerating solvent-based purification investments that isolate these contaminants before thermal processing.
Electronics assemblers are consolidating procurement around certified recycled content quotas, displacing spot-market virgin metal purchases with long-term offtake agreements from qualified urban mining suppliers. This contract structuring is most visible in Germany and Japan, where automotive and industrial electronics manufacturers face binding circularity disclosures under supply chain due diligence frameworks. Tier-one component suppliers now specify minimum recycled copper and gold percentages in their technical purchasing requirements.
E-Scrap Recycling Market Segmentation
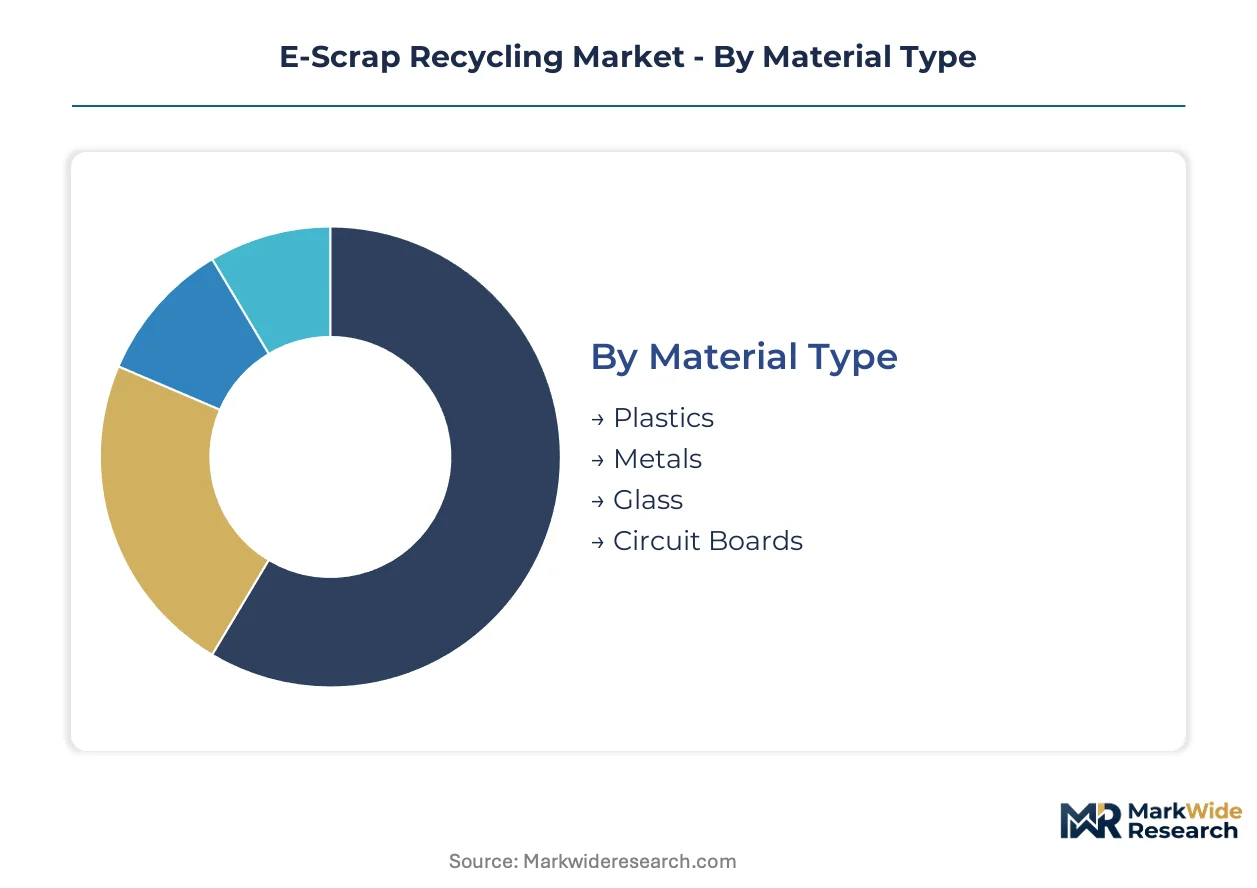
E-scrap recycling segmentation reveals how material heterogeneity and collection logistics shape processor economics. Recovery technology selection varies sharply across feedstock types, dictating capital intensity and margin structures for operators.
Material Type:
Material composition determines recovery pathway selection and revenue potential across the value chain.
- Metals:Copper, gold, palladium, and rare earth elements concentrate in circuit boards and connectors, commanding premium recovery economics. Smelter integration in Germany and China captures these fractions through pyrometallurgical processing, though virgin concentrate price swings compress margins during copper market downturns.
- Circuit Boards:Printed circuit boards contain the highest precious metal density per kilogram of any e-scrap category. Hydrometallurgical circuits in South Korea selectively leach cobalt and rare earth elements that furnace-only processing would lose to slag, enabling closed-loop returns to battery manufacturers.
- Plastics:Brominated flame retardant contamination complicates thermal processing, requiring solvent-based purification investments that isolate persistent organic pollutants before smelting.
- Glass:Cathode ray tube glass faces hazardous waste classification under EPA rules, limiting cross-border shipment options and fragmenting feedstock flows to specialized treatment facilities.
The dominant share belongs to Metals, while Circuit Boards is closing the gap fastest.
Collection Method:
Collection infrastructure density varies with population concentration and regulatory enforcement maturity.
- Industrial Collection:Large-volume generators including data centers and telecommunications operators provide homogeneous feedstock with predictable metal content. Contracts with these sources command premium pricing due to lower sorting costs and certified chain-of-custody documentation required for battery passport compliance.
- Drop-off Centers:Municipal and retail collection points aggregate consumer-generated e-scrap across diverse product categories. Germany's dense urban mining clusters concentrate these facilities within 150-kilometer radii of preprocessing plants, minimizing logistics costs.
- Curbside Pickup:Residential collection programs face contamination challenges from commingled waste streams, requiring additional mechanical sorting investments.
- Collection Events:Periodic community drives generate episodic volume spikes that strain preprocessing capacity planning and labor scheduling.
Industrial Collection captures the highest margin per ton collected, while Drop-off Centers is expanding most quickly.
End User:
End-user categories reflect divergent compliance obligations and circularity disclosure requirements.
- Manufacturers:Consumer electronics producers face extended producer responsibility mandates that internalize collection costs and drive integrated circular service models. Automotive and industrial electronics manufacturers in Germany and Japan specify minimum recycled copper and gold percentages in technical purchasing requirements.
- Businesses:Enterprise IT asset disposition generates high-value server and networking equipment with concentrated precious metal content. Data destruction certifications add service layer revenue beyond material recovery.
- Consumers:Individual generators respond to convenience and awareness campaigns, though collection rates remain below regulatory targets in most jurisdictions.
- NGOs:Non-profit collection programs bridge gaps in formal infrastructure, particularly in emerging markets with limited compliance enforcement.
Manufacturers account for the largest contracted volume, while Businesses is gaining share fastest.
Processing Technology:
Technology selection balances capital recovery timelines against feedstock flexibility and product purity requirements.
- Pyrometallurgy:Smelter-based processing dominates for complex multi-element feeds from shredded printed circuit boards, leveraging proven scalability and high throughput. Continuous stack monitoring upgrades required by EPA hazardous waste combustion standards strain mid-scale operator balance sheets.
- Hydrometallurgy:Selective leaching circuits achieve lower energy intensity and higher purity outputs for lithium-ion battery black mass. Hybrid configurations combining pyrometallurgical smelting with hydrometallurgical finishing compress capital recovery timelines by 20-30 percent compared to standalone furnace investments.
- Mechanical Recycling:Shredding and density-based sorting reduce devices to sub-100mm particles before magnetic separation, serving as preprocessing for downstream metallurgical recovery.
- Bioleaching:Microbial extraction processes substitute bio-based reagents for conventional mineral acids under tightening REACH substance restrictions, though commercial deployment remains limited.
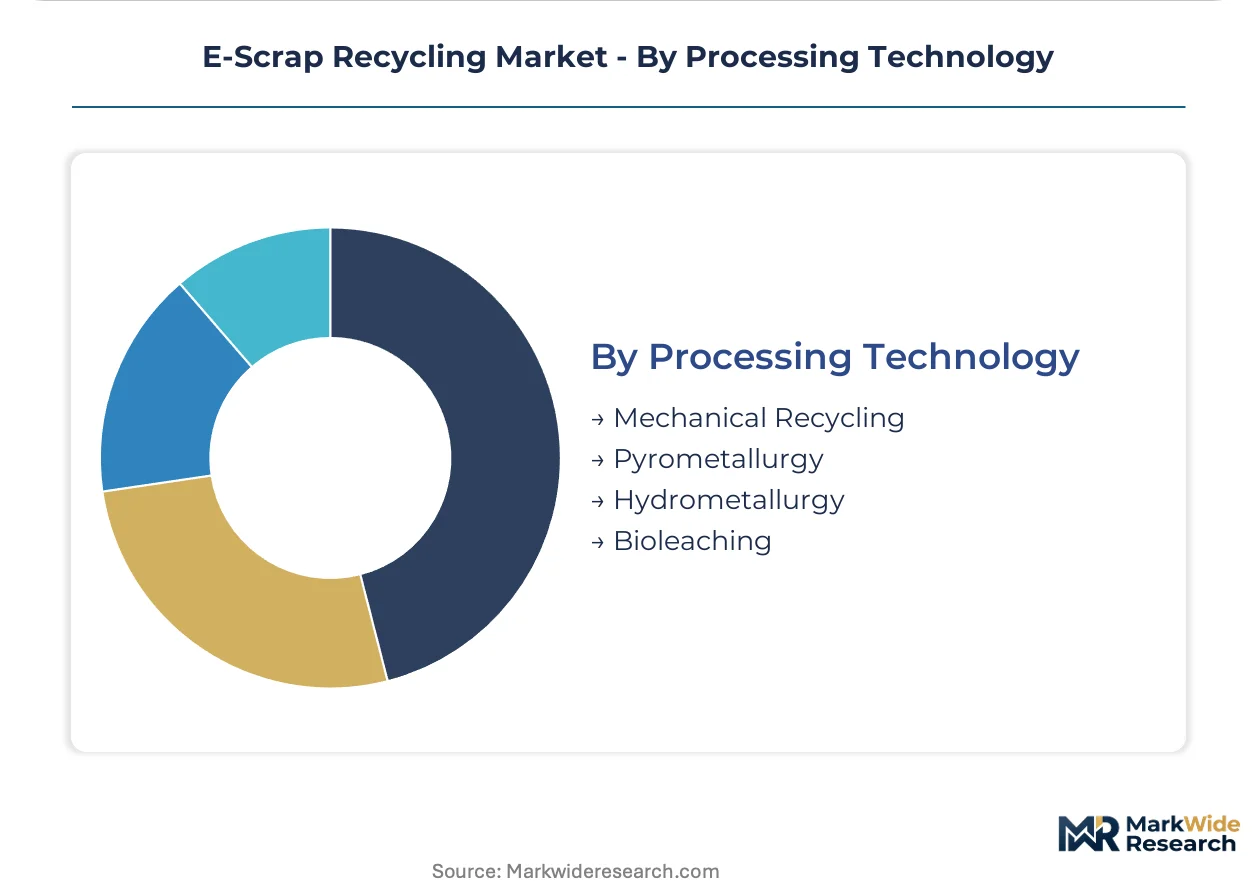
Pyrometallurgy retains the dominant installed base, while Hydrometallurgy is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Japan exhibit the lowest price elasticity due to binding circularity disclosure requirements, while operators in India and Southeast Asia face acute margin compression from informal sector competition.
United States
Data center decommissioning and enterprise IT asset disposition generate high-volume feedstock with concentrated precious metal content. The EPA regulates cathode ray tube disposal under hazardous waste rules, creating specialized treatment pathways. Dallas-Fort Worth anchors preprocessing capacity for southwestern states, with smelter partnerships extending to Mexico for copper recovery.
Germany
Automotive and industrial electronics manufacturers specify minimum recycled copper and gold percentages in technical purchasing requirements. The EU WEEE Directive mandates collection targets and recycling efficiencies that national infrastructure must achieve. Hamburg and Munich concentrate smelter capacity, mechanical preprocessing, and precious metal refining within 150-kilometer urban mining clusters.
China
Domestic electric vehicle retirement waves are generating lithium-ion battery black mass volumes for hydrometallurgical processing. The country's national environmental regulator enforces dual carbon goals that privilege lower-energy recovery pathways. The Yangtze River Delta hosts integrated dismantling-refining operations serving electronics manufacturers with compliant feedstock alternatives.
Japan
Consumer electronics producers face extended producer responsibility mandates that internalize collection costs and drive circular service models. METI oversees industrial standards that shape permissible recovery chemistries. The Kanto region around Tokyo concentrates urban mining infrastructure for high-grade circuit board processing.
India
E-waste management rules mandate phased collection targets for manufacturers, creating first-mover advantages for integrated operators. The country's national environmental regulator enforces hazardous waste classifications that fragment cross-state feedstock flows. Delhi-Mumbai corridors are attracting dismantling-refining investments to serve domestic electronics assembly demand.
E-Scrap Recycling Market Vendor Landscape
Capability concentration sits with integrated smelter operators possessing hydrometallurgical finishing expertise; scale advantage sits with dense collection network operators spanning multiple continents. The market structures around three tiers: precious metal refiners with pyrometallurgical dominance, battery-focused hydrometallurgical specialists, and logistics-intensive collection platform operators. Strategic moves concentrate on hybrid processing technology deployment and regional collection infrastructure consolidation.
Within the integrated refining tier, Aurubis AG and Umicore SA exemplify operators combining smelter scale with selective leaching capabilities for complex multi-element feeds. Sims Limited occupies a position among collection-logistics specialists with dense network coverage. These three entities represent distinct competitive archetypes: German-headquartered smelter integration, Belgian-headquartered hydrometallurgical expertise, and Australian-headquartered transcontinental collection platforms.
| Leading Market Players |
|---|
| Umicore SA |
| Dowa Holdings Co., Ltd. |
| Enviro-Hub Holdings Ltd. |
| Aurubis AG |
| Boliden Group |
| Stena Metall AB |
| Sims Limited |
| Electronic Recyclers International |
| Veolia Environment SA |
| Others |
Supply Flow & Price Mechanics
Copper concentrate price volatility determines both margin compression thresholds for secondary smelters and the geographic shape of feedstock aggregation networks. When virgin mining output collapses below recovery processing thresholds, German and Chinese operators redirect circuit board flows toward hybrid pyrometallurgical-hydrometallurgical facilities that maintain precious metal capture economics.
Pricing Analysis
Extended collection service contracts drive lifetime value for integrated operators serving automotive and industrial electronics manufacturers under binding circularity disclosures. Three-tier pricing structure across certified-refiner, standard-processor, and informal-sector levels reflects chain-of-custody documentation depth and REACH compliance verification. Cost compression in the standard-processor tier is intensifying because informal sector competitors in West Africa and Southeast Asia externalize environmental liabilities. Consumer-generated feedstock through drop-off centers exhibits highest price sensitivity, while German and Japanese manufacturers under extended producer responsibility mandates show lowest elasticity.
Supply Chain Analysis
Electronics manufacturing services concentration in China, Vietnam, and Mexico shapes preprocessing equipment deployment patterns for end-of-life collection. The e-scrap recycling supply chain draws from copper concentrate spot markets, rare earth element separation circuits, and brominated flame-retardant contaminated plastic fractions. Single-source vulnerability sits with smelter capacity clustered around Hamburg, Munich, and the Yangtze River Delta. Distribution runs through certified recycler accreditation networks mandated by EU WEEE Directive collection targets and EPA hazardous waste combustion standards.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
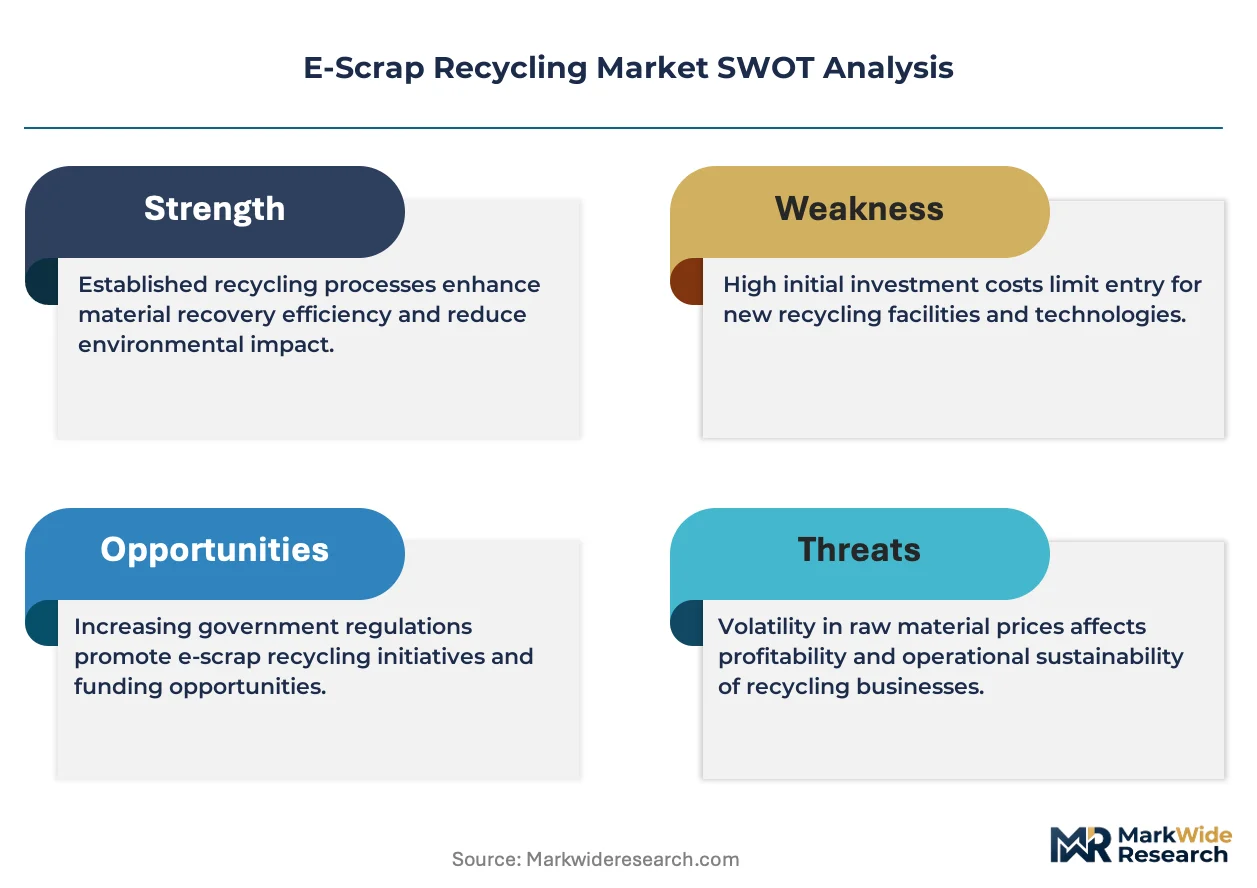
The e-scrap recycling market functions as a regulatory-entrenchment moat where EU WEEE Directive accreditation and Basel Convention hazardous waste permits create switching costs that lock in feedstock access for incumbent operators.
For Market Incumbents: Pre-empt margin erosion from informal sector competition by consolidating collection logistics density in Delhi-Mumbai corridors and Germany's urban mining clusters. Invest in robotic disassembly and AI-driven component recognition to process lower-grade mixed electronics previously rejected by manual sorting operations. Acquire hydrometallurgical finishing capabilities to capture cobalt and rare earth elements from lithium-ion battery black mass that furnace-only processing would lose to slag. For New Entrants and Emerging Players: Pursue first-mover positioning in India's phased manufacturer collection targets before integrated dismantling-refining operations saturate Delhi-Mumbai infrastructure. Target battery passport compliance services as the most penetrable white-space segment, since digital material traceability requirements will privilege recyclers with verified chain-of-custody systems. Establish go-to-market partnerships with electric vehicle manufacturers seeking compliant feedstock alternatives to mined concentrates. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors hybrid-technology operators with smelter scale and selective leaching capabilities. Long-term viability over the next decade hinges on regulatory tightening of cross-border waste shipment rules and critical raw materials acts reshaping feedstock access. Acquisition targets should demonstrate EPA hazardous waste combustion standard compliance and continuous stack monitoring infrastructure. Watch battery passport mandate implementation timelines as the signal for inflection in recovery economics.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Processing Technology Deployment | Dual-route pyrometallurgical-hydrometallurgical configurations compress capital recovery timelines for urban mining facilities. |
| Collection Infrastructure Consolidation | Dense networks within 150-kilometer radii of preprocessing plants minimize logistics costs under EU WEEE Directive targets. |
| Robotic Disassembly Investment | AI-driven component recognition enables profitable processing of glued-unibody consumer electronics previously rejected. |
| Battery Passport Compliance Systems | Verified chain-of-custody documentation privileges recyclers for critical raw materials recovery under emerging mandates. |
| Bio-Based Reagent Substitution | REACH substance restrictions force hydrometallurgical operators to replace mineral acids with microbial extraction processes. |
Methodological Framework
Operator-level perspectives from smelter plant managers, collection logistics directors, regulatory compliance officers, and battery black mass procurement leads anchored the qualitative base. Primary interviews combined with secondary validation from EPA hazardous waste filings, EU WEEE Directive implementation reports, Basel Convention amendment texts, and SEC disclosures from publicly traded recyclers. Bottom-up feedstock volume modeling and top-down regulatory target reconciliation triangulated market sizing across material type, collection method, and processing technology segments.
Scenario-bracketing framed volume and value outputs across the analysis window, with segmentation dimensions spanning metals recovery versus plastics processing, industrial collection versus consumer drop-off, and pyrometallurgical versus hydrometallurgical technology selection. CAGRs derived from feedstock generation rates tied to electric vehicle retirement waves and consumer electronics replacement cycles. Forecast inputs incorporated REACH substance restriction timelines and battery passport implementation phases without year-specific anchoring.
Macroeconomic conditions sit as an overlay; deviation in copper concentrate spot prices and rare earth element supply disruptions would shift the trajectory of secondary smelter margin structures. Forecasts reflect assumptions about regulatory enforcement consistency and informal sector containment. Quarterly review of EU WEEE Directive collection target achievement rates and EPA stack monitoring compliance citations is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Waste Management
Europe E-Waste Management Market
E-Waste Management
Electronic Scrap Recycling Market
E-Waste Management
Solar Panel Recycling Market
E-Waste Management
Smart Waste Management Market
E-Waste Management
Global E-Waste Recycling and Reuse Service Market
E-Waste Management
Middle East and Africa Solar Panel Recycling Market
E-Waste Management
Solar Trash Compactors Market
E-Waste Management
Solar Panel Recycling Management Market
E-Waste Management
E-Waste Management Market
E-Waste Management
Electronic Waste Recycling Market
E-Waste Management
Solar Waste Recycling Market
E-Waste Management
Release Liner Recycling Market
E-Waste Management
North America E-Waste Management Market
E-Waste Management
APAC E-Waste Management Market
E-Waste Management
UAE E-Waste Management Market
E-Waste Management
Aluminum Cans Recycling Market