
 Continuous Emission Monitoring Systems (CEMS) Market | 2026-2036
Continuous Emission Monitoring Systems (CEMS) Market Size, Share, and Industry Trends Forecast 2026-2036
Continuous Emission Monitoring Systems (CEMS) Market Insights
Aftermarket service revenue is fragmenting across hardware calibration, remote diagnostics, and predictive maintenance contracts. Thermo Fisher Scientific leverages its analytical instrument heritage to dominate gas analyzer refurbishment cycles. ABB Ltd. anchors European utility relationships through integrated digital service platforms. Yokogawa Electric Corporation competes in Asia-Pacific with localized technical support networks.
Continuous Emission Monitoring Systems comprise integrated hardware-software assemblies that measure flue gas concentrations of pollutants including sulfur dioxide, nitrogen oxides, and particulate matter using extractive or in-situ sampling methods at temperatures exceeding 300°C. These systems serve primary industrial purpose by providing real-time emission data for regulatory reporting and combustion process control. Gas analyzers command the largest product segment as coal and natural gas plants face escalating accuracy requirements under performance standards. Cloud-based deployment represents the fastest-expanding configuration as utilities integrate CEMS data with enterprise asset management platforms. Regulatory compliance applications absorb the majority of installed base value due to mandatory continuous monitoring provisions in operating permits.
The EPA enforces 40 CFR Part 60 and Part 75 standards that mandate CEMS installation, certification, and quality assurance procedures for affected fossil fuel combustion sources. China's MEE administers GB 13223 and GB 13271 emission limits that require power sector CEMS upgrades with networked data transmission to provincial environmental platforms. Stakeholders must monitor evolving data integrity requirements as regulators transition from periodic audits to continuous automated validation of CEMS performance records.
Market Dynamics
Coal-to-gas fuel switching in power generation is compressing CEMS hardware refresh cycles as utilities consolidate monitoring infrastructure across mixed-fuel fleets. This structural shift accelerates demand for multi-pollutant analyzer platforms that handle variable sulfur loads without hardware swaps.
Growth Catalysts
- EPA 40 CFR Part 75:Mandatory NOx and SO2 monitoring for fossil fuel combustion sources drives hardware replacement at coal-fired facilities facing compliance deadlines.
- China's MEE networked data mandates:Provincial environmental platforms require real-time CEMS data transmission, forcing power sector retrofits with integrated telemetry modules.
- Extractive sampling methods:These techniques dominate high-temperature applications above 300°C where in-situ probes degrade, securing durable demand for heated sample conditioning systems.
Market Restraints
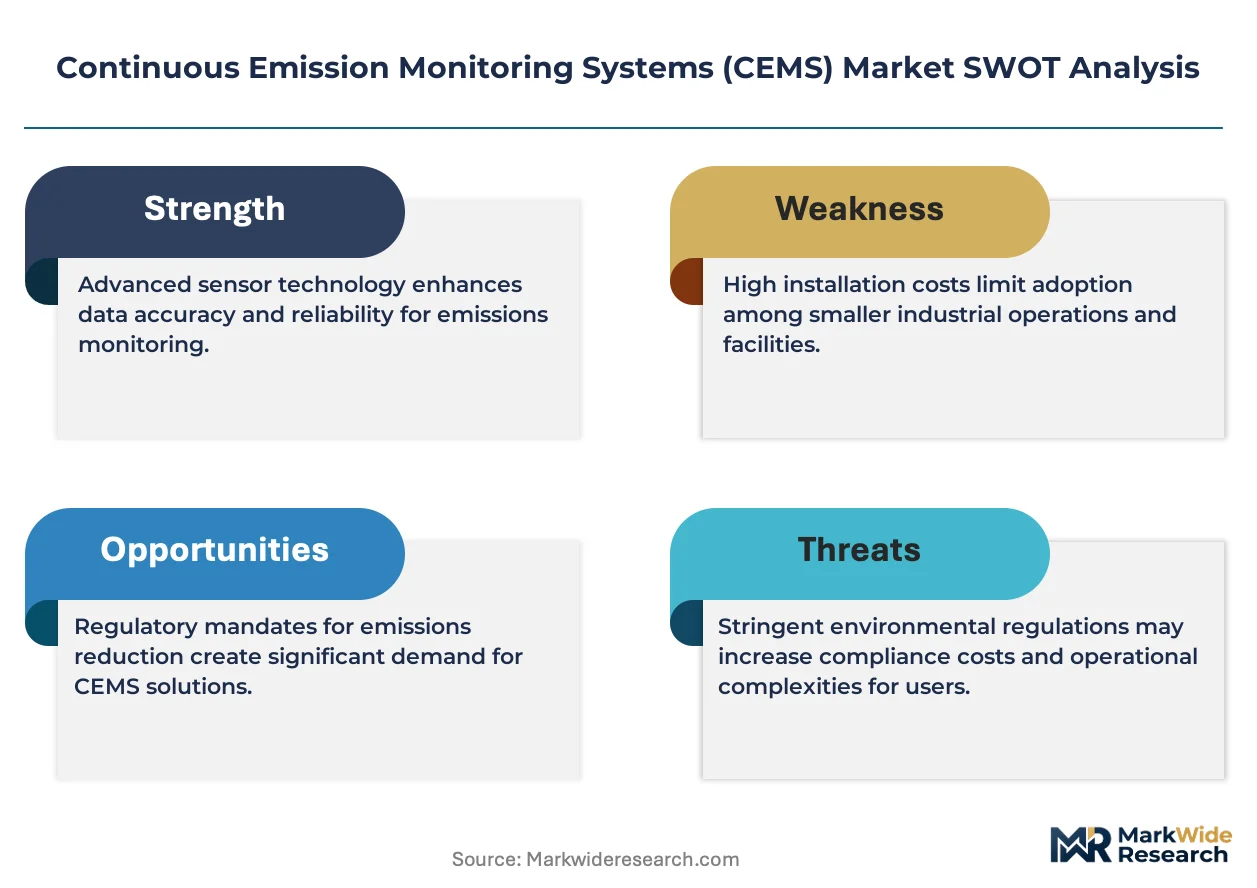
- Specialized ceramic probe supply:Concentrated sourcing from German and Japanese refractory manufacturers creates lead time volatility for high-temperature sampling components.
- Calibration gas cost structure:Zero-grade nitrogen and certified reference materials face price pressure from industrial gas supply constraints, elevating operating expenditure for continuous quality assurance.
- Mercury analyzer technical limitation:Cold vapor atomic fluorescence detection requires gold amalgamation pre-concentration that complicates real-time validation protocols under EPA performance specifications.
Strategic Opportunities
- India's CEA emission norms:Thermal power plants exceeding 500MW capacity face new continuous monitoring mandates, opening greenfield installation demand ahead of enforcement timelines.
- Predictive maintenance convergence:Machine learning algorithms applied to analyzer drift patterns enable shift from calendar-based to condition-based service scheduling.
- Cement sector application:Rotary kiln emission monitoring remains underpenetrated relative to power generation, with kiln inlet temperatures exceeding 1000°C requiring specialized probe designs.
Industry Challenges
- Analyzer technician skill gap:Cross-training between optical spectroscopy and electrochemical sensor maintenance functions lags hardware complexity, extending mean time to repair at remote plant sites.
- Data acquisition system integration:Legacy distributed control systems from 1990s-era installations lack native Ethernet connectivity, forcing expensive protocol gateway deployments for cloud platform integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Continuous Emission Monitoring Systems (CEMS) Market |
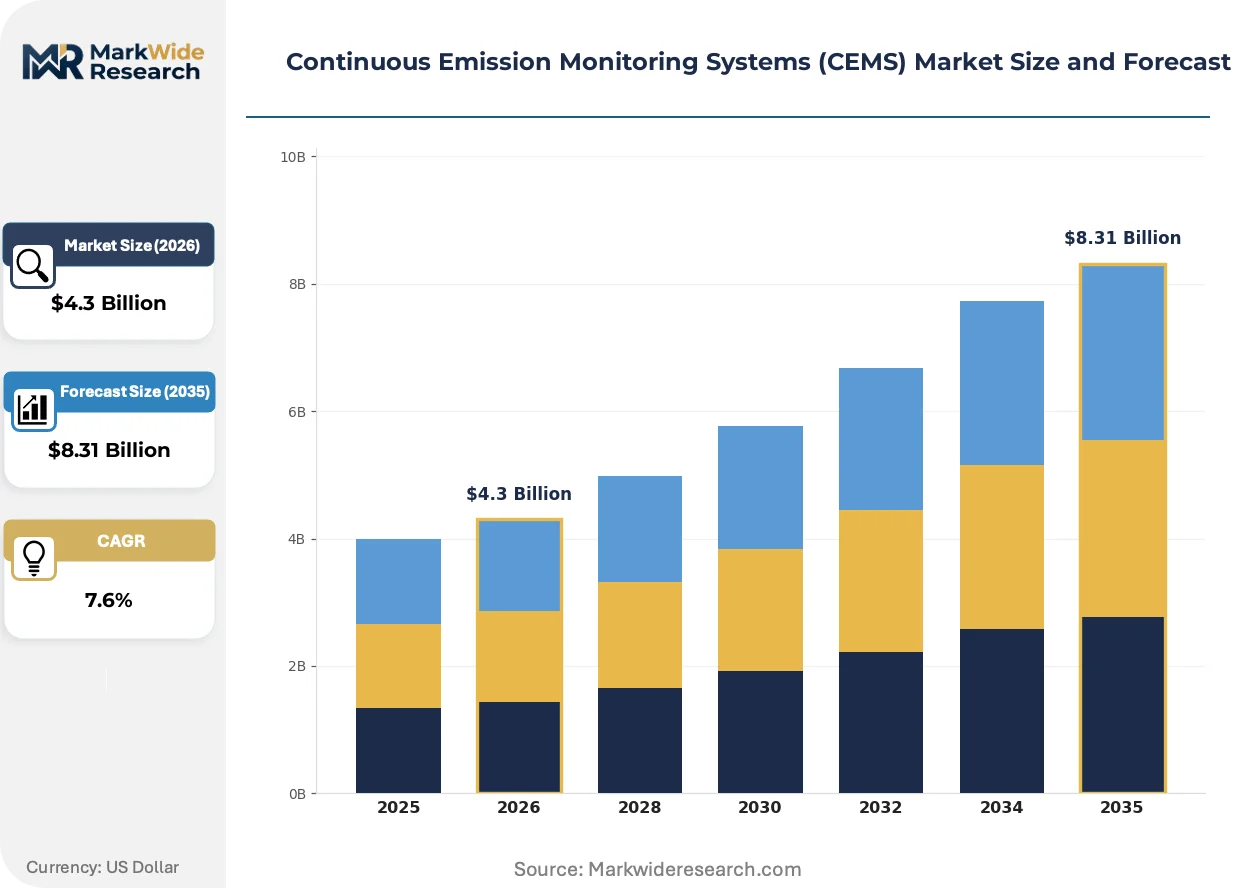
| Market Size in 2026 | $4.3 Billion |
| Market Size in 2035 | $8.31 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gas Analyzers, Particulate Monitors, Opacity Monitors, Flow Monitors End User: Manufacturing Facilities, Energy Plants, Waste Management, Chemical Industries Deployment: On-premises, Cloud-based, Hybrid, Remote Monitoring Application: Regulatory Compliance, Process Optimization, Emission Reporting, Environmental Monitoring |
| Companies Covered | Thermo Fisher Scientific Inc., General Electric Company, ABB Ltd., Fuji Electric Co., Ltd., Horiba Ltd., Siemens AG, AMETEK, Inc., Yokogawa Electric Corporation, Emerson Electric Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Continuous Emission Monitoring Systems (CEMS) Market Trends and Innovations
Digital twin architectures are reshaping how CEMS data flows from stack-mounted sensors to enterprise decision systems. This transformation compresses the boundary between field instrumentation and central analytics.
Extractive sampling systems with heated umbilical lines are virtualizing the physical probe location relative to the analyzer cabinet. Power utilities with multi-stack configurations adopt centralized analyzer shelters connected via heated sample lines up to 100 meters, reducing per-stack capital intensity. This topology is virtualizing the traditional distributed analyzer architecture into consolidated measurement nodes serving multiple emission points.
China's MEE enforcement of GB 13223-2011 amendments tightens particulate matter limits for coal-fired boilers, compelling utilities to upgrade opacity monitors with beta attenuation or light-scattering technologies. The policy shift elevates accuracy requirements from indicative monitoring to quantitative compliance verification. Affected plants in Shandong and Hebei provinces accelerate analyzer procurement ahead of provincial inspection campaigns.
Service contract unbundling separates hardware warranty from calibration and data validation obligations. Independent service providers now compete with original equipment manufacturers for multiyear maintenance agreements, particularly at industrial facilities without dedicated environmental compliance staff. This procurement fragmentation is most visible in the US Midwest where chemical manufacturers source analyzer refurbishment from third-party metrology specialists.
Continuous Emission Monitoring Systems (CEMS) Market Segmentation
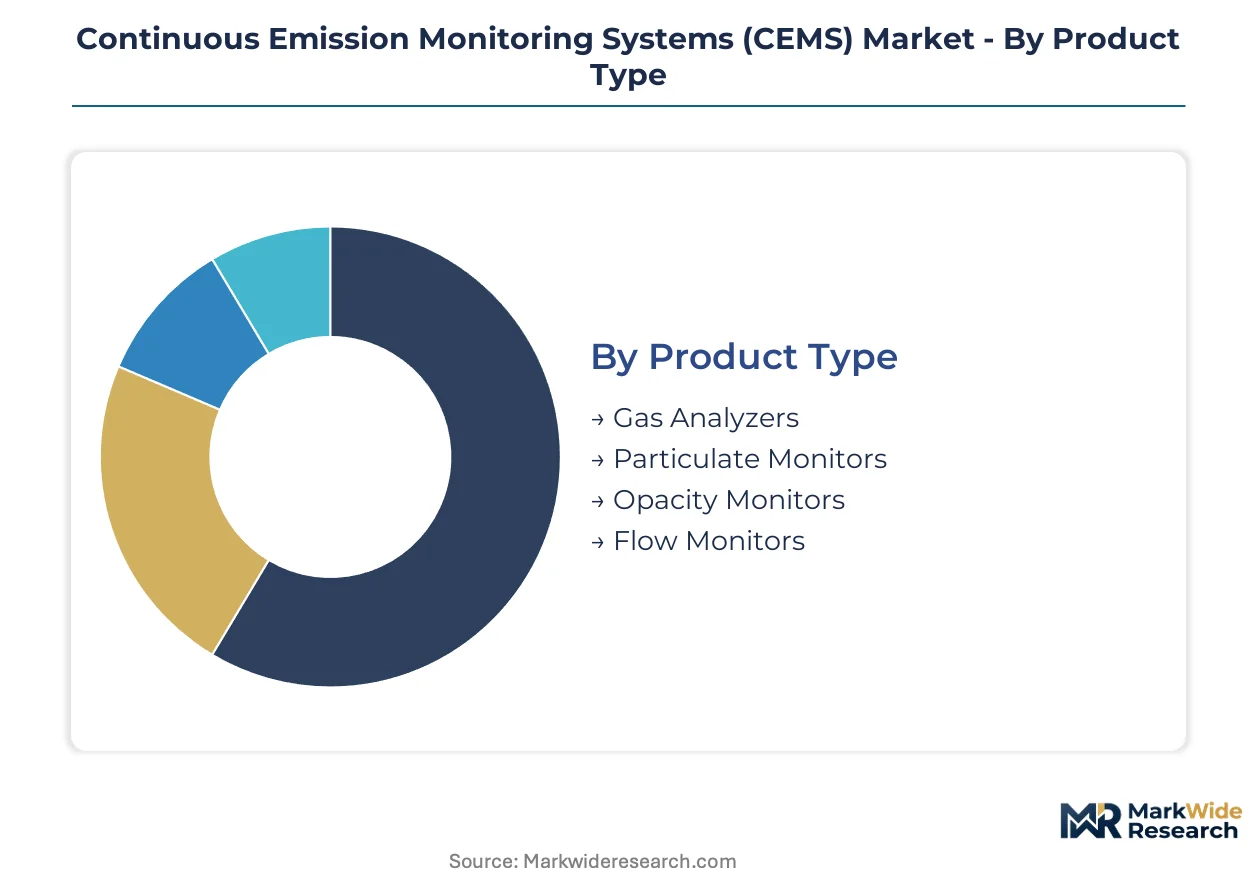
CEMS procurement patterns diverge sharply across hardware categories and deployment models, with service contract structures varying from annual calibration cycles to comprehensive predictive maintenance agreements. Understanding these segment boundaries clarifies where vendor margins concentrate versus where price competition intensifies.
Product Type:
After-sales service intensity peaks with gas analyzer platforms, where probe degradation and drift correction demand quarterly technician visits at coal-fired installations.
- Gas Analyzers:These systems employ non-dispersive infrared, ultraviolet fluorescence, or chemiluminescence detection to quantify SO2, NOx, and CO concentrations in extracted flue gas samples. Demand concentrates at coal-fired power plants in Shandong and Hebei provinces as China's MEE enforces GB 13223-2011 particulate matter amendments ahead of provincial inspection campaigns.
- Particulate Monitors:Beta attenuation and light-scattering technologies measure dust loadings for quantitative compliance verification rather than indicative opacity readings. Cement rotary kilns in India drive procurement as CEA emission norms tighten continuous monitoring requirements for thermal plants exceeding 500MW capacity.
- Opacity Monitors:Transmissometer-based systems provide visual emission density readings for regulatory screening.
- Flow Monitors:Ultrasonic and differential pressure methods calculate stack gas velocity for mass emission calculations.
By volume, gas analyzers lead. By growth pace, particulate monitors are ahead.
End User:
Cost tier segmentation separates capital-intensive utility deployments from mid-scale industrial installations with constrained environmental compliance staffing.
- Energy Plants:Coal and natural gas combustion facilities anchor hardware demand with multi-pollutant analyzer requirements under EPA 40 CFR Part 75 and China's networked data mandates. These installations generate the longest service contract durations due to mandatory quality assurance testing.
- Manufacturing Facilities:Steel, cement, and pulp production sites face emerging CEMS obligations as regulators expand continuous monitoring beyond power generation. Procurement emphasizes standardized analyzer configurations to reduce spare parts inventory complexity at multi-site operators.
- Waste Management:Incineration and landfill gas recovery operations require specialized mercury and dioxin monitoring protocols.
- Chemical Industries:Petrochemical crackers and sulfur recovery units demand corrosion-resistant sampling systems for aggressive process streams.
Energy plants absorb the majority of installed base value. Manufacturing facilities are climbing the fastest as regulatory scope widens.
Deployment:
Volume concentration favors on-premises installations at legacy facilities, while margin expansion tracks cloud-based configurations with recurring software subscription revenue.
- On-premises:Traditional architecture houses data acquisition systems and analyzers within plant boundaries, suiting facilities with strict cybersecurity policies or unreliable external connectivity. These deployments dominate at 1990s-era installations where legacy distributed control systems lack native Ethernet connectivity.
- Cloud-based:Enterprise asset management integration enables centralized diagnostics across multi-stack configurations. Power utilities with heated sample line topologies adopt these platforms to virtualize measurement nodes serving multiple emission points from consolidated analyzer shelters.
- Hybrid:Local buffering with cloud synchronization balances latency sensitivity and remote accessibility.
- Remote Monitoring:Telemetry modules transmit data to provincial environmental platforms under China's MEE networked data mandates.
On-premises retains the largest installed base. Cloud-based configurations are gaining share fastest as utilities consolidate digital infrastructure.
Application:
Customer type segmentation distinguishes mandatory regulatory installations from discretionary process optimization deployments with divergent procurement authority structures.
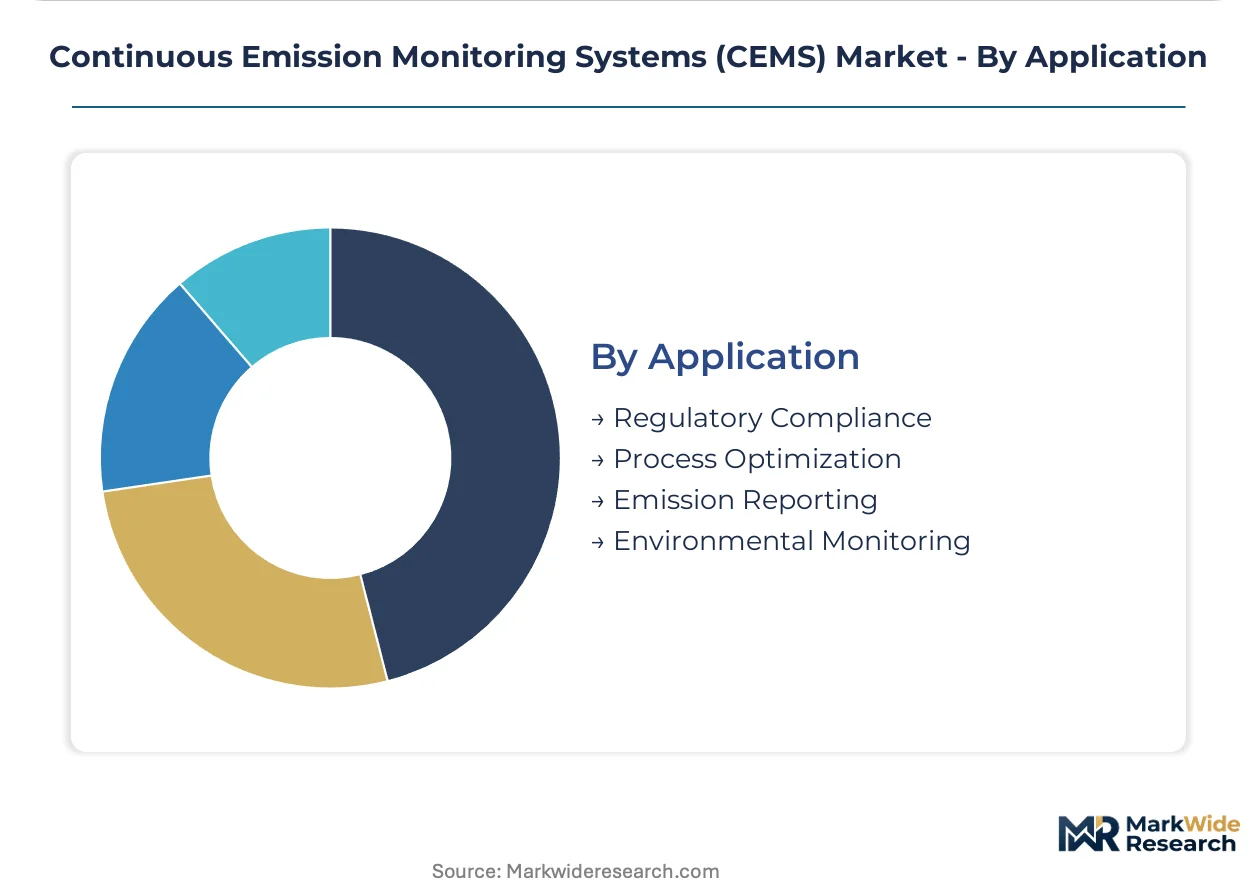
- Regulatory Compliance:Mandatory continuous monitoring provisions in operating permits drive baseline demand with non-negotiable installation timelines. EPA 40 CFR Part 60 and Part 75 certification requirements enforce specific analyzer performance specifications and quality assurance procedures.
- Process Optimization:Combustion control applications use real-time emission feedback to adjust air-fuel ratios and minimize excess oxygen. These deployments concentrate at natural gas combined-cycle plants seeking thermal efficiency gains beyond environmental obligations.
- Emission Reporting:Automated data validation and electronic submission to regulatory platforms reduce manual compliance labor.
- Environmental Monitoring:Fence-line and ambient air quality applications extend CEMS technology beyond stack monitoring.
Regulatory compliance commands the majority of current value. Process optimization is expanding most quickly as fuel costs pressure operational efficiency investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CEMS manufacturing clusters concentrate in Germany, Japan, and the United States, with each hub serving distinct regional compliance regimes. Component sourcing for high-temperature probes remains concentrated among specialized refractory producers in these markets.
United States
EPA 40 CFR Part 75 mandates drive hardware replacement cycles at coal-fired facilities across the Midwest and Southeast. Mercury and Air Toxics Standards enforcement accelerates multi-pollutant analyzer upgrades. Utilities in Texas and Ohio consolidate monitoring infrastructure as coal-to-gas switching reshapes fleet configurations.
China
GB 13223 and GB 13271 emission limits compel power sector retrofits with networked data transmission modules. Shandong and Hebei provinces accelerate analyzer procurement ahead of MEE inspection campaigns. Coal-fired plants in these industrial corridors face the tightest particulate matter compliance deadlines.
Germany
EU Industrial Emissions Directive implementation sustains demand for extractive sampling systems at lignite-fired stations in the Rhineland. Specialized ceramic probe manufacturers anchor component supply chains in Bavaria and Baden-Württemberg. These fabrication clusters serve both domestic utilities and export markets requiring high-temperature sampling hardware.
India
CEA emission norms for thermal plants exceeding 500MW capacity open greenfield installation demand ahead of enforcement timelines. Maharashtra and Gujarat host the largest concentration of affected coal-fired capacity. Cement rotary kilns in Rajasthan and Madhya Pradesh emerge as secondary demand centers as regulatory scope widens beyond power generation.
Japan
METI efficiency standards and environmental ministry guidelines sustain replacement demand at coastal coal and LNG facilities. Yokohama and Nagoya industrial corridors maintain installed bases of 1990s-era systems requiring protocol gateway upgrades for cloud integration. Domestic analyzer producers serve these retrofit markets alongside specialized service providers.
Continuous Emission Monitoring Systems (CEMS) Market Competitive Landscape
Analytical instrument conglomerates and industrial automation specialists split the market across hardware fabrication and integrated service platforms. Consolidation pressure concentrates among gas analyzer manufacturers facing calibration gas supply constraints and technician skill gaps. Three strategic archetypes dominate: diversified laboratory equipment suppliers leveraging refurbishment expertise, process automation vendors bundling CEMS with distributed control systems, and regional electrical engineering groups with localized technical networks. Competitive moves center on predictive maintenance service unbundling and cloud platform partnerships for enterprise asset management integration.
Within the diversified instrumentation tier, Thermo Fisher Scientific Inc. and AMETEK, Inc. represent the analytical heritage archetype with established refurbishment cycle capabilities. ABB Ltd. and Siemens AG exemplify the integrated automation approach, anchoring European utility relationships through digital service platforms. Yokogawa Electric Corporation occupies a position within the Asia-Pacific regional specialist archetype, competing through localized technical support networks rather than global scale. These three groupings capture distinct procurement authority structures across utility, industrial, and emerging market customer segments.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| General Electric Company |
| ABB Ltd. |
| Fuji Electric Co., Ltd. |
| Horiba Ltd. |
| Siemens AG |
| AMETEK, Inc. |
| Yokogawa Electric Corporation |
| Emerson Electric Co. |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in heated sample conditioning systems across German and Japanese manufacturing clusters is compressing margins for extractive sampling hardware while forcing suppliers toward bundled service contracts to recover value.
Pricing Analysis
After-sales service revenue, encompassing probe refurbishment cycles and predictive maintenance subscriptions, drives lifetime value capture across CEMS deployments. Three-tier pricing structure across premium, standard, and economy levels separates EPA-certified configurations from indicative monitoring systems and basic opacity meters. Cost compression in calibration gas supply is intensifying because industrial gas bottlenecks elevate zero-grade nitrogen expenditure. Chemical manufacturers in the US Midwest exhibit highest price sensitivity due to constrained environmental compliance staffing, while integrated utilities accept premium tiers for networked data transmission capabilities.
Supply Chain Analysis
Tariff exposure between Germany and China dominates sourcing volatility for specialized ceramic probes used in high-temperature extractive sampling. Manufacturing concentrates in Germany, Japan, and the United States, with refractory fabrication anchored in Bavaria and Baden-Württemberg. Component sourcing draws from zirconia ceramic substrates, platinum-rhodium thermocouples, and corrosion-resistant sampling umbilical lines. Single-source vulnerability persists for gold amalgamation pre-concentration modules in mercury analyzers. Distribution runs through authorized service networks rather than direct OEM channels, with regional electrical engineering groups controlling last-mile installation and commissioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-based deployment architectures are disrupting traditional CEMS procurement, with EPA and China's MEE mandates accelerating the shift from capital hardware to recurring software subscription models.
For Market Incumbents: Pre-empt technician skill gaps by acquiring specialized metrology training platforms before third-party service providers capture refurbishment cycles. Consolidate probe supply relationships through backward integration into ceramic refractory production, countering lead time volatility from German and Japanese suppliers. Anchor multi-year enterprise asset management partnerships to lock in cloud-based configuration demand.
For New Entrants and Emerging Players: Cement rotary kilns in Rajasthan and Madhya Pradesh represent the most penetrable entry point, with kiln inlet temperatures exceeding 1000°C creating demand for specialized probe designs absent from incumbent portfolios. India's CEA emission norms for thermal plants exceeding 500MW capacity offer greenfield installation opportunities ahead of enforcement timelines. Pursue calibration gas supply partnerships as a differentiated service wedge.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because continuous monitoring mandates expand beyond power generation into steel, cement, and chemical sectors with non-negotiable compliance timelines. Target predictive maintenance software specialists with machine learning capabilities applied to analyzer drift patterns. Watch for MEE inspection campaign acceleration in Shandong and Hebei provinces as the inflection signal for hardware procurement spikes.
| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Launch | Machine learning algorithms enable shift from calendar-based to condition-based service scheduling for gas analyzers. |
| Cloud Platform Integration Partnership | Enterprise asset management connectivity virtualizes measurement nodes across multi-stack utility configurations. |
| Specialized Probe Design Expansion | Cement rotary kiln applications above 1000°C require refractory probe architectures distinct from power sector standards. |
| Calibration Gas Supply Agreement | Long-term contracts for zero-grade nitrogen and certified reference materials stabilize operating expenditure volatility. |
| Regional Technical Support Network Buildout | Localized service presence captures aftermarket revenue from industrial facilities without dedicated compliance staff. |
Research Methodology
A standing panel of utility environmental compliance officers, CEMS service technicians, ceramic probe manufacturing engineers, and provincial environmental platform administrators provided ongoing calibration across primary fieldwork. Secondary validation drew from EPA 40 CFR Part 75 certification records, China's MEE networked data transmission protocols, EU Industrial Emissions Directive implementation reports, and customs trade data for high-temperature sampling components. Bottom-up installation tracking across coal-fired and natural gas facilities was triangulated against top-down regulatory mandate analysis.
Scenario bracketing around EPA enforcement intensity, China's dual carbon policy acceleration, and India's CEA norm implementation timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end-user industry, deployment architecture, and application purpose. CAGRs were derived from unit installation forecasts weighted by average system value and service contract attach rates. Fuel switching patterns and retrofit program acceleration served as industry-specific demand inputs.
Stress conditions across calibration gas supply constraints, ceramic probe lead time volatility, and technician cross-training lags were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and technology substitution rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Monitoring
Europe Air Quality Monitoring Market
Environmental Monitoring
South America Air Quality Monitoring Market
Environmental Monitoring
Quality Monitoring Sensor for Water Market
Environmental Monitoring
Environmental Test Equipment Market
Environmental Monitoring
Real-Time Flood Monitoring and Warning System Market
Environmental Monitoring
Middle East and Africa Air Quality Monitoring Market
Environmental Monitoring
Green Mining Market
Environmental Monitoring
Water Quality Monitoring Equipment Market
Environmental Monitoring
Latin America Cloud Seeding Market
Environmental Monitoring
Global Cloud Seeding Equipment Market
Environmental Monitoring
Ecotoxicological Studies Market
Environmental Monitoring
Asia-Pacific Food and Environment Manual Testing Market
Environmental Monitoring
Water Quality Analyzer Market
Environmental Monitoring
Environment Testing Services Market
Environmental Monitoring
Environment Monitoring Devices Market
Environmental Monitoring
Water Quality Monitoring Systems Market