
 Global Hydrogen Electrolyzers Market | 2026-2036
Global Hydrogen Electrolyzers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hydrogen Electrolyzers Market Outlook
The EU Green Deal is pivoting the cost-of-entry calculus for electrolyzer manufacturers selling into Europe, forcing compliance with stricter carbon accounting and local content thresholds. Siemens Energy leverages its turbine heritage to anchor large-scale PEM projects in Germany and the Middle East. Nel Hydrogen sustains vertical integration from stack manufacturing to hydrogen fueling stations, competing across the full value chain. Thyssenkrupp Nucera dominates alkaline electrolyzer engineering for industrial ammonia and steel clients, positioning its technology for gigawatt-scale deployments.
Hydrogen electrolyzers are electrochemical systems that split water into hydrogen and oxygen using direct current electricity, with alkaline units operating at 60-80°C and PEM variants reaching 50-80°C with proton-conducting polymer membranes; their primary purpose is producing high-purity hydrogen for industrial feedstock, energy storage, and zero-emission fuel applications. Alkaline electrolyzers occupy the mature cost-efficient tier for grid-connected industrial hydrogen, while PEM electrolyzers lead in dynamic response applications pairing with intermittent renewable power. Solid oxide electrolyzers, though nascent, promise the highest efficiency at elevated temperatures and represent the fastest-growing technology segment for integration with industrial waste heat.
The EU AI Act and F-Gas Regulation join the EU Green Deal in shaping electrolyzer demand, with the F-Gas Regulation restricting fluorinated membrane precursors and the Green Deal mandating renewable hydrogen quotas for transport and industry. Japan's METI hydrogen roadmap and South Korea's MFDS certification pathways create parallel compliance architectures for stack efficiency and safety standards. Stakeholders must monitor how diverging regional certification regimes fragment equipment trade and determine whether to pursue multi-standard product platforms or geographically specialized designs.
Market Dynamics
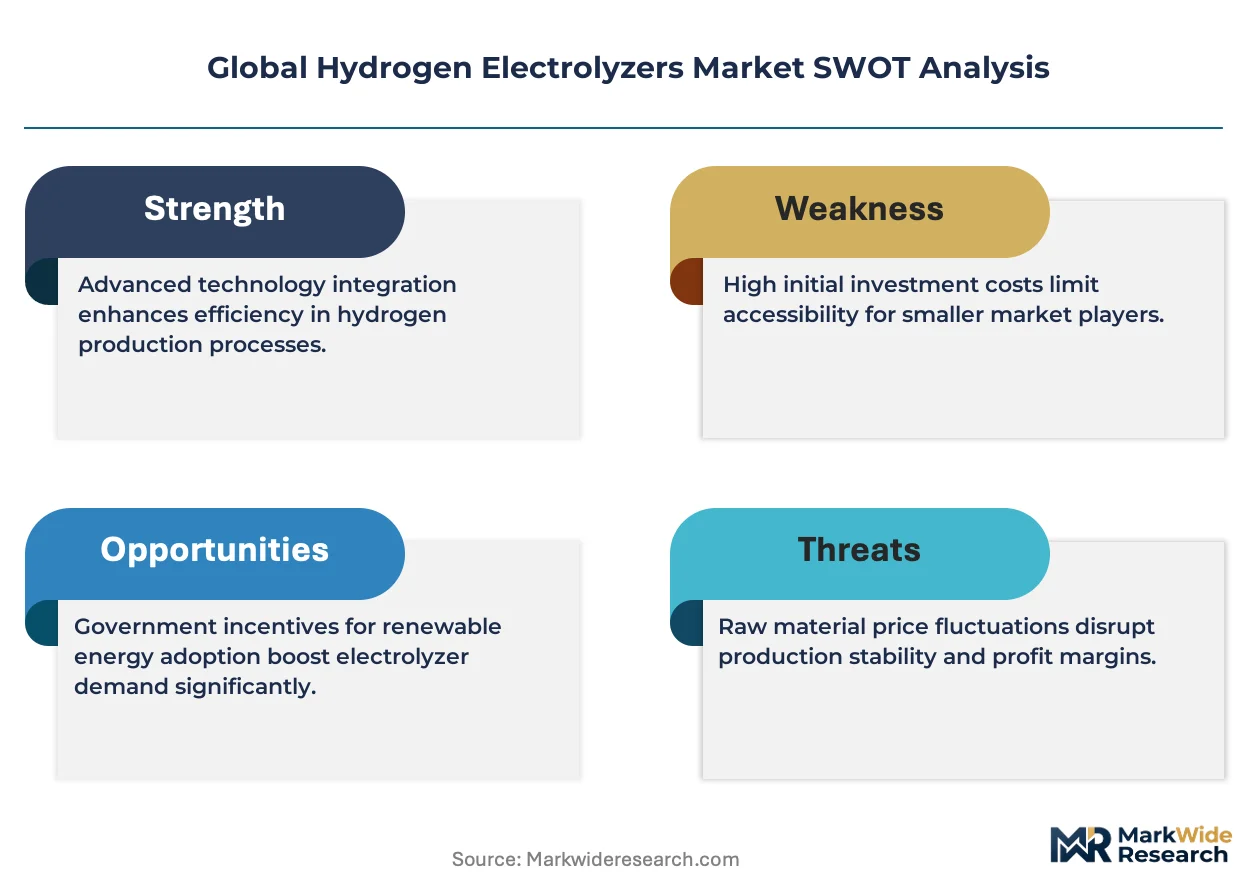
Electrolyzer manufacturers face a structural compression between alkaline cost curves and PEM flexibility premiums, as renewable hydrogen offtake contracts in Germany and Japan force technology choices before gigawatt-scale deployment economics mature.
Growth Catalysts
- EU Green Deal carbon border adjustments:Industrial ammonia and steel producers in Germany accelerate renewable hydrogen procurement to maintain export competitiveness under tightening emissions accounting.
- Japan METI hydrogen roadmap:The 2040 commercialization timeline drives PEM electrolyzer demand for industrial clusters seeking dynamic response pairing with offshore wind.
- Alkaline stack cost engineering:Chinese manufacturing scale compresses capex per kilowatt, enabling grid-connected industrial hydrogen at price points competitive with unabated steam methane reforming.
Market Restraints
- Fluorinated membrane precursor constraints:The EU F-Gas Regulation restricts perfluorinated sulfonic acid supply chains, elevating PEM stack input costs and creating geographic sourcing bottlenecks.
- Iridium catalyst concentration:South African and Russian mining dominance for proton exchange membrane electrodes creates supply security exposure for PEM manufacturers.
- Grid interconnection queues:Utility-scale renewable hydrogen projects face 3-5 year transmission access delays in Germany and California, deferring revenue recognition for electrolyzer deployments.
Strategic Opportunities
- Solid oxide electrolyzer integration:Waste heat capture from steel and chemical plants in Japan enables 80%+ system efficiency, positioning high-temperature stacks for industrial decarbonization retrofits.
- India PLI scheme manufacturing:Production-linked incentives for electrolyzer component localization attract alkaline engineering investments targeting Middle East and Southeast Asia export markets.
- Offshore wind-to-hydrogen platforms:North Sea cluster developments in Denmark and the Netherlands create demand for marinized PEM systems with salt-air corrosion resistance.
Industry Challenges
- Stack degradation modeling:Limited operational data beyond 50,000 hours for alkaline systems and 30,000 hours for PEM creates financing uncertainty for project debt structures.
- Multi-standard certification timelines:Divergent IEC, ASME, and KGS approval pathways for South Korea and German deployments extend product qualification cycles by 18-24 months.
- Electrolyzer-grid control system integration:Legacy SCADA architectures in European chemical plants require custom frequency response programming for renewable power coupling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hydrogen Electrolyzers Market |
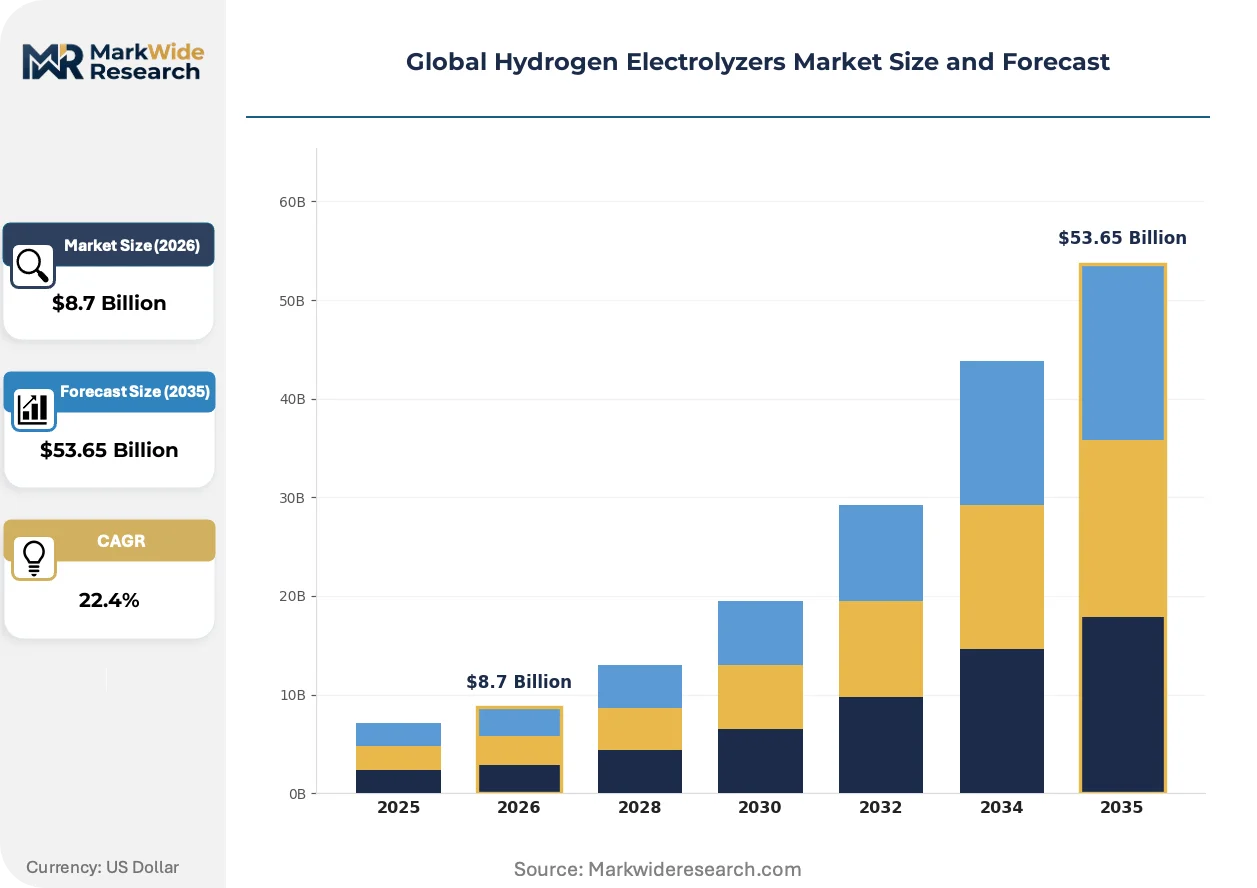
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $53.65 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alkaline Electrolyzers, PEM Electrolyzers, Solid Oxide Electrolyzers, Others End User: Industrial, Commercial, Residential, Transportation Installation: Onshore, Offshore, Mobile, Stationary Application: Energy Storage, Fuel Cell Vehicles, Power Generation, Chemical Production |
| Companies Covered | Siemens Energy, Nel Hydrogen, Thyssenkrupp Nucera, Plug Power, ITM Power, John Cockerill Hydrogen, McPhy Energy, Asahi Kasei, LONGi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hydrogen Electrolyzers Market Strategic Shifts
Containerized electrolyzer systems are compressing project development timelines, while membrane chemistry advances and offtake contracting innovation reshape competitive positioning across alkaline, PEM, and solid oxide technology tiers.
Stack manufacturing is modularizing around 10-20 megawatt building blocks that enable phased capacity expansion. Industrial developers in Germany and the Netherlands deploy these units in 100-megawatt clusters, reducing single-point commissioning risk. This architecture is compressing engineering-procurement-construction timelines from 36 months to 18 months for greenfield hydrogen facilities.
The EU AI Act imposes conformity assessment requirements on electrolyzer control systems using machine learning for predictive maintenance. Stack manufacturers must document algorithm training datasets and failure-mode coverage, elevating compliance costs for PEM systems with embedded diagnostics. German and French industrial hydrogen projects now specify CE-marked control modules with third-party algorithmic audit trails.
Power purchase agreement structures are displacing traditional equipment ownership models for utility-scale deployments. Developers in Denmark and Australia contract electrolyzer capacity as a service, transferring stack degradation risk to manufacturers. This compresses project equity requirements and accelerates final investment decisions for offshore wind-to-hydrogen platforms.
Global Hydrogen Electrolyzers Market Segmentation
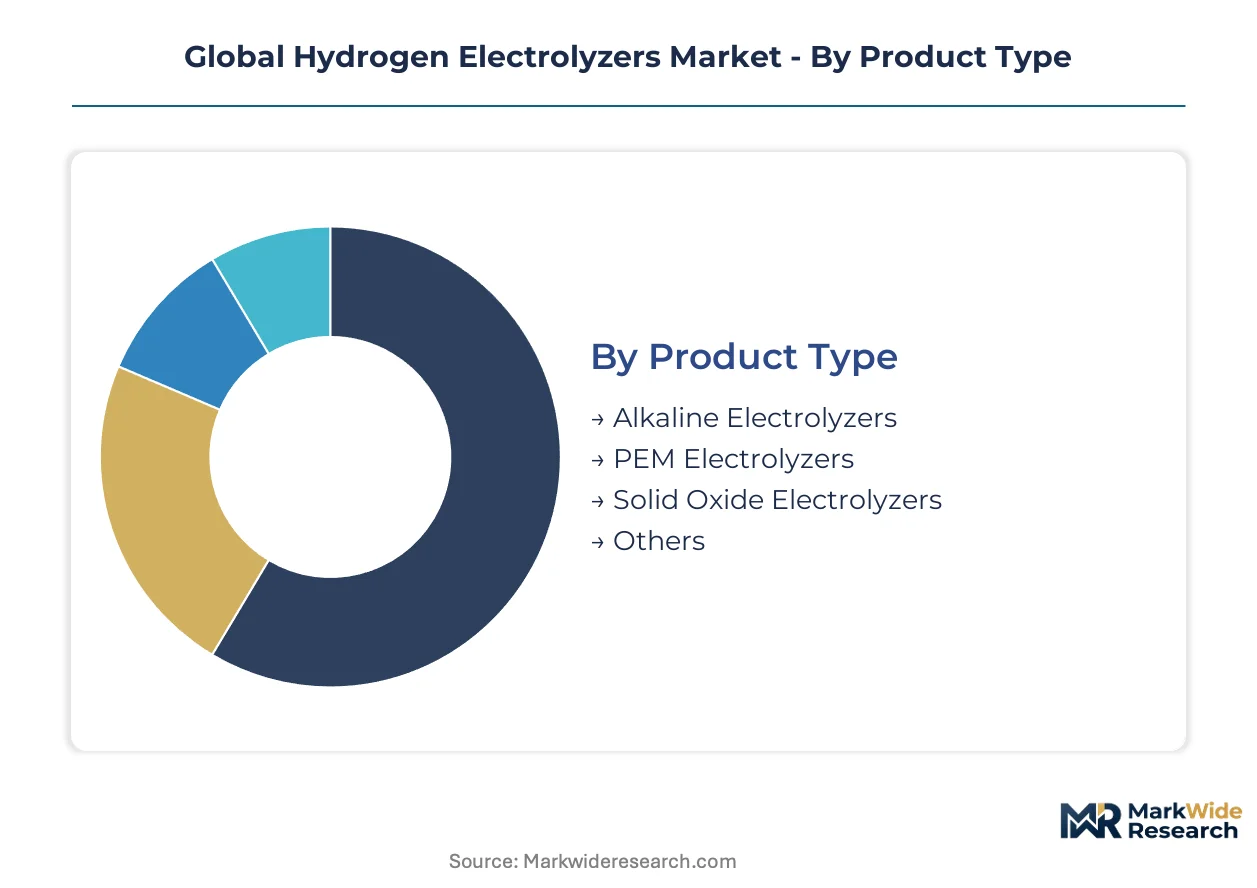
Technology choice in hydrogen electrolyzers determines capital efficiency, operational flexibility, and regulatory compliance across divergent power-to-gas applications. Segmentation reveals where alkaline cost engineering dominates grid-connected industrial demand versus where PEM dynamic response commands premium positioning.
Product Type:
Alkaline systems anchor volume shipments through established manufacturing scale, while PEM variants capture premium pricing for renewable-coupled installations.
- Alkaline Electrolyzers:These systems utilize aqueous potassium hydroxide electrolyte and nickel-based electrodes operating at atmospheric or elevated pressure. Demand concentrates with German ammonia producers and Chinese industrial clusters seeking lowest-cost hydrogen for feedstock replacement under EU carbon border adjustments.
- PEM Electrolyzers:Proton exchange membrane stacks employ perfluorinated sulfonic acid membranes and iridium catalysts for rapid load-following capability. Japanese industrial decarbonization projects and South Korean hydrogen refueling networks prioritize this technology for pairing with intermittent offshore wind and solar resources.
- Solid Oxide Electrolyzers:High-temperature ceramic cells operating at 700-800°C achieve superior efficiency when integrated with industrial waste heat from steel and chemical plants.
- Others:Emerging anion exchange membrane and reversible fuel cell configurations address specific niche applications in distributed energy systems.
Mature deployment sits with alkaline electrolyzers. Newer deployment is concentrated in PEM systems for renewable-coupled applications.
End User:
Industrial offtake drives absolute capacity additions, while transportation applications exhibit the steepest expansion trajectory as fuel cell vehicle fleets scale.
- Industrial:Ammonia synthesis, petroleum refining, and steel direct reduction constitute the dominant demand source. German chemical parks and Middle East fertilizer complexes anchor procurement volumes under tightening emissions accounting regimes.
- Transportation:Hydrogen refueling infrastructure for heavy-duty trucking and maritime bunkering commands system designs optimized for rapid dispensing pressure and high-purity output.
- Commercial:Data center backup power and distributed generation applications favor modular containerized configurations with remote monitoring capabilities.
- Residential:Micro-combined heat and power systems and home refueling stations represent nascent demand concentrated in Japan's ENE-FARM program expansion zones.
Volume concentration remains with industrial end users. Fastest capacity scaling appears in transportation applications as fleet operators electrify long-haul corridors.
Installation:
Stationary land-based systems dominate current manufacturing output, though offshore platform configurations are attracting engineering investment for North Sea wind-to-hydrogen developments.
- Stationary:Fixed industrial installations at chemical plants and refineries constitute the established deployment mode. German Ruhr district clusters and Rotterdam port facilities exemplify large-scale stationary integration with existing pipeline infrastructure.
- Offshore:Marinized electrolyzer platforms co-located with wind farms eliminate transmission constraints for remote renewable resources. Danish and Dutch North Sea developments are pioneering salt-air corrosion-resistant stack enclosures.
- Onshore:Ground-mounted utility-scale systems at renewable generation sites enable direct coupling without grid interconnection delays.
- Mobile:Containerized transportable units serve temporary construction power and emergency response applications requiring rapid redeployment.
Established capacity sits with stationary installations. Emerging deployment concentrates in offshore configurations for stranded renewable integration.
Application:
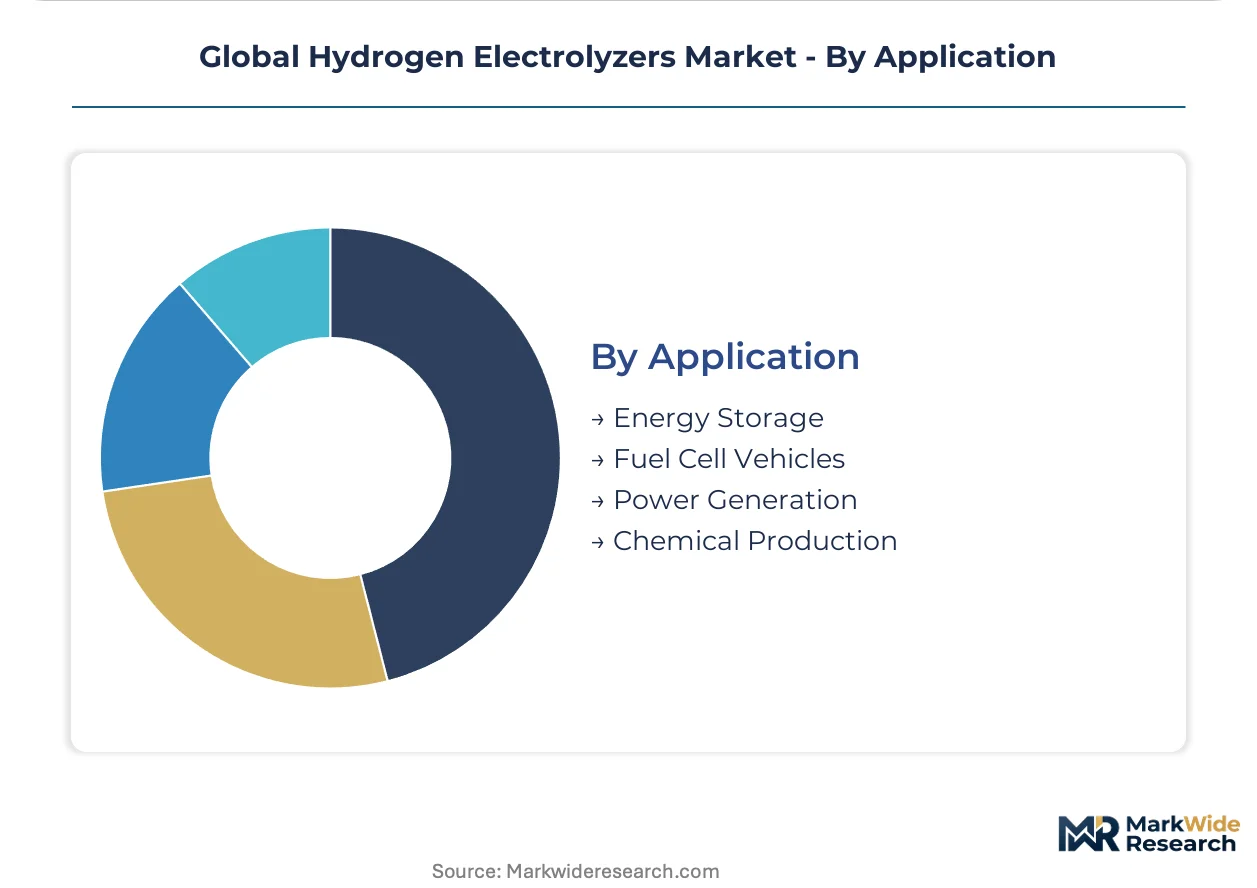
Chemical production absorbs the largest share of electrolyzer capacity, while energy storage applications are gaining share fastest as grid operators seek long-duration flexibility.
- Chemical Production:Green hydrogen feedstock for ammonia, methanol, and synthetic fuels represents the primary commercial outlet. German steelmakers and Dutch chemical clusters are converting existing steam methane reforming capacity to electrolytic hydrogen under EU Green Deal compliance timelines.
- Energy Storage:Power-to-gas systems convert surplus renewable electricity into hydrogen for seasonal storage and grid reinjection. California and German transmission operators are piloting salt cavern storage paired with electrolyzer farms.
- Fuel Cell Vehicles:High-purity hydrogen dispensing for passenger and commercial vehicle fleets requires contaminant specifications below 1 ppm total impurities.
- Power Generation:Hydrogen-fired turbines and fuel cell power plants utilize electrolyzer output for dispatchable clean electricity.
Current capacity concentration rests with chemical production. Steepest growth trajectory appears in energy storage as renewable penetration increases grid flexibility requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones for renewable hydrogen in Rotterdam, Jubail, and Gujarat concentrate electrolyzer demand through tax abatements and streamlined permitting. These zones attract manufacturing investment and anchor offtake contracting for industrial decarbonization.
Germany
Ruhr district chemical parks and Hamburg port clusters drive alkaline electrolyzer procurement for ammonia feedstock switching. The EU Green Deal carbon border adjustment mechanism tightens compliance timelines for exporters. Siemens Energy anchors large-scale PEM deployments in Lower Saxony wind-to-hydrogen corridors.
China
Inner Mongolia and Xinjiang renewable bases pair with coastal industrial zones for hydrogen transmission. MIIT dual carbon goals mandate electrolyzer capacity additions in steel and chemical sectors. LONGi and alkaline engineering specialists concentrate manufacturing scale in Jiangsu and Zhejiang provinces.
Japan
Kansai industrial clusters and Kyushu offshore wind zones prioritize PEM systems for dynamic load-following. METI hydrogen roadmap targets commercialize 2040 timelines for steel and chemical decarbonization. ENE-FARM residential expansion in Tokyo metro creates distributed electrolyzer demand for micro-CHP systems.
United States
Texas Gulf Coast hydrogen hubs and California Central Valley renewable farms anchor utility-scale deployments. IRA production tax credits compress green hydrogen cost curves for ammonia and sustainable aviation fuel projects. Plug Power and ITM Power position for Gulf Coast petrochemical retrofit opportunities.
Saudi Arabia
NEOM gigaproject and Jubail industrial city integrate electrolyzer capacity with solar and wind generation for ammonia export. The national hydrogen strategy targets blue and green hydrogen supply to European and Asian markets. ACWA Power and industrial partners develop marinized systems for Red Sea coastal installations.
Global Hydrogen Electrolyzers Market Competitive Environment
Chinese producers anchor the cost-engineering tier; German and Japanese specialists hold premium positioning for high-efficiency systems. The vendor base separates into consolidated stack manufacturers and modular system integrators competing on deployment speed. Three archetypes dominate: industrial conglomerates with turbine heritage, pure-play hydrogen engineering firms, and diversified energy equipment suppliers. Capacity expansion and strategic technology licensing constitute the dominant competitive moves as manufacturers race to secure gigawatt-scale project pipelines.
Within the industrial conglomerate tier, Siemens Energy and Thyssenkrupp Nucera exemplify engineering heritage leveraged for large-scale project execution. Nel Hydrogen occupies a position spanning stack manufacturing through downstream integration. Among Asia-Pacific specialists, Asahi Kasei and LONGi represent divergent technology pathways—membrane chemistry expertise versus photovoltaic-scale manufacturing discipline.
| Leading Market Players |
|---|
| Siemens Energy |
| Nel Hydrogen |
| Thyssenkrupp Nucera |
| Plug Power |
| ITM Power |
| John Cockerill Hydrogen |
| McPhy Energy |
| Asahi Kasei |
| LONGi |
| Others |
Value Chain & Pricing Dynamics
Alkaline stack manufacturing migration from European engineering centers to Chinese coastal provinces simultaneously compresses unit economics and concentrates procurement leverage among Jiangsu and Zhejiang production clusters. This geographic shift forces PEM manufacturers to defend margin structures through iridium catalyst efficiency gains while navigating fluorinated membrane precursor restrictions under EU F-Gas Regulation compliance timelines.
Pricing Analysis
Short lead-time premiums of 15-25% apply to PEM systems for Japanese offshore wind-to-hydrogen projects facing METI roadmap deadlines, while spot inventory discounts emerge for standardized alkaline units from Chinese manufacturers with excess production capacity. Three-tier pricing structure across premium, standard, and economy levels separates iridium-loaded PEM stacks with KGS certification from nickel-based alkaline systems with CE marking and unbranded commodity units for industrial feedstock buyers. Cost compression in alkaline tiers is intensifying because LONGi and engineering specialists are vertically integrating cell stack production with renewable energy manufacturing. Ammonia producers in Germany exhibit highest price sensitivity due to carbon border adjustment exposure, while Saudi gigaproject developers prioritize system reliability over unit cost.
Supply Chain Analysis
Freight cost volatility from Shanghai to Rotterdam has elevated landed cost premiums for European-bound alkaline systems, compressing margins for German system integrators dependent on Chinese cell stack imports. Supply concentrates in China for membrane electrode assemblies, South Africa for iridium catalysts, and Japan for perfluorinated sulfonic acid membranes. Raw material dependencies include nickel mesh electrodes, proton-conducting polymer films, and high-purity potassium hydroxide electrolyte. Single-source vulnerability for iridium from Russian and South African mining operations creates supply security exposure for PEM manufacturers. Distribution runs through EPC contractors and industrial gas suppliers for large-scale chemical plant deployments, with direct OEM relationships dominating transportation infrastructure projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal carbon border adjustment mechanism constructs a cost-of-compliance moat that rewards electrolyzer manufacturers with certified renewable hydrogen supply chains and penalizes unverified imports. F-Gas Regulation membrane precursor restrictions compound this barrier by elevating input costs for non-compliant suppliers.
For Market Incumbents: Anchor market position through backward integration into iridium catalyst recycling capabilities to offset South African supply concentration risk. Defend against Chinese alkaline cost engineering by securing long-term offtake contracts with German ammonia producers under EU Green Deal compliance timelines. Prioritize certification investment for multi-standard product platforms covering IEC, ASME, and KGS approval pathways to compress 18-24 month qualification cycles.
For New Entrants and Emerging Players: Launch via containerized system leasing models targeting Indian PLI scheme manufacturing incentives for Middle East export markets. White-space opportunity concentrates in solid oxide electrolyzer integration with Japanese steel plant waste heat recovery, where operational data scarcity limits incumbent lock-in. Target distributed commercial applications including data center backup power and remote industrial sites with modular 10-20 megawatt building blocks that reduce single-point commissioning risk.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by industrial conglomerates seeking turbine-to-hydrogen vertical integration. Long-term viability favors manufacturers with captive membrane chemistry expertise and established gigawatt-scale project pipelines. Acquisition target archetype includes solid oxide engineering specialists with demonstrated 80%+ system efficiency and industrial waste heat integration capabilities. Watch for F-Gas Regulation enforcement intensity as inflection indicator for PEM stack input cost trajectories.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Buildout | Chinese manufacturers expand Jiangsu production to capture German ammonia feedstock switching demand. |
| Backward Integration | PEM specialists develop in-house iridium catalyst coating to reduce South African supply exposure. |
| Technology Licensing | Alkaline engineering firms license stack designs to Indian PLI scheme beneficiaries for Middle East exports. |
| Long-term Supply Agreement | Japanese industrial clusters contract PEM capacity for Kansai steel decarbonization under METI roadmap. |
| Joint Venture | European EPC contractors partner with offshore wind developers for North Sea marinized system deployment. |
Study Parameters
Trade flow databases, IEA hydrogen project tracking, and SEC filings from disclosed electrolyzer manufacturers formed the secondary backbone for demand quantification and competitive positioning assessment. Primary interviews with utility planning officers, IPP project developers, EPC contractors, and fuel supply specialists validated deployment timelines and technology selection criteria. Bottom-up stack shipment aggregation and top-down renewable hydrogen demand modeling were triangulated against electrolyzer manufacturing capacity announcements.
Historical trendline analysis of alkaline and PEM system cost curves informed the projection framework across the analysis window. Segmentation dimensions modeled include electrolyzer technology type, end-use industry application, installation configuration, and regional regulatory cluster. CAGRs were derived from capacity-weighted average deployment trajectories incorporating project development cycle durations and grid interconnection queue delays. Industry-specific forecast inputs include F-Gas Regulation compliance cost pass-through assumptions and METI hydrogen roadmap commercialization timelines.
Policy enforcement variance, iridium supply disruption, and offshore wind development delays are the dominant revision risks that could compress or extend forecast trajectories. Forecasts reflect documented assumptions regarding technology cost reduction curves and regulatory implementation schedules. Stakeholders should weight assumptions against their own operating context and regional compliance exposure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydrogen Energy
Hydrogen Energy Electrolyzer Market
Hydrogen Energy
Asia Pacific Liquid Hydrogen Market
Hydrogen Energy
Hydrogen Production Electrolyser Market
Hydrogen Energy
Solar Hydrogen Panel Market
Hydrogen Energy
Hydrogen Ejector Market
Hydrogen Energy
Green Hydrogen Storage Technology Market
Hydrogen Energy
Hydrogen Market
Hydrogen Energy
Hydrogen Refueling Protocol and Dispenser Performance Test Systems Market
Hydrogen Energy
Green Hydrogen Energy Storage System Market
Hydrogen Energy
Hydrogen Powered Engine Market
Hydrogen Energy
Hydrogen Purification Units Market
Hydrogen Energy
70MPa High Pressure Hydrogen Storage Cylinders Market
Hydrogen Energy
Hydrogen Purification Technologies Market
Hydrogen Energy
Hydrogen Generator Market
Hydrogen Energy
Black Hydrogen Market
Hydrogen Energy
US Hydrogen Fueling Station Market