
 Green Hydrogen Storage Technology Market | 2026-2036
Green Hydrogen Storage Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Green Hydrogen Storage Technology Market Insights
Carbon fiber composite tanks are expanding their share in high-pressure hydrogen containment, displacing conventional metal-lined cylinders across transport and stationary applications. GKN Hydrogen leverages its automotive heritage to dominate lightweight pressure vessel design. Linde sustains global leadership through captive electrolyzer and storage infrastructure integration. McPhy Energy specializes in solid-state metal hydride systems for compact, low-pressure deployment.
Green hydrogen storage technology encompasses engineered systems for retaining hydrogen produced via electrolysis using renewable electricity, operating at pressures from 350 to 700 bar or cryogenic temperatures near 20 Kelvin. Its primary purpose is to bridge temporal and spatial gaps between variable renewable generation and industrial or mobility offtake. Tank storage leads installed capacity due to modularity and faster deployment timelines, while underground caverns attract capital for seasonal buffering where suitable geology exists. Metal hydrides command premium pricing in confined-space applications such as fuel cell vehicles, where volumetric density outweighs gravimetric penalties.
The EU Green Deal and F-Gas Regulation shape equipment standards and refrigerant choices for liquefaction pathways, while Germany's KBA certifies onboard storage for commercial vehicle integration. The US Department of Energy and NHTSA jointly influence tank safety protocols and vehicle crashworthiness requirements. Stakeholders must weigh geological screening timelines against metal hydride material cost curves when committing capital to multi-decade storage assets.
Market Dynamics
Carbon fiber composite pressure vessels are compressing deployment timelines for high-capacity hydrogen storage, forcing steel tank manufacturers to accelerate material transitions or cede transport applications entirely.
Growth Catalysts
- EU Green Deal industrial mandates:Binding decarbonization targets for steel and ammonia producers are pulling forward demand for 700-bar gaseous storage systems at German and Dutch port clusters.
- Metal hydride material advances:Lanthanum-nickel alloy formulations now achieve 1.5 wt% hydrogen density, unlocking onboard storage for fuel cell buses where space constraints rule out compressed gas.
- Germany's KBA certification streamlining:Harmonized vehicle integration protocols are reducing time-to-market for commercial fleet operators seeking Type IV tank approvals.
Market Restraints
- Carbon fiber feedstock concentration:Toray, Hexcel, and SGL Carbon control 70% of aerospace-grade precursor supply, exposing tank fabricators to polyacrylonitrile price volatility and allocation rationing.
- Cryogenic liquefaction energy penalty:Boil-off losses of 0.3-1% daily and 30-40% round-trip efficiency drain project economics where renewable electricity costs remain elevated.
- Geological screening timelines:Salt cavern feasibility studies require 3-5 years of seismic and geomechanical analysis before construction permits, delaying seasonal storage investments in regions without proven formations.
Strategic Opportunities
- India's National Hydrogen Mission:PLI scheme subsidies for electrolyzer manufacturing are creating captive storage demand at renewable energy parks in Gujarat and Tamil Nadu.
- Offshore wind-to-hydrogen platforms:Integration of desalination, electrolysis, and liquid organic hydrogen carrier synthesis at North Sea installations bypasses onshore land constraints.
- US Inflation Reduction Act hydrogen production tax credits:$3/kg PTC eligibility is attracting capital to Gulf Coast salt dome developments for cavern-scale buffering of export-oriented production.
Industry Challenges
- Composite pressure vessel technician scarcity:Filament winding and autofrettage operations require specialized certifications that training institutes have not scaled to match deployment schedules.
- ISO 19881/EC 79 harmonization gaps:Divergent burst-test protocols and permeation measurement standards are forcing dual certification runs for equipment serving both European and Asian markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Green Hydrogen Storage Technology Market |
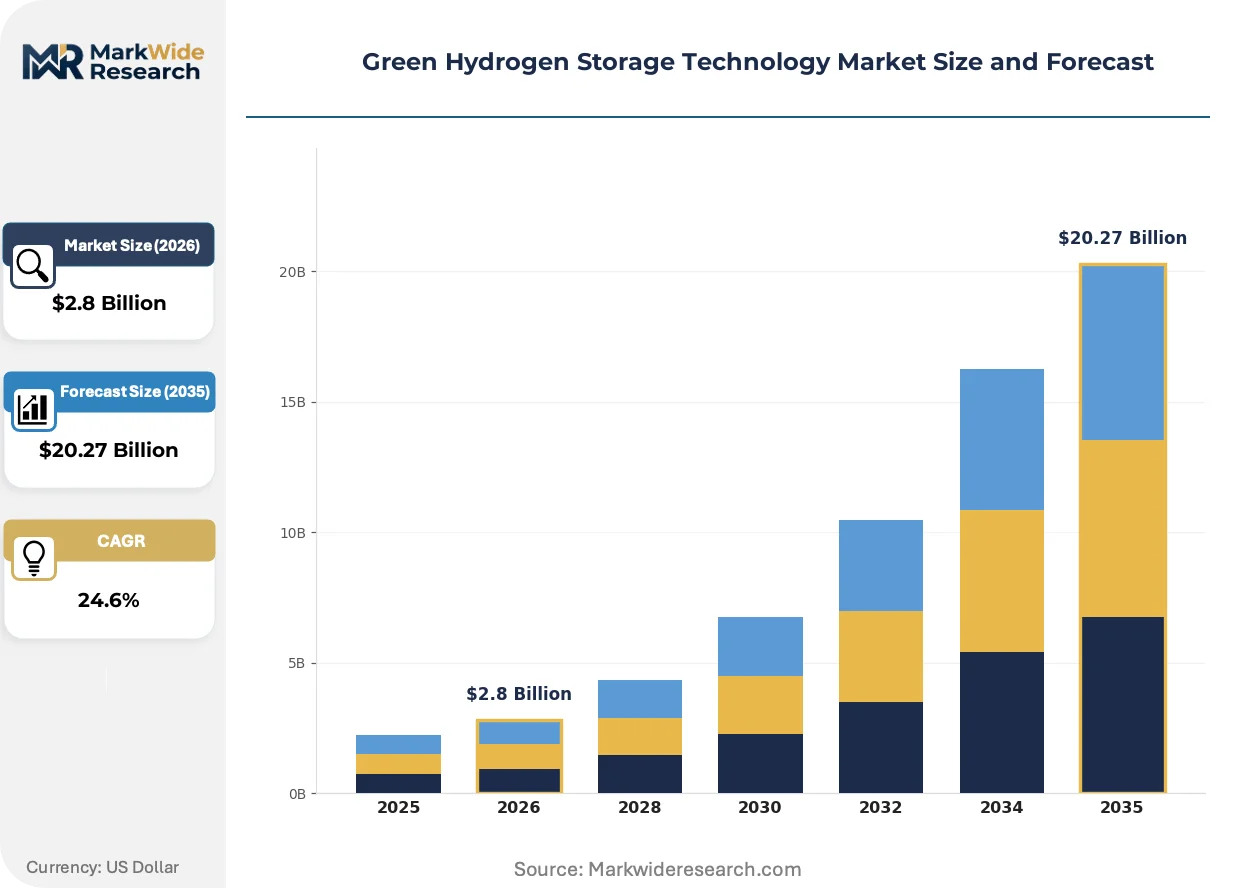
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $20.27 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Storage Type: Tank Storage, Underground Caverns, Metal Hydrides, Chemical Hydrogen Storage End User: Energy Producers, Industrial Users, Transportation Sector, Power Plant Operators Technology: Compression, Liquefaction, Adsorption, Reversible Chemical Reaction Application: Fuel Cell Vehicles, Renewable Energy Integration, Backup Power Supply, Industrial Processes |
| Companies Covered | GKN Hydrogen, GRZ Technologies, NPROXX, 3M Company, Hbank Technologies Inc., Air Liquide, Air Products and Chemicals, Inc., Linde, McPhy Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Green Hydrogen Storage Technology Market Trends and Innovations
Material science breakthroughs and regulatory calibration are compressing the gap between laboratory performance and field deployment for hydrogen containment systems.
Solid-state metal hydride cartridges are integrating with modular electrolyzer-skid designs to eliminate compressor stages entirely. Remote industrial sites in Norway and Chile are adopting these low-pressure systems where maintenance access is limited. The technology is integrating gaseous and liquid storage pathways into unified asset portfolios, allowing operators to arbitrage between delivery modes based on offtake timing.
The EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants used in hydrogen liquefaction plants, forcing equipment suppliers to adopt magnetic-bearing turbo-expanders and helium-neon mixed refrigerant cycles. Industrial gas majors operating Rotterdam and Antwerp terminals are retrofitting cold boxes ahead of 2030 compliance deadlines. Cryogenic storage economics are tightening as refrigerant substitution adds 8-12% to capital costs for new liquefaction trains.
Steel producers in Sweden and Spain are consolidating procurement around long-term hydrogen supply agreements with embedded storage service fees, displacing spot-market molecule purchases. Engineering firms are responding with build-own-operate models for cavern and tank farm assets, transferring balance-sheet risk from industrial offtakers to infrastructure specialists. This contractual evolution is most advanced where EU carbon border adjustment mechanisms expose import-competitive sectors to emissions pricing differentials.
Green Hydrogen Storage Technology Market Segmentation
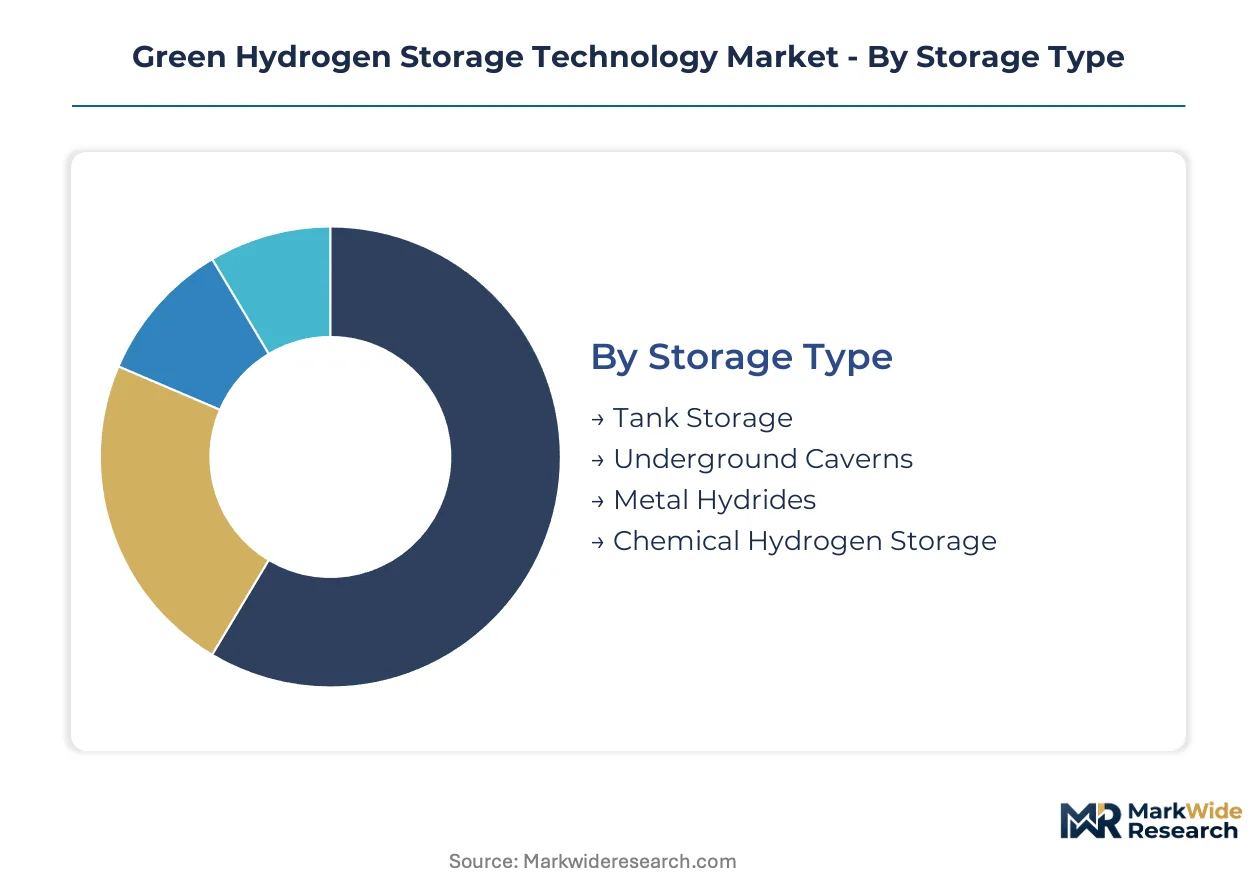
Storage technology selection in green hydrogen infrastructure hinges on pressure-temperature tradeoffs, geological availability, and offtake velocity requirements. Segmentation reveals how capital deployment splits between proven tank systems and emerging solid-state alternatives.
Storage Type:
Carbon fiber precursor supply concentration among Japanese and German chemical conglomerates shapes tank manufacturing economics and regional deployment feasibility.
- Tank Storage:Type III and Type IV composite pressure vessels dominate transport and stationary buffering at 350-700 bar operating pressures. German automotive suppliers and Dutch port operators anchor demand for modular tank farms enabling rapid capacity scaling.
- Underground Caverns:Salt dome and depleted gas field conversions enable seasonal TWh-scale storage where suitable geology exists. US Gulf Coast salt formations and Northern European sedimentary basins concentrate feasibility studies, though 3-5 year screening timelines delay project commitments.
- Metal Hydrides:Lanthanum-nickel and magnesium-based alloys achieve compact low-pressure containment for confined-space applications.
- Chemical Hydrogen Storage:Liquid organic hydrogen carriers and ammonia cracking systems enable maritime and long-haul transport logistics.
Today's leader: Tank Storage. Tomorrow's challenger: Metal Hydrides.
End User:
Procurement scale and hydrogen purity requirements divide the customer base between bulk industrial offtakers and distributed mobility operators.
- Industrial Users:Steel, ammonia, and refinery operators drive the largest single-site storage deployments under EU Green Deal decarbonization mandates. German steel clusters and Dutch chemical corridors are consolidating long-term supply agreements with embedded storage service fees.
- Transportation Sector:Fuel cell bus fleets and heavy-duty trucking operators prioritize volumetric density and fast-fill protocols over absolute cost minimization. KBA certification harmonization is accelerating Type IV tank integration for commercial vehicle platforms.
- Energy Producers:Renewable power developers require buffering assets to manage curtailment risk and offtake timing mismatches.
- Power Plant Operators:Grid-scale hydrogen peaking facilities need multi-day storage duration to arbitrage wholesale electricity price volatility.
Industrial Users command current capacity bookings. Transportation Sector applications are climbing the fastest as fleet electrification accelerates.
Technology:
Round-trip efficiency penalties and capital intensity separate mature compression pathways from emerging liquefaction and solid-state alternatives.
- Compression:Multi-stage mechanical compression to 350-700 bar remains the baseline for gaseous storage, with diaphragm and ionic liquid compressor technologies displacing conventional reciprocating designs in high-purity applications.
- Liquefaction:Cryogenic cooling to 20 Kelvin enables highest gravimetric density for maritime export, though 30-40% energy penalty and boil-off losses constrain economics. EU F-Gas Regulation refrigerant phase-downs are forcing magnetic-bearing turbo-expander retrofits at Rotterdam and Antwerp terminals.
- Adsorption:Metal-organic framework and carbon-based sorbents operate at moderate pressures with reduced thermal management requirements.
- Reversible Chemical Reaction:Liquid organic hydrogen carriers and ammonia synthesis enable ambient-temperature transport with catalytic release at destination.
Compression retains installed base dominance. Liquefaction faces steepest expansion trajectory as export-oriented production scales.
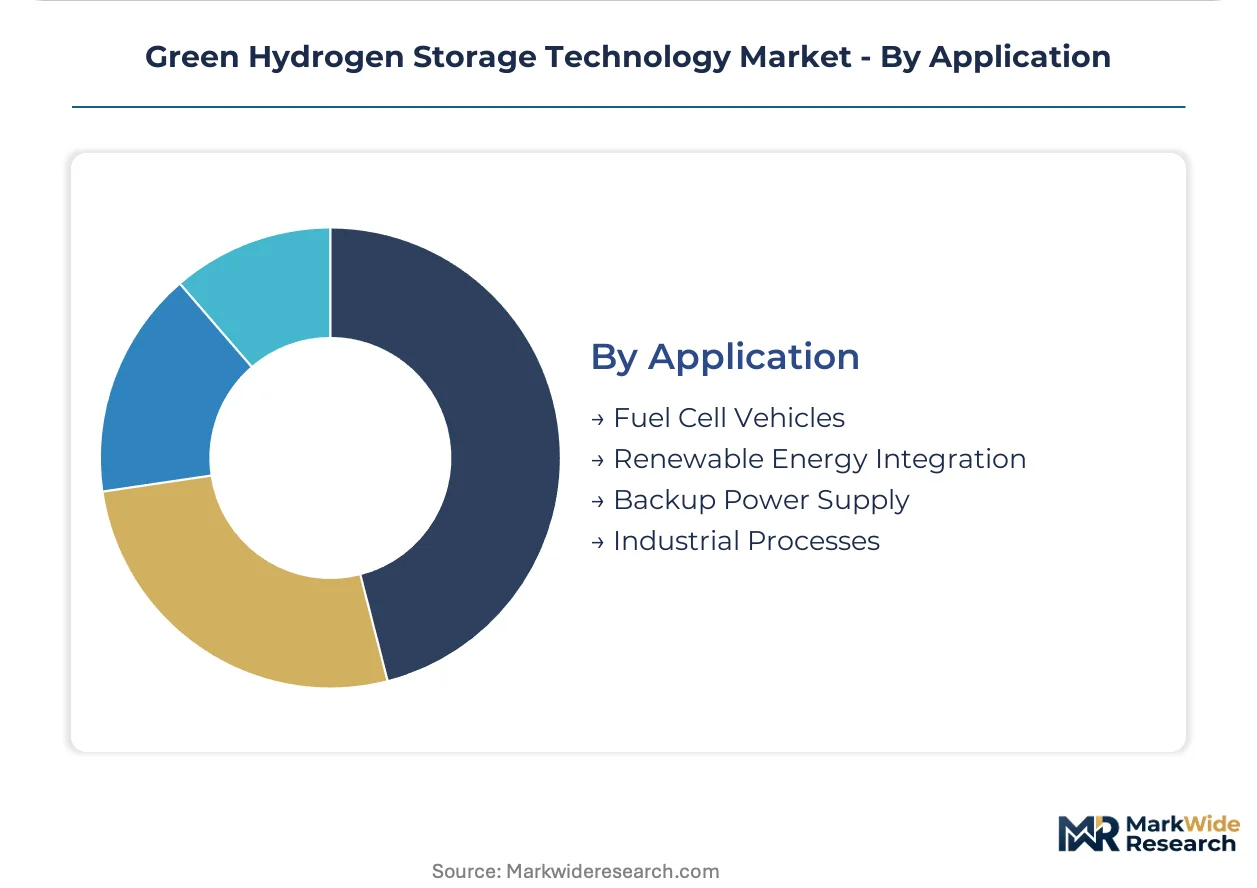
Application:
End-use velocity requirements and space constraints dictate storage modality selection across mobility, grid, and stationary industrial contexts.
- Industrial Processes:Steel direct reduction and ammonia synthesis demand continuous high-volume hydrogen supply with minimal pressure drop, favoring pipeline-connected cavern or tank farm configurations. Swedish and Spanish producers are transferring balance-sheet risk to infrastructure specialists through build-own-operate contracts.
- Fuel Cell Vehicles:Onboard storage density and crashworthiness requirements have locked in 700-bar Type IV tanks for passenger cars, with metal hydride cartridges gaining traction in fuel cell buses where packaging flexibility outweighs gravimetric penalty.
- Renewable Energy Integration:Electrolyzer-buffering systems bridge variable wind and solar generation with industrial offtake schedules.
- Backup Power Supply:Telecommunications and data center operators deploy compact hydrogen storage for diesel generator displacement in emissions-sensitive jurisdictions.
Industrial Processes anchor current investment flows. Fuel Cell Vehicles represent the fastest-growing application as commercial fleet deployment accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial clusters anchor near-term deployment of large-scale hydrogen storage infrastructure. The EU Green Deal mandates steel and ammonia decarbonization across member states. National regulatory frameworks and geological endowments are shaping divergent storage technology preferences.
Germany
Ruhr steel producers and Hamburg port operators drive demand for 700-bar gaseous storage systems. KBA certification protocols streamline Type IV tank integration for commercial vehicle fleets. North Rhine-Westphalia hosts concentrated electrolyzer-buffering projects at chemical corridor sites.
United States
Gulf Coast salt dome formations attract cavern-scale seasonal storage investments. IRA hydrogen production tax credits pull capital toward export-oriented production buffering. Texas and Louisiana industrial zones concentrate feasibility studies for multi-TWh underground facilities.
Netherlands
Rotterdam and Antwerp terminal operators retrofit cryogenic infrastructure ahead of EU F-Gas Regulation deadlines. Maritime hydrogen export logistics demand liquefaction capacity expansion. Port clusters integrate magnetic-bearing turbo-expanders to replace phased-down refrigerants.
India
Gujarat and Tamil Nadu renewable energy parks generate captive storage demand under National Hydrogen Mission subsidies. PLI scheme support for electrolyzer manufacturing creates localized buffering requirements. Western and southern coastal states anchor early industrial offtake agreements.
Sweden
SSAB and other steel producers consolidate procurement around long-term hydrogen supply with embedded storage fees. Build-own-operate contracts transfer cavern asset risk to infrastructure specialists. Northern sedimentary basins attract seasonal buffering investments for industrial direct reduction processes.
Green Hydrogen Storage Technology Market Competitive Landscape
Global majors compete with regional champions across electrolyzer-to-storage integration capabilities. The vendor base splits between industrial gas conglomerates with captive infrastructure and specialized tank fabricators with automotive heritage. Three archetypes dominate: integrated gas majors, composite pressure vessel specialists, and solid-state metal hydride innovators. Capacity expansion and strategic partnerships represent the primary competitive vectors as offtakers seek long-term supply security.
Within the integrated gas tier, Linde and Air Liquide exemplify full-chain positioning from electrolyzer deployment through storage infrastructure operation. McPhy Energy occupies a specialist position in solid-state containment systems. These three anchors illustrate divergent strategic bets: scale-driven molecule handling versus compact low-pressure technology for confined-space applications.
| Leading Market Players |
|---|
| GKN Hydrogen |
| GRZ Technologies |
| NPROXX |
| 3M Company |
| Hbank Technologies Inc. |
| Air Liquide |
| Air Products and Chemicals, Inc. |
| Linde |
| McPhy Energy |
| Others |
Pricing and Supply Chain Analysis
Polyacrylonitrile precursor pricing volatility cascades through carbon fiber composite pressure vessel manufacturing, compressing margins for tank fabricators while amplifying cost differentials between aerospace-grade and industrial-grade storage systems across German and Dutch port deployments.
Pricing Analysis
Input-cost pass-through from Toray and Hexcel carbon fiber allocations drives contract-based long-term offtake agreements as the dominant pricing model. Price differentiation separates KBA-certified Type IV tanks from uncertified alternatives, with volume scale and after-sales service bundling as secondary tiering factors. Pricing pressure intensifies in transport applications as steel cylinder manufacturers slash quotes to defend share against composite displacement. Industrial users show lowest price sensitivity due to embedded storage service fees in decarbonization mandates, while distributed mobility operators exhibit acute cost consciousness.
Supply Chain Analysis
Workforce scarcity for filament winding and autofrettage certifications concentrates manufacturing capacity in Germany, Japan, and South Korea despite raw material dependencies on aerospace-grade carbon fiber from Japanese and German chemical conglomerates. The supply chain draws from polyacrylonitrile precursors, lanthanum-nickel alloy feedstocks, and magnetic-bearing turbo-expander components. Single-source vulnerability in carbon fiber precursor supply exposes tank fabricators to allocation rationing. Distribution runs through engineering-procurement-construction contractors and industrial gas majors operating integrated electrolyzer-to-storage portfolios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Green hydrogen storage technology functions as a stable compounder anchored by binding EU industrial decarbonization mandates that institutionalize multi-decade demand visibility regardless of near-term hydrogen price cycles.
For Market Incumbents: Hedge carbon fiber supply exposure through backward integration into precursor manufacturing or captive offtake agreements with Toray and SGL Carbon. Accelerate technician certification programs in partnership with German and Dutch technical institutes to preempt workforce bottlenecks that constrain capacity expansion timelines. Defend margin position by embedding storage service fees within long-term industrial supply contracts rather than competing on spot tank sales. For New Entrants and Emerging Players: Direct-to-fleet digital sales platforms bypass entrenched EPC channels for fuel cell bus and trucking operators seeking rapid Type IV tank procurement. Target India's PLI-subsidized electrolyzer manufacturing clusters in Gujarat and Tamil Nadu where localized storage demand outstrips incumbent infrastructure presence. Pursue metal hydride cartridge integration with modular electrolyzer skids as the most penetrable white-space application. For Investors and Strategic Acquirers: Consolidation pressure builds where carbon fiber composite fabrication capabilities concentrate among automotive heritage suppliers lacking electrolyzer integration. Frame long-term viability around build-own-operate infrastructure specialists capturing balance-sheet risk transfer from steel and ammonia producers. Watch KBA certification harmonization progress with Asian regulators as the signal indicating acceleration in cross-border tank standardization and scalable fleet deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon Fiber Precursor | Mitigates Toray-Hexcel-SGL allocation rationing exposure for pressure vessel fabricators. |
| KBA-Aligned Certification Investment | Unlocks Type IV tank access to German commercial vehicle fleets under harmonized protocols. |
| Build-Own-Operate Cavern Contracts | Transfers multi-decade asset risk from SSAB and Spanish steel producers to infrastructure specialists. |
| Metal Hydride-Electrolyzer Skid Integration | Eliminates compressor stages for remote Norwegian and Chilean industrial sites. |
| Magnetic-Bearing Turbo-Expander Retrofit | Secures EU F-Gas Regulation compliance for Rotterdam and Antwerp liquefaction terminals. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with electrolyzer project developers, carbon fiber pressure vessel procurement leads at automotive suppliers, KBA certification engineers, salt cavern geomechanical specialists, and industrial gas storage infrastructure operators with secondary validation against SEC filings from Linde and Air Products, EU Green Deal implementation progress reports, German KBA type-approval databases, and IEA hydrogen project tracking data. Bottom-up electrolyzer capacity buildout estimates triangulated against top-down industrial decarbonization mandate targets.
Segment-weighting applied differential growth coefficients across storage type, end user, technology, and application dimensions over the projection horizon. The analytical framework modeled tank storage, underground cavern, metal hydride, and chemical hydrogen pathways against industrial, transportation, energy producer, and power plant operator demand archetypes. CAGRs derived from electrolyzer deployment curves, carbon fiber precursor supply elasticity, and geological screening timeline distributions. Forecast inputs included EU carbon border adjustment mechanism phase-in schedules and IRA hydrogen production tax credit eligibility thresholds.
The model assumes a particular technology adoption path; alternative pathways for solid-state metal hydride systems achieving breakthrough gravimetric density would alter the outlook. Forecasts reflect assumptions regarding KBA-Asian regulator harmonization timelines and salt cavern permitting velocity. Material deviation in carbon fiber precursor allocation protocols or EU F-Gas Regulation enforcement intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydrogen Energy
Solar Hydrogen Panel Market
Hydrogen Energy
Liquid Organic Hydrogen Carrier (LOHC) Market
Hydrogen Energy
Hydrogen Production Electrolyser Market
Hydrogen Energy
Hydrogen Generator Market
Hydrogen Energy
USA Hydrogen Electrolyzer Market
Hydrogen Energy
Hydrogen Purification Units Market
Hydrogen Energy
Asia-Pacific Clean Hydrogen Market
Hydrogen Energy
70MPa High Pressure Hydrogen Storage Cylinders Market
Hydrogen Energy
Hydrogen Purification Technologies Market
Hydrogen Energy
Liquid Hydrogen Market
Hydrogen Energy
Alkaline Water Electrolysis Market
Hydrogen Energy
Hydrogen Ejector Market
Hydrogen Energy
Hydrogen Energy Electrolyzer Market
Hydrogen Energy
Hydrogen Tanks Market
Hydrogen Energy
Clean Hydrogen Market
Hydrogen Energy
Europe Clean Hydrogen Market