
 Packaging Waste Recycling Market | 2026-2036
Packaging Waste Recycling Market Size, Share, and Industry Trends Forecast 2026-2036
Packaging Waste Recycling Market Outlook
Project finance tied to green bonds and asset-light leasing of sorting infrastructure is fragmenting competitive access in packaging waste recycling. WM leverages its national collection network to sustain vertical integration across hauling and materials recovery facilities. KW Plastics anchors its position through specialized HDPE and PP reprocessing capacity that dominates North American recycled resin supply. Envision Plastics differentiates via proprietary EcoPrime food-grade rPET technology that extends its reach into regulated packaging applications.
Packaging waste recycling encompasses the recovery and reprocessing of discarded packaging materials—predominantly thermoplastics, paperboard, aluminum, and soda-lime glass—through mechanical shredding, optical sorting, washing, and pelletization or repulping to restore material value for new packaging production. Mechanical recycling of polyethylene terephthalate and high-density polyethylene remains the dominant process pathway, though chemical recycling of mixed flexibles is gaining commercial traction as contamination-tolerant alternative. Plastic recycling by material type captures the largest value share, yet chemical and thermal recycling processes are expanding fastest as brands seek food-contact approved outputs from difficult-to-sort feedstocks. Collection through deposit return systems generates the cleanest material streams and commands margin premiums over curbside commingled flows, while industrial collection from distribution centers yields predictable volume contracts.
The EPA enforces resource conservation standards that shape landfill diversion targets and materials recovery facility permitting in the United States. ECHA implements REACH and RoHS frameworks that restrict hazardous additives in recycled packaging substrates across Europe, while the EU Green Deal's Packaging and Packaging Waste Regulation tightens recycled content quotas. Stakeholders must monitor how divergent chemical recycling approval pathways between FDA and EFSA jurisdictions determine which technologies achieve food-contact clearance and therefore access premium brand contracts.
Market Dynamics
Extended producer responsibility mandates are forcing brand owners to internalize end-of-life packaging costs, reshaping competitive economics across collection, sorting, and reprocessing tiers. This regulatory compression is accelerating capital deployment into contamination-tolerant technologies and regional hub infrastructure.
Growth Catalysts
- EU Green Deal Packaging Regulation:Mandatory recycled content quotas for plastic packaging create guaranteed offtake contracts for reprocessors serving food and beverage brands.
- Chemical recycling commercialization:Pyrolysis and depolymerization units unlock food-contact approved outputs from mixed flexible films previously routed to energy recovery.
- Germany's dual-system infrastructure:Household penetration rates for separate collection exceed 90%, generating the cleanest post-consumer feedstock streams in Europe.
Market Restraints
- Feedstock cost volatility:Virgin resin pricing indexed to naphtha and natural gas liquids compresses recycled pellet margins when oil markets soften.
- Optical sorting equipment concentration:European and Japanese machinery suppliers control 80% of near-infrared and robotics-based separation technology, creating capex bottlenecks.
- REACH authorization complexity:ECHA's substance-by-substance evaluation of legacy additives in recycled polymers delays food-contact approvals by 18-36 months.
Strategic Opportunities
- Deposit return system expansion:Italy, Portugal, and Romania are implementing container deposit frameworks modeled on German and Scandinavian precedents, opening new collection infrastructure investment.
- Post-industrial film aggregation:Consolidation of distribution center stretch wrap and pallet film from retail logistics chains yields predictable, high-purity polyethylene feedstock.
- FDA food-contact notification pathway:Accelerated review timelines for novel recycling technologies enable faster market access for chemical recycling outputs versus EFSA's precautionary approach.
Industry Challenges
- Polymer identification workforce gaps:Manual sorting facilities struggle to recruit technicians trained in resin identification codes and contamination detection at line speeds.
- Multi-technology integration complexity:Mechanical recycling lines retrofitted with chemical recycling pre-processing units face yield losses and downtime during feedstock transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Packaging Waste Recycling Market |
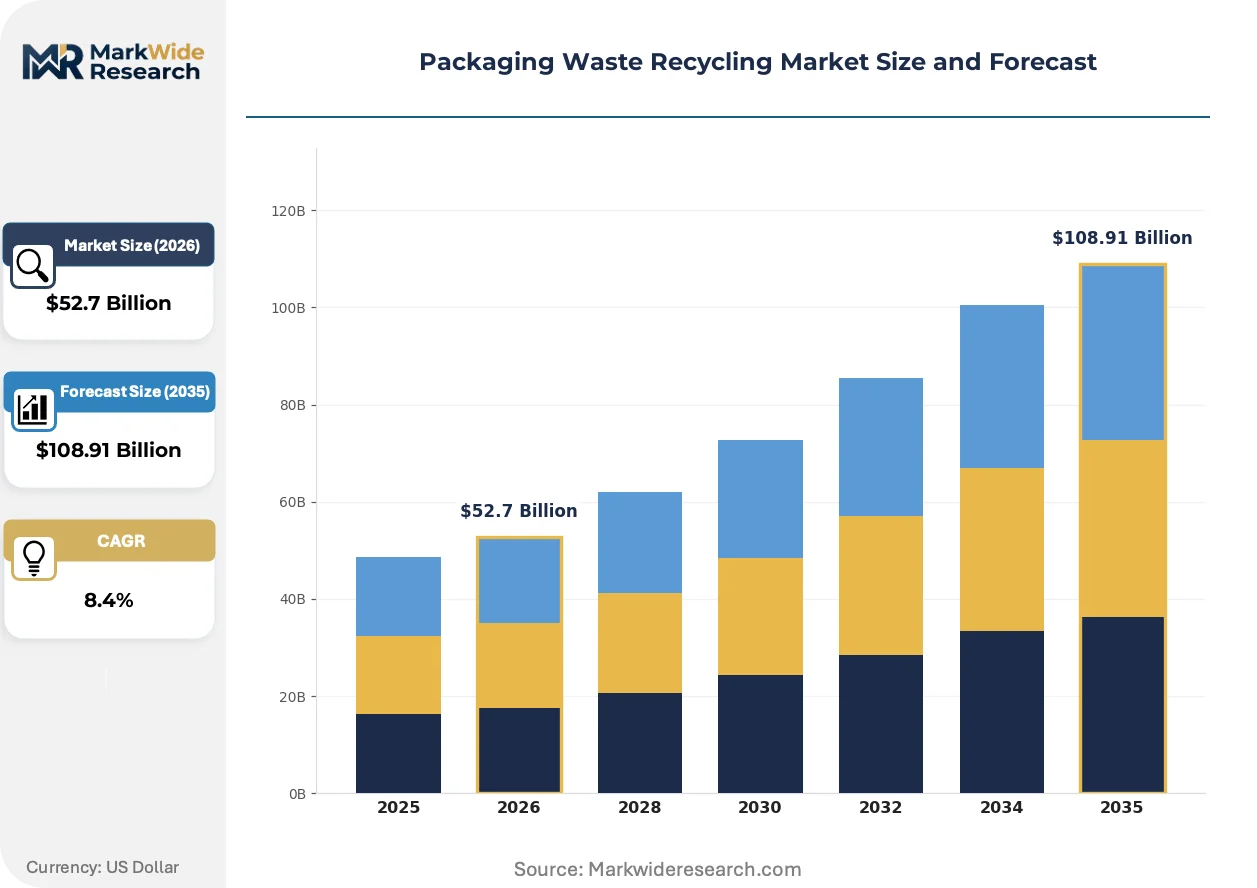
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $108.91 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Paper, Metal, Glass Collection Method: Curbside Pickup, Drop-off Center, Deposit Return, Industrial Collection End User: Household, Commercial, Industrial, Municipal Recycling Process: Mechanical, Chemical, Thermal, Biological |
| Companies Covered | Avangard Innovative, Envision Plastics, KW Plastics, WM, Phoenix Technologies, Ultra-Poly, Parc Corporation, PADNOS, B&B Plastics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Packaging Waste Recycling Market Strategic Shifts
Digital traceability and artificial intelligence are redefining how packaging waste flows are verified, priced, and routed through reprocessing networks. These capabilities are compressing information asymmetries between collectors, brands, and regulators.
Artificial intelligence-powered optical sorting is collapsing the historical trade-off between throughput and contamination removal efficiency. Food-grade rPET producers in North America and Europe are retrofitting lines with deep-learning vision systems that identify and eject non-target polymers at 98% accuracy rates. This capability is collapsing the premium previously commanded by deposit-return-sourced bales over curbside commingled material.
REACH and RoHS frameworks are tightening restrictions on hazardous additives in recycled packaging substrates across Europe. ECHA's 2024 update to the candidate list of substances of very high concern now covers additional phthalates and brominated flame retardants common in legacy packaging. Flexible film reprocessors serving non-food applications are most affected, with many redirecting capital to decontamination equipment or exiting regulated segments entirely.
Brand procurement teams are consolidating supplier relationships around vertically integrated recyclers with certified food-contact capabilities. Unilever and Coca-Cola Systems have reduced their approved rPET supplier lists by 60% since 2022, replacing fragmented merchant resin purchases with multi-year tolling agreements. This concentration is most visible in Germany and the Netherlands, where dual-system compliance costs favor scale and regulatory certainty over price competition.
Packaging Waste Recycling Market Segmentation
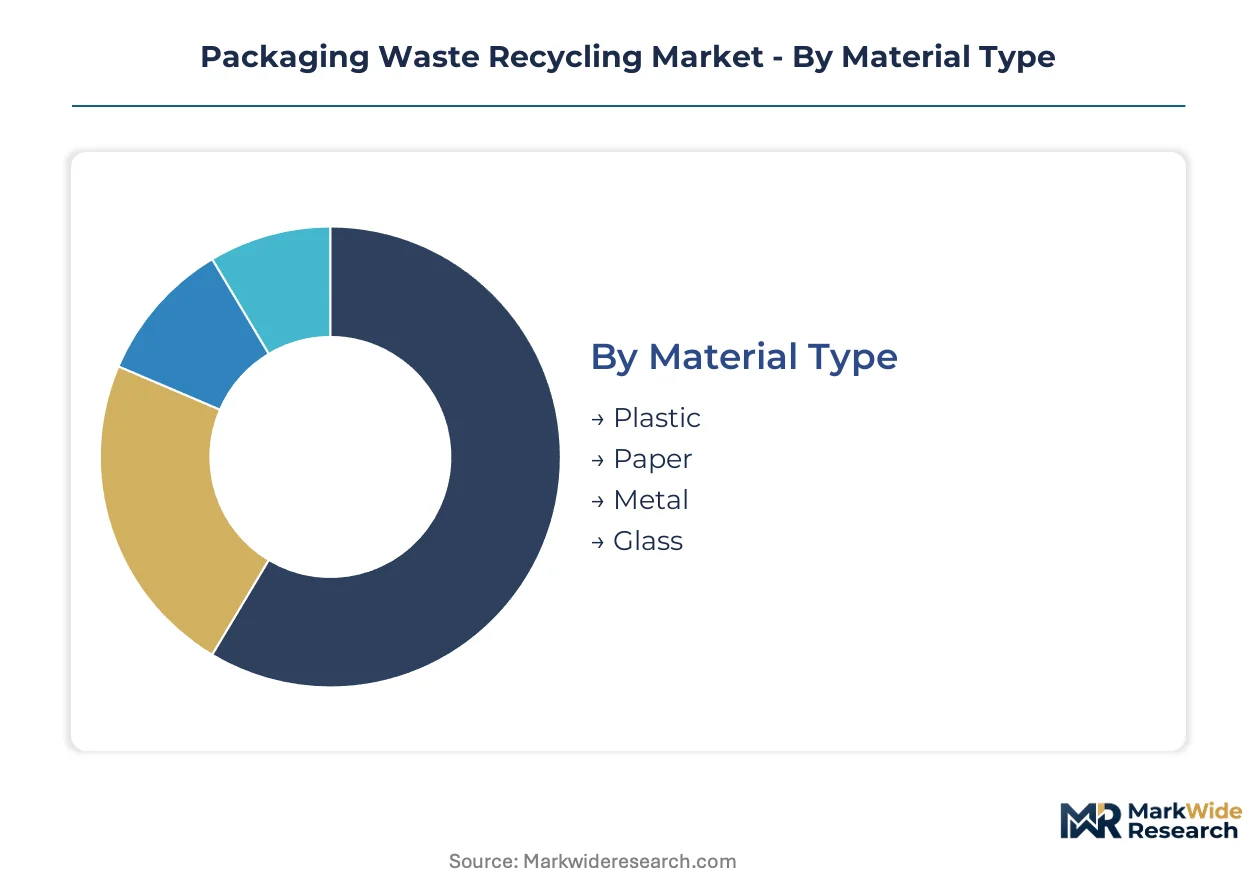
Packaging waste recycling markets fragment along material chemistry, collection logistics, and reprocessing technology dimensions. Each segmentation axis determines margin structure, regulatory exposure, and capital intensity for operators across the value chain.
Material Type:
Thermoplastics, fiber-based substrates, and inert materials each demand distinct sorting infrastructure and end-market specifications.
- Plastic:Polyethylene terephthalate and high-density polyethylene dominate mechanical reprocessing volumes. Demand concentrates in beverage bottle-to-bottle applications across Germany and the Netherlands, where EFSA food-contact approvals command premium pricing over non-food grades.
- Paper:Corrugated containerboard and folding carton repulping generates predictable tonnage from retail distribution networks. Demand concentrates in German dual-system collection zones, where source-separated fiber avoids costly deinking stages required for commingled municipal flows.
- Metal:Aluminum can sheet and steel tinplate recovery leverages eddy-current and magnetic separation.
- Glass:Soda-lime cullet reprocessing for container manufacturing requires color sorting and ceramic contamination removal.
Established volume favors Plastic; emerging adoption favors Metal.
Collection Method:
Feedstock purity and predictability vary dramatically by collection modality, shaping reprocessor offtake contracts and capital deployment.
- Curbside Pickup:Commingled municipal streams generate volume scale but require capital-intensive optical sorting and washing lines. Margin pressure intensifies when virgin resin prices soften, compressing the spread between bale acquisition and pellet sales.
- Deposit Return:Container deposit systems yield contamination rates below 2% versus 15-25% for curbside flows. Germany's dual-system infrastructure anchors European supply, with household penetration exceeding 90% and generating food-grade feedstock premiums.
- Drop-off Center:Self-haul collection captures motivated households and small commercial generators seeking diversion credits.
- Industrial Collection:Distribution center stretch wrap and pallet film aggregation yields predictable polyethylene volumes with minimal contamination.
Predictable supply contracts favor Industrial Collection; steepest expansion trajectory favors Deposit Return.
End User:
Generator scale and material homogeneity determine collection economics and reprocessing route selection.
- Household:Residential packaging discards flow through municipal contracts or extended producer responsibility schemes. Cost recovery depends on sorting technology efficiency and residue rates sent to energy recovery.
- Commercial:Retail and foodservice operations generate corrugated cardboard and flexible film in concentrated locations. Germany's VerpackG mandates drive compliance investment across franchise and independent operators.
- Industrial:Manufacturing and logistics facilities produce bulk polyethylene film and polypropylene strapping with minimal commingling.
- Municipal:Public sector waste authorities negotiate hauling and processing contracts with dual-system operators or integrated waste managers.
Contract concentration favors Commercial; infrastructure buildout favors Municipal.
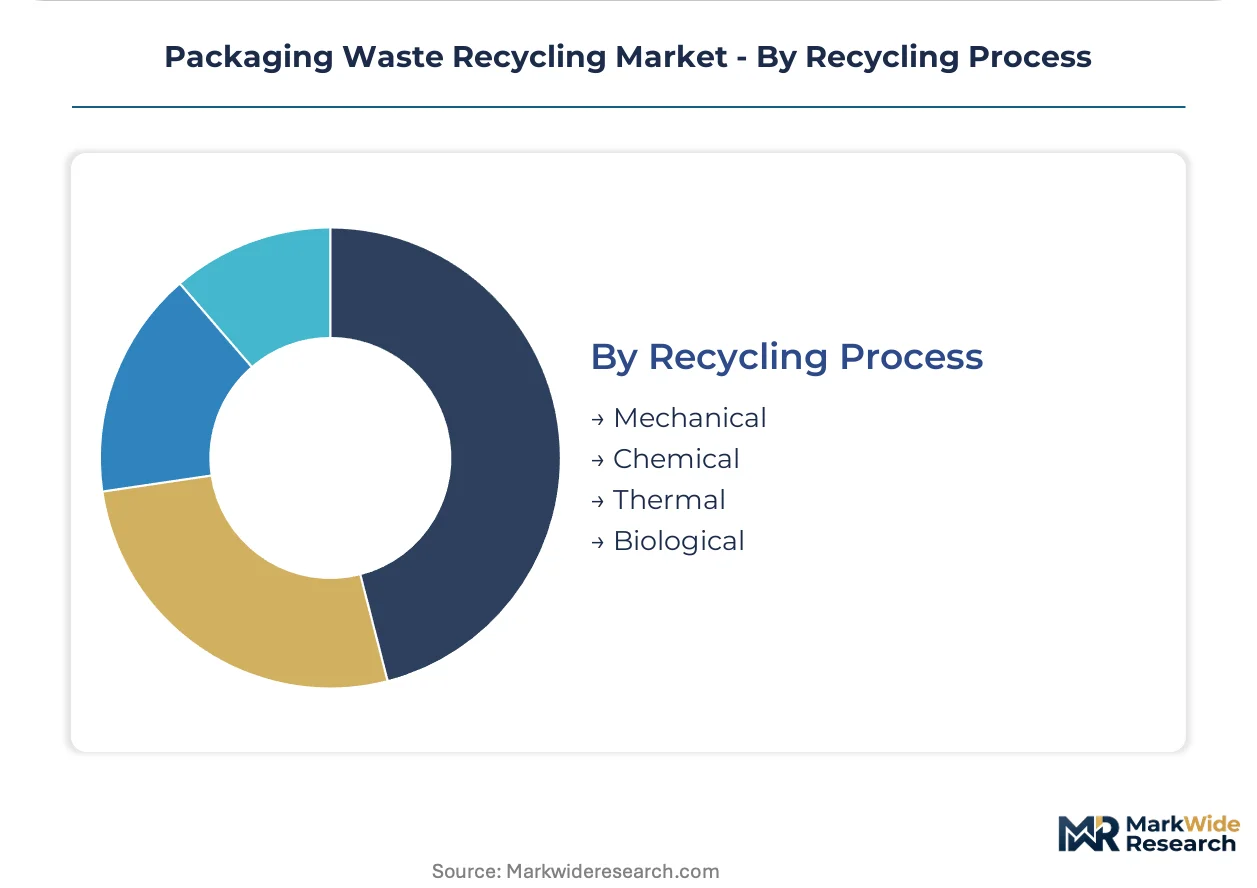
Recycling Process:
Technology selection balances feedstock tolerance, output quality specifications, and regulatory approval timelines.
- Mechanical:Shredding, washing, and pelletization of single-polymer streams remains the dominant cost structure. FDA food-contact notifications for novel mechanical processes proceed faster than EFSA equivalency determinations, favoring North American deployment for beverage brand contracts.
- Chemical:Pyrolysis and depolymerization units process mixed flexible films into monomer or naphtha-range outputs. REACH authorization complexity for pyrolysis oils delays European commercialization versus accelerated FDA review pathways.
- Thermal:Waste-to-energy and cement kiln co-processing handles residual fractions with calorific value.
- Biological:Enzymatic and fermentation-based routes target biodegradable packaging substrates.
Margin stability favors Mechanical; technology investment favors Chemical.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Extended producer responsibility mandates and green bond financing are redistributing packaging waste recycling capacity toward jurisdictions with mature collection infrastructure and regulatory certainty. National policy frameworks now determine competitive access more than feedstock availability or labor costs.
Germany
Dual-system packaging recovery infrastructure generates household penetration rates exceeding 90%, producing the cleanest post-consumer feedstock streams in Europe. The VerpackG extended producer responsibility framework tightens collection targets and compliance costs for brand owners. The Düsseldorf-Cologne industrial corridor concentrates mechanical reprocessing capacity serving beverage and food-contact applications.
United States
Deposit return system expansion across California, Oregon, and Maine is diverting PET and aluminum from curbside commingled flows into cleaner material streams. The EPA enforces landfill diversion targets and materials recovery facility permitting standards that shape regional infrastructure investment. The Southeast manufacturing belt—Georgia, South Carolina, and Tennessee—hosts expanding pelletization capacity tied to Coca-Cola Systems and Unilever procurement consolidation.
Netherlands
EFSA food-contact approval concentration attracts premium rPET demand from pan-European beverage brands seeking regulatory certainty. The EU Green Deal's Packaging and Packaging Waste Regulation tightens recycled content quotas for plastic packaging placed on the Dutch market. The Rotterdam-Antwerp port cluster serves as the primary entry point for pyrolysis oil imports and chemical recycling feedstock preprocessing.
Japan
METI's resource circulation policy framework mandates container-to-container recycling rates for PET bottles above 85%, driving investment in optical sorting and washing technology. JIS standards for recycled plastics create certification barriers that favor established reprocessors with quality management systems. The Kanto region around Tokyo concentrates consumer packaging generation and mechanical recycling infrastructure serving domestic brand procurement.
India
Extended producer responsibility rules under the Plastic Waste Management Rules, 2016, are tightening compliance obligations for FMCG and e-commerce brands operating in urban centers. BIS standards for recycled plastics are gradually harmonizing with food-contact safety requirements. The Maharashtra-Gujarat industrial corridor hosts emerging mechanical reprocessing clusters serving detergent and non-food packaging applications.
Packaging Waste Recycling Market Competitive Environment
Channel-controlling players compete with product-specialist players across fragmented tiers of collection, sorting, and reprocessing. National hauling networks and regional resin specialists each defend position through asset-light leasing arrangements and captive feedstock contracts. Three archetypes dominate: vertically integrated waste managers with collection-to-pellet operations; specialized thermoplastics reprocessors with food-contact certifications; and chemical recycling technology licensors seeking offtake partnerships. Competitive moves concentrate on M&A for regional hub consolidation and strategic partnerships for pyrolysis feedstock supply.
Among North American resin specialists, KW Plastics and Envision Plastics exemplify the product-specialist archetype through differentiated reprocessing capabilities. WM represents the channel-controlling model through its national collection network integration. These three entities anchor the competitive structure that smaller regional operators and emerging chemical recycling ventures must navigate for feedstock access and brand offtake contracts.
| Leading Market Players |
|---|
| Avangard Innovative |
| Envision Plastics |
| KW Plastics |
| WM |
| Phoenix Technologies |
| Ultra-Poly |
| Parc Corporation |
| PADNOS |
| B&B Plastics |
| Others |
Value Chain & Pricing Dynamics
The Düsseldorf-Cologne industrial corridor anchors European mechanical reprocessing capacity, and its concentration of EFSA-certified food-grade rPET output translates directly into pricing power over beverage brand procurement teams. Virgin resin volatility indexed to naphtha spreads feeds back into bale acquisition economics, forcing curbside-dependent operators to absorb margin compression when oil markets soften.
Pricing Analysis
Certification level creates the primary spread between food-contact approved pellets and non-food grades. Three-tier pricing structure separates EFSA-notified rPET from FDA-cleared mechanical outputs and uncertified industrial grades, with deposit-return-sourced material commanding premiums over curbside flows. Cost compression in curbside-sourced tiers is intensifying because optical sorting capex bottlenecks delay contamination removal efficiency gains. Small regional reprocessors exhibit highest price sensitivity, while integrated waste managers with captive collection networks maintain negotiating leverage.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for optical sorting equipment and decontamination reactor components. Feedstock sourcing draws from Germany's dual-system collection zones, the Southeast US manufacturing belt, and Japan's Kanto region. Pyrolysis oil imports hinge on Rotterdam-Antwerp port preprocessing capacity. Distribution runs through vertically integrated national haulers and specialized resin merchants serving consolidated brand procurement teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Extended producer responsibility mandates are transforming packaging waste recycling into a platform economy where feedstock traceability and regulatory certification interoperability determine competitive access. Digital ledger integration across dual-system operators and brand compliance platforms represents the decisive ecosystem shift.
For Market Incumbents: Harden collection network density in Germany and the Netherlands against chemical recycling entrants seeking pyrolysis feedstock supply. Invest in EFSA equivalency determination pipelines to defend food-grade certification premiums. Backward integration into deposit return system operations secures cleanest feedstock streams before competitors consolidate regional hub capacity.
For New Entrants and Emerging Players: Pursue post-industrial film aggregation contracts from retail distribution centers, where stretch wrap and pallet film yields predictable polyethylene volumes with minimal contamination. Italy, Portugal, and Romania offer penetrable deposit return system infrastructure buildout opportunities. Position chemical recycling units near Rotterdam-Antwerp to leverage existing feedstock preprocessing and pyrolysis oil import logistics.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because extended producer responsibility frameworks permanently reallocate end-of-life costs to brand owners and their contracted recyclers. Target specialized thermoplastics reprocessors with EFSA food-contact certifications and established tolling relationships with Coca-Cola Systems or Unilever. Monitor FDA food-contact notification approval velocity as inflection signal for North American chemical recycling commercialization timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Deposit Return System Expansion | Italy's container deposit framework implementation opens collection infrastructure investment comparable to German precedents. |
| Chemical Recycling Capacity Buildout | Pyrolysis unit deployment near Rotterdam-Antwerp leverages existing feedstock preprocessing and EU Green Deal compliance demand. |
| EFSA Certification Investment | Food-contact approval pipelines defend premium pricing against uncertified mechanical reprocessing competitors. |
| Post-Industrial Film Aggregation | Distribution center stretch wrap contracts yield predictable polyethylene feedstock with contamination rates below deposit-return thresholds. |
| Digital Traceability Platform Integration | Blockchain-verified chain-of-custody systems compress information asymmetries between collectors and brand procurement teams. |
Study Parameters
Operator-level perspectives from materials recovery facility managers, dual-system compliance officers, brand sustainability procurement leads, and pyrolysis technology licensors anchored the qualitative base. Secondary validation drew from EPA landfill diversion reports, ECHA REACH authorization databases, EU Green Deal regulatory filings, and German VerpackG compliance disclosures. Bottom-up bale flow modeling and top-down green bond financing analysis were triangulated against operating capacity announcements.
Scenario bracketing around virgin resin price volatility, chemical recycling approval timelines, and deposit return system expansion pace structured the analytical framework. Segmentation dimensions spanned material chemistry, collection modality, reprocessing technology, and end-use certification tier across the projection horizon. CAGRs were derived from installed capacity buildout curves and brand recycled content mandate compliance schedules. Feedstock contamination rate trajectories and optical sorting technology adoption curves served as industry-specific forecast inputs.
Sensitivities concentrate around EFSA equivalency determination delays, FDA food-contact notification acceleration, and oil market softness compressing recycled pellet spreads. Forecasts reflect assumptions regarding regulatory enforcement consistency and brand procurement consolidation velocity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Waste Management
Electronic Scrap Recycling Market
E-Waste Management
PET Bottle Recycling Market
E-Waste Management
E-Waste Management Market
E-Waste Management
Smart Waste Management Market
E-Waste Management
Electronic Waste Recycling Market
E-Waste Management
Europe E-Waste Management Market
E-Waste Management
UAE E-Waste Management Market
E-Waste Management
Middle East and Africa Solar Panel Recycling Market
E-Waste Management
Recycling Equipment and Machinery Market
E-Waste Management
Solar Trash Compactors Market
E-Waste Management
Smart Waste Collection Market
E-Waste Management
Release Liner Recycling Market
E-Waste Management
Solar Panel Recycling Management Market
E-Waste Management
North America E-Waste Management Market
E-Waste Management
Lithium-Ion Battery Reuse and Recycling Market
E-Waste Management
APAC E-Waste Management Market