
 Sustainable Air Filter Market | 2026-2036
Sustainable Air Filter Market Size, Share, and Industry Trends Forecast 2026-2036
Sustainable Air Filter Market Insights
Direct-to-facility procurement channels is reconfiguring how sustainable air filters reach end users, bypassing traditional HVAC distributor networks in favor of specification-driven sales. Mann+Hummel leverages its captive automotive filtration expertise to anchor industrial clean room contracts in Europe. Camfil competes through vertical integration into media manufacturing, controlling nanofiber membrane supply from polymer to pleated element. Donaldson Company specializes in high-durability pleated designs that extend replacement intervals for data center operators.
Sustainable air filters employ biodegradable or recyclable media substrates—often cellulose, polylactic acid, or electrospun biopolymers—engineered to capture particulate matter and gaseous contaminants while minimizing landfill burden at end of life. HEPA filters retain dominant share in healthcare and pharmaceutical applications where particulate retention thresholds demand MERV 17-20 performance. Electrostatic filters gain traction in commercial buildings seeking reduced pressure-drop energy savings. Bio-based filters occupy a nascent but expanding position among educational institutions prioritizing circular procurement policies.
EPA ENERGY STAR specifications and OSHA indoor air quality guidelines tighten performance verification requirements for filters deployed in US office complexes and manufacturing facilities. The EU Ecodesign Directive and CE marking under the MDR framework shape product access across European healthcare and hospitality venues. Stakeholders must monitor evolving biodegradability certification standards and regional procurement mandates to align R&D roadmaps with compliance trajectories.
Market Dynamics
EU F-Gas Regulation and REACH compliance are forcing manufacturers to eliminate synthetic refrigerant-linked chemistries from filter media, restructuring supply chains toward bio-based substrates and nanofiber membranes.
Growth Catalysts
- Healthcare procurement mandates:Clinics across Germany and Japan are expanding orders for low-emission filtration systems. Pharmaceutical manufacturing corridors in Switzerland and Singapore drive clean room installation volume.
- REACH and F-Gas Regulation:The EU compliance frameworks compel substitution of synthetic media with biodegradable alternatives. Manufacturers reformulate polymer inputs to retain CE marking access.
- Electrospun biopolymers:Cellulose and polylactic acid substrates achieve particulate retention parity with synthetic equivalents. Educational institutions prioritize circular procurement policies favoring landfill-burden reduction.
Market Restraints
- Raw material cost volatility:Fluctuations in cellulose pulp and polylactic acid resin prices compress margin structures for media producers.
- Supply concentration risk:Nanofiber membrane production clusters in select European polymer processing hubs, creating single-source dependencies.
- Technical performance ceiling:Bio-based HEPA filters struggle to achieve MERV 20 consistency at scale, limiting penetration in critical pharmaceutical containment applications.
Strategic Opportunities
- Data center cooling optimization:High-durability pleated designs extend replacement intervals for hyperscale operators seeking pressure-drop energy savings.
- US federal procurement alignment:EPA ENERGY STAR specifications and OSHA indoor air quality guidelines tighten verification requirements, favoring certified suppliers.
- Aftermarket service unbundling:Direct-to-facility channels bypass HVAC distributor networks, enabling specification-driven sales with higher margin capture.
Industry Challenges
- Biodegradability certification timelines:Evolving regional standards for end-of-life validation delay product launches and require redundant testing protocols.
- Legacy HVAC integration friction:Retrofitting bio-based filters into existing building management systems demands custom housing adaptations and airflow recalibration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sustainable Air Filter Market |
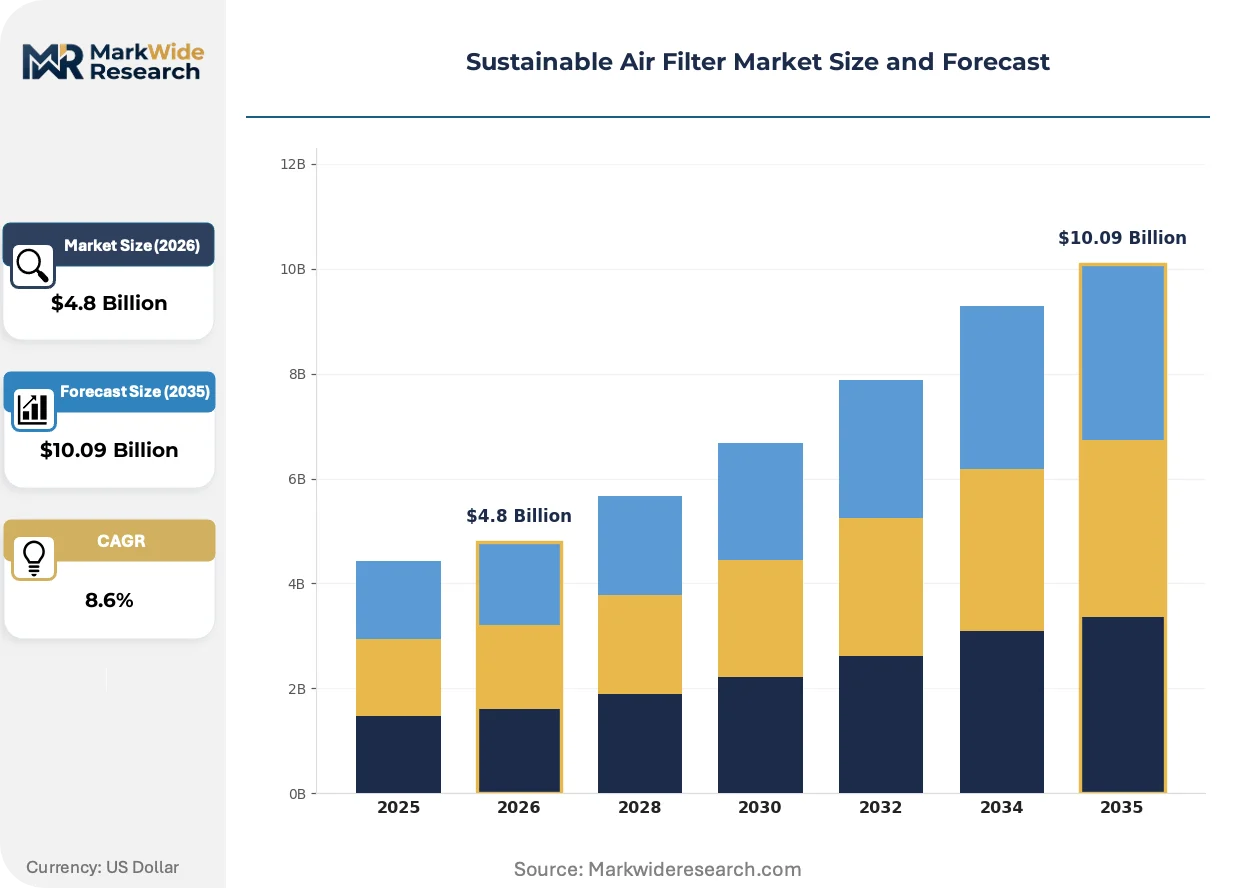
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.09 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HEPA Filters, Electrostatic Filters, Activated Carbon Filters, Photocatalytic Filters, Bio-based Filters Technology: Nanofiber Membranes, Electrospinning, Activated Carbon Adsorption, UV Photocatalysis, Biodegradable Materials Application: Residential HVAC, Commercial Buildings, Clean Rooms, Public Transportation, Data Centers End User: Office Complexes, Educational Institutions, Healthcare Clinics, Hospitality Venues, Manufacturing Facilities |
| Companies Covered | AAF International, Honeywell International, Camfil, Donaldson Company, 3M Company, Freudenberg Filtration Technologies, Mann+Hummel, IQAir, Blade Air, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sustainable Air Filter Market Trends and Innovations
Material science advances and regulatory chemistry bans are converging to reshape filter media composition, with nanofiber architectures and bio-based substrates displacing legacy synthetic constructions.
Electrospun nanofiber membranes are hybridizing cellulose and polylactic acid substrates to capture sub-micron particulate while maintaining biodegradability credentials. Pharmaceutical manufacturers in Switzerland and Singapore are piloting these constructions for clean room deployment. The technology is hybridizing performance tiers, compressing the gap between standard and premium filter categories.
REACH authorization procedures and the EU F-Gas Regulation are eliminating perfluorinated compounds from membrane manufacturing processes. Industrial filter producers must reformulate polymer inputs or forfeit CE marking eligibility for healthcare and hospitality applications. German and Japanese healthcare procurement offices are prioritizing suppliers with verified synthetic-free chemistry chains.
Facility engineering teams are consolidating vendor relationships around specification-driven direct contracts, displacing traditional HVAC distributor intermediaries. Data center operators and pharmaceutical manufacturers are negotiating multi-year filter service agreements with media producers directly. This channel compression is most visible in Northern European markets where procurement teams hold ISO 14001 environmental management certifications.
Sustainable Air Filter Market Segmentation
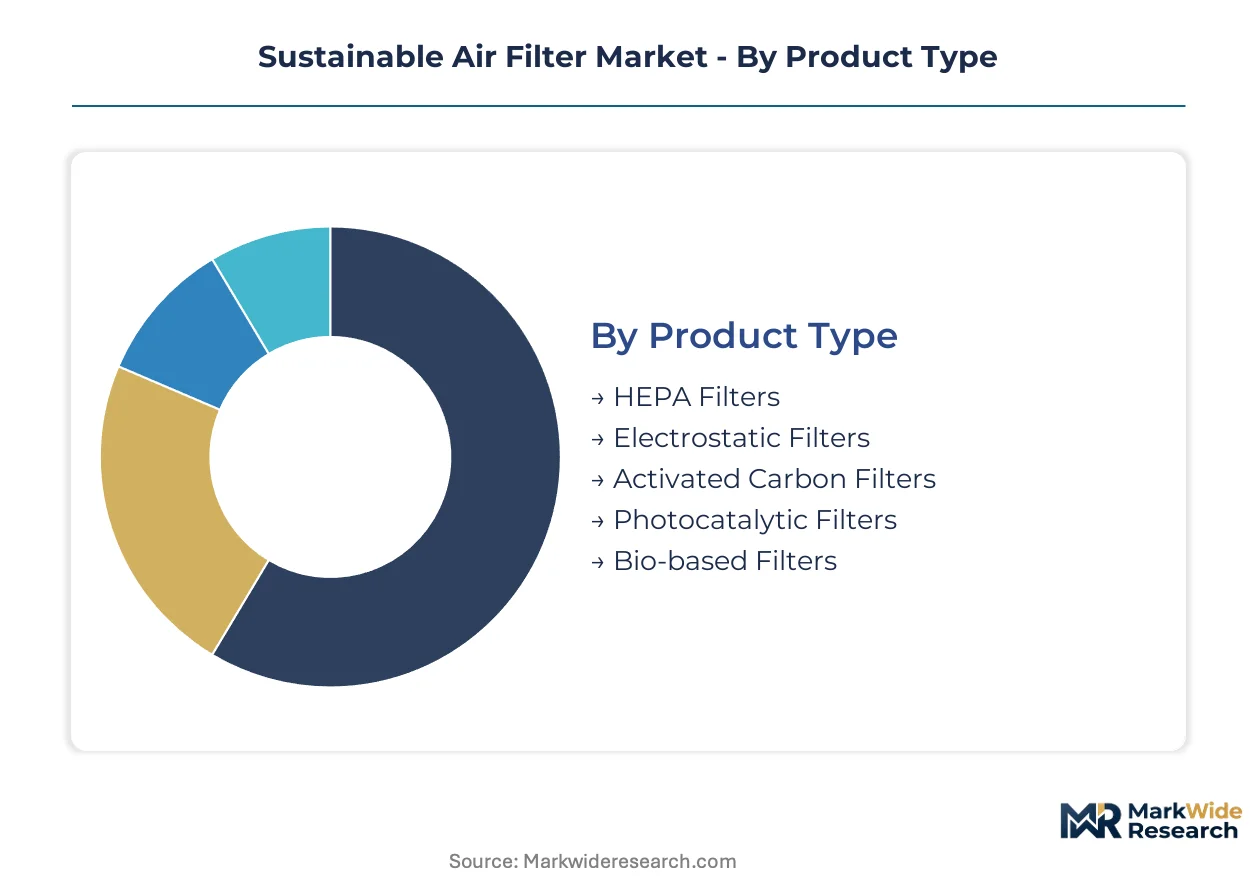
Sustainable air filter segmentation reveals how technical specifications, deployment environments, and procurement priorities fragment demand across divergent performance tiers and compliance thresholds. Understanding these divisions illuminates where bio-based substrates compete against legacy synthetics and which end-use verticals drive specification upgrades.
Product Type:
The use-case spectrum spans critical containment environments demanding MERV 20 retention through ambient air quality management in commercial spaces.
- HEPA Filters:Engineered from glass fiber or advanced nanofiber composites to achieve particulate retention thresholds between MERV 17-20. Healthcare clinics across Germany and Switzerland anchor procurement volume for pharmaceutical containment and surgical suite applications where synthetic chemistry elimination faces strict REACH scrutiny.
- Electrostatic Filters:Deploy charged media to capture particulate matter with reduced pressure drop versus mechanical alternatives. Data center operators in Singapore prioritize these designs for cooling optimization, trading absolute retention efficiency for energy savings in non-critical air handling zones.
- Activated Carbon Filters:Adsorbent media targeting gaseous contaminants and volatile organic compounds in hospitality venues and commercial buildings.
- Photocatalytic Filters:UV-activated titanium dioxide coatings for microbial reduction in public transportation systems and high-occupancy facilities.
- Bio-based Filters:Cellulose and polylactic acid substrates designed for circular end-of-life disposal, gaining traction among educational institutions with landfill reduction mandates.
The dominant share belongs to HEPA Filters, while Bio-based Filters are closing the gap fastest.
Technology:
Cost tier differentiation separates premium nanofiber architectures from commodity biodegradable alternatives competing on circular credentials rather than performance parity.
- Nanofiber Membranes:Sub-micron fiber diameters create high surface area capture media with minimal airflow resistance. Swiss pharmaceutical manufacturers pilot these constructions for clean room deployment where synthetic-free chemistry chains satisfy procurement verification requirements.
- Electrospinning:Manufacturing process enabling hybrid cellulose-polylactic acid substrates that bridge biodegradability with particulate retention approaching synthetic equivalents.
- Activated Carbon Adsorption:Mature technology for molecular contaminant removal in commercial building retrofits.
- UV Photocatalysis:Oxidative air treatment systems integrated into transportation infrastructure and healthcare ventilation.
- Biodegradable Materials:End-of-life certified substrates responding to EU Ecodesign Directive procurement preferences in Northern European public sector contracts.
Nanofiber Membranes command premium positioning, with Electrospinning gaining share fastest as manufacturing scale reduces unit economics.
Application:
Volume concentration tracks regulatory intensity, with compliance-heavy environments outpacing discretionary upgrade cycles in consumer-facing segments.
- Clean Rooms:Controlled environments demanding continuous particulate monitoring and validated filtration performance. Pharmaceutical manufacturing corridors in Switzerland and Singapore drive specification-grade procurement with multi-year service agreements replacing spot purchasing.
- Data Centers:Hyperscale cooling infrastructure where pressure-drop optimization translates directly to energy expenditure. Operators negotiate direct contracts with media producers, bypassing traditional HVAC distribution channels for specification-driven sourcing.
- Residential HVAC:Replacement market cycling on consumer awareness and seasonal maintenance patterns.
- Commercial Buildings:EPA ENERGY STAR and OSHA guideline compliance driving verification requirements for US office complexes.
- Public Transportation:Fleet-wide air quality upgrades in municipal bus and rail systems.
Clean Rooms retain the dominant position, while Data Centers are expanding most quickly through direct procurement channel migration.
End User:
Customer type fragmentation reflects divergent procurement authority structures, from centralized facilities management in corporate offices to decentralized purchasing in educational systems.
- Healthcare Clinics:German and Japanese procurement offices prioritize low-emission filtration systems with verified synthetic-free chemistry documentation. CE marking under MDR frameworks and REACH compliance shape supplier qualification requirements.
- Educational Institutions:Universities and school districts adopting circular procurement policies favoring bio-based filters with biodegradable certification. Budget constraints limit penetration of premium nanofiber alternatives despite sustainability preferences.
- Office Complexes:Corporate real estate portfolios standardizing on ENERGY STAR verified products for US federal lease compliance.
- Hospitality Venues:Hotel chains responding to guest-facing air quality marketing and regional ventilation codes.
- Manufacturing Facilities:Industrial process environments balancing occupational exposure limits with production uptime requirements.
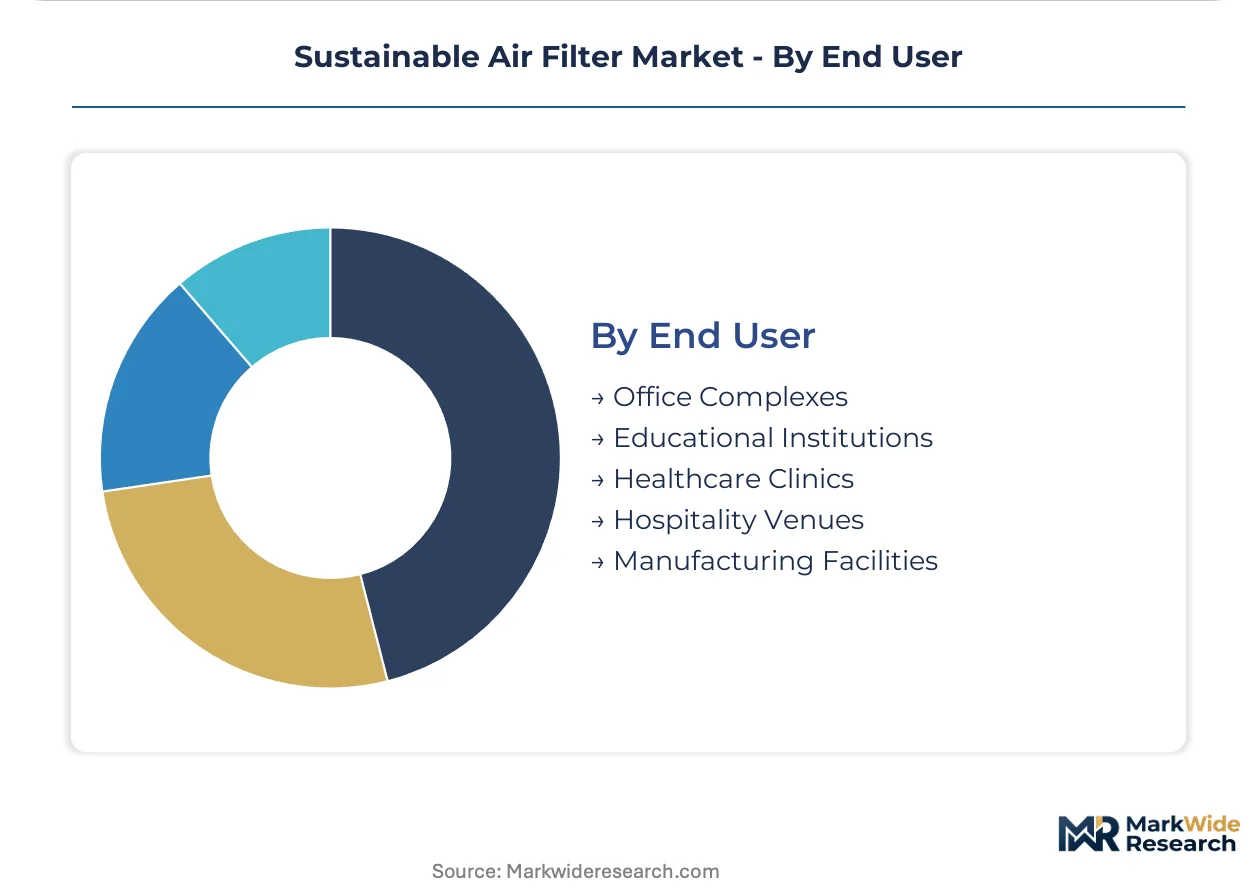
Healthcare Clinics dominate procurement value, with Educational Institutions climbing the fastest on circular policy adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's chemical processing infrastructure anchors European supply chains for bio-based polymer feedstocks used in sustainable filter media manufacturing.
Germany
Healthcare clinics in Berlin and Munich are expanding procurement of low-emission filtration systems for surgical suites. REACH compliance and the EU F-Gas Regulation compel manufacturers to eliminate synthetic refrigerant-linked chemistries from filter media. The pharmaceutical manufacturing corridor in Baden-Württemberg drives clean room installation volume with multi-year service agreements.
Switzerland
Pharmaceutical manufacturers in Basel cluster demand specification-grade HEPA filters with verified synthetic-free chemistry chains. Swissmedic oversight and MDR framework CE marking requirements shape supplier qualification protocols. The Greater Zurich Area anchors nanofiber membrane pilot programs for clean room deployment.
Singapore
Data center operators negotiate direct contracts with media producers for cooling optimization, bypassing traditional HVAC distribution channels. The country's national environmental regulator enforces stringent indoor air quality guidelines for commercial buildings. The Jurong Innovation District concentrates electrostatic filter deployment for hyperscale infrastructure.
Japan
Healthcare procurement offices in Tokyo and Osaka prioritize suppliers with documented low-emission filtration credentials. METI guidelines and JIS standards tighten performance verification requirements for filters deployed in manufacturing facilities. The Kansai region anchors clean room installations serving semiconductor and pharmaceutical production.
United States
EPA ENERGY STAR specifications and OSHA indoor air quality guidelines drive verification requirements for filters in office complexes and manufacturing facilities. Federal procurement alignment favors certified suppliers for US government lease compliance. The Research Triangle Park in North Carolina concentrates pharmaceutical clean room demand.
Sustainable Air Filter Market Competitive Landscape
On the supply side, the industry is consolidating around specification-driven direct contracts that bypass traditional HVAC distributor networks. Tiered competitive positioning separates premium nanofiber membrane producers from commodity biodegradable substrate fabricators. Three archetypes dominate: automotive filtration specialists pivoting into industrial clean rooms, vertically integrated media manufacturers controlling polymer-to-pleated-element supply chains, and high-durability pleated design houses targeting data center replacement interval extension. M&A activity concentrates on nanofiber membrane production assets, while strategic partnerships link bio-based substrate developers with pharmaceutical procurement networks.
Within the premium-tier vector, Camfil and Mann+Hummel occupy positions exemplifying divergent integration strategies. Camfil represents the archetype of upstream control over nanofiber membrane supply from polymer inputs through finished pleated elements. Mann+Hummel anchors the automotive-to-industrial pivot archetype, leveraging captive filtration expertise to secure European clean room contracts. Donaldson Company sits within the high-durability specialization tier, with its pleated design focus aligning with data center operator procurement priorities for extended replacement intervals and pressure-drop energy savings.
| Leading Market Players |
|---|
| AAF International |
| Honeywell International |
| Camfil |
| Donaldson Company |
| 3M Company |
| Freudenberg Filtration Technologies |
| Mann+Hummel |
| IQAir |
| Blade Air |
| Others |
Pricing and Supply Chain Analysis
The Rhine-Alpine freight corridor's volatile container rates transmit cost pressure through European nanofiber membrane supply chains, compressing margins for media producers while enabling premium pricing power for vertically integrated filter manufacturers serving German pharmaceutical clean rooms.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates sustainable air filter procurement, with nanofiber HEPA constructions commanding 40-60% premiums over cellulose-based alternatives due to REACH compliance verification and Swissmedic certification requirements. Price differentiation hinges on biodegradability certification tier and direct-to-facility contract volume, with data center operators negotiating multi-year service agreements that soften unit economics. Cost compression in bio-based substrate tiers is intensifying because polylactic acid resin supply fluctuates with agricultural commodity cycles. Educational institutions exhibit highest price sensitivity, while Swiss pharmaceutical manufacturers prioritize synthetic-free chemistry documentation over procurement cost.
Supply Chain Analysis
EU dual-use export controls on electrospinning equipment limit technology transfer to non-member manufacturing bases, concentrating nanofiber membrane production in German and Swiss polymer processing hubs. Raw material flows draw from Swedish cellulose pulp mills, Thai polylactic acid resin plants, and Belgian specialty chemical additive suppliers. Single-source vulnerability permeates electrospun biopolymer substrate supply, with Port of Rotterdam congestion periodically disrupting feedstock delivery to Northern European filter pleating facilities. Distribution runs through specification-driven direct contracts that displace traditional HVAC distributor networks, particularly for clean room and data center end users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Filter-as-a-service contracts with predictive replacement scheduling and waste-stream management are expanding faster than standalone hardware sales, creating recurring revenue pools that justify upfront media technology investments.
For Market Incumbents: Build certification moats around REACH-compliant synthetic-free chemistry chains to defend against Asian membrane producers seeking European market entry. Deepen backward integration into polylactic acid resin compounding to buffer agricultural commodity volatility. Secure multi-year service agreements with Swiss pharmaceutical manufacturers before MDR framework CE marking deadlines tighten supplier qualification protocols. For New Entrants and Emerging Players: Japanese healthcare procurement offices represent underpenetrated demand for low-emission filtration systems with METI-aligned documentation. Target educational institutions in Northern Europe with biodegradable-certified product lines priced below nanofiber alternatives. Pursue direct-to-facility channel partnerships with ISO 14001-certified facility management firms to bypass established HVAC distribution gatekeepers. For Investors and Strategic Acquirers: Carve-out targets emerge from automotive filtration divisions of diversified industrial conglomerates seeking portfolio simplification. Five-to-ten-year viability favors manufacturers with captive electrospinning capabilities and pharmaceutical clean room reference contracts. Monitor EU F-Gas Regulation enforcement intensity as inflection indicator for bio-based substrate demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Biopolymer Resin | Captive polylactic acid supply insulates margin structures from agricultural commodity swings. |
| Direct-to-Facility Channel Establishment | Bypassing HVAC distributors captures specification premium in data center procurement. |
| Biodegradability Certification Investment | EU Ecodesign Directive alignment unlocks Northern European public sector contract access. |
| Clean Room Service Agreement Expansion | Multi-year pharmaceutical contracts replace spot purchasing with predictable replacement revenue. |
| Nanofiber Membrane Capacity Addition | Electrospinning scale-up bridges performance gap between bio-based and synthetic HEPA constructions. |
Research Methodology
Operator-level perspectives from clean room facility managers, pharmaceutical procurement directors, data center cooling engineers, HVAC contractor specification writers, and biodegradability certification auditors anchored the qualitative base. Secondary validation drew from ECHA REACH registration databases, EU F-Gas Regulation implementation reports, SEC filings of listed filtration companies, and Swissmedic MDR guidance documents. Bottom-up demand modeling triangulated against top-down market sizing from trade flow analysis.
Scenario-bracketing around regulatory enforcement intensity and bio-based substrate performance evolution shaped the analytical framework across the analysis window. Segmentation dimensions included filter technology tier, end-use application criticality, procurement channel structure, and regional compliance regime cluster. CAGRs derived from installed base growth rates, replacement cycle compression, and specification upgrade penetration curves, with pharmaceutical manufacturing capacity expansion and hyperscale data center buildout serving as volume anchors.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Asian membrane producers or accelerated EU biodegradability mandate timelines would shift outcomes. Material shifts in cellulose pulp pricing volatility or electrospinning equipment export control enforcement would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Air Quality Control Systems
Oxygen Filters Market
Air Quality Control Systems
Europe Nitrogen Oxide Control Systems Market
Air Quality Control Systems
Asia-Pacific Indoor Air Purification Market
Air Quality Control Systems
Air Scrubber Market
Air Quality Control Systems
US Air Quality Analyzers Market
Air Quality Control Systems
Environmental Control System (ECS) Market
Air Quality Control Systems
UV Air Purifiers Market
Air Quality Control Systems
Ozone Generation Market
Air Quality Control Systems
Middle-East and Africa Industrial Air Quality Control Systems Market
Air Quality Control Systems
North America Industrial Air Quality Control Systems Market
Air Quality Control Systems
Europe Industrial Air Quality Control Systems Market
Air Quality Control Systems
Anti-Pollution Mask Market
Air Quality Control Systems
Air Pollution Control Equipment Market
Air Quality Control Systems
Southeast Asia Air Purifier Market
Air Quality Control Systems
Singapore Air Purifier Market
Air Quality Control Systems
Indoor Air Purification Market