
 Artificial Green Wall Market | 2026-2036
Artificial Green Wall Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Green Wall Market Insights
Aftermarket service revenue from moss preservation and panel replacement is narrowing as manufacturers shift toward subscription-based maintenance contracts. Vistafolia leverages its proprietary UV-stabilized polyethylene formulation to command premium positioning in Middle Eastern hospitality projects. National Tree Company anchors the North American mass-retail channel through standardized ready-made kits. Commercial Silk differentiates by offering Class A fire-rated foliage systems that meet stringent building code requirements for high-rise installations.
Artificial green walls comprise engineered plant replicas mounted on structural substrates, typically utilizing UV-resistant polyethylene or polyurethane foliage attached to galvanized steel or aluminum frames with integrated irrigation-compatible drainage layers, serving primarily to deliver biophilic aesthetics without biological maintenance burdens. Modular panels capture the dominant share of commercial specification due to faster on-site assembly and lower skilled-labor requirements than customized installations. Synthetic fabrics lead material demand for interior applications where tactile authenticity drives selection, while metal substrate systems accelerate fastest in exterior deployments requiring wind-load compliance.
The EPA regulates VOC emissions from synthetic materials under TSCA Title VI, while California's Department of Public Health enforces CDPH Section 01350 for indoor air quality in commercial spaces, and the EU Green Deal's circular economy action plan pressures producers toward recyclable polymer streams. These frameworks elevate compliance costs for budget-tier imports while rewarding manufacturers with certified material traceability. Stakeholders must weigh fire-rating jurisdiction against botanical realism trade-offs when specifying systems for mixed-occupancy buildings.
Market Dynamics
Biophilic design mandates in commercial construction are compressing specification cycles while fire-rating compliance costs bifurcate the vendor base between certified systems and commodity imports.
Growth Catalysts
- LEED v4.1 Certification Pull:North American developers pursuing WELL Building Standard points specify low-VOC polyethylene foliage systems to satisfy indoor air quality credits.
- Hospitality Procurement Concentration:Dubai and Singapore hotel operators drive demand for UV-stabilized exterior panels that withstand desert heat and tropical humidity without degradation.
- Modular Installation Economics:Faster on-site assembly of standardized panel systems reduces skilled labor requirements in urban mixed-use developments across the United States, United Kingdom, and Australia.
Market Restraints
- Petrochemical Input Volatility:Polyethylene and polyurethane resin prices fluctuate with crude oil indices, squeezing margin on mid-tier synthetic foliage production.
- Fire-Rating Jurisdiction Complexity:California's Department of Public Health enforces CDPH Section 01350 for indoor air quality while local fire codes demand Class A rated materials, creating compliance cost stacking.
- Living Wall Substitution:Irrigated moss and preserved plant systems capture premium interior projects where maintenance budgets permit biological alternatives.
Strategic Opportunities
- Subscription Maintenance Contracts:Manufacturers pivot from episodic panel replacement to recurring service revenue models in commercial real estate portfolios.
- EU Green Deal Alignment:Recyclable polymer streams and circular economy action plan compliance open specification access to European public sector procurement.
- Retail Channel Expansion:Ready-made kit formats penetrate North American mass-market home improvement and e-commerce channels previously served only by custom commercial installers.
Industry Challenges
- Fire-Rating Botanical Realism Trade-off:Class A rated materials often sacrifice tactile authenticity, forcing specification teams to balance code compliance with design intent.
- Installation Skill Fragmentation:Modular systems reduce labor requirements but create dependency on certified installer networks that remain geographically sparse outside major metropolitan construction markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Green Wall Market |
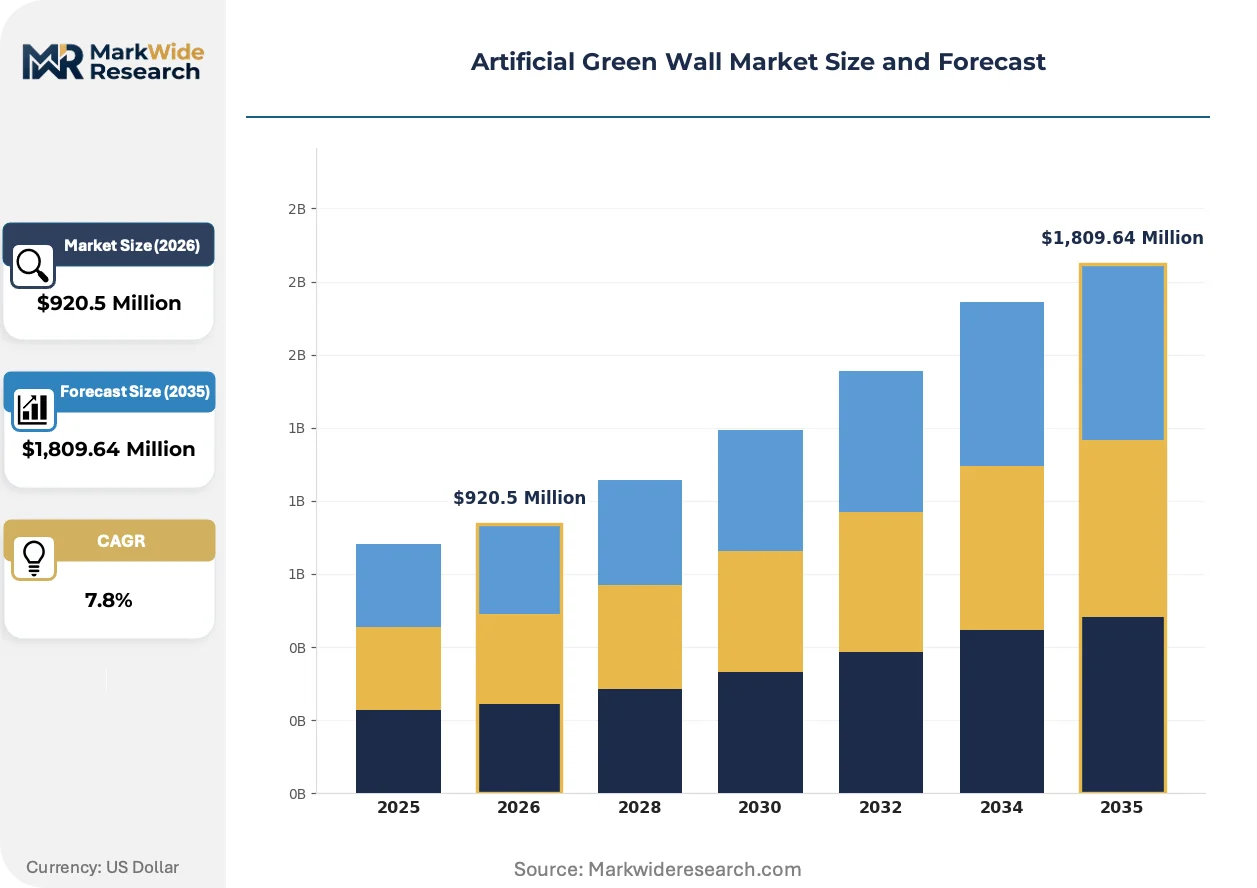
| Market Size in 2026 | $920.5 Million |
| Market Size in 2035 | $1,809.64 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical Gardens, Modular Panels, Ready-Made Kits, Customized Installations Material: Synthetic Fabrics, Plastic, Foam, Metal Application: Residential Spaces, Commercial Buildings, Hotels, Public Spaces Installation Type: Wall-Mounted, Freestanding, Indoor, Outdoor |
| Companies Covered | Vistafolia, National Tree Company, Commercial Silk, Green Wallscapes, Silk Plants Direct, EdenVert, Nearly Natural Inc, Garden on the Wall, Artificial Plants Unlimited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Green Wall Market Trends and Innovations
Digital specification tools and material science advances are compressing the gap between synthetic and living systems while regulatory pressure on indoor air quality accelerates certified product differentiation.
Photorealistic 3D scanning and molding technology is virtualizing the surface texture and color variation of natural foliage. High-end hospitality designers in Dubai and Singapore specify these advanced polyethylene replicas for exterior installations where UV degradation previously limited product lifespan. The technology is virtualizing the traditional compromise between durability and aesthetic authenticity.
REACH regulation in Europe and EPA TSCA Title VI in the United States impose escalating compliance burdens on volatile organic compound emissions from synthetic materials. Manufacturers with certified material traceability capture specification share while budget-tier imports face market access restrictions. Interior commercial projects in California and Germany now require CDPH Section 01350 or equivalent documentation as a baseline qualification.
Building operators increasingly bundle maintenance services into long-term facility management contracts rather than purchasing panels outright. Third-party service providers and original manufacturers compete for recurring revenue streams in commercial real estate portfolios. This procurement evolution is most advanced in United States and United Kingdom urban office markets where landlord-tenant service agreements dominate.
Artificial Green Wall Market Segmentation
Segmentation in artificial green walls reveals how procurement cycles, compliance burdens, and installation logistics fragment demand across building types and material specifications. Understanding these divisions clarifies where specification cycles compress and where margin pools concentrate.
Product Type:
Modular panels turn inventory fastest through standardized production, while customized installations stretch project timelines across months of design iteration.
- Modular Panels:Pre-engineered grid systems with galvanized steel frames and clip-in foliage mats enable rapid on-site assembly. Hospitality developers in Dubai and Singapore specify these for phased hotel renovations where downtime minimization drives procurement. The format reduces skilled labor requirements and accelerates project completion timelines.
- Customized Installations:Architect-specific designs with irregular geometries and bespoke botanical arrangements command extended production cycles. High-end commercial lobbies in London and New York commission these for brand differentiation, accepting longer lead times for unique aesthetic outcomes.
- Vertical Gardens:Self-contained column or freestanding garden structures serve spatial zoning functions in open-plan offices and retail atriums.
- Ready-Made Kits:Consumer-oriented packaged systems target residential DIY installation through mass-retail channels.
Modular panels dominate installed base. Customized installations are where expansion concentrates.
Material:
Cost tiers stratify sharply between commodity polymers and certified metal substrates, with fire-rating compliance acting as the primary price escalator.
- Synthetic Fabrics:Woven polyethylene and polyurethane textiles deliver tactile authenticity for interior applications where occupant touch proximity matters. LEED v4.1 projects in California and New York specify low-VOC certified variants to satisfy indoor air quality credits. The material leads interior specification but degrades under UV exposure.
- Metal:Aluminum and galvanized steel substrate systems provide structural integrity for exterior wind-load compliance. Australian coastal developments and Middle Eastern high-rises specify these for durability in extreme climate exposure, accepting premium pricing for longevity.
- Plastic:Injection-molded polyethylene foliage components serve budget-tier commercial and residential applications where cost minimization outweighs longevity requirements.
- Foam:Polyurethane foam substrates enable lightweight installations on structural capacity-constrained walls in older building retrofits.
Synthetic fabrics capture volume leadership in interior segments. Metal substrates are climbing the fastest in exterior specification.
Application:
Customer type determines maintenance burden tolerance and upfront capital allocation, bifurcating demand between service-contracted commercial portfolios and one-time residential purchases.
- Commercial Buildings:Office landlords and corporate headquarters specify artificial systems to satisfy biophilic design mandates while eliminating irrigation infrastructure. WELL Building Standard pursuit in United States and United Kingdom urban markets drives low-VOC material specification. Long-term facility management contracts increasingly bundle panel maintenance into service agreements.
- Hotels:Hospitality operators in climate-stressed geographies prioritize UV-stabilized exterior panels for lobby entrances, pool decks, and rooftop venues. Dubai and Singapore procurement teams demand fire-rated systems that meet local building codes without sacrificing visual impact.
- Residential Spaces:Homeowners and multifamily developers purchase ready-made kits or commission modest custom installations for private outdoor living areas.
- Public Spaces:Municipal and transit authorities deploy vandal-resistant synthetic foliage in airports, subway stations, and government buildings where maintenance access is constrained.
Commercial buildings anchor revenue concentration. Hotels are gaining share fastest in exterior specification.
Installation Type:
Geography and building vintage dictate structural attachment methods, with wall-mounted systems requiring substrate evaluation and freestanding units demanding floor loading analysis.
- Wall-Mounted:Direct-to-substrate attachment systems dominate retrofit applications where floor space preservation matters. United Kingdom and Australian urban mixed-use developments specify these for atrium and corridor treatments where spatial efficiency is paramount.
- Outdoor:Weather-rated systems with drainage layers and UV stabilization serve exterior facades, rooftop venues, and climate-exposed hospitality installations. REACH and EPA TSCA Title VI compliance documentation increasingly gates specification access.
- Freestanding:Self-supporting partition and column structures enable spatial division without permanent building modification.
- Indoor:Climate-controlled environment systems prioritize low-VOC emissions and fire-rating compliance over weather resistance.
Wall-mounted configurations hold the largest installed base. Outdoor installations are where specification activity is intensifying.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement patterns diverge sharply by climate stress and certification stringency. Hospitality developers in arid and tropical zones prioritize UV-stabilized exterior systems, while temperate-zone commercial builders emphasize indoor air quality compliance and fire ratings.
United States
Commercial real estate portfolios in New York and Los Angeles specify low-VOC polyethylene foliage to secure WELL Building Standard points. EPA TSCA Title VI regulates synthetic material emissions, elevating compliance costs for imported panels. Certified installer networks cluster in Chicago and Atlanta, serving retrofit demand across aging office stock.
United Arab Emirates
Dubai hotel operators drive procurement of fire-rated exterior panels for rooftop venues and pool decks exposed to desert heat. MOHAP enforces building material safety standards that intersect with local fire codes. Procurement teams in Abu Dhabi specify UV-stabilized systems from hospitality-focused fabricators for phased resort renovations.
Germany
Office landlords in Frankfurt and Munich specify recyclable polymer substrates to align with EU Green Deal circular economy requirements. REACH regulation imposes material traceability burdens that filter out budget-tier imports. Industrial clusters in North Rhine-Westphalia host specification consultants advising on CDPH-equivalent indoor air quality documentation.
Australia
Coastal mixed-use developments in Sydney and Melbourne specify metal substrate systems for wind-load compliance in salt-air exposure. State-level building codes in New South Wales and Victoria mandate fire-rating documentation for high-rise installations. Brisbane hospitality projects increasingly bundle maintenance services into long-term facility contracts.
Singapore
Tropical humidity and strict urban greening mandates concentrate demand for exterior-grade synthetic foliage in Marina Bay hospitality clusters. The Building and Construction Authority enforces fire safety standards that shape specification toward Class A rated materials. Procurement teams prioritize modular panel formats to minimize installation downtime in operating hotels.
Artificial Green Wall Market Competitive Landscape
Capability concentration sits with certified-system specialists; scale advantage sits with mass-market kit distributors. The vendor base stratifies across three tiers: premium-grade hospitality suppliers, mid-tier commercial specifiers, and retail-channel commodity providers. Fire-rating certification and UV stabilization IP separate the top tier from price-driven competitors. M&A activity targets installer network consolidation, while portfolio diversification pushes manufacturers toward subscription service models.
Within the premium-tier segment, Vistafolia and Commercial Silk exemplify divergent specialization paths—one leveraging proprietary material formulations for climate-stressed exterior applications, the other anchoring Class A fire-rated specification for high-rise compliance. National Tree Company occupies a position at the scale-driven end, standardizing ready-made kits for North American mass-retail penetration. These three represent the archetype spectrum: formulation-led, compliance-led, and distribution-led competitive positioning.
| Leading Market Players |
|---|
| Vistafolia |
| National Tree Company |
| Commercial Silk |
| Green Wallscapes |
| Silk Plants Direct |
| EdenVert |
| Nearly Natural Inc |
| Garden on the Wall |
| Artificial Plants Unlimited |
| Others |
Pricing and Supply Chain Analysis
Chinese polyethylene resin suppliers anchor the upstream cost structure, concentrating margin capture with UV-stabilization formulators in the United Arab Emirates and fire-rating certification specialists in Germany who command premium positioning in hospitality procurement.
Pricing Analysis
Long-term offtake agreements dominate hospitality and commercial real estate procurement, locking in volume commitments for modular panel systems over multi-year facility management contracts. Three-tier pricing structure across premium, standard, and economy levels separates Class A fire-rated metal substrate systems from mid-tier synthetic fabric installations and commodity plastic kits. Cost compression in the mid-tier is intensifying because petrochemical input volatility squeezes polyethylene and polyurethane resin margins. Budget-tier residential buyers exhibit highest price sensitivity, while Dubai hotel operators and WELL-certified office landlords absorb premium pricing for compliance-grade specifications.
Supply Chain Analysis
Export-control regimes on advanced polymer stabilization additives limit technology flows from German chemical specialists to unlicensed Asian fabricators, constraining fire-rating performance in budget-tier imports. Manufacturing concentrates in China, India, and Vietnam for injection-molded foliage components, while Germany and the United States host specialized UV-stabilization and fire-retardant formulation. Supply chains draw from crude oil derivatives, galvanized steel, and aluminum substrate feedstocks. Single-source vulnerability sits with Chinese polyethylene resin supply for cost-competitive tiers. Distribution runs through certified installer networks in major metropolitan construction markets, direct commercial specification for hospitality projects, and mass-retail channels for residential kits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biophilic design mandates are disrupting commercial construction procurement, with REACH and EPA TSCA Title VI compliance creating irreversible specification barriers that favor certified-system specialists over commodity importers.
For Market Incumbents: Insulate premium positioning by deepening captive supply of UV-stabilized polyethylene formulations and acquiring certified installer networks in underserviced secondary metros. Vistafolia's proprietary material science and Commercial Silk's fire-rating specialization demonstrate how formulation IP and compliance certification defend against price-driven import competition. Subscription maintenance contract bundling locks in recurring revenue against episodic replacement cycles.
For New Entrants and Emerging Players: Pursue white-space opportunity in Australian coastal wind-load applications and German recyclable polymer compliance segments where incumbent coverage remains thin. The EU Green Deal circular economy action plan opens specification access for traceable material streams in Frankfurt and Munich office markets. A direct-to-facility-manager digital specification platform bypasses traditional architect-channel gatekeeping.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated specialists with captive UV-stabilization IP and certified installer network density across the United States and United Kingdom urban corridors. Long-term viability over the coming decade hinges on regulatory compliance moats deepening as REACH and EPA frameworks tighten. Watch for CDPH Section 01350 equivalent documentation becoming baseline qualification in additional state jurisdictions as the inflection signal for accelerated certified-product consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Subscription Maintenance Contract Rollout | Recurring revenue models capture facility management budgets in United States commercial real estate portfolios. |
| Fire-Rating Certification Investment | Class A rated systems unlock high-rise specification in Singapore and Dubai hospitality clusters. |
| Recyclable Polymer Stream Development | EU Green Deal alignment opens European public sector procurement in Germany and France. |
| Certified Installer Network Expansion | Geographic density in secondary metros reduces project completion timelines for modular panel deployment. |
| UV-Stabilization Formulation IP | Proprietary polyethylene chemistry extends product lifespan in Middle Eastern desert heat exposure. |
Research Methodology
Cross-validation between primary interviews with specification consultants, hospitality procurement directors, and commercial real estate facility managers anchors the qualitative findings against secondary validation from EPA TSCA Title VI filings, REACH substance registration databases, and WELL Building Standard project directories. Bottom-up triangulation across installer network capacity assessments and top-down reconciliation with construction spending data by building type ensures dimensional consistency. Trade data from customs records and SEC 10-K disclosures of publicly listed building materials suppliers provide additional calibration points.
Calibration against historical specification cycle timing and regulatory implementation trajectories shapes the projection framework across the analysis window. Segmentation dimensions modeled include product format, material substrate, installation type, end-use building category, and regional certification stringency tier. CAGRs derive from fitted growth curves anchored to disclosed project pipelines and facility management contract renewal rates. Fire-code adoption timelines and biophilic design mandate rollout schedules serve as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in commercial construction lending rates and petrochemical feedstock indices would shift the trajectory. Forecasts reflect assumptions about regulatory enforcement continuity and certification standard stability. Material shifts in REACH substance restriction scope or EPA indoor air quality rulemaking would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Green Building Materials
North America Green Buildings Market
Green Building Materials
Eco Flooring Market
Green Building Materials
Green Silica Market
Green Building Materials
United States Green Cement Market
Green Building Materials
Asia Pacific Green Cement Market
Green Building Materials
Energy Efficient Window and Door Market
Green Building Materials
Global Green Walls Market
Green Building Materials
Eco-Friendly Bitumen Market
Green Building Materials
Green Building Market
Green Building Materials
Green Building Materials Market
Green Building Materials
Europe Green Cement Market
Green Building Materials
Green Concrete Market
Green Building Materials
Green Rebar Market
Green Building Materials
Green Coatings Market
Green Building Materials
China Green Building Materials Market
Green Building Materials
Solar Windows Market