
 Women Probiotic Market | 2026-2036
Women Probiotic Market Size, Share, and Industry Trends Forecast 2026-2036
Women Probiotic Market Insights
China's probiotic manufacturing corridor is reconfiguring supply dynamics for women's health formulations across Asia-Pacific. Danone leverages its European dairy heritage to anchor premium positioning in clinically validated strains. Nestlé Health Science competes through pharmaceutical-grade manufacturing partnerships that extend its reach into practitioner channels. Yakult Honsha sustains dominance in liquid delivery formats through decades of consumer habit formation in East Asian markets.
Women probiotics comprise live microbial preparations, typically delivering colony-forming units ranging from one billion to fifty billion per dose, formulated to colonize the urogenital and gastrointestinal tracts for therapeutic or prophylactic benefit. These preparations serve commercial purposes spanning digestive regularity, vaginal microbiome restoration, and immune modulation through strain-specific mechanisms. Capsules and tablets occupy the core margin pool due to stability advantages and pharmacy channel preference, while gummies represent the fastest-growing format as taste-masked delivery attracts younger adult women. Vaginal health applications command premium pricing relative to general digestive support, reflecting both clinical specificity and higher regulatory scrutiny for urogenital claims.
FDA oversight of dietary supplement labeling, EFSA health claim authorization processes, and WHO guidelines on probiotic quality standards collectively elevate barriers to market entry and reward substantiated formulation science. EMA-aligned markets enforce stricter strain documentation than jurisdictions with self-affirmed GRAS frameworks, fragmenting competitive intensity by geography. Stakeholders must monitor evolving definitions of live culture viability thresholds as regulators reconcile traditional CFU metrics with emerging metabolomic and transcriptomic quality indicators.
Market Dynamics
Strain-specific labeling mandates from FDA and EFSA are compressing formulation pipelines and forcing manufacturers to rebuild quality documentation from genomic identification through shelf-life validation, privileging laboratories with deep strain banking capabilities.
Growth Catalysts
- Vaginal microbiome restoration protocols:OB-GYN practices in the United States are integrating Lactobacillus crispatus and L. rhamnosus GR-1 into prenatal care standards, creating institutional pull for clinically documented formulations.
- EFSA Article 13.1 health claim pathways:The authorization framework for immune function and digestive health claims rewards substantiated strain dossiers, accelerating investment in human intervention trials across European markets.
- Direct-to-consumer subscription models:Digital health platforms enable continuous microbiome monitoring paired with personalized probiotic regimens, locking in recurring revenue streams for precision formulation providers.
Market Restraints
- Freeze-drying input volatility:Specialized cryoprotectant sugars and pharmaceutical-grade excipients face supply pressure from competing demand in mRNA vaccine stabilization, elevating unit economics for CFU preservation.
- Single-source strain dependency:Dominant culture collections in France and Denmark control access to well-documented urogenital isolates, concentrating licensing leverage with heritage microbiology institutes.
- WHO viability threshold ambiguity:Pending revisions to live culture enumeration standards create regulatory uncertainty for products targeting emerging metabolomic quality indicators.
Strategic Opportunities
- Perimenopausal urogenital applications:Estrogen decline disrupts vaginal Lactobacillus dominance, opening formulation white space for hormone-independent microbiome support in women aged 45-55.
- Pharmacy-practitioner channel convergence:Compounding pharmacies and integrative medicine clinics seek private-label partnerships with strain-traceable manufacturers, bypassing mass retail margin compression.
- CSRD-aligned sustainability disclosure:European corporate sustainability reporting mandates create competitive differentiation for fermentation facilities with verified carbon footprint reduction and circular water systems.
Industry Challenges
- Multi-omics integration talent scarcity:Strain selection now requires computational biology expertise spanning metagenomic analysis and host transcriptomics, functions concentrated in academic rather than commercial laboratories.
- cGMP fermentation scale-up timelines:Clinical-grade manufacturing capacity for 50 billion CFU doses requires 18-24 month facility qualification cycles, constraining speed-to-market for validated formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Women Probiotic Market |
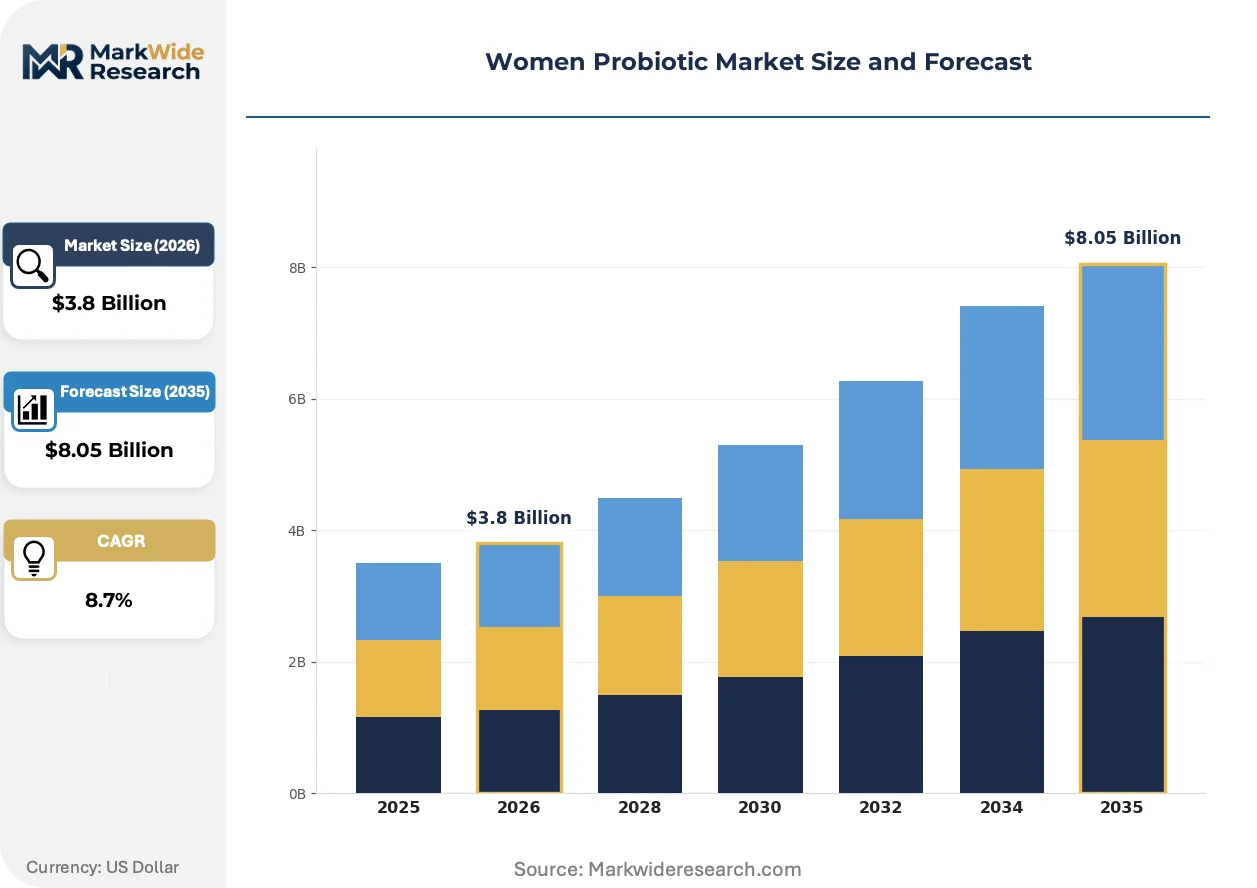
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capsules, Tablets, Powders, Liquid Supplements, Gummies Application: Digestive Health, Vaginal Health, Immune Support, Skin Care, Bone Health End User: Adult Women, Pregnant Women, Lactating Mothers, Elderly Females Distribution Channel: Pharmacies, Online Retail, Specialty Stores, Supermarkets, Wellness Centers |
| Companies Covered | Danone, Yakult Honsha, Nestlé Health Science, BioGaia, Probi AB, Amway, Reckitt Benckiser Group, Church & Dwight, dsm-firmenich, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Women Probiotic Market Trends and Innovations
Live culture delivery systems are converging with digital biomarker tracking, compressing the feedback loop between supplementation and measurable microbiome outcomes while fragmenting traditional pharmacy channel control.
Synbiotic formulations combining targeted prebiotic fibers with strain-specific probiotics are hybridizing product architectures. Younger adult women in direct-to-consumer channels adopt these dual-action formats at three times the rate of single-ingredient alternatives. The technology is hybridizing margin structures by commanding premium positioning while reducing per-SKU manufacturing complexity.
EFSA's evolving stance on urogenital health claims is tightening evidentiary requirements for vaginal microbiome products. Manufacturers must now submit strain-specific human studies demonstrating colonization persistence rather than relying on proxy digestive health data. French and German markets exhibit the most pronounced response, with retailers delisting formulations lacking Article 13.5 authorization.
Subscription-based replenishment models are displacing episodic pharmacy purchases for core digestive and immune formulations. Millennial and Gen Z buyers in the United States favor auto-ship programs paired with app-based symptom tracking over retail aisle selection. This behavioral pivot concentrates lifetime value with platforms owning the customer data layer rather than product manufacturers.
Women Probiotic Market Segmentation
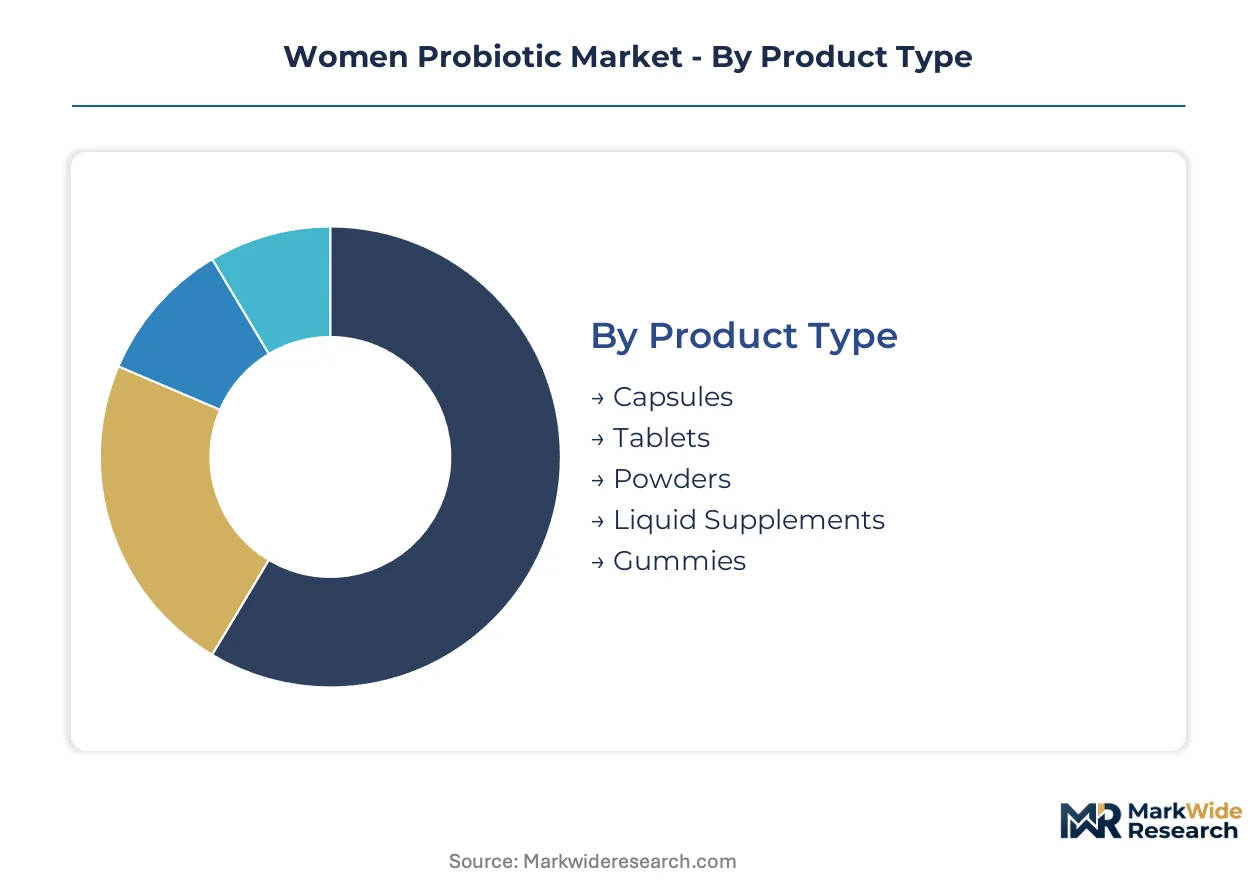
Women probiotic formulations fragment across delivery technologies, clinical applications, and channel architectures that each impose distinct manufacturing and regulatory requirements. Understanding these divides reveals where margin concentrates versus where volume scales.
Product Type:
Use-case spectrum spans clinical precision through convenience-driven consumption, with stability requirements and taste preferences driving format selection.
- Capsules:Two-piece hard gelatin or HPMC shells protect live cultures from gastric acid through enteric coating technologies. Pharmacy channels in the United States favor this format for strain-specific prescriptions and insurance reimbursement pathways.
- Tablets:Compressed formulations with binders and disintegrants sacrifice some CFU viability for manufacturing efficiency and packaging convenience. Direct-to-consumer platforms in Germany and France drive demand for effervescent and chewable variants targeting younger demographics.
- Powders:Sachet-dosed formulations permit flexible dosing and combination with food matrices. Pediatric and perimenopausal applications in Japan favor this format for mixing with yogurt or beverages.
- Liquid Supplements:Ready-to-drink suspensions require cold-chain distribution but offer immediate consumption. Yakult Honsha's heritage infrastructure dominates this segment across East Asian convenience retail.
- Gummies:Pectin or gelatin matrices mask bitterness through flavor systems while introducing moisture sensitivity challenges. Social media marketing and subscription boxes in the United States accelerate adoption among women aged 25-35.
Established volume favors capsules; emerging adoption favors gummies.
Application:
Clinical specificity commands premium positioning, with urogenital and immune endpoints facing stricter evidentiary thresholds than general wellness claims.
- Digestive Health:General microbiome balance formulations targeting bloating, regularity, and IBS symptom management constitute the baseline volume category. Mass retail channels in the United States and Germany stock these as shelf-stable commodities with lower per-unit margins.
- Vaginal Health:Lactobacillus crispatus and L. rhamnosus GR-1 formulations target bacterial vaginosis prevention and pH restoration. OB-GYN practices in the United States increasingly recommend these as first-line interventions, creating institutional prescription pull.
- Immune Support:Strain-specific claims for respiratory and systemic immune modulation require EFSA Article 13.1 authorization in European markets. Human intervention trials for L. paracasei and B. lactis strains dominate R&D investment.
- Skin Care:Gut-skin axis formulations target acne, eczema, and aging through anti-inflammatory mechanisms. South Korean beauty retailers and French pharmacy chains are expanding shelf space for these hybrid cosmeceutical products.
- Bone Health:Calcium absorption and vitamin D metabolism support through specific Lactobacillus strains addresses postmenopausal osteoporosis risk. Japanese functional food regulations favor this application in fermented dairy delivery.
Digestive health anchors revenue scale; vaginal health commands margin expansion.
End User:
Physiological state determines strain selection, dosing protocols, and regulatory classification across the female lifecycle.
- Adult Women:General wellness and preventive maintenance formulations for women aged 18-44 represent the broadest addressable population. Subscription platforms and pharmacy chains in the United States target this segment with personalized microbiome testing bundles.
- Pregnant Women:Gestational diabetes prevention, Group B Streptococcus colonization reduction, and infant immune priming drive strain-specific demand. FDA pregnancy category considerations and EFSA prenatal health claim pathways impose formulation constraints.
- Lactating Mothers:Transfer of beneficial strains through breast milk and mastitis prevention motivate postnatal supplementation. L. fermentum and L. salivarius isolates dominate clinical research in Australian and Canadian maternal health protocols.
- Elderly Females:Antibiotic-associated diarrhea prevention, nutrient absorption, and immune senescence mitigation address aging-related microbiome decline. Pharmacy-practitioner channels in Germany and Switzerland emphasize this segment for polypharmacy management.
Adult women generate volume concentration; pregnant women attract premium formulation investment.
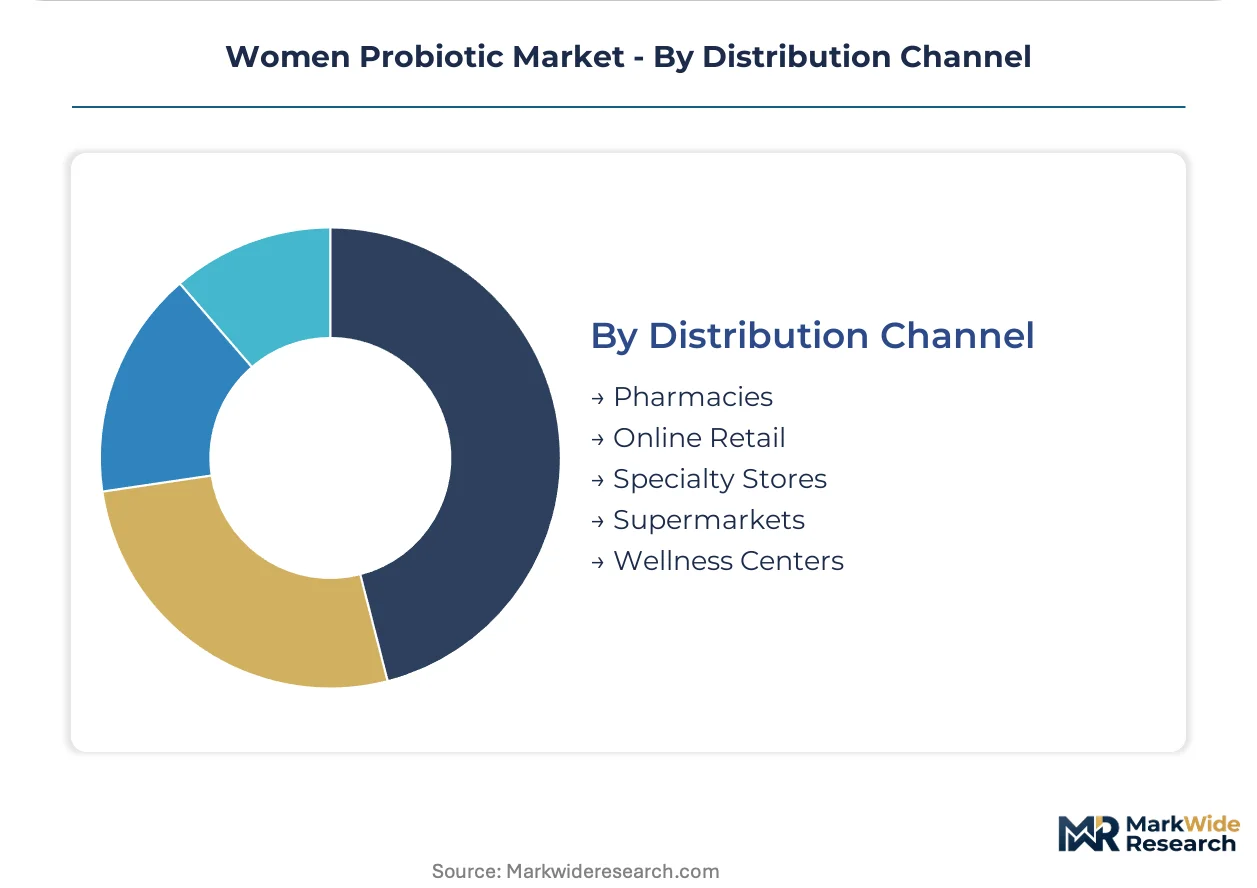
Distribution Channel:
Channel selection determines margin capture, customer data ownership, and regulatory exposure for health claims.
- Pharmacies:Brick-and-mortar and digital pharmacy networks provide clinical credibility and insurance reimbursement access. German and French markets maintain strict pharmacist consultation requirements for urogenital health products.
- Online Retail:Direct-to-consumer platforms and marketplace aggregators enable subscription mechanics and microbiome test integration. Amazon and specialized wellness platforms in the United States dominate this channel's growth trajectory.
- Specialty Stores:Health food retailers and organic chains curate premium strain selections with transparent sourcing credentials. Whole Foods Market and independent cooperatives in California and New York set quality benchmarks.
- Supermarkets:Mass retail placement sacrifices margin for volume exposure in refrigerated dairy and supplement aisles. Walmart and Target in the United States and Carrefour in France compete on price-positioned SKUs.
- Wellness Centers:Integrative medicine clinics, compounding pharmacies, and spa facilities offer practitioner-guided selection with higher service attachment. Functional medicine networks in Arizona and Florida expand private-label partnerships.
Pharmacies defend margin through clinical authority; online retail captures steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Strain banking infrastructure concentrates in France and Denmark, concentrating licensing leverage for urogenital isolates among heritage microbiology institutes. Manufacturing scale clusters in China's probiotic corridor and Germany's pharmaceutical-grade fermentation facilities. Demand pull concentrates in the United States, where direct-to-consumer platforms and OB-GYN prescription protocols create premium pricing power.
United States
Subscription-based microbiome platforms and pharmacy-practitioner channel convergence drive premium formulation demand. FDA pregnancy category labeling requirements shape prenatal probiotic development pathways. The Greater Boston biotech corridor hosts precision fermentation startups targeting strain-specific genomic documentation.
Germany
Pharmacy consultation mandates for urogenital health products reinforce clinical authority channels. EFSA Article 13.1 authorization processes reward substantiated immune and digestive health dossiers. Bavaria's pharmaceutical manufacturing belt anchors cGMP fermentation capacity for 50 billion CFU clinical-grade doses.
China
Domestic probiotic manufacturing corridors reconfigure supply dynamics for women's health formulations across Asia-Pacific. SAMR strain registration requirements and GB standards elevate quality documentation barriers. Yangtze River Delta fermentation facilities expand capacity for synbiotic and liquid delivery formats.
France
Heritage culture collections control access to well-documented Lactobacillus crispatus isolates for vaginal microbiome applications. ANSM oversight of urogenital health claims tightens evidentiary requirements beyond proxy digestive data. Paris-region microbiology institutes license proprietary strains to global formulation partners.
Japan
Functional food regulations favor bone health and immune applications in fermented dairy delivery. METI guidelines on live culture viability thresholds influence regional quality standards. Tokyo-Osaka distribution networks sustain Yakult Honsha's dominance in liquid probiotic convenience retail.
Women Probiotic Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in strain banking and fermentation technology. The vendor base organizes around three archetypes: European dairy heritage conglomerates with clinical validation infrastructure, Asian liquid-format specialists with decades of consumer habit formation, and pharmaceutical-grade manufacturers serving practitioner channels. Consolidation pressures concentrate in strain documentation capabilities and cGMP fermentation scale-up timelines. Competitive moves center on private-label partnerships with compounding pharmacies and microbiome test-platform integrations.
Among European heritage players, Danone leverages dairy-rooted strain portfolios while Nestlé Health Science occupies pharmaceutical-grade manufacturing partnerships. Yakult Honsha anchors the liquid delivery format tier through East Asian distribution density. These three exemplify divergent archetypes: dairy-platform integration, pharma-channel extension, and format-specific habit formation.
| Leading Market Players |
|---|
| Danone |
| Yakult Honsha |
| Nestlé Health Science |
| BioGaia |
| Probi AB |
| Amway |
| Reckitt Benckiser Group |
| Church & Dwight |
| dsm-firmenich |
| Others |
Pricing and Supply Chain Analysis
The Yangtze River Delta freight corridor's cold-chain logistics costs directly shape margin allocation between premium strain-documented formulations and commodity-grade alternatives, concentrating pricing power with manufacturers who control both genomic validation laboratories and temperature-controlled distribution infrastructure.
Pricing Analysis
EFSA Article 13.1 authorization dictates the pricing tier structure across European markets, separating clinically substantiated vaginal health formulations from proxy digestive claims. Three-tier pricing structure across premium, standard, and economy levels reflects strain documentation depth, with pharmacy channels in Germany commanding highest premiums for ANSM-compliant urogenital isolates. Cost compression in the standard tier intensifies because supermarket buyers in France and the United States negotiate volume contracts without certification requirements. Direct-to-consumer subscription platforms exhibit lowest price sensitivity, while mass retail procurement teams drive hardest bargain terms.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculations for cryoprotectant sugars and pharmaceutical-grade excipients. Manufacturing gravity centers on China's Yangtze River Delta fermentation belt, France's Paris-region culture collections, and Germany's Bavarian pharmaceutical corridor. Raw material dependencies span specialized freeze-drying inputs, HPMC capsule shells, and strain banking licenses from heritage microbiology institutes. Single-source vulnerability concentrates in Danish and French Lactobacillus crispatus isolate collections. Distribution runs through pharmacy networks in Germany, direct-to-consumer platforms in the United States, and convenience retail chains in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Strain-specific labeling mandates from FDA and EFSA are accelerating market disruption, creating winner-take-most dynamics for manufacturers with pre-built genomic documentation infrastructure and cGMP fermentation capacity.
For Market Incumbents: Harden strain banking capabilities through exclusive licensing agreements with French and Danish heritage culture collections, insulating against single-source dependency risks. Expand cGMP fermentation footprint in Germany's Bavarian manufacturing belt to compress 18-24 month facility qualification timelines. Deepen vertical integration into cryoprotectant sugar supply to offset mRNA vaccine stabilization demand competition.
For New Entrants and Emerging Players: Establish a beachhead in perimenopausal urogenital applications, where estrogen-independent microbiome support commands formulation white space among women aged 45-55. Target pharmacy-practitioner channel convergence in Arizona and Florida functional medicine networks, bypassing mass retail margin compression. Pursue private-label partnerships with compounding pharmacies seeking strain-traceable manufacturing allies.
For Investors and Strategic Acquirers: Carve-out targets emerge from European dairy conglomerates divesting non-core probiotic strain portfolios amid pharmaceutical-grade manufacturing partnership priorities. Long-term viability hinges on computational biology talent acquisition spanning metagenomic analysis and host transcriptomics. Watch EFSA's evolving metabolomic quality indicator standards as the signal for regulatory inflection timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Strain-Specific Genomic Documentation | EFSA and FDA labeling mandates reward laboratories with deep banking capabilities and shelf-life validation infrastructure. |
| Pharmacy-Practitioner Channel Partnership | Compounding pharmacies in Arizona and Florida seek private-label alliances to bypass mass retail margin erosion. |
| Synbiotic Formulation Development | Prebiotic-probiotic hybrids command premium positioning while reducing per-SKU manufacturing complexity for younger demographics. |
| cGMP Fermentation Scale-Up | Bavarian facilities anchor clinical-grade capacity for 50 billion CFU doses with 18-24 month qualification cycles. |
| Digital Biomarker Platform Integration | Subscription models paired with app-based symptom tracking concentrate lifetime value with data-layer owners. |
Research Methodology
Desk research of FDA 483 inspection observations, EFSA Article 13.1 authorization databases, and WHO probiotic quality guidelines preceded structured interviews with OB-GYN practitioners, compounding pharmacy operators, strain banking laboratory directors, and direct-to-consumer platform product managers. Secondary validation drew from SAMR strain registration filings, ANSM urogenital health claim decisions, and METI live culture viability standards. Bottom-up demand modeling across delivery formats and applications was triangulated against top-down manufacturer capacity assessments.
Assumptions around regulatory stability in EMA-aligned markets and sustained cold-chain infrastructure investment in the Yangtze River Delta were held fixed, while strain-specific labeling enforcement timelines and cryoprotectant input cost trajectories were varied across sensitivity bands. Segmentation dimensions spanned delivery technology, clinical application endpoint, female lifecycle physiological state, and channel architecture. CAGRs were derived from growth rate convergence modeling against historical adoption curves in adjacent microbiome therapeutic categories. Human intervention trial completion rates and pharmacy-practitioner channel expansion velocity served as industry-specific forecast inputs.
Stress conditions across EFSA urogenital claim authorization delays, freeze-drying input supply disruptions, and WHO viability threshold revision timing were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about strain banking access concentration and cGMP fermentation capacity constraints. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Probiotic Supplements
South America Probiotics Market
Probiotic Supplements
Global Probiotic Based Dietary Supplements Market
Probiotic Supplements
Synbiotic Foods Market
Probiotic Supplements
United States Feed Probiotics Market
Probiotic Supplements
Stirred Yogurt Culture Market
Probiotic Supplements
Shelf Stable Probiotics Market
Probiotic Supplements
Digestion Aids Market
Probiotic Supplements
South America Feed Probiotics Market
Probiotic Supplements
Probiotics for Kids Market
Probiotic Supplements
Brazil Probiotics Market
Probiotic Supplements
South America Digestive Health Supplements Market
Probiotic Supplements
Probiotics Gummies Market
Probiotic Supplements
Herbal Yeast Market
Probiotic Supplements
Anti-Diarrheal Supplements Market
Probiotic Supplements
Psychobiotic Supplements Market
Probiotic Supplements
Single-Strain Probiotics Market