
 Dairy Products Market | 2026-2036
Dairy Products Market Size, Share, and Industry Trends Forecast 2026-2036
Dairy Products Market Intelligence
Ingredient processing and value-added formulation is reconfiguring where margin pools accumulate across the dairy value chain. Lactalis leverages its integrated milk collection networks across multiple geographies to sustain cost advantages in cheese production. Nestlé anchors its position through specialized nutrition science capabilities in infant formula and medical dairy applications.
Dairy products encompass fluid milk, fermented goods, and concentrated derivatives standardized for protein content, fat percentage, and microbial safety through pasteurization, homogenization, and ultrafiltration processes. These products serve as essential nutritional inputs for human consumption, industrial food manufacturing, and specialized clinical diets. Cheese and yogurt command expanding shelf space in retail channels as consumers prioritize protein density and probiotic functionality. Milk retains volume dominance but faces margin compression in commoditized fresh segments where private labels compete aggressively.
The FDA enforces Grade A Pasteurized Milk Ordinance standards that dictate pathogen limits and interstate shipment rules across the United States. EFSA and EMA coordinate on novel dairy ingredient approvals and residue monitoring protocols that shape product access into European retail and pharmaceutical channels. Stakeholders must monitor evolving allergen disclosure requirements and carbon footprint auditing standards that will determine supplier eligibility in regulated procurement channels.
Market Dynamics
Protein fractionation and precision fermentation are redistributing value capture from traditional fluid milk toward functional ingredients and alternative dairy platforms, compressing margins in commodity segments while opening premium positioning for bioactive compounds.
Growth Catalysts
- Urban Protein Demand in China:Tier-1 and Tier-2 city consumers are prioritizing yogurt and cheese with elevated protein density, pulling reformulation investments toward Greek-style and strained products.
- FSSAI Quality Mandates:India's stricter labeling and microbial safety benchmarks are consolidating supplier bases as smaller processors exit, creating volume concentration for compliant operators.
- Precision Fermentation Scale-Up:Whey and casein protein production via microbial hosts is reducing land and feed dependencies, attracting capital from ingredient manufacturers seeking supply security.
Market Restraints
- Feed Cost Volatility:Alfalfa and soybean meal price swings in the United States and Brazil directly compress dairy farm operating margins, limiting reinvestment in herd expansion.
- Supply Concentration in Oceania:Fonterra and a limited cooperative structure control the majority of New Zealand milk solids, creating single-source risk for global cheese and butter procurement.
- Regulatory Friction from EU Deforestation Regulation:EUDR traceability requirements for cattle-linked soy imports are extending compliance timelines and raising verification costs for European dairy exporters.
Strategic Opportunities
- Underpenetrated Southeast Asian Markets:Vietnam, Indonesia, and the Philippines exhibit per-capita cheese consumption below one kilogram annually, creating white space for affordable processed cheese and UHT milk positioning.
- Medical Nutrition Applications:Specialized clinical diets for sarcopenia and dysphagia patients are driving demand for texture-modified dairy with elevated leucine content.
- Carbon Footprint Auditing Standards:ISO 14067-aligned product-level carbon labeling is becoming a procurement gate for European retail private label contracts, rewarding early adopters with shelf access.
Industry Challenges
- Microbiome Specialist Scarcity:Formulation of clinically validated probiotic strains requires rare expertise in strain-specific clinical trial design and regulatory dossier preparation.
- Legacy ERP Integration:Batch-level traceability for allergen management and carbon accounting demands retrofitting decades-old manufacturing execution systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dairy Products Market |
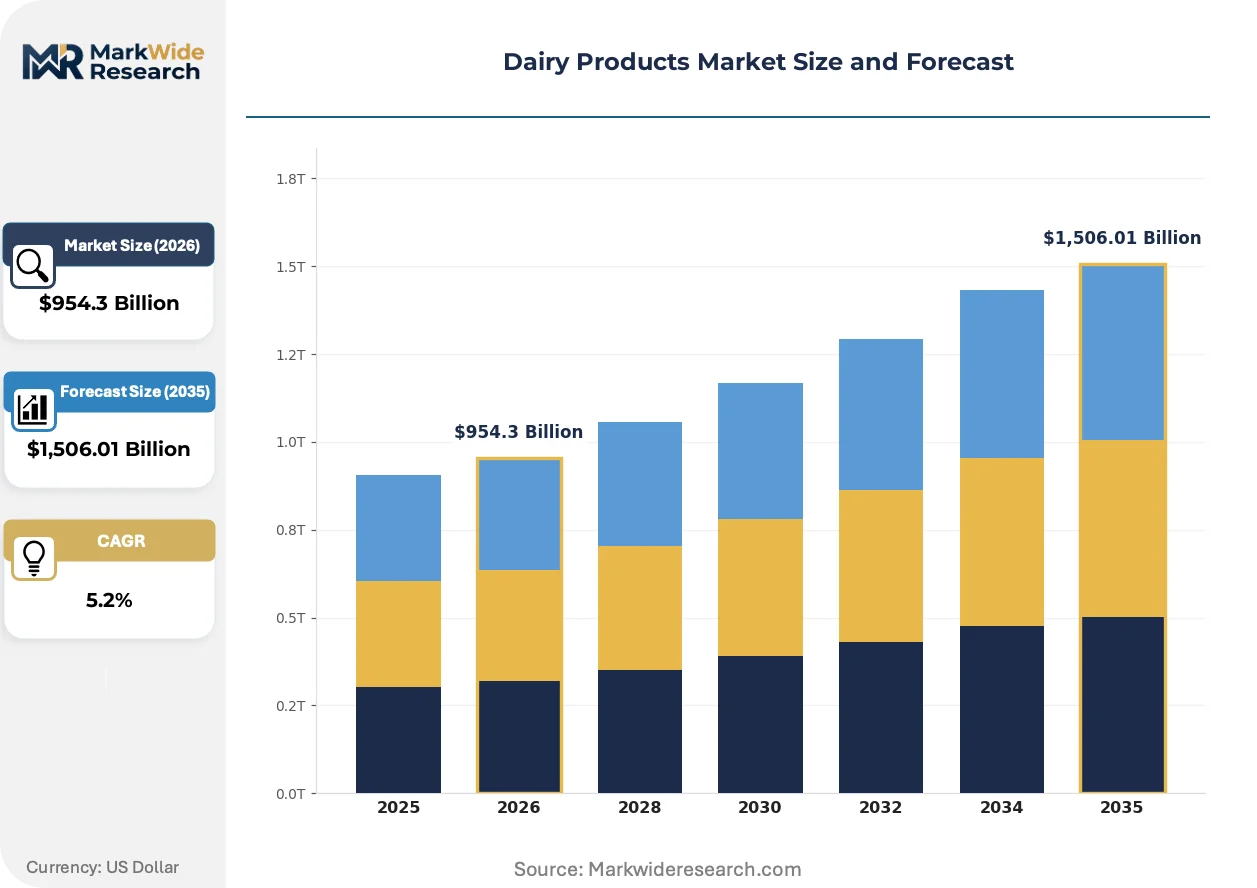
| Market Size in 2026 | $954.3 Billion |
| Market Size in 2035 | $1,506.01 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Milk, Cheese, Butter, Yogurt, Cream, Whey Packaging Type: Bottle, Carton, Pouch, Tub, Sachet, Drum Application: Infant Nutrition, Culinary, Beverage, Confectionery, Cosmetics, Pharmaceuticals Customer Type: Supermarkets, Specialty Stores, Foodservice, Wholesalers, Online Retailers, Convenience Stores |
| Companies Covered | Lactalis, Nestlé, Dairy Farmers of America, Danone, Yili Group, Fonterra, Arla Foods, FrieslandCampina, Mengniu Dairy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dairy Products Market Strategic Shifts & Innovations
Bioprocessing convergence and regulatory disclosure mandates are redefining competitive advantage away from scale economies toward ingredient specificity and supply chain transparency.
Precision fermentation for dairy proteins is hybridizing the competitive landscape between conventional extraction and microbial production. Ingredient manufacturers in the United States and Singapore are commissioning commercial-scale facilities for whey protein isolate equivalents. This technology is compressing the cost curve for functional proteins while forcing traditional processors to defend through bioactive compound differentiation.
EFSA's evolving stance on novel food approvals is reshaping ingredient launch timelines across European markets. The agency's expanded requirements for extended allergenicity assessments are delaying market entry for precision fermentation-derived caseins. Infant formula and sports nutrition segments are most affected, with several applicants pivoting toward US FDA GRAS self-determination pathways to circumvent European delays.
Foodservice operators are consolidating dairy procurement through direct contracting with processor cooperatives, bypassing traditional distributor tiers. Large quick-service chains in China and the United States are mandating supplier-specific sustainability certifications and volume commitments. This concentration is most visible in cheese and cream sourcing for pizza and coffee applications, where procurement teams now prioritize traceability dashboards over spot-market flexibility.
Dairy Products Market Segmentation
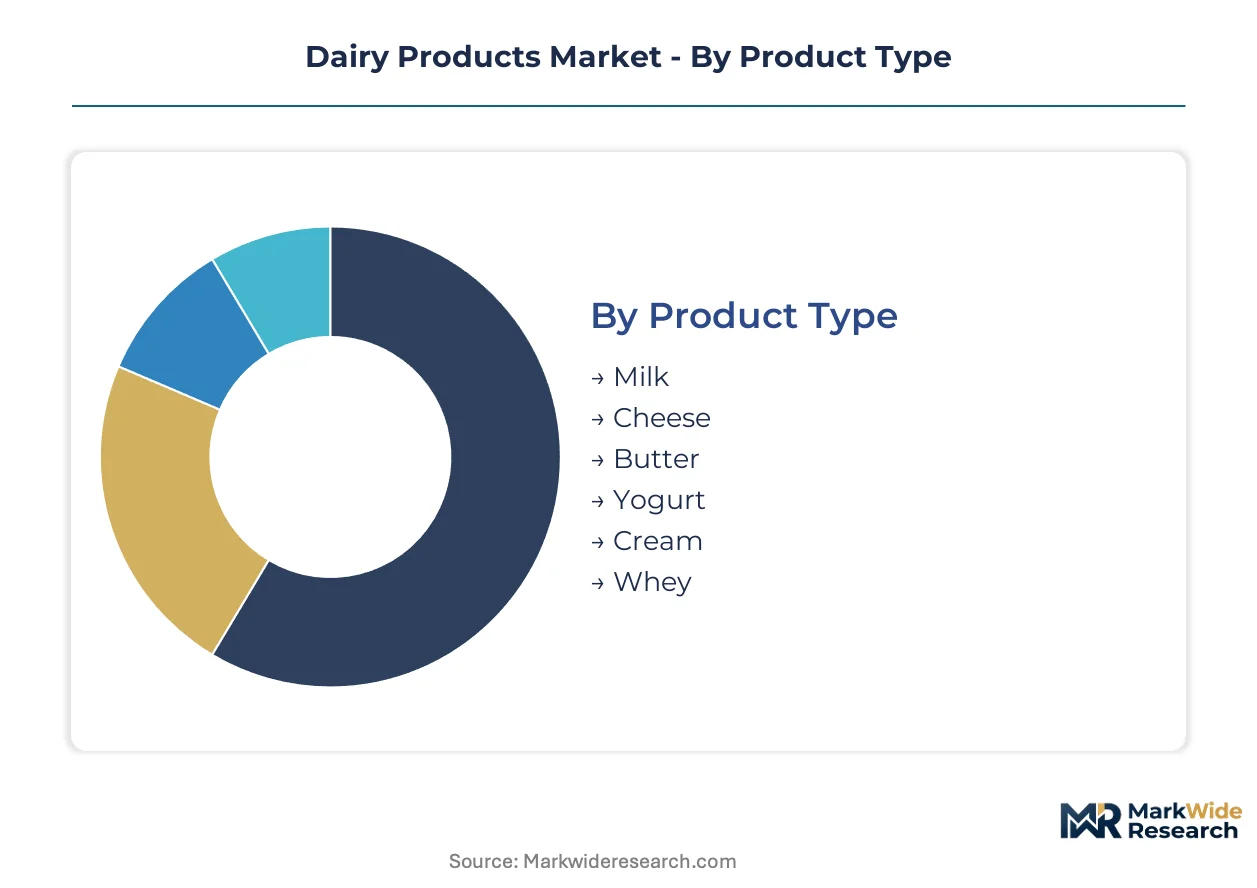
Segmentation in dairy products determines procurement cadence and margin structure. Product shelf-life ranges from hours for fresh fluid milk to years for dried whey isolates. Packaging and channel choices directly govern cold-chain investment and geographic reach.
Product Type:
Cycle times vary dramatically across dairy categories. Fresh fluid products turn inventory daily while aged cheese and protein concentrates operate on multi-month or multi-year production horizons.
- Milk:Standardized fluid milk requires pasteurization and homogenization to achieve microbial safety and fat stability. Demand concentrates in foodservice channels across China and India where tea and coffee applications pull volume despite margin compression from private-label competition.
- Cheese:Curdled and aged dairy proteins span fresh varieties to hard-aged formats with protein content ranging from 20% to 35%. Urban Chinese consumers in Tier-1 cities are prioritizing protein-dense options, pulling reformulation toward Greek-style and strained positioning.
- Butter:Churned fat product with minimum 80% milkfat content serving baking and spread applications.
- Yogurt:Fermented milk with live cultures delivering probiotic functionality and elevated protein density in strained formats.
- Cream:Fat-rich dairy layer separated from milk for culinary and beverage applications requiring specific whipping or stability properties.
- Whey:Liquid byproduct of cheese manufacturing processed into protein concentrates and isolates for sports nutrition and clinical applications.
Milk anchors the volume base while whey gains share at the steepest rate.
Packaging Type:
Cost tiers separate premium shelf-stable formats from economy bulk handling. Aseptic cartons and multilayer pouches command 3-5x the packaging cost of basic sachets or drums.
- Bottle:PET or HDPE containers for fluid milk and drinkable yogurt with resealability for multi-serve consumption.
- Carton:Aseptic multilayer paperboard enabling ambient distribution and extended shelf-life without refrigeration infrastructure.
- Pouch:Flexible multilayer film for yogurt and cream with lightweight logistics advantages and portion control functionality.
- Tub:Polypropylene containers for spoonable yogurt and spreadable cheese with stackability for retail shelf efficiency.
- Sachet:Single-serve flexible packets for condensed milk and creamer powders targeting price-sensitive emerging market consumers.
- Drum:Industrial-grade containers for bulk whey powder and butteroil serving ingredient manufacturers and food processors.
Carton and pouch formats are expanding most quickly in Asia-Pacific while drum packaging retains dominance in ingredient trade.
Application:
Customer type determines specification stringency. Infant nutrition and pharmaceutical applications demand lot-level traceability and contaminant testing that culinary and cosmetic buyers rarely require.
- Infant Nutrition:Specialized formulas requiring precise protein ratios, DHA/ARA fortification, and clinical validation for metabolic tolerance. China's SAMR mandates registration and formula verification that limits supplier eligibility to established multinationals with dossier capabilities.
- Culinary:Chef-driven applications spanning sauce bases, dessert preparations, and baking formulations where fat functionality and flavor intensity drive selection.
- Beverage:Coffee, tea, and smoothie applications demanding foaming stability or clean-label positioning.
- Confectionery:Chocolate and candy manufacturing requiring specific milk powder particle size and fat crystallization behavior.
- Cosmetics:Lactic acid and milk lipid derivatives for skin hydration and exfoliation formulations.
- Pharmaceuticals:Excipients and active ingredients meeting pharmacopeial standards for tablet binding or parenteral nutrition.
Infant nutrition anchors the value concentration while culinary applications deliver the broadest volume throughput.
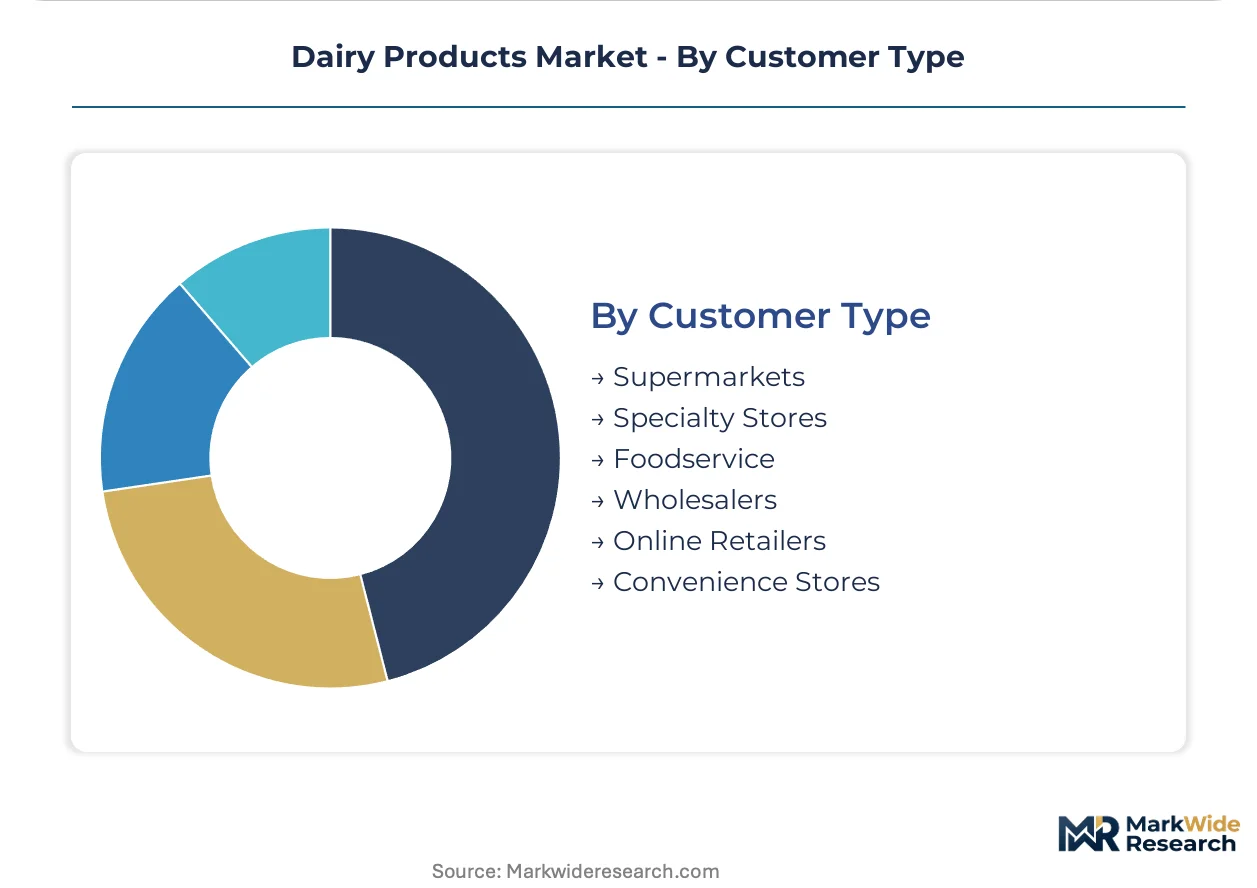
Customer Type:
Channel concentration shapes supplier capability requirements. Foodservice and supermarket buyers now mandate sustainability certifications and volume commitments that exclude smaller processors.
- Supermarkets:Multi-format retail commanding private-label development, promotional funding, and category management support with shelf-space fees determining placement.
- Specialty Stores:Curated retail emphasizing artisan provenance, organic certification, and regional origin storytelling that commands price premiums.
- Foodservice:Restaurant, hotel, and institutional operators consolidating procurement through direct processor contracts with traceability dashboard requirements.
- Wholesalers:Distribution intermediaries serving independent retailers and smaller food manufacturers with break-bulk and credit services.
- Online Retailers:E-commerce platforms requiring shelf-stable or chilled last-mile logistics and subscription-friendly packaging formats.
- Convenience Stores:Small-format retail prioritizing grab-and-go single-serve portions and extended shelf-life for limited refrigeration capacity.
Supermarkets retain the largest revenue share while online retailers are climbing the fastest as delivery infrastructure matures in urban China and Southeast Asia.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across geographies. Indian and Indonesian buyers prioritize affordable UHT milk and processed cheese, while urban Chinese consumers absorb premiums for protein-dense Greek yogurt and artisan cheese varieties.
China
Tier-1 cities drive demand for strained yogurt and aged cheese with elevated protein content. SAMR mandates infant formula registration and verification that limits supplier eligibility to established multinationals. Yangtze River Delta processors are expanding cold-chain infrastructure to serve Shanghai's premium retail channels.
United States
Foodservice operators consolidate cheese and cream procurement through direct processor contracts with sustainability dashboard requirements. FDA enforces Grade A Pasteurized Milk Ordinance standards dictating pathogen limits and interstate shipment rules. Wisconsin and California dairy cooperatives are investing in precision fermentation partnerships to diversify protein sourcing.
India
Mass-market consumers pull volume toward affordable pouch-packed milk and processed cheese slices. FSSAI mandates stricter labeling and microbial safety benchmarks that consolidate supplier bases as smaller processors exit. Gujarat and Maharashtra dairy cooperatives are upgrading testing laboratories to meet compliance deadlines.
Germany
Retail private label contracts now require ISO 14067-aligned carbon footprint auditing as a procurement gate. EFSA and EMA coordinate on novel dairy ingredient approvals and residue monitoring protocols. Bavarian processors are piloting blockchain traceability for cattle-linked soy imports under EUDR requirements.
Brazil
Domestic demand concentrates in UHT milk and requeijão cheese spread for price-sensitive households. ANVISA monitors dairy ingredient safety and novel food approvals for sports nutrition applications. São Paulo and Minas Gerais cooperatives are expanding powder processing capacity to serve African export markets.
Dairy Products Market Key Industry Players
Capability concentration sits with science-driven nutrition specialists; scale advantage sits with integrated milk collection networks spanning multiple geographies. The market structures around three tiers: multinational nutrition science platforms, cooperative-backed commodity processors, and regional private-label suppliers. Dominant competitive moves include backward integration into captive milk supply and portfolio diversification toward medical nutrition and precision fermentation ingredients.
Within the integrated cooperative tier, Lactalis and Fonterra exemplify scale-driven positioning through geographically distributed milk sourcing networks. Nestlé occupies a position representing the nutrition science archetype, anchoring specialized applications in infant formula and clinical dairy segments. FrieslandCampina sits within the cooperative-backed multinational category, bridging commodity processing and branded ingredient development.
| Leading Market Players |
|---|
| Lactalis |
| Nestlé |
| Dairy Farmers of America |
| Danone |
| Yili Group |
| Fonterra |
| Arla Foods |
| FrieslandCampina |
| Mengniu Dairy |
| Others |
Cost & Logistics Intelligence
Overcapacity in European commodity cheese production is forcing processors toward contract manufacturing and private-label partnerships, compressing spot-market premiums while rewarding integrated operators with captive milk supply. This utilization imbalance feeds directly into pricing power asymmetries across fresh versus aged product tiers.
Pricing Analysis
Ingredient service contracts and extended formulation partnerships now anchor lifetime value for dairy processors serving infant nutrition and sports nutrition channels. Three-tier pricing structure across premium, standard, and economy levels separates A2 protein-certified fluid milk from conventional fluid products and basic commodity powder. Price differentiation hinges on organic certification grade and cold-chain delivery infrastructure. Cost compression in standard-tier cheese is intensifying because Brazilian and Argentine exporters are expanding EU market access. Emerging market foodservice buyers exhibit highest price sensitivity; clinical nutrition procurement teams show lowest sensitivity due to regulatory validation requirements.
Supply Chain Analysis
Extended payment terms from European retail consolidators are squeezing working capital for mid-tier processors, accelerating consolidation toward cooperative-backed entities with supply-chain finance facilities. Milk solids supply concentrates in New Zealand, the Netherlands, and Germany, with protein concentrate processing anchored in the United States and Ireland. Feed inputs draw from Argentine soybean meal, Ukrainian corn, and Brazilian alfalfa. Single-source vulnerability runs through Fonterra's dominance in global whole milk powder trade. Distribution runs through processor-direct contracts with quick-service chains and supermarket private-label procurement offices, bypassing traditional distributor tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dairy markets are fragmenting across protein functionality lines, as precision fermentation and medical nutrition applications create specialty niches that resist commoditization. Urban China's demand for protein-dense yogurt and India's FSSAI compliance thresholds are pulling supplier capabilities in divergent directions.
For Market Incumbents: Insulate premium positioning by securing A2 beta-casein and organic-certified milk supply through backward integration into named-herd genetics programs. Expand precision fermentation partnerships in Singapore and the United States to hedge against feed cost volatility. Defend against precision fermentation entrants by accelerating clinical validation for bioactive peptide applications in sarcopenia and dysphagia nutrition.
For New Entrants and Emerging Players: Vietnam's cheese consumption below one kilogram per capita annually offers white-space positioning for affordable processed cheese and UHT milk pouches. Target Indonesia's convenience store channel with shelf-stable, single-serve yogurt formats. Enter through direct foodservice contracts with coffee chain operators seeking traceability dashboards rather than competing for supermarket shelf space against established cooperatives.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across precision fermentation protein facilities, favoring early-stage platforms with offtake agreements over asset-heavy commodity processors. Over the medium-term horizon, vertically integrated nutrition science specialists with dossier capabilities for SAMR and FDA submissions represent the most defensible acquisition profile. Watch EFSA novel food approval timelines as the signal indicating whether European market entry premiums will compress or sustain.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Reduces land and feed dependencies while attracting ingredient manufacturer capital seeking supply security. |
| Carbon Footprint Certification | ISO 14067-aligned auditing becomes procurement gate for European retail private label contracts. |
| Direct Foodservice Contracting | Bypasses distributor tiers and mandates supplier-specific sustainability dashboards from quick-service chains. |
| Medical Nutrition Formulation | Texture-modified dairy with elevated leucine content addresses sarcopenia and dysphagia patient populations. |
| Blockchain Traceability Implementation | Bavarian processors pilot distributed ledgers for EUDR-compliant cattle-linked soy import verification. |
Research Approach
The analysis maps fluid milk, cheese, yogurt, whey derivatives, and precision fermentation platforms, each validated through cooperative procurement managers, foodservice chain operators, infant formula regulatory affairs leads, and clinical nutrition formulators. Primary interviews with dairy processors across New Zealand, the Netherlands, India, and the United States combined with secondary validation from FSSAI compliance filings, EFSA novel food registers, SAMR infant formula registrations, and Fonterra auction price data. Bottom-up volume modeling triangulated against top-down macroeconomic consumption trends.
Assumptions held feed cost volatility within historical bands and regulatory approval timelines at observed EFSA and FDA durations across the projection horizon. Segmentation dimensions modeled include product type, packaging format, application channel, and customer tier. CAGRs derived from regression analysis of protein demand elasticity against urban income growth in China and India. Forecast inputs incorporated FSSAI laboratory upgrade timelines and cold-chain infrastructure buildout rates in the Yangtze River Delta.
The forecast holds incumbent behavior within observed patterns; aggressive moves by precision fermentation platforms or rapid EUDR enforcement acceleration would shift outcomes. Macroeconomic deviation in Chinese consumer spending, regulatory timeline compression in novel food approvals, or technological breakthroughs in microbial protein cost curves would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Flavored Yogurt Market
Dairy Products
United Kingdom Dairy Market
Dairy Products
GCC Cheese Market
Dairy Products
Solidified Yogurt Market
Dairy Products
Global Yogurt Powder Market
Dairy Products
Asia-Pacific Dairy Market
Dairy Products
Reconstituted Milk Market
Dairy Products
Spicy Dairy Products Market
Dairy Products
Cream and Soft Cheese Market
Dairy Products
China Milk Protein Market
Dairy Products
Recombined Milk Market
Dairy Products
Smoked Cheese Market
Dairy Products
Global Goat Milk Derivatives Market
Dairy Products
North America Casein and Caseinate Market
Dairy Products
Goat Milk Products Market
Dairy Products
Savory Dairy Products Market