
 UHT Whipping Cream Market | 2026-2036
UHT Whipping Cream Market Size, Share, and Industry Trends Forecast 2026-2036
UHT Whipping Cream Market Analytics
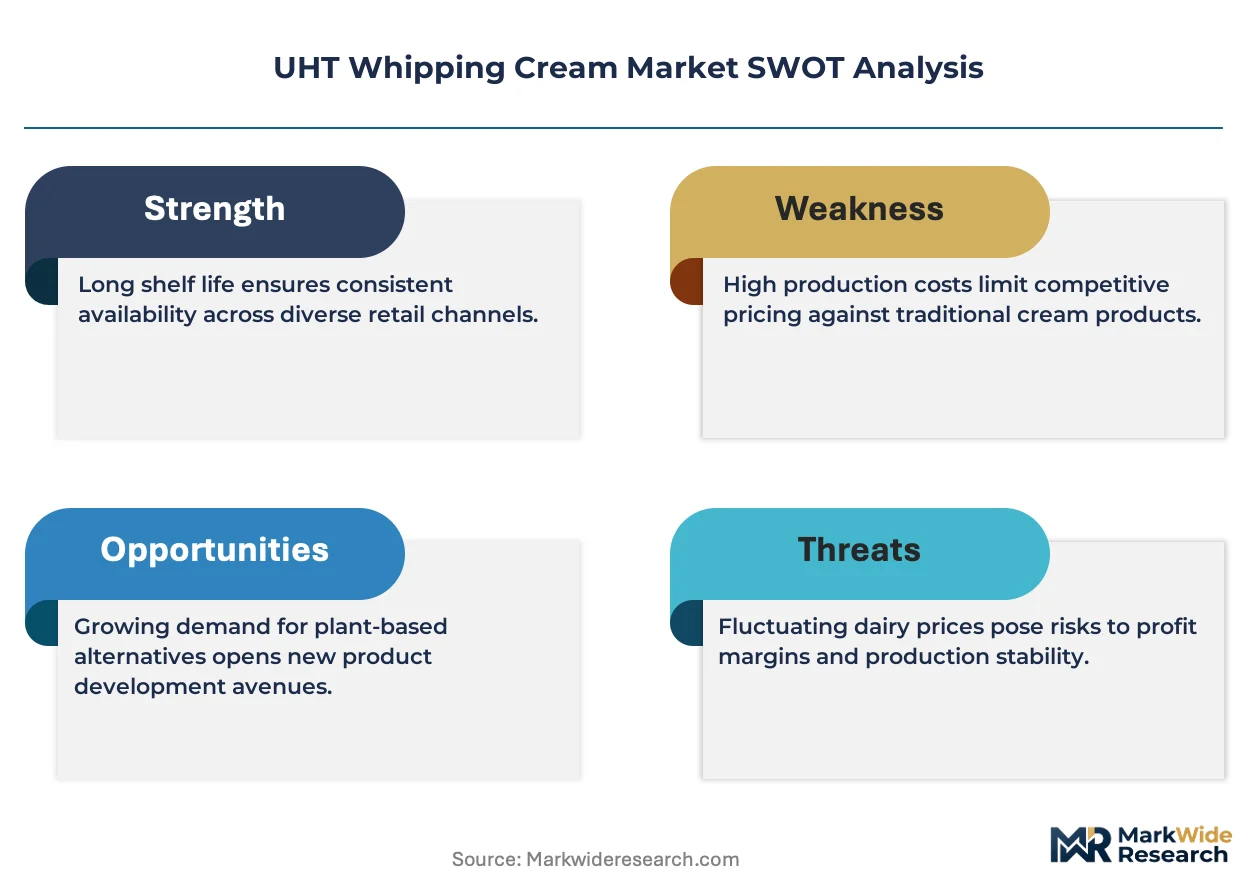
Dairy processing technician shortages across Europe are reorganizing plant automation investments and training pipelines. Fonterra Co-operative Group leverages its New Zealand sourcing base to sustain long-haul UHT cream exports into Asian markets. Nestlé S.A. anchors its portfolio through R&D intensity in stabilized cream formulations for hot-climate distribution. Arla Foods AMBA differentiates via cooperative-owned supply chains that control raw milk quality from farm to aseptic filling line.
UHT whipping cream denotes dairy cream heat-treated at ultra-high temperatures, typically above 135 degrees Celsius for two to five seconds, then aseptically packaged to achieve shelf stability without refrigeration until opening. The process destroys spoilage microorganisms while preserving fat structure and whipping functionality for commercial baking and beverage applications. Dairy-based formulations dominate volume due to established cold chain partnerships and chef preference for fat-based aeration, though non-dairy alternatives are capturing margin pools in vegan bakery and plant-based catering channels. Aseptic packs lead packaging type demand because of their barrier properties and pallet efficiency, while pouches are gaining traction in food service for portion control and reduced waste.
The EU F-Gas Regulation and REACH framework govern refrigerant choices and packaging material compliance across European UHT cream operations, directly influencing capital expenditure timelines and supplier qualification. The FDA oversees interstate dairy safety standards in the United States, including Grade A pasteurized milk ordinances that extend to UHT processing plants exporting into American territories. Stakeholders must monitor evolving refrigerant phase-down schedules and aseptic packaging substrate rules to anticipate retrofit costs and reformulation requirements.
Market Dynamics
EU F-Gas Regulation mandates are compressing cold chain equipment replacement cycles across European dairy processing, forcing capital reallocation toward lower-emission refrigeration systems before hydrofluorocarbon phase-down deadlines.
Growth Catalysts
- Bakery chain expansion:Artisanal patisseries and commercial bakeries are extending refrigerated dessert portfolios, drawing on extended-shelf-life dairy inputs for operational flexibility.
- REACH framework compliance:Packaging material standards under ECHA oversight are standardizing aseptic substrate specifications, reducing supplier qualification friction for cross-border trade.
- Asian food service density:Centralized dairy cooperatives in Germany supply dense distributor networks that feed export demand into high-growth Asian markets.
Market Restraints
- Energy cost volatility:Natural gas and electricity price swings directly impact UHT processing economics, compressing margin buffers for mid-scale operators.
- Raw milk supply concentration:Cooperative-owned supply chains in Northern Europe control quality from farm to aseptic filling, limiting independent processor access to premium inputs.
- Non-dairy substitution threat:Plant-based cream alternatives are capturing margin pools in vegan bakery and plant-based catering channels, pressuring dairy-based volume growth.
Strategic Opportunities
- Food service pouch formats:Portion-control packaging is gaining traction in commercial kitchens seeking waste reduction and inventory precision.
- Hot-climate distribution networks:Stabilized cream formulations enable shelf-stable logistics into regions with limited cold chain infrastructure.
- EU Green Deal alignment:Lower-emission refrigeration retrofits qualify for sustainability-linked financing instruments, accelerating equipment modernization timelines.
Industry Challenges
- Dairy processing technician scarcity:Qualified operator shortages across Europe are forcing automation investments and compressed training pipelines.
- Aseptic packaging substrate recertification:Evolving barrier material rules under REACH require ongoing reformulation and supplier requalification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UHT Whipping Cream Market |
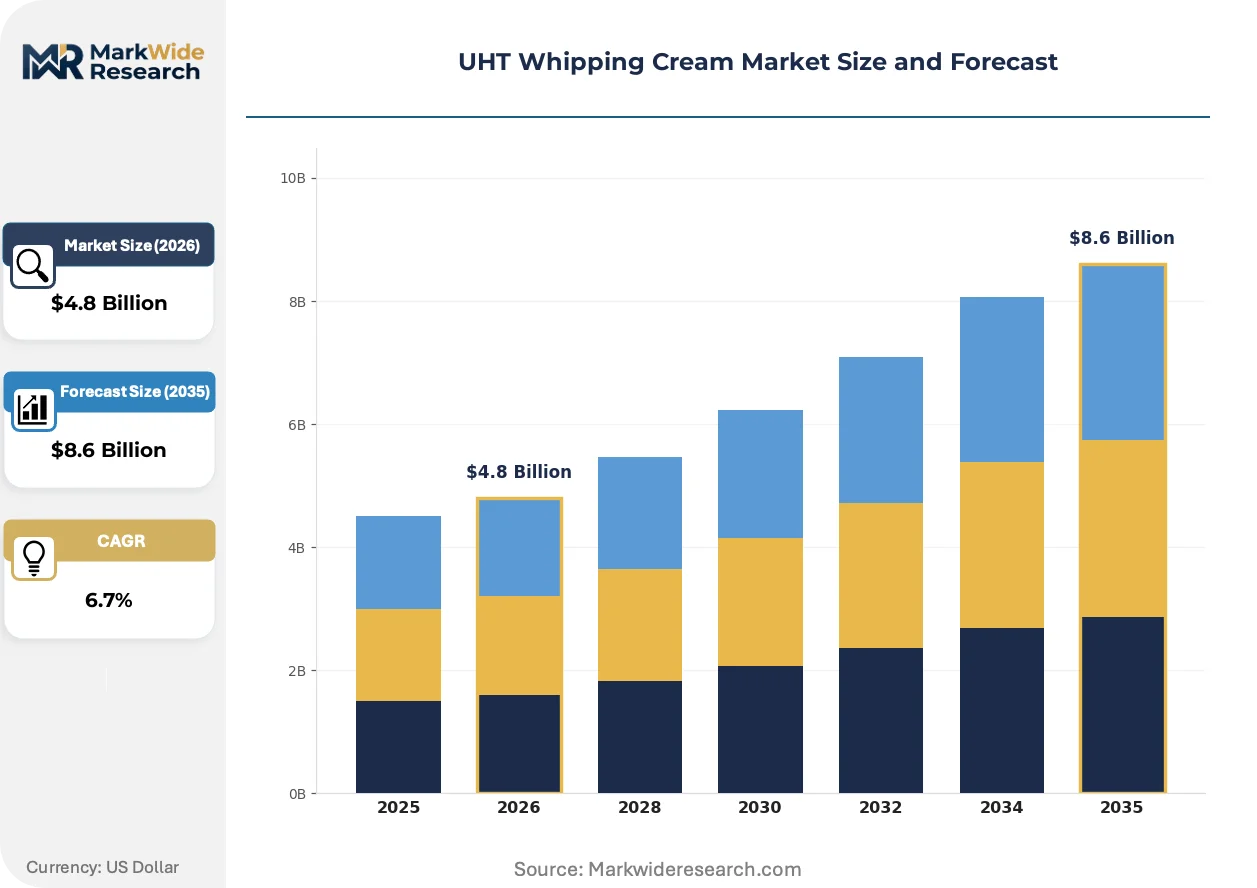
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vegetarian, Dairy-Based, Non-Dairy, Flavored Packaging Type: Aseptic Packs, Cartons, Bottles, Pouches End User: Food Service, Retail, Bakery, Catering Distribution Channel: Online, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Fonterra Co-operative Group, Danone, Nestlé S.A., Land O’Lakes, The Kraft Heinz Company, FrieslandCampina N.V., Arla Foods AMBA, Amul, Lactalis Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UHT Whipping Cream Market Evolving Landscape
Processing automation and packaging material science are converging to reshape cost structures and shelf-life performance across UHT cream manufacturing.
Advanced aseptic filling systems are decomposing traditional batch processing economics by enabling continuous flow operations with reduced human intervention. Mid-scale dairy processors in France and Italy are retrofitting legacy lines at accelerated pace. This technology compression is decomposing the labor cost advantage previously held by manual-intensive operations in lower-wage markets.
The EU F-Gas Regulation is mandating hydrofluorocarbon phase-down schedules that force refrigeration equipment replacement before natural end-of-life. Dairy processors face compressed capital expenditure timelines to install lower-emission cooling systems. German and Dutch facilities are responding fastest, leveraging cooperative financing structures to spread retrofit costs across member farms.
Food service buyers are consolidating procurement around portion-control pouch formats that reduce kitchen waste and simplify inventory management. Traditional multi-liter carton supply is losing share in commercial bakery and restaurant channels. This shift is most visible in France and the United Kingdom, where chain operators specify single-serve packaging in supplier tenders.
UHT Whipping Cream Market Segmentation
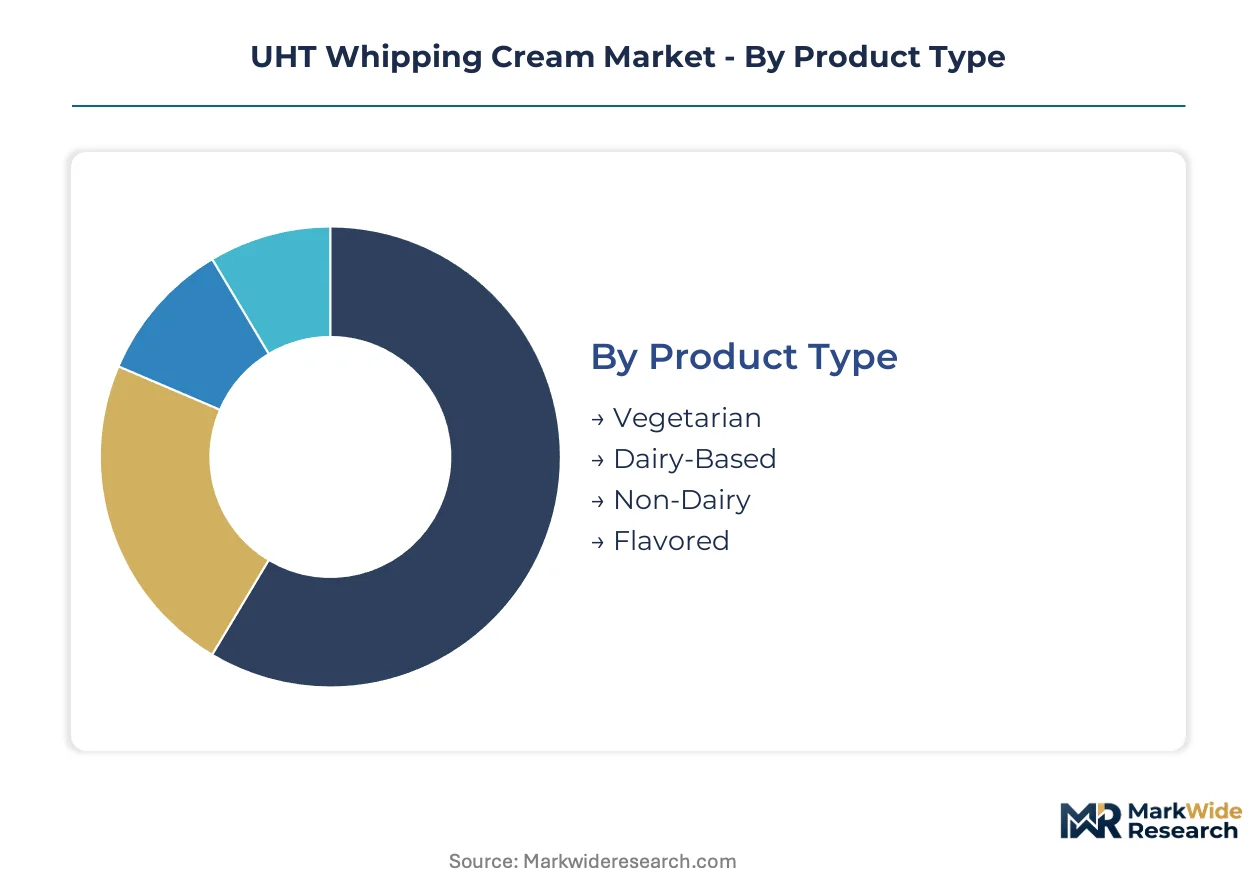
UHT whipping cream segmentation reflects divergent technical requirements across cold chain infrastructure and end-use applications. Product formulation, packaging barrier properties, and distribution channel economics each create distinct margin pools that processors must navigate simultaneously.
Product Type:
Dairy-based formulations face distinct regulatory treatment under EFSA safety standards and REACH additive frameworks compared to plant-derived alternatives, creating compliance cost differentials that reshape competitive positioning.
- Dairy-Based:Heat-treated cream above 135 degrees Celsius preserves fat structure for commercial aeration. German centralized cooperatives supply dense food service networks across Europe and Asia, leveraging extended shelf life for export logistics.
- Non-Dairy:Plant-derived emulsions capture margin pools in vegan bakery channels. These formulations bypass traditional dairy cold chain partnerships but face EFSA novel food scrutiny and REACH emulsifier compliance costs that compress price competitiveness.
- Vegetarian:Lactose-free dairy variants serve religious dietary requirements and intolerance-sensitive segments. Production concentrates in Dutch and Irish facilities with specialized membrane filtration capabilities.
- Flavored:Vanilla, chocolate, and coffee infusions target premium dessert applications. Stabilizer selection must satisfy both EFSA additive limits and hot-climate distribution stability requirements.
Dairy-based handles the majority of throughput; non-dairy is climbing the fastest on share.
Packaging Type:
Barrier material specifications under REACH and ECHA oversight create tiered compliance burdens that concentrate investment in formats with established substrate approval pathways.
- Aseptic Packs:Multi-layer cartons with aluminum or ethylene vinyl alcohol barriers achieve 6-12 month ambient shelf stability. German and Dutch processors dominate supply through cooperative financing structures that spread capital costs across member farms.
- Pouches:Flexible film formats with portion-control dosing reduce commercial kitchen waste. French and UK chain operators increasingly specify single-serve packaging in supplier tenders, displacing multi-liter carton demand.
- Cartons:Gable-top formats serve retail channels with established dairy cold chain partnerships. Recyclability requirements under EU Packaging and Packaging Waste Regulation drive substrate reformulation cycles.
- Bottles:PET and HDPE formats target food service bulk procurement. Lightweighting initiatives respond to extended producer responsibility fees in German and French markets.
Aseptic packs command the installed base; pouches are gaining share fastest in food service channels.
End User:
Volume concentration and margin structure diverge sharply between operational buyers seeking inventory flexibility and consumer-facing channels demanding format variety.
- Food Service:Commercial kitchens and restaurant chains prioritize portion control and waste reduction. Procurement consolidation around pouch formats is visible in France and the United Kingdom.
- Bakery:Artisanal patisseries and industrial bakeries extend refrigerated dessert portfolios. Extended-shelf-life inputs enable production scheduling flexibility without cold storage dependency.
- Retail:Supermarket and convenience store channels demand format variety across price tiers. Private label penetration concentrates in German and UK grocery consolidation.
- Catering:Event and institutional food service requires bulk stability and transport resilience. Hot-climate distribution networks favor stabilized cream formulations with enhanced emulsifier systems.
Food service absorbs the largest volume share; bakery is expanding most quickly on throughput.
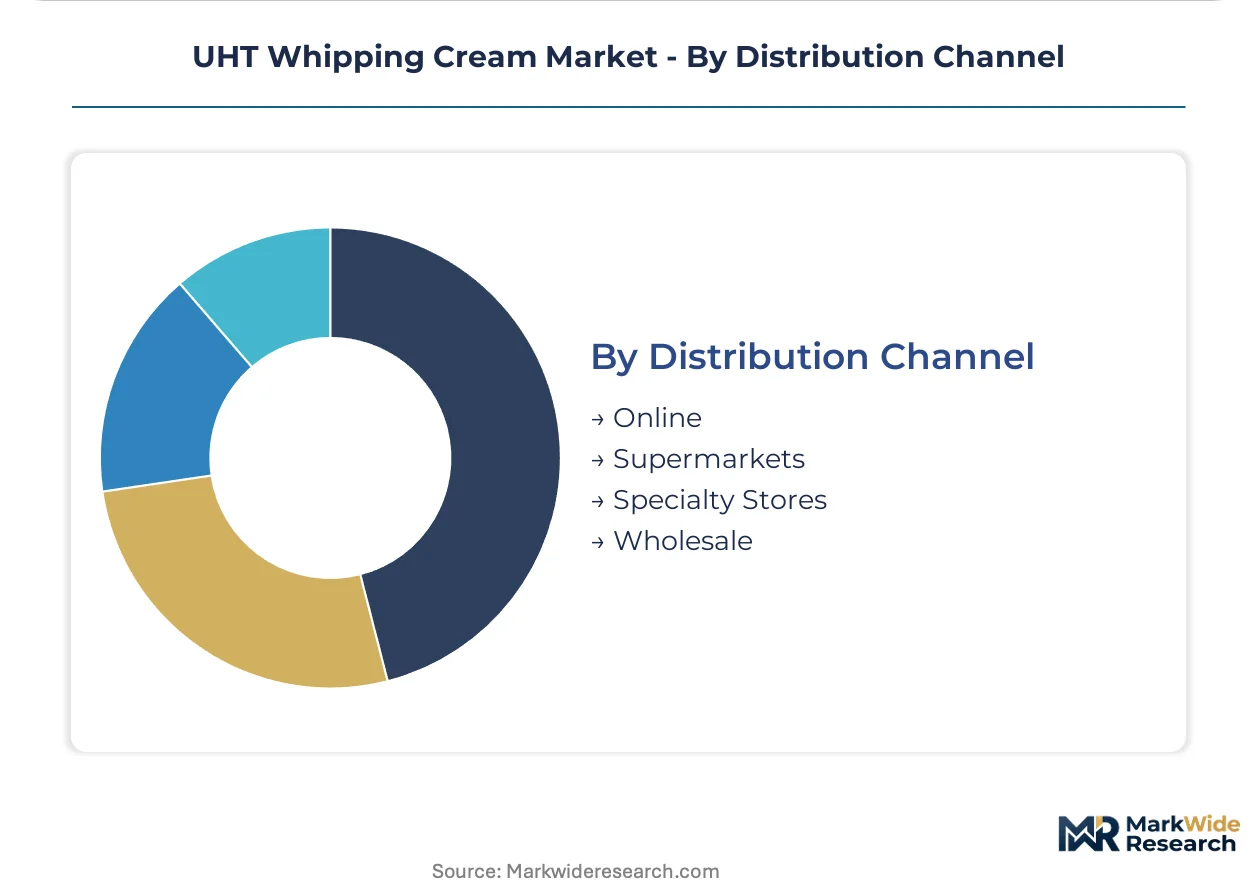
Distribution Channel:
Channel economics reflect cold chain infrastructure availability and buyer procurement sophistication across geographic markets.
- Wholesale:Food service distributors and dairy cooperatives supply dense networks of commercial kitchens. German cooperative structures feed export demand into Asian markets through established logistics partnerships.
- Supermarkets:Grocery retail chains dominate consumer-facing volume with multi-format shelf presence. UK and French consolidation limits supplier negotiation leverage for mid-scale processors.
- Specialty Stores:Gourmet and ethnic food retailers target premium positioning and import varieties. These channels bypass mainstream cold chain partnerships but carry higher working capital requirements.
- Online:Direct-to-consumer and B2B platforms serve fragmented demand with delivery logistics complexity. Last-mile cold chain reliability remains a constraint outside urban density centers.
Wholesale channels move the dominant share; online is gaining traction fastest on penetration rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies, with European markets prioritizing extended-shelf-life logistics for food service export while Asian markets emphasize stabilized formulations for hot-climate distribution without cold chain dependency.
Germany
Centralized dairy cooperatives supply dense networks of food service distributors feeding both domestic bakery chains and Asian export demand. The EU F-Gas Regulation mandates hydrofluorocarbon phase-down schedules that compress refrigeration equipment replacement cycles before natural end-of-life. Processing clusters concentrate in Bavaria and Lower Saxony where cooperative financing structures spread retrofit capital costs across member farms.
France
Artisanal patisseries extend refrigerated dessert portfolios requiring extended-shelf-life dairy inputs for production scheduling flexibility. REACH framework compliance under ECHA oversight standardizes aseptic substrate specifications for cross-border trade. Industrial dairy processing concentrates in Brittany and Normandy where coastal logistics facilitate cream export into North African markets.
United Kingdom
Commercial bakery and restaurant chains consolidate procurement around portion-control pouch formats that reduce kitchen waste and simplify inventory management. The UK Packaging and Packaging Waste Regulation drives substrate reformulation cycles for recyclability compliance. Greater London and the Midlands host dense food service distributor networks displacing traditional multi-liter carton supply with single-serve specifications.
China
Hot-climate distribution networks favor stabilized cream formulations with enhanced emulsifier systems for shelf-stable logistics into interior provinces with limited cold chain infrastructure. SAMR oversees dairy safety standards including Grade A pasteurized milk ordinances extending to UHT processing plants. Processing capacity clusters in the Yangtze River Delta where coastal dairy imports blend with domestic production for bakery and beverage manufacturing.
Netherlands
Specialized membrane filtration capabilities support lactose-free and vegetarian dairy variant production serving religious dietary requirements across European and Middle Eastern markets. The EU Green Deal qualifies lower-emission refrigeration retrofits for sustainability-linked financing instruments. Dairy technology providers concentrate in the Randstad region where proximity to Rotterdam port accelerates aseptic packaging material import and finished product export logistics.
UHT Whipping Cream Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with cooperative structures and multinational dairy conglomerates commanding distinct advantages in raw milk access and cold chain partnerships. The market structure reflects tiered consolidation where scale-driven processors leverage centralized sourcing while mid-cap specialists compete on formulation customization and regional distribution agility. Three archetypes dominate: cooperative-owned supply chains controlling quality from farm to aseptic filling line; multinational food conglomerates anchoring portfolios through R&D intensity in stabilized formulations; and regional dairy processors specializing in hot-climate distribution networks. Competitive moves concentrate on automation investments addressing technician shortages and pouch format capacity expansion for food service channel capture.
Within the cooperative tier, Fonterra Co-operative Group and Arla Foods AMBA exemplify structures that integrate raw milk quality control with export logistics into Asian markets. Nestlé S.A. occupies a position representing multinational R&D intensity in stabilized cream formulations. These three anchors illustrate how geographic sourcing bases, cooperative ownership models, and centralized research functions create differentiated competitive positions without overlapping strategic territory.
| Leading Market Players |
|---|
| Fonterra Co-operative Group |
| Danone |
| Nestlé S.A. |
| Land O'Lakes |
| The Kraft Heinz Company |
| FrieslandCampina N.V. |
| Arla Foods AMBA |
| Amul |
| Lactalis Group |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between German dairy cooperatives and food service distributors lock in both raw milk access and price visibility across multi-quarter horizons, insulating processors from spot market volatility while compressing margin buffers for independent operators lacking cooperative backing.
Pricing Analysis
Contract-based long-term offtake dominates procurement between German cooperatives and downstream distributors, with price differentiation resting on volume scale and certification grade under EFSA safety standards. Cost compression in mid-tier dairy processing is intensifying because energy price volatility erodes margin buffers for operators without cooperative financing structures. Food service chains demonstrate highest price sensitivity due to consolidated procurement power, while specialty retailers exhibit lowest sensitivity given premium positioning tolerance.
Supply Chain Analysis
Inventory lead times for aseptic packaging substrates extend procurement cycles as REACH recertification demands force ongoing supplier requalification. Raw material sourcing concentrates in Germany, the Netherlands, and France, with production drawing from specialized membrane filtration equipment, multi-layer barrier films, and stabilized emulsifier systems. Single-source vulnerability in aluminum barrier supply creates structural exposure. Distribution runs through cooperative-owned cold chain networks feeding dense food service distributor partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as food service procurement consolidates around pouch formats, creating niche entry points for packaging specialists and regional processors outside cooperative structures.
For Market Incumbents: Shield margin position by accelerating automation investments addressing technician scarcity across European processing facilities. Deepen backward integration into stabilized emulsifier R&D to counter non-dairy substitution threats in vegan bakery channels. Prioritize pouch format capacity expansion in France and the United Kingdom where chain operators specify single-serve packaging. For New Entrants and Emerging Players: Anchor in hot-climate distribution networks serving interior Chinese provinces where cold chain infrastructure gaps favor shelf-stable formulations. Target specialty stores and online channels bypassing cooperative-dominated wholesale structures. Pursue go-to-market partnerships with membrane filtration technology providers to shortcut lactose-free production capability gaps. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale processors with established REACH-compliant substrate pathways and food service pouch capacity. Long-term viability favors operators with demonstrated export logistics into Asian markets and cooperative financing access. Watch for EU F-Gas Regulation compliance deadlines as inflection indicators accelerating equipment replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| Pouch Format Capacity Expansion | Captures food service procurement consolidation around portion-control packaging in France and UK. |
| Backward Integration into Emulsifier R&D | Secures formulation autonomy for hot-climate distribution networks lacking cold chain infrastructure. |
| Lower-Emission Refrigeration Retrofit | Qualifies German and Dutch processors for EU Green Deal sustainability-linked financing instruments. |
| Long-Term Supply Agreement with Barrier Film Suppliers | Insulates against REACH recertification cycles disrupting aseptic packaging substrate availability. |
| Direct-to-Food-Service Platform Launch | Bypasses cooperative wholesale structures consolidating procurement around single-serve specifications. |
Research Methodology
Desk research of dairy cooperative annual reports, EFSA safety filings, and EU customs trade data preceded structured interviews with plant operations managers, food service procurement directors, packaging substrate suppliers, and cold chain logistics coordinators. Primary fieldwork with German and Dutch processors validated secondary data on automation investment timelines and F-Gas compliance schedules. Bottom-up volume modeling across product type, packaging format, and end-use segments triangulated against top-down macro dairy consumption trends.
Variance decomposition across the projection horizon isolates drivers including bakery chain expansion rates, pouch format penetration curves, and non-dairy substitution velocity. Segmentation dimensions modeled encompass product formulation, packaging barrier properties, distribution channel economics, and regional cold chain infrastructure maturity. CAGRs were derived from slope analysis of historical dairy processing capacity additions projected against food service demand elasticity. Industry-specific inputs include ECHA substrate approval timelines and cooperative financing structure prevalence.
Material uncertainties — refrigerant phase-down schedule acceleration, REACH barrier material rule evolution, and Asian import tariff adjustments — sit outside the modeled envelope. Forecasts reflect assumptions about technician training pipeline recovery and energy price stabilization. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Condensed Milk Market
Dairy Products
US Yogurt and Probiotic Drink Market
Dairy Products
India Dairy Market
Dairy Products
Ultra High Temperature Milk Market
Dairy Products
Dairy Blends Market
Dairy Products
Processed Cheese Market
Dairy Products
North America Dairy Desserts Market
Dairy Products
North America Cheese Market
Dairy Products
Sweet Whey Market
Dairy Products
Natural Cheese Market
Dairy Products
Oman Dairy Products and Juice Market
Dairy Products
Mascarpone Cheese Market
Dairy Products
Dairy Products Market
Dairy Products
Canada Milk Protein Market
Dairy Products
Yogurt Drink Market
Dairy Products
Europe Flavored Milk Market