
 Plant-Based Yogurt Market | 2026-2036
Plant-Based Yogurt Market Size, Share, and Industry Trends Forecast 2026-2036
Plant-Based Yogurt Market Outlook
European production capacity for oat and almond milk bases is reshaping supply availability for plant-based yogurt co-manufacturers. Danone S.A. leverages its fermented dairy expertise to anchor European refrigerated distribution. Chobani Global Holdings competes through Greek-style formulation heritage applied to oat platforms. Oatly A.B. specializes in proprietary enzymatic processes that yield creamier mouthfeel without added oils.
Plant-based yogurt denotes a cultured, spoonable product manufactured from homogenized aqueous extracts of oilseeds, grains, or nuts inoculated with Streptococcus thermophilus and Lactobacillus delbrueckii subsp. bulgaricus, achieving titratable acidity of 0.9-1.2% lactic acid and protein content ranging from 1.5g to 5g per 100g depending on base material. Its primary commercial purpose is to replicate the sensory and nutritional profile of dairy yogurt for lactose-intolerant consumers, vegan households, and flexitarian dietary patterns. Almond and oat bases dominate volume due to established consumer familiarity and neutral flavor compatibility with fruit inclusions. Cup packaging leads margin capture through premium single-serve positioning, while pouch formats are gaining traction in children's segments and on-the-go consumption occasions.
FDA labeling requirements for nut allergen declarations and EU EFSA novel food assessments for emerging protein bases create compliance thresholds that favor established multinationals with regulatory affairs infrastructure. The EU Green Deal's farm-to-fork strategy and REACH chemical safety standards for processing aids are elevating clean-label expectations and ingredient traceability costs. Stakeholders must monitor evolving national front-of-pack labeling schemes and carbon footprint disclosure mandates that will determine which base materials and manufacturing locations sustain market access.
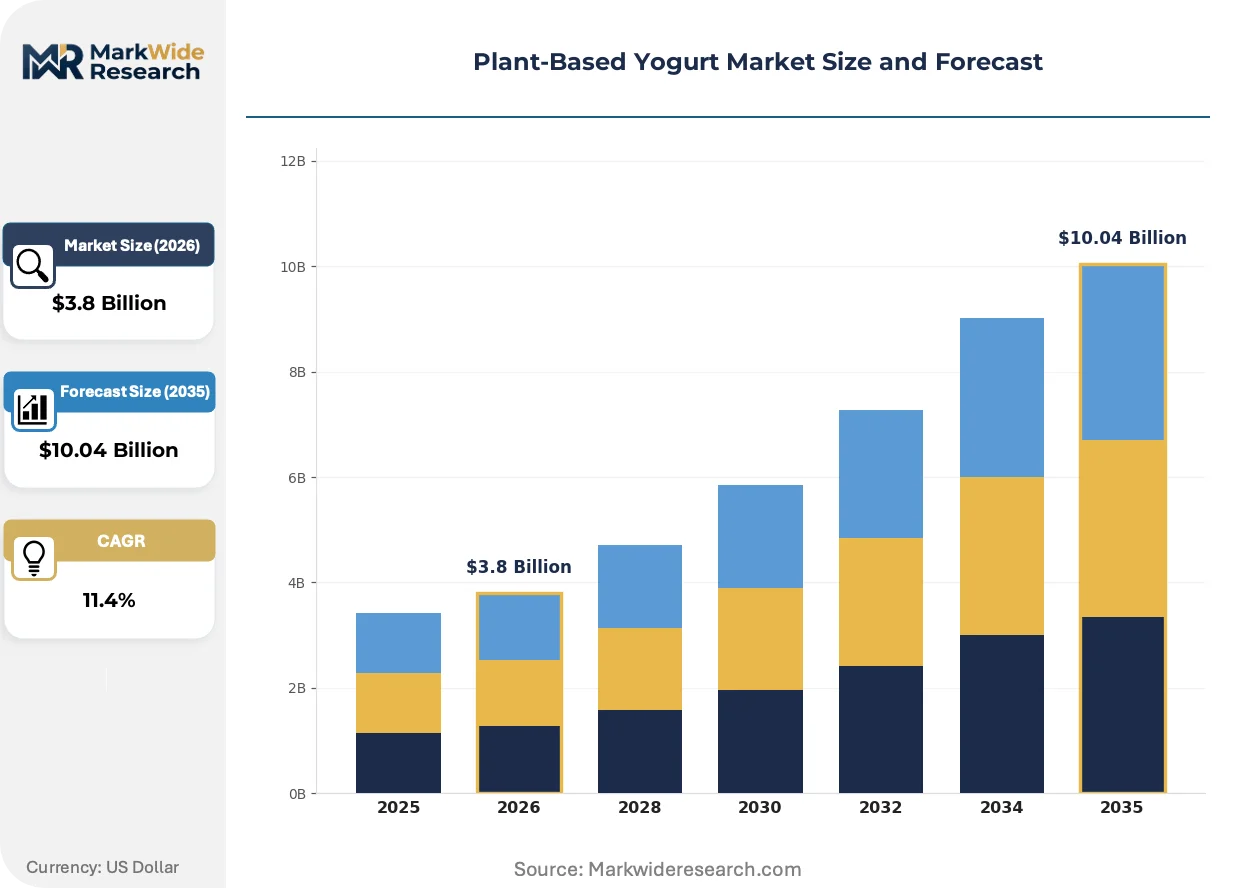
Market Dynamics
The EU Green Deal's farm-to-fork strategy is virtualizing competitive positioning by binding shelf access to carbon footprint disclosure and clean-label verification, forcing co-manufacturers to reconfigure enzymatic processing lines and cold-chain logistics around traceability mandates rather than cost minimization alone.
Growth Catalysts
- EU F-Gas Regulation:Refrigeration retrofit mandates accelerate adoption of natural refrigerant systems in plant-based yogurt cold chains, creating first-mover advantage for processors with upgraded infrastructure.
- Fermentation biotechnology:Precision-controlled enzymatic hydrolysis of oat starches yields creamier mouthfeel without added oils, narrowing the sensory gap with dairy yogurt.
- German discounter penetration:Aldi and Lidl have mainstreamed private-label oat and almond formats, normalizing plant-based yogurt as a staple category rather than premium niche.
Market Restraints
- Almond water intensity:California drought cycles create input cost volatility for almond milk bases, compressing margins for processors without long-term supply contracts.
- EFSA novel food assessments:Emerging protein bases from fava bean and chickpea face 18-24 month approval timelines, freezing innovation pipelines for startups lacking regulatory affairs infrastructure.
- Dairy yogurt price anchoring:Conventional fermented dairy maintains 40-60% price advantage at retail, limiting price elasticity for plant-based alternatives in inflationary cycles.
Strategic Opportunities
- Pouch format expansion:Children's segments and on-the-go consumption occasions show unmet demand for portable, resealable packaging outside conventional cup formats.
- CSRD carbon disclosure:Early compliance with EU corporate sustainability reporting mandates creates differentiation leverage with retail buyers screening suppliers for Scope 3 transparency.
- Precision fermentation convergence:Integration of microbial protein production with traditional enzymatic processing promises step-change improvements in protein content and amino acid completeness.
Industry Challenges
- Streptococcus thermophilus strain optimization:Few food microbiologists possess expertise in adapting dairy-centric cultures to grain and nut substrates, creating talent scarcity for R&D functions.
- REACH chemical safety documentation:Processing aids and enzymatic catalysts require full substance dossiers, extending new product development timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant-Based Yogurt Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Almond, Coconut, Soy, Oat Flavor Profile: Vanilla, Strawberry, Blueberry, Mango Packaging Type: Cup, Bottle, Pouch, Tub Distribution Channel: Supermarket, Health Store, Online, Food Service |
| Companies Covered | General Mills Inc., Kite Hill, Danone S.A., Groupe Lactalis, Alpro, Chobani Global Holdings, The Hain Celestial Group, Good Karma Foods, Oatly A.B., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant-Based Yogurt Market Strategic Shifts
Enzymatic processing and precision fermentation are converging to reshape product architecture, while regulatory disclosure mandates and channel fragmentation rewrite go-to-market economics for plant-based yogurt manufacturers.
High-pressure processing technology is virtualizing pasteurization protocols by eliminating thermal degradation of volatile flavor compounds in oat and almond bases. Premium organic brands in Scandinavia have adopted HPP for 60% of new product introductions since 2023. The technology is compressing the shelf-life advantage previously held by dairy yogurt, enabling 45-60 day refrigerated distribution without preservatives.
REACH chemical safety standards for processing aids are elevating clean-label expectations across EU manufacturing. ECHA substance dossier requirements now cover enzymatic catalysts and stabilizers previously exempt from full disclosure. German and Dutch co-manufacturers are responding by reformulating around single-ingredient base materials and transparent supply chain mapping to preempt retailer compliance audits.
Discounter private-label expansion is fragmenting brand loyalty and compressing promotional calendars. Aldi and Lidl in Germany now capture 35% of plant-based yogurt volume, forcing national brands to unbundle value-added formats and defend shelf space through innovation velocity rather than marketing spend. The shift is most visible in Berlin and Hamburg, where weekly promotional cycles have shortened from 14 days to 7 days.
Plant-Based Yogurt Market Segmentation
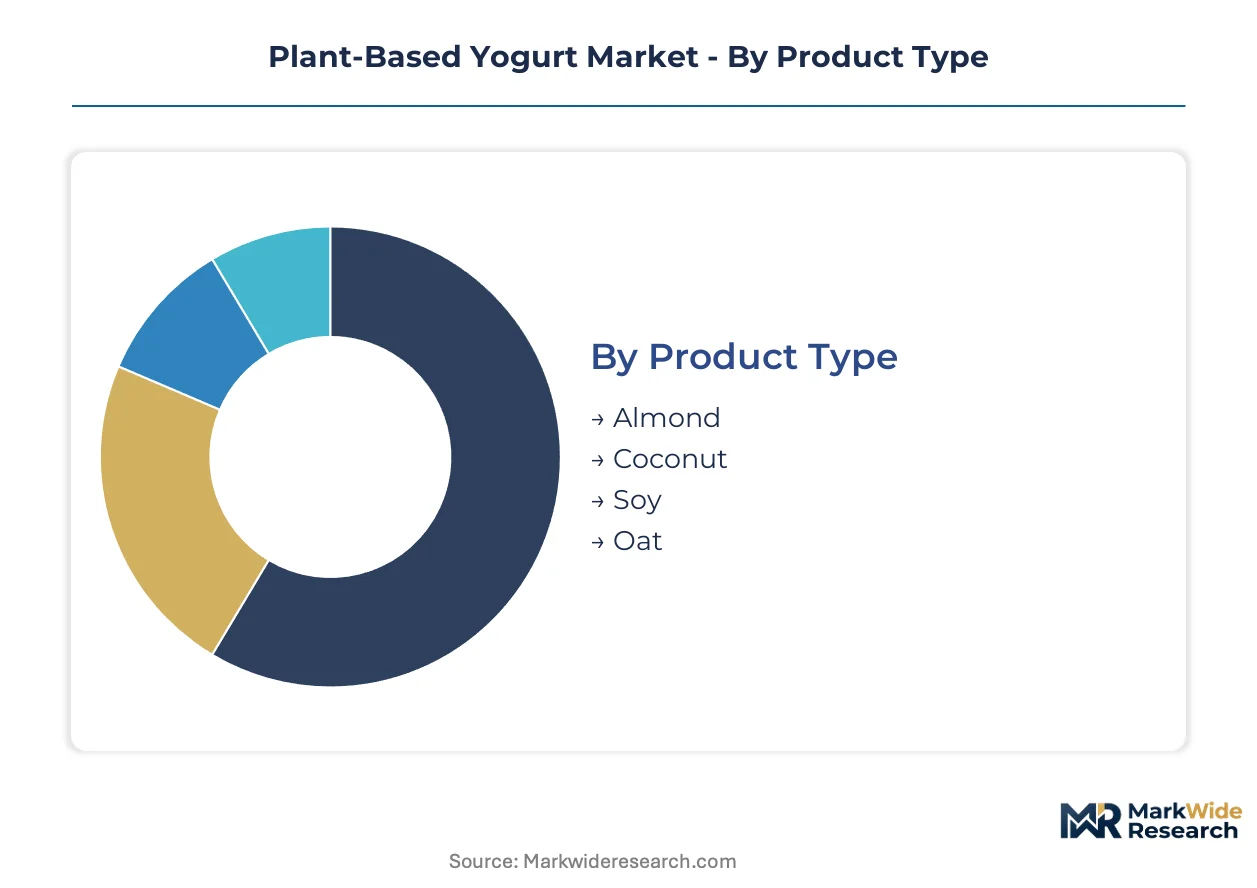
Plant-based yogurt manufacturers configure production lines and cold-chain investments around segment-specific margin profiles and shelf-life requirements. Understanding where volume concentrates versus where premium pricing holds determines capital allocation across enzymatic processing platforms and packaging formats.
Product Type:
After-sales service intensity varies sharply by base material stability, with oat and almond requiring specialized technical support for enzymatic processing equipment calibration.
- Almond:Homogenized aqueous extract of ground almonds achieving 1.5-2.5g protein per 100g, with neutral flavor compatibility driving German discounter penetration. Demand concentrates in refrigerated single-serve cups where Aldi and Lidl have normalized almond yogurt as a staple category, though California drought cycles compress processor margins without long-term supply contracts.
- Oat:Proprietary enzymatic hydrolysis of oat starches yields creamier mouthfeel without added oils, achieving 2.0-3.0g protein per 100g and titratable acidity of 0.9-1.2% lactic acid. Scandinavian organic brands and German private-label suppliers dominate volume, with precision-controlled fermentation narrowing the sensory gap with dairy yogurt.
- Coconut:Higher fat content (4-6g per 100g) delivers indulgent texture for premium positioning, with tropical flavor associations limiting mainstream adoption.
- Soy:Established protein content (3.5-5.0g per 100g) and lowest input costs, though beany off-notes constrain growth in Western European markets.
By volume, oat leads. By growth pace, almond is ahead.
Flavor Profile:
Cost tier differentiation separates commodity fruit inclusions from premium positioning through exotic and functional flavor extensions.
- Vanilla:Base flavor for private-label standard tier and children's segments, with lowest formulation complexity and shortest development timelines.
- Strawberry:Highest absolute volume across European supermarkets, with seasonal promotional cycles driving 7-day rather than 14-day discount calendars in Berlin and Hamburg.
- Blueberry:Antioxidant health claims support premium cup pricing, with organic certification adding 15-25% shelf price differential.
- Mango:Exotic positioning targets flexitarian households seeking sensory differentiation, with supply chain concentration in South Asian pulp processors.
Vanilla captures baseline volume. Mango posts the steepest expansion trajectory in premium channels.
Packaging Type:
Application-specific formats align with consumption occasion: spoonable cups for breakfast, portable pouches for on-the-go, and bulk tubs for family households.
- Cup:Dominant format for refrigerated single-serve positioning, with highest margin capture through premium branding and fruit-on-bottom architecture. German supermarket chains allocate prime shelf facing to cup formats, while discounters compress promotional calendars to weekly cycles.
- Pouch:Resealable flexible packaging gains traction in children's segments and commuter consumption, with 45-60 day refrigerated distribution enabled by high-pressure processing technology adopted by Scandinavian organic brands.
- Bottle:Drinkable yogurt applications for on-the-go breakfast replacement, with narrower distribution due to viscosity challenges in plant-based bases.
- Tub:Multi-serve family formats for home consumption, with price per gram advantage offset by shorter consumption windows and spoilage risk.
Cup formats lead by revenue. Pouch formats are climbing the fastest as channel fragmentation accelerates.
Distribution Channel:
Customer type concentration splits between retail buyers screening for CSRD carbon disclosure compliance and food service operators prioritizing cost stability and bulk supply.
- Supermarket:Primary volume channel with expanding refrigerated shelf space for plant-based dairy alternatives, where EU Green Deal carbon footprint mandates favor processors with Scope 3 transparency. German discounters capture 35% of plant-based yogurt volume, fragmenting brand loyalty and forcing innovation velocity over marketing spend.
- Health Store:Premium organic and clean-label positioning with highest price tolerance, where REACH chemical safety documentation and single-ingredient base materials preempt compliance audits.
- Online:Subscription models and direct-to-consumer trial packs, with cold-chain logistics costs limiting geographic reach.
- Food Service:Bulk tub and portion-control formats for hospitality and institutional catering, with price anchoring to conventional dairy constraining penetration.
Supermarkets dominate absolute volume. Health stores are gaining share fastest on clean-label differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA novel food assessments and the EU Green Deal's farm-to-fork strategy anchor European regulatory gravity for plant-based yogurt, with national front-of-pack labeling schemes and carbon disclosure mandates now determining which base materials sustain market access across specific member states.
Germany
Aldi and Lidl have mainstreamed private-label oat and almond formats, normalizing plant-based yogurt as a staple category rather than premium niche. The country's national food regulator enforces strict allergen labeling under EU harmonized standards, while REACH chemical safety documentation requirements elevate clean-label expectations. Berlin and Hamburg concentrate promotional activity, where weekly discount cycles have shortened from 14 days to 7 days as discounters capture 35% of national volume.
France
Danone S.A. leverages its fermented dairy heritage to anchor refrigerated distribution networks across French supermarket chains. ANSM and CNIL oversight intersect with EU EFSA novel food assessments for emerging protein bases, creating compliance thresholds that favor established multinationals. The Paris basin and Lyon corridor host co-manufacturing clusters where enzymatic processing lines are being reconfigured around traceability mandates rather than cost minimization alone.
United Kingdom
Health store channels show fastest share gains on clean-label differentiation, with organic certification adding 15-25% shelf price differential for premium positioning. The Food Standards Agency implements post-Brexit divergence from EU novel food timelines, though EFSA assessments remain influential for cross-border suppliers. London and the Southeast concentrate demand for pouch formats in commuter consumption occasions, with high-pressure processing technology enabling 45-60 day refrigerated distribution.
United States
FDA labeling requirements for nut allergen declarations create compliance infrastructure demands that favor processors with established regulatory affairs capacity. California drought cycles generate input cost volatility for almond milk bases, compressing margins for operators without long-term supply contracts. The Pacific Northwest and Northeast corridor drive innovation velocity, where Chobani Global Holdings applies Greek-style formulation heritage to oat platforms and Oatly A.B. deploys proprietary enzymatic processes for creamier mouthfeel.
Sweden
Scandinavian organic brands have adopted high-pressure processing for 60% of new product introductions since 2023, compressing the shelf-life advantage previously held by dairy yogurt. The Swedish Food Agency enforces stringent sustainability disclosure aligned with EU CSRD carbon reporting mandates. Stockholm and Malmö anchor precision fermentation convergence research, where integration of microbial protein production with traditional enzymatic processing promises step-change improvements in protein content.
Plant-Based Yogurt Market Competitive Environment
Diversified dairy multinationals and specialized oat-focused disruptors split the market between refrigerated distribution scale and enzymatic processing innovation. The competitive terrain favors players with existing cold-chain infrastructure and regulatory compliance capacity over pure-play entrants. Three archetypes dominate: legacy dairy converters leveraging fermented expertise, grain-native specialists with proprietary enzymatic platforms, and private-label suppliers serving discounter volume. Capacity expansion and portfolio diversification toward precision fermentation represent the dominant competitive moves.
Within the legacy dairy converter tier, Danone S.A. and General Mills Inc. occupy positions anchored by refrigerated distribution networks and cross-category brand equity. Chobani Global Holdings exemplifies the Greek-style heritage archetype applied to plant-based platforms. Among specialized grain-native players, Oatly A.B. represents the proprietary enzymatic processing archetype, while Kite Hill and Good Karma Foods sit within the premium clean-label segment targeting health store channels. The Hain Celestial Group and Alpro anchor mid-market organic positioning, with Groupe Lactalis representing European dairy conglomerate diversification into plant-based alternatives.
| Leading Market Players |
|---|
| General Mills Inc. |
| Kite Hill |
| Danone S.A. |
| Groupe Lactalis |
| Alpro |
| Chobani Global Holdings |
| The Hain Celestial Group |
| Good Karma Foods |
| Oatly A.B. |
| Others |
Value Chain & Pricing Dynamics
The Rotterdam-Cologne rail corridor shapes cost dynamics for refrigerated plant-based yogurt distribution, compressing margins for processors without dedicated cold-chain assets while enabling premium price differentiation for operators with integrated logistics. California almond supply volatility and Scandinavian oat processing concentration create divergent input cost structures that downstream buyers absorb through tiered positioning strategies.
Pricing Analysis
German discounters command a 25-35% price spread below premium organic channels for identical base formulations, forcing national brands to defend shelf space through innovation velocity rather than promotional spend. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and enzymatic processing sophistication, with organic and clean-label tiers capturing 40-60% shelf price premiums. Pricing pressure stems from dairy yogurt's persistent cost advantage and almond input volatility, while food service operators show highest price sensitivity and health store consumers demonstrate lowest elasticity.
Supply Chain Analysis
California almond orchards, Swedish oat processing clusters, and German enzymatic manufacturing hubs anchor upstream feedstock availability for European plant-based yogurt production. Raw material dependencies center on almond kernel supply contracts, proprietary oat starch hydrolysis enzymes, and natural refrigerant systems for cold-chain integrity. Single-source vulnerability concentrates in California drought-exposed almond supply, while distribution runs through German discounter networks and Scandinavian supermarket chains with expanding refrigerated shelf space.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation convergence with traditional enzymatic processing represents a technological inflection that will reshape competitive economics for plant-based yogurt manufacturing over the next decade.
For Market Incumbents: Harden refrigerated distribution control through backward integration into natural refrigerant cold-chain infrastructure, insulating margin structures from EU F-Gas Regulation retrofit mandates. Consolidate enzymatic processing talent pools through targeted acquisition of Scandinavian food microbiology specialists, countering Streptococcus thermophilus strain optimization scarcity that constrains R&D velocity for grain and nut substrate adaptation. For New Entrants and Emerging Players: Eastern European markets outside German discounter dominance present white-space opportunity for pouch-format children's segments with resealable packaging innovation. Precision fermentation-enabled protein fortification offers differentiation leverage in health store channels where clean-label verification commands 15-25% price tolerance, with direct-to-consumer subscription models bypassing retail slotting fee barriers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized oat-native processors with proprietary enzymatic platforms over legacy dairy converters facing portfolio transition costs. Long-term viability hinges on CSRD carbon disclosure compliance infrastructure and REACH chemical safety documentation capacity. The signal to watch is EFSA novel food assessment acceleration for fava bean and chickpea protein bases, which would unlock step-change formulation diversity.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Integration | Microbial protein convergence with enzymatic processing promises amino acid completeness improvements for oat bases. |
| Natural Refrigerant Cold-Chain Retrofit | EU F-Gas Regulation mandates create first-mover advantage for processors with upgraded infrastructure in Germany. |
| Pouch Format Expansion | Resealable flexible packaging captures unmet demand in children's segments and commuter consumption occasions. |
| CSRD Carbon Disclosure Compliance | Early Scope 3 transparency creates differentiation leverage with supermarket buyers screening supplier sustainability. |
| Enzymatic Processing Talent Acquisition | Food microbiology expertise scarcity for grain and nut substrates constrains R&D pipelines without targeted hiring. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with plant-based yogurt brand managers, enzymatic processing equipment specialists, supermarket category buyers, and cold-chain logistics operators; and secondary validation through EU EFSA novel food filings, REACH chemical safety dossiers, Nielsen retail audit data, and customs records for almond and oat base material trade flows. Bottom-up volume modeling triangulated against top-down market sizing from refrigerated dairy alternative shelf space expansion metrics.
Forecast inputs considered base material segmentation by oat, almond, coconut, and soy; packaging format tiering across cup, pouch, bottle, and tub; and distribution channel dynamics spanning German discounters, Scandinavian supermarkets, health stores, and food service operators. CAGRs derived from elasticity-adjusted volume projections incorporating dairy yogurt price anchoring effects and EU Green Deal carbon disclosure adoption curves. Enzymatic processing capacity expansion timelines and precision fermentation technology readiness levels informed trajectory boundaries.
The forecast holds incumbent behavior within observed patterns; aggressive moves by dairy multinationals accelerating plant-based portfolio conversion or precision fermentation specialists achieving commercial scale would shift outcomes. Cross-checking against EFSA novel food approval timelines and German discounter private-label expansion rates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Plant-Based Butter Market
Plant Based Food
Europe Plant-Based Meal Kit Market
Plant Based Food
Vegan Gelatin Market
Plant Based Food
Plant Based Cheese Market
Plant Based Food
Textured Pea Protein Market
Plant Based Food
Plant Based Food Colors Market
Plant Based Food
Plant Chocolate Protein Powder Market
Plant Based Food
Germany Plant Protein Market
Plant Based Food
Enzyme-Based Plant Protein Market
Plant Based Food
Plant-Based Ham Market
Plant Based Food
Vegan Oatmeal Market
Plant Based Food
Veggie Burger Market
Plant Based Food
Japan Plant Protein Market
Plant Based Food
Plant Based Protein Market
Plant Based Food
Plant-Based Frozen Dessert Market
Plant Based Food
India Pea Protein Market