
 Automotive Adaptive Cruise Control Market | 2026-2036
Automotive Adaptive Cruise Control Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Adaptive Cruise Control Market Intelligence
OEM procurement channels for advanced driver-assistance systems is rewriting how tier-1 suppliers secure long-term program wins. Bosch leverages its integrated sensor-to-software stack to dominate highway-speed radar deployments. Continental sustains competitive pressure through deep manufacturing scale across European and North American assembly networks.
Automotive adaptive cruise control constitutes an intelligent vehicle speed management system that modulates throttle, braking, and transmission inputs through fused sensor arrays—typically combining 77 GHz radar modules, mono or stereo cameras, and ultrasonic proximity detectors—to maintain operator-set velocities while dynamically adjusting headway to preceding traffic. The technology serves the primary commercial purpose of reducing driver workload during sustained cruising and mitigating rear-end collision frequency on high-speed roadways. Radar-based architectures anchor current revenue pools given their proven all-weather reliability and established cost curves, while camera-based fusion systems represent the fastest-expanding segment as convolutional neural networks enhance object classification precision. Electric vehicles constitute a concentrated demand vector where adaptive cruise integration supports brand differentiation in premium battery-electric platforms.
The National Highway Traffic Safety Administration mandates automatic emergency braking on new light vehicles in the United States, effectively normalizing the sensor infrastructure that enables adaptive cruise functionality. The European Union's General Safety Regulation extends similar requirements across EU member states, compelling OEMs to standardize longitudinal control systems. Stakeholders must monitor how cybersecurity certification under UN R155 reshapes supplier qualification timelines and software update protocols.
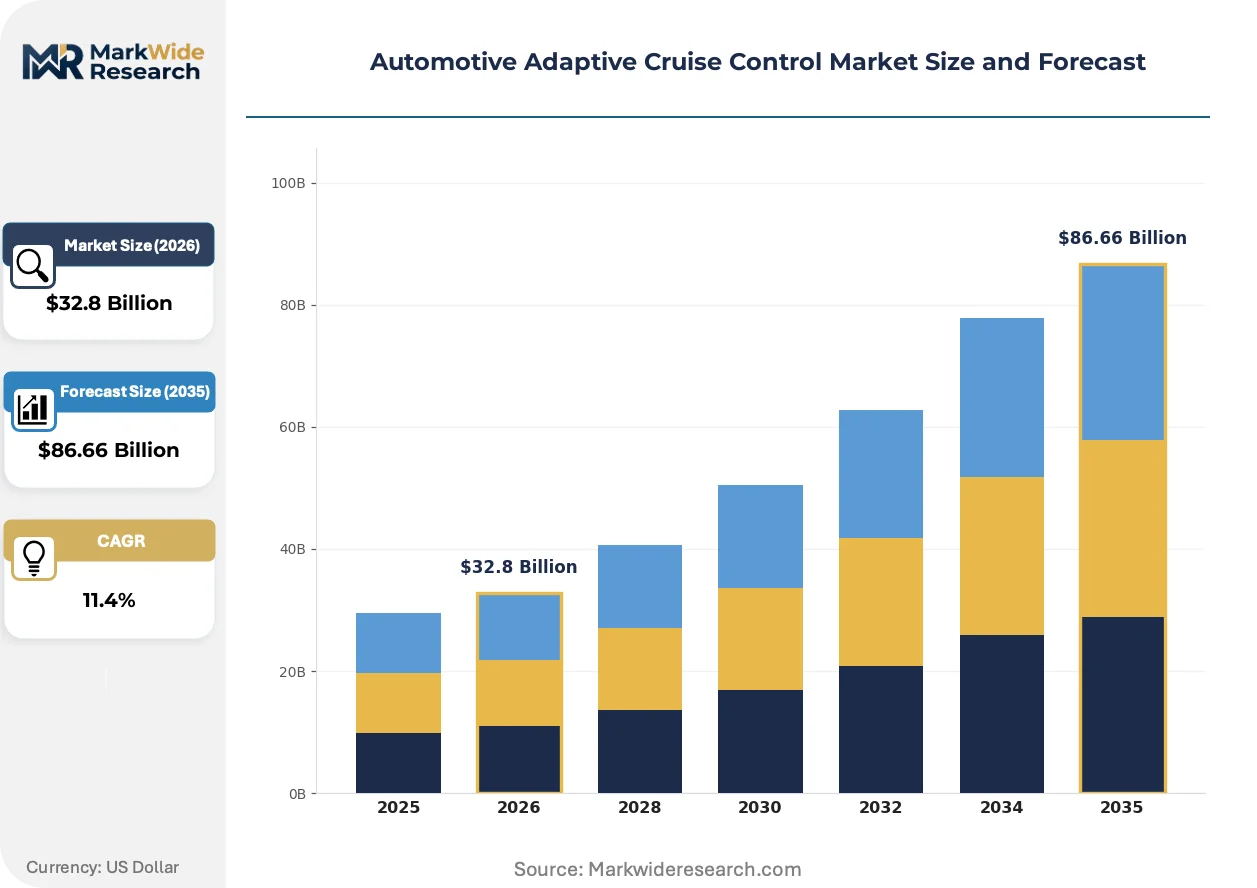
Market Dynamics
Radar-to-camera sensor fusion is compressing development cycles as passenger vehicle OEMs consolidate longitudinal control architectures under unified domain controllers. This technical consolidation is redrawing competitive boundaries between semiconductor suppliers and tier-1 system integrators.
Growth Catalysts
- UN R155 cybersecurity certification:The UN regulation mandates software update protocols and security management systems for vehicles, compelling OEMs to standardize over-the-air update infrastructure that supports adaptive cruise control calibration.
- 77 GHz radar cost curves:Semiconductor foundries in Taiwan and Germany have achieved 40% die-size reductions through advanced packaging, enabling mid-market vehicle segments to adopt highway-speed radar systems previously reserved for premium platforms.
- Electric vehicle platform differentiation:Battery-electric OEMs in China and South Korea bundle adaptive cruise with regenerative braking coordination as a standard feature, creating baseline consumer expectations that propagate across powertrain categories.
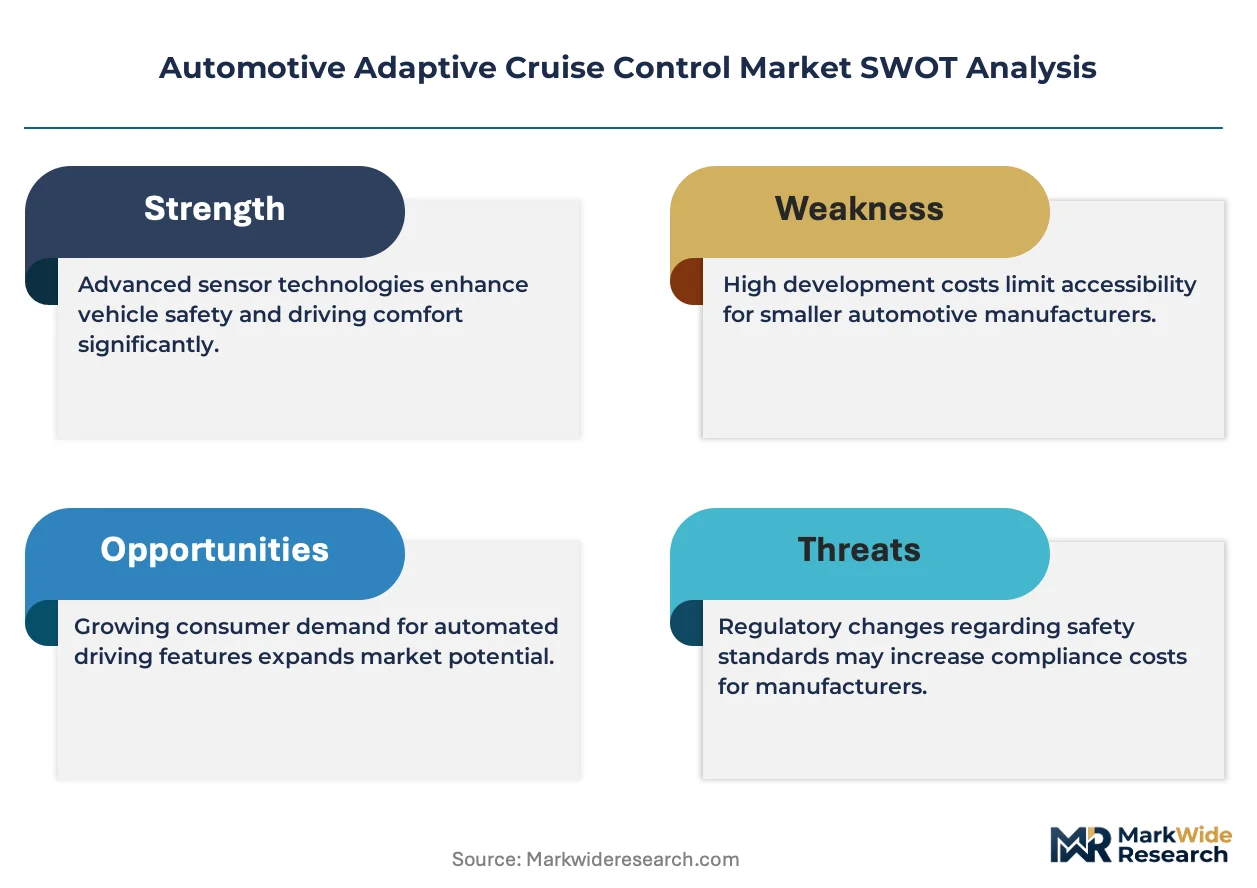
Market Restraints
- LiDAR substitution threat:Solid-state LiDAR arrays from Israeli and Chinese suppliers are penetrating highway-speed applications, threatening to displace radar-centric architectures in premium segments within five years.
- Semiconductor supply concentration:77 GHz radar front-end modules depend on gallium arsenide foundry capacity concentrated in Taiwan, exposing procurement schedules to geopolitical friction and export control volatility.
- Firmware validation bottlenecks:ISO 26262 functional safety certification for sensor fusion algorithms extends development timelines by 14-18 months, compressing window for model-year integration.
Strategic Opportunities
- India PLI scheme for automotive electronics:The Production Linked Incentive scheme subsidizes local manufacturing of advanced driver-assistance sensors, creating first-mover advantage for suppliers establishing radar assembly in Tamil Nadu and Gujarat.
- Truck platooning convergence:Vehicle-to-vehicle communication protocols are hybridizing with adaptive cruise architectures to enable coordinated braking in commercial freight corridors across Germany and the United States.
- Aftermarket retrofit channels:Independent garages in Brazil and Mexico are developing camera-based retrofit kits for vehicle fleets, bypassing OEM-controlled distribution and capturing commercial vehicle operators seeking compliance with evolving insurance requirements.
Industry Challenges
- Sensor fusion algorithm talent scarcity:OEMs and tier-1 suppliers compete for machine learning engineers with specific expertise in temporal sensor alignment and occlusion handling, with compensation premiums reaching 35% above general automotive software roles.
- Legacy CAN bus integration friction:Older vehicle architectures lack the data bandwidth and deterministic latency required for fused sensor arrays, forcing expensive gateway module redesigns or feature degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Adaptive Cruise Control Market |
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $86.66 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Radar Based, Lidar Based, Camera Based, Ultrasonic Sensors, GPS Assisted Vehicle Type: Passenger Cars, Light Commercial Vehicles, Heavy Trucks, Electric Vehicles Application: Highway Driving, Urban Traffic, Stop-and-Go Traffic, Collision Avoidance, Lane Keeping Support End User: OEMs, Tier-1 Suppliers, Vehicle Assemblers, Aftermarket Providers |
| Companies Covered | Denso, Valeo, Bosch, Mobileye, Magna International, Continental, Aptiv, Autoliv, ZF Friedrichshafen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Adaptive Cruise Control Market Strategic Shifts & Innovations
Convolutional neural networks are replacing heuristic control algorithms in headway management systems, enabling predictive responses to cut-in vehicles and degraded lane markings. This computational shift is redefining hardware-software boundaries across the supplier ecosystem.
Imaging radar architectures are hybridizing 4D point-cloud generation with dense velocity mapping to resolve the ghost-object problem that has limited pure radar systems in cluttered urban environments. Premium OEMs in Germany and Japan are adopting these modules for stop-and-go traffic functionality previously requiring camera confirmation. The technology is hybridizing cost structures by reducing the sensor count required for SAE Level 2+ certification.
REACH chemical restrictions on solder materials and flame-retardant substrates are forcing radar module suppliers to requalify printed circuit board laminates and thermal interface compounds. The European regulation's industrial consequence extends to Asian contract manufacturers serving European OEM export programs. Module suppliers in South Korea and Taiwan are accelerating halogen-free substrate qualification to maintain EU market access.
Fleet operators are consolidating procurement decisions at the holding-company level rather than delegating to individual brand purchasing departments, compressing supplier negotiation cycles and favoring multi-brand platform contracts. This concentration is displacing the traditional tier-1 direct-to-OEM model in North American and European commercial vehicle segments. The shift is most visible in long-haul trucking where logistics conglomerates specify uniform driver-assistance specifications across mixed-brand fleets.
Automotive Adaptive Cruise Control Market Segmentation
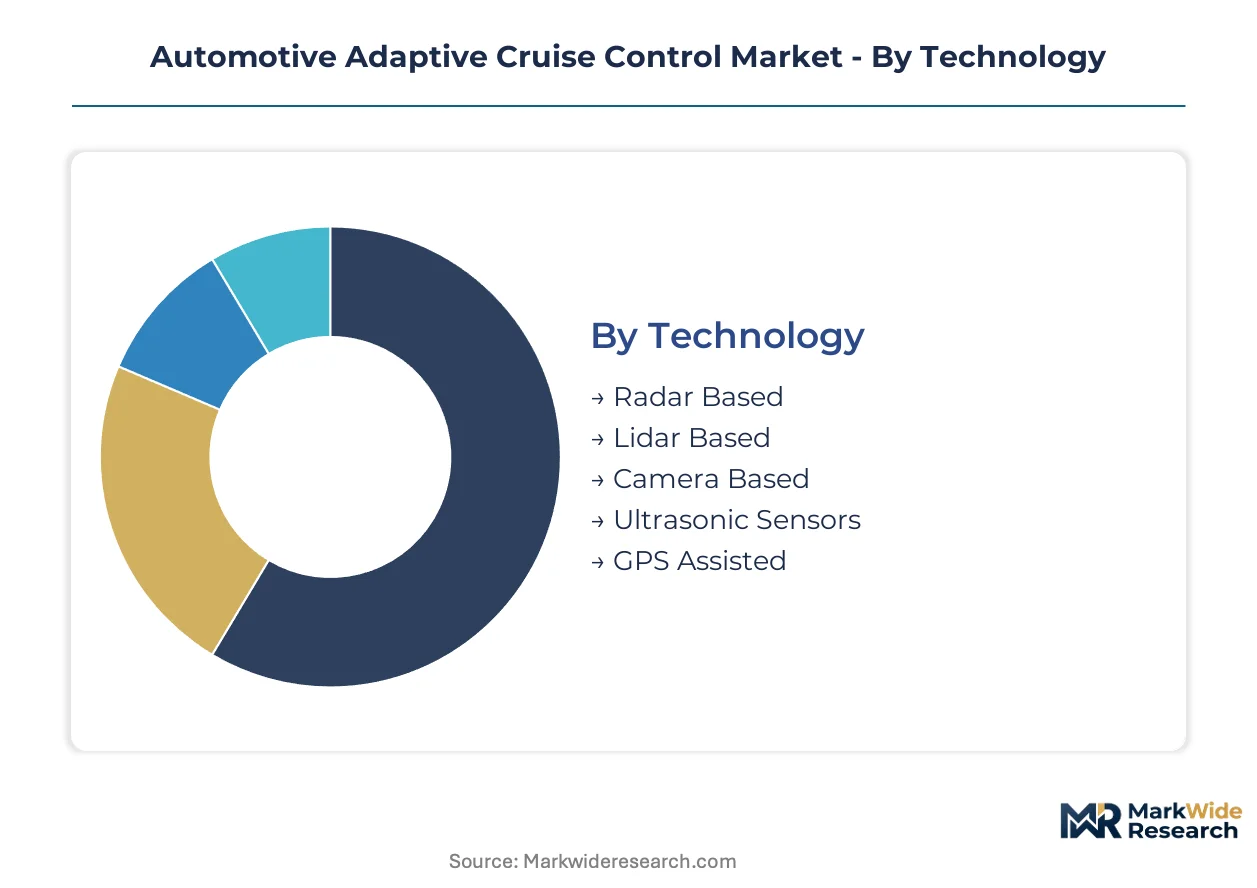
Adaptive cruise control architectures fragment across sensor modalities, vehicle platforms, and operational domains. Procurement patterns diverge sharply between OEM-integrated highway systems and aftermarket urban retrofit kits.
Technology:
Use-case spectrum spans all-weather reliability through precision ranging to cost-optimized proximity detection.
- Radar Based:77 GHz front-end modules deliver velocity-independent object detection through precipitation and darkness. German and Japanese OEMs specify these for highway-speed longitudinal control where NHTSA mandates automatic emergency braking compatibility.
- Camera Based:Convolutional neural networks process mono or stereo optical arrays for lane marking interpretation and cut-in vehicle prediction. South Korean battery-electric platforms bundle camera fusion as standard equipment, compressing cost curves through semiconductor integration.
- Lidar Based:Solid-state arrays from Israeli suppliers penetrate premium highway applications.
- Ultrasonic Sensors:Parking-proximity heritage limits deployment to low-speed stop-and-go functionality.
- GPS Assisted:Map-correlated speed limit adaptation sees niche adoption in luxury German nameplates.
The dominant share belongs to Radar Based, while Camera Based is closing the gap fastest.
Vehicle Type:
Cost tier stratification separates premium integration from fleet-standard specifications.
- Passenger Cars:Mid-market sedans and crossovers represent volume concentration as UN R155 cybersecurity certification forces standardized over-the-air update infrastructure across mass-production nameplates.
- Electric Vehicles:Battery-electric architectures exploit regenerative braking coordination to differentiate driver-assistance experiences. Chinese OEMs bundle adaptive cruise as baseline equipment, establishing consumer expectations that propagate to internal-combustion segments.
- Light Commercial Vehicles:Fleet procurement consolidation at holding-company level favors multi-brand platform contracts.
- Heavy Trucks:Platooning protocols in German freight corridors drive vehicle-to-vehicle communication hybridization.
Passenger Cars command the largest installed base, though Electric Vehicles demonstrate the steepest expansion trajectory.
Application:
Volume concentrates where regulatory mandates intersect with measurable collision reduction.
- Highway Driving:Sustained-speed cruising generates the primary commercial purpose for throttle and transmission modulation. United States interstate corridors and German autobahn networks anchor procurement specifications for radar-dominant systems.
- Stop-and-Go Traffic:Imaging radar with 4D point-cloud generation resolves ghost-object detection without camera confirmation. Japanese premium OEMs deploy these modules for urban congestion automation.
- Urban Traffic:Cluttered environments strain pure radar classification accuracy.
- Collision Avoidance:Automatic emergency braking mandates normalize underlying sensor infrastructure.
- Lane Keeping Support:Lateral control integration demands camera-radar fusion calibration.
Highway Driving retains the dominant deployment share, yet Stop-and-Go Traffic is gaining share fastest.
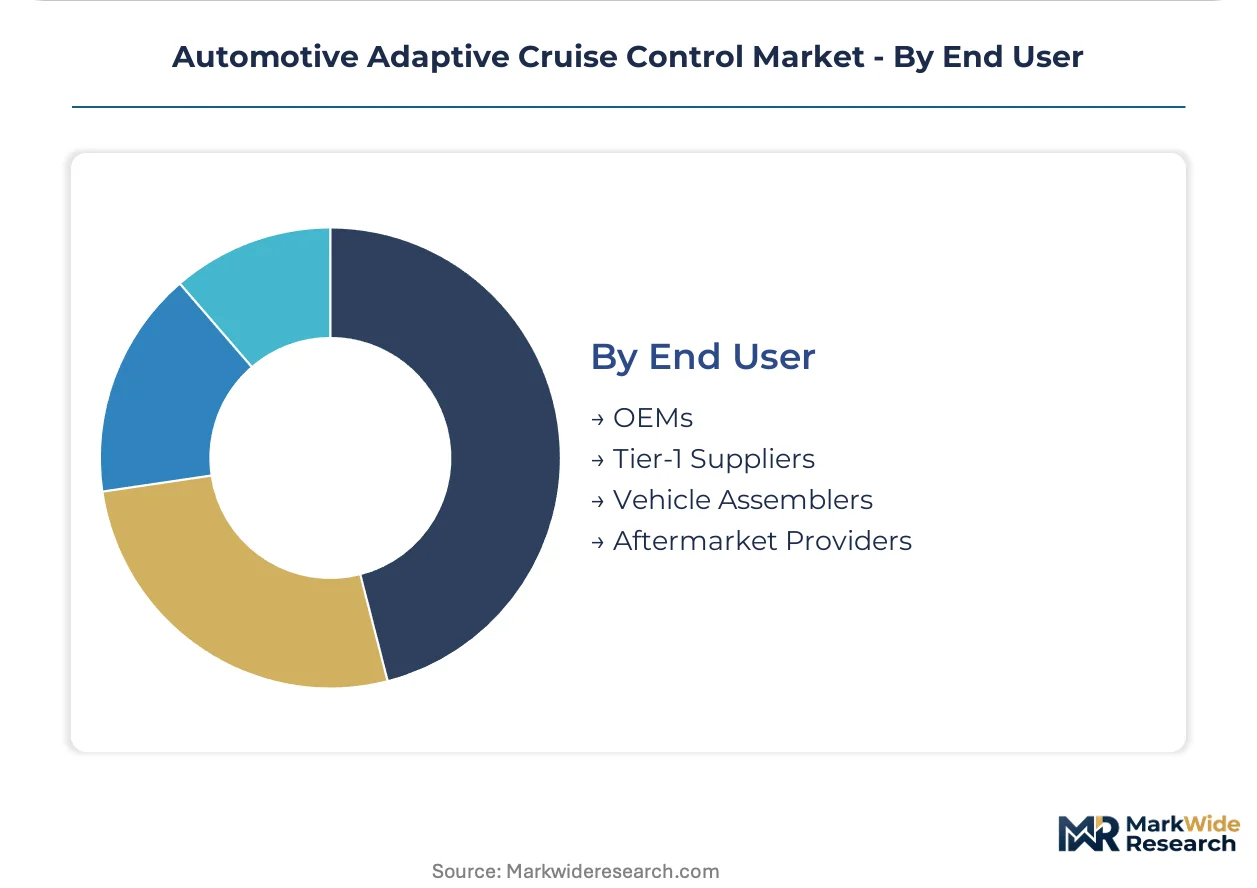
End User:
Supply concentration shapes margin capture across the value chain.
- OEMs:Brand-differentiated feature packaging drives direct procurement of domain-controller-integrated systems. European and North American assembly networks specify Bosch and Continental for long-term program wins.
- Aftermarket Providers:Independent garages in Brazil and Mexico develop camera-based retrofit kits for commercial fleet operators seeking insurance compliance without OEM-controlled distribution channels.
- Tier-1 Suppliers:Semiconductor-to-software stack integration determines competitive positioning.
- Vehicle Assemblers:Contract manufacturing arrangements in Tamil Nadu and Gujarat leverage India's PLI scheme for automotive electronics.
OEMs control the dominant procurement volume, while Aftermarket Providers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
National safety mandates and production incentives are redrawing procurement geography for adaptive cruise control systems. Germany, Japan, the United States, China, and India concentrate divergent regulatory frameworks and manufacturing clusters that shape supplier investment priorities.
Germany
Premium OEM specification of highway-speed radar systems drives sensor procurement volumes. KBA enforces UN R155 cybersecurity certification timelines that compress supplier qualification windows. Stuttgart and Ingolstadt anchor radar-to-software integration facilities where Bosch and Continental coordinate tier-1 program deliveries.
Japan
Imaging radar adoption for stop-and-go traffic functionality accelerates urban deployment. METI coordinates domestic semiconductor foundry capacity expansion for 77 GHz front-end modules. Nagoya and Toyota City concentrate subsystem assembly where Denso manages sensor fusion calibration for domestic nameplates.
United States
NHTSA automatic emergency braking mandates normalize longitudinal control sensor infrastructure across light vehicle segments. Michigan and Ohio assembly networks specify multi-brand platform contracts for radar-dominant highway systems. Detroit-area engineering centers coordinate firmware validation cycles for SAE Level 2+ certification.
China
Battery-electric OEMs bundle adaptive cruise as baseline equipment across premium and mid-market platforms. MIIT dual carbon goals accelerate regenerative braking coordination requirements in driver-assistance specifications. Shanghai and Shenzhen concentrate camera-radar fusion development where domestic suppliers challenge incumbent tier-1 positions.
India
PLI scheme subsidies for automotive electronics attract radar module assembly investment from multinational suppliers. BIS certification requirements extend development timelines for sensor fusion algorithms. Tamil Nadu and Gujarat contract manufacturing clusters leverage incentive structures to capture European OEM export program volumes.
Automotive Adaptive Cruise Control Market Key Industry Players
On the supply side, the industry is consolidating around integrated sensor-to-software stacks that compress procurement decision cycles. Tier-1 system integrators with captive semiconductor sourcing dominate highway-speed deployments, while specialized vision processors challenge incumbents in camera-fusion segments. Two strategic archetypes define competitive positioning: diversified automotive suppliers with domain controller integration capabilities, and semiconductor-focused specialists with convolutional neural network expertise. Dominant competitive moves include strategic partnerships for over-the-air update infrastructure and geographic expansion through PLI scheme manufacturing localization.
Within the diversified supplier tier, Bosch and Continental exemplify integrated stack providers that anchor European and North American OEM procurement channels. Denso occupies a position representing Japanese keiretsu-affiliated subsystem integration. Mobileye exemplifies the vision-processor specialist archetype that has displaced traditional tier-1 camera module sourcing in premium electric vehicle platforms. These three anchors illustrate how competitive boundaries are redrawing between hardware-software integration depth and algorithm-specific expertise.
| Leading Market Players |
|---|
| Denso |
| Valeo |
| Bosch |
| Mobileye |
| Magna International |
| Continental |
| Aptiv |
| Autoliv |
| ZF Friedrichshafen |
| Others |
Cost & Logistics Intelligence
Taiwanese gallium arsenide foundry concentration for 77 GHz radar front-end modules anchors upstream margin capture, while downstream pricing power fragments across German tier-1 integrators and Chinese battery-electric OEMs bundling adaptive cruise as standard equipment.
Pricing Analysis
Volume-discount tiering structures separate highway-speed radar deployments for premium German OEMs from mid-market passenger car specifications and aftermarket retrofit kits in Brazil and Mexico. Pricing stratifies across premium, standard, and economy tiers driven by ISO 26262 functional safety certification levels and semiconductor integration depth. Cost compression in camera-fusion segments intensifies because South Korean battery-electric platforms normalize bundled feature expectations. Fleet procurement consolidation at holding-company level exhibits highest price sensitivity; premium German nameplates with SAE Level 2+ certification requirements show lowest.
Supply Chain Analysis
Export-control restrictions on gallium arsenide wafer processing equipment constrain 77 GHz radar module flows from Taiwanese foundries to European and North American assembly networks. Geographic supply concentration centers on Taiwan, Germany, and South Korea for front-end semiconductor fabrication. Raw material dependencies encompass gallium arsenide substrates, advanced packaging compounds, and halogen-free printed circuit board laminates requalified under REACH chemical restrictions. Single-source vulnerability from Taiwanese foundry concentration poses structural supply chain risk. Distribution runs through tier-1 system integrators with direct OEM program relationships rather than open component markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent radar-centric architectures face substitution pressure from solid-state LiDAR arrays penetrating premium highway applications, requiring defensive repositioning across sensor fusion technology portfolios.
For Market Incumbents: Insulate highway-speed radar deployments by deepening captive gallium arsenide sourcing relationships with Taiwanese foundries amid export-control volatility. Accelerate imaging radar with 4D point-cloud generation development to counter LiDAR substitution threats in stop-and-go traffic segments. Secure UN R155 cybersecurity certification ahead of qualification window compression.
For New Entrants and Emerging Players: Pursue aftermarket retrofit channel penetration in Brazil and Mexico where independent garages bypass OEM-controlled distribution for commercial fleet insurance compliance. Target camera-based fusion system white space in mid-market battery-electric platforms where South Korean OEMs established bundled-feature baselines. Leverage India's PLI scheme manufacturing subsidies for radar module assembly cost positioning.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed automotive electronics specialists holding halogen-free substrate qualifications for EU market access. Long-term viability over the analysis window hinges on domain controller integration depth and over-the-air update infrastructure ownership. Watch for imaging radar adoption inflection in Japanese premium OEM urban congestion automation as signal of technology transition timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Bosch and Continental consolidate highway-speed radar architectures under unified domain controllers. |
| Software-Defined Vehicle Investment | OEMs over-the-air update infrastructure supports adaptive cruise calibration per UN R155 mandates. |
| Geographic Manufacturing Footprint | India PLI scheme subsidies attract radar module assembly in Tamil Nadu and Gujarat contract clusters. |
| Battery Supply Agreement | Chinese OEMs bundle regenerative braking coordination with adaptive cruise for platform differentiation. |
| Charging Infrastructure Partnership | Electric vehicle charging networks integrate fleet telematics with platooning protocol development. |
Research Approach
Operator-level perspectives from tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and dealership operations anchored the qualitative base for this analysis. Primary interview findings combined with secondary validation from vehicle production databases, IHS Markit registration data, SEC filings, and regulatory submission records. Bottom-up segment sizing and top-down macroeconomic triangulation cross-checked volume estimates across technology, vehicle type, and application dimensions.
Scenario-bracketing framed demand trajectories across the projection horizon, modeling vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster segmentation. CAGRs derived from regression analysis against historical adoption curves and regulatory mandate implementation schedules. Forecast inputs encompassed NHTSA automatic emergency braking compliance timelines and MIIT dual carbon goal specifications for regenerative braking coordination.
Macroeconomic conditions sit as an overlay; deviation in semiconductor capital expenditure cycles and gallium arsenide substrate pricing would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory implementation pace and foundry capacity expansion. Material shifts in UN R155 cybersecurity certification timelines or export-control regime stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
France Autonomous Navigation Market
Autonomous Vehicles
Autonomous Emergency Braking (AEB) Market
Autonomous Vehicles
Adaptive Cruise Control (ACC) and Blind Spot Detection (BSD) Market
Autonomous Vehicles
Asia-Pacific Automotive Advanced Driver Assistance Systems Market
Autonomous Vehicles
Autopilot Systems Market
Autonomous Vehicles
Automatic Steering System Market
Autonomous Vehicles
Middle East and Africa ADAS Market
Autonomous Vehicles
Autonomous (Driverless) Car Market
Autonomous Vehicles
Connected Vehicle Technology Market
Autonomous Vehicles
Global Driverless Car Market
Autonomous Vehicles
Automotive Autonomous Emergency Braking System Market
Autonomous Vehicles
Autonomous Vehicles and Car Patent Market
Autonomous Vehicles
Automotive Predictive Technology Market
Autonomous Vehicles
Automated Valet Parking (AVP) Market
Autonomous Vehicles
Autonomous Driving Component Market
Autonomous Vehicles
Global Robot Cars and Trucks Market