
 Global Automotive Navigation System Market | 2026-2036
Global Automotive Navigation System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Navigation System Market Analysis
China is reshaping capacity build-outs for automotive navigation hardware as domestic EV production scales. Garmin Ltd. leverages its consumer GPS heritage to compete in aftermarket portable units. Denso Corporation anchors Japanese OEM supply chains with embedded navigation modules. HERE Technologies controls high-definition mapping data pipelines for autonomous driving fleets.
An automotive navigation system integrates satellite positioning receivers, inertial sensors, and digital map databases to compute real-time vehicle location, route optimization, and turn-by-turn guidance with lane-level precision. Embedded navigation dominates OEM factory installations where hardware-software integration meets stringent automotive-grade temperature and vibration specifications. Smartphone navigation captures aftermarket volume through Apple CarPlay and Android Auto mirroring protocols. Fleet management applications generate recurring revenue from telematics-linked route analytics and driver behavior monitoring.
China's MIIT enforces connected-vehicle data localization standards that restrict cross-border map transmission, creating compliance barriers for foreign navigation providers. Europe's GDPR and EU AI Act impose algorithmic transparency requirements on route prediction engines processing driver behavior data. The US NHTSA references ISO 26262 functional safety standards for navigation systems feeding ADAS control loops. Stakeholders must evaluate regulatory fragmentation before committing to unified global platform architectures.
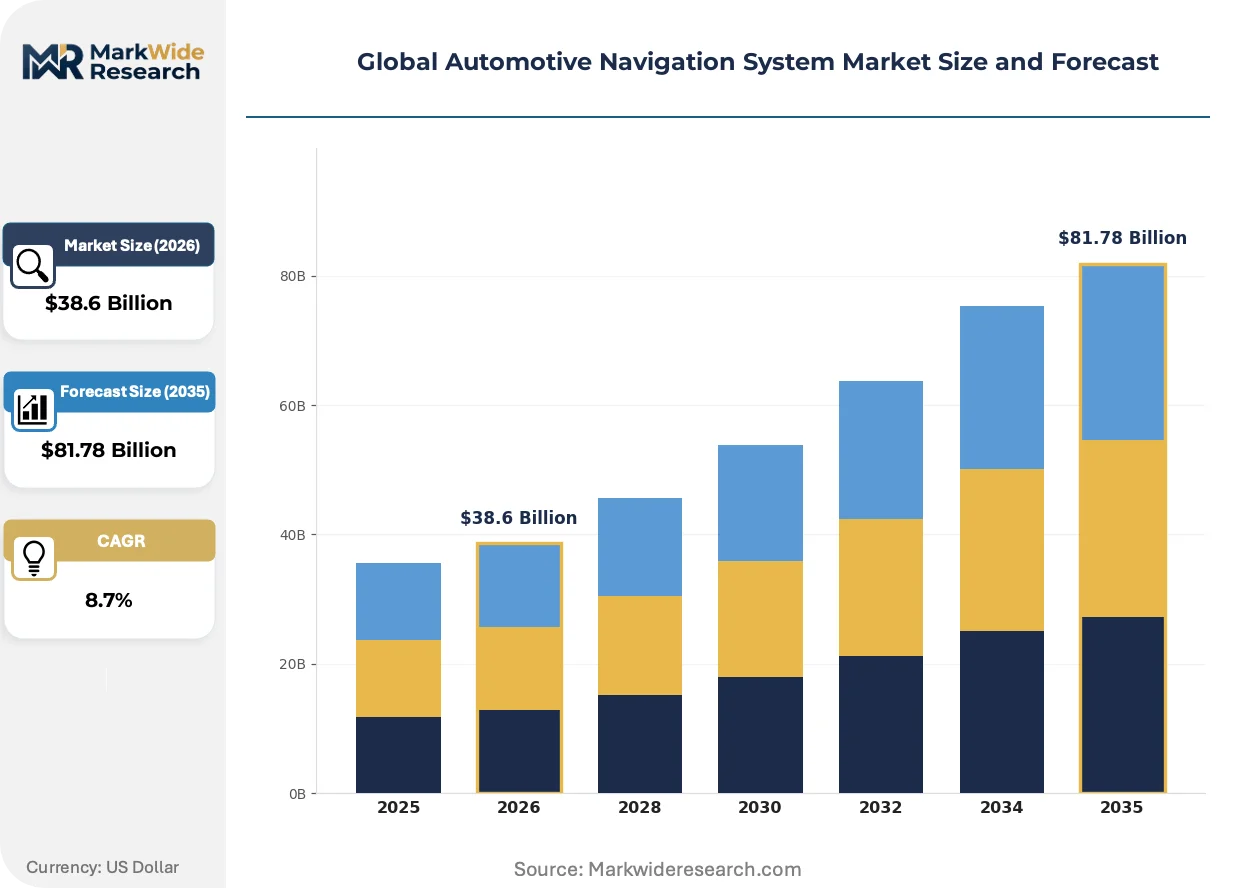
Market Dynamics
OEMs now embed navigation hardware directly into vehicle electrical architectures to feed sensor fusion pipelines for ADAS and autonomous driving, compressing the aftermarket and elevating automotive-grade reliability requirements.
Growth Catalysts
- ADAS Integration Mandates:Euro NCAP protocols now weight navigation-linked predictive speed adaptation in safety scoring, forcing OEMs to spec embedded systems with lane-level map precision.
- China's EV Scale:Domestic manufacturers in Shenzhen and Shanghai ship navigation-integrated digital cockpits as standard equipment, normalizing the cost curve for global tier-1 adoption.
- HD Mapping Pipelines:Autonomous fleet operators in California, Germany, and Japan commission centimeter-accuracy road geometry updates, creating recurring data licensing demand.
Market Restraints
- Semiconductor Supply Concentration:Advanced GNSS receiver silicon and automotive-grade inertial sensors concentrate among Taiwanese and South Korean foundries, exposing OEMs to single-source risk.
- Data Localization Friction:China's MIIT mandates restrict cross-border transmission of vehicle trajectory data, fragmenting cloud-based map update architectures.
- Smartphone Mirroring Substitution:Apple CarPlay and Android Auto deliver turn-by-turn guidance through existing handsets, eroding willingness-to-pay for factory-installed navigation in mass-market segments.
Strategic Opportunities
- Indian Market Underpenetration:Domestic automakers in Chennai and Pune still specify aftermarket portable units for entry vehicles, creating white space for embedded module conversion.
- Telematics-Linked Fleets:Commercial vehicle operators in Brazil and Mexico adopt route analytics platforms that bundle navigation with fuel optimization and driver scoring.
- EU AI Act Compliance:Algorithmic transparency requirements for route prediction engines create service revenue for audit-ready navigation software vendors.
Industry Challenges
- Functional Safety Certification:ISO 26262 ASIL-B compliance for navigation systems feeding ADAS control loops demands 18-24 month validation cycles, compressing model-year refresh windows.
- Map Data Licensing Complexity:Fragmented intellectual property rights across satellite imagery providers, road authorities, and private surveyors inflate procurement negotiation overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Navigation System Market |
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $81.78 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable GPS, Embedded Navigation, Smartphone Navigation, Hybrid Navigation Technology: GPS, GLONASS, GNSS, Dead Reckoning End User: Passenger Cars, Commercial Vehicles, Fleet Management, Ride-sharing Services Application: Traffic Navigation, Route Planning, Location Tracking, Geofencing |
| Companies Covered | Garmin Ltd., Denso Corporation, TomTom International BV, Pioneer Corporation, Alpine Electronics, Continental AG, Robert Bosch GmbH, Aisin AW Co., HERE Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Navigation System Market Emerging Trajectories
Navigation hardware architectures are converging with vehicle sensor networks and cloud compute fabrics, dissolving the boundary between positioning modules and broader telematics platforms.
High-definition map generation is migrating from dedicated survey vehicles to crowdsourced vehicle sensor feeds. OEMs in Stuttgart and Munich now ingest anonymized camera and lidar data from customer fleets to refresh road geometry weekly rather than quarterly. This compression of update latency is collapsing the competitive moat of legacy map data incumbents.
Europe's GDPR and EU AI Act now impose algorithmic transparency and data minimization requirements on navigation systems processing driver behavior for route prediction. Tier-1 suppliers serving German premium OEMs must document decision logic for regulatory audit. The compliance burden falls heaviest on predictive traffic routing and personalized destination suggestion features.
Fleet procurement teams now unbundle navigation hardware from telematics service contracts, selecting best-of-breed positioning modules while sourcing route analytics from specialized software vendors. This disaggregation is most visible among North American logistics operators running mixed-brand truck fleets, where standardized APIs replace vertically integrated black-box solutions.
Global Automotive Navigation System Market Segmentation
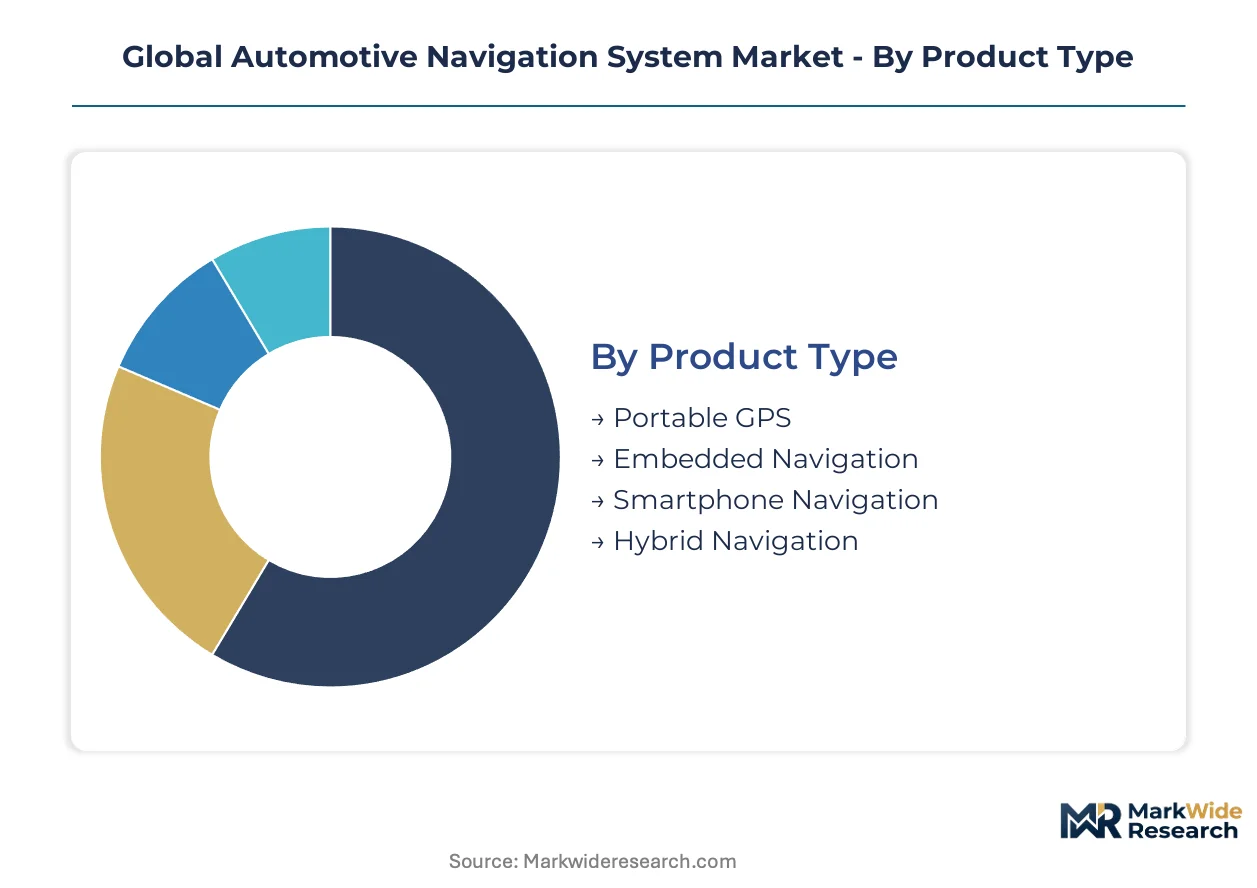
Segmentation in automotive navigation systems reveals divergent investment cycles across hardware form factors, positioning technologies, and service models. Understanding these temporal patterns helps suppliers align R&D roadmaps with OEM procurement calendars and aftermarket replacement rhythms.
Product Type:
Embedded navigation systems carry the longest validation cycles at 36-48 months, while smartphone navigation turns over with annual OS releases. Portable GPS and hybrid configurations occupy intermediate refresh windows tied to semiconductor node advances.
- Portable GPS:Self-contained units with dedicated receivers and offline map storage serve rental fleets and emerging market entry vehicles. Demand concentrates in India's Chennai-Pune automotive corridor where domestic OEMs specify aftermarket units for cost-sensitive hatchbacks.
- Embedded Navigation:Factory-integrated modules with automotive-grade GNSS receivers and inertial sensors feed ADAS sensor fusion pipelines. German premium OEMs in Stuttgart mandate lane-level precision for predictive speed adaptation, compressing supplier qualification timelines.
- Smartphone Navigation:Apple CarPlay and Android Auto mirroring protocols leverage handset processing power and cloud connectivity. Mass-market segments in Brazil and Mexico show accelerating substitution as OEMs delete factory navigation to reduce bill-of-materials costs.
- Hybrid Navigation:Dual-mode systems combine embedded hardware resilience with smartphone cloud connectivity for traffic updates. Japanese OEMs in Toyota City deploy these architectures to balance offline reliability with real-time data freshness.
Embedded navigation dominates installed base. Smartphone navigation is where expansion concentrates.
Technology:
Cost tier separates satellite constellation licensing fees from royalty-free augmentation methods. GNSS multi-constellation receivers command premium pricing against single-system GPS modules.
- GPS:The legacy US satellite constellation provides baseline positioning accuracy for mass-market applications. China's domestic EV manufacturers in Shenzhen increasingly specify GPS-GLONASS dual-mode receivers to ensure redundancy.
- GLONASS:Russia's satellite network improves urban canyon performance through additional visible satellites. Russian and CIS market vehicles mandate GLONASS primary capability under national technical regulations.
- GNSS:Multi-constellation receivers integrating GPS, GLONASS, Galileo, and BeiDou deliver sub-meter accuracy for autonomous driving fleets. California-based robotaxi operators commission centimeter-accuracy road geometry updates, creating recurring data licensing demand.
- Dead Reckoning:Inertial measurement units using wheel speed sensors and gyroscopes maintain position during tunnel and parking structure outages. German tier-1 suppliers integrate these modules with embedded navigation for ADAS control loop redundancy.
GNSS multi-constellation systems command premium pricing tiers. Dead Reckoning augmentation is climbing the fastest as urban autonomy requirements tighten.
End User:
Volume scale differentiates passenger car OEM factory installations from specialized fleet procurement patterns. Ride-sharing platforms generate recurring service revenue against one-time hardware sales.
- Passenger Cars:OEM factory installations integrate navigation with digital cockpit displays and voice control systems. European premium segments in Munich and Stuttgart normalize embedded navigation as standard equipment, elevating automotive-grade reliability requirements.
- Commercial Vehicles:Heavy-duty trucks and buses require specialized routing for weight-restricted bridges and hazardous material corridors. North American logistics operators running mixed-brand fleets unbundle navigation hardware from telematics contracts.
- Fleet Management:Telematics-linked route analytics combine positioning with fuel optimization and driver behavior scoring. Brazilian and Mexican commercial vehicle operators adopt these bundled platforms for compliance and cost control.
- Ride-sharing Services:Algorithmic dispatch and dynamic pricing depend on real-time driver location and estimated arrival calculations. Urban mobility platforms in California and Germany commission HD map updates for geofenced autonomous service zones.
Passenger cars dominate installed base. Fleet management is where expansion concentrates.
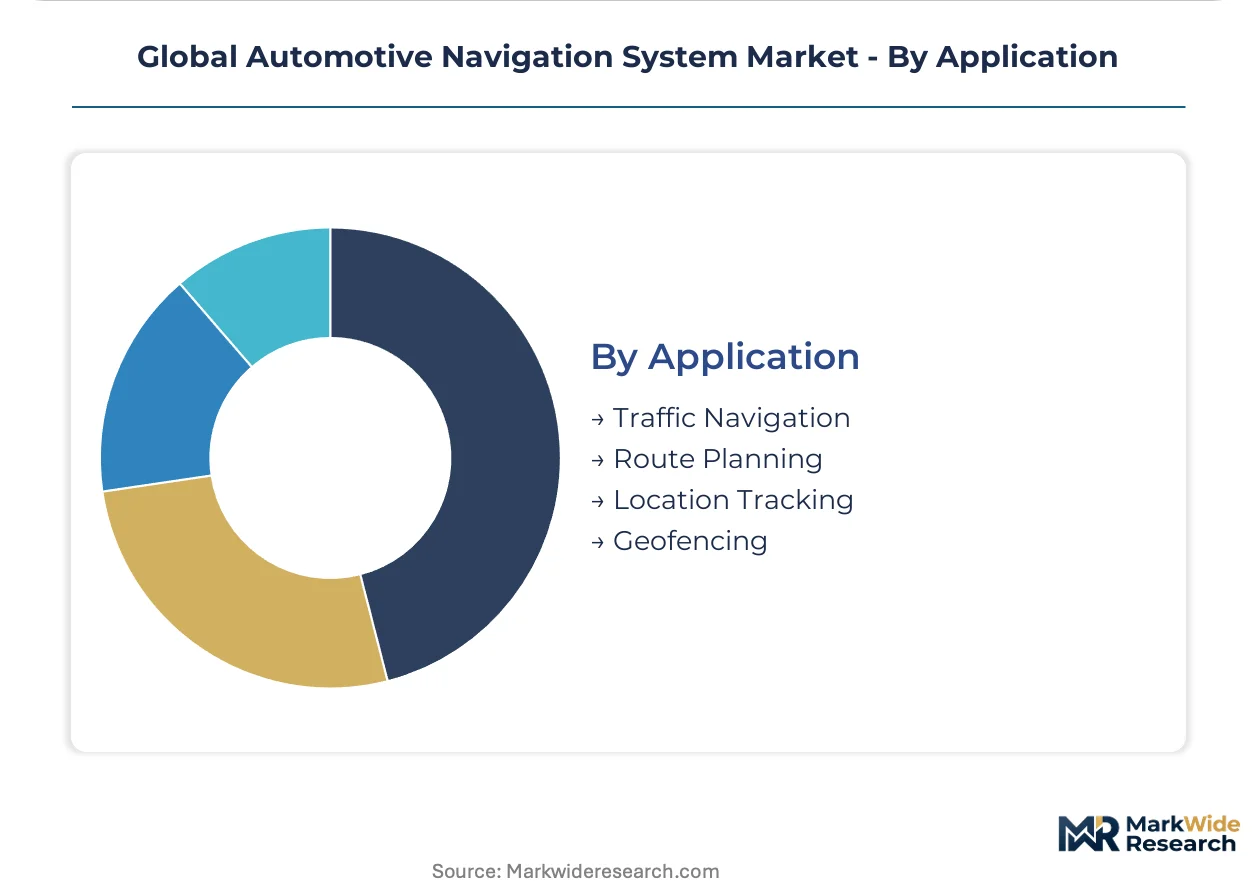
Application:
Functional maturity separates established turn-by-turn guidance from emerging geofencing enforcement capabilities. Traffic navigation carries the highest consumer willingness-to-pay.
- Traffic Navigation:Real-time congestion detection and dynamic rerouting using probe vehicle data and municipal sensor feeds. Euro NCAP protocols now weight navigation-linked predictive speed adaptation in safety scoring.
- Route Planning:Multi-criteria optimization balancing distance, time, fuel consumption, and charging station availability for electric vehicles. Chinese EV manufacturers in Shanghai ship navigation-integrated digital cockpits as standard equipment.
- Location Tracking:Continuous position reporting for stolen vehicle recovery and parental monitoring applications. Insurance telematics providers in the UK and Germany mandate these capabilities for usage-based premium calculations.
- Geofencing:Virtual perimeter enforcement for low-emission zones, speed-limited areas, and autonomous vehicle operational design domains. EU AI Act compliance requirements now impose algorithmic transparency obligations on geofencing decision logic.
Traffic navigation dominates installed base. Geofencing is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwanese and South Korean foundries concentrate advanced GNSS receiver silicon production, exposing OEMs to single-source risk across multiple continents. Germany, China, Japan, and the United States anchor embedded navigation demand through distinct regulatory and industrial pathways.
United States
California-based robotaxi operators commission centimeter-accuracy HD map updates, creating recurring data licensing demand. The NHTSA references ISO 26262 functional safety standards for navigation systems feeding ADAS control loops. Detroit's automotive corridor integrates embedded navigation with digital cockpit architectures for premium pickup and SUV segments.
Germany
Premium OEMs in Stuttgart and Munich mandate lane-level map precision for predictive speed adaptation under Euro NCAP protocols. The EU AI Act imposes algorithmic transparency requirements on route prediction engines processing driver behavior data. Bavaria's automotive cluster compresses supplier qualification timelines for ASIL-B compliant navigation modules.
China
Domestic EV manufacturers in Shenzhen and Shanghai ship navigation-integrated digital cockpits as standard equipment. The MIIT enforces connected-vehicle data localization standards that restrict cross-border map transmission. Yangtze River Delta production hubs normalize the cost curve for global tier-1 embedded module adoption.
Japan
Toyota City OEMs deploy hybrid navigation architectures balancing offline reliability with real-time cloud connectivity. METI technical standards govern automotive-grade receiver performance for domestic factory installations. Nagoya's supplier ecosystem anchors embedded module production for Japanese OEM export programs.
India
Domestic automakers in Chennai and Pune specify aftermarket portable units for cost-sensitive entry vehicles, creating embedded conversion white space. The BIS mandates localization capabilities for connected vehicle platforms under national automotive regulations. Tamil Nadu's manufacturing corridor attracts tier-1 navigation hardware investments serving Southeast Asian export markets.
Global Automotive Navigation System Market Vendor Landscape
Electronics conglomerates and specialized positioning technology firms split the market through divergent vertical integration strategies. Tier-1 automotive suppliers compete against consumer GPS heritage players for OEM factory installation contracts. Two archetypes dominate: diversified industrial electronics groups with captive semiconductor access, and focused mapping data and software specialists. Consolidation pressure intensifies through strategic partnerships for HD map pipeline access and capacity expansion for automotive-grade receiver production.
Among diversified industrial electronics groups, Continental AG and Robert Bosch GmbH exemplify the integrated-module archetype with embedded navigation hardware feeding OEM sensor fusion pipelines. Garmin Ltd. represents the consumer-heritage specialist competing for aftermarket portable unit volume. HERE Technologies anchors the mapping-data specialist tier controlling high-definition road geometry pipelines for autonomous fleet operators.
| Leading Market Players |
|---|
| Garmin Ltd. |
| Denso Corporation |
| TomTom International BV |
| Pioneer Corporation |
| Alpine Electronics |
| Continental AG |
| Robert Bosch GmbH |
| Aisin AW Co. |
| HERE Technologies |
| Others |
Supply Flow & Price Mechanics
The Yangtze River Delta freight corridor channels semiconductor components from Taiwanese foundries to Shenzhen assembly plants, compressing logistics costs for embedded navigation modules while amplifying price differentiation between automotive-grade and consumer-grade receiver tiers. This corridor's cost dynamics concentrate pricing power among GNSS silicon suppliers serving German premium OEMs, forcing downstream module vendors to absorb margin pressure or cede volume to Chinese domestic EV manufacturers.
Pricing Analysis
ISO 26262 dictates the pricing tier structure across the automotive navigation market, separating ASIL-B certified embedded modules from uncertified aftermarket alternatives. Three-tier pricing structure across premium, standard, and economy levels stratifies by functional safety grade and constellation licensing breadth. Cost compression in the mass-market tier intensifies because smartphone mirroring protocols erode willingness-to-pay for factory-installed systems. Fleet management operators show the least price sensitivity due to recurring telematics service bundling, while entry-level passenger car segments in India and Brazil drive aggressive procurement negotiation.
Supply Chain Analysis
Extended payment terms from German tier-1 suppliers now stretch to 90-120 days, squeezing working capital for Taiwanese and South Korean foundries producing advanced GNSS receiver silicon. The supply chain draws from Japanese inertial sensor specialists and Chinese domestic EV cockpit integrators for module assembly. Single-source vulnerability concentrates in automotive-grade MEMS gyroscope production, where two Japanese suppliers anchor global capacity. Distribution runs through OEM direct procurement for embedded systems and specialized electronics distributors for aftermarket portable units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across regulatory jurisdictions creates niche opportunities for navigation specialists who architect compliance-first platform designs rather than unified global solutions. The divergence between China's data localization mandates and Europe's algorithmic transparency requirements splits procurement specifications, opening doors for regional software vendors.
For Market Incumbents: Entrench ASIL-B certification leadership by accelerating validation cycles for navigation modules feeding ADAS control loops. Add captive semiconductor packaging capacity in Taiwan or South Korea to defend against foundry allocation constraints. Lock long-term HD map licensing agreements with HERE Technologies before autonomous fleet operators consolidate data pipeline access.
For New Entrants and Emerging Players: India's Chennai-Pune automotive corridor offers embedded conversion white space as domestic OEMs still specify aftermarket portable units for cost-sensitive hatchbacks. Target Brazilian commercial vehicle operators with telematics-bundled route analytics platforms that unbundle hardware from service contracts. Pursue white-label partnerships with European tier-1 suppliers seeking algorithmic transparency documentation for EU AI Act compliance.
For Investors and Strategic Acquirers: The EU AI Act's algorithmic transparency requirements reshape the acquisition landscape toward audit-ready navigation software vendors with documented decision logic for predictive routing engines. Position holdings for a 5-10 year window where regulatory fragmentation sustains premium pricing for compliance-capable platforms. Monitor NHTSA rulemaking on navigation-linked ADAS performance standards as the signal for accelerated OEM embedded system refresh cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| ASIL-B Certification Acceleration | Compresses 18-24 month validation cycles to capture Euro NCAP-linked OEM procurement windows. |
| HD Map Data Pipeline Partnership | Secures recurring licensing revenue from California and German autonomous fleet operators. |
| China Data Localization Compliance | Enables market access under MIIT connected-vehicle standards for foreign navigation providers. |
| Fleet Telematics Platform Integration | Bundles navigation hardware with fuel optimization for Brazilian logistics operator procurement. |
| Automotive-Grade MEMS Capacity Expansion | Reduces single-source risk from Japanese inertial sensor suppliers for ADAS redundancy. |
Methodological Framework
Desk research of vehicle production databases, IHS Markit registration data, and regulatory filing repositories preceded structured interviews with Tier 1 supplier procurement managers, OEM platform engineers, aftermarket distribution channel heads, and fleet telematics operators. Primary fieldwork combined telephone and in-person conversations across Stuttgart, Munich, Shenzhen, Shanghai, and Detroit automotive clusters. Secondary validation drew from SEC filings of listed navigation hardware vendors, customs trade data for GNSS receiver imports, and ISO 26262 certification registries. Bottom-up unit shipment estimates triangulated against top-down OEM production forecasts.
Assumptions held OEM embedded navigation attach rates fixed at observed levels across the projection horizon, while scenario analysis varied smartphone mirroring substitution velocity and autonomous fleet HD map update frequency. Segmentation dimensions modeled include vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster. CAGRs derived from logistic diffusion curves fitted to historical technology adoption patterns in automotive electronics, cross-referenced with semiconductor node transition timelines and regulatory mandate implementation schedules.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by Chinese domestic EV manufacturers or accelerated NHTSA rulemaking on navigation-linked ADAS would shift outcomes. Macroeconomic contraction in European premium automotive demand, escalation of Taiwan Strait logistics disruptions, or breakthrough advances in smartphone-based positioning accuracy would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
Park Assist Camera Market
Telematics and Infotainment
Infotainment System UX and Latency Test Platforms for Connected Vehicles Market
Telematics and Infotainment
Asia Pacific Automotive Infotainment Systems Market
Telematics and Infotainment
Global in Dash Navigation System Market
Telematics and Infotainment
Dashboard Camera Market
Telematics and Infotainment
Europe Automotive Telematics Market
Telematics and Infotainment
Automotive Dashboard Camera Market
Telematics and Infotainment
Motorcycle Infotainment System Market
Telematics and Infotainment
Telematics in Automotive Market
Telematics and Infotainment
Automotive Personal Navigation Systems Market
Telematics and Infotainment
Global Carpool-As-A-Service Market
Telematics and Infotainment
In-Car Infotainment Market
Telematics and Infotainment
Mobile Resource Management (MRM) Market
Telematics and Infotainment
Europe Dashboard Camera Market
Telematics and Infotainment
Intelligent Transport Systems (ITS) Market
Telematics and Infotainment
Automotive Wi-Fi Router Market