
 Self-Driving Truck Market | 2026-2036
Self-Driving Truck Market Size, Share, and Industry Trends Forecast 2026-2036
Self-Driving Truck Market Analysis
Texas is fragmenting as competing autonomous truck developers establish overlapping proving grounds and commercial route networks. Waymo LLC leverages its Waymo Driver platform heritage from passenger robotaxi operations to anchor long-haul freight automation. Torc Robotics sustains deep integration with Daimler Truck's manufacturing scale through their strategic development partnership. Kodiak Robotics differentiates via its modular SensorPod architecture that enables rapid hardware swaps across varied fleet configurations.
Self-driving trucks constitute heavy-duty commercial vehicles equipped with multi-modal perception stacks—typically combining LiDAR point-cloud mapping, camera-based computer vision, and radar redundancy—to execute longitudinal and lateral control without continuous human supervision. These systems operate at SAE Level 4 autonomy, requiring no driver intervention within predefined operational design domains while maintaining fallback readiness for edge-case scenarios. Camera Systems and LiDAR dominate technology stack procurement, with Radar gaining share as cost-efficient redundancy for highway-speed obstacle detection. Freight Transport leads Service Type deployment, though Last Mile Delivery is attracting capital as urban automation exemptions expand.
NHTSA governs Federal Motor Vehicle Safety Standards compliance for automated driving system exemptions, while FMCSA shapes hours-of-service regulations that autonomous operations fundamentally disrupt. Texas DOT and Arizona DOT administer state-level testing permits that determine where developers can accumulate real-world mileage without safety drivers. Stakeholders must monitor how state-level liability frameworks evolve as commercial deployments transition from supervised to driverless operations.
Market Dynamics
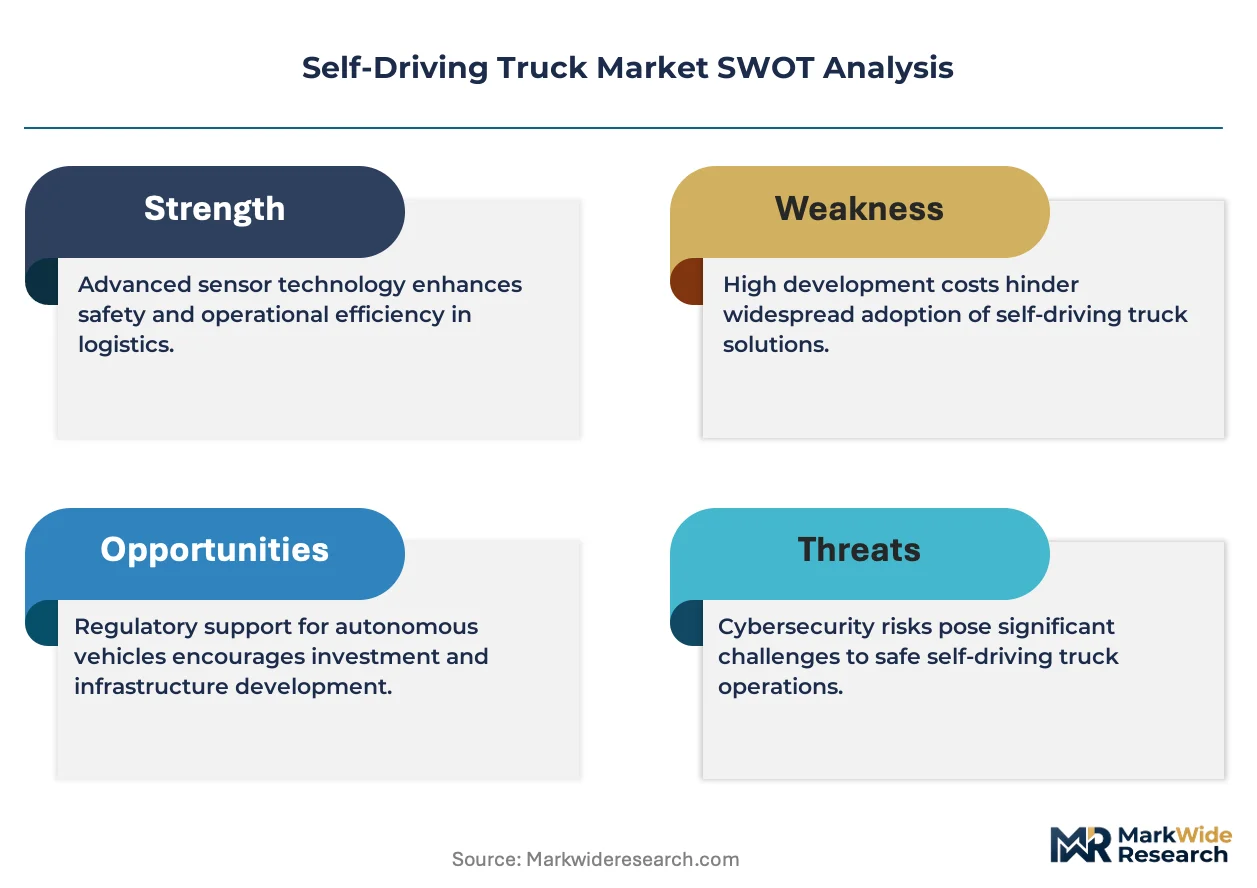
SAE Level 4 autonomy is collapsing the traditional driver-hours model that governed freight economics for decades, forcing carriers to restructure operating cost assumptions around sensor maintenance and remote supervision centers rather than human wage scales.
Growth Catalysts
- FMVSS Exemption Pathways:NHTSA's evolving automated driving system exemptions are compressing commercial deployment timelines for heavy-duty vehicles operating on interstate corridors.
- Texas DOT Permissive Framework:State-level testing permits without safety driver requirements enable rapid accumulation of real-world mileage across the I-10 and I-35 freight corridors.
- LiDAR-Camera Sensor Fusion:Multi-modal perception stacks combining point-cloud mapping with computer vision redundancy are resolving edge-case detection failures that previously blocked highway-speed automation.
Market Restraints
- LiDAR Component Concentration:High-performance solid-state LiDAR supply concentrates among a handful of specialized photonics manufacturers, creating input bottlenecks for scaled fleet builds.
- FMCSA Hours-of-Service Friction:Federal Motor Carrier Safety Administration regulations governing driver duty cycles create compliance ambiguity for supervised versus fully driverless operations.
- Edge-Case Validation Burden:Rare scenario testing requirements for snow, construction zones, and emergency vehicle interactions extend certification timelines beyond typical automotive development cycles.
Strategic Opportunities
- Last-Mile Automation Expansion:Urban freight exemptions in select municipalities are opening short-haul depot-to-dock applications previously blocked by dense pedestrian environments.
- SensorPod Modular Architecture:Rapid hardware swap capabilities enable fleet operators to configure perception stacks for specific route conditions without vehicle downtime.
- Arizona DOT Driverless Permits:State regulators' progression to fully unsupervised testing creates regulatory precedent that neighboring jurisdictions are adopting.
Industry Challenges
- Remote Supervisor Talent Scarcity:Fleet operators struggle to recruit and retain technicians capable of interpreting real-time sensor feeds and intervening during system disengagements.
- Legacy TMS Integration Complexity:Autonomous dispatch systems require extensive middleware development to interface with existing transportation management platforms at major carriers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Self-Driving Truck Market |
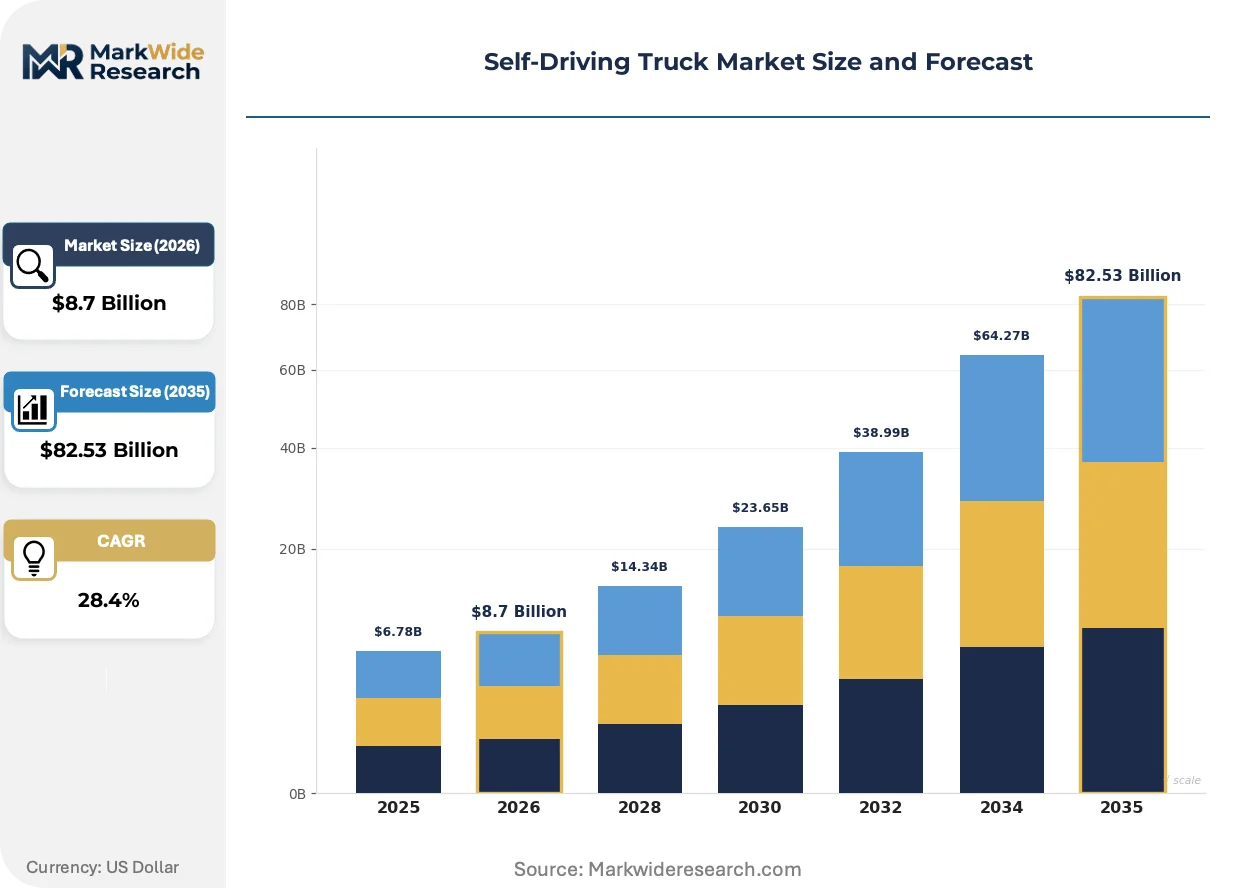
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $82.53 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: LiDAR, Camera Systems, Radar, Ultrasonic Sensors End User: Logistics Companies, Freight Carriers, Retail Distributors, E-Commerce Providers Deployment: On-Road, Off-Road, Dedicated Lanes, Mixed Traffic Service Type: Freight Transport, Last Mile Delivery, Load Hauling, Transportation Management |
| Companies Covered | Waymo LLC, Torc Robotics, Aurora Innovation, TuSimple, Einride, Kodiak Robotics, Daimler Truck, Volvo Trucks, PACCAR, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Self-Driving Truck Market Emerging Trajectories
Freight automation is collapsing traditional distinctions between long-haul line-haul and regional distribution economics as sensor costs fall and operational design domains expand.
LiDAR point-cloud density is collapsing the cost-performance tradeoff that previously forced developers to choose between high-resolution mapping and hardware affordability. Tier 1 suppliers are shipping automotive-grade solid-state units at price points that enable retrofitting existing Class 8 tractors rather than requiring ground-up vehicle design. This compression is enabling mid-size carriers to pilot autonomous operations without committing to full fleet replacement.
NHTSA's automated driving system exemption process is creating regulatory clarity that the European Union's AI Act has yet to match for heavy commercial vehicles. The divergence is accelerating first-mover deployment in the United States while European developers await harmonized type-approval frameworks. German regulators at KBA are responding with accelerated testing corridors on the A9 autobahn to retain automotive competitiveness.
Freight procurement is fragmenting as shippers unbundle line-haul from first-mile and last-mile services to optimize for autonomous-compatible segments. Large retailers are rewriting RFP specifications to identify routes suitable for driverless operation, creating tiered pricing structures that reward carriers with certified autonomous capabilities. This bifurcation is most visible in Texas, where Dallas-Fort Worth distribution centers are redesigning dock scheduling around automated truck arrival windows.
Self-Driving Truck Market Segmentation
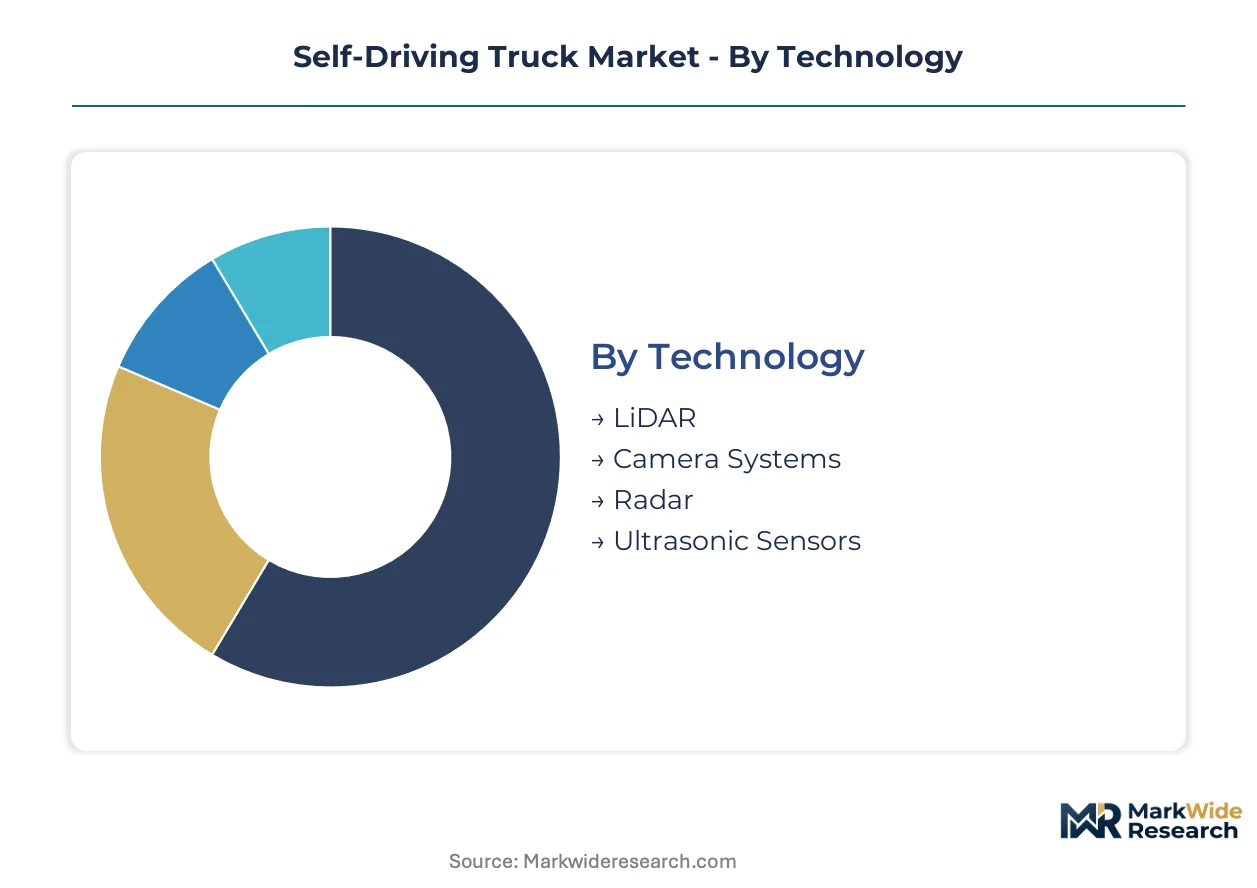
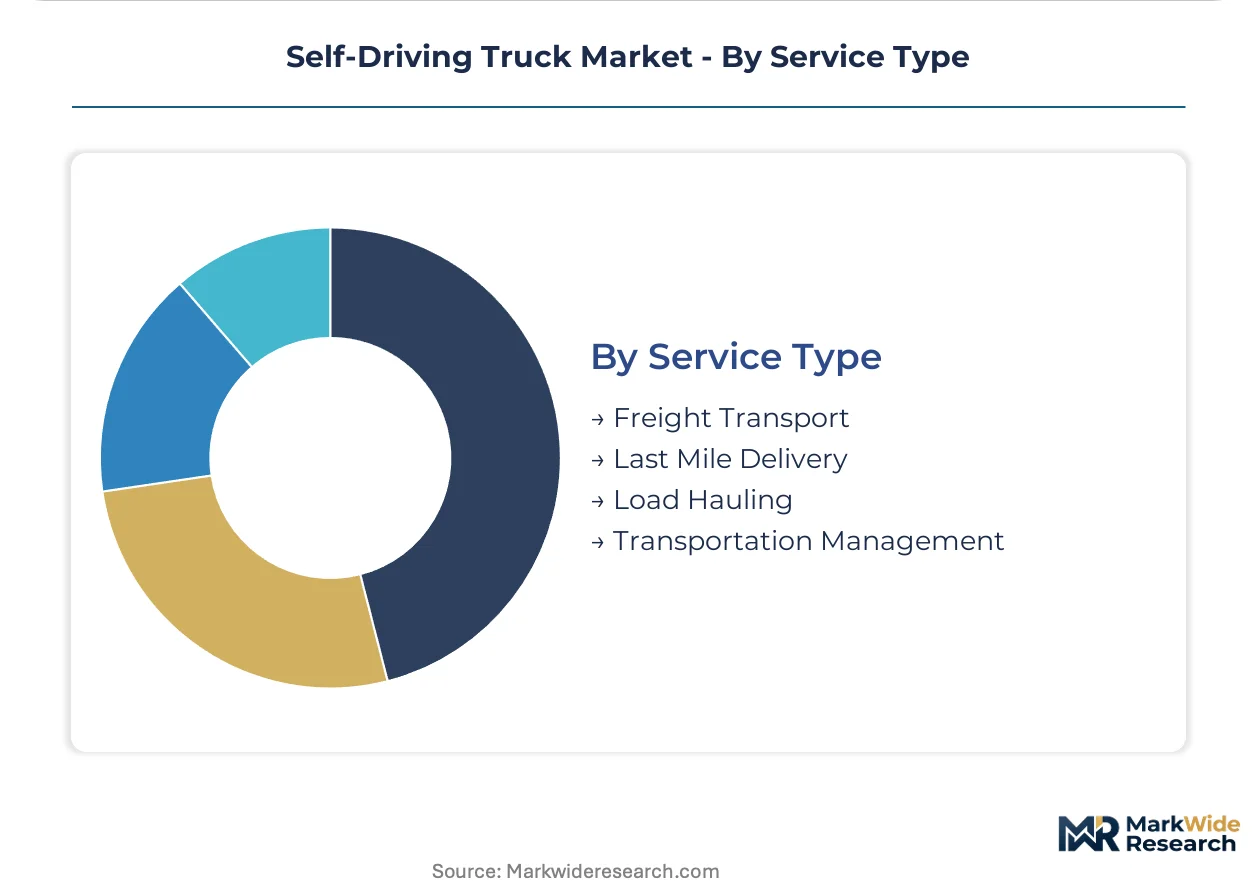
Self-driving truck segmentation reveals how technology choices, deployment environments, and service models reshape capital allocation across the freight automation value chain. Understanding these divisions exposes where sensor costs, regulatory clarity, and operational design domain expansion concentrate commercial momentum.
Technology:
The perception stack spectrum spans cost-performance tradeoffs that determine fleet retrofit economics versus ground-up vehicle design.
- LiDAR:Solid-state units generate dense point-cloud mapping for centimeter-level localization in varied lighting conditions. Procurement concentrates among Texas-based fleet pilots where NHTSA exemption pathways reward high-fidelity environmental modeling for highway-speed automation.
- Camera Systems:Computer vision modules process visual scene understanding through deep neural networks trained on freight-specific object classification. Arizona DOT testing permits enable rapid mileage accumulation where camera-dominant stacks compete on hardware cost efficiency.
- Radar:Frequency-modulated continuous-wave sensors provide velocity measurement and all-weather redundancy at lower unit economics than LiDAR.
- Ultrasonic Sensors:Short-range proximity detection supports low-speed maneuvering in depot yards and loading dock approaches.
Established volume favors Camera Systems; emerging adoption favors LiDAR.
End User:
Customer archetypes diverge in route predictability, fleet scale, and tolerance for supervised versus driverless operations.
- Freight Carriers:Asset-heavy operators with dedicated lane contracts and terminal infrastructure amortize autonomous system costs across high-utilization schedules. These firms anchor early deployment along I-10 and I-35 corridors where Texas DOT permits enable driverless accumulation.
- Logistics Companies:Third-party providers integrate autonomous capacity into multi-modal networks, prioritizing interoperability with existing transportation management platforms.
- Retail Distributors:Private fleet operators with predictable distribution center routes optimize for dock-to-dock automation within defined operational design domains.
- E-Commerce Providers:Velocity-focused shippers with high-frequency, short-haul requirements drive last-mile automation exemptions in select urban municipalities.
Freight Carriers dominate current procurement; E-Commerce Providers are climbing the fastest as urban exemptions expand.
Deployment:
Operating environment constraints determine sensor configuration complexity and fallback system requirements.
- On-Road:Interstate and highway operations in mixed traffic demand full SAE Level 4 redundancy with remote supervision center integration. This segment concentrates in Arizona and Texas where state regulators have established permissive testing frameworks for heavy-duty autonomous vehicles.
- Dedicated Lanes:Segmented corridor operations with controlled access points reduce perception stack requirements and accelerate commercial deployment timelines.
- Mixed Traffic:Unrestricted road sharing with human-driven vehicles and vulnerable road users imposes the most stringent edge-case validation burdens.
- Off-Road:Mining, construction, and agricultural sites with geofenced boundaries enable earlier automation adoption through simplified operational design domains.
Dedicated Lanes capture near-term volume; Mixed Traffic holds the steepest expansion trajectory contingent on regulatory harmonization.
Service Type:
Revenue model differentiation separates asset utilization strategies from software-enabled network optimization.
- Freight Transport:Long-haul line-haul services between distribution centers constitute the primary autonomous truck application, with carriers restructuring operating cost assumptions around sensor maintenance rather than driver wage scales.
- Last Mile Delivery:Urban depot-to-dock operations previously blocked by dense pedestrian environments now attract capital as municipal exemptions proliferate.
- Load Hauling:Project-based bulk material movement in construction and energy sectors leverages off-road deployment simplicity.
- Transportation Management:Software layer services optimize autonomous fleet dispatch, route planning, and remote supervision coordination.
Freight Transport anchors current revenue; Last Mile Delivery is gaining share fastest as urban automation frameworks mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The I-10 and I-35 interstate corridors anchor North American freight automation infrastructure, enabling continuous driverless accumulation across Texas and Arizona testing grounds. State-level regulatory divergence is creating geographic concentration effects that reshape deployment sequencing.
United States
Texas DOT and Arizona DOT administer the most permissive heavy-duty autonomous vehicle testing frameworks globally, enabling Waymo LLC and Kodiak Robotics to accumulate driverless mileage across Dallas-Fort Worth distribution networks. NHTSA's FMVSS exemption pathways compress commercial deployment timelines for interstate corridor operations. The I-10 freight corridor between Phoenix and Houston serves as the primary proving ground for SAE Level 4 fleet validation.
Germany
KBA regulators at the Federal Motor Transport Authority are accelerating testing corridor designations on the A9 autobahn to retain automotive competitiveness against U.S. first-mover deployment. Daimler Truck leverages its Stuttgart manufacturing base to integrate Torc Robotics development partnerships into European type-approval frameworks. The A9 corridor between Munich and Nuremberg concentrates German autonomous freight validation.
China
MIIT standards development for intelligent connected vehicles is creating parallel regulatory pathways for heavy-duty automation distinct from Western SAE frameworks. NMPA oversight of automotive safety systems extends to autonomous truck perception stack certification. The Yangtze River Delta freight corridor between Shanghai and Suzhou hosts domestic developer testing.
Sweden
Einride's Stockholm headquarters anchors Nordic electric-autonomous freight integration, with regulators permitting driverless operations in geofenced industrial zones ahead of highway deployment. The country's national transport administration prioritizes freight automation within its carbon-neutral logistics roadmap. Gothenburg port automation clusters serve as entry points for continental European expansion.
Japan
METI industrial policy directs autonomous truck development toward labor-shortage mitigation in aging rural logistics networks. JIS standards development for automated driving systems proceeds in parallel with international harmonization efforts. The Chubu region around Nagoya concentrates automotive supplier integration for perception stack manufacturing.
Self-Driving Truck Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in sensor and compute modules. The vendor base stratifies across three functional layers: full-stack autonomy developers, Tier 1 truck OEMs with captive integration programs, and modular hardware suppliers. Technology licensing and strategic development partnerships constitute the dominant competitive moves, with vertical control over perception stack procurement separating scale-capable players from pilot-stage operators.
Within the full-stack autonomy tier, Waymo LLC and Aurora Innovation exemplify platform-first positioning, while Torc Robotics occupies a partnership-anchored role through its Daimler Truck integration. These three entities represent divergent pathways to commercial deployment: captive technology origination, independent venture-scale development, and OEM-embedded strategic collaboration.
| Leading Market Players |
|---|
| Waymo LLC |
| Torc Robotics |
| Aurora Innovation |
| TuSimple |
| Einride |
| Kodiak Robotics |
| Daimler Truck |
| Volvo Trucks |
| PACCAR |
| Others |
Supply Flow & Price Mechanics
Overcapacity in solid-state LiDAR photonics manufacturing is compressing unit economics and forcing tier-1 suppliers into volume-commitment contracts with autonomous truck developers. This utilization dynamic simultaneously erodes pricing power upstream while enabling downstream fleet operators to negotiate favorable sensor procurement terms that accelerate retrofit economics.
Pricing Analysis
Volume-discount tiering structures stratify across fleet scale commitments, with large freight carriers capturing 30-40% unit cost advantages over pilot-stage operators. Pricing differentiation hinges on perception stack certification grade—NHTSA exemption pathway validation commands premium positioning—and geographic delivery cost to Texas and Arizona proving grounds. Cost compression in camera-dominant stacks is intensifying because Tier 1 automotive suppliers are scaling automotive-grade computer vision modules. Mid-size carriers exhibit the highest price sensitivity, while asset-heavy operators with dedicated lane contracts demonstrate greater tolerance for upfront sensor investment.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for autonomous truck perception stack procurement. Component manufacturing concentrates in Taiwan, South Korea, and Japan for high-performance LiDAR emitters and specialized compute silicon. Raw material dependencies span rare-earth elements for laser diodes, high-purity germanium for photodetectors, and advanced substrates for sensor fusion processors. Single-source vulnerability in solid-state LiDAR MEMS fabrication creates concentrated disruption risk. Distribution runs through Tier 1 automotive supplier networks with direct OEM integration programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Freight automation constitutes a defensive-moat market where regulatory entrenchment—specifically NHTSA exemption accumulation and state-level testing permit density—creates durable competitive positioning that late entrants cannot readily replicate.
For Market Incumbents: Insulate accumulated mileage advantages by deepening integration with Daimler Truck and PACCAR manufacturing footprints. Secure exclusive SensorPod architecture licensing to block modular hardware competitors. Prioritize remote supervision center density along I-10 and I-35 corridors to create switching cost barriers against emerging platform entrants. For New Entrants and Emerging Players: Build out last-mile automation capabilities in Dallas-Fort Worth and Phoenix urban freight zones where municipal exemptions are expanding fastest. Target retail distributors with predictable distribution center routes as the most penetrable customer archetype. Pursue transportation management software partnerships as the primary go-to-market angle to bypass capital-intensive fleet ownership requirements. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among full-stack autonomy developers with embedded OEM partnerships rather than standalone hardware suppliers. Long-term viability across the autonomous freight value chain hinges on regulatory relationship depth and real-world mileage accumulation. Monitor NHTSA exemption grant velocity as the critical inflection signal for commercial deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Perception Stack Certification Investment | NHTSA exemption pathway validation accelerates commercial deployment timelines for interstate corridor operations. |
| OEM Strategic Partnership | Daimler Truck and Torc Robotics integration demonstrates captive manufacturing scale advantages in European type-approval frameworks. |
| Remote Supervision Center Expansion | Texas DOT permissive frameworks enable driverless mileage accumulation without safety driver cost structures. |
| SensorPod Modular Architecture Licensing | Rapid hardware swap capabilities reduce fleet downtime across varied route condition configurations. |
| Last-Mile Urban Exemption Pursuit | Municipal automation frameworks in Dallas-Fort Worth unlock depot-to-dock revenue streams previously blocked by pedestrian density. |
Methodological Framework
Operator-level perspectives from fleet operations directors, autonomous vehicle program managers, Tier 1 supplier procurement leads, and state DOT permitting officials anchored the qualitative base for this analysis. Primary interview insights combined with secondary validation against NHTSA exemption filings, FMCSA regulatory dockets, Texas DOT and Arizona DOT permit registries, and autonomous vehicle mileage disclosure reports. Bottom-up sensor cost modeling and top-down freight automation market sizing underwent iterative triangulation to converge on segment-level estimates.
Scenario-bracketing framed the analytical approach across the projection horizon, with optimistic and conservative regulatory adoption pathways bounding the central forecast. Segmentation dimensions modeled include technology stack composition, deployment environment constraints, service type revenue models, and fleet scale tier. CAGRs derived from logistic diffusion curves fitted to historical automotive technology adoption patterns, with inputs from LiDAR cost decline trajectories and state-level regulatory permit velocity.
Practitioners should monitor NHTSA exemption grant rates, solid-state LiDAR supplier capacity utilization, and FMCSA hours-of-service regulatory clarification for early signals of forecast deviation. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
Germany Autonomous Navigation Market
Autonomous Vehicles
Autonomous Vehicle Management Services Market
Autonomous Vehicles
L4 Autonomous Driving Market
Autonomous Vehicles
Europe Autonomous Navigation Market
Autonomous Vehicles
HD Map for Autonomous Vehicle Market
Autonomous Vehicles
Adaptive Cruise Control (ACC) and Blind Spot Detection (BSD) Market
Autonomous Vehicles
Battery-Electric Self-Driving Car Market
Autonomous Vehicles
Autonomous Parking System Market
Autonomous Vehicles
Predictive Automobile Technology Market
Autonomous Vehicles
Autonomous Vehicle ECU Market
Autonomous Vehicles
Canada Autonomous Navigation Market
Autonomous Vehicles
Self-Driving Bus Market
Autonomous Vehicles
India Automotive Advanced Driver Assistance Systems Market
Autonomous Vehicles
Autonomous Ride-Sharing Services Market
Autonomous Vehicles
Autonomous Delivery Robots Market
Autonomous Vehicles
Self-Driving Electric Vehicle Market