
 Semi Autonomous and Autonomous Vehicles Market | 2026-2036
Semi Autonomous and Autonomous Vehicles Market Size, Share, and Industry Trends Forecast 2026-2036
Semi Autonomous and Autonomous Vehicles Market Intelligence
The competitive landscape for autonomous systems is shifting as a clear divergence emerges between automakers offering premium, integrated Level 3 capabilities and those focusing on mass-market Level 2+ driver-assist packages. Mercedes-Benz Group AG leads in certified Level 3 systems for consumer vehicles in specific jurisdictions. Waymo specializes in developing Level 4 autonomous ride-hailing services. Meanwhile, Continental AG supplies a broad range of sensor and software components to multiple original equipment manufacturers.
Semi autonomous and autonomous vehicles are defined by their ability to perform driving tasks with reduced or no human intervention, categorized by SAE International's Levels of Driving Automation from 1 to 5. These systems function by processing data from a suite of sensors like LIDAR and cameras through sophisticated computer vision algorithms. Level 2 and Level 3 systems currently dominate the market volume, primarily for personal use in consumer vehicles. The fastest-growing segment involves Level 4 technology, driven by deployments in controlled environments for logistics and ride sharing applications.
Regulatory frameworks are critical in shaping deployment pathways, with agencies like the US NHTSA, the European Commission, and China's MIIT establishing guidelines for testing and public road usage. These regulations directly influence vehicle design, data privacy protocols, and the certification requirements for safety-critical systems. The key decision for industry stakeholders now revolves around establishing a consensus on international data sharing standards and a clear liability model for automated driving incidents.
Market Dynamics
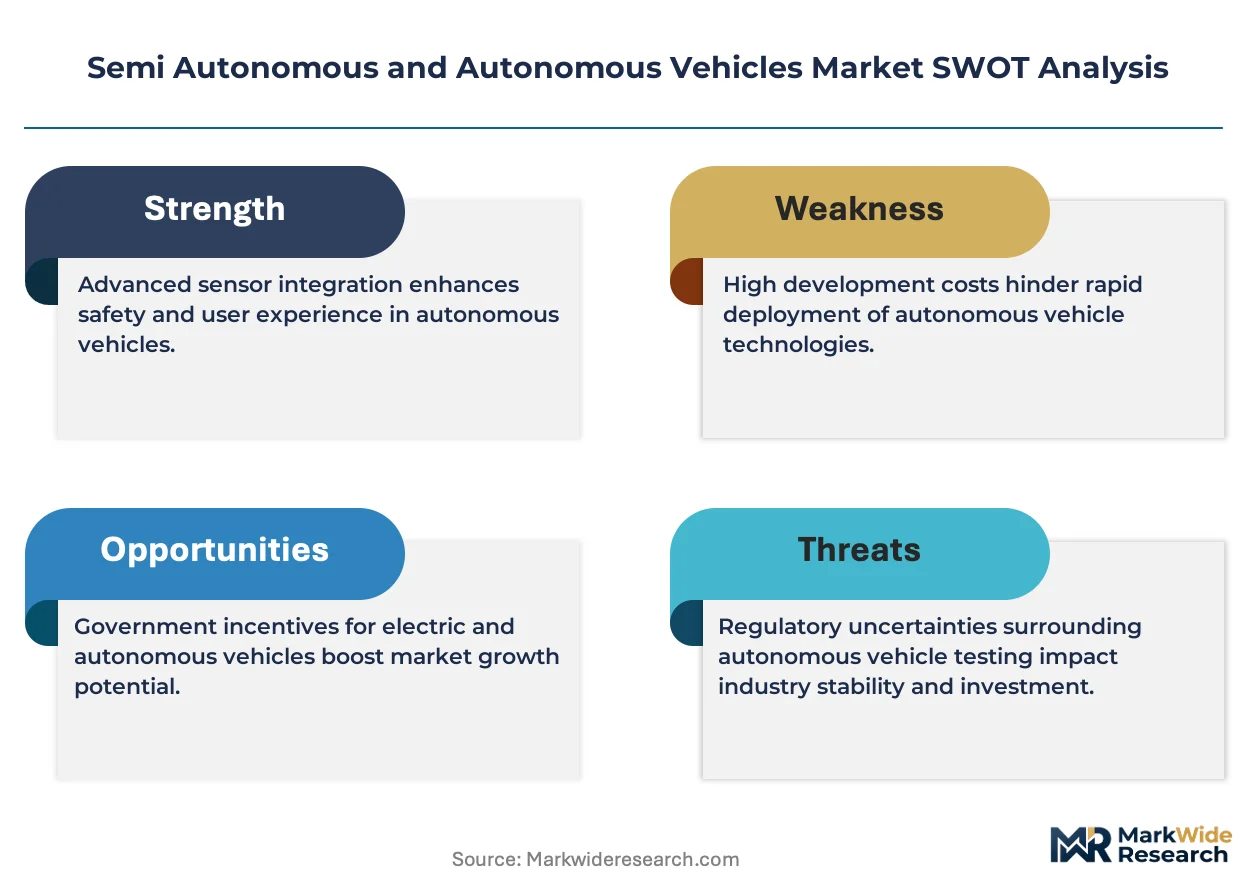
The fundamental market dynamic is the technological and commercial divergence between incremental Level 2+ enhancements for the mass market and the capital-intensive pursuit of Level 4 and 5 autonomy for specialized applications like ride-hailing and logistics.
Growth Catalysts
- Logistics Efficiency Mandates:The freight transport sector's push for reduced operating costs and faster delivery times is a primary catalyst for Level 4 autonomous trucks on hub-to-hub routes.
- Government Support in China:Proactive policies from China's MIIT, combined with significant public investment in smart road infrastructure, create a uniquely favorable environment for large-scale AV testing and deployment.
- Maturation of Sensor Fusion:Advances in algorithms that process and integrate data from LIDAR, radar, and camera suites are enabling more reliable perception systems, which are essential for higher levels of automation.
Market Restraints
- High System Cost:The expense of automotive-grade LIDAR sensors and high-performance computing platforms remains a significant barrier to the widespread adoption of Level 3 and higher systems in personal vehicles.
- Fragmented Regulatory Frameworks:A lack of harmonized international safety and validation standards between bodies like the US NHTSA and the European Commission complicates development and slows cross-border deployment.
- Adverse Condition Performance:Autonomous systems continue to face reliability challenges in difficult weather conditions such as heavy snow or rain, and in navigating unpredictable human behavior in dense urban settings.
Strategic Opportunities
- Controlled Environment Automation:Deploying fully autonomous vehicles in closed-loop environments like ports, mining sites, and large distribution centers offers a clear and immediate path to commercialization with fewer regulatory hurdles.
- V2X Communication Services:The integration of vehicle-to-everything (V2X) technology creates an opportunity to offer data services that enhance situational awareness beyond the range of onboard sensors, improving safety and traffic flow.
- Smart City Pilot Programs:Government-led initiatives in geographies like the UAE and Singapore provide dedicated testbeds for deploying autonomous shuttles and robotaxi services, accelerating learning and public acceptance.
Industry Challenges
- Specialized Talent Scarcity:A persistent shortage of engineers with expertise in both AI and safety-critical automotive systems engineering creates a significant bottleneck for development and validation teams.
- Validation and Simulation Burden:The immense capital and time required to verify system safety through billions of miles of simulated and real-world driving presents a major operational challenge for all developers.
- Cybersecurity and Data Governance:Establishing robust protocols to protect vehicles from cyber threats and manage the vast amounts of sensitive data they generate in compliance with rules like GDPR is a critical operational hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semi Autonomous and Autonomous Vehicles Market |
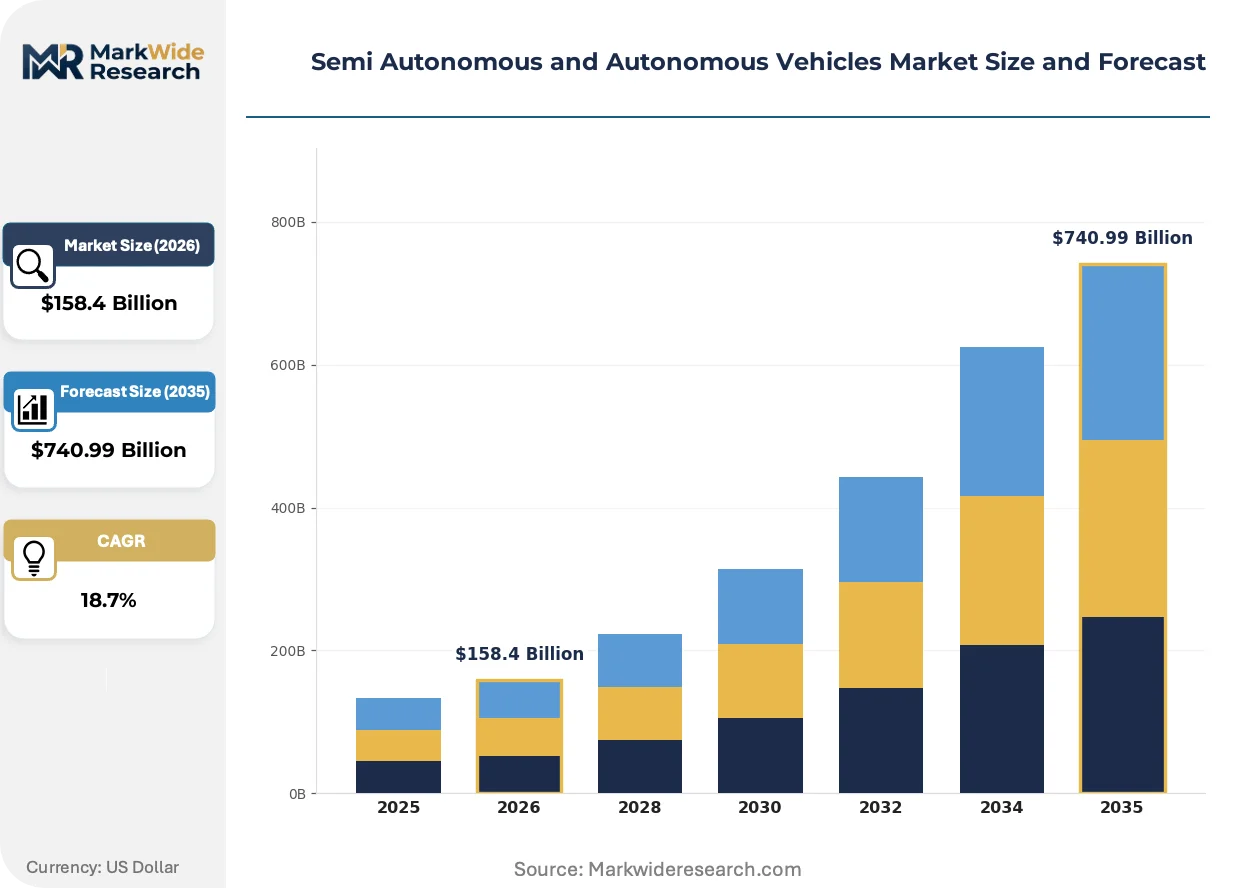
| Market Size in 2026 | $158.4 Billion |
| Market Size in 2035 | $740.99 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Level 1, Level 2, Level 3, Level 4 End User: Consumers, Logistics, Public Transport, Ride Sharing Technology: Sensor Fusion, Computer Vision, LIDAR, Machine Learning Application: Personal Use, Freight Transport, Autonomous Delivery, Emergency Services |
| Companies Covered | Tesla, Waymo, Mercedes-Benz Group AG, BMW AG, General Motors, Ford Motor Company, Volkswagen, Continental AG, Robert Bosch GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semi Autonomous and Autonomous Vehicles Market Strategic Shifts & Innovations
The market is being redefined by the transition to software-defined vehicles, where core functionality and performance are increasingly decoupled from hardware. This shift enables continuous improvement and new business models through over-the-air updates, changing the nature of automotive engineering.
Centralized compute architectures combine the processing for sensors, infotainment, and vehicle controls onto a single, powerful system-on-a-chip. Automakers pursuing Level 3 and higher automation are rapidly adopting these platforms to manage the immense data throughput. This paradigm is absorbing the functions of dozens of disparate electronic control units, simplifying vehicle design and enabling complex software updates.
The European Commission's updated General Safety Regulation establishes a clear legal and technical framework for the type approval of automated driving systems. This provides a predictable certification pathway for automakers to launch vehicles with Level 3 features across all EU member states. The passenger car segment is most affected, now aligning its validation processes with these specific pan-European requirements to gain market access.
A demand-side shift toward subscription-based feature activation is altering how consumers access advanced driver-assistance functions. This model unbundles capabilities like automated parking or highway lane-keeping from fixed vehicle trim levels, allowing for post-purchase activation via software. This trend is most prominent in the premium electric vehicle segment in North America and Europe, creating new recurring revenue streams for manufacturers.
Semi Autonomous and Autonomous Vehicles Market Segmentation
The Semi Autonomous and Autonomous Vehicles Market differentiates across various dimensions, reflecting the complex interplay of technological maturity, operational use cases, and regulatory readiness. Understanding these distinct segments is crucial for stakeholders to identify growth pockets and tailor development strategies. This segmentation highlights where innovation and investment are concentrating.
Product Type:
Supply concentration in the autonomous vehicle market currently favors established driver-assist systems, while advanced capabilities are gaining traction in specialized niches.
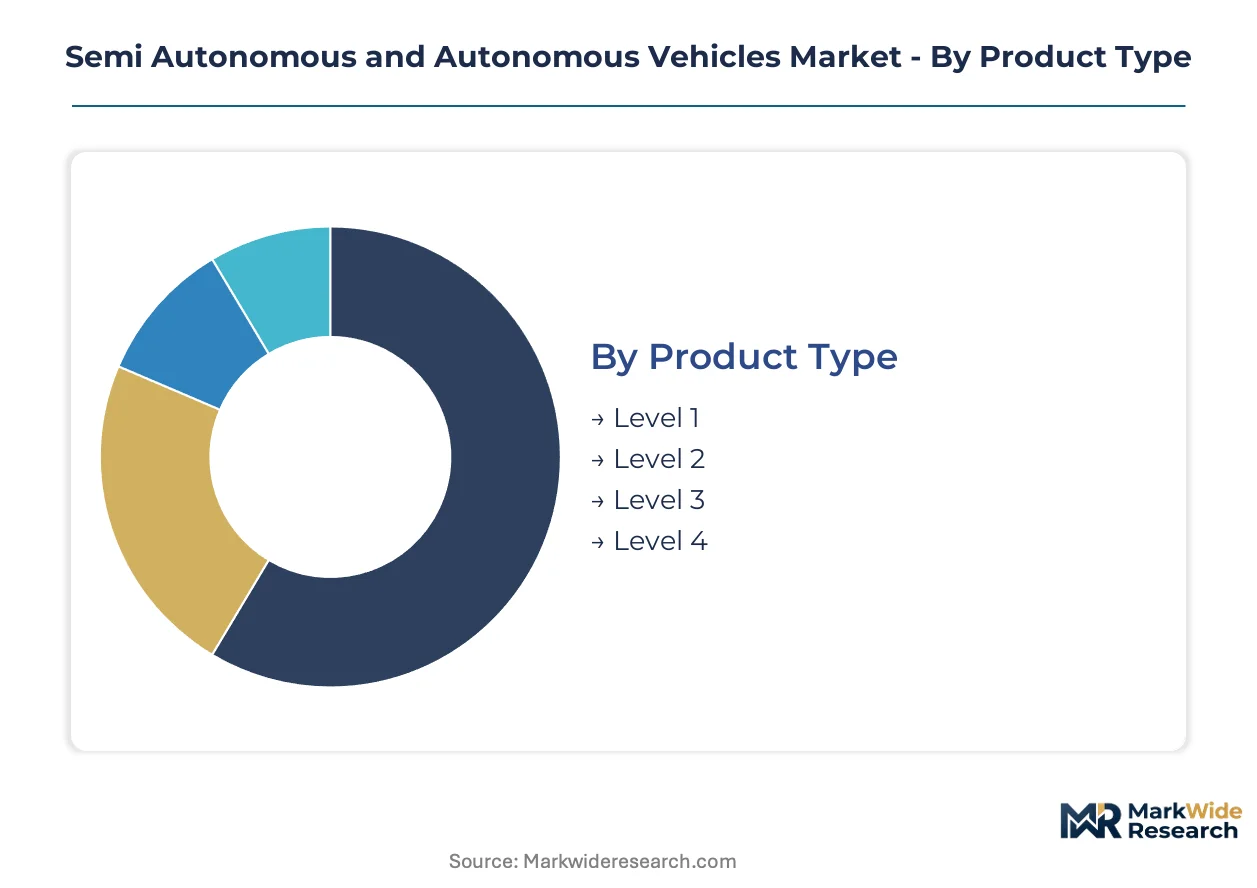
- Level 1:These systems provide minimal driver assistance, offering a single automated function like adaptive cruise control. They are standard in many new consumer vehicles.
- Level 2:These systems combine at least two automated functions, such as adaptive cruise control with lane centering, requiring continuous driver supervision. Demand concentrates significantly in consumer vehicles, particularly in Europe and North America, driven by convenience and safety features.
- Level 3:Conditional automation allows drivers to disengage under specific conditions. These systems demand human readiness to intervene, with Mercedes-Benz offering them in select European jurisdictions.
- Level 4:High automation systems can perform all driving functions under specific operational design domains, with no expectation of human intervention. Demand is concentrating in China and the US for ride-hailing and logistics applications, driven by operational efficiency mandates.
Today's leader: Level 2. Tomorrow's challenger: Level 4.
End User:
The market's end-user segments are shaped by the varied application requirements and the differing risk tolerances across industries for autonomous technologies.
- Consumers:Individual buyers of personal vehicles equipped with semi-autonomous features, primarily Level 2 and Level 3 systems. Demand is strong in North America and Europe, driven by convenience, safety, and comfort features.
- Logistics:Companies utilizing autonomous vehicles for freight transport, warehousing, and last-mile delivery, often employing Level 4 technology. Demand is particularly high in the US for long-haul trucking and in China for urban delivery, driven by cost reduction and efficiency.
- Public Transport:Government agencies and private operators deploying autonomous shuttles and buses for urban mobility solutions.
- Ride Sharing:Companies operating autonomous taxis and ride-hailing services, typically in controlled urban environments.
The consumer segment represents the largest volume, while logistics is expanding most quickly.
Technology:
The maturity curve of various underlying technologies dictates their current market penetration and future growth potential within autonomous systems.
- Sensor Fusion:This technology integrates data from multiple sensors like LIDAR, radar, and cameras to create a comprehensive environmental model. Its maturation is critical for Level 3 and Level 4 systems, particularly in complex urban scenarios.
- Computer Vision:Algorithms that enable vehicles to interpret visual data from cameras, identifying objects, lanes, and traffic signs.
- LIDAR:Light Detection and Ranging sensors create precise 3D maps of the vehicle's surroundings, essential for robust perception in higher automation levels. Demand is intensifying in Level 4 applications, especially in robotaxis and autonomous trucks, due to its accuracy.
- Machine Learning:Advanced algorithms that allow autonomous systems to learn from data, improving perception, prediction, and decision-making capabilities.
Sensor fusion forms the core intelligence, with LIDAR gaining share fastest for advanced perception.
Application:
The market's application segments are differentiated by their operational environments, regulatory requirements, and the specific value propositions they offer to end-users.
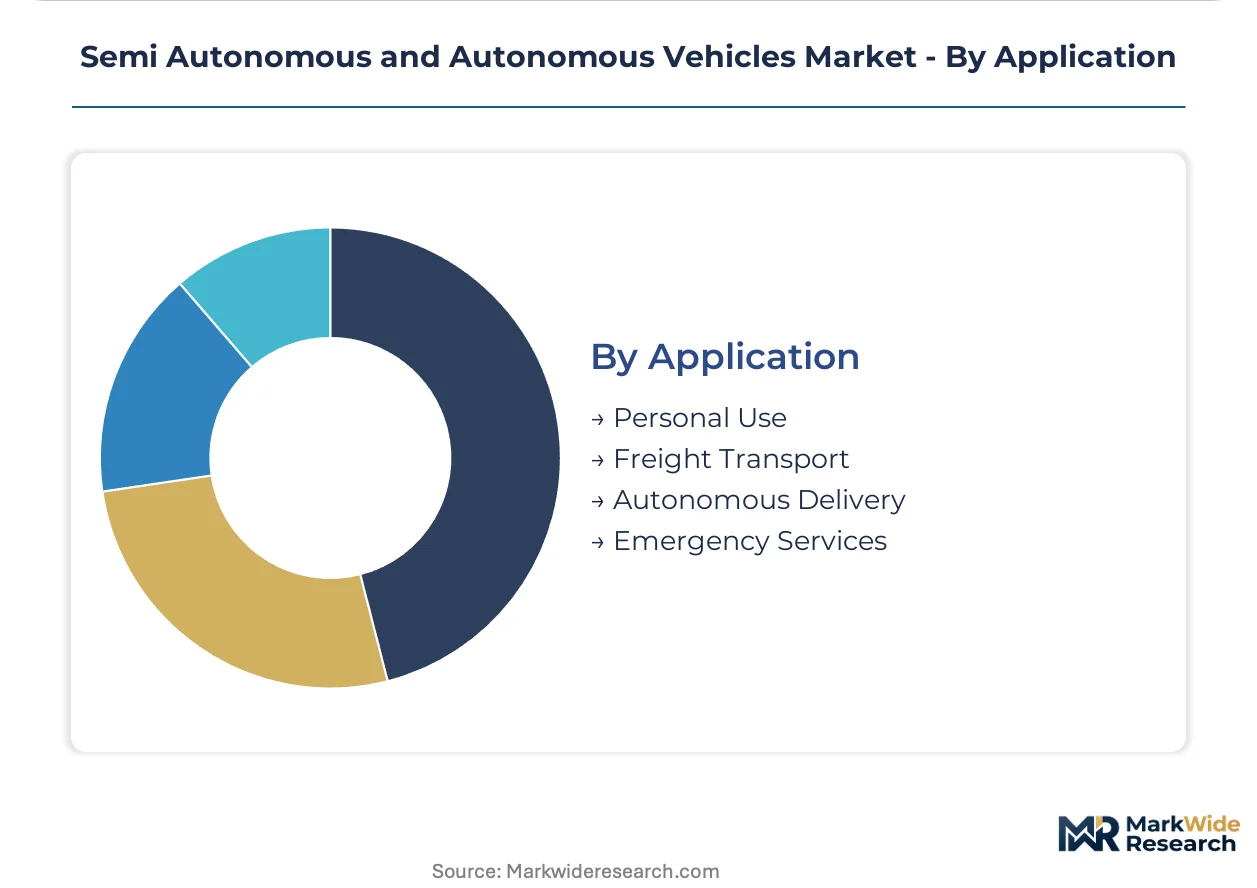
- Personal Use:Autonomous features integrated into privately owned consumer vehicles for daily commuting and travel. Level 2 and Level 3 systems dominate this segment, with demand concentrated in technologically advanced economies like Germany and Japan.
- Freight Transport:Autonomous trucks and specialized vehicles employed for long-haul logistics and port operations. This segment primarily utilizes Level 4 technology, with significant deployments in the US and China driven by mandates for efficiency and reduced labor costs.
- Autonomous Delivery:Automated vehicles and robots for last-mile delivery of goods and packages in urban and suburban areas.
- Emergency Services:Autonomous vehicles designed to assist in emergency response, including ambulances and police support vehicles.
Personal use currently holds the largest market volume, while freight transport exhibits the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Talent concentration in software engineering and AI anchors the global development of semi-autonomous and autonomous vehicles. Key nations are attracting significant investment due to their robust research ecosystems and skilled workforces. These regions are actively shaping the technological trajectory and commercial deployment of advanced driving systems.
China
Demand for autonomous vehicles in China is driven by logistics efficiency mandates and urban mobility solutions. Proactive policies from China's MIIT, combined with significant public investment, create a favorable environment. Cities like Shanghai and Beijing establish dedicated testbeds for robotaxis and autonomous delivery services.
United States
The United States sees strong demand for Level 4 autonomous ride-hailing and long-haul trucking applications. The US NHTSA establishes guidelines for testing and public road usage, influencing vehicle design and certification. Silicon Valley remains a hub for software development and AI innovation, attracting major autonomous vehicle companies.
Germany
Germany's automotive engineering prowess drives demand for premium Level 3 systems in consumer vehicles. The KBA provides a clear legal and technical framework for type approval of automated driving systems. Stuttgart and Munich are centers for automakers developing advanced driver-assistance features.
Japan
Japan's aging population and focus on safety drive demand for autonomous public transport and mobility solutions. METI supports research and development in autonomous driving technologies, including V2X communication. Tokyo and Toyota City deploy autonomous shuttles and test advanced driver-assist systems in urban environments.
South Korea
South Korea's advanced telecommunications infrastructure and smart city initiatives fuel demand for autonomous shuttles and connected vehicle services. The Ministry of Land, Infrastructure and Transport (MOLIT) sets guidelines for autonomous vehicle testing and commercialization. Seoul and Pangyo Technovalley actively develop and test Level 4 autonomous systems.
Semi Autonomous and Autonomous Vehicles Market Key Industry Players
Top-tier vendors anchor the development of full-stack autonomous driving solutions, while specialized component suppliers and software integrators form foundational layers. The market structure exhibits a blend of consolidation among established automotive players and fragmentation within the technology provider segment. Archetypes include full-stack autonomous developers, premium OEM integrators, and broad sensor/software suppliers. Strategic partnerships between technology firms and traditional automakers are a dominant competitive move.
Within the full-stack autonomous development tier, Waymo exemplifies a company focused on Level 4 ride-hailing services, demonstrating expertise in complex urban operational design domains and extensive real-world testing. Continental AG represents a leading broad sensor and software component supplier to multiple original equipment manufacturers, providing critical perception and processing hardware platforms. Mercedes-Benz Group AG occupies a position among premium OEM integrators, leading in certified Level 3 systems for consumer vehicles, particularly within specific European jurisdictions and under defined operational conditions.
| Leading Market Players |
|---|
| Tesla |
| Waymo |
| Mercedes-Benz Group AG |
| BMW AG |
| General Motors |
| Ford Motor Company |
| Volkswagen |
| Continental AG |
| Robert Bosch GmbH |
| Others |
Cost & Logistics Intelligence
The EU Green Deal mandates for sustainable mobility gate both qualified component supply and premium-tier pricing access for advanced autonomous vehicle systems. These regulations drive innovation and differentiate offerings in the market.
Pricing Analysis
Bundled versus unbundled service offerings define the pricing landscape for autonomous vehicle features. Subscription-based feature activation dominates, especially in premium electric vehicles, creating new recurring revenue streams. Price differentiation stems from certification levels for systems like Level 3 and the brand premium of OEM integrators. Cost compression in Level 2+ systems intensifies due to the high system cost of advanced components, making consumers more price sensitive than logistics operators.
Supply Chain Analysis
Regional distribution centers and hub-and-spoke patterns are critical for the timely delivery of autonomous vehicle components. Supply concentration for advanced hardware relies heavily on specialized manufacturing in China and software development in the United States. Key component dependencies include LIDAR sensors and high-performance computing platforms. Single-source vulnerability for these specialized inputs presents a structural risk, with distribution running through direct channels to original equipment manufacturers and then to end-user fleets or consumers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a stable compounder, driven by persistent logistics efficiency mandates across freight transport applications. The long-term trajectory for autonomous systems remains robust, reflecting sustained investment and technological progress.
For Market Incumbents: Acquire specialized AI software startups to accelerate Level 4 development and mitigate the threat from emerging pure-play autonomous developers. Invest in advanced sensor manufacturing capabilities to secure critical component supply and reduce reliance on third-party vendors. Prioritize certification investment for Level 3 systems to expand market access across European jurisdictions. Focus R&D on improving adverse condition performance to enhance system reliability.
For New Entrants and Emerging Players: Specialized perception technology offers a first-mover wedge into niche industrial automation for controlled environments like ports and mining sites. Target underpenetrated segments requiring Level 4 capabilities with fewer regulatory hurdles. Develop V2X communication services as a go-to-market angle, enhancing situational awareness beyond onboard sensors. Offer subscription-based models for software-defined vehicle features to generate recurring revenue streams.
For Investors and Strategic Acquirers: Roll-up economics work for technology integrators because of the fragmented nature of specialized software and sensor development. Long-term viability rests on autonomous systems becoming foundational for future mobility and logistics infrastructure over the next decade. Target acquisition profiles include specialized AI software developers and advanced sensor manufacturers. The signal to watch for inflection is the establishment of harmonized international data sharing standards for automated driving incidents.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | Enables continuous improvement and new business models through over-the-air updates. |
| LIDAR Sensor Development | Enhances robust perception for Level 4 applications in robotaxis and autonomous trucks. |
| V2X Communication Partnership | Integrates vehicle-to-everything technology to improve situational awareness and traffic flow. |
| Smart City Pilot Participation | Accelerates learning and public acceptance for autonomous shuttles and robotaxi services. |
| Certification Pathway Alignment | Secures market access for Level 3 features across multiple European member states. |
Research Approach
Coverage spans China, the United States, Germany, and Japan, with primary inputs from each region. This involved combining insights from OEM platform engineers, logistics fleet managers, regulatory affairs leads, and AI software developers. Secondary validation drew from US NHTSA guidelines, European Commission regulations, China MIIT policies, and specialized industry reports. A rigorous bottom-up and top-down triangulation approach ensured data consistency.
Market granularity was modeled across product type, end user, technology, application, and key geographic regions. The analytical framework integrated historical trends and projected market dynamics over the analysis window to derive compound annual growth rates. Key forecast inputs included the maturation of sensor fusion technologies and specific government infrastructure investments. This detailed segmentation supports robust future projections.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to fragmented regulatory frameworks and adverse weather performance challenges. These forecasts reflect underlying assumptions about technological advancements and market adoption. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
China Autonomous Navigation Market
Autonomous Vehicles
Autonomous Vehicle ECU Market
Autonomous Vehicles
Robotaxi Market
Autonomous Vehicles
Latin America ADAS Market
Autonomous Vehicles
Automated Valet Parking (AVP) Market
Autonomous Vehicles
Self-Driving Electric Vehicle Market
Autonomous Vehicles
Autonomous Bus Market
Autonomous Vehicles
Zonal Vehicle Control Unit Architectures Market
Autonomous Vehicles
Singapore Autonomous Navigation Market
Autonomous Vehicles
Self-Driving Bus Market
Autonomous Vehicles
Global Robot Cars and Trucks Market
Autonomous Vehicles
Spain Autonomous Navigation Market
Autonomous Vehicles
US Autonomous Car Market
Autonomous Vehicles
Blind Spot Detection Market
Autonomous Vehicles
Europe Autonomous Navigation Market
Autonomous Vehicles
Autonomous Driving Technology Market