
 Automated Truck Technology Market | 2026-2036
Automated Truck Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Automated Truck Technology Market Insights
Fleet procurement channels for autonomous trucking are reshaping how OEMs and technology vendors reach end customers. Waymo LLC leverages its Waymo Driver platform to anchor partnerships with freight networks seeking Level 4 automation on designated corridors. Aurora Innovation Inc. sustains development velocity through its Aurora Horizon service, competing on integrated hardware-software stacks rather than component sales. Daimler Truck AG dominates manufacturing scale, extending its traditional dealer and direct-fleet relationships into autonomous vehicle-as-a-service models.
Automated truck technology encompasses sensor fusion systems, drive-by-wire architectures, and redundant computing platforms that enable commercial vehicles to operate without continuous human supervision across highway and limited urban environments. These systems typically integrate LiDAR arrays with 360-degree coverage, high-definition GPS correction, and neural network-based perception stacks to achieve operational design domains spanning defined freight corridors. Long-haul shipping represents the most structurally advanced application segment, with established freight density and predictable route geometry supporting early commercialization, while last-mile delivery remains technically fragmented due to unstructured urban environments. Heavy-duty trucks concentrate current capital deployment and margin pools, though autonomous delivery vans are attracting technology specialization as e-commerce fulfillment networks seek density in urban zones.
The US NHTSA governs Federal Motor Vehicle Safety Standards for automated driving system equipment, while the FAA coordinates unmanned aerial and ground cargo integration in certain pilot zones; the EU AI Act and CE marking requirements shape algorithmic transparency and type-approval pathways for European deployment. These frameworks create divergent compliance burdens that favor vendors with regulatory affairs capacity across multiple jurisdictions. Stakeholders must monitor how state-level operational permits in the US and emerging EU harmonization timelines alter viable go-to-market sequencing without assuming regulatory convergence.
Market Dynamics
Fleet operators in North America and Europe face acute driver shortages exceeding sixty thousand unfilled positions, forcing logistics providers toward supervised autonomy as the only scalable path to maintain freight velocity across major corridors.
Growth Catalysts
- EU F-Gas Regulation:Phase-down mandates for fluorinated greenhouse gases are accelerating electric and hydrogen powertrain adoption in automated truck platforms, creating regulatory pull for zero-emission autonomous fleets.
- Long-haul freight density:Predictable highway geometry and established shipping volumes on Texas-Arizona-California corridors enable supervised Level 4 deployment without urban complexity.
- Neural network perception:Transformer-based sensor fusion architectures are reducing false-positive rates in adverse weather, expanding operational design domains beyond clear-sky conditions.
Market Restraints
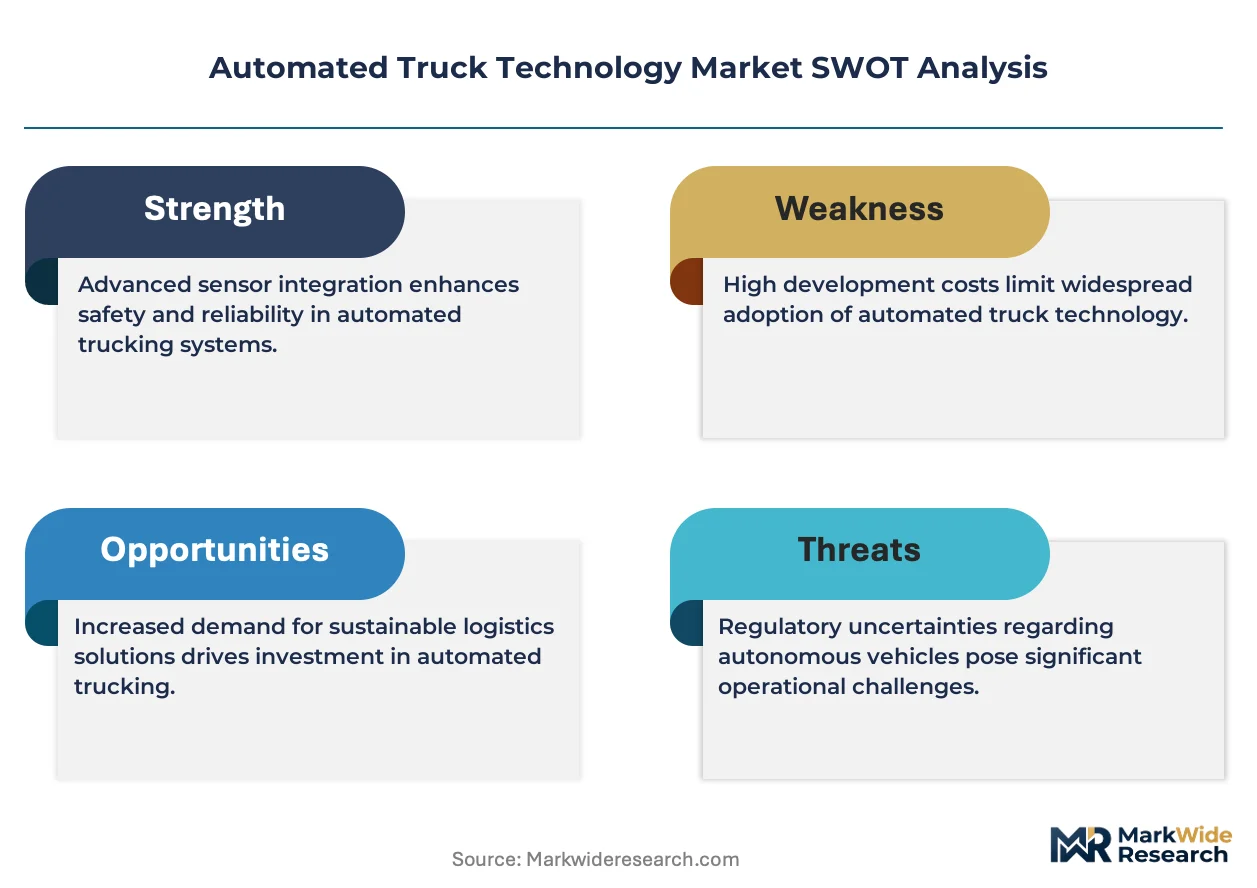
- LiDAR supply concentration:High-performance solid-state LiDAR arrays depend on limited semiconductor foundry capacity in Taiwan and South Korea, creating input bottlenecks for sensor stack procurement.
- US NHTSA FMVSS compliance:Federal Motor Vehicle Safety Standards lack specific test protocols for automated driving system equipment, forcing manufacturers into prolonged exemption petition cycles.
- Human-supervised fallback costs:Remote operator centers and in-cab safety drivers add labor overhead that narrows the operating cost advantage against conventional trucking.
Strategic Opportunities
- EU AI Act algorithmic transparency:Early compliance with European Union conformity assessment pathways positions vendors for streamlined type-approval across member states.
- Platooning corridor infrastructure:Dedicated cooperative intelligent transport systems on German autobahn segments enable vehicle-to-infrastructure coordination that reduces following distances and fuel consumption.
- Last-mile van automation:E-commerce fulfillment networks in dense urban zones present unserved demand for smaller automated delivery vehicles with lower sensor payload requirements.
Industry Challenges
- Systems safety engineering talent:ISO 26262 functional safety certification requires specialized hardware-software integration expertise that outpaces current graduate pipeline output.
- Multi-jurisdiction operational permitting:US state-level autonomous vehicle regulations vary in driver presence requirements, insurance mandates, and weight exemptions, complicating interstate route planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automated Truck Technology Market |
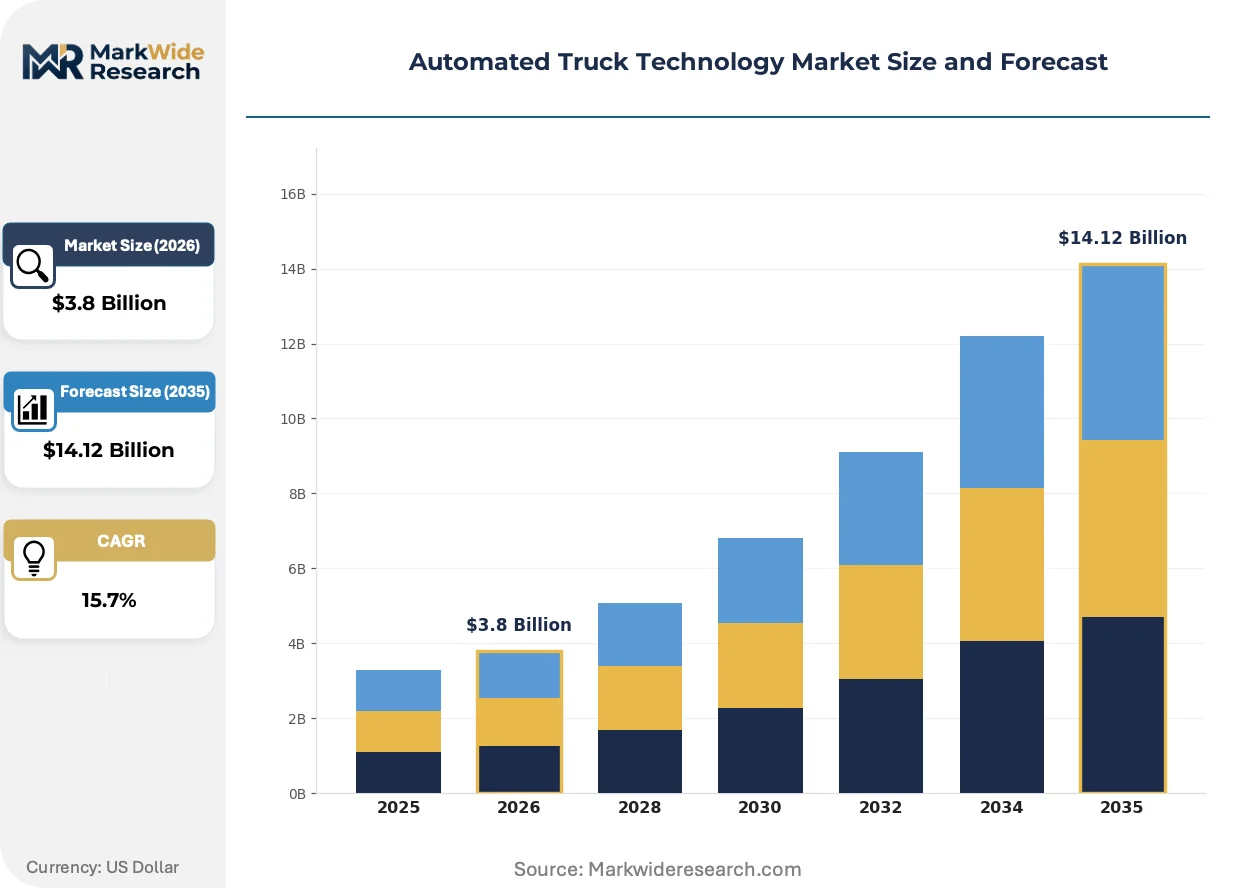
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $14.12 Billion |
| CAGR (2026 – 2036) | 15.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Freight Transportation, Supply Chain Management, Last-Mile Delivery, Long-Haul Shipping Vehicle Type: Heavy-Duty Trucks, Light-Duty Trucks, Autonomous Delivery Vans, Specialty Vehicles Technology: LiDAR, Computer Vision, GPS Navigation, AI Algorithms End User: Logistics Providers, Retail Companies, Fleet Operators, Agricultural Sector |
| Companies Covered | Waymo LLC, Aurora Innovation Inc., TuSimple Holdings Inc., PlusAI Inc., Daimler Truck AG, Embark Trucks Inc., Einride AB, Gatik AI Inc., PACCAR Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automated Truck Technology Market Trends and Innovations
Sensor hardware commoditization and regulatory framework maturation are compressing the timeline from pilot deployment to revenue service, while fleet procurement models pivot from asset ownership to per-mile service contracts.
Camera-first perception stacks with transformer-based depth estimation are rendering obsolete expensive multi-LiDAR configurations that dominated early autonomous truck prototypes. Tier 1 suppliers in Germany and Japan are qualifying vision-only systems for highway operational design domains. This compression of sensor bill-of-materials is enabling mid-size freight carriers to access automation technology previously reserved for capital-rich national fleets.
The EU AI Act's risk-based classification system for automated driving algorithms is forcing vendors to document training data provenance and model validation protocols before CE marking approval. European type-approval authorities are rejecting black-box neural networks that lack traceable decision pathways. Heavy-duty truck manufacturers are responding by establishing in-house explainable AI teams and partnering with academic institutions for regulatory-grade verification methods.
Fleet procurement departments are unbundling vehicle acquisition from technology subscription, treating automation hardware as an operating expense rather than capital expenditure. Third-party autonomous trucking-as-a-service providers are capturing direct relationships with retail shippers that previously negotiated through OEM dealer networks. This channel disintermediation is most pronounced among US regional carriers operating fixed routes between distribution centers, where per-mile pricing aligns costs directly with freight volume fluctuations.
Automated Truck Technology Market Segmentation
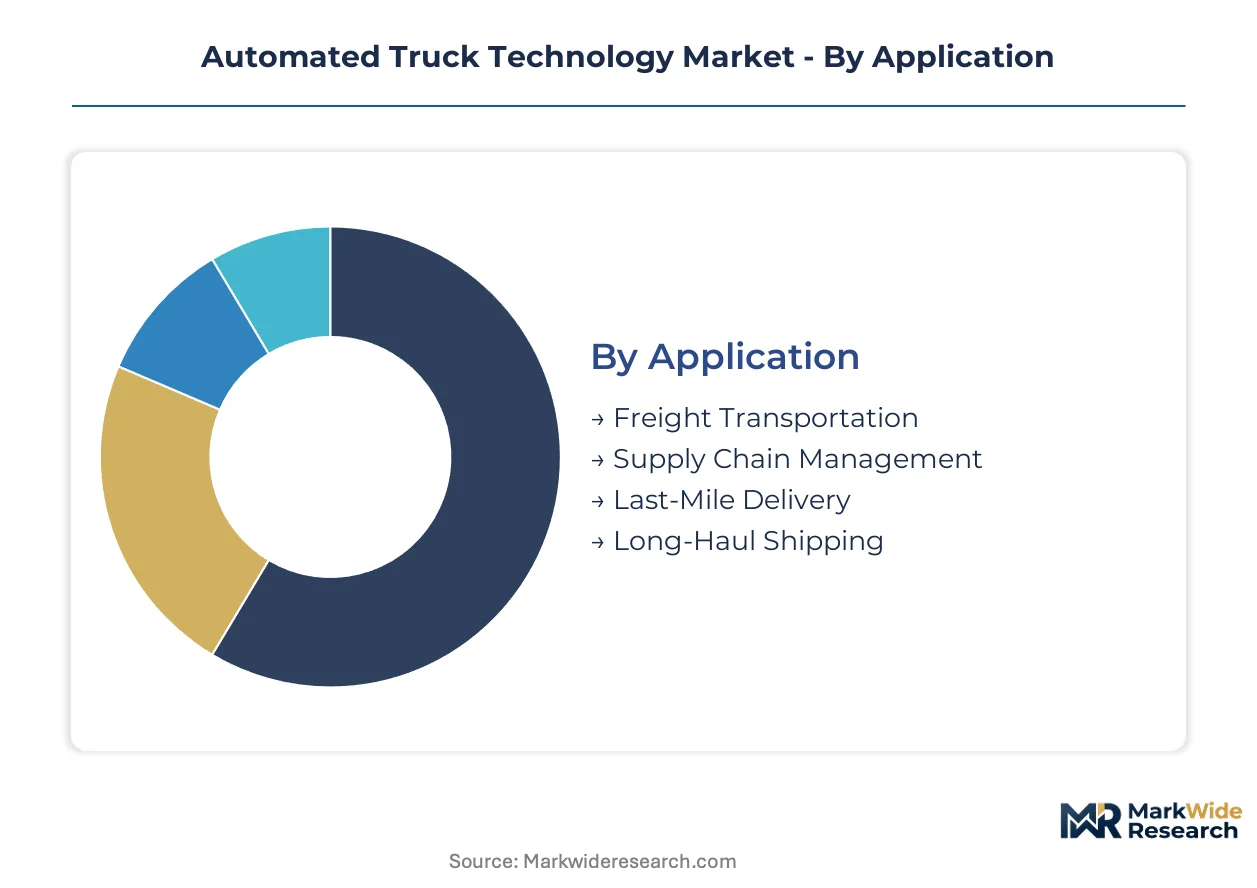
Automated truck technology deploys differently across operational contexts, with each segment demanding distinct sensor configurations, software architectures, and service support models. Procurement patterns vary sharply between long-haul freight networks and urban delivery fleets, creating divergent technology roadmaps for vendors.
Application:
After-sales service intensity escalates with operational complexity, as freight corridors require continuous mapping updates while last-mile deployments demand rapid incident response capabilities.
- Freight Transportation:Hub-to-hub automation on interstate corridors leverages predictable highway geometry and established weigh station infrastructure. Demand concentrates among US-based logistics providers operating Texas-Arizona-California routes, where supervised Level 4 deployment has achieved commercial scale.
- Long-Haul Shipping:Extended operational design domains spanning multiple states require redundant computing stacks and remote operator center integration. European freight networks on German autobahn corridors are deploying platooning systems with cooperative intelligent transport infrastructure.
- Supply Chain Management:Yard automation and depot-to-depot shuttles optimize trailer positioning within distribution networks.
- Last-Mile Delivery:Unstructured urban environments with pedestrian interaction impose technical fragmentation and higher sensor payload requirements.
By volume, Freight Transportation leads. By growth pace, Last-Mile Delivery is expanding most quickly.
Vehicle Type:
Capital deployment and margin pools concentrate in heavy-duty platforms, though lighter vehicle categories are attracting specialized technology development for density-constrained urban zones.
- Heavy-Duty Trucks:Class 8 tractors dominate current autonomous fleet procurement, integrating LiDAR arrays with 360-degree coverage and neural network perception stacks. US fleet operators are prioritizing these platforms for cross-country freight density corridors.
- Autonomous Delivery Vans:Smaller form factors with reduced sensor payload requirements address e-commerce fulfillment network demands in dense European and North American urban zones.
- Light-Duty Trucks:Regional distribution applications with moderate payload requirements.
- Specialty Vehicles:Refuse collection, mining haulage, and agricultural automation with customized operational design domains.
Heavy-Duty Trucks capture the largest revenue share. Autonomous Delivery Vans are climbing the fastest as urban logistics electrifies.
Technology:
Component cost structures and supplier concentration vary dramatically across sensor modalities, with solid-state LiDAR dependent on limited semiconductor foundry capacity.
- LiDAR:High-performance solid-state arrays provide 360-degree environmental mapping with centimeter-level precision. Supply bottlenecks in Taiwan and South Korea are constraining procurement timelines for North American truck manufacturers.
- Computer Vision:Camera-first perception with transformer-based depth estimation is displacing multi-LiDAR configurations in highway operational design domains. Tier 1 suppliers in Germany and Japan are qualifying these systems for cost-sensitive fleet segments.
- AI Algorithms:Neural network-based decision stacks require explainable AI documentation for EU AI Act compliance.
- GPS Navigation:High-definition correction services enable lane-level positioning on mapped corridors.
LiDAR maintains the largest installed base. Computer Vision is gaining share fastest through sensor commoditization.
End User:
Procurement authority is shifting from traditional OEM dealer networks toward direct relationships between autonomous technology providers and freight shippers.
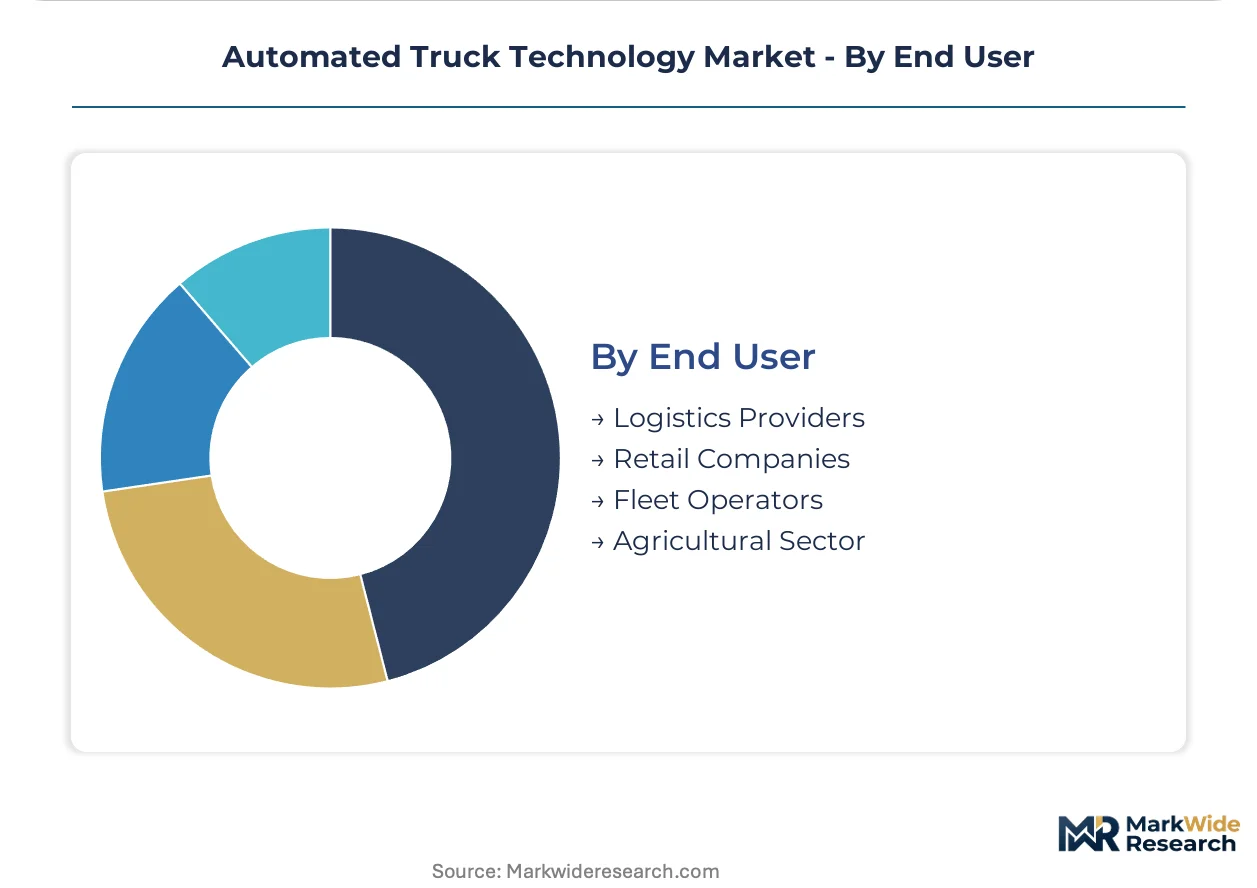
- Logistics Providers:Third-party carriers are adopting autonomous trucking-as-a-service models with per-mile pricing. US regional operators on fixed distribution center routes are unbundling vehicle acquisition from technology subscription.
- Fleet Operators:Asset-heavy national fleets are deploying supervised autonomy to address driver shortages exceeding sixty thousand unfilled positions across North America.
- Retail Companies:Major shippers are contracting directly with autonomous technology vendors, bypassing traditional procurement channels.
- Agricultural Sector:Specialty automation for harvest logistics and grain transport with seasonal utilization patterns.
Logistics Providers represent the deepest current penetration. Retail Companies are advancing fastest through direct technology partnerships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Interstate 10 corridor linking Texas, Arizona, and California anchors North American deployment velocity for supervised autonomous freight operations. European manufacturers leverage the German autobahn cooperative intelligent transport infrastructure to validate platooning systems at commercial scale. Asian technology developers concentrate validation programs around dedicated logistics zones in Shanghai and Seoul where regulatory sandboxes permit expanded operational design domains.
United States
Fleet operators face acute driver shortages exceeding sixty thousand unfilled positions across interstate corridors. The NHTSA governs Federal Motor Vehicle Safety Standards exemption petitions for automated driving system equipment. Pilot programs with major retailers operate on Texas-Arizona-California freight corridors where predictable highway geometry supports Level 4 deployment.
Germany
Automotive OEMs and Tier 1 suppliers command manufacturing scale for heavy-duty autonomous platforms serving European freight networks. The EU AI Act and CE marking requirements shape algorithmic transparency and type-approval pathways for deployment across member states. Stuttgart and Munich industrial clusters host explainable AI development teams partnering with academic institutions for regulatory-grade verification methods.
China
Domestic logistics providers accelerate procurement of autonomous heavy-duty trucks for long-haul corridors connecting manufacturing hubs with coastal ports. The MIIT coordinates GB standards for intelligent connected vehicles with SAMR oversight of commercial deployment permits. Yangtze River Delta logistics zones around Shanghai host validation programs for hub-to-hub automation on dedicated freight routes.
Japan
Precise manufacturing expertise from industrial automation translates into sensor fusion and drive-by-wire component supply for global truck manufacturers. METI programs support cooperative vehicle-to-infrastructure development on designated expressway segments. Nagoya and Tokyo metropolitan corridors serve as testbeds for platooning coordination with minimal following distances.
South Korea
Semiconductor foundry capacity in Taiwan and domestic memory chip production underpin solid-state LiDAR and computing platform supply chains. The MFDS coordinates with transport authorities on safety validation frameworks for commercial autonomous vehicle operation. Daegu-Gyeongbuk logistics clusters attract pilot programs for automated freight shuttles between inland distribution centers and Busan port facilities.
Automated Truck Technology Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying sensor arrays and computing hardware to multiple downstream service providers. The vendor base organizes around three strategic archetypes: full-stack autonomy developers bundling perception software with fleet operations, traditional truck manufacturers extending dealer networks into vehicle-as-a-service models, and Tier 1 automotive suppliers qualifying commoditized sensor packages for cost-sensitive carrier segments. Competitive moves concentrate on strategic partnerships anchoring freight network relationships and backward integration into captive LiDAR semiconductor supply.
Within the full-stack autonomy tier, Waymo LLC and Aurora Innovation Inc. exemplify platform-centric positioning through direct shipper relationships that bypass traditional OEM procurement channels. Daimler Truck AG anchors the manufacturer-integrated archetype, leveraging established production scale and dealer infrastructure to bundle autonomous hardware with vehicle financing and service contracts. These three entities collectively illustrate how competitive advantage migrates toward control of fleet operator relationships rather than component technology differentiation alone.
| Leading Market Players |
|---|
| Waymo LLC |
| Aurora Innovation Inc. |
| TuSimple Holdings Inc. |
| PlusAI Inc. |
| Daimler Truck AG |
| Embark Trucks Inc. |
| Einride AB |
| Gatik AI Inc. |
| PACCAR Inc. |
| Others |
Pricing and Supply Chain Analysis
Taiwanese semiconductor foundry capacity constrains solid-state LiDAR procurement timelines, amplifying pricing power for sensor stack vendors serving North American truck manufacturers while compressing margins for downstream integrators.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates fleet procurement, with differentiation driven by ISO 26262 functional safety certification grade and bundled after-sales service intensity. Cost compression in the economy tier is intensifying because camera-first perception stacks displace multi-LiDAR configurations. Regional carriers exhibit the highest price sensitivity, while national logistics providers with fixed distribution center routes prioritize reliability over unit cost.
Supply Chain Analysis
High-purity silicon wafers, indium phosphide substrates, and automotive-grade GPUs anchor upstream feedstock dependencies for autonomous truck platforms. Manufacturing concentrates in Taiwan, South Korea, and Germany, with single-source vulnerability around Taiwan's 300mm foundry capacity for solid-state LiDAR ASICs. Distribution runs through Tier 1 automotive suppliers qualifying commoditized sensor packages for direct OEM integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now governs competitive outcomes as fleet operators unbundle vehicle acquisition from technology subscription, creating interoperability imperatives between autonomous driving stacks and legacy fleet management systems.
For Market Incumbents: Build regulatory affairs capacity as the primary moat against emerging full-stack autonomy developers. Deepen backward integration into captive LiDAR semiconductor supply through foundry partnerships in Taiwan and South Korea. Secure NHTSA FMVSS exemption petitions early to lock in operational design domain permits on Texas-Arizona-California corridors before state-level regulations diverge further.
For New Entrants and Emerging Players: Mid-market regional carriers operating fixed depot-to-depot routes in the US Southeast represent the most penetrable entry point, as these fleets lack capital for national-scale autonomy programs and exhibit acute driver shortage pressure. Target per-mile service contracts with e-commerce fulfillment networks seeking density in secondary distribution hubs, bypassing established OEM dealer channels entirely.
For Investors and Strategic Acquirers: Long-term, this sits as a fleet-operator relationship play because direct shipper contracts disintermediate traditional procurement channels and capture recurring revenue streams. Acquisition targets should display explainable AI documentation readiness for EU AI Act compliance and established freight network partnerships. Watch NHTSA test protocol finalization as the signal indicating transition from exemption-dependent deployment to standardized commercial scaling.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Waymo Driver and Aurora Horizon anchor direct shipper relationships bypassing OEM networks. |
| Backward Integration | Daimler Truck AG extends manufacturing scale into captive LiDAR supply through foundry partnerships. |
| Regulatory Certification | EU AI Act compliance positions vendors for streamlined CE marking across member states. |
| Geographic Expansion | German autobahn cooperative intelligent transport infrastructure enables platooning validation at commercial scale. |
| Strategic Partnership | Third-party autonomous trucking-as-a-service providers capture retail shipper contracts through per-mile pricing. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with fleet operations directors, autonomous vehicle program managers, Tier 1 supplier procurement leads, and NHTSA regulatory affairs specialists; and secondary validation against SEC 10-K filings, NHTSA exemption petition dockets, EU type-approval databases, and IHS Markit commercial vehicle production data. Bottom-up unit economics modeling triangulated against top-down market sizing across vehicle class, automation level, and regional regulatory cluster.
Forecast inputs incorporated sensor bill-of-materials cost curves, fleet replacement cycle timing, and state-level operational permit issuance velocity across the analysis window. Segmentation dimensions modeled include application type, vehicle class, technology modality, and end-user procurement authority. CAGRs derived from logistic diffusion curves fitted to pilot deployment timelines and revenue service conversion rates.
Macroeconomic conditions sit as an overlay; deviation in freight volume indices, semiconductor capital expenditure cycles, or diesel-electric powertrain substitution rates would shift the trajectory. Cross-checking against NHTSA autonomous vehicle test data and EU type-approval issuance timelines is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
Latin America ADAS Market
Autonomous Vehicles
Advanced Driver Assistance System (ADAS) Market
Autonomous Vehicles
Automotive Lidar Market
Autonomous Vehicles
Automotive Autonomous Shuttle Market
Autonomous Vehicles
Spain Autonomous Navigation Market
Autonomous Vehicles
Autonomous Vehicle Sensor Market
Autonomous Vehicles
Autonomous Freight Trains Market
Autonomous Vehicles
Autonomous Vehicle Simulation Software Market
Autonomous Vehicles
Global Driverless Car Market
Autonomous Vehicles
Autonomous Vehicle ECU Market
Autonomous Vehicles
Robotaxi Market
Autonomous Vehicles
Autonomous Bus Market
Autonomous Vehicles
Autonomous Parking System Market
Autonomous Vehicles
Self-Driving Electric Vehicle Market
Autonomous Vehicles
Adaptive Cruise Control (ACC) and Blind Spot Detection (BSD) Market
Autonomous Vehicles
North America Adaptive Steering Market