
 Dry Mix Mortar Market | 2026-2036
Dry Mix Mortar Market Size, Share, and Industry Trends Forecast 2026-2036
Dry Mix Mortar Market Analysis
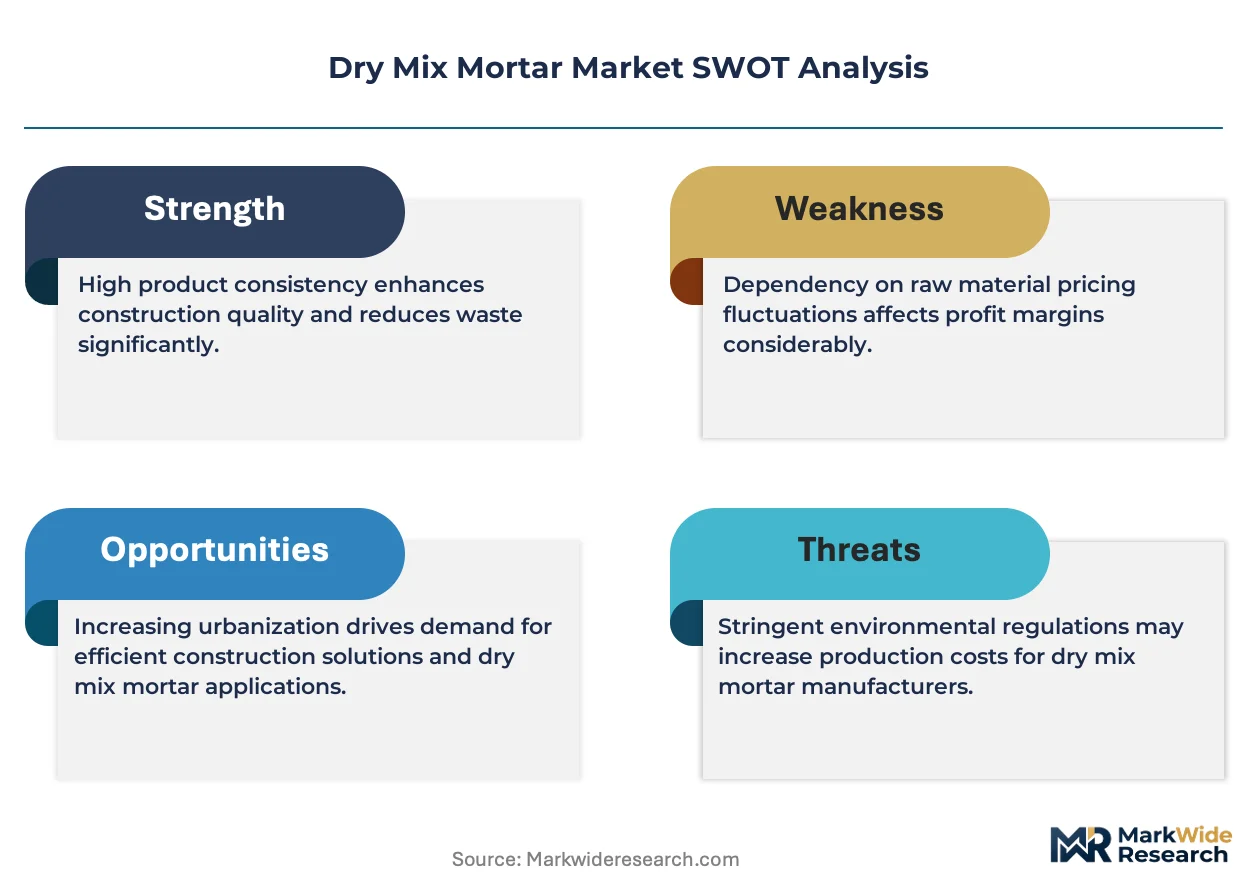
The gap between premium polymer-modified formulations and basic cement-sand blends is broadening. Sika AG leverages its polymer additive portfolio to command specification-driven projects, while Mapei S.p.A. anchors its position through color-matched render systems for architectural facades. BASF SE competes on dispersion powder chemistry that improves open time and adhesion strength.
Dry mix mortar comprises pre-blended binders, aggregates, and functional additives that require only water addition on site, typically achieving compressive strengths from 5 MPa for levelling compounds to 60 MPa for structural repair grades. Its primary purpose is to replace site-mixed plasters and adhesives with batch-consistent, labor-saving formulations. Adhesive mortar and thin-set mortar concentrate margin pools where polymer modification commands price premiums, while render mortar sustains volume leadership across residential and commercial cladding. Bagged packaging dominates distribution channels for projects below 500 kg consumption, though bulk silo systems penetrate large-scale commercial and industrial developments.
REACH compliance in Europe restricts volatile organic compound content in cementitious systems, while China's GB standards mandate freeze-thaw resistance testing for exterior applications. India's BIS certification requirements for packaged construction materials block uncertified imports from neighboring markets. Stakeholders must monitor how carbon border adjustments and embodied carbon disclosure rules reshape sourcing decisions for cementitious raw materials.
Market Dynamics
Polymer modification chemistry is reconfiguring competitive boundaries between commodity blenders and specialty additive suppliers, compressing margins for basic cement-sand formulations while concentrating value capture among dispersion powder innovators.
Growth Catalysts
- GB standards compliance pressure:China's tightening construction material quality thresholds are forcing informal producers toward certified supply chains, expanding the addressable market for pre-blended formulations.
- Bagged distribution network expansion:Regional packagers in India are scaling last-mile delivery infrastructure, penetrating tier-2 and tier-3 construction corridors previously served by site-mixing.
- Residential construction acceleration:Southeast Asia's housing development pipeline is pulling thin-set and adhesive mortar volumes as builders adopt labor-saving installation methods.
Market Restraints
- White cement supply concentration:Production of the key decorative render feedstock clusters in select Mediterranean and Middle Eastern hubs, exposing formulators to freight cost volatility and currency fluctuation risk.
- Redispersible polymer powder import dependency:Asian blenders rely on European and Korean dispersion powder supply, creating working capital intensity from extended inventory cycles.
- Site-mix substitution persistence:Informal labor pools and sand availability at pithead prices sustain traditional plastering methods in cost-sensitive residential segments.
Strategic Opportunities
- Carbon disclosure mandate alignment:The EU Green Deal's embodied carbon reporting requirements for construction materials create specification advantages for producers with verified Environmental Product Declarations.
- Bulk silo system penetration:Commercial and industrial developments above 500 kg consumption thresholds present equipment-leasing and captive blending service models.
- Repair and renovation specialization:Structural repair grades commanding 60 MPa compressive strength specifications offer margin expansion in aging building stock maintenance.
Industry Challenges
- Application technician certification gaps:Shortages of trained installers for polymer-modified systems limit specification uptake in markets where skill transfer from traditional plastering remains incomplete.
- REACH compliance documentation burden:European volatile organic compound restrictions require extensive substance registration and testing protocols, extending product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dry Mix Mortar Market |
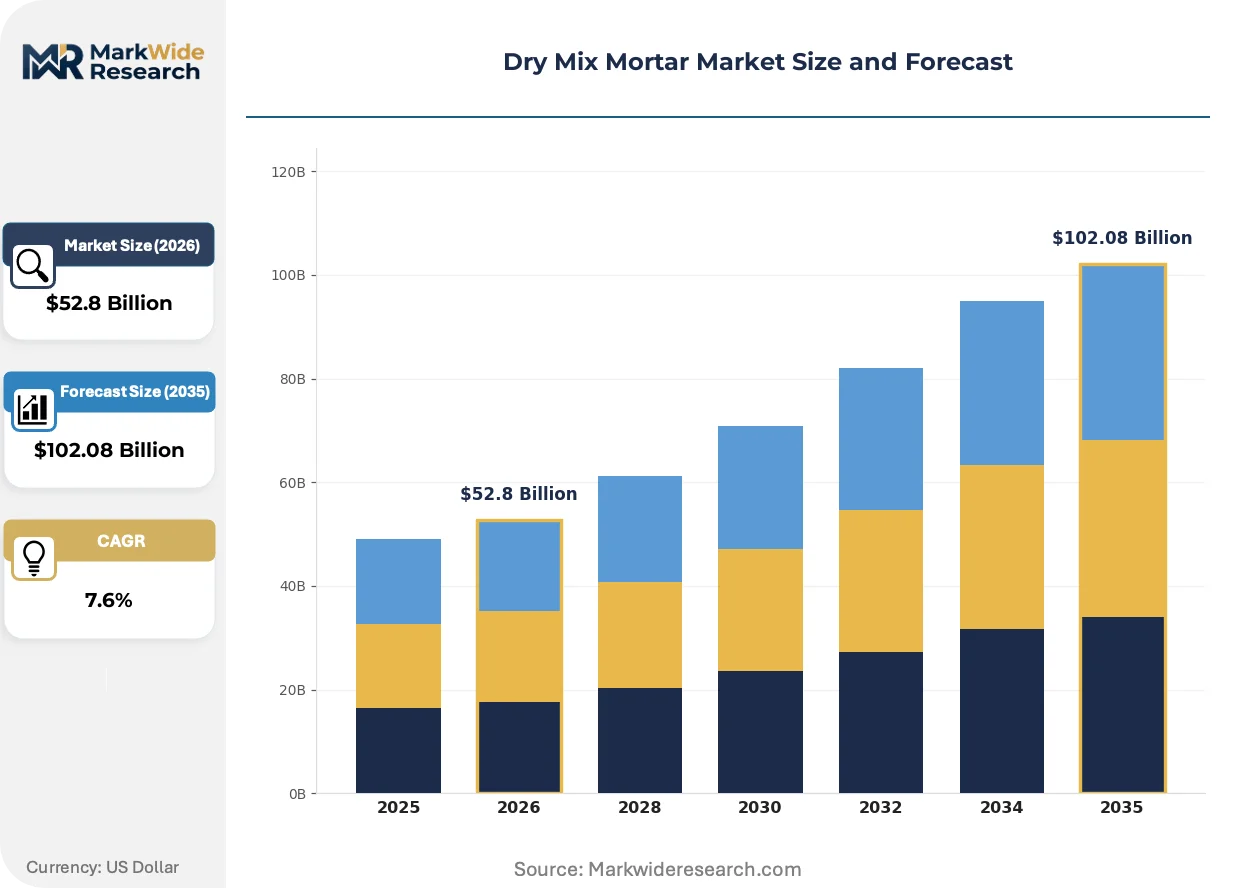
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $102.08 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adhesive Mortar, Repair Mortar, Thin-set Mortar, Render Mortar Application: Flooring, Wall Coverings, Masonry, Tile Bonding End User: Residential, Commercial, Industrial, Institutional Packaging Type: Bagged, Bulk, Pails, Boxes |
| Companies Covered | CEMEX S.A.B. de C.V., Ardex Group, Sika AG, UltraTech Cement Limited, Mapei S.p.A., Saint-Gobain, Holcim Ltd., Pidilite Industries Limited, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dry Mix Mortar Market Emerging Trajectories
Formulation science is advancing beyond binary cement-polymer blends toward multi-functional additive systems that simultaneously control rheology, adhesion, and durability in single-package solutions.
Hybrid cellulose-ether and starch-ether rheology modifiers are expanding into self-levelling compounds and tile adhesives requiring extended open time. Flooring contractors in commercial fit-out segments are specifying these systems for large-format tile installation. The technology is expanding into markets previously dominated by basic cement-sand screeds, compressing volume share of unmodified site mixes.
REACH restrictions on volatile organic compound content in cementitious systems are compelling reformulation of sealants and coatings used in conjunction with dry mix mortars. Manufacturers are substituting solvent-based acrylics with waterborne alternatives, increasing raw material costs by 8-15 percent. Exterior render applications face additional freeze-thaw resistance testing mandates under China's GB standards, favoring producers with in-house climatic simulation capabilities.
Builder procurement patterns are consolidating toward single-source specification packages where mortar, waterproofing, and tile adhesive systems carry unified brand certification. Large residential developers in Vietnam and Indonesia are adopting approved vendor lists that exclude uncertified regional blenders. This concentration is most visible in high-rise condominium construction where defect liability periods extend beyond ten years.
Dry Mix Mortar Market Segmentation
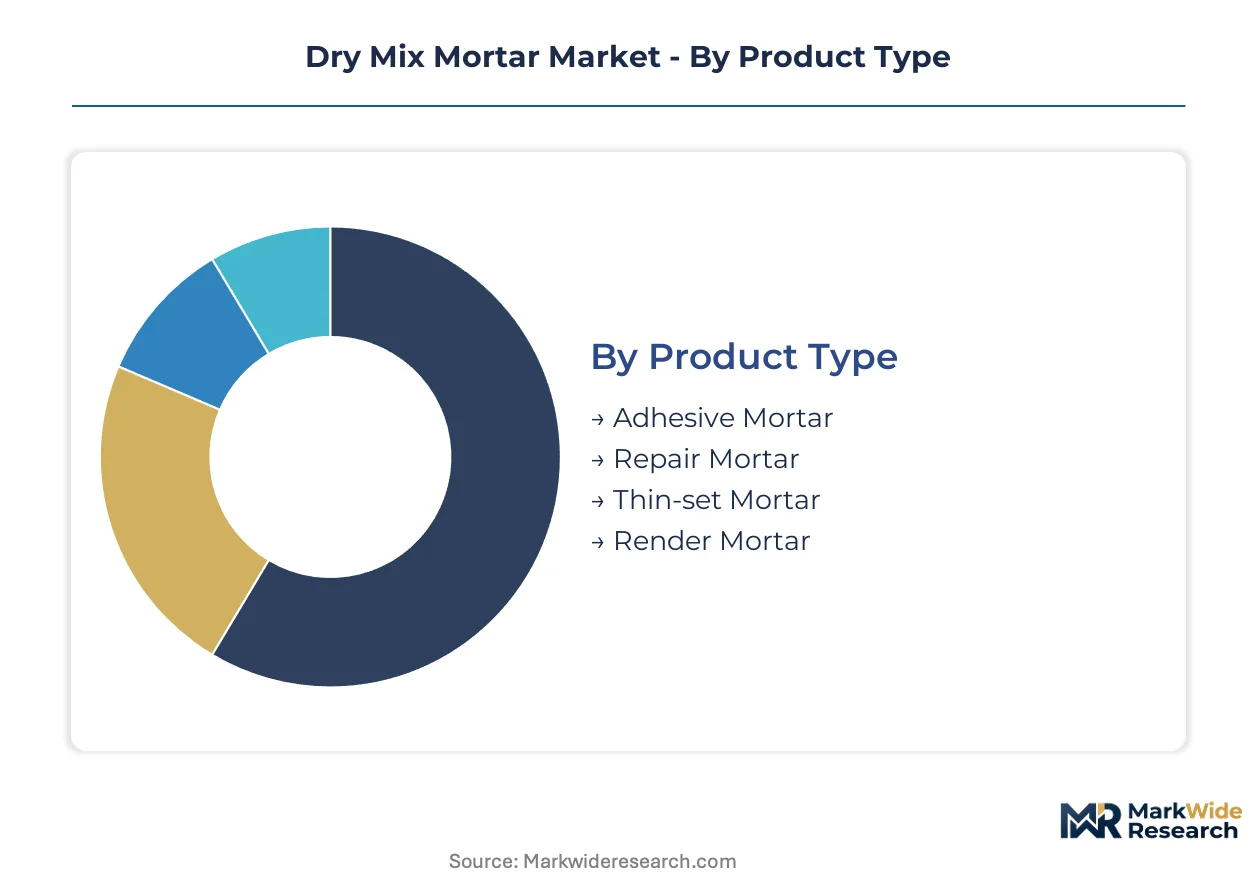
Segmentation in dry mix mortar reveals how formulation chemistry and packaging economics split value capture between commodity blenders and specialty additive suppliers. Understanding these divides exposes where margin pools concentrate and where volume scale dominates.
Product Type:
Supply concentration in polymer-modified grades is compressing margins for basic cement-sand blends while dispersing value toward dispersion powder innovators.
- Adhesive Mortar:Polymer-modified formulations incorporating redispersible powders achieve enhanced bond strength for large-format tile installation. Demand clusters in Southeast Asian high-rise residential developments where labor-saving thin-bed methods displace traditional thick-set applications.
- Render Mortar:Pre-blended cement-lime or cement-sand mixtures for exterior and interior plastering constitute the volume anchor across residential construction. India's bagged distribution networks and China's GB-compliant certified supply chains sustain render mortar as the default specification for new housing stock.
- Repair Mortar:Structural grades achieve compressive strengths up to 60 MPa for concrete restoration and structural rehabilitation.
- Thin-set Mortar:Low-thickness adhesive systems for ceramic and porcelain tile installation penetrate commercial flooring retrofits.
Render mortar absorbs the bulk of installed capacity; adhesive mortar is expanding most quickly.
Application:
Cost tier differentiation separates specification-grade systems in commercial developments from economy blends in informal residential construction.
- Tile Bonding:Polymer-modified thin-set and adhesive mortars command price premiums in large-format porcelain and natural stone installation. Vietnam and Indonesia's high-rise condominium pipelines specify certified systems with extended defect liability coverage.
- Flooring:Self-levelling compounds and screed mortars incorporating hybrid cellulose-ether rheology modifiers displace site-mixed cement-sand beds in commercial fit-outs.
- Wall Coverings:Decorative render and skim coat systems for architectural facades depend on white cement supply concentration from Mediterranean and Middle Eastern production hubs.
- Masonry:Block-laying and brick-bonding mortars remain vulnerable to site-mix substitution where sand availability at pithead prices undercuts pre-blended economics.
Tile bonding captures the steepest specification upgrade trajectory; masonry retains the largest volume base.
End User:
Customer type determines procurement sophistication, with institutional buyers mandating certified Environmental Product Declarations while residential developers prioritize last-mile bagged availability.
- Residential:Housing construction across Southeast Asia and India's tier-2 corridors drives bagged mortar consumption as builders shift from site-mixing toward labor-saving pre-blended formulations.
- Commercial:Office and retail developments above 500 kg consumption thresholds adopt bulk silo systems with captive blending or equipment-leasing service models.
- Industrial:Warehouse and manufacturing facility construction specifies high-performance repair and flooring systems with accelerated curing characteristics.
- Institutional:Government and healthcare projects mandate BIS certification in India and GB compliance in China, excluding uncertified regional blenders from approved vendor lists.
Residential construction deploys the greatest product volume; institutional specifications are climbing the fastest on compliance mandates.
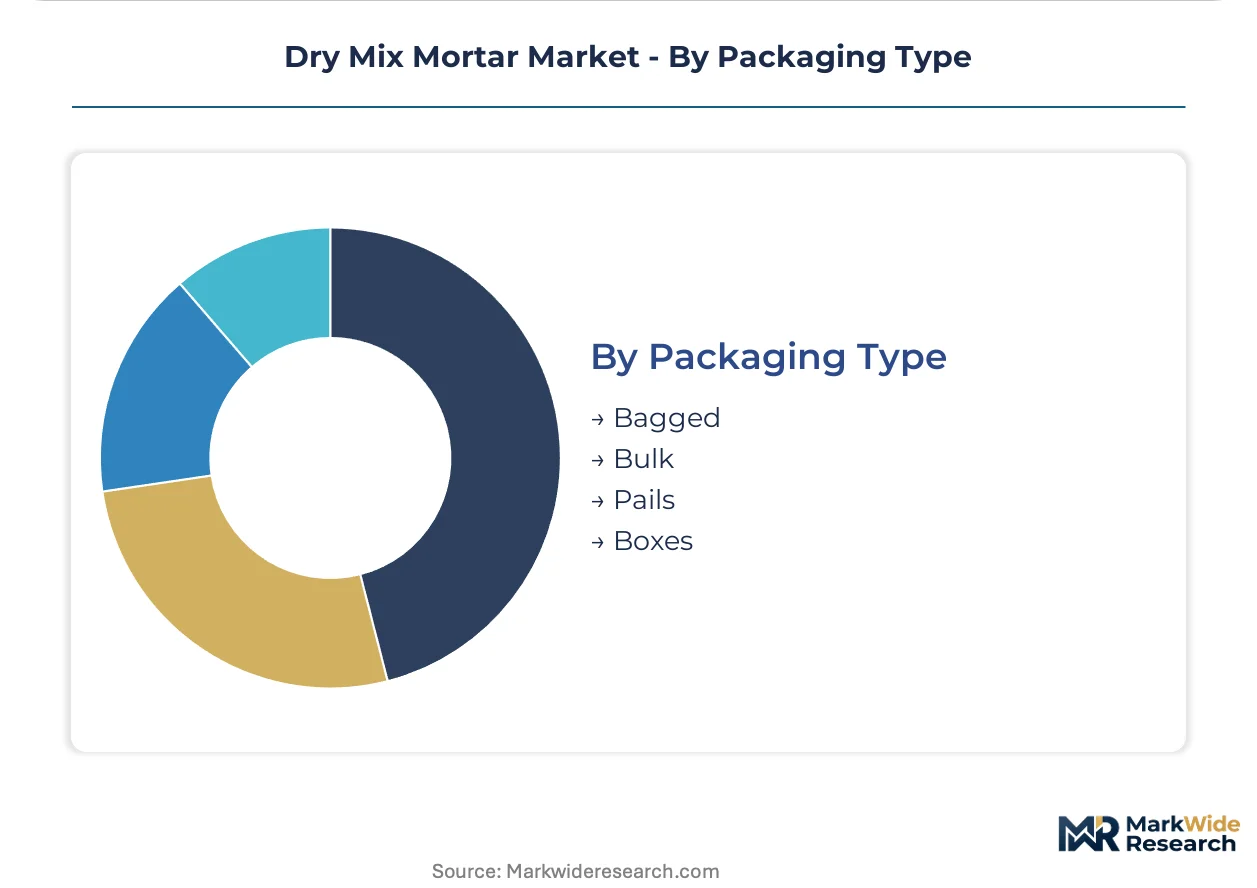
Packaging Type:
Volume scale dictates packaging economics, with bagged formats dominating below-threshold consumption and bulk systems penetrating large-scale developments.
- Bagged:25-50 kg paper or woven polypropylene sacks dominate projects below 500 kg consumption, with India's UltraTech Cement and regional packagers scaling last-mile distribution into tier-3 construction corridors.
- Bulk:Silo-delivered systems serve commercial and industrial developments with continuous consumption, reducing packaging waste and enabling just-in-time inventory management.
- Pails:Smaller-format containers target repair and renovation segments requiring partial quantity usage.
- Boxes:Carton packaging for specialty repair compounds and small-batch decorative renders penetrates retail hardware channels.
Bagged packaging commands the greatest installed base; bulk delivery is gaining share fastest in commercial construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai anchors the world's largest dry mix mortar production cluster, with Yangtze River Delta formulators supplying pre-blended systems across China's eastern seaboard. Southeast Asian construction corridors and India's tier-2 cities are emerging as volume growth poles.
China
High-rise residential towers in Shenzhen and Guangzhou drive specification-grade adhesive mortar demand. GB standards for freeze-thaw resistance and compressive strength tighten compliance thresholds, pushing informal blenders toward certified supply chains. Zhejiang Province houses the densest concentration of redispersible polymer powder compounding facilities serving domestic and export markets.
India
Affordable housing schemes and metro rail expansion in Mumbai, Delhi-NCR, and Bangalore pull bagged mortar volumes. BIS certification requirements for packaged construction materials block uncertified imports from Bangladesh and Nepal. UltraTech Cement scales last-mile distribution through regional packagers penetrating tier-3 construction corridors in Maharashtra and Gujarat.
Germany
Energy-efficient renovation mandates for aging building stock sustain repair mortar specifications in Berlin and Rhine-Ruhr industrial zones. REACH compliance documentation for volatile organic compound content extends product launch timelines for reformulated systems. Bavaria-based dispersion powder innovators supply polymer additives across European formulator networks.
United States
Commercial flooring retrofits in Dallas-Fort Worth and Atlanta specify self-levelling compounds with extended open time. EPA guidelines on construction material emissions influence procurement patterns for institutional developers. Texas and Florida construction corridors adopt bulk silo systems for large-scale warehouse and distribution center projects.
Vietnam
High-rise condominium pipelines in Ho Chi Minh City and Hanoi specify certified thin-set systems with extended defect liability coverage. Approved vendor lists from Japanese and South Korean contractors exclude uncertified regional blenders. Da Nang and Hai Phong industrial zones attract mortar formulators serving export-oriented manufacturing facility construction.
Dry Mix Mortar Market Vendor Landscape
Premium-margin players sit above commodity-margin players across formulation chemistry tiers, with polymer-modified specialists commanding specification-driven price premiums while cement-sand blenders compete on volume scale. The vendor base stratifies between multinational additive suppliers, integrated cement producers with downstream blending operations, and regional packagers focused on last-mile distribution. Three archetypes dominate: dispersion powder innovators capturing value from specialty chemistry, scale-driven cement majors leveraging raw material integration, and niche specialists targeting repair and renovation segments. Capacity expansion and strategic partnerships represent the dominant competitive moves, with formulators securing captive additive supply and distribution networks.
Within the multinational chemical tier, BASF SE and Sika AG occupy positions anchored by polymer additive portfolios and specification relationships with institutional developers. UltraTech Cement Limited exemplifies the integrated cement-major archetype, with captive clinker supply and scaled bagged distribution networks across South Asian construction corridors. Mapei S.p.A. represents the specialty-formulator position, with color-matched render systems targeting architectural facade specifications.
| Leading Market Players |
|---|
| CEMEX S.A.B. de C.V. |
| Ardex Group |
| Sika AG |
| UltraTech Cement Limited |
| Mapei S.p.A. |
| Saint-Gobain |
| Holcim Ltd. |
| Pidilite Industries Limited |
| BASF SE |
| Others |
Supply Flow & Price Mechanics
Redispersible polymer powder import costs from European and Korean producers cascade through three distinct pricing tiers, with freight volatility and currency exposure compressing margins for Asian blenders while concentrating value capture among dispersion powder innovators with captive supply.
Pricing Analysis
Value-based pricing anchored to compressive strength outcomes and defect liability coverage dominates specification-grade projects. Three-tier pricing structure across premium polymer-modified, standard cement-lime, and economy cement-sand levels separates certified systems from informal blends. Price differentiation rests on BIS and GB certification attainment plus volume scale in bulk silo deployments. Cost compression in basic cement-sand tiers is intensifying because site-mix substitution persists where sand availability at pithead prices undercuts pre-blended economics. Residential developers in India's tier-3 corridors exhibit highest price sensitivity; institutional buyers in Vietnam's high-rise condominium pipeline demonstrate lowest sensitivity due to extended defect liability requirements.
Supply Chain Analysis
Bagged distribution networks through regional packagers handle sub-500 kg project demand across India's Maharashtra and Gujarat construction corridors. Raw material sourcing draws from white cement production clustering in Mediterranean and Middle Eastern hubs, redispersible polymer powder compounding in Zhejiang Province and South Korea, and domestic clinker supply from integrated cement majors. Single-source vulnerability in dispersion powder supply creates working capital intensity from extended inventory cycles. Bulk silo systems with equipment-leasing service models penetrate commercial developments above consumption thresholds in Texas and Florida construction corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from China's GB standards compliance mandates is forcing informal producers toward certified supply chains, eliminating uncertified regional blenders and concentrating market share among integrated majors and specialty formulators with additive portfolios.
For Market Incumbents: Deepen captive supply of redispersible polymer powders through backward integration into Zhejiang Province compounding facilities or long-term offtake agreements with Korean producers. Expand BIS and GB certification coverage to exclude emerging regional packagers from approved vendor lists in India's affordable housing schemes. Site-mix substitution persistence in cost-sensitive residential segments remains the primary volume threat requiring channel control through scaled last-mile distribution. For New Entrants and Emerging Players: Enter via repair and renovation specialization targeting structural repair grades with 60 MPa compressive strength specifications in Germany's energy-efficient renovation pipeline. Target carbon disclosure mandate alignment in EU Green Deal jurisdictions where Environmental Product Declaration verification creates specification barriers for incumbents lacking embodied carbon documentation. Pursue equipment-leasing service models for bulk silo systems as the primary go-to-market angle in commercial flooring retrofit segments. For Investors and Strategic Acquirers: Approved vendor list consolidation by Japanese and South Korean contractors in Vietnam's high-rise condominium pipeline is the leading indicator that specification-grade adhesive mortar share is concentrating among certified producers. Acquisition targets should emphasize regional packagers with scaled bagged distribution in India's tier-2 and tier-3 corridors plus captive additive supply relationships. Watch for carbon border adjustment implementation signals in European construction material procurement as the inflection indicator for Environmental Product Declaration valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Additives | Zhejiang Province dispersion powder facilities secure captive supply against Korean import dependency. |
| GB Standards Certification Investment | Freeze-thaw resistance testing capabilities exclude informal blenders from China's eastern seaboard projects. |
| Bulk Silo Equipment-Leasing Expansion | Texas and Florida warehouse construction corridors adopt just-in-time inventory service models. |
| Environmental Product Declaration Verification | EU Green Deal embodied carbon reporting creates specification advantages in German renovation mandates. |
| Last-Mile Distribution Network Scale-Up | UltraTech Cement's regional packager partnerships penetrate Maharashtra and Gujarat tier-3 corridors. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with plant managers at dispersion powder compounding facilities, procurement leads at Southeast Asian high-rise developers, distribution channel partners in India's tier-2 cities, and technical R&D directors at specialty formulators validated demand patterns. Secondary sources included BIS certification databases, China's GB standards documentation, REACH compliance registries, SEC 10-K filings from integrated cement majors, and construction material customs records. Bottom-up project pipeline tracking across Vietnam, Indonesia, and India triangulated against top-down cement consumption forecasts.
Granularity-level modeling operated at product type, application, end user, and packaging format dimensions across the projection horizon. Formulation chemistry tiers separated polymer-modified from unmodified grades; regional production clusters distinguished Yangtze River Delta supply from Mediterranean white cement sourcing; procurement sophistication levels segmented institutional from residential demand. CAGRs derived from volume trajectory analysis incorporating housing starts data, metro rail expansion timelines, and commercial flooring retrofit cycles. Industry-specific inputs included redispersible polymer powder import volume patterns and BIS certification issuance rates.
Revisions become necessary when carbon border adjustment mechanisms accelerate, GB standards expand to interior applications, or white cement supply disruptions from Mediterranean production hubs materialize. Forecasts reflect assumptions regarding site-mix substitution persistence rates, dispersion powder technology transfer timelines, and certification cost pass-through elasticity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Construction Repair Composites Market
Building Materials
Global Metal Cladding Market
Building Materials
Light Gauge Steel Framing Market
Building Materials
Shotcrete Market
Building Materials
Italy Architectural Coatings Market
Building Materials
Lightweight Precast Wall Panel Market
Building Materials
Door Frame Metal Market
Building Materials
India Concrete Admixtures Market
Building Materials
China Aluminum Door and Window Market
Building Materials
Building Asphalt Market
Building Materials
Rubbing Bricks Market
Building Materials
Lightweight Cellular Concrete Market
Building Materials
Asia-Pacific Building and Construction Sheets Market
Building Materials
Latin America Facade Market
Building Materials
Cement Tiles Market
Building Materials
Fiber Cement Market