
 Bolt (Fastener) Market | 2026-2036
Bolt (Fastener) Market Size, Share, and Industry Trends Forecast 2026-2036
Bolt (Fastener) Market Analysis
Buyer concentration across North American automotive OEM supply chains is pivoting toward fewer, larger tier-one integrators with expanded fastener specification authority. MacLean-Fogg Component Solutions leverages captive forging capacity to anchor long-term contracts with these consolidated purchasers. Precision Castparts Corp sustains aerospace-grade bolt dominance through superalloy metallurgy leadership. Illinois Tool Works Inc. competes across diversified industrial channels with broad SKU breadth and embedded distributor relationships.
A bolt is a threaded mechanical fastener with an external male thread designed to mate with a pre-tapped hole or nut, typically manufactured through cold forging, thread rolling, and heat treatment to achieve tensile strengths exceeding 800 MPa for structural grades. Its primary purpose is to clamp components under controlled preload in assemblies subject to vibration, thermal cycling, or dynamic loads. Hex bolts in steel alloys occupy the largest volume share across construction and heavy machinery, where standardization and cost efficiency dominate procurement criteria. Stainless steel variants in M8 and M12 sizes command premium positioning in marine and chemical processing applications where corrosion resistance determines lifecycle value.
The US Department of Transportation's NHTSA enforces FMVSS crashworthiness standards that mandate specific fastener grades in vehicle structures, while REACH and RoHS in Europe restrict hexavalent chromium plating processes and drive conversion to zinc-nickel or organic coatings. China's GB standards and SAMR market surveillance protocols enforce thread tolerance and material certification for domestic infrastructure projects. Stakeholders must monitor evolving alloy substitution timelines and regional certification reciprocity to align capacity investments with shifting compliance boundaries.
Market Dynamics
Automotive electrification is compressing fastener procurement cycles as OEMs redesign chassis architectures around battery pack integration, forcing suppliers to retool cold forging lines for high-tensile alloy grades that satisfy crashworthiness mandates without adding mass.
Growth Catalysts
- EV Platform Expansion:Germany and China are scaling threaded fastener procurement for electric vehicle assembly lines, with tier-one integrators specifying M12 and M14 high-tensile bolts for battery tray mounting.
- ECE R94 Compliance:European crashworthiness standards mandate upgraded fastener grades in passenger cell structures, pulling material specifications toward 10.9 and 12.9 property classes.
- India PLI Manufacturing:Production-linked incentive schemes are accelerating threaded fastener consumption across industrial corridors in Maharashtra and Tamil Nadu for machinery and construction equipment build-out.
Market Restraints
- Alloy Price Volatility:Nickel and molybdenum input costs swing unpredictably, compressing margin buffers for cold forgers serving price-sensitive construction distributors.
- Supplier Concentration Risk:Superalloy metallurgy capability clusters in Western European and Japanese specialty steel mills, creating chokepoints for aerospace-grade bolt producers.
- REACH Chemical Restrictions:European ECHA rules on hexavalent chromium plating force coating conversion, adding process steps and capital burden for exporters serving EU automotive OEMs.
Strategic Opportunities
- Underpenetrated Southeast Asia:Vietnam and Indonesia infrastructure build-out lacks domestic high-tensile forging capacity, opening import substitution windows for regional bolt suppliers.
- Dual Carbon Alignment:China's MIIT carbon intensity targets are creating preferential procurement lanes for fasteners produced with electric arc furnace steel and verified low-carbon metallurgy.
- Digital Thread Traceability:Blockchain-enabled material certification is emerging as a channel innovation, with German automotive OEMs piloting immutable grade verification from melt to assembly.
Industry Challenges
- Heat Treatment Skill Scarcity:Controlled atmosphere quenching and tempering expertise is thinning as veteran technicians retire, constraining capacity expansion for 12.9-grade structural bolts.
- Multi-Standard Certification Lag:Simultaneous GB, ISO, and ASTM qualification timelines stretch 18-24 months, delaying market entry for forged fastener specialists targeting cross-border infrastructure contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bolt (Fastener) Market |
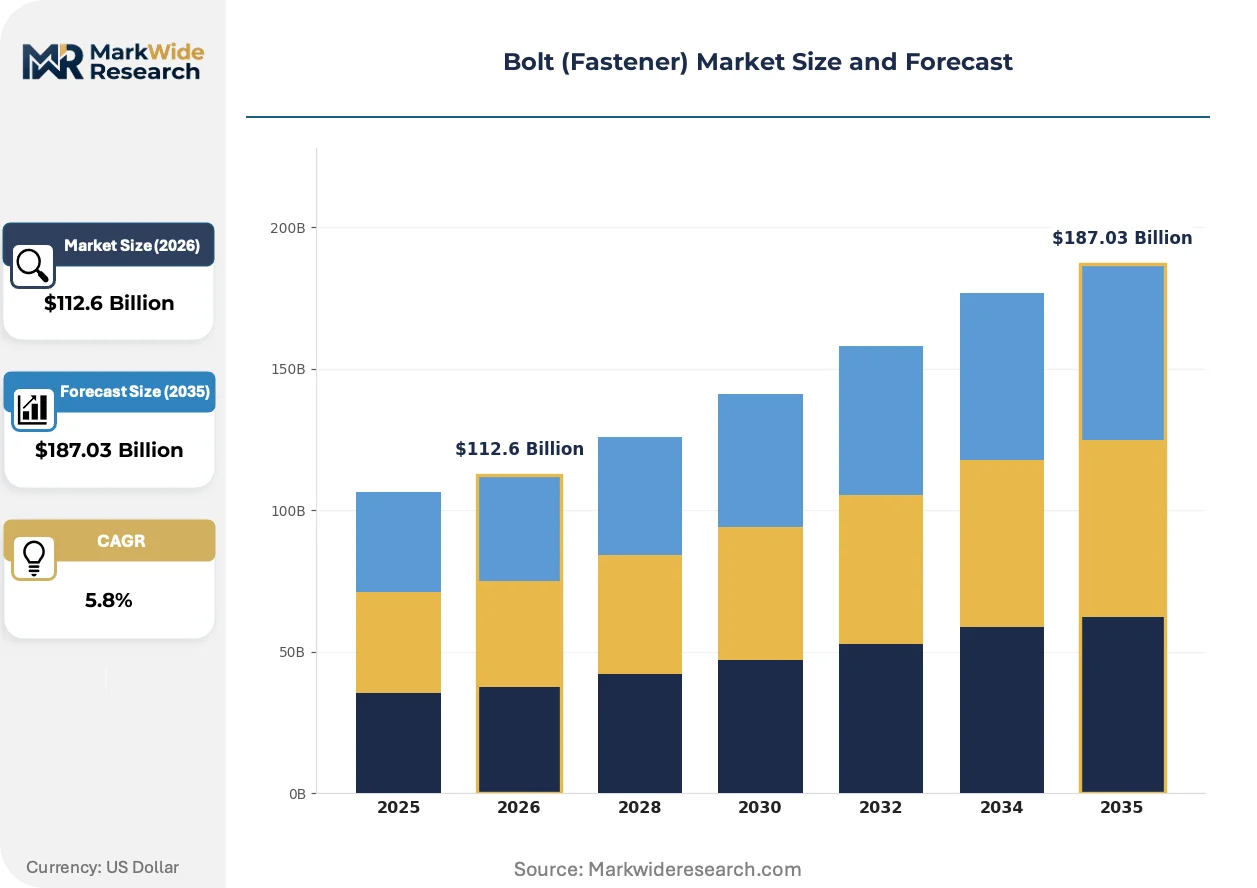
| Market Size in 2026 | $112.6 Billion |
| Market Size in 2035 | $187.03 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hex Bolt, Carriage Bolt, Lag Bolt, Eye Bolt Material: Steel, Stainless Steel, Alloy, Nylon Application: Automotive, Construction, Aerospace, Electronics Size: M3, M8, M12, M16 |
| Companies Covered | MacLean-Fogg Component Solutions, Birmingham Fastener Inc., Precision Castparts Corp, Patriot Bolt and Fastener, National Bolt & Nut Corporation, Illinois Tool Works Inc., Portland Bolt & Manufacturing Company, Lightning Bolt & Supply Inc., Howmet Aerospace Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bolt (Fastener) Market Emerging Trajectories
Material science advances and digital manufacturing protocols are compressing development cycles while regulatory chemistry bans are forcing surface treatment reinvention across the fastener value chain.
Titanium aluminide intermetallics are integrating into aerospace engine fastener applications where density reduction outweighs raw material cost premiums. Pratt & Whitney and Rolls-Royce procurement specifications now favor these alloys for turbine section bolting. The technology is integrating upstream forging partnerships with specialty mill operators who control intermetallic melt chemistry.
REACH Annex XVII restrictions on hexavalent chromium are eliminating traditional zinc-yellow plating from European automotive supply chains. ECHA enforcement timelines are compressing coating conversion windows to 24 months for tier-two suppliers. German OEMs are responding by mandating zinc-nickel or organic topcoat specifications in new platform RFQs.
Consolidated tier-one integrators are compressing supplier bases and internalizing fastener specification authority previously held by distributors. MacLean-Fogg and similar captive forgers are securing decade-long direct contracts with Detroit and Stuttgart OEMs. This concentration is most visible in North American automotive channels where distributor margins are compressing 40-60 percent.
Bolt (Fastener) Market Segmentation

Fastener procurement patterns diverge sharply across dimensional and material boundaries, with specification authority consolidating around tier-one integrators who dictate grade requirements by end-use severity. Segmentation discipline separates commodity volume plays from premium-grade positioning where metallurgy certification and traceability command price premiums.
Product Type:
Supply concentration clusters around cold forging capacity optimized for high-volume geometries, with captive forgers in Germany and China locking in decade-long contracts for standardized hex profiles.
- Hex Bolt:Six-sided head geometry dominates structural assembly across construction and heavy machinery, with M12 and M16 sizes absorbing the bulk of German automotive battery tray procurement. Demand concentrates in Maharashtra and Tamil Nadu industrial corridors where infrastructure build-out requires grade 8.8 and 10.9 property classes under BIS certification.
- Carriage Bolt:Rounded head with square neck prevents rotation in wood-to-metal fastening, capturing specification share in North American construction distribution where historical ANSI/ASME standards persist. Michigan and Ontario OEMs specify these for non-structural interior vehicle trim where vibration resistance matters less than installation speed.
- Lag Bolt:Self-tapping wood screw design with hex head drives demand in timber framing and utility pole installation across the US Southeast and Pacific Northwest.
- Eye Bolt:Looped head configuration serves lifting and rigging applications in marine and offshore sectors where DNV GL certification governs working load limits.
Hex bolt absorbs the bulk of installed capacity; eye bolt is expanding most quickly on offshore wind installation demand.
Material:
Cost tier stratification separates commodity carbon steel from superalloy grades where nickel and molybdenum content determines crashworthiness qualification timelines.
- Steel:Low and medium carbon grades dominate volume production through cold forging lines optimized for 8.8 property class output, with Indian PLI-linked manufacturers scaling capacity in Pune and Ahmedabad industrial zones. REACH-compliant zinc-nickel coating conversion adds process steps for EU-bound exports.
- Stainless Steel:Austenitic 304 and 316 grades command premium positioning in chemical processing and marine environments where chloride exposure dictates lifecycle value. M8 and M12 sizes from Japanese specialty mills satisfy JIS specifications for desalination plants in Saudi Arabia and UAE.
- Alloy:High-tensile grades with chromium and vanadium additions achieve 12.9 property class for aerospace engine bolting where density reduction justifies raw material cost premiums.
- Nylon:Glass-reinforced polymer grades serve electronics and consumer appliance assembly where electrical insulation and corrosion elimination outweigh mechanical strength requirements.
Steel commands the greatest forging tonnage; alloy grades gain share fastest on aerospace engine platform expansion.
Application:
End-use severity determines certification burden, with automotive and aerospace channels demanding full material traceability while construction tolerates mill certificate-only documentation.
- Automotive:Chassis and powertrain assembly specifications are compressing procurement cycles as EV platforms redesign around battery pack integration, with ECE R94 compliance mandating 10.9 and 12.9 grades for passenger cell structures. Stuttgart and Detroit OEMs now require zinc-nickel or organic coatings in place of hexavalent chromium plating.
- Construction:Structural steel erection and infrastructure build-out consume standard hex bolts in grade 8.8, with Indian National Highway projects and Indonesian toll road development driving threaded fastener consumption. Price sensitivity dominates procurement criteria where distributor relationships determine contract capture.
- Aerospace:Turbine section bolting specifications favor titanium aluminide intermetallics where Pratt & Whitney and Rolls-Royce procurement teams prioritize density reduction. Superalloy metallurgy capability clusters in Western European and Japanese specialty mills.
- Electronics:Miniaturized M3 precision threads serve PCB mounting and enclosure assembly where torque control and stripping prevention outweigh tensile strength requirements.
Construction channels move the greatest bolt volume; aerospace specifications are climbing the fastest on engine platform renewal cycles.
Size:
Volume distribution skews toward mid-range diameters where standardization and tooling amortization intersect, with M8 and M12 sizes capturing specification share across multiple end-use categories.
- M3:Precision thread pitch serves electronics assembly and instrumentation where stripping torque limits dictate installation protocols.
- M8:Universal diameter bridges light machinery and automotive interior applications, with stainless variants commanding premium in marine environments.
- M12:Structural workhorse size dominates construction and heavy machinery where 10.9 grade availability is standard across distributor inventories. German automotive OEMs specify M12 high-tensile bolts for battery tray mounting on EV platforms.
- M16:Heavy structural grade serves wind turbine tower assembly and mining equipment where preload requirements exceed 100 kN.
M12 captures the greatest specification share across end-use categories; M16 is gaining traction fastest on renewable energy infrastructure scaling.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nickel and molybdenum deposits in Sudbury, Ontario anchor North American specialty alloy supply chains for high-tensile fastener grades. Cold forging capacity clusters around automotive assembly corridors in Germany, China, and India where EV platform retooling accelerates procurement cycles.
Germany
Stuttgart and Munich OEMs specify M12 and M14 high-tensile bolts for battery tray mounting on electric vehicle platforms. ECE R94 crashworthiness standards mandate 10.9 and 12.9 property classes for passenger cell structures. Bavaria's industrial corridor hosts captive forgers locking in decade-long supply contracts with consolidated tier-one integrators.
China
MIIT dual carbon targets create preferential procurement lanes for fasteners produced with electric arc furnace steel and verified low-carbon metallurgy. GB standards and SAMR market surveillance enforce thread tolerance and material certification for domestic infrastructure projects. Yangtze River Delta forging clusters scale capacity for EV chassis architectures around battery pack integration.
United States
NHTSA FMVSS crashworthiness standards mandate specific fastener grades in vehicle structures, pulling material specifications toward high-tensile alloys. Michigan and Ohio automotive corridors compress procurement cycles as OEMs redesign platforms for electrification. Detroit-based tier-one integrators internalize specification authority previously held by distributors.
India
PLI-linked manufacturing schemes accelerate threaded fastener consumption across industrial corridors in Maharashtra and Tamil Nadu. BIS certification governs grade 8.8 and 10.9 structural bolts for National Highway infrastructure build-out. Pune and Ahmedabad forging zones scale cold forging capacity to serve machinery and construction equipment demand.
Japan
METI industrial policy supports superalloy metallurgy capability for aerospace engine bolting applications. JIS specifications for austenitic stainless grades satisfy desalination plant demand in Middle Eastern export markets. Nagoya and Osaka specialty mills control intermetallic melt chemistry for turbine section fastener procurement.
Bolt (Fastener) Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue coating conversion and digital traceability services. The vendor base stratifies across captive forgers with in-house forging capacity, specialty metallurgy houses serving aerospace channels, and diversified industrial conglomerates with embedded distributor networks. Two dominant competitive moves define current positioning: tier-one integrators compressing supplier bases through direct long-term contracting, and REACH-driven coating conversion investments for European automotive compliance.
Among North American-based fabricators, MacLean-Fogg Component Solutions and Precision Castparts Corp exemplify contrasting archetypes. MacLean-Fogg occupies a position within the captive forging tier, anchoring supply relationships through integrated production capacity. Precision Castparts represents specialty metallurgy leadership, sitting within the aerospace-grade segment where superalloy certification creates defensive positioning. Illinois Tool Works Inc. exemplifies diversified industrial channel coverage, embedding itself across broad SKU portfolios and established distributor relationships rather than direct OEM contracting.
| Leading Market Players |
|---|
| MacLean-Fogg Component Solutions |
| Birmingham Fastener Inc. |
| Precision Castparts Corp |
| Patriot Bolt and Fastener |
| National Bolt & Nut Corporation |
| Illinois Tool Works Inc. |
| Portland Bolt & Manufacturing Company |
| Lightning Bolt & Supply Inc. |
| Howmet Aerospace Inc. |
| Others |
Supply Flow & Price Mechanics
Controlled atmosphere quenching technicians in Germany's Bavarian industrial corridor command wage premiums that compress margin spreads between commodity grade 8.8 bolts and certified 12.9 structural grades. Labor-cost differentials between veteran heat treatment specialists and standard forging operators translate directly into three-tier pricing stratification across European automotive supply chains.
Pricing Analysis
Volume-massive construction-grade M12 hex bolts trade on thin margin spreads anchored to steel scrap indices, while aerospace superalloy fasteners capture substantial premiums tied to nickel-molybdenum content and DNV GL certification burden. Price differentiation separates mill-certificate-only construction tiers from full-traceability automotive and aerospace grades requiring blockchain-enabled material verification. Pricing pressure intensifies in standard carbon steel segments as Indian PLI-linked capacity expansion floods Asian distributor channels. Construction procurement teams in Indonesia and Vietnam exhibit highest price sensitivity; German tier-one integrators specify coating-converted zinc-nickel grades with lowest elasticity.
Supply Chain Analysis
Direct-to-OEM channels handle consolidated tier-one integrator demand in Michigan, Stuttgart, and Shanghai automotive corridors, while construction distributors stock standardized inventory across Indian industrial zones. Raw material dependencies center on Sudbury nickel deposits, Chinese ferrochrome output, and Japanese specialty molybdenum bar. Geographic supply concentration clusters in Germany's captive forging belt, China's Yangtze River Delta EV component zones, and India's Pune-Ahmedabad machinery manufacturing corridor. Single-source vulnerability looms in superalloy metallurgy capability held by Western European and Japanese specialty mills. Distribution runs through tier-one integrators internalizing specification authority previously held by independent distributors.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bolt market sits in a coating-technology transition as REACH-mandated zinc-nickel and organic topcoats displace legacy hexavalent chromium plating across European automotive supply chains.
For Market Incumbents: Hedge against margin compression in commodity carbon steel tiers by securing captive electric arc furnace capacity for verified low-carbon metallurgy certification under China's MIIT dual carbon protocols. Deepen backward integration into specialty alloy melt chemistry partnerships with Japanese and Western European mills to defend aerospace-grade positioning against superalloy supply chokepoints. For New Entrants and Emerging Players: Capture import substitution windows in Vietnam and Indonesian infrastructure build-out where domestic high-tensile forging capacity remains underdeveloped. Target M12 and M16 structural grades for National Highway and toll road development projects where BIS certification barriers are lower than automotive-grade qualification timelines. Lead with REACH-compliant coating conversion services as differentiated entry wedge for EU-bound automotive tier-two suppliers facing compressed 24-month conversion deadlines. For Investors and Strategic Acquirers: Re-rating potential sits with captive forgers possessing in-house heat treatment expertise given accelerating EV platform procurement cycles and thinning veteran technician pools. Long-term viability favors specialists controlling 12.9-grade quenching capability and direct OEM contracting relationships over distributor-dependent commodity producers. Monitor German automotive OEM blockchain pilot programs for material traceability as inflection signal for premium-grade certification premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Coating Conversion Investment | REACH Annex XVII compliance secures EU automotive RFQ eligibility for tier-two suppliers. |
| Captive Forging Capacity Expansion | Direct OEM contracting in Stuttgart and Detroit corridors displaces distributor intermediation. |
| Specialty Alloy Partnership | Upstream control over nickel-molybdenum melt chemistry defends aerospace-grade positioning. |
| Digital Traceability Platform | Blockchain-enabled grade verification from melt to assembly satisfies German OEM pilot requirements. |
| Regional Import Substitution | Vietnam and Indonesia infrastructure build-out lacks domestic high-tensile forging supply. |
Methodological Framework
Independent corroboration across fastener procurement executives at German and Chinese automotive OEMs, heat treatment operations managers in Bavaria and Pune, and construction distribution buyers in Maharashtra and Tamil Nadu underwrites the qualitative findings. Secondary validation drew from NHTSA FMVSS documentation, ECHA REACH restriction timelines, BIS certification registries, and MIIT dual carbon policy disclosures. Bottom-up demand modeling across EV platform bolt specifications and top-down steel consumption analysis were triangulated against customs trade data and specialty alloy mill output records.
Comparable-period anchoring linked forward projections to historical EV platform rollout cycles, infrastructure build-out trajectories, and aerospace engine platform renewal patterns. Segmentation dimensions spanned product type, material grade tier, application severity, and dimensional specification across automotive, construction, aerospace, and electronics end-uses. CAGRs were derived from elasticity-adjusted demand curves incorporating alloy substitution timelines and regional certification reciprocity assumptions. Forecast inputs included ECE R94 compliance adoption curves, PLI scheme capacity scaling in Indian industrial corridors, and REACH coating conversion enforcement intensity.
The model holds under stable nickel-molybdenum input cost regimes and sustained EV platform investment; deviation in alloy price volatility or regulatory enforcement acceleration would shift grade substitution timelines and margin tier boundaries. Periodic stress-testing of base assumptions against SAMR market surveillance intensity and ECHA restriction expansion scope is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Cement Market
Building Materials
Door Frame Metal Market
Building Materials
Recycled Construction Aggregates Market
Building Materials
Stone Adhesive Market
Building Materials
Global Builders Joinery and Carpentry of Wood Market
Building Materials
North America Cement Market
Building Materials
Portland Cement Market
Building Materials
HDG Steel Pipe Market
Building Materials
US Contract Glazing Market
Building Materials
India Concrete Admixtures Market
Building Materials
Canada Architectural Coatings Market
Building Materials
Europe Acrylic Resin Dispersion Based Primers in Construction Market
Building Materials
United Kingdom White Cement Market
Building Materials
North America Building and Construction Sheets Market
Building Materials
Global Metal Cladding Market
Building Materials
Construction Stone Market