
 Graphene Electronics Market | 2026-2036
Graphene Electronics Market Size, Share, and Industry Trends Forecast 2026-2036
Graphene Electronics Market Intelligence
Direct-to-OEM sales channels for high-purity graphene films are reshaping competitive positioning among material suppliers seeking to capture value in nascent applications. Graphenea specializes in CVD graphene production targeting research and advanced prototyping. NanoXplore Inc. leverages its large-scale powder production capacity to serve industrial composite and battery markets. Versarien plc operates through strategic partnerships to integrate its proprietary graphene inks into commercial products like textiles and packaging.
Graphene electronics utilize the single-atom-thick carbon lattice of graphene for fabricating novel electronic components. The material's exceptional carrier mobility, exceeding 200,000 cm²/Vs, and high thermal conductivity enable the development of high-frequency and low-power devices. Within product types, supercapacitors and sensors represent the fastest-growing segments due to performance benefits in energy storage and detection. Flexible electronics, a key technology area, commands significant R&D investment for applications in next-generation wearable devices and displays.
Material commercialization is governed by chemical registration frameworks like the EU's REACH regulation, managed by ECHA, and substance evaluations by the US EPA. Concurrently, ISO technical committees are developing crucial standards for graphene characterization, which ensures material consistency and quality across the global supply chain. Stakeholder success will depend on navigating this evolving regulatory landscape while securing scalable, high-yield manufacturing processes.
Market Dynamics
The Graphene Electronics Market's trajectory is defined by the critical need to bridge the gap between lab-proven material performance and industrial-scale manufacturability. Demand for high-performance components from the consumer electronics sector pressures suppliers to develop cost-effective, high-yield production methods for consistent, high-purity graphene.
Growth Catalysts
- Advanced Manufacturing Techniques:Progress in chemical vapor deposition (CVD) processes enables the production of large-area, high-quality graphene films, which are essential for transparent conductive electrodes in flexible displays and touch screens.
- Consumer Electronics Integration:The push for smaller, lighter, and more powerful devices in the consumer electronics industry drives the adoption of graphene for applications like thermal management films, flexible circuits, and next-generation wearables.
- Energy Storage Performance:Graphene's high surface area and electrical conductivity are enhancing the performance of supercapacitors, leading to faster charging and longer cycle life for energy storage systems in electronics and electric vehicles.
Market Restraints
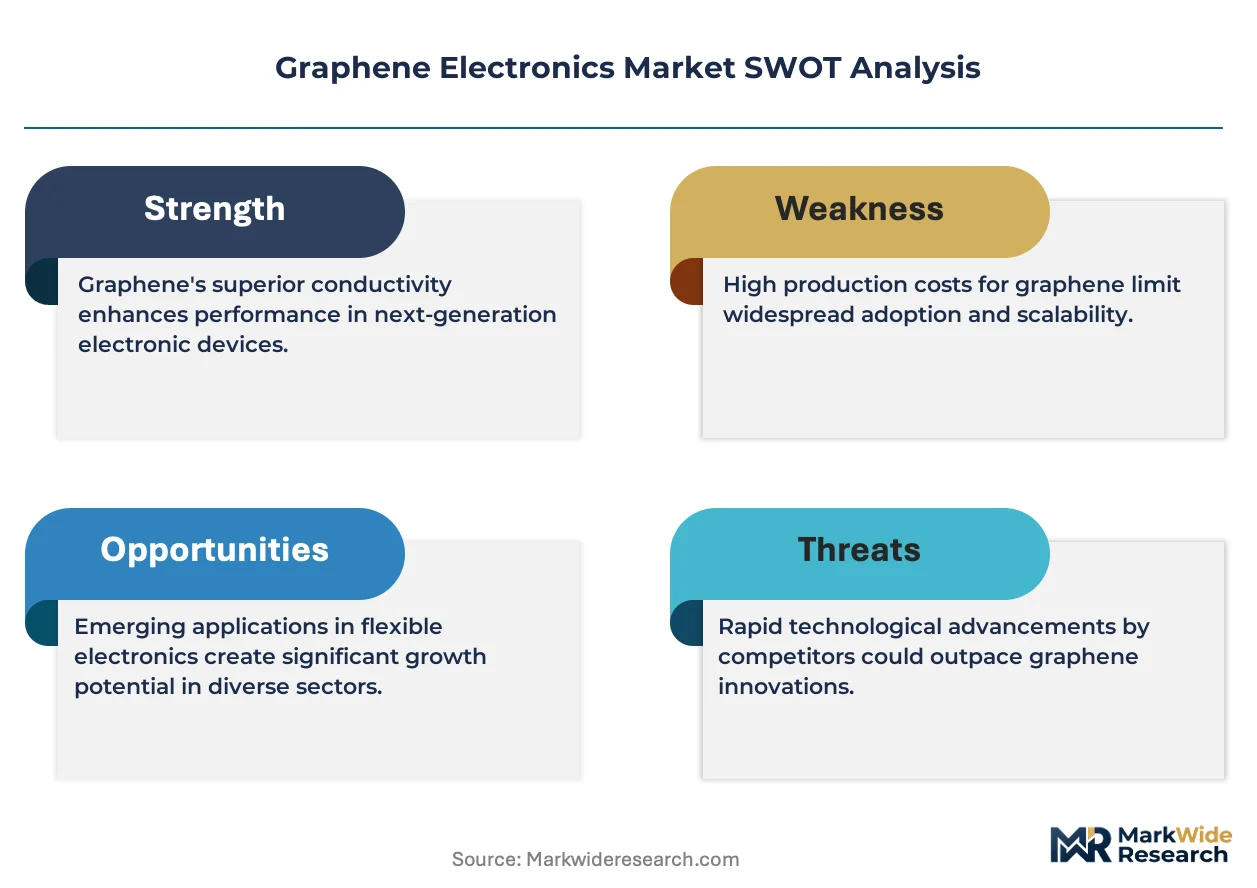
- High Production Costs:The expense associated with producing high-purity, defect-free graphene remains a significant barrier to mass-market adoption, particularly for exfoliation and CVD methods that require controlled environments and costly precursors.
- Lack of Standardization:Inconsistent material quality and the absence of universally accepted characterization standards create uncertainty for end-users, complicating device integration and hindering supply chain reliability across different producers.
- Regulatory Hurdles:Navigating complex chemical registration frameworks, such as the EU's REACH regulation and substance evaluations by the US EPA, adds significant time and cost for material suppliers seeking to commercialize new graphene products.
Strategic Opportunities
- Next-Generation RF Electronics:Graphene's exceptional carrier mobility presents an opportunity to develop high-frequency transistors and radio-frequency integrated circuits (RFICs) for advanced communication systems, including 6G and satellite communications.
- Biomedical Sensing Platforms:The material's sensitivity to surface changes creates opportunities for highly specific biosensors, enabling new diagnostic tools for point-of-care testing, DNA sequencing, and continuous health monitoring devices.
- Hybrid Material Systems:Combining graphene with other 2D materials like hexagonal boron nitride (h-BN) or transition metal dichalcogenides (TMDs) opens pathways to create heterostructures with tailored electronic and optoelectronic properties for novel devices.
Industry Challenges
- CMOS Integration Complexity:Integrating graphene-based components into established silicon CMOS manufacturing workflows is a major technical challenge, risking cross-contamination and requiring significant process and equipment modifications.
- Intellectual Property Navigation:A dense and often overlapping patent landscape for graphene synthesis and applications creates licensing complexities and risks of litigation, which can deter commercialization efforts, particularly for smaller companies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Graphene Electronics Market |
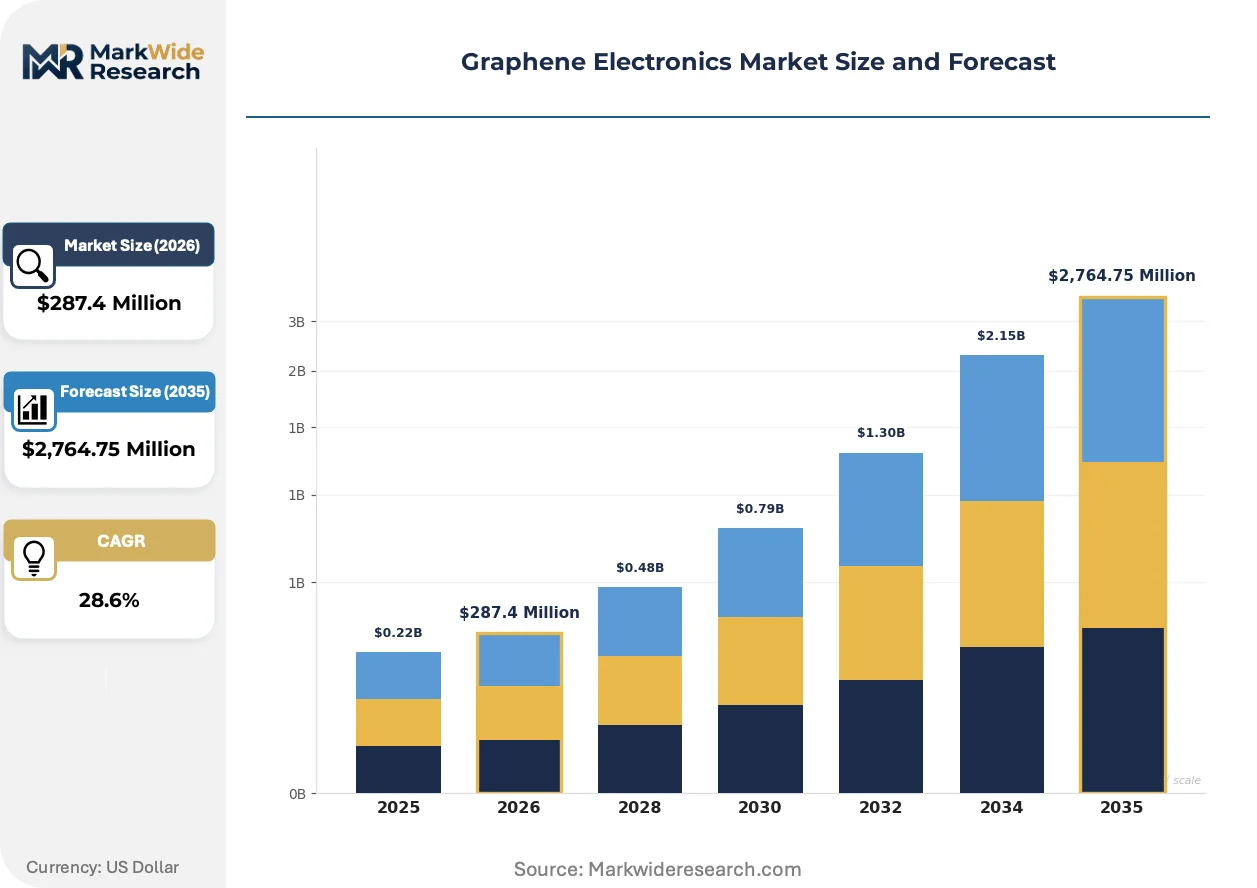
| Market Size in 2026 | $287.4 Million |
| Market Size in 2035 | $2,764.75 Million |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transistors, Supercapacitors, Sensors, LED Displays Technology: Flexible Electronics, Transparent Conductors, Photonic Devices, RF Components End User: Consumer Electronics, Telecommunications, Automotive, Aerospace Application: Energy Storage, Wearable Devices, High-Frequency Circuits, Imaging Systems |
| Companies Covered | Graphenea, Nanotech Energy, Carbon Rivers, Global Graphene Group, Zentek Ltd., NanoXplore Inc., Graphene Manufacturing Group, Versarien plc, NanoIntegris Technologies, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Graphene Electronics Market Strategic Shifts & Innovations
The market is shifting focus from fundamental material research to application-specific product engineering. This transition is marked by the development of standardized materials and the formation of direct partnerships between material producers and original equipment manufacturers to solve specific integration challenges.
Graphene field-effect transistors (GFETs) are an important evolution, utilizing the material's extreme sensitivity for advanced sensing. The medical diagnostics and environmental monitoring sectors are early adopters, using GFETs for real-time detection of biomarkers and pollutants. The focus of development is migrating from demonstrating basic material properties in research labs to engineering reliable, integrated sensor modules for commercial field deployment.
Development of global standards by the International Organization for Standardization (ISO) is bringing much-needed consistency to the supply chain. Specific technical specifications for graphene characterization provide a common benchmark for defining material properties like layer number, purity, and defect density. Electronics component manufacturers are most affected, as they can now enforce verifiable quality metrics on material suppliers, reducing integration risk.
A significant change in buying behavior involves electronics OEMs establishing direct development and supply agreements with graphene producers. This model bypasses traditional chemical distributors, enabling co-creation of customized materials for specific applications like flexible displays or thermal interface materials. This direct procurement pattern is most visible within the advanced electronics manufacturing hubs of South Korea and Taiwan.
Graphene Electronics Market Segmentation
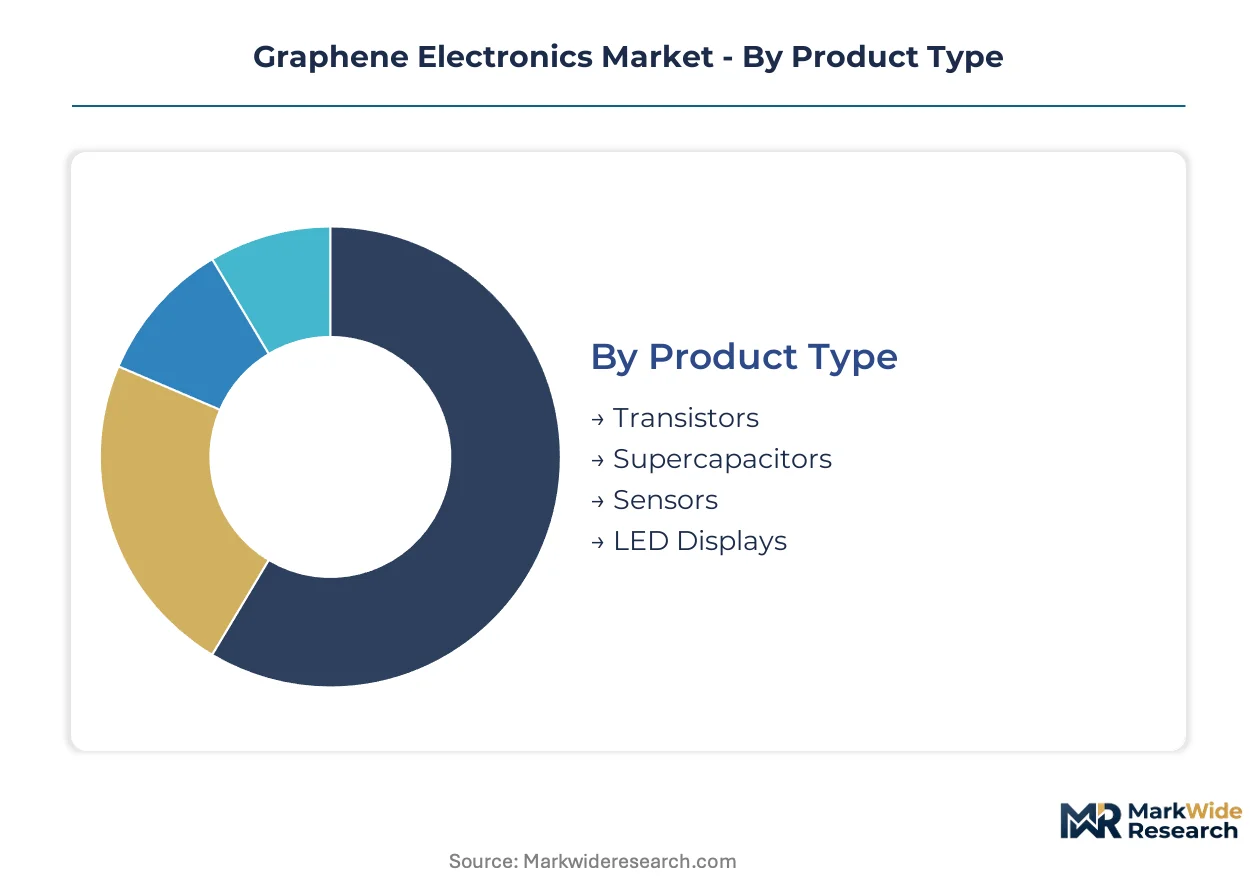
The Graphene Electronics Market is segmented by product type, technology, end user, and application, reflecting the diverse pathways through which graphene's unique properties are commercialized. Understanding these distinct categories provides clarity on market dynamics and strategic investment areas within this nascent industry.
Product Type:
The commercialization cycle for graphene-based products varies significantly, with some segments achieving rapid prototyping and others requiring extensive R&D before market entry.
- Supercapacitors:Graphene's high surface area and electrical conductivity enhance energy storage performance, enabling faster charging and longer cycle life. Demand concentrates in consumer electronics and electric vehicles seeking advanced power solutions.
- Sensors:Utilizing graphene's extreme sensitivity to surface changes, these devices enable highly specific detection of biomarkers and pollutants. Medical diagnostics and environmental monitoring sectors are early adopters, driving demand for real-time detection.
- Transistors:Graphene field-effect transistors (GFETs) leverage exceptional carrier mobility for high-frequency and low-power device development.
- LED Displays:Graphene films serve as transparent conductive electrodes, improving efficiency and flexibility in next-generation display technologies.
Graphene transistors currently dominate the installed base for initial prototyping. Supercapacitors are where expansion concentrates, driven by energy storage demands.
Technology:
Differentiation in graphene electronics technology often stems from its core functional application, dictating material specifications and integration complexities.
- Flexible Electronics:This technology area commands significant R&D investment, leveraging graphene's mechanical strength and conductivity for next-generation wearable devices and displays. Consumer electronics OEMs drive demand for advanced form factors.
- Transparent Conductors:Advances in chemical vapor deposition (CVD) enable high-quality graphene film production for these conductors. Demand concentrates within South Korea's and Taiwan's advanced electronics manufacturing hubs for flexible displays.
- Photonic Devices:Graphene's unique optical properties enable modulators and detectors for high-speed optical communication systems.
- RF Components:Graphene's exceptional carrier mobility facilitates high-frequency transistors and radio-frequency integrated circuits for advanced communication.
Flexible electronics technology demonstrates the steepest expansion trajectory. Transparent conductors also show significant growth potential.
End User:
The scale of commercial investment by end-user industries significantly influences the development and adoption pace of graphene electronics.
- Consumer Electronics:This sector pressures suppliers for cost-effective, high-yield graphene production for applications like flexible displays, thermal management films, and advanced wearables. Demand is concentrated in South Korea and Taiwan.
- Telecommunications:Graphene's properties are critical for next-generation RF electronics, including high-frequency transistors and RFICs for 6G and satellite communication systems. This segment focuses on high-performance components.
- Automotive:Graphene enhances battery performance, lightweight composites, and advanced sensor systems for electric vehicles and autonomous driving.
- Aerospace:This industry explores graphene for lightweight structures, thermal management, and robust sensors in extreme environments.
Consumer electronics represent the largest end-user segment. Telecommunications is rapidly increasing its uptake of graphene solutions.
Application:
Market readiness for specific graphene applications varies, with some areas already seeing commercial integration while others remain in advanced development.
- Energy Storage:Graphene's high surface area and electrical conductivity significantly enhance supercapacitor performance, leading to faster charging and longer cycle life in electronics and electric vehicles.
- Wearable Devices:Flexible electronics, enabled by graphene, are crucial for next-generation wearable technology, including smart patches, health monitors, and interactive textiles. This area commands significant R&D investment.
- High-Frequency Circuits:Graphene's exceptional carrier mobility is leveraged for developing advanced transistors and integrated circuits in communication systems.
- Imaging Systems:Graphene-based photodetectors offer high sensitivity and broad spectral response for advanced medical and industrial imaging.
Energy storage applications currently hold the largest market share. Wearable devices are poised for substantial growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power for graphene electronics remains concentrated in East Asian manufacturing hubs like South Korea, while European markets like Germany focus on high-value, specialized applications. This regional disparity reflects varying investment priorities and supply chain integration models. Manufacturers in these key regions drive demand for advanced graphene materials.
South Korea
South Korea's consumer electronics sector drives demand for flexible displays and advanced wearables. The Ministry of Food and Drug Safety (MFDS) oversees regulatory approval for graphene-based biomedical sensing platforms. The Seoul Capital Area hosts major electronics OEMs, accelerating graphene film integration into next-generation devices.
Taiwan
Taiwan's advanced electronics manufacturing relies on high-quality transparent conductive electrodes for displays and touchscreens. The country's Environmental Protection Administration (EPA) manages chemical substance registration for novel materials. Hsinchu Science Park acts as a focal point for semiconductor and display manufacturers adopting graphene technologies.
The United States
The United States shows high demand for graphene in next-generation RF electronics and advanced biomedical sensing platforms. The US EPA conducts substance evaluations for new materials, influencing commercialization pathways. Innovation hubs like Silicon Valley and Boston are centers for developing graphene-based high-frequency circuits and diagnostic tools.
Germany
Germany's automotive sector and industrial equipment manufacturers seek graphene for enhanced battery performance and durable sensors. The European Chemicals Agency (ECHA) manages the EU's REACH regulation, impacting graphene material commercialization. Bavaria and North Rhine-Westphalia are key regions for advanced materials research and industrial application development.
China
China's vast consumer electronics market and electric vehicle industry generate substantial demand for cost-effective graphene solutions. The Ministry of Industry and Information Technology (MIIT) supports domestic graphene production and application development. The Yangtze River Delta region is a major manufacturing base integrating graphene into various electronic components and energy storage systems.
Graphene Electronics Market Key Industry Players
Material suppliers and application integrators split the graphene electronics market, reflecting diverse strategies to commercialize advanced materials. The competitive landscape shows a tiered structure, with a few large-scale graphene producers operating alongside numerous niche specialists. Companies engage in strategic partnerships to integrate proprietary graphene materials into commercial products, especially for nascent applications. Capacity expansion and technology licensing are common competitive moves employed to secure early market share and accelerate product development.
Within the specialized material supply segment, Graphenea, NanoXplore Inc., and Versarien plc exemplify distinct commercialization approaches. Graphenea, a Spain-based firm, primarily focuses on high-purity CVD graphene production for research and advanced prototyping. Canada-based NanoXplore Inc. occupies a position as a large-scale powder producer, serving industrial composite and battery markets with its material. UK-headquartered Versarien plc sits within the archetype of leveraging strategic partnerships to integrate its proprietary graphene inks into diverse commercial products like textiles and packaging. These entities highlight the varied pathways to market for graphene materials.
| Leading Market Players |
|---|
| Graphenea |
| Nanotech Energy |
| Carbon Rivers |
| Global Graphene Group |
| Zentek Ltd. |
| NanoXplore Inc. |
| Graphene Manufacturing Group |
| Versarien plc |
| NanoIntegris Technologies, Inc. |
| Others |
Cost & Logistics Intelligence
Underutilized CVD graphene production capacity in advanced manufacturing hubs like South Korea influences supplier behavior and pricing posture. This capacity allows for greater flexibility in meeting fluctuating demand from consumer electronics OEMs, impacting material costs.
Pricing Analysis
Configured-to-order high-purity graphene films command a significant premium over standard industrial-grade graphene powders. The dominant pricing model remains contract-based long-term offtake agreements for large-volume buyers, while project-based pricing serves R&D and prototyping. Price differentiation stems from material quality grade, specific customization levels, and the volume scale of procurement. Pricing softness for standard graphene powders reflects increasing competition among producers. Consumer electronics OEMs demonstrate high price sensitivity for mass-market applications, whereas research institutions are less price-sensitive for specialized, high-purity materials.
Supply Chain Analysis
Upstream graphite precursors and specialized chemical feedstocks for CVD processes anchor the graphene electronics supply chain. Geographic supply concentration for high-quality graphene films centers within South Korea and Taiwan, driven by advanced electronics manufacturing. Single-source vulnerability for specific high-purity precursors represents a structural supply chain risk. Direct-to-OEM sales channels dominate the distribution model for high-purity graphene films, bypassing traditional chemical distributors to facilitate co-development and custom material specification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Graphene Electronics Market presents a defensive-moat story for established players, bolstered by high switching costs for OEMs integrating novel materials into complex electronic systems.
For Market Incumbents:
Insulate market position by investing heavily in scalable, high-yield manufacturing processes, particularly advanced CVD techniques. Secure long-term supply agreements with major consumer electronics and telecommunications OEMs to counter margin pressure from emerging producers. Expand capacity in key regional hubs like South Korea and Taiwan to maintain proximity to demand. Prioritize R&D into material standardization and characterization to reduce integration risks for end-users.
For New Entrants and Emerging Players:
Niche high-frequency RF components and advanced biosensors represent penetrable white spaces for new entrants. Focus on specialized applications requiring graphene's extreme sensitivity or exceptional carrier mobility, where performance outweighs initial cost barriers. Target the medical diagnostics and advanced communication sectors as the most penetrable segments for high-value solutions. A strategic partnership model with research institutions or specialized component manufacturers offers a viable go-to-market angle.
For Investors and Strategic Acquirers:
Long-term, this sits as a foundational materials platform play because of graphene's unique properties and broad application potential across diverse electronics sectors. Acquisition targets should include specialized material producers holding strong intellectual property in synthesis methods or application-specific graphene formulations. The successful integration of graphene into a mass-market flexible display or a widely adopted medical diagnostic device serves as a critical signal to watch for broader market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for CVD Graphene | Increases supply of large-area, high-quality films essential for flexible displays and transparent conductors. |
| Technology Licensing Agreements | Broadens the application reach of proprietary graphene synthesis methods across diverse electronic components. |
| Strategic Partnerships with OEMs | Accelerates the co-development and integration of customized graphene materials into next-generation devices. |
| Investment in Regulatory Approval Pathways | Facilitates commercialization of graphene-based products in regulated sectors like biomedical and automotive. |
| Contribution to ISO Standardization Efforts | Establishes common benchmarks for material quality, reducing uncertainty for electronics component manufacturers. |
Research Approach
Findings reconcile primary fieldwork against secondary review of academic journals, patent databases, and national chemical registration filings. Primary interviews engaged R&D directors at graphene producers, procurement leads at consumer electronics OEMs, regulatory affairs specialists, and academic researchers in materials science. This approach ensured a robust bottom-up and top-down triangulation of market data.
Forecast inputs considered include technological advancements, regulatory frameworks, and end-user adoption rates across the analysis window. The analytical framework modeled segmentation dimensions such as product type, technology, end user, application, and regional manufacturing capacity. CAGRs were derived from historical growth trends and projected technology adoption curves, incorporating industry-specific inputs like CVD production yield improvements and regulatory approval timelines.
Macroeconomic conditions sit as an overlay; deviation in global trade policies or R&D funding levels would shift the trajectory of graphene electronics adoption. Forecasts reflect assumptions documented regarding market dynamics and technological progression. Cross-checking against national innovation reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Semiconductor Wafer Frame Market
Semiconductor Devices
Temperature-Controlled Semiconductor Market
Semiconductor Devices
Semiconductor Wafer Market
Semiconductor Devices
Middle East and Africa Silicon Carbide Wafers Market
Semiconductor Devices
AMD Motherboards Market
Semiconductor Devices
Printed Circuit Board (PCB) Laminate Market
Semiconductor Devices
Thick Film Devices Market
Semiconductor Devices
Silicon on Insulator Market
Semiconductor Devices
DNA Chip Market
Semiconductor Devices
CMP Pads Market
Semiconductor Devices
Epi Wafer Market
Semiconductor Devices
Nanowires Market
Semiconductor Devices
Laneth-16 Market
Semiconductor Devices
Japan International CEP Market
Semiconductor Devices
Ram BOP Market
Semiconductor Devices
Flip Chip Market