
 Ram BOP Market | 2026-2036
Ram BOP Market Size, Share, and Industry Trends Forecast 2026-2036
Ram BOP Market Analytics
Aftermarket service revenue is tilting toward condition-based monitoring and predictive refurbishment contracts. NOV Inc. leverages its integrated blowout preventer platform to capture recurring service streams across installed bases. Baker Hughes Company anchors its position through subsea Ram BOP specialization and pressure-control engineering depth. Shandong Kerui Holding Group competes on manufacturing scale and cost-optimized conventional Ram BOP supply for onshore operators.
A Ram BOP is a well control device employing horizontally opposed steel rams to seal the annular space around drill pipe or shear through pipe entirely, rated typically from 5,000 to 20,000 psi working pressure depending on stack configuration. The equipment forms the final mechanical barrier against uncontrolled formation fluid release during drilling, completion, or workover operations. Hydraulic BOP systems dominate capital allocation among product types due to their established reliability in high-pressure environments, while Annular BOP units command premium positioning for their ability to seal around variable pipe geometries. Advanced Technology segments including automation systems are capturing disproportionate R&D investment as operators pursue remote actuation and real-time pressure monitoring capabilities.
API standards govern Ram BOP design validation and pressure-testing regimens across North American operations, while NORSOK specifications shape Norwegian Continental Shelf requirements for subsea well control integrity. The US Bureau of Safety and Environmental Enforcement enforces blowout preventer maintenance and certification mandates following post-Macondo regulatory restructuring. Brazil's national petroleum regulator imposes local content thresholds and prescriptive testing intervals for pre-salt drilling equipment. Stakeholders must weigh upgrade cycles against regulatory compliance horizons as inspection intervals compress and documentation requirements expand.
Market Dynamics
Deepwater drilling contractors are compressing Ram BOP replacement cycles as API 16A specification revisions mandate tighter pressure-testing protocols and real-time monitoring integration across subsea stacks.
Growth Catalysts
- Pre-salt basin expansion:Brazil's national petroleum regulator enforces local content thresholds that stimulate domestic Ram BOP procurement for ultra-deepwater rigs operating in the Santos Basin.
- Remote actuation mandates:Norway's Petroleum Safety Authority requires automated well control systems on all new subsea installations, accelerating hydraulic BOP upgrades with integrated sensors.
- Condition-based monitoring:Offshore drilling contractors in the US Gulf of Mexico are adopting predictive refurbishment contracts that extend equipment life while reducing unplanned downtime.
Market Restraints
- Specialized alloy supply concentration:High-strength steel forgings for ram blocks concentrate among a limited supplier base in East Asia, exposing procurement to geopolitical disruption.
- Extended certification timelines:API 16A validation protocols now require multi-stage pressure cycling tests that stretch delivery schedules for new stack configurations.
- Subsea installation complexity:Technical limitations in remote hydraulic actuation at depths exceeding 3,000 meters constrain Ram BOP deployment in frontier ultra-deepwater zones.
Strategic Opportunities
- Decommissioning retrofit demand:Norway's North Sea fields require Ram BOP upgrades for plug-and-abandonment operations, creating aftermarket volume in mature basins.
- Digital twin integration:Convergence of finite element modeling with real-time sensor feeds enables virtual pressure-testing that reduces physical validation costs.
- Extended-reach onshore drilling:Horizontal well programs in the Permian Basin drive demand for compact Ram BOP stacks suited to pad drilling configurations.
Industry Challenges
- Subsea systems engineering talent:Shortages of hydraulic control specialists and high-pressure sealing engineers constrain OEM capacity expansion and field service deployment.
- Legacy stack interoperability:Integration complexity with existing BOP control systems delays adoption of automated monitoring modules on retrofitted offshore rigs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ram BOP Market |
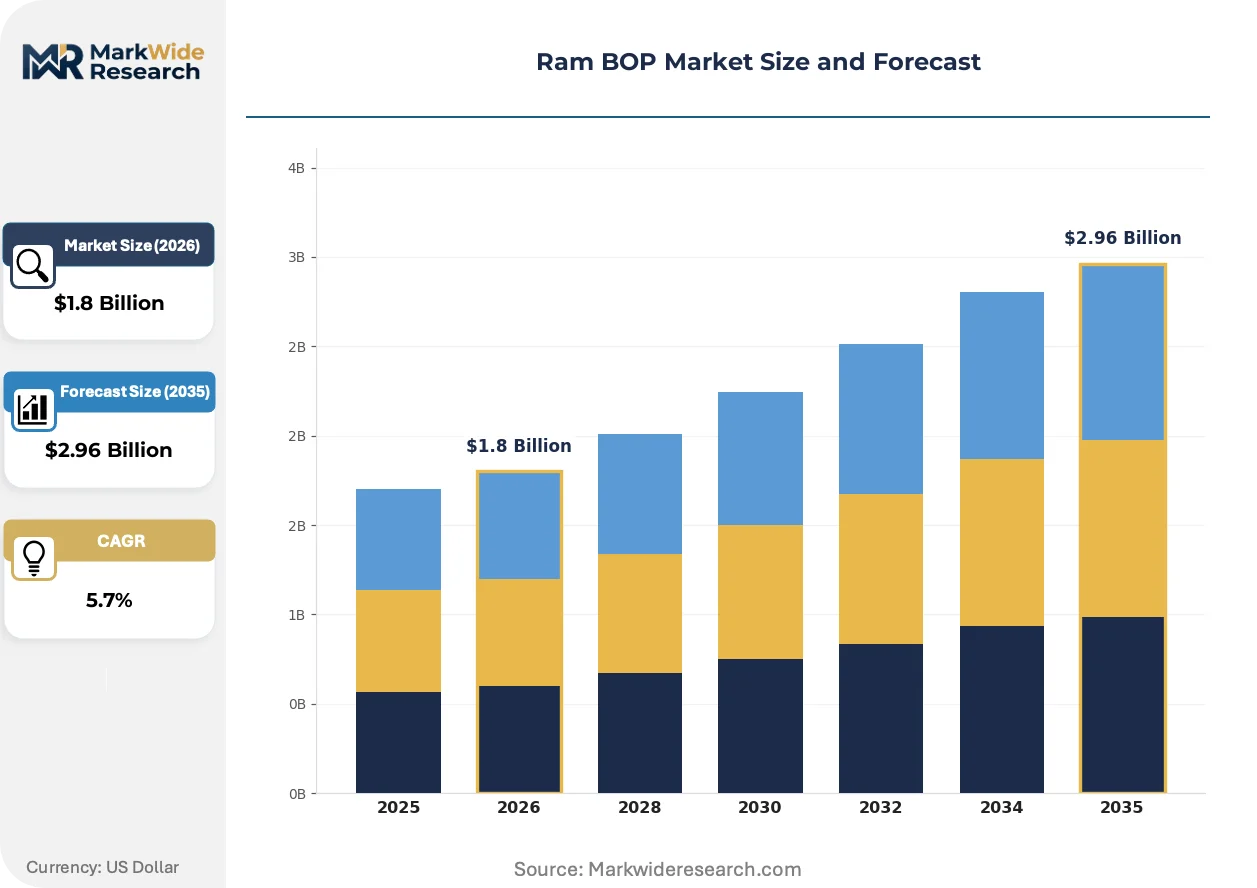
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic BOP, Annular BOP, Ram BOP, Stack BOP End User: Oil & Gas Industry, Offshore Drilling, Onshore Drilling, Exploration Companies Application: Drilling Operations, Well Control, Blowout Prevention, Safety Management Technology: Conventional Technology, Advanced Technology, Automation Systems, Monitoring Solutions |
| Companies Covered | Schlumberger Limited, NOV Inc., Baker Hughes Company, Uztel S.A., Halliburton Company, Control Flow Inc., Weatherford International, Shandong Kerui Holding Group, TIS Manufacturing Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ram BOP Market Evolving Landscape
Digitalization is penetrating Ram BOP engineering through virtual validation platforms, regulatory pressure is hardening certification requirements across North Atlantic jurisdictions, and contractor procurement models are pivoting toward integrated service agreements.
Digital twin technology is virtualizing Ram BOP design validation by simulating pressure cycling and fatigue loading before physical prototype fabrication. Offshore drilling contractors in Norway and Brazil are adopting these platforms to compress qualification timelines for custom stack configurations. This virtualization is reducing physical test iterations and accelerating regulatory submission packages for subsea deployments.
API 16A specification revisions are tightening pressure-testing protocols for subsea well control equipment through mandatory real-time data logging and third-party witness requirements. The industrial consequence is extended certification timelines and elevated documentation burdens for manufacturers serving North American offshore markets. Deepwater rig operators in the US Gulf of Mexico are responding by consolidating procurement with suppliers possessing integrated testing and certification capabilities.
Service contract unbundling is reshaping how offshore contractors acquire Ram BOP capability, with separate sourcing of equipment, installation, and aftermarket support replacing traditional bundled procurement. Independent drilling contractors are displacing OEM service arms with specialized third-party refurbishment providers in the North Sea. This pattern is most visible among mid-sized contractors in Norway seeking cost optimization without sacrificing regulatory compliance coverage.
Ram BOP Market Segmentation
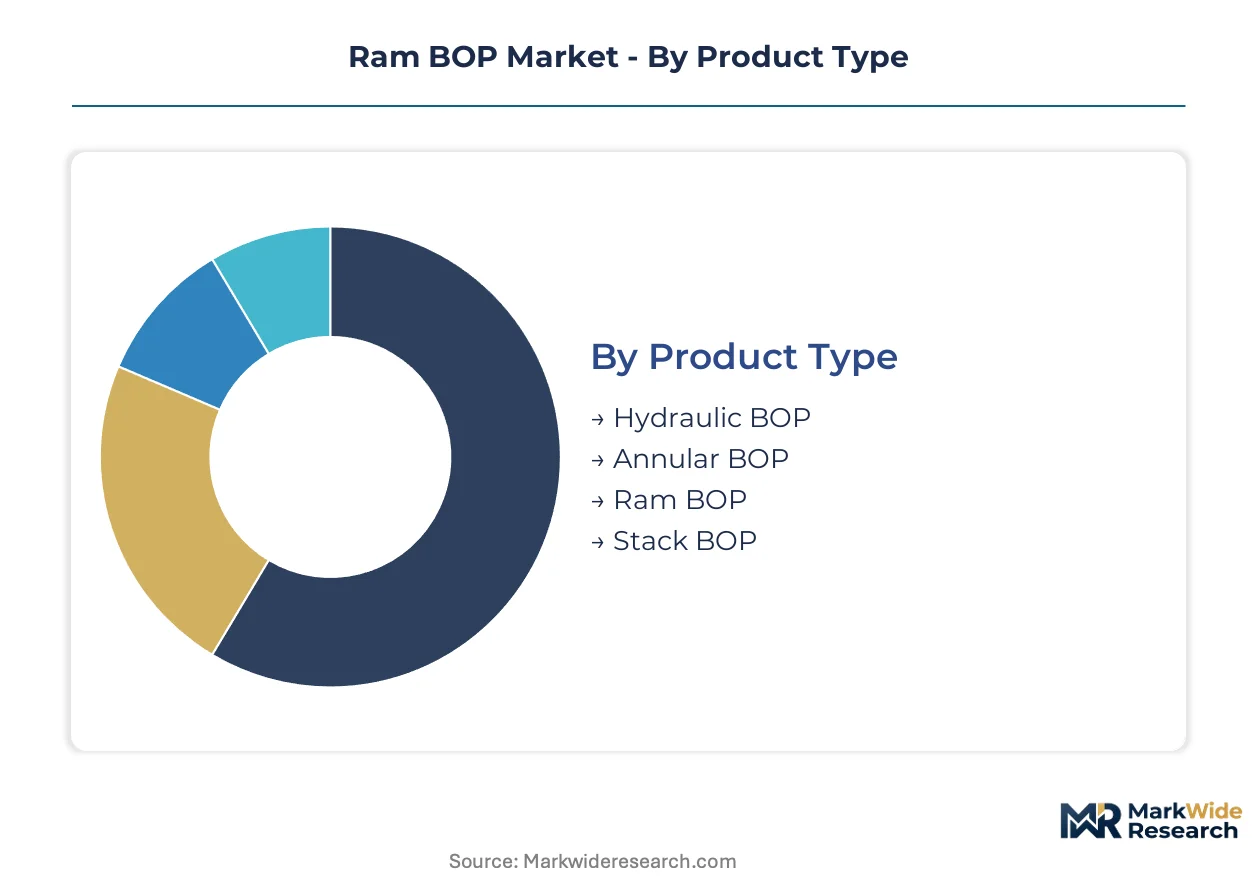
Ram BOP procurement patterns diverge sharply across equipment configurations, with aftermarket service intensity varying by product complexity and operational environment. Understanding these segment boundaries clarifies where capital allocation concentrates versus where recurring revenue streams materialize.
Product Type:
After-sales service intensity escalates with hydraulic system complexity, creating divergent margin profiles across equipment categories.
- Hydraulic BOP:These systems employ pressurized fluid networks to actuate ram closure against wellbore pressure, typically rated 10,000 to 20,000 psi for subsea stacks. Demand concentrates among deepwater contractors in Brazil's Santos Basin and the US Gulf of Mexico, where API 16A mandates real-time pressure monitoring integration. Extended replacement cycles and predictive refurbishment contracts generate substantial aftermarket revenue for OEM service arms.
- Annular BOP:Annular units utilize elastomeric packing elements to seal around irregular pipe geometries and kellys, commanding premium positioning for their operational flexibility. Norway's Petroleum Safety Authority requirements for automated well control on new subsea installations accelerate procurement of sensor-integrated annular configurations. The segment's complex elastomer replacement schedules sustain higher service contract attachment rates than ram-based alternatives.
- Ram BOP:Conventional ram blocks employ opposed steel sealing elements for pipe-specific or blind/shear closure.
- Stack BOP:Integrated multi-component assemblies combine ram and annular elements in configurable arrangements.
Hydraulic BOP holds the largest share; momentum sits with Annular BOP.
End User:
Customer procurement sophistication varies with operational scale, separating integrated majors from independent drilling contractors.
- Oil & Gas Industry:Integrated supermajors and national oil companies operate captive BOP fleets with in-house maintenance capabilities. These operators in Norway and Brazil pursue long-term service agreements bundling equipment supply with condition-based monitoring, compressing third-party refurbishment opportunities.
- Offshore Drilling:Contract drillers face compressed dayrate environments that elevate equipment utilization targets and accelerate wear-related replacement demand. US Gulf of Mexico contractors respond to BSEE maintenance mandates by consolidating procurement with suppliers offering integrated certification and testing capabilities.
- Onshore Drilling:Land-based operators prioritize capital efficiency in pad drilling configurations.
- Exploration Companies:Wildcat-focused entities favor rental and leased BOP solutions to preserve balance sheet flexibility.
Oil & Gas Industry captures the dominant procurement volume; Offshore Drilling exhibits the steepest expansion trajectory.
Application:
Functional use case determines equipment specification stringency and regulatory oversight intensity.
- Drilling Operations:Primary BOP deployment during active hole construction requires continuous pressure containment readiness. Brazil's national petroleum regulator imposes local content thresholds and prescriptive testing intervals that shape procurement specifications for pre-salt drilling campaigns.
- Well Control:Emergency intervention applications demand instantaneous actuation reliability under extreme pressure differentials. Norway's North Sea decommissioning programs generate plug-and-abandonment retrofit demand for well control configurations adapted to aging infrastructure.
- Blowout Prevention:Ultimate barrier functions against uncontrolled formation fluid release.
- Safety Management:Regulatory compliance and personnel protection applications.
Drilling Operations anchors current installed base; Well Control is gaining share fastest amid regulatory tightening.
Technology:
Digital capability integration separates legacy equipment from next-generation platforms commanding pricing premiums.
- Conventional Technology:Established hydraulic and mechanical architectures without integrated sensor networks dominate onshore and mature offshore markets. These systems face extended certification timelines as API 16A revisions mandate multi-stage pressure cycling tests that stretch delivery schedules.
- Advanced Technology:Next-generation platforms incorporate finite element modeling outputs and real-time diagnostics. Norway and Brazil operators adopt these configurations to compress qualification timelines and satisfy automated well control mandates.
- Automation Systems:Remote actuation and closed-loop pressure management capabilities.
- Monitoring Solutions:Sensor networks enabling predictive maintenance and virtual validation.
Conventional Technology retains the largest installed base; Advanced Technology represents the fastest-growing trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Deepwater contractors in Brazil deploy Ram BOP stacks rated for 20,000 psi in pre-salt formations, while US Gulf of Mexico operators prioritize real-time monitoring integration over sheer pressure ratings. Norwegian North Sea drillers emphasize automated well control mandates that exceed baseline API specifications. This consumption-mix differential shapes procurement patterns across the three dominant offshore basins.
United States
Deepwater contractors in the Gulf of Mexico compress Ram BOP replacement cycles as the US Bureau of Safety and Environmental Enforcement enforces post-Macondo maintenance mandates. API 16A specification revisions require multi-stage pressure cycling tests with third-party witness protocols. Houston anchors the supplier ecosystem, with fabrication yards in Louisiana assembling subsea stacks for ultra-deepwater rigs.
Brazil
Pre-salt basin expansion drives procurement of 20,000 psi rated Ram BOP configurations for Santos Basin operations. Brazil's national petroleum regulator imposes local content thresholds and prescriptive testing intervals that stimulate domestic manufacturing partnerships. Rio de Janeiro hosts engineering centers where contractors integrate automated monitoring modules into stack assemblies.
Norway
North Sea decommissioning programs generate plug-and-abandonment retrofit demand for aging infrastructure. Norway's Petroleum Safety Authority mandates automated well control systems on all new subsea installations, accelerating hydraulic BOP upgrades with integrated sensors. Stavanger concentrates subsea systems engineering talent for frontier ultra-deepwater development.
China
State-backed drilling contractors expand high-pressure Ram BOP procurement for deepwater exploration in the South China Sea. The country's national petroleum regulator aligns testing protocols with API 16A while promoting domestic fabrication capabilities. Qingdao and Shanghai host manufacturing clusters producing cost-optimized conventional stacks for onshore and shallow-water deployment.
United Kingdom
North Sea mature basin operators require Ram BOP upgrades for extended-reach drilling and abandonment campaigns. Health and Safety Executive regulations govern well control equipment integrity through prescriptive inspection intervals. Aberdeen maintains service hub concentration for subsea stack refurbishment and recertification.
Ram BOP Market Competitive Landscape
Capability concentration sits with integrated oilfield service conglomerates; scale advantage sits with specialized regional fabricators. The market structures around three tiers: full-service providers bundling equipment with predictive maintenance contracts, component specialists focusing on high-pressure sealing engineering, and cost-optimized manufacturers serving onshore pad drilling configurations. Dominant competitive moves include vertical integration into aftermarket service streams and strategic partnerships for local content compliance in Brazil and Norway.
Within the integrated service tier, NOV Inc. and Baker Hughes Company exemplify archetypes combining subsea specialization with pressure-control engineering depth. Shandong Kerui Holding Group anchors the scale-driven segment, representing Chinese manufacturing concentration for conventional Ram BOP supply. Halliburton Company occupies a position bridging equipment provision with field service deployment across multiple offshore basins.
| Leading Market Players |
|---|
| Schlumberger Limited |
| NOV Inc. |
| Baker Hughes Company |
| Uztel S.A. |
| Halliburton Company |
| Control Flow Inc. |
| Weatherford International |
| Shandong Kerui Holding Group |
| TIS Manufacturing Ltd. |
| Others |
Value Network & Pricing Analysis
Qingdao's manufacturing clusters anchor global Ram BOP fabrication capacity, with state-backed foundries in Shandong Province feeding cost-optimized conventional stacks into onshore drilling markets. This geographic concentration grants Chinese producers pricing leverage in standard-pressure segments while exposing buyers to logistics premiums for subsea-qualified equipment sourced from Stavanger or Houston.
Pricing Analysis
Long-term offtake contracts dominate Ram BOP procurement among integrated supermajors, compressing spot-market liquidity for project-based drillers. Price differentiation rests on API 16A certification tier and after-sales service bundling, with sensor-integrated subsea configurations commanding substantial premiums over conventional hydraulic units. Pricing pressure intensifies in the onshore tier as Shandong Kerui and domestic Chinese fabricators expand high-volume output for Permian Basin pad drilling. Independent offshore contractors exhibit acute price sensitivity due to compressed dayrate environments, while national oil companies prioritize total-cost-of-ownership over upfront equipment expenditure.
Supply Chain Analysis
Extended payment terms from 90 to 180 days now characterize procurement relationships between offshore drilling contractors and East Asian forging houses, straining working capital for specialized alloy suppliers. High-strength steel forgings for ram blocks concentrate in China, South Korea, and Japan, with chromium-molybdenum billet and nickel-based superalloy casting feeding critical pressure-containing components. Single-source vulnerability in subsea hydraulic control systems exposes OEMs to geopolitical disruption and extended lead times for frontier ultra-deepwater stacks. Distribution runs through Houston and Rio de Janeiro service hubs for integrated certification and testing capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Predictive refurbishment contracts and condition-based monitoring subscriptions are expanding faster than hardware replacement cycles, transforming Ram BOP economics toward recurring-revenue models. This service-attach dynamic rewards suppliers with installed base scale and field engineering density.
For Market Incumbents: Harden defensive moats by deepening backward integration into high-strength steel forging capacity and API 16A certification infrastructure. NOV Inc. and Baker Hughes Company should prioritize captive supply of nickel-based superalloy castings to offset East Asian supply concentration risk. Condition-based monitoring platform stickiness represents the priority lever against independent third-party refurbishment entrants displacing OEM service arms in the North Sea. For New Entrants and Emerging Players: Build out specialized engineering capabilities in plug-and-abandonment retrofit configurations for Norway's North Sea decommissioning wave. The most penetrable white-space sits in compact Ram BOP stacks tailored to extended-reach onshore drilling in the Permian Basin, where cost-optimized manufacturing from Qingdao clusters can undercut integrated service pricing. A rental-leasing go-to-market model preserves balance sheet flexibility for wildcat-focused exploration companies. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors automated well control specialists with sensor-integrated hydraulic BOP platforms over conventional equipment fabricators. Long-term viability over the next decade rests on regulatory compliance depth and digital twin integration capabilities. Acquisition targets should demonstrate proven API 16A validation track records and established service infrastructure in Brazil or Norway. The signal to watch is API specification revision timing, as accelerated pressure-testing mandates would compress qualification timelines and favor incumbents with integrated testing capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| Condition-Based Monitoring Platform Deployment | Predictive refurbishment contracts lock in recurring revenue across installed bases in the US Gulf of Mexico. |
| API 16A Certification Infrastructure Investment | Integrated testing capabilities compress delivery schedules amid multi-stage pressure cycling mandates. |
| Subsea Systems Engineering Talent Acquisition | Hydraulic control specialists constrain OEM capacity expansion and field service deployment. |
| Digital Twin Integration Partnership | Virtual pressure-testing reduces physical validation costs for custom stack configurations in Brazil. |
| Local Content Compliance Joint Venture | Brazil's national petroleum regulator stimulates domestic manufacturing partnerships for pre-salt procurement. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with subsea systems engineers, offshore drilling procurement directors, API certification specialists, and aftermarket service heads; and secondary validation through API specification documentation, BSEE enforcement records, ANP regulatory filings, and NORSOK standard repositories. Bottom-up equipment deployment tallies across Brazil's Santos Basin, the US Gulf of Mexico, and Norway's North Sea were triangulated against top-down capital expenditure disclosures from integrated supermajors and contract drillers.
Forecast inputs incorporated pressure rating tier, operational environment, automation integration level, and regional regulatory cluster across the projection horizon. CAGRs were derived from equipment replacement cycle compression rates and predictive service contract attachment trajectories. Subsea installation depth limitations and specialized alloy supply constraints were modeled as binding capacity factors.
Stress conditions across API 16A revision timing, Brazilian local content threshold adjustments, and East Asian forging capacity utilization were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory compliance horizons and contractor procurement consolidation patterns. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Global Vacuum Capacitors Market
Semiconductor Devices
Field Effect Transistor Market
Semiconductor Devices
COF (Chip-On-Film) Market
Semiconductor Devices
China Semiconductor Device Market
Semiconductor Devices
Silicon on Insulator Market
Semiconductor Devices
Japan MLCC Market
Semiconductor Devices
Chip on Flex Market
Semiconductor Devices
Global Gan on Diamond Semiconductor Substrates Market
Semiconductor Devices
Field Programmable Gate Array (FPGA) Market
Semiconductor Devices
Silicon-Based Anode Market
Semiconductor Devices
Rad-Hard Mosfets Market
Semiconductor Devices
Global Bipolar Power Transistor Market
Semiconductor Devices
Europe MLCC Market
Semiconductor Devices
Global Trench Gate Power MOSFET Market
Semiconductor Devices
Global Through Silicon via (TSV) Technology Market
Semiconductor Devices
Gallium Nitride (Gan) Semiconductor Devices Market